
 US Evidence Management Market | 2026-2036
US Evidence Management Market Size, Share, and Industry Trends Forecast 2026-2036
US Evidence Management Market Insights
FBI CJIS Security Policy is decoupling compliance costs from legacy infrastructure budgets, forcing agencies to reassess total cost of ownership before procurement. NICE Ltd leverages its digital intelligence platform to anchor federal agency relationships across the intelligence community. Omnigo Software LLC specializes in chain-of-custody workflows for mid-sized municipal police departments. Motorola Solutions Inc. dominates mobile evidence capture through its integrated public safety communications ecosystem.
US evidence management encompasses the systematic collection, storage, retrieval, and preservation of digital and physical evidence within criminal justice workflows, typically requiring AES-256 encryption, audit-grade metadata tagging, and tamper-evident logging to maintain legal admissibility. Software solutions lead product type revenue as agencies replace paper-based logging with automated chain-of-custody platforms. Cloud-based deployment is expanding fastest among sheriffs' offices seeking elastic storage for body-worn camera footage without capital-intensive server farms. AI analytics within the technology dimension is capturing disproportionate R&D investment as prosecutors demand predictive evidence sorting and facial recognition integration.
FBI CJIS Security Policy, state-level public records retention statutes, and local procurement transparency ordinances collectively mandate multi-layered access controls and independent audit trails for all evidence systems. The Department of Justice's equitable sharing program further conditions federal grant eligibility on demonstrated digital evidence management maturity. Stakeholders must weigh interoperability commitments against vendor lock-in risks as agencies consolidate around fewer platform providers.
Market Dynamics
The FBI CJIS Security Policy is forcing state and local law enforcement agencies to decouple compliance costs from legacy infrastructure budgets, triggering a wholesale reassessment of procurement strategies and total cost of ownership calculations across municipal, county, and federal systems.
Growth Catalysts
- Agency Consolidation:California, Texas, and Florida are driving enterprise-scale deployments as sheriffs' offices and police departments merge evidence management platforms to eliminate redundant systems.
- Federal Grant Conditioning:The Department of Justice's equitable sharing program ties funding eligibility to demonstrated digital evidence management maturity, accelerating platform upgrades.
- Body-Worn Camera Proliferation:Elastic cloud storage demand from law enforcement agencies is surging as terabyte-scale video evidence requires automated chain-of-custody workflows.
Market Restraints
- CJIS Compliance Burden:The FBI's multi-layered access control mandates impose architectural constraints that extend procurement cycles and inflate integration costs for legacy system replacements.
- Vendor Concentration Risk:Platform consolidation around dominant providers creates lock-in scenarios that limit interoperability and compress negotiation leverage for mid-sized municipal departments.
- Capital Intensity of On-Premises Infrastructure:AES-256 encryption hardware and tamper-evident logging systems require substantial upfront investment that strains county-level IT budgets.
Strategic Opportunities
- AI Analytics Integration:Predictive evidence sorting and facial recognition capabilities are attracting disproportionate R&D investment from prosecutors seeking workflow automation.
- Cloud Migration Tailwinds:Sheriffs' offices in Florida and Texas are abandoning server farms for elastic storage models that convert capital expenditures to operational spending.
- Mid-Sized Municipal Penetration:Chain-of-custody workflow specialization for departments with 50-200 officers represents an underserved segment between federal and rural deployments.
Industry Challenges
- CJIS Security Officer Shortage:Agencies struggle to hire personnel with dual expertise in criminal justice information systems and cybersecurity audit protocols.
- Interoperability Friction:Proprietary data formats from incumbent platforms complicate evidence sharing between jurisdictions and create integration bottlenecks during multi-agency investigations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Evidence Management Market |
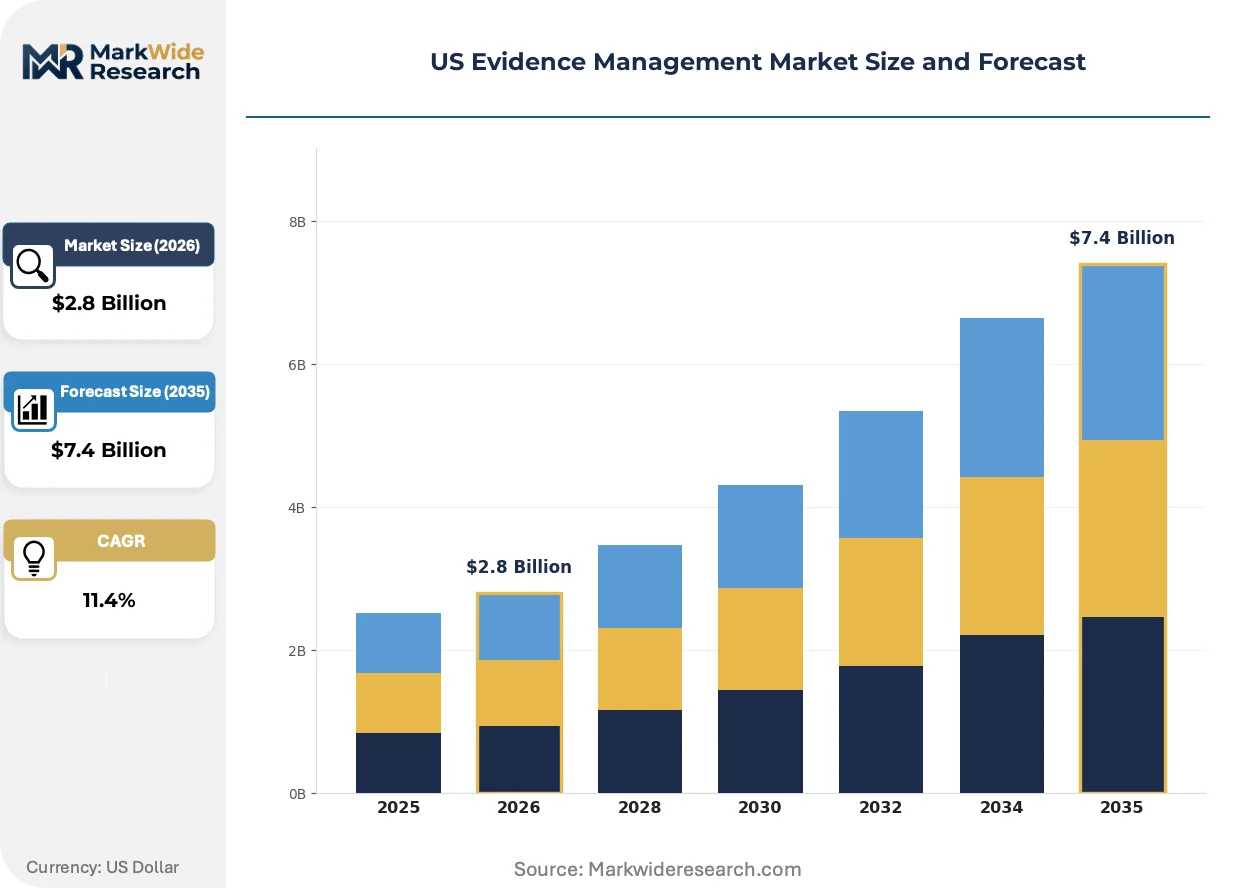
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Storage Systems, Mobile Applications, Cloud Services End User: Law Enforcement Agencies, Legal Firms, Government Organizations, Private Security Firms Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Technology: Blockchain, AI Analytics, Digital Forensics, IoT Integration |
| Companies Covered | NICE Ltd, Omnigo Software LLC, Open Text Corporation, Hitachi Vantara LLC, Panasonic Corporation, Motorola Solutions Inc., Oracle Corporation, IBM Corporation, Axon Enterprise, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Evidence Management Market Trends and Innovations
Digital evidence platforms are undergoing rapid architectural transformation as artificial intelligence capabilities, federal security mandates, and procurement model evolution converge to redefine competitive positioning across law enforcement technology stacks.
Automated chain-of-custody platforms are rewriting how evidence integrity is maintained from collection through adjudication. State and local agencies are adopting these systems at accelerated pace to replace paper-based logging. The technology is compressing audit preparation timelines while reducing human error rates in metadata tagging workflows.
The FBI CJIS Security Policy is tightening data handling requirements for all systems accessing criminal justice information. This regulatory pressure is forcing architectural redesigns that segment networks and implement independent audit trails. Cloud-based deployments face the steepest compliance burden as agencies reconcile elastic infrastructure with physical access control mandates.
Subscription-based procurement is displacing perpetual licensing across municipal police departments and sheriffs' offices. Software-as-a-service models are replacing capital-intensive server purchases with predictable operational expenditures. California and Texas agencies are pioneering this transition, using federal grant flexibility to fund multi-year platform subscriptions rather than hardware depreciation schedules.
US Evidence Management Market Segmentation
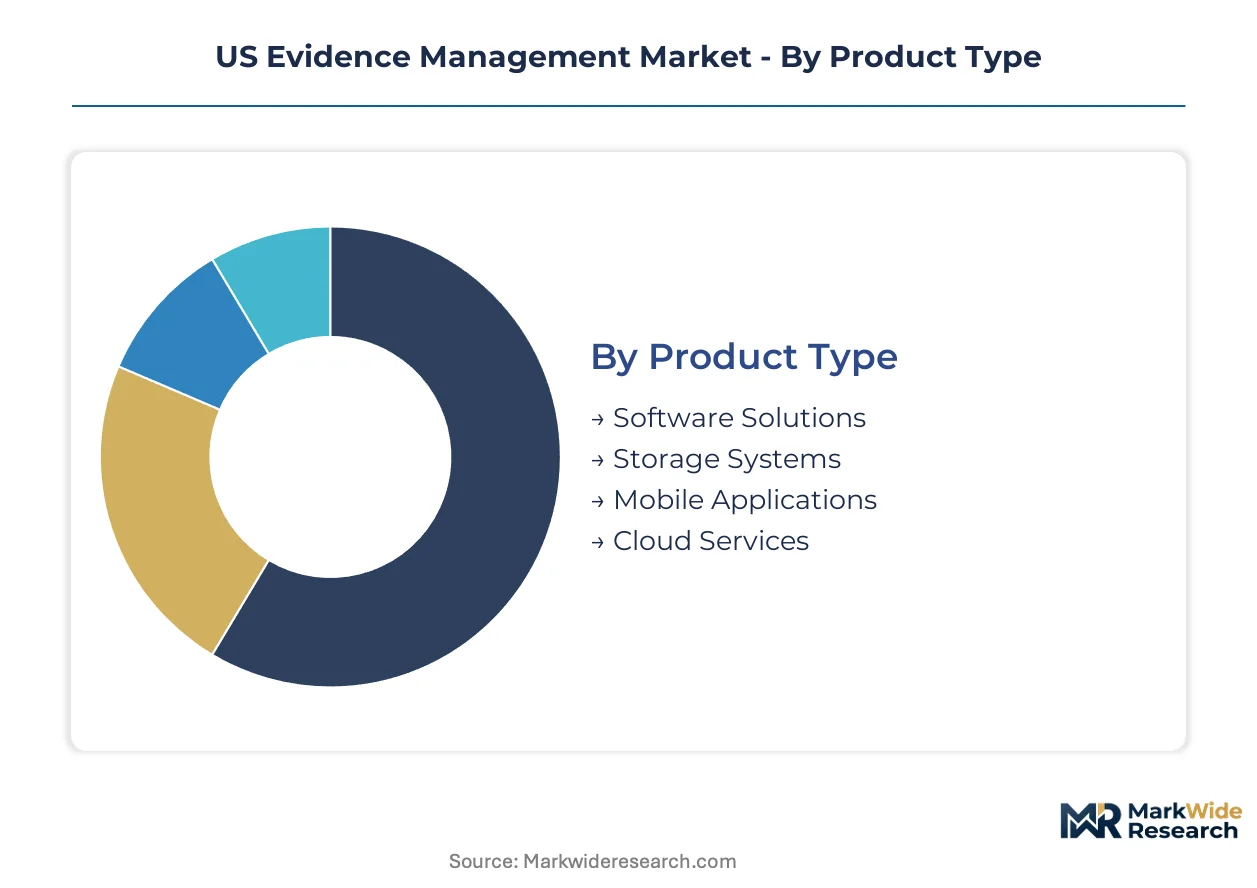
Segmentation in US evidence management reveals how procurement priorities diverge between federal agencies demanding hardened security architectures and municipal departments seeking operational flexibility. The report examines four critical dimensions—product type, end user, deployment model, and underlying technology—to map where investment concentrates and where vendor specialization creates competitive moats.
Product Type:
Standardization dominates at the infrastructure layer while customization proliferates at the application layer, creating a bifurcated procurement landscape where agencies buy commodity storage but demand bespoke workflow software.
- Software Solutions:Chain-of-custody automation platforms with AES-256 encryption and tamper-evident logging form the revenue core. California and Texas agencies are consolidating around enterprise suites that integrate evidence intake, lab analysis tracking, and prosecutor discovery portals under single vendor relationships.
- Storage Systems:On-premises hardware arrays with FIPS 140-2 validated encryption modules serve agencies with CJIS Security Policy audit requirements. County sheriffs in Florida favor these systems for body-worn camera footage retention despite higher capital intensity.
- Mobile Applications:Field evidence capture tools with offline sync capabilities support patrol officers in bandwidth-constrained environments.
- Cloud Services:Elastic object storage with CJIS-compliant access controls converts capital expenditures to operational spending for mid-sized departments.
Leading the category by volume: Software Solutions. Growing fastest: Cloud Services.
End User:
Procurement authority concentrates differently across customer types—federal grant eligibility shapes law enforcement buying patterns while legal firms prioritize discovery-ready export formats over acquisition cost.
- Law Enforcement Agencies:State and local police departments plus sheriffs' offices constitute the demand anchor, with FBI CJIS Security Policy compliance serving as the non-negotiable qualification threshold. Agency consolidation in California, Texas, and Florida is driving enterprise-scale platform replacements.
- Legal Firms:Defense attorneys and prosecutors require evidence management systems with native e-discovery integration and automated redaction workflows. These buyers prioritize audit trail completeness over per-seat licensing costs.
- Government Organizations:District attorneys, public defenders, and court administrators need interagency evidence sharing capabilities with role-based access segmentation.
- Private Security Firms:Corporate security departments and campus police units seek lighter-weight solutions without full CJIS certification overhead.
Dominating procurement volume: Law Enforcement Agencies. Expanding most quickly: Legal Firms.
Deployment:
Cost tier stratification is pronounced—on-premises deployments demand substantial upfront capital while cloud and managed service models shift spending to predictable operational budgets favored by finance-constrained municipalities.
- On-Premises:Dedicated server infrastructure with physical access controls satisfies agencies with stringent data sovereignty requirements. These installations require CJIS Security Policy-compliant security officers and independent audit infrastructure.
- Cloud-Based:Multi-tenant SaaS platforms with CJIS-compliant encryption key management are gaining share fastest among sheriffs' offices in Florida and Texas seeking elastic storage without server farm capital intensity.
- Hybrid:Split architectures keep sensitive evidence on-premises while archiving cold cases to cloud tiers optimize spending across evidence lifecycle stages.
- Managed Services:Outsourced platform operation with vendor-assumed compliance liability appeals to small municipal departments lacking in-house cybersecurity expertise.
Highest revenue concentration: On-Premises. Steepest expansion trajectory: Cloud-Based.
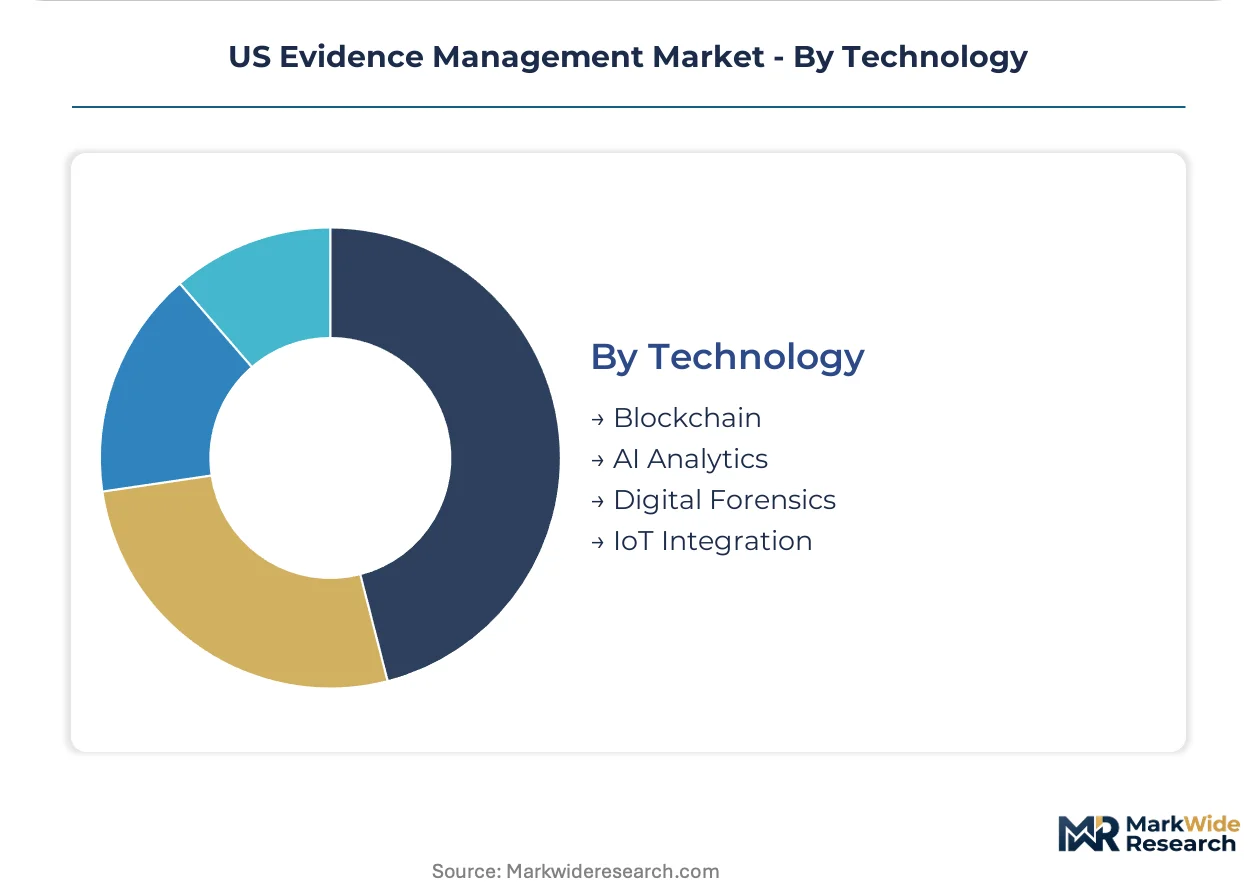
Technology:
Maturity varies sharply—digital forensics represents established practice while blockchain evidence hashing remains experimental, creating a technology adoption curve that segments R&D investment and vendor positioning.
- AI Analytics:Predictive evidence sorting, facial recognition integration, and automated metadata extraction are capturing disproportionate development investment. Prosecutors in high-volume jurisdictions demand these capabilities for workflow acceleration.
- Digital Forensics:Established toolsets for mobile device extraction, network traffic analysis, and deleted file recovery constitute the technology backbone. These systems require specialized examiner certification and chain-of-custody integration.
- Blockchain:Distributed ledger hashing for tamper-evident evidence logging is piloting in federal agencies seeking cryptographic integrity guarantees beyond traditional audit trails.
- IoT Integration:Automated evidence ingestion from body-worn cameras, dashcams, and facility sensors reduces manual logging error rates.
Commanding current investment: Digital Forensics. Gaining share fastest: AI Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise Zone tax incentives in California's Central Valley and Texas Opportunity Zones are accelerating evidence management platform procurement by sheriffs' offices seeking federal grant leverage.
California
Agency consolidation across Los Angeles County and the Bay Area is eliminating redundant evidence systems. The California Public Records Act mandates retention schedules that exceed federal minimums. San Diego's regional crime lab serves as a procurement anchor for cloud-based chain-of-custody platforms.
Texas
Sheriffs' offices in Harris and Dallas counties are migrating terabyte-scale body-worn camera archives to elastic storage models. The Texas Commission on Law Enforcement requires CJIS-compliant training for all evidence custodians. Austin's public safety technology corridor hosts vendor pilot programs for AI analytics integration.
Florida
Municipal police departments in Miami-Dade and Orange County are abandoning server farms for managed service contracts. The Florida Department of Law Enforcement's evidence standards exceed FBI baseline requirements. Tampa Bay's interagency task force operates a shared digital evidence repository serving twelve jurisdictions.
New York
The NYPD's evidence management modernization is driving procurement standards for mid-sized departments statewide. New York State Division of Criminal Justice Services administers grant programs conditioning funding on CJIS Security Policy maturity. Rochester's consolidated public safety campus demonstrates hybrid deployment architecture for cold case archiving.
Illinois
Cook County's evidence integrity scandal has triggered statewide procurement reforms emphasizing audit-grade metadata tagging. The Illinois State Police mandate independent security assessments for all digital evidence platforms. Chicago's regional forensic laboratory sets interoperability standards for prosecutor discovery portal integration.
US Evidence Management Market Competitive Landscape
California-based technology vendors anchor the premium-tier segment; Texas and Florida specialists hold mid-market positions through chain-of-custody workflow expertise. The vendor base stratifies across three tiers: diversified public safety conglomerates, pure-play evidence management software developers, and cloud infrastructure providers seeking CJIS compliance certification. Strategic moves concentrate on agency consolidation capture and federal security clearance acquisition.
Within the diversified technology tier, NICE Ltd and Motorola Solutions Inc. exemplify platform consolidation strategies that bundle evidence management with adjacent public safety communications infrastructure. Oracle Corporation occupies a position among enterprise software providers leveraging existing criminal justice database relationships. These three companies represent contrasting archetypes: federal intelligence community anchoring, mobile-first field capture specialization, and enterprise database integration respectively.
| Leading Market Players |
|---|
| NICE Ltd |
| Omnigo Software LLC |
| Open Text Corporation |
| Hitachi Vantara LLC |
| Panasonic Corporation |
| Motorola Solutions Inc. |
| Oracle Corporation |
| IBM Corporation |
| Axon Enterprise, Inc. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into CJIS-certified data centers anchors both supply security and pricing power for evidence management vendors serving California, Texas, and Florida law enforcement agencies. This captive infrastructure strategy insulates platform providers from third-party cloud compliance bottlenecks while supporting subscription pricing premiums tied to guaranteed audit-grade availability.
Pricing Analysis
Short lead-time premiums for CJIS Security Policy audit readiness command pricing advantages over standard deployment schedules. Three-tier pricing structure across premium, standard, and economy levels separates federal intelligence community deployments from municipal police department subscriptions and rural sheriff office managed services. Price differentiation rests on certification depth and after-sales compliance support intensity. Cost compression in the economy tier is intensifying because cloud infrastructure commoditization erodes hardware margins. Mid-sized municipal departments with 50-200 officers exhibit highest price sensitivity; federal agencies with equitable sharing grant flexibility show lowest.
Supply Chain Analysis
AES-256 encryption hardware supply rests on FIPS 140-2 validated module producers concentrated in the United States, Taiwan, and Germany. Cloud infrastructure draws from hyperscale data center operators with CJIS-compliant physical access controls. Tamper-evident logging components hinge on specialized semiconductor fabrication. Single-source vulnerability in encryption chip supply creates procurement risk during federal security clearance backlogs. Distribution runs through direct vendor-agency relationships with state procurement offices and federal grant administrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CJIS Security Officer certification capacity constraints prop pricing power for vendors with pre-cleared implementation teams, creating supply-constrained vendor selection dynamics across state and local agency procurement cycles.
For Market Incumbents: Anticipate subscription pricing erosion as cloud-native entrants target mid-sized municipal departments with AI-augmented workflow automation. Defensive consolidation moves should emphasize acquiring CJIS-certified implementation specialists in Texas and Florida to tighten service delivery capacity. Channel control through exclusive relationships with state purchasing cooperatives represents the priority lever against margin compression. For New Entrants and Emerging Players: Digital-channel direct sales routes to under-50-officer rural departments bypass incumbent field sales infrastructure. White-space targets include tribal police agencies lacking CJIS compliance expertise and campus security units seeking lighter certification overhead. A CJIS readiness assessment tool offered as lead generation captures procurement timing intelligence before formal RFP release. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified public safety conglomerates seeking federal security clearance portfolios. Long-term viability framing favors vendors with demonstrated equitable sharing grant navigation and prosecutor discovery portal integration. The signal to watch is state-level agency consolidation announcements in California and Texas as inflection indicators for platform replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| CJIS Compliance Certification Investment | FBI Security Policy audit readiness unlocks federal agency procurement eligibility and grant-conditioned state contracts. |
| AI Analytics Platform Integration | Predictive evidence sorting capabilities differentiate vendor positioning for high-volume prosecutor offices in Harris County and Los Angeles. |
| Cloud Migration Partnership Program | Elastic storage conversion agreements with Texas sheriffs' offices transform capital expenditure budgets into recurring subscription revenue. |
| Mid-Market Workflow Specialization | Chain-of-custody automation tailored for 50-200 officer departments captures underserved segment between federal and rural deployments. |
| Interoperability Standards Leadership | Open API architectures reduce vendor lock-in friction during multi-agency task force evidence sharing in Tampa Bay and San Diego regional hubs. |
Research Methodology
Multi-period observation of CJIS Security Policy amendment timelines, federal grant disbursement patterns, and body-worn camera procurement volumes anchored the trend analysis, supplemented by interviews with evidence custodians at state police agencies, CJIS Security Officers, municipal IT directors, prosecutor discovery coordinators, and cloud platform compliance leads. Secondary validation drew from FBI CJIS policy bulletins, Department of Justice equitable sharing program reports, state procurement databases, and vendor CJIS compliance certifications. Bottom-up segment sizing triangulated against top-down federal grant allocation analysis.
Segment-weighting across product type, end user, deployment model, and technology dimensions structured the analytical framework over the projection horizon. Deployment model splits between on-premises, cloud-based, hybrid, and managed services captured infrastructure transition dynamics. Technology weighting emphasized AI analytics adoption curves against established digital forensics baselines. CAGRs derived from elasticity-adjusted demand modeling incorporating grant funding volatility and agency consolidation announcements. Forecast inputs included body-worn camera shipment projections and CJIS audit backlog durations.
The model holds under stable federal grant funding and CJIS policy implementation timelines; deviation in congressional appropriations cycles or accelerated Security Policy amendment schedules would shift deployment trajectory assumptions. Forecasts reflect documented assumptions regarding agency consolidation pace and cloud compliance certification velocity. A small set of named triggers warrants ongoing watch: FBI CJIS Security Policy revision announcements, state-level public records retention statute changes, and hyperscaler CJIS compliance certification status.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Digital Credential Management Software Market
Security Software
Cloud File Security Software Market
Security Software
United States Consumer Identity and Access Management Market
Security Software
Data Leakage Prevention Product Market
Security Software
Global Enterprise Key Management Market
Security Software
Security Software Market
Security Software
GDPR Software and Tools Market
Security Software
Endpoint Detection and Response Market
Security Software
Application Control Software Market
Security Software
Global Optical Encryption Market
Security Software
Facial Recognition Market
Security Software
Global Background Check Software Market
Security Software
Quantum Key Distribution System Market
Security Software
Global Data Breach Notification Software Market
Security Software
Europe Smart Doorbell Market
Security Software
Secure Digital Card Market