
 Saudi Arabia Managed Security Services Market | 2026-2036
Saudi Arabia Managed Security Services Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Managed Security Services Market Insights
Market Dynamics
Mid-market enterprises is collapsing as the dominant buyer archetype while large government and critical infrastructure contracts command disproportionate vendor attention. STC Group leverages its sovereign telecom infrastructure to anchor managed security offerings across state-backed entities. Palo Alto Networks competes through specialized threat intelligence platforms calibrated for Gulf Cooperation Council threat environments. Check Point Software Technologies dominates the perimeter appliance layer with hardware-integrated managed services deployed at Saudi Aramco facilities.
Segmentation Structure
Managed security services encompass continuous monitoring, threat detection, incident response, and compliance management delivered through subscription-based outsourcing arrangements, typically integrating SIEM, SOAR, and EDR platforms with 24/7 security operations center oversight. Cloud Security commands the fastest expansion trajectory as Saudi organizations migrate workloads to sovereign and hyperscale cloud environments under NCA cloud security requirements. Network Security retains the largest revenue pool due to persistent perimeter investment across oil and gas infrastructure. The Government end-user segment occupies premium pricing tiers given classified workload handling mandates and domestic data residency stipulations.
Regulatory Environment
The National Cybersecurity Authority (NCA) enforces mandatory cybersecurity controls for critical national infrastructure, directly shaping procurement specifications and vendor qualification criteria across the Kingdom. SAMR and SDAIA interoperability standards, alongside NCA Essential Cybersecurity Controls, force foreign providers to localize operations and partner with Saudi-registered entities. Stakeholders must monitor evolving NCA compliance tier expansions beyond critical infrastructure into healthcare and manufacturing verticals.
Market Dynamics
The National Cybersecurity Authority's Essential Cybersecurity Controls framework is compressing procurement cycles while mandating sovereign data handling, forcing foreign MSS providers to localize operations through Saudi-registered partnerships or lose eligibility for critical infrastructure contracts.
Growth Catalysts
- NCA ECC Mandate:The Essential Cybersecurity Controls framework compels critical infrastructure operators to outsource security monitoring to qualified providers, creating guaranteed demand pools in energy and finance sectors.
- Cloud Migration Acceleration:Saudi Aramco and SABIC are migrating operational technology workloads to sovereign cloud environments, requiring continuous compliance validation that only MSSPs with local Security Operations Centers can deliver.
- SDAIA Data Governance:The Saudi Data and Artificial Intelligence Authority's cross-border data restrictions are forcing multinationals to establish in-Kingdom security operations rather than rely on regional hubs in Dubai or Singapore.
Market Restraints
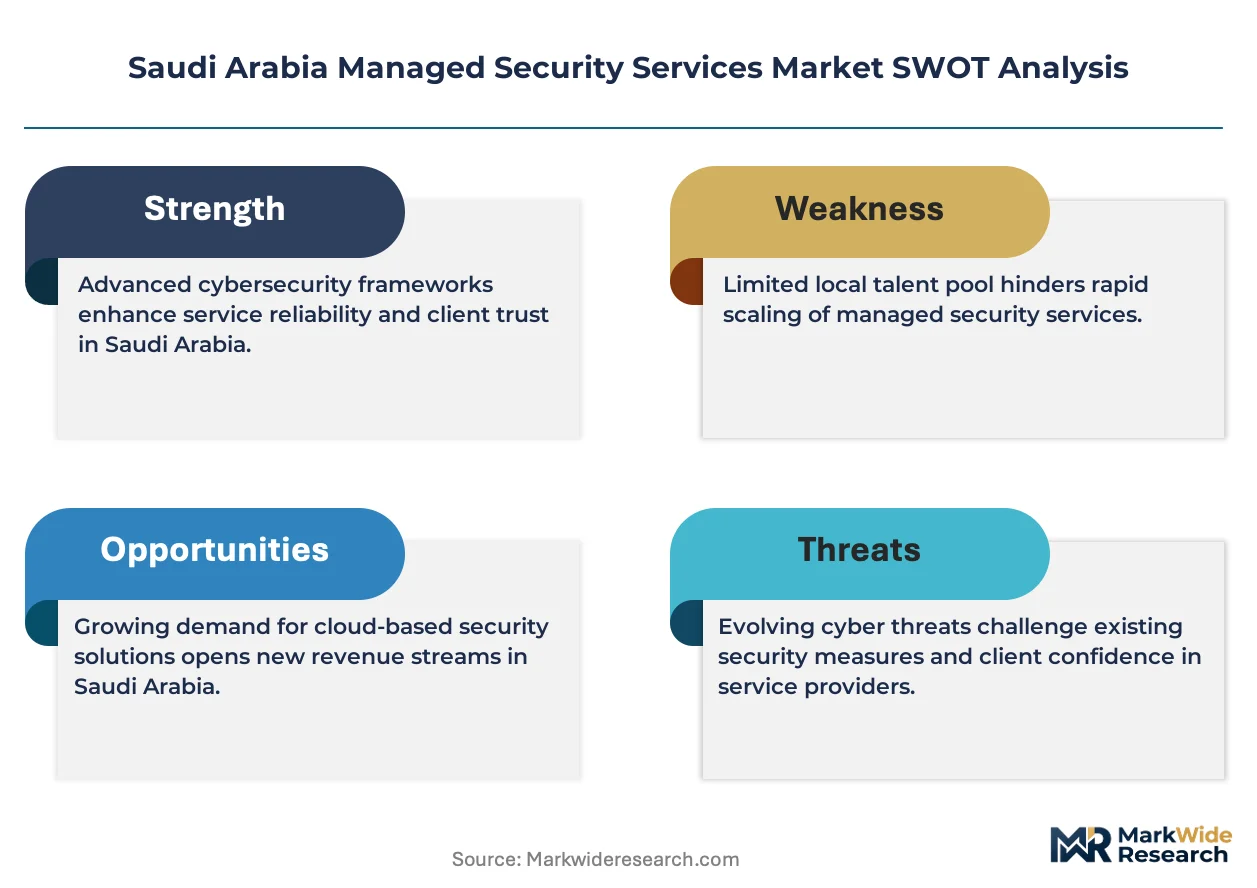
- Certified Talent Scarcity:The domestic pipeline of CISSP and GCIH-certified analysts remains insufficient relative to SOC expansion requirements, inflating personnel costs for 24/7 coverage mandates.
- Hardware Dependency:Perimeter security deployments at oil and gas facilities require specialized industrial control system appliances with extended procurement lead times from European and North American suppliers.
- Localization Requirements:NCA vendor qualification criteria effectively exclude pure-play foreign MSSPs without Saudi joint venture structures, limiting competitive pressure on incumbent pricing.
Strategic Opportunities
- Healthcare Vertical Expansion:NCA compliance tier extensions into healthcare will compel hospital networks in Jeddah and the Eastern Province to adopt managed detection and response services for patient data protection.
- OT Security Convergence:The intersection of IT security operations with industrial control system monitoring creates white space for providers capable of unified visibility across enterprise and operational technology environments.
- Neom Infrastructure Pre-positioning:The giga-project's zero-trust architecture specifications offer first-mover positioning for MSSPs willing to embed security operations into city-scale digital infrastructure construction phases.
Industry Challenges
- Multivendor Integration Complexity:Saudi enterprises typically operate heterogeneous security stacks combining legacy Check Point appliances with cloud-native tooling, complicating unified telemetry and response orchestration.
- Cleared Personnel Vetting:Government segment contracts require security clearance processes that extend onboarding timelines for foreign-national analysts, constraining SOC staffing flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Managed Security Services Market |
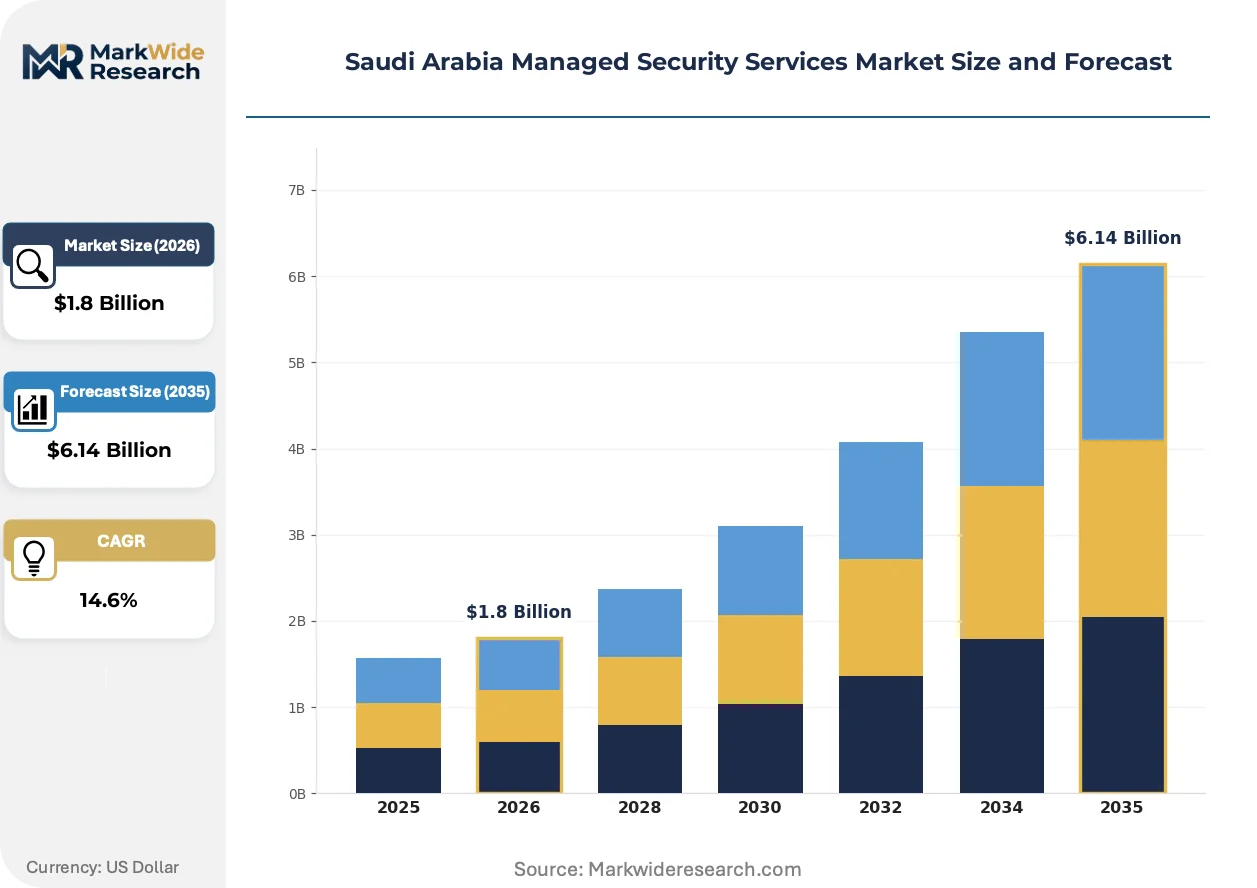
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Network Security, Endpoint Security, Cloud Security, Application Security Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed End User: Healthcare, BFSI, Government, Manufacturing Security Layer: Perimeter Security, Application Layer Security, Data Security, Identity Management |
| Companies Covered | STC Group, International Business Machines Corporation, Cisco Systems, Inc., Palo Alto Networks, Saudi Information Technology Company (SITE), Capgemini SE, Accenture PLC, Check Point Software Technologies, Fortinet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Managed Security Services Market Trends and Innovations
Generative AI capabilities are compressing threat detection latency while regulatory pressure on data sovereignty is fragmenting service delivery architectures across the Kingdom's economic zones.
Extended Detection and Response platforms are bifurcating the MSS landscape between consolidated vendors offering native endpoint, network, and cloud telemetry, and specialized providers integrating third-party signals through open APIs. Mid-market financial institutions in Riyadh are adopting hybrid XDR deployments faster than oil sector counterparts due to lighter legacy infrastructure burdens. This technology convergence is compressing margins for pure-play network monitoring specialists while elevating providers with unified data lake architectures.
NCA cloud security requirements are mandating encryption key custody within Saudi territorial boundaries, forcing hyperscale providers to establish dedicated sovereign cloud regions with localized encryption management. The regulation compels foreign MSSPs to deploy in-country Security Operations Centers rather than deliver remotely from regional hubs. Financial services and government segments are responding by prioritizing providers with demonstrated NCA audit compliance over technical feature differentiation.
Subscription contracting for security outcomes is displacing traditional device-based pricing as Saudi Aramco and STC Pay negotiate guaranteed mean-time-to-detect metrics with financial penalties. This model transfers operational risk to MSSPs while compressing upfront implementation fees into recurring performance-based structures. The shift is most visible in Riyadh's banking sector, where digital wallet providers prioritize outcome-based partnerships over conventional managed firewall arrangements.
Saudi Arabia Managed Security Services Market Segmentation
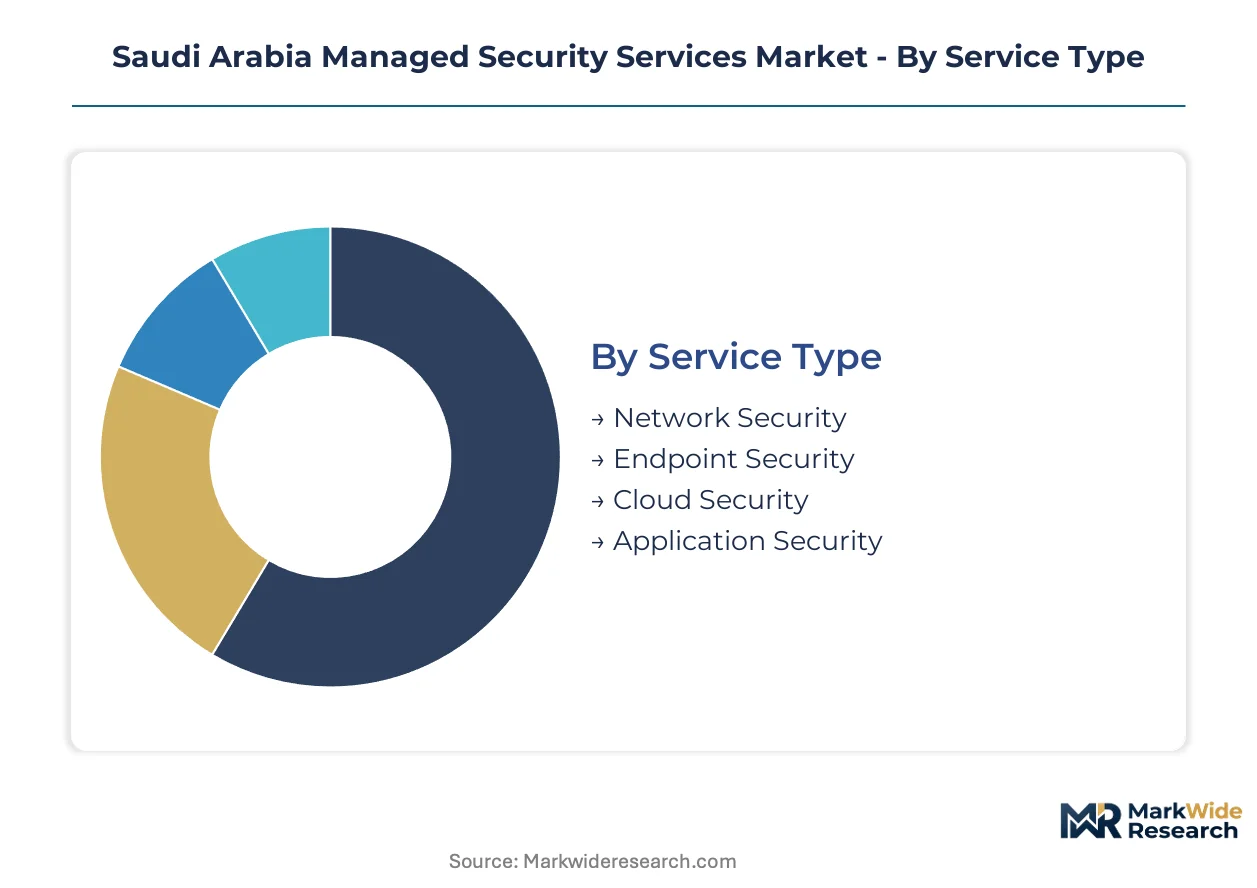
Segmentation in Saudi Arabia's managed security services market reveals how NCA compliance mandates and sovereign data requirements reshape vendor economics across service delivery models. Each category exposes distinct margin pressures and procurement patterns that determine competitive positioning.
Service Type:
Margin pools concentrate in continuous monitoring and threat detection services where 24/7 SOC coverage commands premium pricing from critical infrastructure operators.
- Network Security:Perimeter monitoring and firewall management services dominate revenue pools across oil and gas facilities. Saudi Aramco's industrial control environments sustain demand for specialized network segmentation and intrusion detection systems with extended hardware refresh cycles.
- Cloud Security:Sovereign cloud migration under NCA requirements is accelerating demand for encryption key custody and compliance validation services. Riyadh-based financial institutions prioritize cloud-native security operations centers over legacy perimeter models as digital banking scales.
- Endpoint Security:EDR platform management and device monitoring services address remote workforce expansion across mid-market enterprises.
- Application Security:Code scanning and runtime protection services support fintech application deployment in regulated environments.
Network Security holds installed capacity. Cloud Security is rotating up the share rankings.
Deployment Model:
Cost tier differentiation separates sovereign-mandated in-country operations from regional hub delivery, with hybrid architectures capturing middle-market budgets.
- Cloud-Based:Fully outsourced security operations delivered from hyperscale environments with localized data residency. STC Pay and digital wallet providers favor this model for rapid scaling without capital deployment.
- Hybrid:Split architectures combining on-premises SIEM with cloud-native analytics platforms. Manufacturing verticals in Jubail Industrial City adopt hybrid models to preserve OT network isolation while gaining threat intelligence scale.
- On-Premises:Dedicated appliance and software deployments at classified government facilities with air-gapped security operations.
- Managed:Fully outsourced SOC-as-a-service with guaranteed SLA structures and outcome-based contracting terms.
Hybrid deployments retain the largest customer count. Cloud-Based delivery is climbing the fastest as sovereign cloud regions mature.
End User:
Application intensity varies sharply across verticals, with government and BFSI segments absorbing premium pricing for cleared personnel and classified handling protocols.
- Government:National security and critical infrastructure agencies mandate domestic data residency and Saudi-cleared analysts. NCA qualification requirements restrict vendor pools and sustain margin premiums for qualified providers.
- BFSI:SAMA-regulated banks and emerging fintechs drive demand for fraud detection and digital identity protection. Riyadh's banking sector leads adoption of subscription-based outcome contracting with MTTD guarantees.
- Healthcare:Hospital networks in Jeddah and the Eastern Province face emerging NCA compliance tier extensions for patient data protection.
- Manufacturing:SABIC and petrochemical operators require converged IT-OT security monitoring for operational technology environments.
Government commands premium pricing tiers. BFSI is gaining share fastest as digital banking infrastructure expands.
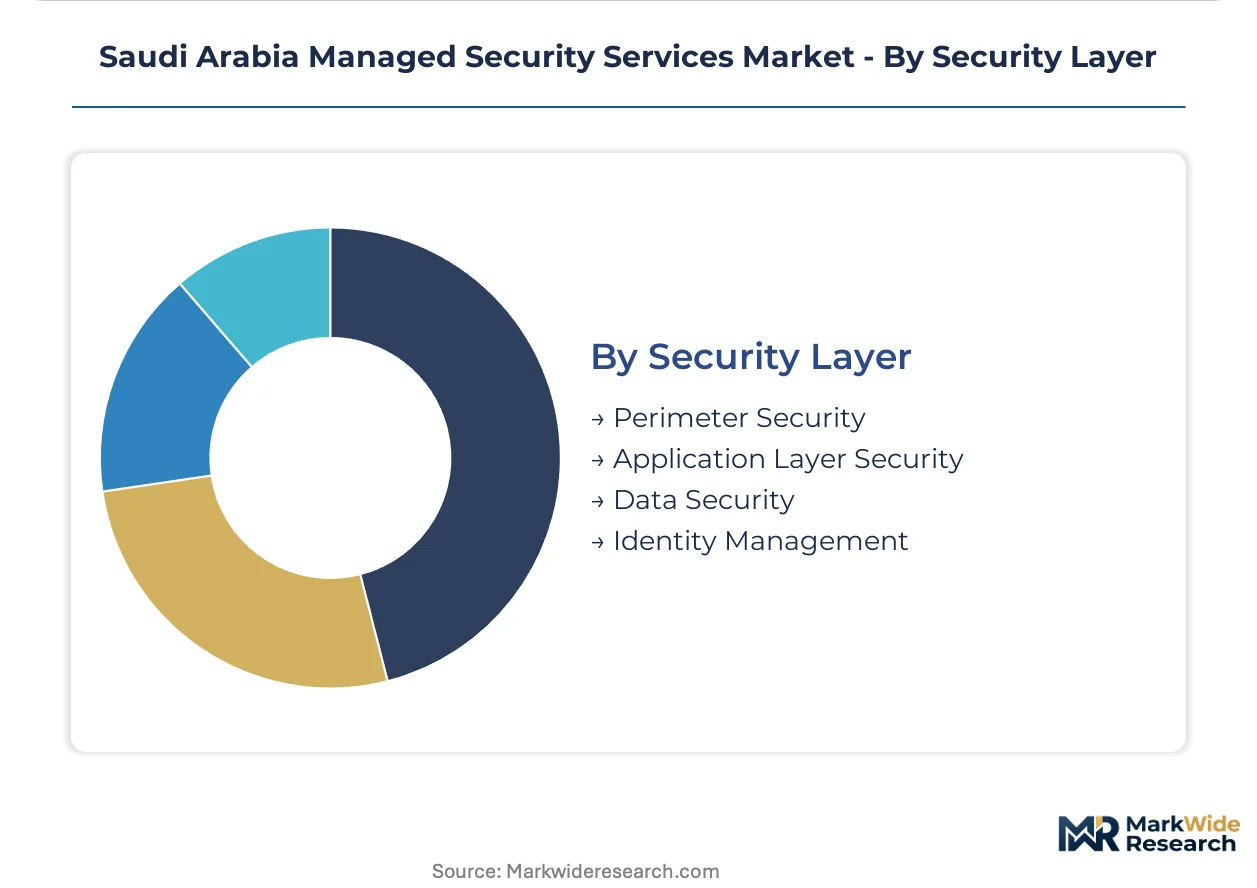
Security Layer:
Maturity gradients separate established perimeter markets from emerging identity-centric architectures, with data security investments accelerating under SDAIA governance rules.
- Data Security:Encryption management, data loss prevention, and classification services address SDAIA cross-border restrictions. Financial services prioritize providers with demonstrated key custody within Saudi territorial boundaries.
- Identity Management:Privileged access management and zero-trust architecture implementations support Neom's city-scale digital infrastructure specifications.
- Perimeter Security:Firewall and intrusion prevention system management retains largest revenue base across legacy oil and gas installations.
- Application Layer Security:Web application firewalls and API protection services secure digital payment platforms and government e-services portals.
Perimeter Security maintains the deepest installed base. Data Security is expanding most quickly under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports managed security services expertise across the Gulf Cooperation Council, with Riyadh-based providers delivering NCA-compliant operations to UAE and Kuwaiti critical infrastructure operators under cross-border service frameworks.
Riyadh
The capital region concentrates government security procurement under NCA direct oversight, with SAMA-regulated banks driving subscription-based outcome contracting. STC Group anchors sovereign cloud security operations from Riyadh data centers serving state-backed entities. Digital wallet providers and fintech clusters in King Abdullah Financial District prioritize MTTD-guaranteed partnerships over conventional firewall management.
Eastern Province
Saudi Aramco's industrial control environments sustain specialized network segmentation demand across Jubail and Ras Tanura facilities. Petrochemical operators require converged IT-OT security monitoring for operational technology workloads migrating to sovereign cloud. SABIC facilities drive hardware-integrated managed services with extended appliance refresh cycles from European suppliers.
Western Region
Jeddah hospital networks face emerging NCA compliance tier extensions for patient data protection as healthcare cybersecurity mandates expand. The Red Sea coastal corridor hosts maritime logistics operators adopting hybrid security architectures. King Abdullah Economic City attracts MSSPs positioning for financial services diversification beyond Riyadh's concentration.
NEOM Northwest
The giga-project's zero-trust architecture specifications create first-mover positioning for providers embedding security operations into city-scale digital infrastructure construction. NEOM's data sovereignty requirements mandate localized encryption key custody and Saudi-cleared analyst pools. Smart city deployments prioritize identity-centric architectures over legacy perimeter models.
Saudi Arabia Managed Security Services Market Competitive Landscape
Player mix skews toward telecom-captive providers and global platform specialists competing through NCA qualification pathways. Market structure concentrates around sovereign-anchored incumbents with critical infrastructure clearances and foreign specialists forced into joint venture structures. Strategic archetypes include state-backed telecom integrators, global cybersecurity platforms with localized delivery, and regional IT services firms with NCA audit credentials. Dominant competitive moves encompass Saudi joint venture formation for foreign entrants and SOC capacity expansion in Riyadh to capture government segment premiums.
Among Riyadh-based providers, STC Group exemplifies the telecom-captive archetype leveraging sovereign infrastructure across state contracts. Global platform specialists Palo Alto Networks and Check Point Software Technologies occupy positions requiring localization partnerships for NCA eligibility. Accenture PLC and Capgemini SE represent the IT services tier adapting regional delivery models to sovereign data requirements.
| Leading Market Players |
|---|
| STC Group |
| International Business Machines Corporation |
| Cisco Systems, Inc. |
| Palo Alto Networks |
| Saudi Information Technology Company (SITE) |
| Capgemini SE |
| Accenture PLC |
| Check Point Software Technologies |
| Fortinet |
| Others |
Pricing and Supply Chain Analysis
Outcome-based subscription contracts lock in multi-year revenue visibility for qualified providers while anchoring price floors through guaranteed MTTD performance metrics and NCA compliance tier premiums. This structure concentrates procurement power among STC Group and SITE for critical infrastructure segments while compressing margins for non-qualified foreign entrants.
Pricing Analysis
Next-generation XDR platforms command 40-60% premiums over legacy SIEM-managed services due to unified telemetry architectures and automated response orchestration. Three-tier pricing structure across premium, standard, and economy levels separates government-cleared operations from commercial mid-market offerings and basic monitoring tiers. Pricing pressure stems from certified analyst scarcity inflating personnel costs for 24/7 SOC coverage mandates. Mid-market enterprises exhibit highest price sensitivity, while government agencies absorb premium tiers for domestic data residency and cleared personnel requirements.
Supply Chain Analysis
Extended hardware lead times from European and North American suppliers constrain perimeter appliance deployments at Saudi Aramco and SABIC facilities, stretching refresh cycles to 36-48 months. Component sourcing draws from Taiwan for semiconductors, Germany for industrial control system hardware, and the United States for specialized threat intelligence platforms. Single-source vulnerability concentrates in SIEM and SOAR platform licensing from Palo Alto Networks and IBM. Distribution runs through Riyadh-based system integrators with NCA audit credentials for final-mile deployment and sovereign data handling compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's managed security services market represents early-cycle expansion as NCA compliance tier extensions penetrate healthcare and manufacturing verticals previously outside mandatory cybersecurity controls. Sovereign data requirements and localization mandates create structural tailwinds for domestic-anchored providers.
For Market Incumbents: Secure NCA qualification expansions into emerging healthcare compliance tiers before foreign joint ventures achieve certification velocity. Defend government segment positioning through SOC capacity expansion in Riyadh and Eastern Province hubs, countering emerging competition from UAE-based providers with Saudi-registered partnerships.
For New Entrants and Emerging Players: Lead with specialized OT security convergence capabilities targeting SABIC and petrochemical operators in Jubail Industrial City, where unified IT-OT visibility remains underserved. Prioritize healthcare vertical entry through MDR services for Jeddah hospital networks facing imminent NCA tier extensions, leveraging cloud-native delivery to bypass legacy infrastructure disadvantages.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap regional IT services firms with existing NCA audit credentials and Saudi-cleared analyst pools, positioned for consolidation into platform specialists. Long-term viability hinges on regulatory compliance moats rather than technical feature differentiation. Monitor NEOM infrastructure procurement announcements as inflection indicators for zero-trust architecture adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Saudi Joint Venture Formation | NCA qualification eligibility unlocks critical infrastructure contract access for foreign MSSPs. |
| SOC Capacity Expansion | Riyadh-based operations centers capture government segment premiums and cleared personnel pools. |
| OT Security Capability Buildout | Unified IT-OT visibility addresses SABIC and Saudi Aramco operational technology convergence requirements. |
| Healthcare Vertical Pre-positioning | Early MDR deployment captures Jeddah hospital networks before NCA tier extension enforcement. |
| Neom Infrastructure Partnership | Zero-trust architecture embedding secures long-term city-scale security operations contracts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with CISOs at SAMA-regulated banks, NCA compliance officers, SOC operations directors, and procurement leads at Saudi Aramco and SABIC facilities; and secondary validation through SAMA regulatory circulars, NCA Essential Cybersecurity Controls documentation, SEC filings from listed cybersecurity vendors, hyperscaler sovereign cloud region announcements, and customs data on security appliance imports. Bottom-up service line sizing triangulated against top-down addressable market estimates.
Across the analysis window, the forecast framework modeled service type segmentation, deployment model adoption curves, end-user vertical penetration rates, and security layer investment intensity. CAGRs derived from regression analysis of historical procurement patterns and regulatory mandate implementation timelines. Specific inputs included NCA compliance tier expansion schedules, sovereign cloud region capacity announcements, and certified analyst pipeline projections from Saudi vocational training programs.
Underlying assumptions cover NCA enforcement consistency, sovereign cloud region delivery timelines, and certification program scaling, with deviation risk concentrated in regulatory timeline acceleration or delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Privacy Management Software Market
Security Software
Robocall Mitigation Market
Security Software
Secure Web Gateway Market
Security Software
Global Reputation Protection Software Market
Security Software
Private Virtual Communications for Police Network Market
Security Software
Software Protection Dongle Market
Security Software
Global Enterprise Data Loss Prevention Software Market
Security Software
User Provisioning Software Market
Security Software
Global Data Masking Market
Security Software
Sound Masking Systems Market
Security Software
Content Protection and Watermarking Market
Security Software
Website Monitoring Software Market
Security Software
Personal Data Recovery Software Market
Security Software
Cybersecurity Software Market
Security Software
North America Secure Access Service Edge Market
Security Software
Cloud Encryption Software Market