
 ATM Security Market | 2026-2036
ATM Security Market Size, Share, and Industry Trends Forecast 2026-2036
ATM Security Market Analysis
Banking sector deployment of intelligent ATM terminals is expanding as financial institutions replace aging machines with integrated biometric and encryption-ready platforms. Diebold Nixdorf leverages its manufacturing scale to dominate North American and European upgrade cycles. NCR Corporation sustains R&D intensity in cloud-connected security architectures. Fujitsu anchors Asian supply chains through specialized hardware production for regional banks.
ATM security encompasses physical and electronic protection systems designed to safeguard automated teller machines against fraud, theft, and cyber intrusion, typically incorporating hardened enclosures, anti-skimming sensors, encrypted PIN pads, and real-time network monitoring with response thresholds under 50 milliseconds. The primary purpose is to preserve cash integrity and consumer trust in self-service banking channels. Encryption modules command premium margins as PCI DSS 4.0 mandates drive hardware refresh demand across financial institutions. Biometric readers represent the fastest-growing product category as fingerprint and iris recognition displace legacy card-only authentication. Cloud-based solutions within the technology dimension are displacing on-premise management consoles as banks pursue centralized threat visibility.
FDA standards for biometric data handling, PCI Security Standards Council encryption protocols, and the EU Digital Operational Resilience Act collectively shape product certification requirements and procurement eligibility for ATM security vendors. India's BIS certification and RBI cybersecurity guidelines add further compliance layers for equipment deployed in emerging markets. Stakeholders must monitor regulatory divergence between biometric privacy regimes and payment network mandates when prioritizing R&D investment and geographic market entry sequencing.
Market Dynamics
Biometric authentication is forcing wholesale replacement of legacy card-only ATM fleets as financial institutions confront PCI DSS 4.0 compliance deadlines and escalating fraud sophistication. This hardware refresh cycle concentrates procurement authority at regional bank consortiums rather than individual branch managers.
Growth Catalysts
- RBI cybersecurity guidelines:India's central bank mandates end-to-end encryption for all new ATM deployments, accelerating rural network expansion with hardened terminals.
- Fingerprint recognition modules:Brazilian banks deploy biometric readers across metropolitan ATM networks to combat card-skimming syndicates operating in São Paulo and Rio de Janeiro.
- German savings bank consolidation:Sparkassenverbund procurement pools drive standardized security specifications across 5,700 branch locations.
Market Restraints
- Semiconductor supply concentration:Encryption chip fabrication concentrates in Taiwan and South Korea, exposing ATM OEMs to geopolitical supply disruption.
- Biometric data storage costs:GDPR-compliant iris template databases require redundant EU-based server infrastructure, elevating total cost of ownership.
- Copper and hardened steel prices:Physical enclosure materials face commodity volatility that compresses hardware margins.
Strategic Opportunities
- Cloud-based threat monitoring:Indian regional banks bypass on-premise security operations centers through centralized SaaS platforms.
- Iris recognition convergence with contactless cards:Hybrid authentication protocols open premium positioning for next-generation terminals in Germany.
- Rural Brazil penetration:Banco do Brasil and Caixa Econômica Federal expand ATM networks into municipalities below 50,000 population with fraud-resistant biometric units.
Industry Challenges
- PCI DSS 4.0 certification timelines:Hardware validation cycles stretch 18-24 months, compressing deployment windows for compliance-mandated upgrades.
- Legacy mainframe integration:Biometric authentication protocols require middleware development to interface with 1980s-era core banking systems prevalent in German Landesbanken.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ATM Security Market |
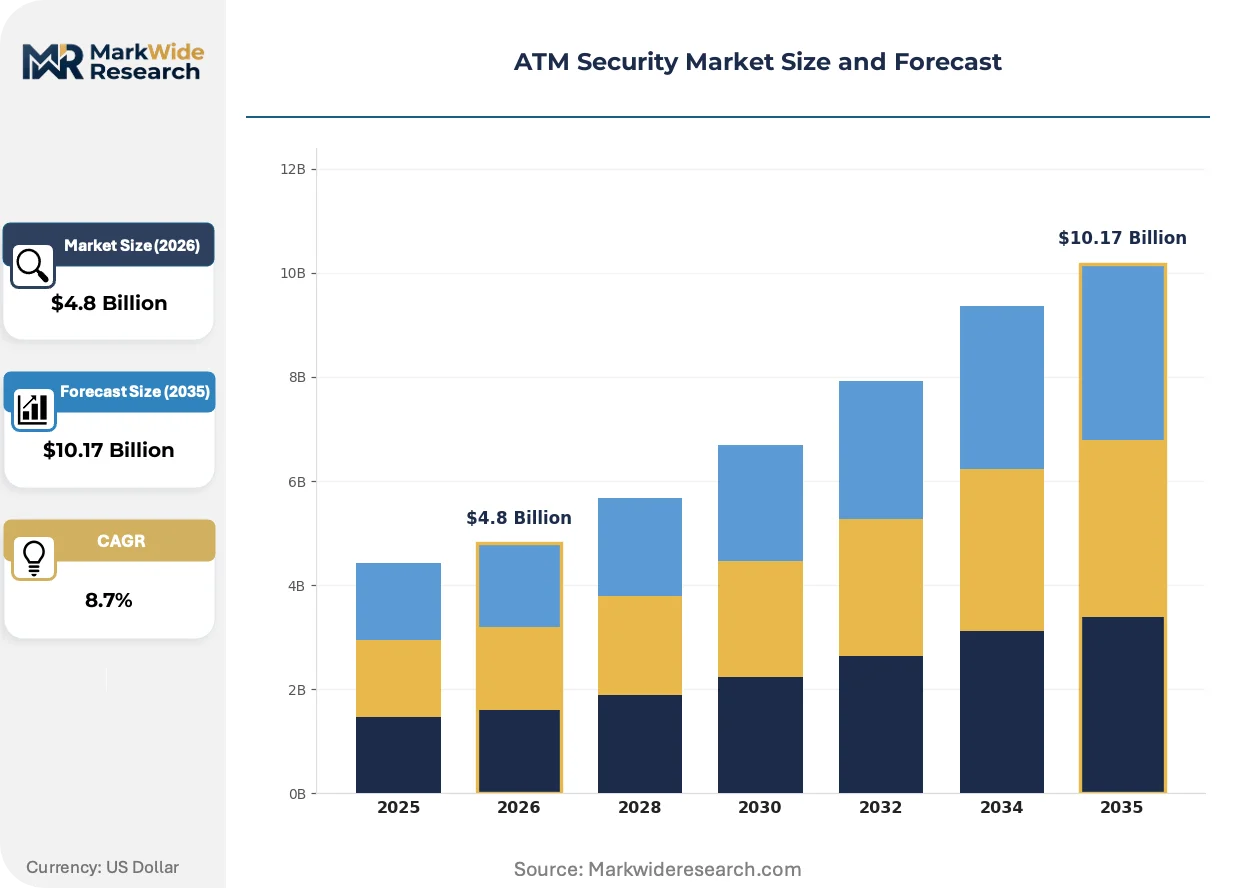
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Skimming Devices, Biometric Readers, Encryption Modules, Surveillance Cameras Technology: Card Security, PIN Encryption, Network Security, Cloud-Based Solutions End User: Financial Institutions, Retailers, Independent Operators, Government Agencies Installation Type: New Installations, Upgrades, Remote Installations, On-site Maintenance |
| Companies Covered | Diebold Nixdorf, NCR Corporation, Fujitsu, GRG Banking, Hyosung TNS, Hitachi, Euronet USA, Triton, KAL ATM Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ATM Security Market Emerging Trajectories
Real-time network monitoring architectures are reshaping how financial institutions detect and neutralize ATM-targeting attacks before cash compromise occurs. Three developments dominate vendor R&D roadmaps.
Edge computing security modules process transaction anomalies locally rather than routing alerts through centralized data centers. Brazilian banks deploy these units across high-crime neighborhoods in São Paulo to achieve sub-50 millisecond response thresholds. This distributed architecture is electrifying competitive positioning for suppliers with embedded systems expertise.
The EU Digital Operational Resilience Act mandates ATM network operators maintain 24-hour recovery capabilities from cyber incidents. Hardware manufacturers must certify business continuity specifications before qualifying for European procurement tenders. German and French banking regulators enforce these standards through quarterly resilience testing protocols.
Service contracting has migrated from per-incident maintenance to subscription-based security operations. Indian private-sector banks unbundle hardware purchase from ongoing threat monitoring, shifting vendor relationships toward recurring revenue models. This restructuring concentrates purchasing decisions at chief information security officer level rather than facilities management.
ATM Security Market Segmentation
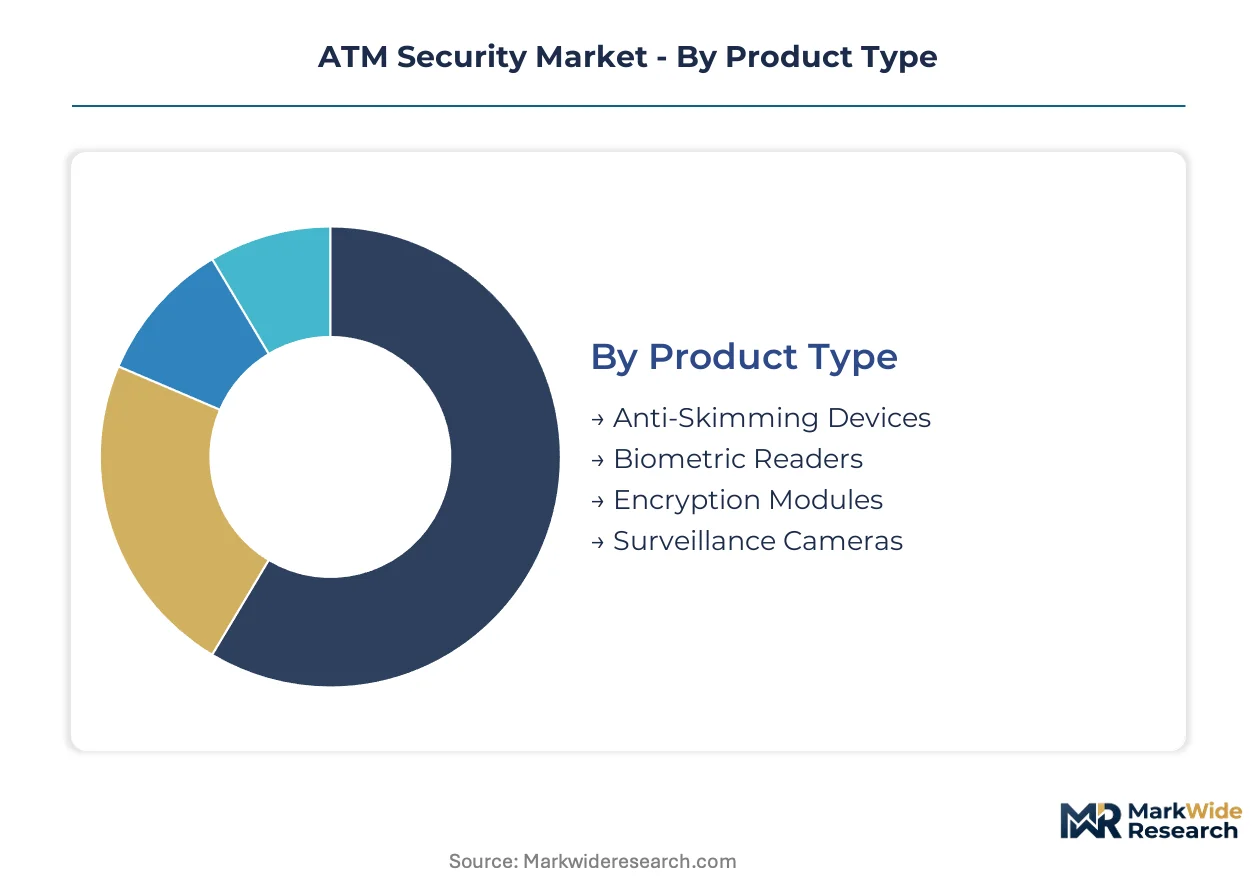
ATM security procurement patterns diverge sharply across product architectures, deployment models, and buyer risk profiles. Understanding these segment boundaries clarifies where hardware margins concentrate versus where service contracts dominate revenue.
Product Type:
Buyers in this category sort by compliance urgency versus fraud exposure severity, with PCI DSS deadlines driving encryption module priority and biometric mandates reshaping authentication infrastructure.
- Anti-Skimming Devices:Magnetic stripe readers with electromagnetic shielding and jitter mechanisms disrupt card-cloning hardware. Brazilian banks deploy these across São Paulo metropolitan ATMs where skimming syndicates operate most aggressively, with ANVISA procurement standards mandating certified installation.
- Biometric Readers:Fingerprint and iris recognition sensors replace card-only authentication through capacitive or optical imaging arrays. Indian regional banks under RBI guidelines purchase these for rural network expansion, with BIS certification requirements filtering supplier eligibility.
- Encryption Modules:Hardware security modules meeting PCI DSS 4.0 standards for PIN and transaction data protection. German Sparkassen procurement pools standardize these specifications across consolidated branch networks.
- Surveillance Cameras:IP-connected cameras with facial recognition analytics and tamper detection. Retail banking deployments in India favor these for unmanned rural terminals.
Volume sits with encryption modules; growth tilts toward biometric readers.
Technology:
Technology selection tracks infrastructure maturity, with cloud adoption accelerating most quickly where legacy mainframe dependency is weakest.
- Card Security:EMV chip validation, dynamic CVV generation, and contactless NFC protocols. Brazilian metropolitan banks prioritize these for card-present transaction integrity.
- PIN Encryption:Triple-DES and AES-256 hardware encryption for keypad entry. German savings banks require these modules for all new terminal deployments under federal banking association standards.
- Network Security:Intrusion detection systems and VPN tunneling for ATM-to-host communication. Indian banks deploy these under RBI cybersecurity guidelines mandating end-to-end encryption.
- Cloud-Based Solutions:Centralized threat monitoring platforms with SaaS delivery models. Private-sector banks in India bypass on-premise security operations centers through these subscription architectures.
Network security commands the largest installed base; cloud-based solutions are climbing the fastest.
End User:
End-user segments separate by regulatory scrutiny intensity and cash-handling volume, with financial institutions facing the strictest certification requirements.
- Financial Institutions:Commercial banks, credit unions, and cooperative banks operating proprietary ATM fleets. These buyers concentrate procurement authority at regional consortium levels in Germany and India.
- Retailers:Supermarket chains and convenience stores operating white-label ATMs. Brazilian retail networks deploy biometric-enabled terminals to reduce cash-handling fraud.
- Independent Operators:Third-party ATM deployers unaffiliated with specific financial institutions. These operators in India favor cloud-managed security to minimize on-site technical staffing.
- Government Agencies:Postal banks and state-owned financial institutions. Banco do Brasil and Caixa Econômica Federal drive rural penetration with fraud-resistant biometric units.
Financial institutions dominate current spending; independent operators show the steepest expansion trajectory.
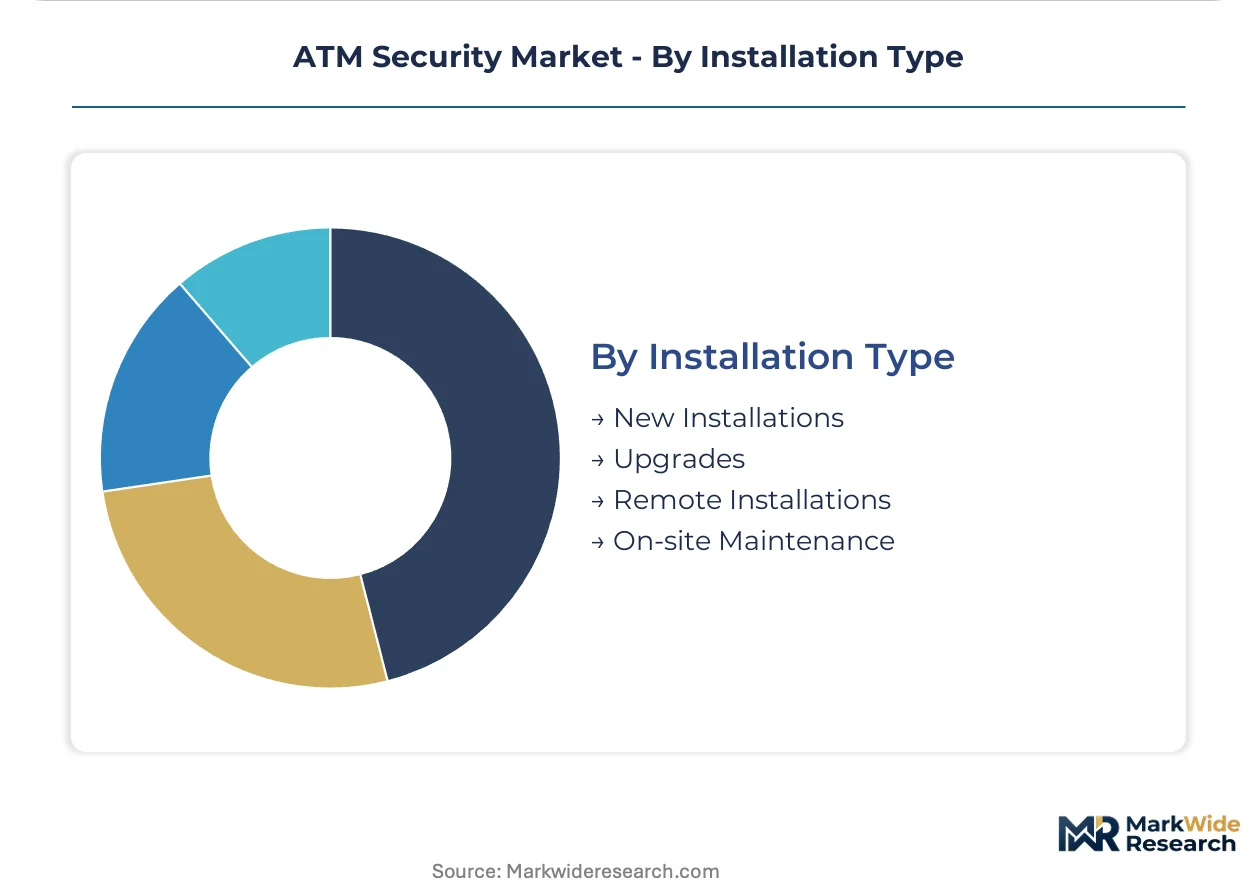
Installation Type:
Installation economics hinge on legacy fleet age and regulatory deadline proximity, with upgrade cycles accelerating where compliance mandates are tightest.
- New Installations:Complete terminal deployment with integrated security subsystems. Rural India and Brazil below-50,000-population municipalities drive this segment.
- Upgrades:Retrofit of biometric readers, encryption modules, or anti-skimming hardware into existing terminals. German Sparkassen consolidation creates standardized upgrade specifications across thousands of branches.
- Remote Installations:Unmanned deployment with centralized monitoring. Indian regional banks favor these for cost-efficient rural network expansion.
- On-site Maintenance:Physical servicing of security hardware with technician dispatch. Brazilian high-crime neighborhoods require rapid-response maintenance contracts.
Upgrades represent the largest near-term volume; remote installations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ATM security equipment production concentrates in Germany, Japan, and Taiwan, while deployment demand concentrates in India, Brazil, and Germany as these markets expand rural banking access and modernize urban fleets.
India
Rural ATM network expansion and RBI cybersecurity guidelines drive procurement of biometric-enabled terminals with end-to-end encryption. The central bank mandates hardened security specifications for all new deployments, accelerating replacement cycles. Regional banks in Maharashtra and Karnataka concentrate procurement authority for standardized rural terminal rollouts.
Brazil
Metropolitan anti-fraud upgrades and government-backed financial inclusion programs fuel demand for fingerprint recognition modules. ANVISA procurement standards mandate certified anti-skimming installations across São Paulo and Rio de Janeiro networks. Banco do Brasil and Caixa Econômica Federal expand into municipalities below 50,000 population with fraud-resistant units.
Germany
Sparkassenverbund consolidation and PCI DSS 4.0 compliance deadlines standardize security specifications across 5,700 branch locations. The EU Digital Operational Resilience Act mandates 24-hour cyber recovery capabilities for ATM network operators. Bavaria and North Rhine-Westphalia host the densest concentrations of terminal manufacturing and banking consortium procurement pools.
United States
Legacy fleet modernization and EMV migration completion sustain upgrade demand for encryption-ready platforms. PCI Security Standards Council protocols govern hardware certification eligibility for financial institution procurement. Diebold Nixdorf anchors North American supply chains through Ohio-based manufacturing scale serving regional bank consortiums.
Japan
Advanced biometric integration and aging terminal replacement sustain demand for iris recognition and contactless authentication modules. METI industrial standards shape domestic certification requirements for ATM security hardware. Tokyo-Osaka corridor banks concentrate procurement of next-generation terminals with embedded edge computing security.
ATM Security Market Vendor Landscape
Top-tier vendors anchor manufacturing scale and R&D intensity, while mid-tier specialists compete on regional customization and compliance agility. The vendor base stratifies across three tiers: integrated hardware-software platforms, component specialists, and regional system integrators. Two strategic archetypes dominate: scale-driven OEMs with captive manufacturing and software-centric challengers with cloud-native architectures. Competitive moves concentrate on strategic partnerships for biometric module sourcing and geographic expansion through local licensing arrangements.
Within the integrated platform tier, Diebold Nixdorf and NCR Corporation exemplify scale-driven positioning through manufacturing breadth and cloud-connected security architectures. Fujitsu occupies a specialist position anchoring Asian supply chains for regional banking procurement. These three entities represent the dominant competitive anchors across North American, European, and Asia-Pacific deployment markets.
| Leading Market Players |
|---|
| Diebold Nixdorf |
| NCR Corporation |
| Fujitsu |
| GRG Banking |
| Hyosung TNS |
| Hitachi |
| Euronet USA |
| Triton |
| KAL ATM Software |
| Others |
Supply Flow & Price Mechanics
Regional bank consortiums in Germany and India concentrate procurement authority through standardized tender specifications, anchoring contract-based long-term offtake pricing that locks in volume commitments across multi-year deployment cycles. This buyer concentration compresses margin flexibility for hardware vendors while elevating service bundling premiums.
Pricing Analysis
Margin tightening in encryption modules reflects PCI DSS 4.0 certification bottlenecks that extend hardware validation timelines and elevate compliance-driven R&D amortization. Three-tier pricing structure across premium, standard, and economy levels separates fully integrated biometric terminals from retrofit encryption kits and basic anti-skimming hardware. Price differentiation hinges on BIS certification grade for Indian deployments and EU Digital Operational Resilience Act compliance tier for European procurement. Independent operators exhibit highest price sensitivity due to thin cash-flow profiles, while Sparkassenverbund pools in Germany absorb premium positioning for resilience-certified platforms.
Supply Chain Analysis
Specialized firmware engineering talent scarcity in Taiwan and South Korea constrains encryption chip fabrication capacity expansion despite surging ATM OEM demand. Component sourcing draws from Taiwanese semiconductor foundries for hardware security modules, German precision engineering clusters for hardened steel enclosures, and Japanese optical sensor manufacturers for iris recognition arrays. Single-source vulnerability concentrates in Taiwan-based encryption chip supply, exposing procurement timelines to geopolitical disruption. Distribution runs through regional banking consortium procurement pools in Germany, direct OEM relationships in Brazil, and cloud-native SaaS platforms for Indian independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
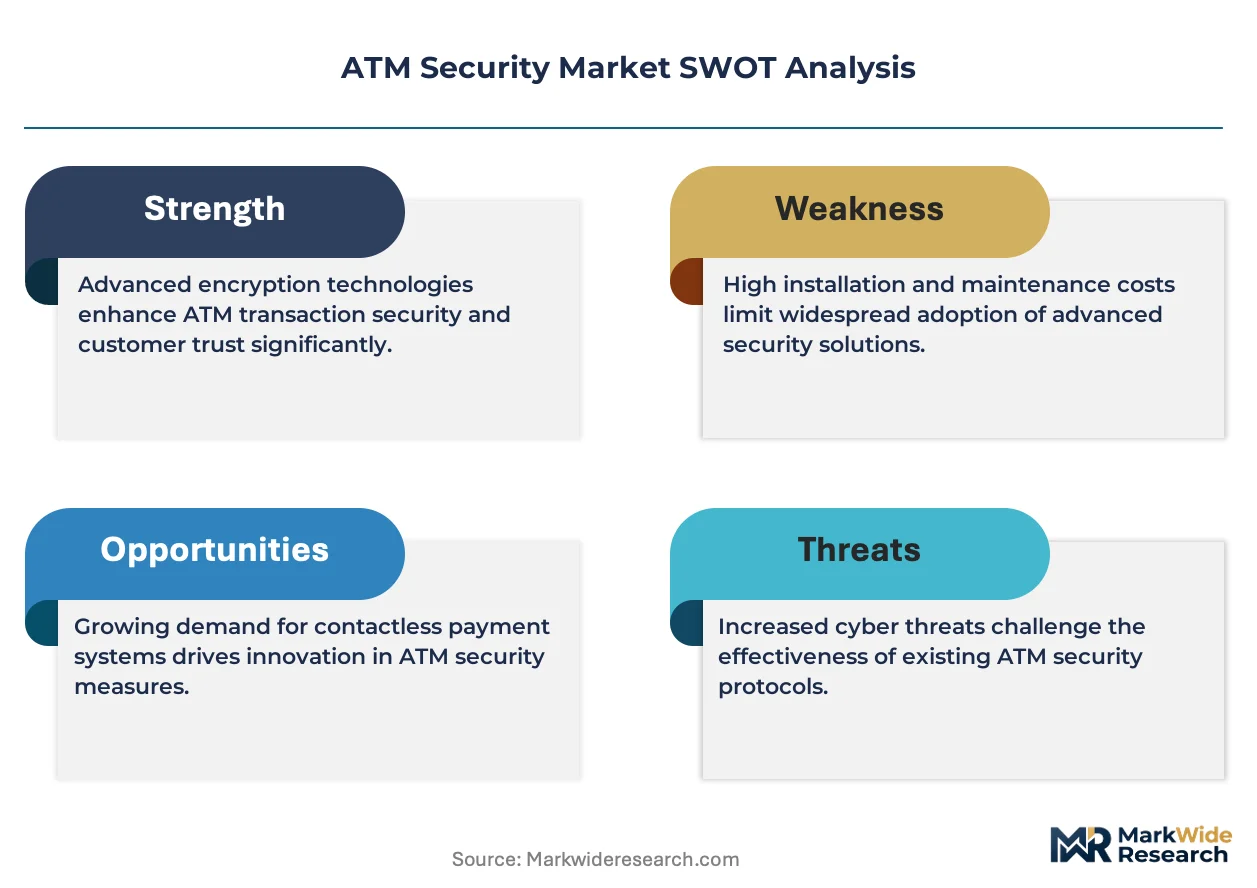
PCI DSS 4.0 compliance deadlines and 18-24 month hardware certification cycles are forcing sub-scale vendors toward exit or acquisition, consolidating procurement influence among tier-one OEMs with captive validation resources.
For Market Incumbents: Cement dominance in encryption module supply through backward integration into Taiwanese chip fabrication partnerships, insulating against supply disruption while capturing margin from compliance-mandated refresh cycles. Deepen R&D investment in edge computing security architectures to neutralize cloud-native challengers targeting Brazilian high-crime neighborhood deployments. For New Entrants and Emerging Players: The premium-to-economy price gap in Indian rural ATM networks opens white-space positioning for biometric reader specialists with BIS certification agility. Target unmanned remote installation segments where incumbent service bundling costs exclude price-sensitive regional banks. Pursue SaaS-native threat monitoring platforms that bypass on-premise security operations center infrastructure requirements. For Investors and Strategic Acquirers: The window for entry favors mid-tier biometric module specialists with EU regulatory clearance and Asian manufacturing partnerships. Long-term viability rests on consolidation of compliance-cleared component suppliers ahead of PCI DSS 5.0 specification drafting. Monitor RBI cybersecurity guideline expansion into tier-two Indian cities as inflection signal for rural penetration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Module Certification Investment | BIS and EU Digital Operational Resilience Act clearance unlocks procurement eligibility across Indian and German consortium tenders. |
| Edge Computing Security Architecture Launch | Sub-50 millisecond response thresholds in São Paulo high-crime neighborhoods electrify competitive positioning for embedded systems vendors. |
| Cloud-Native Threat Monitoring Platform | SaaS delivery models shift Indian private-sector bank vendor relationships toward recurring revenue and CISO-level purchasing authority. |
| Taiwanese Chip Fabrication Partnership | Encryption hardware supply security insulates against geopolitical disruption while capturing premium from PCI DSS 4.0 compliance urgency. |
| Rural Brazil Network Expansion Joint Venture | Banco do Brasil and Caixa Econômica Federal deployment partnerships penetrate municipalities below 50,000 population with fraud-resistant biometric units. |
Methodological Framework
Document review covered RBI cybersecurity circulars, EU Digital Operational Resilience Act implementation guidance, PCI Security Standards Council certification protocols, and ANVISA procurement standards, complemented by interviews with ATM OEM product managers, regional bank consortium procurement leads, biometric sensor engineering directors, and cloud security platform architects. Secondary validation drew from BIS certification registries, Sparkassenverbund tender documentation, Brazilian banking federation fraud reports, and METI industrial standards filings. Bottom-up terminal deployment forecasts triangulated against top-down financial institution capex surveys.
Historical shipment data cross-referenced against panel input from banking technology executives established baseline elasticity parameters across the projection horizon. Segmentation modeling incorporated product architecture tier, deployment model maturity, end-user regulatory scrutiny intensity, and installation type economics. CAGRs derived from slope-consistency checks against banking sector IT spending growth and compliance deadline proximity. Industry-specific inputs included PCI DSS version transition timelines and rural ATM penetration targets under India's financial inclusion mandates.
Inputs from RBI and EU banking regulatory filings were available through the study window; gaps in real-time Sparkassenverbund procurement transaction data introduce uncertainty bands around German upgrade volume assumptions. Forecasts reflect documented compliance deadline schedules and documented semiconductor supply lead times. Material deviation in PCI DSS 5.0 specification timing or Taiwan strait logistics disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Security Orchestration Automation and Response (SOAR) Market
Security Software
AD-Blocking Software Market
Security Software
Italy Endpoint Detection and Response Market
Security Software
Antivirus Software Package Market
Security Software
Global Security Assertion Markup Language (SAML) Authentication Market
Security Software
Global Password Management Software Market
Security Software
Anomaly Detection Tools Market
Security Software
Global Mobile Security Software Market
Security Software
Global Software-Defined Security Market
Security Software
Europe Lawful Interception Market
Security Software
Stalkerware Market
Security Software
Door Phone Market
Security Software
Single Sign-On Market
Security Software
Global Hardware Security Modules (HSM) Market
Security Software
IAM Security Services Market
Security Software
Passwordless Authentication Market