
 France E-Commerce Market | 2026-2036
France E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
France E-Commerce Market Analysis
Buyer concentration in France is shifting as supermarket chains and specialized retailers build proprietary digital channels alongside pure-play marketplaces. Amazon.fr leverages its logistics network to sustain next-day delivery coverage across metropolitan France. Cdiscount anchors its competitive stance through aggressive pricing in electronics and home goods. Fnac-Darty differentiates via integrated click-and-collect services tied to its physical store footprint.
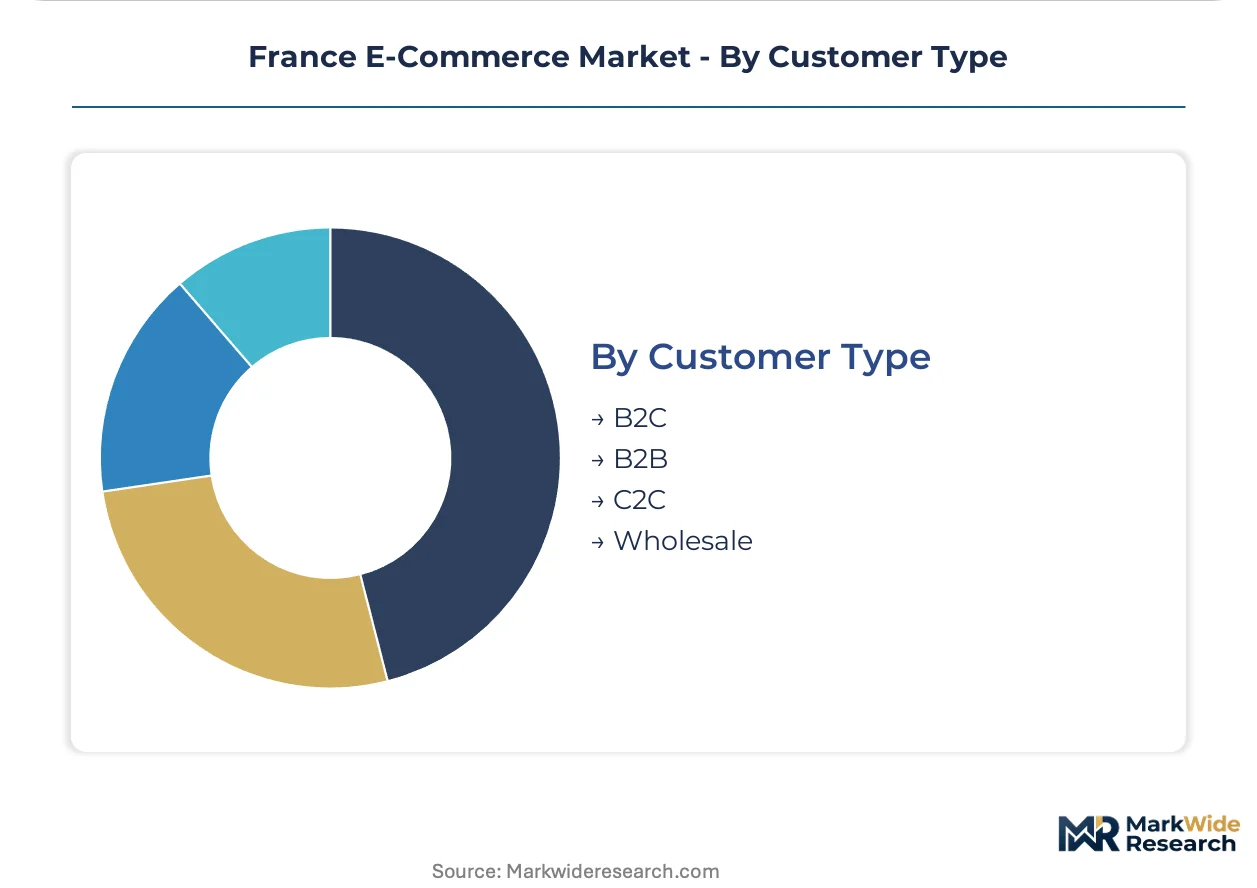
France e-commerce denotes the digital exchange of goods and services through internet-enabled platforms, encompassing transaction processing, inventory management systems, and last-mile fulfillment infrastructure. The sector operates on commission-based revenue models, subscription memberships, and advertising placements, with payment orchestration handling credit card, PayPal, bank transfer, and mobile payment flows. Fashion and electronics currently occupy the largest product category shares, though beauty demonstrates the fastest trajectory as social commerce integration deepens. The B2C customer type dominates transaction volume, while C2C activity through resale platforms expands rapidly among younger demographics seeking circular consumption models.
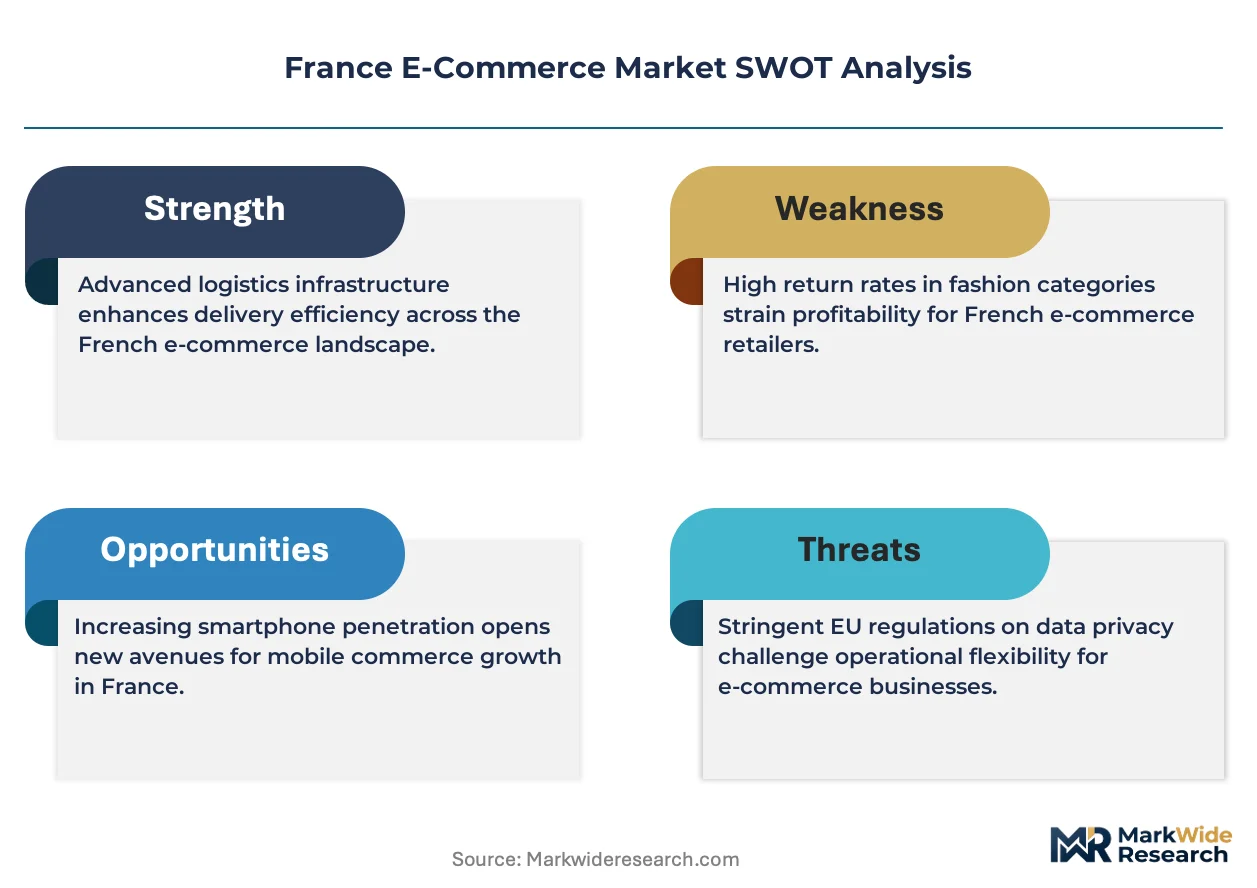
France's national regulator CNIL enforces GDPR-aligned data protection standards that constrain cross-border customer data usage, while the EU Digital Services Act imposes transparency obligations on algorithmic product recommendations. The EU AI Act introduces additional compliance layers for automated pricing and personalized merchandising systems. Stakeholders must monitor how platform liability rules reshape marketplace operator responsibilities versus third-party seller accountability.
Market Dynamics
The EU Digital Services Act imposes new transparency obligations on algorithmic product recommendations, compelling French marketplace operators to restructure seller accountability frameworks and audit automated merchandising systems.
Growth Catalysts
- Dark store fulfillment networks:Grocery chains are deploying automated micro-fulfillment centers in Paris suburbs to compress last-mile delivery windows for fresh food categories.
- GDPR-aligned data portability:CNIL enforcement of customer data ownership rights enables switching between platforms without friction, stimulating competitive service innovation.
- Social commerce integration:Beauty brands leverage TikTok Shop and Instagram Checkout to convert content engagement directly into transactions among 18-34 year-old buyers.
Market Restraints
- Last-mile labor cost inflation:Courier wage pressures in Île-de-France erode margin structures for same-day delivery promises.
- Cross-border data friction:CNIL restrictions on customer data transfers outside the European Economic Area complicate pan-European inventory pooling.
- Commercial real estate scarcity:Limited warehouse availability in Lyon and Marseille metropolitan zones constrains fulfillment node expansion.
Strategic Opportunities
- Circular economy platforms:Resale marketplaces for fashion and electronics remain underdeveloped in secondary cities like Nantes and Strasbourg relative to Paris penetration.
- B2B procurement digitization:Industrial supply catalogs for manufacturing SMEs lack sophisticated e-procurement interfaces present in German or Dutch markets.
- EU AI Act compliance services:Automated pricing algorithms require audit documentation, creating demand for third-party verification tools among mid-sized retailers.
Industry Challenges
- Legacy ERP integration:Established retailers struggle to synchronize decades-old inventory systems with real-time marketplace APIs.
- Phased DSA implementation:Staggered compliance deadlines across 2024-2025 create uncertainty in resource allocation for transparency reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France E-Commerce Market |
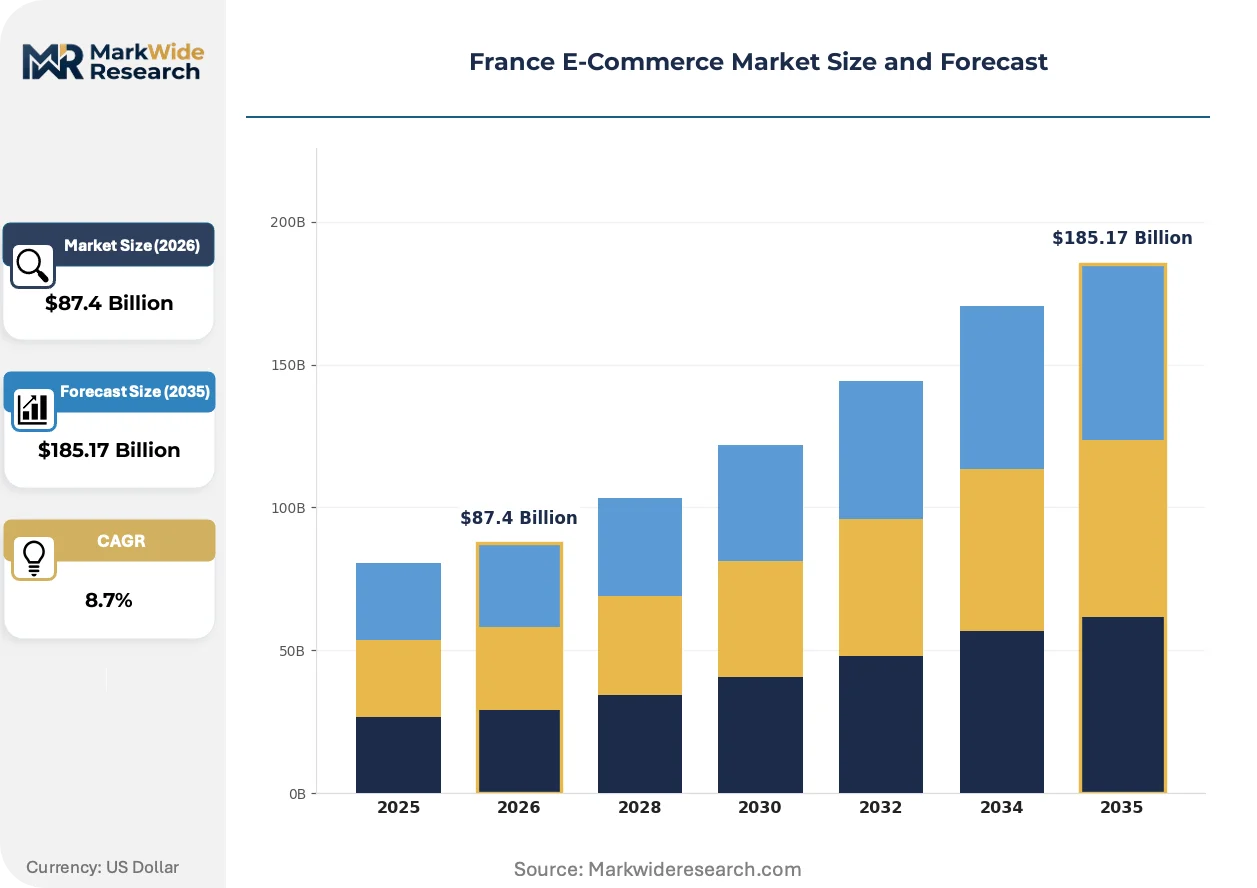
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Fashion, Beauty, Home Goods Delivery Model: Same-Day Delivery, Standard Shipping, Click & Collect, Subscription Delivery Payment Method: Credit Card, PayPal, Bank Transfer, Mobile Payments Customer Type: B2C, B2B, C2C, Wholesale |
| Companies Covered | Amazon.fr, Cdiscount, Vinted, Fnac-Darty, Leboncoin, Temu, eBay, Carrefour, E. Leclerc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France E-Commerce Market Emerging Trajectories
Algorithmic merchandising and automated fulfillment infrastructure are compressing decision cycles across French e-commerce operations. Three developments merit particular attention.
Robotic process automation in warehouse picking is automating order consolidation for multi-SKU baskets. Carrefour and Auchan have deployed autonomous mobile robots in their northern France distribution centers since early 2023. This technology is automating labor allocation away from manual sortation toward exception handling and quality control.
France's CNIL regulator has intensified scrutiny of cookie consent mechanisms under GDPR Article 7, rejecting implied consent frameworks that dominated prior practice. Retailers must now implement granular preference centers before any tracking activates. Beauty and fashion verticals with heavy retargeting dependence face the steepest compliance cost escalation.
Subscription-based replenishment models for household consumables are displacing traditional reordering behavior in urban French households. Amazon Subscribe & Save and niche French operators like La Ruche Qui Dit Oui capture recurring revenue streams that reduce customer acquisition cost volatility. This pattern concentrates among dual-income households in Bordeaux and Toulouse metropolitan zones where delivery predictability outweighs price comparison effort.
France E-Commerce Market Segmentation
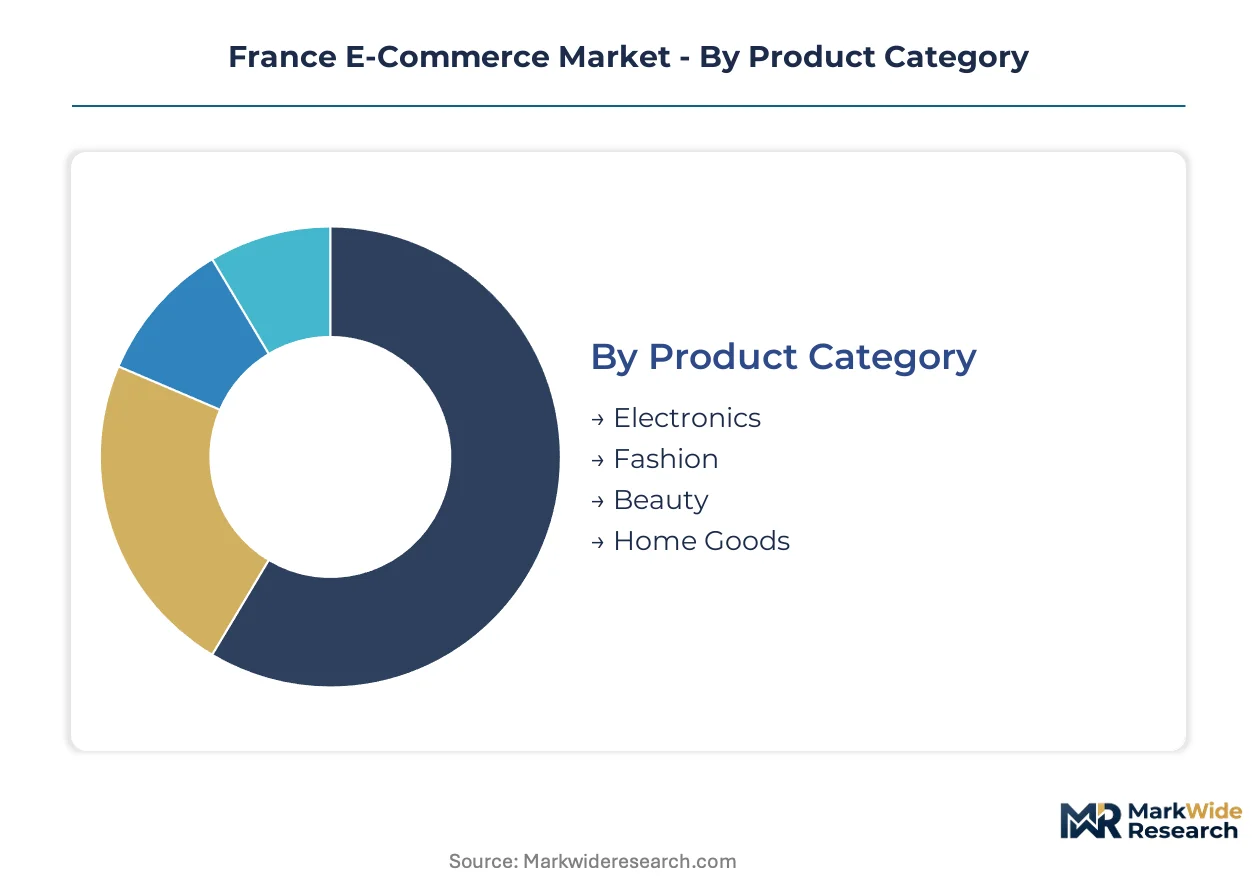
Segmentation in French e-commerce reveals how fulfillment economics and payment infrastructure fragment addressable markets. Each dimension exposes distinct margin pressures, regulatory exposure, and technology investment requirements that shape competitive positioning.
Product Category:
Supply concentration in electronics and fashion warehousing around Paris and Lyon dictates fulfillment network design for specialized inventory.
- Electronics:High-value SKUs with compressed margins demand climate-controlled storage and anti-theft handling protocols. Demand clusters in Île-de-France and Rhône-Alpes where tech-savvy households upgrade devices frequently, though extended warranty disputes strain customer service costs.
- Fashion:Seasonal inventory velocity requires flexible returns processing infrastructure. Paris metropolitan buyers drive premium brand transactions, while secondary cities like Lille and Nice show rising appetite for fast-fashion replenishment cycles.
- Beauty:CNIL consent requirements for personalized skincare recommendations elevate compliance overhead. Social commerce integration accelerates trial-size conversions among younger demographics.
- Home Goods:Bulky fulfillment economics favor regional distribution nodes over centralized Paris hubs. Assembly-required products generate elevated return rates that erode net margins.
Today's leader: Electronics. Tomorrow's challenger: Beauty.
Delivery Model:
Cost tier separation between instant and deferred fulfillment creates distinct customer loyalty mechanics and capital intensity profiles.
- Same-Day Delivery:Dark store networks in Paris suburbs automate grocery and essentials fulfillment. Courier wage inflation in Île-de-France compresses unit economics despite premium pricing acceptance.
- Standard Shipping:Consolidated batch processing through centralized distribution centers optimizes per-package labor allocation. Rural address density gaps in Auvergne and Limousin extend transit windows.
- Click & Collect:Physical store integration leverages existing retail footprints for order staging. Fnac-Darty and Carrefour anchor this model through established metropolitan presence.
- Subscription Delivery:Recurring revenue predictability reduces customer acquisition volatility. Dual-income households in Bordeaux and Toulouse metropolitan zones show strongest adoption for household consumables.
Standard shipping commands volume leadership. Same-day delivery shows steepest expansion trajectory.
Payment Method:
Application-specific payment flows reflect trust hierarchies and demographic adoption patterns across French consumer segments.
- Credit Card:Dominant transaction rail for high-value purchases with chargeback protection. Established fraud detection infrastructure supports cross-border merchant acceptance.
- PayPal:Buyer protection policies reduce perceived risk for marketplace transactions. Younger demographics favor this wallet for discretionary fashion and electronics spending.
- Bank Transfer:SEPA Direct Debit dominates B2B procurement and subscription billing. Settlement lag creates working capital friction for smaller merchants.
- Mobile Payments:Apple Pay and Google Pay penetration accelerates in urban transit corridors. Contactless infrastructure deployment in Lyon and Marseille supports adoption.
Credit cards retain transaction dominance. Mobile payments are gaining share fastest.
Customer Type:
Volume concentration in B2C masks structural margin differences across transaction archetypes and procurement sophistication levels.
- B2C:Individual transaction density drives platform commission revenue and advertising inventory. Paris and Lyon metropolitan zones generate disproportionate order frequency.
- B2B:Industrial supply catalogs for manufacturing SMEs lack sophisticated e-procurement interfaces present in German markets. Payment term negotiations extend sales cycles.
- C2C:Resale platforms expand rapidly among 18-34 year-olds seeking circular consumption models. Authentication and trust infrastructure remain underdeveloped outside Paris.
- Wholesale:Bulk pricing transparency compresses traditional distributor margins. Direct manufacturer relationships displace intermediary layers in electronics and home goods.
B2C anchors current revenue. C2C represents the fastest-climbing opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's e-commerce infrastructure outpaces French fulfillment density, yet France's grocery sector digitizes faster than Italian retail networks. Both markets face divergent regulatory enforcement timelines under EU digital commerce frameworks.
Germany
Industrial B2B procurement digitization and automotive parts marketplaces drive transaction volume expansion. The country's national competition regulator scrutinizes marketplace commission structures under national cartel law amendments. Berlin and Munich metropolitan clusters host dense logistics networks automating same-day delivery for electronics and fashion categories.
United Kingdom
Cross-border fashion resale and grocery subscription models attract venture capital deployment despite post-Brexit customs friction. The national data protection authority enforces consent requirements for algorithmic product recommendations under retained GDPR provisions. London anchors premium beauty and luxury goods transactions, while Manchester and Birmingham distribution centers process mid-market volume.
Italy
Artisan food marketplace growth and luxury fashion authentication services differentiate Southern European positioning. The national data protection authority intensifies cookie consent enforcement for retargeting-dependent verticals. Milan's northern logistics corridor concentrates electronics warehousing, with Naples emerging as a fulfillment node for Mediterranean cross-border shipping.
Spain
Supermarket chain digital transformation and tourism-adjacent retail recovery sustain platform investments. The national data protection authority aligns enforcement with EU Digital Services Act transparency timelines. Barcelona and Madrid metropolitan zones compete for dark store deployment, while Valencia ports handle cross-border inventory staging for North African markets.
Netherlands
Rotterdam-Europoort logistics integration and flower auction digitization create specialized B2B infrastructure. The national data protection authority coordinates with EU-level GDPR implementation working groups. Amsterdam's fintech ecosystem supports payment orchestration innovation for cross-border merchant settlement.
France E-Commerce Market Vendor Landscape
Paris-based retail conglomerates anchor one tier; international marketplace operators hold volume leadership through logistics scale. The vendor structure concentrates around three strategic archetypes: legacy retail chains with physical-digital integration, pure-play marketplaces with fulfillment network advantages, and social-native resale platforms with younger demographic capture. Competitive moves center on dark store capacity expansion and proprietary payment system deployment.
Within the legacy retail integration tier, Carrefour and Fnac-Darty exemplify store-network leverage for click-and-collect services. Amazon.fr occupies a position defined by logistics infrastructure density across metropolitan France. Cdiscount anchors aggressive pricing competition in electronics and home goods categories, representing the domestic marketplace archetype against international entrants.
| Leading Market Players |
|---|
| Amazon.fr |
| Cdiscount |
| Vinted |
| Fnac-Darty |
| Leboncoin |
| Temu |
| eBay |
| Carrefour |
| E. Leclerc |
| Others |
Supply Flow & Price Mechanics
Courier workforce concentration in Île-de-France compresses same-day delivery margins and widens the spread between premium expedited tiers and economy deferred options across French e-commerce.
Pricing Analysis
Capacity additions in automated micro-fulfillment centers across Paris suburbs are reshaping price floors for grocery and essentials categories. The market operates on a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by delivery speed guarantees and after-sales service bundling. Cost compression in same-day tiers is intensifying because courier wage inflation in metropolitan zones erodes unit economics despite premium pricing acceptance. Small-town buyers in Auvergne and Limousin exhibit highest price sensitivity, while Paris metropolitan dual-income households show lowest sensitivity to delivery premiums.
Supply Chain Analysis
Warehouse automation technology supply rests on German robotics producers and Chinese sensor manufacturers. Fulfillment infrastructure draws from automated storage systems, autonomous mobile robots, and climate-controlled inventory management platforms. Single-source vulnerability concentrates in robotic picking arms sourced from Bavarian engineering clusters. Distribution runs through centralized distribution centers in northern France for batch processing, with dark store nodes in Paris suburbs handling instant fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France e-commerce market functions as a regulatory compounder where CNIL enforcement of GDPR Article 7 consent requirements and EU Digital Services Act transparency obligations create sustained compliance demand across retail verticals.
For Market Incumbents: Hedge against margin erosion from last-mile labor cost inflation by deploying proprietary dark store networks in Lyon and Marseille metropolitan zones before real estate scarcity hardens. Anchor defensive positioning through backward integration into automated warehouse robotics rather than relying on third-party logistics contracts. Certification investment in EU AI Act audit documentation for automated pricing algorithms creates switching costs against pure-play marketplace entrants.
For New Entrants and Emerging Players: Social-native resale platforms with integrated authentication represent the most penetrable wedge for capturing 18-34 year-old buyers seeking circular consumption models outside Paris. Target Nantes and Strasbourg secondary cities where fashion and electronics resale infrastructure remains underdeveloped relative to capital penetration. Launch through TikTok Shop and Instagram Checkout integration to convert content engagement directly into transactions without competing on logistics scale.
For Investors and Strategic Acquirers: Grocery chain conglomerates are the most active acquirer in this space, seeking digital transformation capabilities to defend against pure-play marketplace encroachment. Mid-sized retailers with proprietary fulfillment technology and established click-and-collect footprints represent the optimal acquisition target archetype. Watch CNIL enforcement intensity against cookie consent mechanisms as the inflection indicator for compliance service demand and retargeting-dependent vertical margin pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Dark Store Network Expansion | Automated micro-fulfillment in Paris suburbs compresses last-mile delivery windows for fresh food categories. |
| GDPR Compliance Technology Investment | Granular preference center deployment satisfies CNIL scrutiny of cookie consent mechanisms under Article 7. |
| Social Commerce Platform Integration | TikTok Shop and Instagram Checkout convert content engagement directly into beauty and fashion transactions. |
| Subscription Replenishment Model Launch | Recurring revenue predictability reduces customer acquisition cost volatility in Bordeaux and Toulouse metropolitan zones. |
| EU AI Act Audit Documentation | Third-party verification tools for automated pricing algorithms create defensive moats against regulatory enforcement. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with e-commerce platform executives, logistics operations directors, CNIL compliance officers, and retail category managers with secondary validation against SEC filings of listed marketplace operators, French customs trade data, EU Digital Services Act implementation timelines, and retail sector employment statistics from national labor offices. Bottom-up segment sizing and top-down macroeconomic triangulation anchored value estimates.
Historical reference periods established baseline growth trajectories against which projection assumptions were stress-tested across the modeling period. Segmentation dimensions modeled include product category, delivery model, payment method, and customer type, with regional metropolitan cluster penetration rates as an additional industry-specific dimension. CAGRs were derived from trend extrapolation adjusted for regulatory implementation phasing and technology adoption S-curves, incorporating dark store deployment timelines and social commerce integration rates as forecast inputs.
The model holds under steady regulatory enforcement intensity; deviation in CNIL penalty escalation or EU AI Act implementation acceleration would shift compliance cost assumptions and margin projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
LAMEA Dropshipping Market
E-Commerce Solutions
Chile E-Commerce Market
E-Commerce Solutions
North America Automotive E-Commerce Market
E-Commerce Solutions
E-Commerce Software Market
E-Commerce Solutions
Ambient Commerce Market
E-Commerce Solutions
Global Live E-Commerce Market
E-Commerce Solutions
China Alcohol E-Commerce Market
E-Commerce Solutions
Romania E-Commerce Market
E-Commerce Solutions
Middle East and Africa E-Commerce Market
E-Commerce Solutions
E-Commerce Ecosystem Market
E-Commerce Solutions
Multi-Channel E-Commerce Software Market
E-Commerce Solutions
North America B2B E-Commerce Market
E-Commerce Solutions
Omnichannel Commerce Software Market
E-Commerce Solutions
South Africa E-Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Apparel Market
E-Commerce Solutions
Europe FMCG B2B E-Commerce Market