
 Global Network Encryption Market | 2026-2036
Global Network Encryption Market Size, Share, and Industry Trends Forecast 2026-2036
Global Network Encryption Market Intelligence
The procurement landscape for network encryption is pivoting from a focus on large, single-enterprise deployments to a more fragmented base including cloud service providers and mid-sized businesses. Cisco leverages its extensive networking portfolio to embed encryption capabilities directly into its hardware infrastructure. Thales specializes in high-assurance solutions tailored for government and defense clients, a historically stable and high-margin segment. Meanwhile, Juniper Networks competes by offering high-performance, scalable encryption for data center interconnect and cloud environments.
Network encryption involves applying cryptographic algorithms to protect data in transit as it moves between endpoints across a network. These solutions typically operate at Layer 2 or Layer 3 of the OSI model, creating secure tunnels to prevent unauthorized interception or modification. The primary commercial purpose is to ensure data confidentiality and integrity for sensitive communications. Cloud-based deployment models are gaining significant traction over traditional on-premises hardware. Within end-user segments, demand from government agencies and financial institutions provides a stable foundation, while IT enterprises represent the fastest-growing application area.
Regulatory frameworks are a primary catalyst for market adoption. The European Union's GDPR imposes strict penalties for data breaches, compelling organizations to encrypt personal data in transit. In the United States, standards like FIPS 140-2 mandate specific cryptographic module validation for federal government procurement. Chinese regulations from the MIIT also enforce stringent data security protocols for network operators. The critical challenge for solution providers is to deliver stronger encryption without introducing unacceptable latency on high-speed networks.
Market Dynamics
The central tension shaping network encryption is the race to develop quantum-resistant algorithms without compromising the low-latency performance required by data centers and financial trading networks. This conflict between future-proofing security and maintaining current network speed defines vendor product roadmaps and enterprise adoption criteria.
Growth Catalysts
- Regulatory Mandates:The EU's GDPR framework compels organizations handling European citizen data to implement strong data protection, including encryption for data in transit, creating a significant compliance-driven demand source.
- Financial Sector Requirements:The global financial services industry's stringent need for data confidentiality and integrity during transactions and inter-bank communications provides a stable, high-margin demand base for high-assurance encryption solutions.
- Cloud Service Adoption:The migration of enterprise workloads to public and hybrid cloud environments expands the network perimeter and attack surface, necessitating robust encryption for data center interconnect and cloud-to-edge traffic.
Market Restraints
- Performance Overhead:High-grade encryption can introduce latency, a critical performance bottleneck for high-frequency trading, real-time data analytics, and other speed-sensitive applications, limiting adoption where throughput is paramount.
- Solution Cost:The high acquisition and maintenance cost of dedicated high-assurance hardware encryption appliances presents a significant budget obstacle for small and mid-sized businesses, constraining broader market penetration.
- Legacy System Integration:Integrating modern network encryption solutions with older, existing IT infrastructure can be complex and expensive, often requiring significant network re-architecture and creating resistance to upgrades.
Strategic Opportunities
- Securing SD-WAN Deployments:Integrating advanced encryption capabilities directly into Software-Defined Wide Area Network platforms presents an opportunity to offer a unified, secure, and manageable solution for distributed enterprises.
- Mid-Market Penetration:Developing scalable, cloud-delivered encryption-as-a-service models can unlock the underpenetrated mid-sized business segment, which lacks the capital and expertise for traditional hardware deployments.
- Quantum-Resistant Cryptography:Pioneering the commercialization of quantum-resistant cryptography algorithms offers vendors a first-mover advantage in securing long-term contracts with government and critical infrastructure clients concerned about future threats.
Industry Challenges
- Cryptographic Agility:A key operational challenge is designing systems that can be easily updated or reconfigured with new cryptographic algorithms to respond to emerging threats or vulnerabilities without requiring a full hardware replacement.
- Key Management Complexity:Securely generating, distributing, storing, and rotating cryptographic keys at scale remains a significant operational burden and a potential point of failure for large, distributed networks.
- Certification Delays:The lengthy and rigorous validation process for standards like FIPS 140-2 in the United States can create significant delays in bringing new products to the lucrative government market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Network Encryption Market |
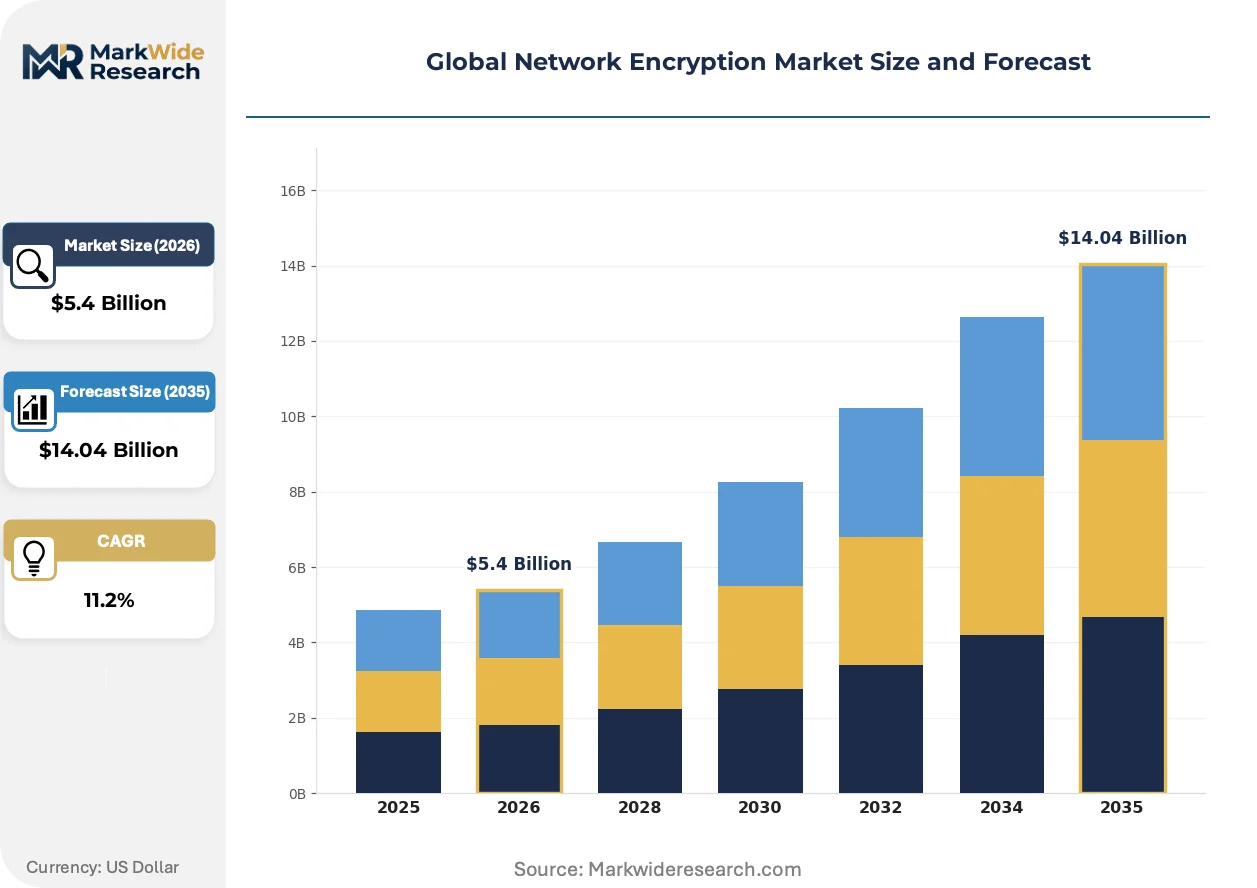
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $14.04 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Encryption Type: Symmetric Key, Asymmetric Key, Hash Functions, Stream Cipher, Block Cipher Application: Data Protection, Email Security, Cloud Security, VPN, Identity Management, Secure Messaging Deployment Mode: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Telecommunications, Government Agencies, Financial Institutions, IT Enterprises, Defense, E-commerce |
| Companies Covered | Atos, Ciena, Cisco, ADVA Optical Networking, Rohde & Schwarz Cybersecurity, Thales, Juniper Networks, Senetas, Nokia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Network Encryption Market Strategic Shifts & Innovations
The market's evolution is defined by a move away from static, hardware-bound security postures. This shift is reshaping the competitive landscape, as vendors now focus on delivering adaptive, software-defined encryption solutions capable of addressing both current high-speed network demands and future quantum threats.
Quantum-Resistant Cryptography (QRC) is a new class of cryptographic protocols designed to withstand attacks from future quantum computers. Government and defense sectors in the United States and Europe are leading early adoption and standardization efforts through bodies like NIST. The development of these next-generation ciphers is overtaking classical cryptographic standards like RSA and ECC in long-term strategic planning for critical infrastructure protection.
Regulatory frameworks from bodies like China's Ministry of Industry and Information Technology (MIIT) enforce stringent data security protocols for network operators. These rules mandate the use of state-approved cryptographic algorithms and influence data handling practices, impacting foreign cloud providers operating within the country. The telecommunications and cloud service provider segments are most affected, compelling them to partner with local technology vendors to ensure compliance.
A significant behavioral change involves enterprises moving from large capital expenditures on hardware appliances to subscription-based, encryption-as-a-service models. This trend disrupts the traditional reseller channel, favoring direct engagement with cloud marketplaces and managed security service providers (MSSPs). This model is most visible among IT enterprises and mid-sized businesses seeking scalable security without high upfront investment.
Global Network Encryption Market Segmentation
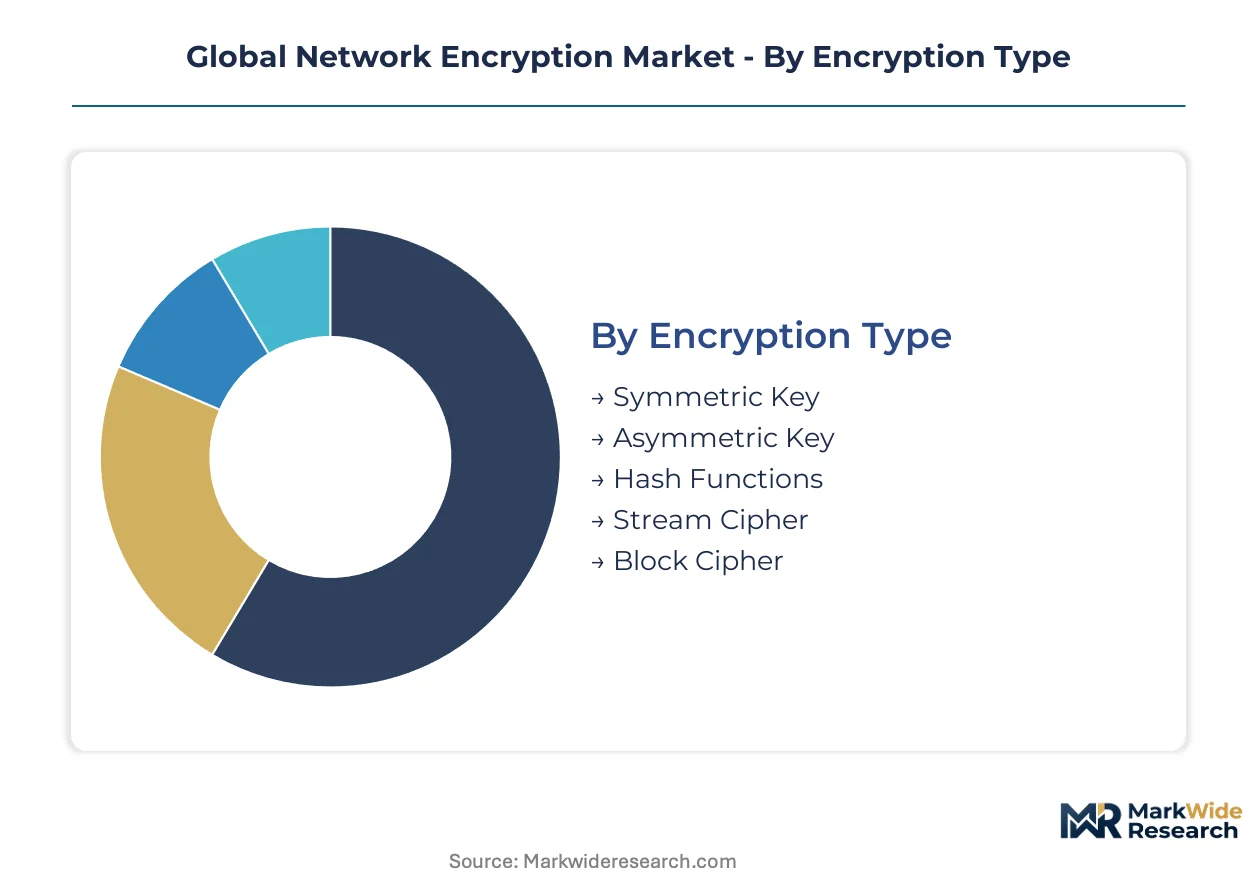
Segmenting the network encryption market illuminates diverse procurement drivers and technological preferences across various organizational types. This granular breakdown helps identify where specific cryptographic solutions or deployment models gain traction, reflecting varying security priorities and operational constraints.
Encryption Type:
Buyers in this category differentiate based on the cryptographic method employed to secure data, balancing strength with computational overhead.
- Symmetric Key:This method utilizes a single secret key for both encryption and decryption, offering high speed and efficiency for bulk data protection. Demand concentrates in high-volume data transfer environments like data centers and cloud service providers due to its performance characteristics.
- Asymmetric Key:Employing a pair of mathematically linked keys (public and private), this type facilitates secure key exchange and digital signatures, crucial for identity verification and initial secure channel establishment. Financial institutions and government agencies prioritize asymmetric key encryption for secure communication and authentication protocols.
- Hash Functions:These algorithms convert data into a fixed-size string of characters, primarily used for data integrity verification and password storage rather than direct data encryption.
- Stream Cipher:Operating on individual bits or bytes of data, stream ciphers are often used in real-time communication protocols where high throughput and low latency are paramount.
- Block Cipher:This method encrypts data in fixed-size blocks, providing robust security for stored data and network packets, commonly implemented in standards like AES.
Volume sits with Symmetric Key encryption; growth tilts toward Asymmetric Key solutions.
Application:
The functional use cases for network encryption define procurement priorities, with organizations selecting solutions tailored to specific security objectives.
- Data Protection:This application focuses on safeguarding sensitive information from unauthorized access, modification, or destruction across various network layers. Demand for robust data protection is high among financial institutions and healthcare providers due to stringent regulatory compliance.
- VPN:Virtual Private Networks establish secure, encrypted connections over public networks, enabling remote users and branch offices to access corporate resources securely. Government agencies and large enterprises rely on VPNs for secure remote access and inter-office communication.
- Email Security:Solutions in this segment encrypt email content and attachments, preventing interception and ensuring confidentiality during transmission.
- Cloud Security:This application secures data and applications hosted in cloud environments, addressing concerns about data residency and control in multi-tenant architectures.
- Identity Management:Network encryption supports identity management by securing authentication credentials and access tokens, preventing unauthorized impersonation.
- Secure Messaging:This segment ensures the confidentiality and integrity of instant messages and chat communications, often utilized in highly sensitive corporate or government contexts.
Demand for network encryption solutions is heavily influenced by the specific security objective.
Deployment Mode:
Customer preference for infrastructure management and operational expenditure drives choices within this category, impacting scalability and resource allocation.
- Cloud-Based:These solutions are delivered as a service over the internet, offering scalability, reduced upfront costs, and simplified management. IT enterprises and mid-sized businesses increasingly adopt cloud-based encryption for its flexibility and ease of deployment.
- On-Premises:Hardware or software solutions installed and managed within an organization's own data center provide maximum control and customization. Government agencies and financial institutions often prefer on-premises deployments for strict data sovereignty and compliance requirements.
- Hybrid:This model combines elements of both on-premises and cloud-based deployments, allowing organizations to manage sensitive data locally while leveraging cloud resources for scalability.
- Managed Services:Third-party providers manage the entire encryption infrastructure, including deployment, monitoring, and key management, offering specialized expertise and operational relief.
The shift towards cloud platforms is redefining how organizations procure and manage their encryption infrastructure.
End User:
The sector-specific regulatory requirements and data sensitivity levels delineate demand across end-user segments, influencing procurement patterns.
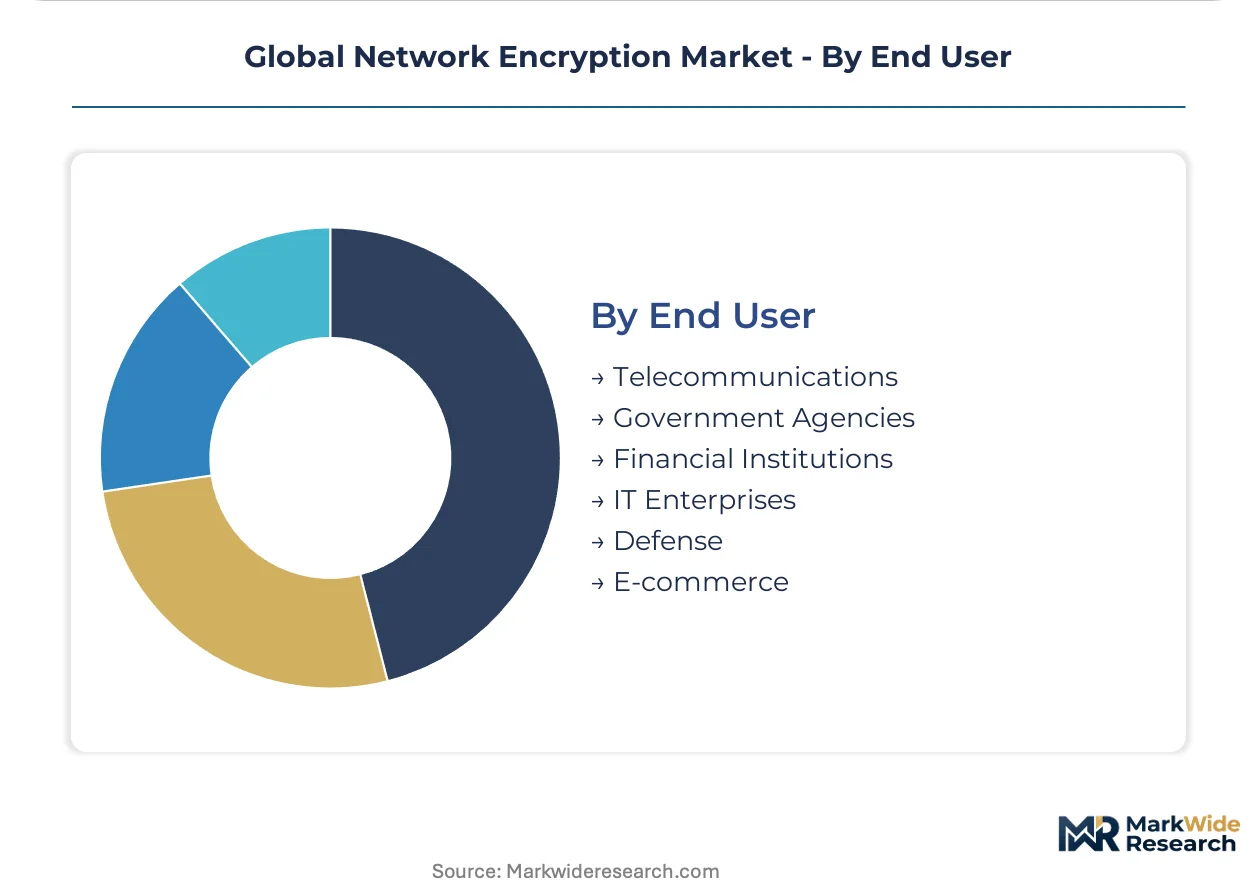
- Financial Institutions:This segment requires high-assurance encryption for protecting sensitive customer data, transaction details, and inter-bank communications, driven by regulations like GDPR and PCI DSS. These organizations demand robust, low-latency solutions to maintain service reliability and compliance.
- Government Agencies:Federal and defense organizations require stringent network encryption to protect classified information, critical infrastructure, and national security data. Procurement is often guided by standards such as FIPS 140-2 in the United States, mandating specific cryptographic module validation.
- Telecommunications:Network operators deploy encryption to secure subscriber data, signaling traffic, and infrastructure, adhering to national data retention and privacy laws.
- IT Enterprises:Businesses across various industries utilize network encryption to protect intellectual property, customer databases, and internal communications, especially with increased remote work adoption.
- Defense:This specialized segment demands military-grade encryption for tactical communications, intelligence gathering, and secure command and control systems.
- E-commerce:Online retailers employ encryption to secure customer payment information and personal data during transactions, building trust and complying with data protection regulations.
Highly regulated industries consistently drive demand for advanced network encryption solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for network encryption solutions spans globally, driven by stringent data protection mandates and the imperative to secure digital infrastructure. Organizations across continents prioritize robust encryption to safeguard sensitive information in transit. This widespread adoption reflects an intensifying focus on cybersecurity resilience against evolving threats.
United States
Strong demand for network encryption originates from government and defense verticals, alongside the financial services industry. Standards like FIPS 140-2 mandate specific cryptographic module validation for federal procurement. Technology hubs in Silicon Valley and the Washington D.C. area drive innovation and adoption for high-assurance security solutions.
Germany
European Union's GDPR framework compels organizations handling citizen data to implement strong data protection, including encryption. The financial services sector in Frankfurt and the automotive industry in Stuttgart require robust solutions for secure data transfer. German enterprises prioritize network encryption to comply with national and EU privacy regulations.
China
Chinese MIIT regulations enforce stringent data security protocols for network operators and cloud service providers. Telecommunications companies and large state-owned enterprises are major consumers of network encryption technologies. Major tech centers in Beijing and Shanghai are focal points for compliance-driven security deployments.
Japan
Japanese enterprises and financial institutions require advanced network encryption to protect sensitive data and ensure business continuity. The Ministry of Economy, Trade and Industry (METI) promotes cybersecurity measures across critical infrastructure sectors. Tokyo's dense corporate landscape and extensive data center infrastructure drive significant demand for secure communications.
India
India's rapidly expanding IT enterprises and financial technology sector fuel substantial demand for network encryption. Emerging data protection laws emphasize the need for robust data in-transit security measures. Bengaluru, as a leading IT hub, sees high adoption of cloud-based and on-premises encryption solutions for corporate data protection.
Global Network Encryption Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue cloud-delivered encryption-as-a-service models. The market exhibits a tiered competitive landscape, with consolidation in core infrastructure solutions and fragmentation among niche players. Strategic archetypes include large networking infrastructure providers, high-assurance security specialists, and performance-optimized data center encryption vendors. Dominant competitive moves involve technology licensing agreements and strategic partnerships to extend solution reach.
Among the established network encryption providers, Cisco, a US-based corporation, exemplifies an infrastructure-centric approach, integrating security directly into its extensive networking hardware. Thales, a France-based public limited company, occupies a position as a high-assurance specialist, serving government and defense clients with stringent security requirements. Juniper Networks, another US-based entity, represents the segment focused on high-performance, scalable encryption solutions for data center interconnect and cloud environments. These entities demonstrate varied strategic focuses within the broader market.
| Leading Market Players |
|---|
| Atos |
| Ciena |
| Cisco |
| ADVA Optical Networking |
| Rohde & Schwarz Cybersecurity |
| Thales |
| Juniper Networks |
| Senetas |
| Nokia |
| Others |
Cost & Logistics Intelligence
The development of quantum-resistant cryptography algorithms simultaneously reshapes cost economics and supply concentration in the network encryption market. This technological shift necessitates significant research and development investments, impacting pricing structures for advanced solutions and concentrating specialized expertise among a few key vendors.
Pricing Analysis
Volume for basic encryption solutions drives competitive pricing, while high-assurance solutions command premium margins. The dominant pricing model incorporates subscription-based encryption-as-a-service for cloud deployments and project-based licensing for on-premises hardware. Price differentiation stems from FIPS 140-2 certification levels and specialized after-sales support. Pricing pressure stems from the commoditization of basic VPN encryption. Mid-sized businesses exhibit the highest price sensitivity, whereas government agencies and financial institutions prioritize performance and compliance over cost.
Supply Chain Analysis
Specialized cryptographic hardware supply rests on a limited number of manufacturers, primarily in the United States and Germany. Key dependencies include secure element chips, high-performance ASICs, and specialized software libraries for cryptographic algorithms. Regulatory restrictions on technology export pose a significant supply chain risk, particularly for advanced encryption components. Distribution runs through direct sales channels for large enterprises and government clients, complemented by managed security service providers (MSSPs) for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a supply-constrained story, where the scarcity of quantum-resistant cryptographic development expertise props up pricing for cutting-edge security solutions.
For Market Incumbents: Anticipate the long-term threat of quantum computing by accelerating R&D in post-quantum cryptography. Deepen vertical integration into specialized hardware manufacturing to control component supply and ensure performance. Invest heavily in FIPS 140-2 certification to maintain access to lucrative government contracts. Strengthen channel partnerships with cloud service providers to counter emerging cloud-native security offerings.
For New Entrants and Emerging Players: Launch via cloud-delivered encryption-as-a-service models to target the underpenetrated mid-sized business segment. Focus on developing quantum-resistant cryptography solutions with agile deployment capabilities. Exploit white-space opportunities in securing Software-Defined Wide Area Network (SD-WAN) deployments. Offer flexible, subscription-based pricing to reduce upfront costs for new customers.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized quantum-resistant cryptography developers given the accelerating global interest in future-proof security. The long-term viability of the network encryption market remains strong, driven by regulatory mandates and persistent cyber threats. Target acquisition archetypes include key management system (KMS) providers and cloud-native security platform vendors. A significant data breach impacting unencrypted critical infrastructure data serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography R&D | Secures long-term contracts with government clients facing future quantum threats. |
| Cloud-Native Encryption-as-a-Service Offering | Unlocks the underpenetrated mid-sized business segment seeking scalable security solutions. |
| FIPS 140-2 Certification Investment | Ensures access to lucrative federal government procurement markets in the United States. |
| SD-WAN Security Integration | Provides a unified, manageable security solution for distributed enterprises and remote workforces. |
| Key Management System (KMS) Development | Addresses a critical operational burden and potential point of failure for large, distributed networks. |
Research Approach
Document review covered regulatory filings, industry association reports, academic cryptographic papers, and technology vendor whitepapers, complemented by interviews with chief technology officers, chief security officers, IT procurement leads, and network architects. This analysis combined primary insights with secondary validation. The study employed a rigorous bottom-up and top-down triangulation approach to ensure data accuracy and market sizing.
The quantitative model produced granular volume and value outputs for the network encryption market across the analysis window. Segmentation dimensions modeled included encryption type, application, deployment mode, end-user segment, and regional regulatory compliance. Compound annual growth rates were derived from historical trends, market drivers, and expert projections. Key forecast inputs included enterprise IT spending trends, regulatory enforcement actions, and quantum computing development timelines.
The model assumes a particular technology adoption path; alternative pathways for quantum-resistant cryptography would alter the outlook. Forecasts reflect assumptions regarding geopolitical stability and the pace of regulatory enforcement. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
User Provisioning Software Market
Security Software
Anti-Money Laundering (AML) Software Solution Market
Security Software
Global Electronic Passports Market
Security Software
Europe User Provisioning Market
Security Software
Global Software-Defined Security Market
Security Software
Wi-Fi Based Home Camera Market
Security Software
Embedded Security Market
Security Software
Source Code Escrow Market
Security Software
Network Camera and Video Analytics Market
Security Software
Europe Smart Doorbell Market
Security Software
Global SMS Firewall Market
Security Software
Saudi Arabia Managed Security Services Market
Security Software
Vsaas Market
Security Software
Data Leakage Prevention Product Market
Security Software
Messaging Security Market
Security Software
Video Intercom Devices and Equipment Market