
 Personal Robots Market | 2026-2036
Personal Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Robots Market Outlook
Direct-to-consumer online channels is tilting toward ecosystem bundling and subscription attach rates. iRobot Corporation leverages its brand strength and proprietary navigation software to sustain premium positioning in North American households. Ecovacs Robotics Co., Ltd. anchors its competitive stance through manufacturing scale and aggressive pricing in European and Asian markets. Sony Group Corporation differentiates by integrating entertainment and sensing capabilities that extend beyond utilitarian cleaning functions.
Personal robots are electromechanical systems equipped with sensors, actuators, and onboard processors capable of autonomous or semi-autonomous operation in unstructured domestic and semi-commercial environments, typically operating on battery power with wireless connectivity protocols. Cleaning robots dominate current shipment volumes due to mature computer vision and simultaneous localization and mapping capabilities, while companion robots represent the fastest-expanding margin pool as natural language processing and affective computing mature. Educational robots occupy a specialized niche where AI-driven adaptive curricula create recurring content revenue streams distinct from hardware margins.
The EU AI Act classifies companion and assistant robots with biometric recognition as high-risk systems, imposing conformity assessments that reshape R&D priorities for machine learning architectures. The FDA regulates robots with health monitoring claims as medical devices, while China's SAMR enforces GB standards on electromagnetic compatibility and data privacy for networked home robots. Stakeholders must monitor divergence between Brussels and Washington on algorithmic transparency mandates, as compliance fragmentation threatens to fragment product architectures and delay cross-border launches.
Market Dynamics
Natural language processing architectures are compressing development cycles for companion robots while simultaneously triggering regulatory pre-certification requirements under the EU AI Act before commercial deployment.
Growth Catalysts
- Elderly care automation:Voice-controlled companion robots are penetrating assisted living facilities in Germany and Japan as workforce shortages intensify demand for affective computing systems.
- GB standards harmonization:China's SAMR electromagnetic compatibility frameworks are streamlining type-approval processes for networked home robots targeting domestic middle-class households.
- SLAM maturation:Simultaneous localization and mapping algorithms are reducing sensor costs for cleaning robots, enabling price compression in European and Asian retail channels.
Market Restraints
- Lithium-ion supply concentration:Battery cell production clusters in East Asia create input cost volatility and logistics vulnerability for robot manufacturers dependent on cylindrical cell formats.
- EU AI Act conformity costs:High-risk system classification for biometric-enabled companion robots imposes third-party assessment fees that structurally disadvantage smaller hardware entrants.
- Technical limitation in unstructured navigation:Domestic environments with variable lighting and obstacle density still exceed reliable autonomous operation thresholds for stair-climbing and furniture manipulation.
Strategic Opportunities
- India household penetration:Sub-urban middle-class adoption of cleaning robots remains underpenetrated relative to smartphone ownership, presenting white-space for localized pricing and Hindi-language voice interfaces.
- Educational content licensing:AI-driven adaptive curricula for STEM robots generate recurring revenue streams distinct from hardware margins, with South Korean after-school academies showing early traction.
- IRA clean energy credits:US domestic assembly of battery-powered robots qualifies for manufacturing incentives, reshaping location decisions for North American market supply.
Industry Challenges
- Edge AI talent scarcity:Embedded machine learning optimization for low-power processors requires specialized firmware engineers, with competition intensifying from automotive and smartphone sectors.
- FDA 510(k) timeline compression:Health monitoring claims trigger medical device pathways that extend commercialization schedules by 18-24 months for wellness-oriented companion robots.
- Legacy smart home integration:Fragmented Matter/Thread/Zigbee protocol support forces multi-stack hardware architectures that inflate bill-of-materials costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Robots Market |
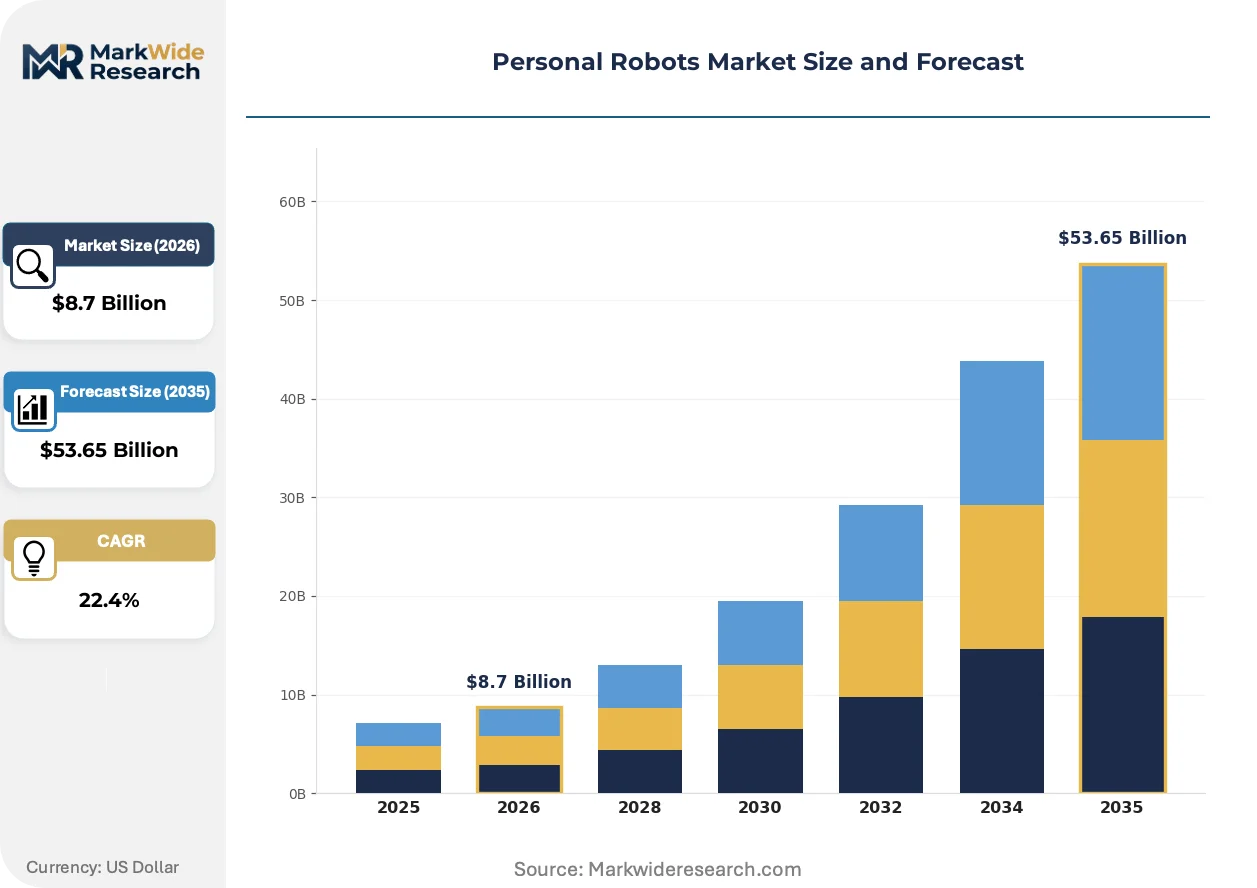
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Companion Robots, Cleaning Robots, Educational Robots, Personal Assistants Technology: AI, Machine Learning, Natural Language Processing, Computer Vision End User: Households, Educational Institutions, Elderly Care Facilities, Small Businesses Feature: Voice Control, Automation, Remote Control, Connectivity |
| Companies Covered | iRobot Corporation, Ecovacs Robotics Co., Ltd., Roborock Technology Co., Ltd., Samsung Electronics Co., Ltd., Dyson Technology Limited, Honda Motor Co., Ltd., Sony Group Corporation, Amazon.com, Inc., UBTECH Robotics Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Robots Market Strategic Shifts
Multimodal sensing fusion is redefining robot-environment interaction models, compressing the gap between industrial automation precision and domestic adaptability.
Edge-deployed transformer models are digitizing voice and gesture interpretation for companion robots. Elderly care facilities in Germany are piloting these systems for non-verbal emotional state detection. The technology is digitizing interaction design, shifting competitive advantage from mechanical engineering toward neural architecture optimization.
The EU AI Act's high-risk system classification is mandating conformity assessments for biometric-enabled companion robots. Manufacturers must document training data provenance and algorithmic decision logic before CE marking. Companion robots with emotion recognition capabilities face the steepest compliance burden, with some firms bifurcating product lines between European and non-European feature sets.
Subscription attach rates for consumables and software updates are displacing pure hardware transactions in direct-to-consumer channels. iRobot's ecosystem bundling and Ecovacs' aggressive pricing both assume recurring revenue streams from mapping data services and automated reordering. This shift is most visible in the United States, where Amazon's Alexa integration has normalized voice-initiated replenishment for cleaning robot components.
Personal Robots Market Segmentation
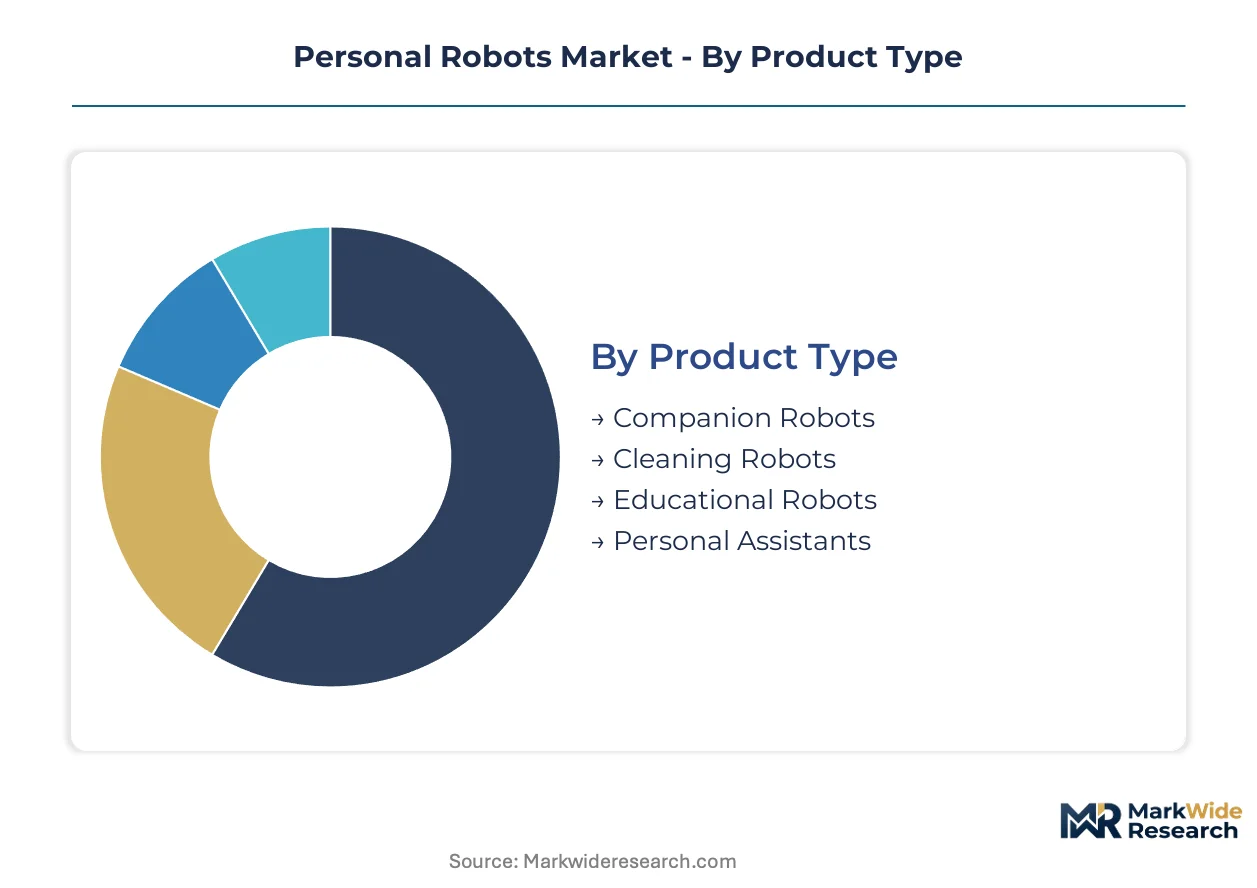
Segmentation in personal robots reveals divergent hardware refresh cycles and margin architectures. Cleaning robots compress replacement timelines through consumable wear, while companion robots extend amortization through software subscription attach. Technology and end-user stratification further fragments procurement patterns across consumer, institutional, and healthcare channels.
Product Type:
Cycle times stretch from eighteen months for floor-care units to seven-year amortization for social companion platforms in assisted living deployments.
- Cleaning Robots:Electromechanical systems deploying simultaneous localization and mapping for autonomous debris removal across hard surfaces and carpeting. Demand concentrates in United States and German households where dual-income families prioritize time savings over manual vacuuming. Sensor cost compression from SLAM maturation accelerates replacement velocity in mass-market retail channels.
- Companion Robots:Affective computing platforms integrating natural language processing and biometric sensing for emotional engagement. Elderly care facilities in Germany and Japan drive procurement as workforce shortages intensify requirements for non-verbal state detection and medication adherence prompting. EU AI Act high-risk classification extends pre-certification timelines.
- Educational Robots:STEM-focused hardware with adaptive curriculum delivery.
- Personal Assistants:Voice-first devices with environmental control integration.
Cleaning robots dominate installed base. Companion robots is where expansion concentrates.
Technology:
Cost tier stratification separates premium neural architectures from commodity sensor fusion stacks.
- AI:Umbrella architectures spanning perception, planning, and actuation loops. Edge deployment constraints in battery-powered form factors favor quantization and pruning techniques that trade accuracy for thermal efficiency. United States and Chinese cloud providers anchor training infrastructure.
- Machine Learning:Model compression for embedded inference on low-power ARM cores.
- Natural Language Processing:Transformer-based speech understanding with multilingual intent classification. Elderly care pilots in Germany leverage non-verbal emotional state detection for dementia patient engagement. Regulatory pre-certification under EU AI Act constrains biometric-enabled deployment timelines.
- Computer Vision:Convolutional networks for obstacle classification and depth estimation.
Computer vision saturates cleaning robot bill-of-materials. Natural language processing is climbing the fastest as companion platforms commercialize.
End User:
Volume concentration in consumer channels masks margin migration toward institutional procurement with service contract attach.
- Households:Direct-to-consumer acquisition through online marketplaces and big-box retail. United States penetration of voice-controlled cleaning robots deepens through Amazon Alexa ecosystem bundling. Replacement cycles compress as mapping data services generate recurring revenue beyond hardware margin.
- Elderly Care Facilities:Institutional procurement with affective computing requirements for workforce augmentation. German assisted living operators pilot companion robots with biometric recognition for resident monitoring. EU AI Act conformity assessments reshape vendor qualification criteria.
- Educational Institutions:South Korean after-school academies deploy STEM robots with adaptive content licensing.
- Small Businesses:Commercial cleaning contractors adopt autonomous floor-care for overnight operations.
Households anchor shipment volume. Elderly care facilities is where margin expansion concentrates.
Feature:
Supply concentration in voice stack licensing shapes competitive differentiation for connectivity-dependent platforms.
- Voice Control:Far-field microphone arrays with cloud-based intent parsing. United States households normalize Alexa and Google Assistant integration for cleaning robot initiation. Hindi-language localization presents white-space for Indian market penetration.
- Automation:Scheduling and autonomous recharge without human intervention.
- Remote Control:Smartphone application oversight with manual override capabilities.
- Connectivity:Wi-Fi and Bluetooth protocols enabling over-the-air updates and data telemetry. Matter/Thread/Zigbee fragmentation inflates multi-stack hardware costs for smart home integration. Subscription attach rates for mapping services displace pure hardware transactions in direct-to-consumer channels.
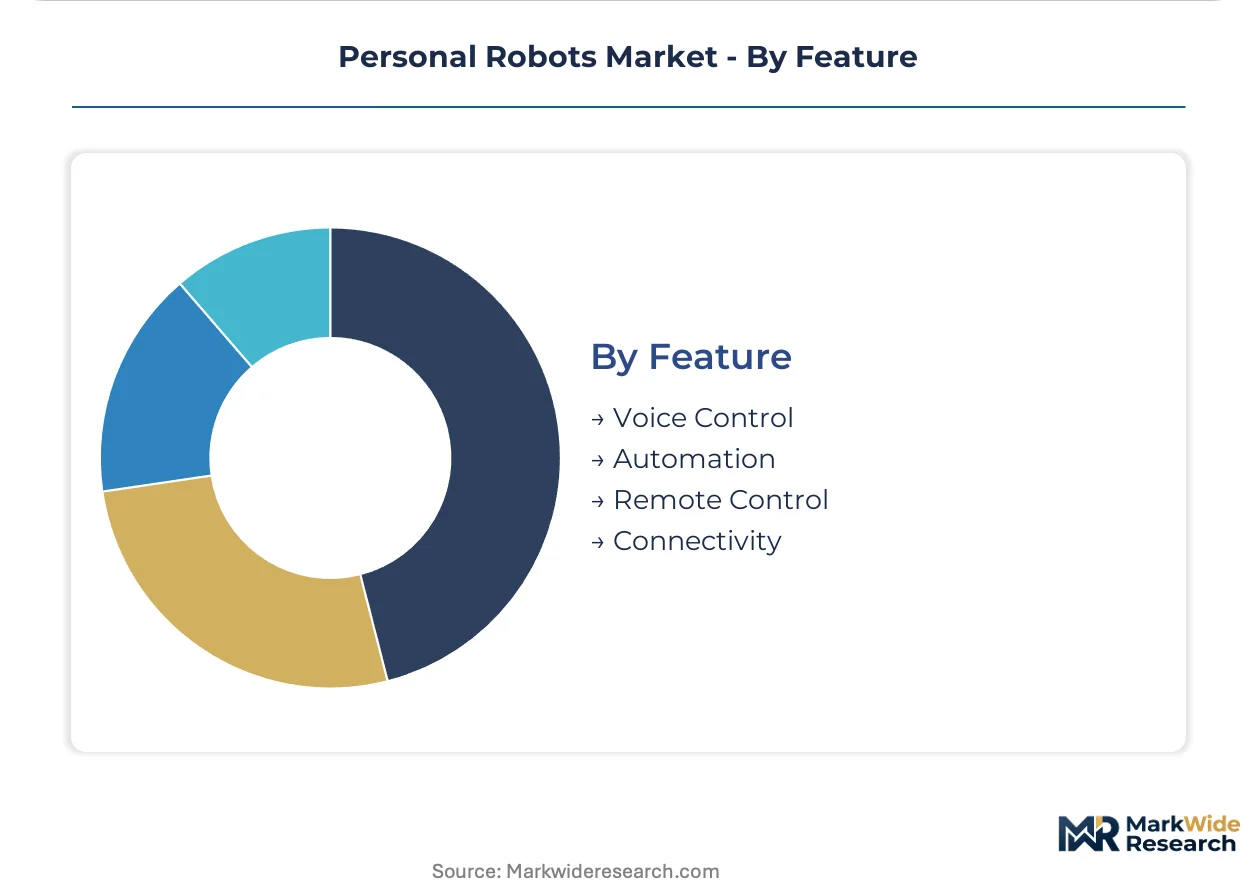
Automation dominates baseline feature expectations. Voice control is gaining share fastest as natural language processing matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German and Japanese institutional channels, while Chinese manufacturing scale compresses hardware margins across Southeast Asian retail markets. Divergent regulatory stringency between Brussels and Washington fragments product architectures. Regional procurement patterns split between voice-first consumer adoption and affective computing deployment in elderly care infrastructure.
United States
Household penetration of voice-controlled cleaning robots deepens through Amazon Alexa ecosystem bundling, with subscription attach rates for mapping services displacing pure hardware transactions. The FDA regulates robots with health monitoring claims as medical devices, extending commercialization timelines for wellness-oriented companion platforms. California's technology corridor anchors cloud-based natural language processing infrastructure for edge-deployed transformer models.
Germany
Elderly care facilities drive institutional procurement of companion robots with biometric recognition capabilities as workforce shortages intensify. The EU AI Act's high-risk system classification imposes third-party conformity assessments that reshape vendor qualification criteria for affective computing platforms. Bavaria's assisted living operators pilot non-verbal emotional state detection systems for dementia patient engagement.
China
Domestic middle-class adoption accelerates as SAMR electromagnetic compatibility frameworks streamline type-approval processes for networked home robots. GB standards on data privacy and electromagnetic compatibility enforce compliance for manufacturers targeting household penetration. The Yangtze River Delta manufacturing cluster concentrates battery cell production and cylindrical cell format assembly for export-oriented robot OEMs.
Japan
Aging demographics propel companion robot deployment in metropolitan elderly care facilities, with METI funding programs supporting affective computing R&D for workforce augmentation. JIS standards govern safety requirements for autonomous domestic devices with biometric sensing capabilities. Tokyo's robotics research institutes collaborate with Osaka-based manufacturers on multimodal sensing fusion for emotional engagement platforms.
South Korea
After-school academies deploy STEM-focused educational robots with adaptive curriculum licensing, generating recurring content revenue streams distinct from hardware margins. MFDS guidelines shape safety protocols for robots with health monitoring capabilities in institutional settings. Seoul's ed-tech cluster concentrates AI-driven adaptive learning platform development for regional export markets.
Personal Robots Market Competitive Environment
Specialized robotics pure-plays and diversified consumer electronics conglomerates split the market between focused innovation and ecosystem leverage. The vendor base concentrates around three strategic archetypes: navigation software specialists, manufacturing scale leaders, and entertainment-technology integrators. Competitive positioning hardens through proprietary SLAM algorithm development, aggressive pricing in European retail channels, and multimodal sensing capabilities that extend beyond utilitarian functions.
Within the navigation-specialist tier, iRobot Corporation and Ecovacs Robotics Co., Ltd. exemplify divergent geographic positioning strategies, with the former anchoring premium North American household penetration and the latter compressing price points across Asian and European mass markets. Sony Group Corporation occupies a distinct position integrating entertainment and sensing capabilities. Roborock Technology Co., Ltd. represents the manufacturing-scale archetype, while Samsung Electronics Co., Ltd. leverages diversified consumer electronics distribution for smart home ecosystem integration. Honda Motor Co., Ltd. and UBTECH Robotics Corp. sit within the humanoid mobility specialist category, with Amazon.com, Inc. and Dyson Technology Limited pursuing adjacent hardware-service convergence models.
| Leading Market Players |
|---|
| iRobot Corporation |
| Ecovacs Robotics Co., Ltd. |
| Roborock Technology Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| Dyson Technology Limited |
| Honda Motor Co., Ltd. |
| Sony Group Corporation |
| Amazon.com, Inc. |
| UBTECH Robotics Corp. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in cylindrical lithium-ion cell production across East Asian manufacturing clusters is compressing supplier margins while amplifying pricing volatility for robot OEMs dependent on battery-powered form factors. This utilization squeeze cascades into procurement posture, forcing tier-one manufacturers toward long-term offtake contracts while smaller entrants absorb spot-market premiums.
Pricing Analysis
Configured-to-order companion robots with biometric recognition capabilities command substantial premiums over standard cleaning platforms due to EU AI Act conformity assessment requirements and specialized NLP architecture licensing. Three-tier pricing structure across premium, standard, and economy levels separates SLAM-enabled navigation systems from basic sensor-fusion stacks, with customization depth and certification grade as primary differentiation drivers. Price erosion runs through mass-market cleaning segments as Chinese manufacturing scale compresses hardware margins. Household consumers exhibit highest price sensitivity, while German elderly care facilities demonstrate inelastic demand for affective computing platforms.
Supply Chain Analysis
Export-control restrictions on advanced GPU and neural processing unit technologies limit component flows to Chinese robot manufacturers, reshaping procurement strategies for edge AI inference capabilities. Supply concentration centers on China's Yangtze River Delta for battery cell assembly, South Korea for memory semiconductors, and Taiwan for sensor microcontrollers. Raw material dependencies span lithium carbonate, rare-earth magnets, and precision optical components. Single-source vulnerability in cylindrical cell formats creates structural risk. Distribution runs through direct-to-consumer online channels with subscription attach for consumables and software updates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is opening as EU AI Act regulatory divergence creates geographic product-line bifurcation, enabling specialized compliance-focused entrants to capture margin pools inaccessible to standardized global platforms.
For Market Incumbents: Insulate proprietary SLAM algorithm advantages through backward integration into sensor module production, while securing FDA pre-submission pathways for wellness-oriented companion robots before health monitoring claims trigger medical device classification. Channel control through Amazon Alexa ecosystem bundling remains critical for North American household penetration defense. For New Entrants and Emerging Players: Build out Hindi-language voice interface capabilities for India's underpenetrated suburban middle-class cleaning robot segment, where smartphone ownership far exceeds robot adoption. Educational content licensing for STEM curricula in South Korean after-school academies offers recurring revenue white-space distinct from hardware margin competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biometric-enabled companion robot sub-segments as EU AI Act conformity assessments mandate third-party documentation and training data provenance systems. Long-term viability favors acquisition targets with embedded firmware optimization capabilities for low-power ARM cores. The signal to watch is edge AI talent migration rates from automotive and smartphone sectors.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Pre-Certification | Third-party assessment investment secures CE marking for biometric-enabled companion platforms before commercial deployment. |
| Backward Integration into Sensor Modules | In-house production of SLAM navigation components reduces bill-of-materials exposure to spot-market volatility. |
| Educational Content Licensing Partnerships | Adaptive STEM curriculum agreements with South Korean academies generate recurring revenue beyond hardware transactions. |
| Hindi-Language Voice Stack Localization | Regional language interfaces unlock penetration in India's suburban household segment with smartphone-normalized consumers. |
| FDA 510(k) Pre-Submission Pathway | Early medical device engagement compresses commercialization timelines for wellness-oriented companion robots with health claims. |
Study Parameters
A spread of perspectives from robotics R&D directors, elderly care facility procurement managers, smart home platform engineers, and lithium-ion battery supply planners converged on the working assumptions underlying demand and cost trajectories. Primary fieldwork combined structured interviews with secondary validation against SEC filings of listed robot manufacturers, SAMR type-approval databases, EU AI Act implementation guidance, and customs trade flow records. Bottom-up shipment modeling and top-down market sizing triangulation anchored volume estimates.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation dimensions spanning product type, technology architecture, end-user channel, and feature configuration. CAGRs derived from installed base replacement velocity, household penetration saturation curves, and institutional procurement cycle analysis. Edge AI inference efficiency gains and battery cell cost trajectories served as key forecast inputs.
Practitioners should monitor lithium supply contract renegotiations and EU AI Act delegated act updates for early signals of forecast revision. Cross-checking against hyperscaler robotics investment disclosures and automotive edge AI hiring patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Wearable Robots and Exoskeletons Market
Robotics and Automation
Agricultural Robots and Mechatronics Market
Robotics and Automation
Nanorobots in Healthcare Market
Robotics and Automation
Asia-Pacific Data Center Robotics Market
Robotics and Automation
Global Exoskeleton Market
Robotics and Automation
Robotic Coffee Bars Market
Robotics and Automation
Grafting Robot Market
Robotics and Automation
Robotic Waste Sorting System Market
Robotics and Automation
Europe Automated Guided Vehicle (AGV) Market
Robotics and Automation
Global Security Robots Market
Robotics and Automation
Asia Pacific Warehouse Robotics Market
Robotics and Automation
Cyber-Physical System Market
Robotics and Automation
Agricultural Robots Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
Global Autonomous Mobile Robot Market
Robotics and Automation
Italy Cloud Robotics Market