
 Remote Browser Market | 2026-2036
Remote Browser Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Browser Market Outlook
EU CSRD disclosure obligations is broadening enterprise accountability for third-party web-borne supply chain risks. Menlo Security leverages cloud-native isolation architecture to anchor its position in large financial services deployments. Palo Alto Networks competes through tight integration between its Prisma Access platform and remote browser capabilities, while Ericom Software specializes in on-premises and air-gapped environments for government buyers.
Remote browser technology executes web content in a sandboxed server environment before transmitting a safe visual stream to the endpoint, typically using HTML5 rendering or pixel-pushing protocols to eliminate local code execution. Its primary commercial purpose is to neutralize malware, phishing, and data exfiltration vectors that exploit traditional client-side browser vulnerabilities. Cloud-based deployment represents the fastest-expanding segment as organizations retire legacy VPN concentrators and redirect capex toward elastic consumption models, while secure browsing applications command the deepest margin pools due to recurring threat-intelligence subscriptions bundled with isolation cores. Containerization technology is gaining share against traditional virtualization approaches because it reduces infrastructure overhead and accelerates session spin-up times for high-volume user bases.
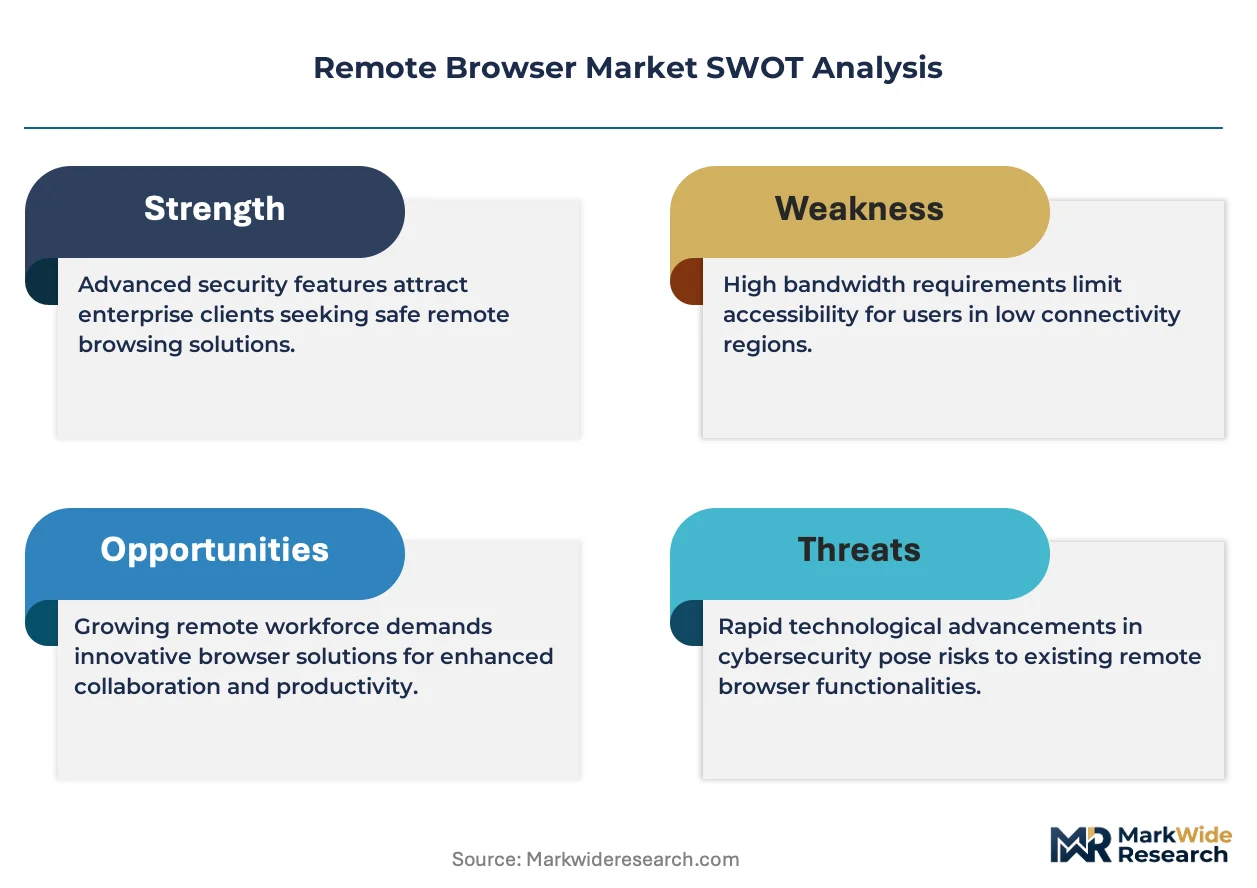
NIST zero-trust architecture guidelines, the EU AI Act risk-management obligations for automated content filtering systems, and HIPAA security rule provisions for healthcare endpoint protection collectively shape product certification requirements and procurement eligibility across the United States and European Union. Vendors must demonstrate continuous compliance attestation to maintain channel access in regulated verticals. Stakeholders should monitor how browser isolation vendors adapt their threat-intelligence pipelines to emerging AI-generated phishing payloads and synthetic identity fraud vectors.
Market Dynamics
Zero-trust architecture mandates are compressing procurement cycles for remote browser solutions as enterprise security teams dismantle perimeter-based network models. Containerized isolation engines are displacing legacy virtualization stacks, forcing infrastructure refresh decisions across federal and financial services buyers.
Growth Catalysts
- NIST zero-trust guidelines:Federal agencies in the United States must segment classified and unclassified traffic through isolated browsing sessions, creating mandatory procurement pools.
- Cloud migration acceleration:Organizations retiring VPN concentrators redirect capital toward elastic remote browser consumption models that scale with hybrid workforce expansion.
- Containerization technology:Reduced infrastructure overhead and faster session spin-up times enable high-volume deployments that virtualization cannot match.
Market Restraints
- Latency sensitivity:Pixel-pushing protocols require sub-50ms server proximity, constraining vendor data center footprints and raising edge infrastructure costs.
- EU AI Act compliance burden:Risk-classification requirements for automated content filtering systems force architectural redesigns that extend product roadmaps.
- HTML5 rendering limitations:Complex web applications with WebGL or real-time collaboration features experience degraded performance in isolated sessions.
Strategic Opportunities
- Healthcare endpoint protection:HIPAA security rule provisions for medical device isolation create underserved demand in hospital systems and telehealth platforms.
- AI-generated phishing defense:Synthetic identity fraud vectors require threat-intelligence pipelines that browser isolation vendors can monetize through subscription tiers.
- Air-gapped government networks:Defense contractors and intelligence agencies need on-premises deployments that cloud-native competitors cannot satisfy.
Industry Challenges
- Threat-intelligence analyst scarcity:Vendors struggle to staff security operations centers capable of processing isolated session telemetry at enterprise scale.
- Legacy application compatibility:Banking and government systems running ActiveX or Java applets require custom plugin bridges that fragment codebase maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Browser Market |
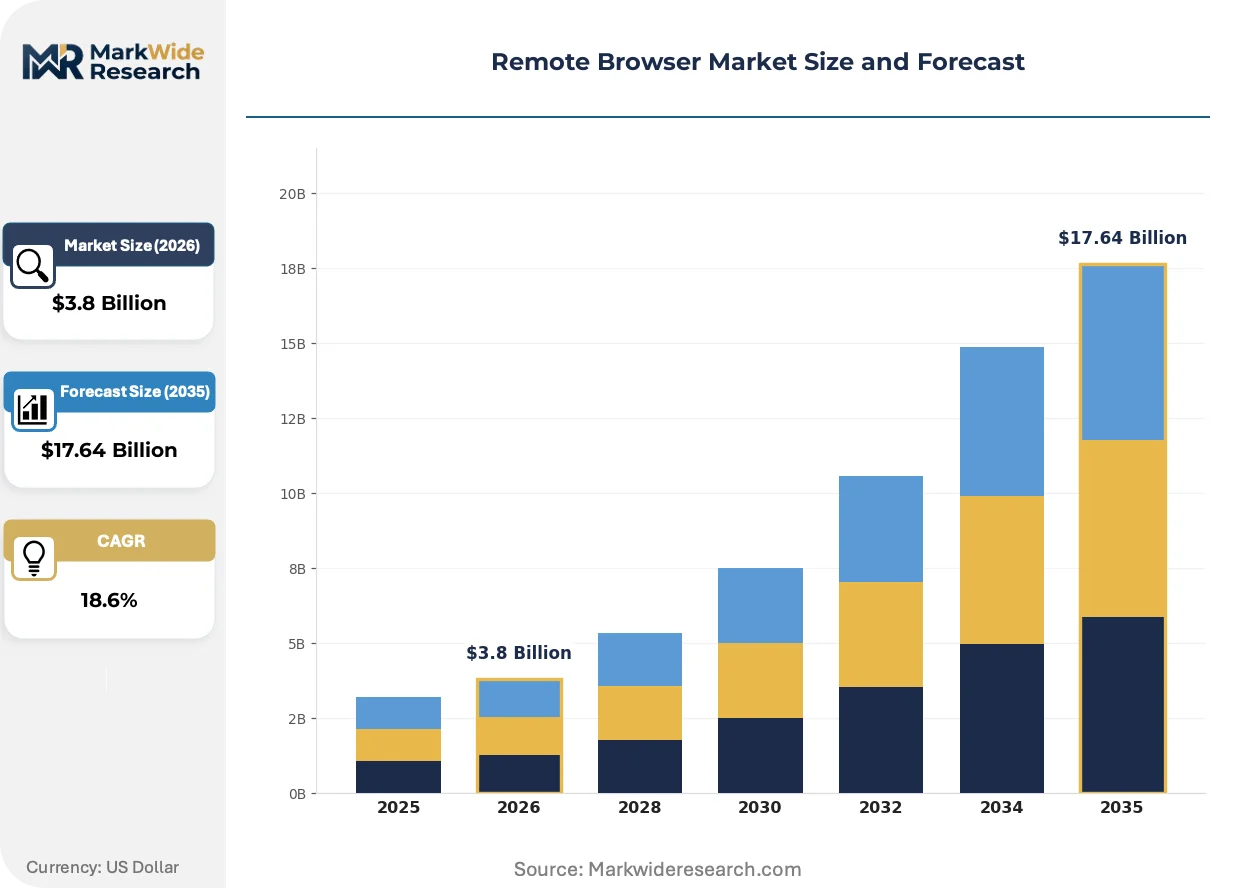
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Service End User: Enterprises, Educational Institutions, Government, Individual Users Application: Remote Access, Secure Browsing, Testing Environments, Web Development Technology: Virtualization, Containerization, HTML5, Client-Server Architecture |
| Companies Covered | Ericom Software, Palo Alto Networks, Menlo Security, Netskope, Proofpoint, Citrix Systems, Cyberinc, Island, Authentic8, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Browser Market Strategic Shifts
Remote browser architecture is converging with identity-centric security fabrics, dissolving the boundary between network access and content isolation. Vendors are racing to embed continuous authentication and behavioral analytics directly into browsing sessions.
Containerization is consolidating remote browser infrastructure by replacing hypervisor-based isolation with lightweight kernel namespaces. Enterprise IT teams in financial services are adopting containerized engines for 10,000-plus seat deployments. This compression is eliminating vendor differentiation previously anchored to proprietary virtualization stacks.
The EU AI Act's risk-management obligations for automated filtering systems are forcing architectural transparency in content classification pipelines. Vendors must document decision logic for high-risk web categorization to maintain procurement eligibility in European Union member states. Healthcare and public sector buyers in Germany and France are prioritizing vendors with pre-certified compliance attestations.
Security procurement teams are unbundling threat-intelligence subscriptions from core isolation licenses to optimize recurring spend. Value-added resellers and managed security service providers are capturing this disaggregation, particularly in United States mid-market accounts where internal security operations maturity lags. Federal integrators are consolidating vendor relationships to simplify compliance auditing.
Remote Browser Market Segmentation
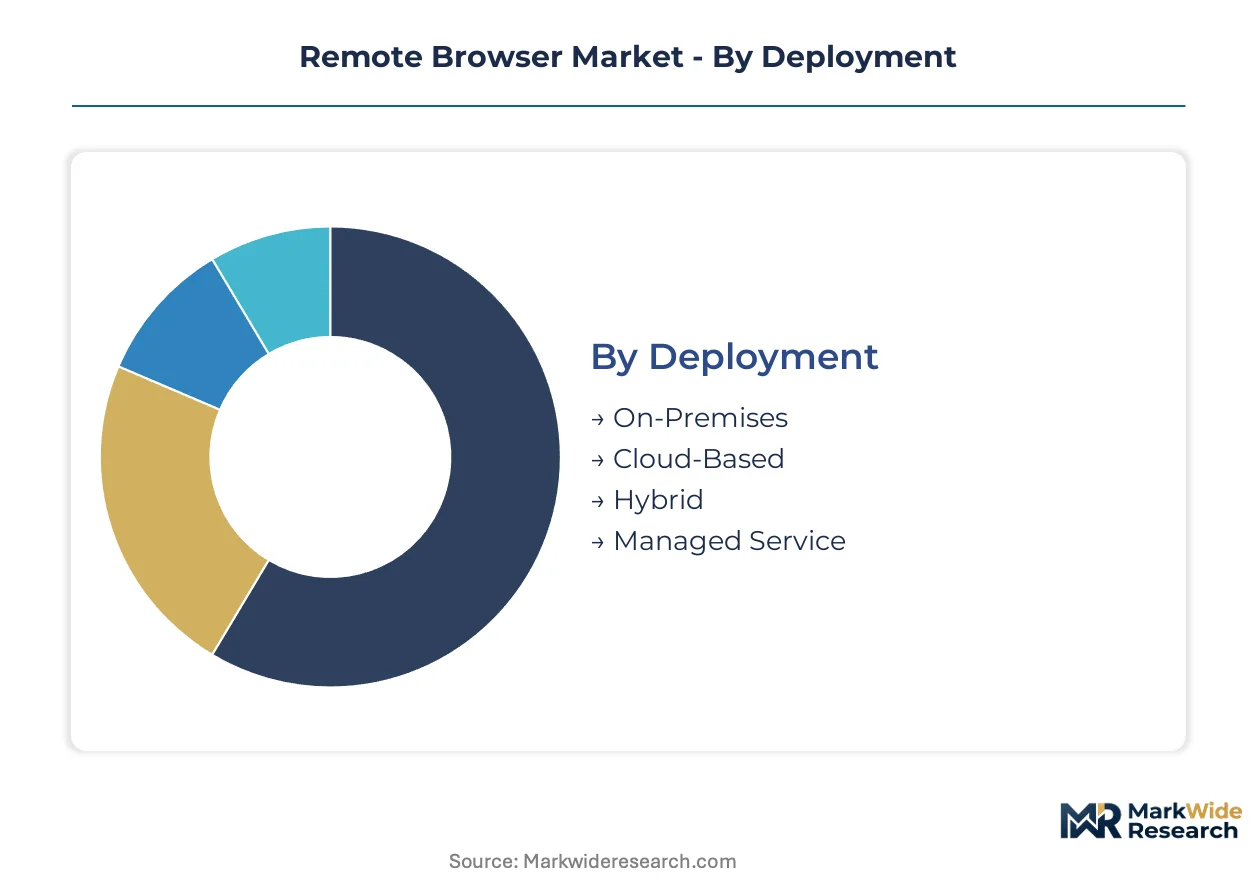
Remote browser segmentation reveals how infrastructure choices, user profiles, and technical architectures determine vendor competitive positioning. Procurement teams evaluate deployment models against latency requirements, compliance mandates, and workforce scale. Technology selections increasingly hinge on containerization advantages versus legacy virtualization maintenance burdens.
Deployment:
Organizations retiring VPN concentrators and perimeter firewalls face upgrade decisions that reshape capital allocation toward elastic consumption models.
- Cloud-Based:Elastic resource provisioning eliminates data center capex while enabling rapid scaling for hybrid workforce expansion. Financial services firms in the United States and Germany concentrate demand here as zero-trust mandates harden procurement criteria.
- On-Premises:Complete data sovereignty and air-gapped operation satisfy defense contractors and intelligence agencies with classified network segmentation requirements. Installation cycles run longer but retain preference where regulatory attestation demands physical infrastructure control.
- Hybrid:Split traffic routing allows sensitive workloads to remain on-premises while routine browsing shifts to cloud instances. Healthcare systems adopt this architecture to isolate medical device traffic from administrative web sessions.
- Managed Service:Outsourced security operations center staffing addresses threat-intelligence analyst scarcity for mid-market enterprises. Providers assume telemetry processing burdens that internal teams cannot resource.
Volume placements concentrate in Cloud-Based deployments; the faster expansion belongs to Managed Service as skills gaps widen.
End User:
Customer type segmentation maps directly to procurement authority complexity and recurring revenue predictability.
- Enterprises:Fortune 500 security teams dismantle perimeter models through isolated browsing for 10,000-plus seat deployments. Containerized engines reduce infrastructure overhead that virtualization stacks cannot match at this scale.
- Government:Federal agencies and defense contractors segment classified and unclassified traffic through mandatory procurement pools created by NIST guidelines. On-premises and air-gapped requirements dominate this vertical.
- Educational Institutions:University IT departments protect research intellectual property and student data across distributed campus networks. Budget constraints favor hybrid deployment models with phased cloud migration.
- Individual Users:Privacy-conscious professionals and journalists seek consumer-grade isolation against tracking and malware. Subscription pricing remains pressure-sensitive compared to organizational accounts.
Revenue concentration sits with Enterprises; Government represents the steepest expansion trajectory as zero-trust mandates compress procurement cycles.
Application:
Use-case segmentation determines feature prioritization across threat neutralization, access flexibility, and development workflow integration.
- Secure Browsing:Malware and phishing vector elimination drives the deepest margin pools through bundled threat-intelligence subscriptions. Banking and healthcare compliance teams mandate this application for endpoint protection.
- Remote Access:VPN replacement initiatives redirect capital toward browser-based network segmentation without client software distribution. Organizations retiring legacy concentrators prioritize this use case.
- Testing Environments:Security researchers execute suspicious code in sandboxed sessions without endpoint contamination risk. Containerized spin-up acceleration enables high-volume malware analysis workflows.
- Web Development:Cross-browser compatibility testing across isolated rendering engines eliminates local environment configuration conflicts. DevOps teams value session reproducibility for debugging pipeline integration.
Secure Browsing commands the largest installed base; Remote Access gains share fastest as hybrid workforce models persist.
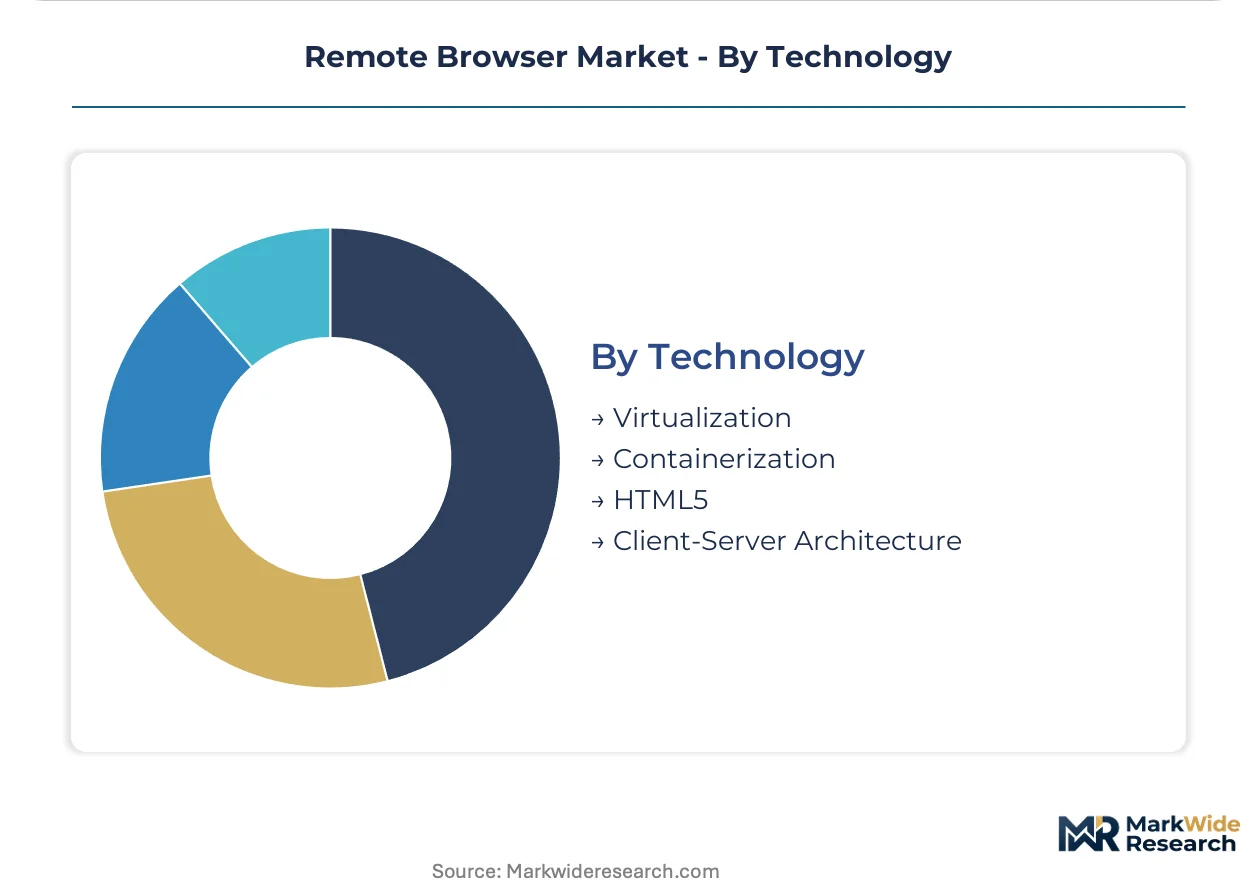
Technology:
Architecture choices determine infrastructure overhead, session performance, and compatibility with modern web standards.
- Containerization:Lightweight kernel namespaces reduce server density requirements and accelerate session initialization to under 100 milliseconds. Financial services deployments above 10,000 seats increasingly mandate this approach.
- Virtualization:Hypervisor-based isolation retains preference for high-assurance government environments requiring hardware-enforced boundaries. Legacy installations face refresh pressure from containerization cost advantages.
- HTML5:Browser-native rendering protocols eliminate plugin dependencies but struggle with WebGL and real-time collaboration features. Complexity limitations constrain adoption for multimedia-heavy enterprise applications.
- Client-Server Architecture:Traditional pixel-pushing protocols demand sub-50ms server proximity, raising edge infrastructure costs. Latency sensitivity limits geographic flexibility for distributed workforces.
Virtualization retains the largest legacy footprint; Containerization climbs the fastest as infrastructure refresh cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Washington DC's federal corridor anchors procurement activity as defense contractors and intelligence agencies scale isolated browsing deployments for classified network segmentation. Cloud migration acceleration across financial services clusters in New York and Chicago redirects capital toward elastic consumption models.
United States
NIST zero-trust guidelines mandate isolated browsing sessions for federal agencies segmenting classified and unclassified traffic. HIPAA security rule provisions drive hospital systems toward medical device isolation architectures. The Southeast corridor from Atlanta to Charlotte hosts expanding managed security service provider operations processing telemetry for mid-market enterprises.
Germany
EU AI Act risk-classification requirements force architectural transparency in automated content filtering pipelines. The country's national data protection regulator enforces strict documentation standards for high-risk web categorization decisions. Frankfurt's financial district concentrates demand from banking compliance teams mandating endpoint protection through bundled threat-intelligence subscriptions.
United Kingdom
GDPR accountability frameworks broaden enterprise liability for third-party web-borne supply chain risks. The Information Commissioner's Office scrutinizes cross-border data flows in isolated browsing sessions. London's fintech corridor drives containerized engine adoption for high-volume deployments exceeding 10,000 seats.
France
CNIL certification requirements prioritize vendors with pre-attested compliance documentation for public sector procurement. Healthcare systems in Île-de-France adopt hybrid architectures isolating medical device traffic from administrative web sessions. The Paris-Saclay research cluster generates demand for sandboxed testing environments executing suspicious code without endpoint contamination.
Japan
METI cybersecurity guidelines accelerate VPN replacement initiatives redirecting capital toward browser-based network segmentation. Financial institutions in Tokyo's Marunouchi district mandate secure browsing applications for phishing vector elimination. Osaka's manufacturing belt experiments with isolated sessions protecting industrial control system interfaces from web-borne threats.
Remote Browser Market Competitive Environment
The competitive structure tilts toward cloud-native specialists with federal certification credentials. Three distinct tiers operate: established cybersecurity platforms with integrated isolation modules, pure-play browser isolation vendors with containerized architectures, and managed service providers outsourcing security operations center staffing. Dominant competitive moves include strategic partnerships with federal integrators and portfolio diversification into adjacent zero-trust access segments.
Within the pure-play tier, Menlo Security and Ericom Software exemplify divergent deployment philosophies. Menlo Security occupies a position among cloud-native specialists anchoring large financial services deployments through elastic resource provisioning. Ericom Software represents the on-premises and air-gapped archetype serving defense contractors and intelligence agencies with physical infrastructure control requirements. Palo Alto Networks sits within the integrated platform tier, competing through tight coupling between its broader security fabric and remote browser capabilities.
| Leading Market Players |
|---|
| Ericom Software |
| Palo Alto Networks |
| Menlo Security |
| Netskope |
| Proofpoint |
| Citrix Systems |
| Cyberinc |
| Island |
| Authentic8 |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure spot pricing indices cascade through remote browser vendor cost structures, compressing margin pools for virtualization-based deployments while amplifying pricing power for containerized engine providers serving federal and financial services buyers with elastic consumption models.
Pricing Analysis
Value-based pricing anchored to threat-neutralization outcomes dominates the remote browser market, with vendors charging premiums proportional to malware interception rates and data exfiltration prevention guarantees. Three-tier pricing structure across premium, standard, and economy levels separates federal-certified deployments from mid-market SaaS tiers and basic consumer isolation. Pricing pressure stems from unbundling of threat-intelligence subscriptions as security procurement teams optimize recurring spend. Government buyers exhibit lowest price sensitivity due to mandatory NIST compliance requirements, while educational institutions face acute budget constraints favoring phased hybrid migrations.
Supply Chain Analysis
Dual-sourcing requirements for hyperscale cloud infrastructure compel remote browser vendors to maintain qualified supplier relationships across at least two of Amazon Web Services, Microsoft Azure, and Google Cloud Platform. Geographic supply concentration centers on the United States, Ireland, and Singapore for edge data center footprints supporting sub-50ms latency mandates. Raw material dependencies include silicon for server processors, optical fiber for backbone connectivity, and specialized ASICs for hardware security modules. Single-source vulnerability in GPU acceleration chips for pixel-pushing protocols creates procurement risk. Distribution runs through federal integrators and managed security service providers capturing mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containerized isolation engine capacity constraints prop pricing power for qualified vendors, as federal procurement pools outstrip available supply from certified providers meeting NIST zero-trust architecture guidelines.
For Market Incumbents: Anticipate containerization technology displacement of legacy virtualization stacks by accelerating kernel namespace R&D investment and securing edge data center leases in underserved Southeast and Midwest corridors. Threat-intelligence analyst scarcity demands automated telemetry processing pipelines to preserve margin structure against pure-play competitors. For New Entrants and Emerging Players: Enter via healthcare endpoint protection white space created by HIPAA medical device isolation requirements, targeting hospital systems in secondary metropolitan markets bypassed by federal-focused incumbents. Managed service packaging addresses internal security operations maturity gaps without requiring direct threat-intelligence infrastructure investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor containerized-engine specialists with pre-existing federal certification credentials in the United States, where procurement backlogs extend deployment timelines beyond 18 months. Long-term viability hinges on AI-generated phishing defense pipeline development. The signal to watch is vendor adaptation rates to synthetic identity fraud vectors as threat-intelligence monetization differentiator.| Strategic Initiative | Industry Significance |
|---|---|
| Federal Certification Investment | NIST zero-trust attestation unlocks mandatory procurement pools for classified network segmentation. |
| Containerization Platform Migration | Kernel namespace adoption reduces infrastructure overhead below virtualization economics for 10,000-plus seat deployments. |
| Threat-Intelligence Pipeline Acquisition | AI-generated phishing defense capabilities command premium subscription tiers in financial services accounts. |
| Edge Data Center Expansion | Sub-50ms server proximity satisfies latency sensitivity for pixel-pushing protocol performance guarantees. |
| Healthcare Vertical Partnership | HIPAA-compliant medical device isolation architectures access underserved hospital system demand. |
Study Parameters
Document review covered vendor technical documentation, federal procurement databases, and cloud infrastructure pricing disclosures, complemented by interviews with CISOs at Fortune 500 enterprises, federal IT security officers, managed security service provider operations directors, and healthcare biomedical engineers. Secondary validation drew from SEC filings of publicly traded cybersecurity platforms, hyperscaler capex disclosures, NIST publication archives, and EU AI Act implementation guidance. Bottom-up deployment volume estimates triangulated against top-down addressable market calculations.
Cross-referencing historical adoption curves with panel input from procurement officers across financial services, government, and healthcare verticals shaped the analytical framework. Segmentation dimensions modeled include deployment architecture, end-user organization type, application use case, and underlying isolation technology. CAGRs were derived from elasticity-adjusted growth trajectories across the projection horizon. Containerization penetration rates and federal procurement cycle compression served as industry-specific forecast inputs.
Revisions become necessary when EU AI Act risk-classification enforcement timelines accelerate, hyperscale cloud provider pricing volatility exceeds historical bands, or threat-intelligence analyst labor market tightness intensifies beyond current projections. Deviation in federal zero-trust mandate implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Charity Accounting Software Market
Software & Services
Specification Management Software Market
Software & Services
Construction Software Market
Software & Services
Global Website Builder Software Market
Software & Services
Database Monitoring Software Market
Software & Services
Global Automation Software Market
Software & Services
Sales Performance Management (SPM) Software Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Global Project Software Market
Software & Services
Optical Coatings Design Software Market
Software & Services
Mobile Application Testing Services (MATS) Market
Software & Services
Blogger Outreach Software Market
Software & Services
Supply Chain Visibility (SCV) Software Market
Software & Services
Global ERP Software Market
Software & Services
Global OKR Software Market
Software & Services
Coaching Management Software Market