
 Parcel Delivery Market | 2026-2036
Parcel Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Parcel Delivery Market Intelligence
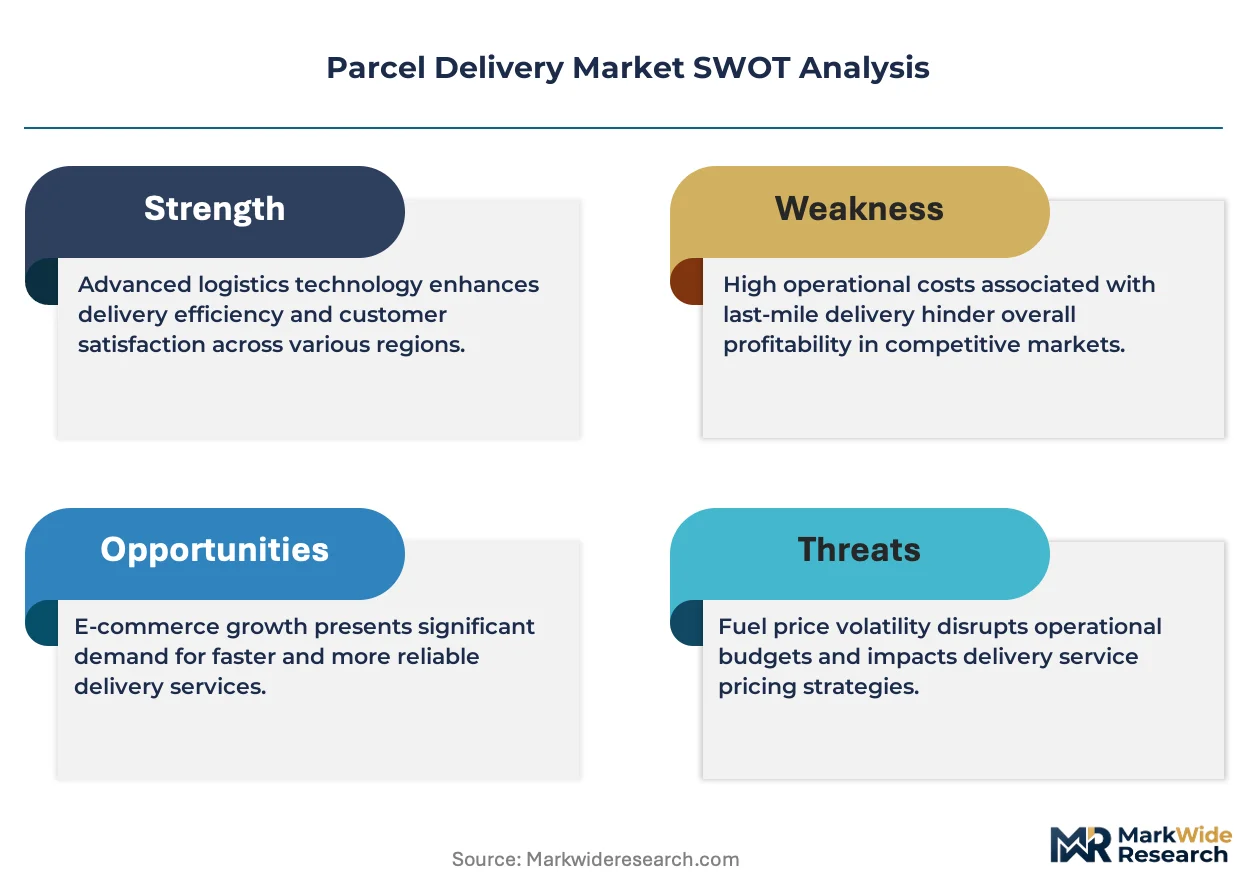
A capital-intensity divergence between automated hub operators and asset-light intermediaries is rotating competitive dynamics across the sector. DHL Express leverages integrated air-and-ground networks to sustain premium express margins across intercontinental lanes. FedEx anchors North American overnight capacity through Memphis superhub operations. Amazon Logistics competes by controlling captive last-mile density in major metropolitan zones.
Parcel delivery encompasses the physical movement of boxed, wrapped, or palletized goods from sender to recipient through scheduled or on-demand networks, typically tracked via barcode or RFID scanning at sortation and handoff points. The primary commercial purpose is enabling time-definite inventory replenishment and direct-to-consumer fulfillment across manufacturing, retail, and personal exchange. Same-day delivery and express delivery segments capture premium pricing from healthcare and electronics shippers requiring temperature control or chain-of-custody documentation. Standard delivery dominates volume throughput for e-commerce retailers optimizing free-shipping thresholds. Drone delivery and automated lockers represent nascent structural bets where regulatory clearance and property access agreements will determine scalability.
The US Postal Service operates under congressional pricing oversight while FAA rules govern commercial drone altitude and beyond-visual-line-of-sight operations. The EU Green Deal and national low-emission zones in Germany, France, and the Netherlands are mandating zero-emission last-mile fleets by specified deadlines. Stakeholders must monitor whether EPA tailpipe standards or EU battery-sourcing rules become the binding constraint on fleet electrification timelines.
Market Dynamics
Fleet electrification mandates are compressing carrier economics while automated sortation investments separate capital-rich hub operators from asset-light intermediaries, fundamentally restructuring competitive moats.
Growth Catalysts
- EU Green Deal mandates:Zero-emission last-mile requirements in Germany, France, and the Netherlands are forcing fleet conversions and opening charging infrastructure contracts.
- E-commerce inventory replenishment:Direct-to-consumer fulfillment networks now absorb the majority of parcel volumes as online shopping penetration deepens across retail verticals.
- Automated sortation hubs:Robotics-enabled facilities in China process extraordinary daily volumes, compressing unit costs and setting throughput benchmarks.
Market Restraints
- Lithium-ion battery supply concentration:Raw material processing bottlenecks in specific geographies constrain fleet electrification timelines for last-mile operators.
- Airspace regulatory fragmentation:FAA beyond-visual-line-of-sight rules and divergent national drone frameworks block scalable drone delivery deployment.
- Real estate access limitations:Urban locker placement and micro-fulfillment site acquisition face municipal zoning restrictions and property cost inflation.
Strategic Opportunities
- Healthcare cold-chain expansion:Temperature-controlled express segments for biologics and pharmaceuticals command premium pricing with stringent chain-of-custody requirements.
- India's e-commerce logistics gap:Underpenetrated tier-2 and tier-3 cities present white-space for automated hub investments and franchise last-mile models.
- EU battery-sourcing incentives:Domestic cell production subsidies under the Critical Raw Materials Act reduce import dependency for electric van fleets.
Industry Challenges
- Electrification technician scarcity:Fleet maintenance networks lack sufficient high-voltage systems training capacity to support rapid EV rollout.
- Legacy warehouse management integration:Automated sortation systems require costly retrofitting of existing facility control software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parcel Delivery Market |
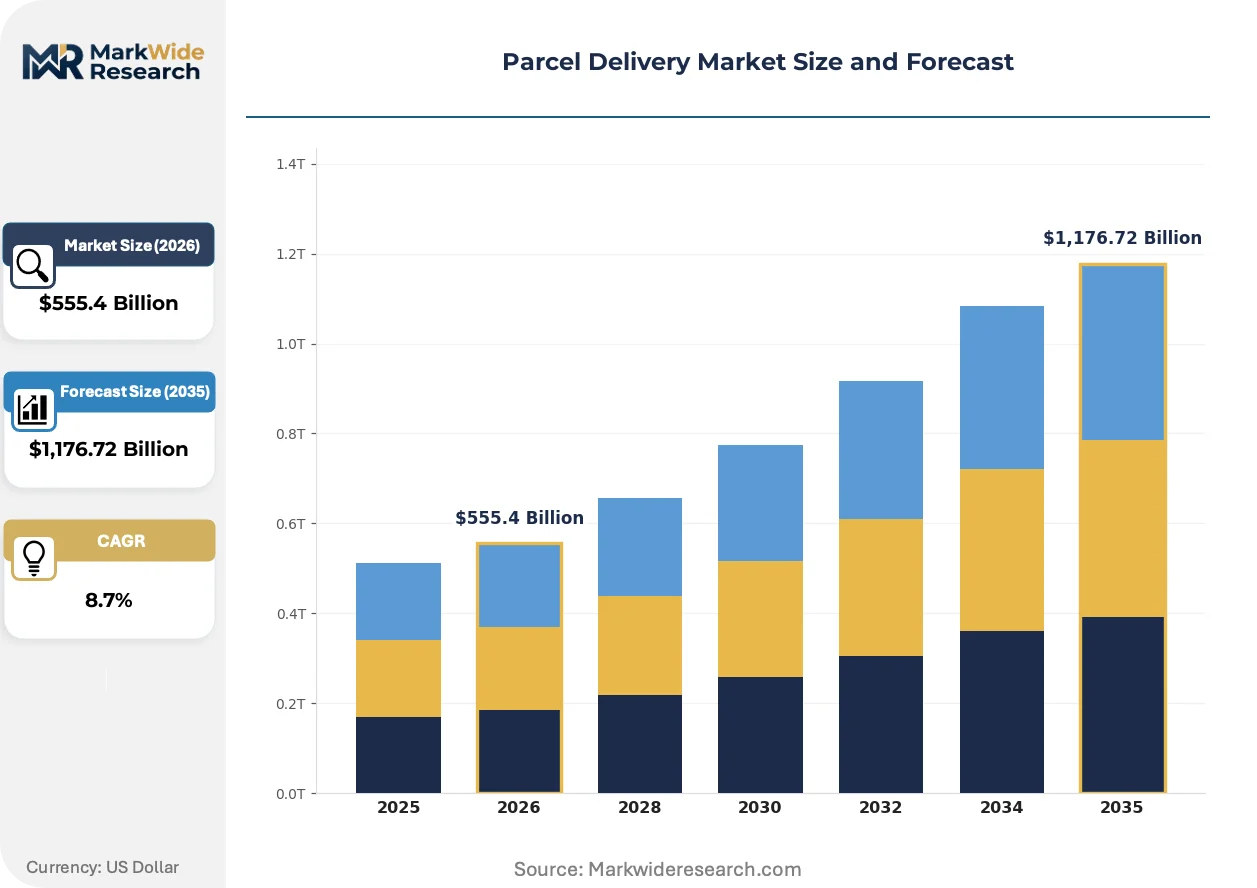
| Market Size in 2026 | $555.4 Billion |
| Market Size in 2035 | $1,176.72 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Standard Delivery, Express Delivery, Scheduled Delivery Delivery Mode: Bike Courier, Van Distribution, Drone Delivery, Automated Lockers, Freight Shipping Customer Type: E-commerce Retailers, Small Businesses, Government Agencies, Individual Consumers, Wholesalers Technology: Route Optimization Software, Real-Time Tracking, Electronic Proof of Delivery, AI-based Sorting, Mobile Apps |
| Companies Covered | DHL Express, Aramex, United Parcel Service (UPS), XPO Logistics, SF Express, FedEx, Amazon Logistics, LaserShip/OnTrac, United States Postal Service (USPS), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parcel Delivery Market Strategic Shifts & Innovations
Autonomous ground vehicles and AI-driven route optimization are compressing labor dependency while regulatory frameworks struggle to match deployment velocity.
Electric vans with swappable battery architectures are supplanting depot-charging models for high-utilization urban routes. Courier fleets in California and the Netherlands are piloting hot-swap stations that eliminate dwell time. This architecture is supplanting traditional overnight charging infrastructure and enabling 22-hour vehicle utilization.
EU battery-sourcing rules under the Critical Raw Materials Act are tightening supply chain disclosure requirements for fleet operators. Manufacturers must now document upstream mining and refining origins for electric vehicle cells. Last-mile carriers with European operations are accelerating supplier audits and diversifying cell procurement to maintain compliance eligibility.
Same-day delivery expectations are compressing inventory positioning decisions for electronics and fashion retailers. Urban micro-fulfillment nodes and dark store networks are displacing centralized distribution for high-velocity SKUs. This pattern is most visible in Chinese metropolitan zones where SF Express and domestic platforms operate integrated instant delivery ecosystems.
Parcel Delivery Market Segmentation
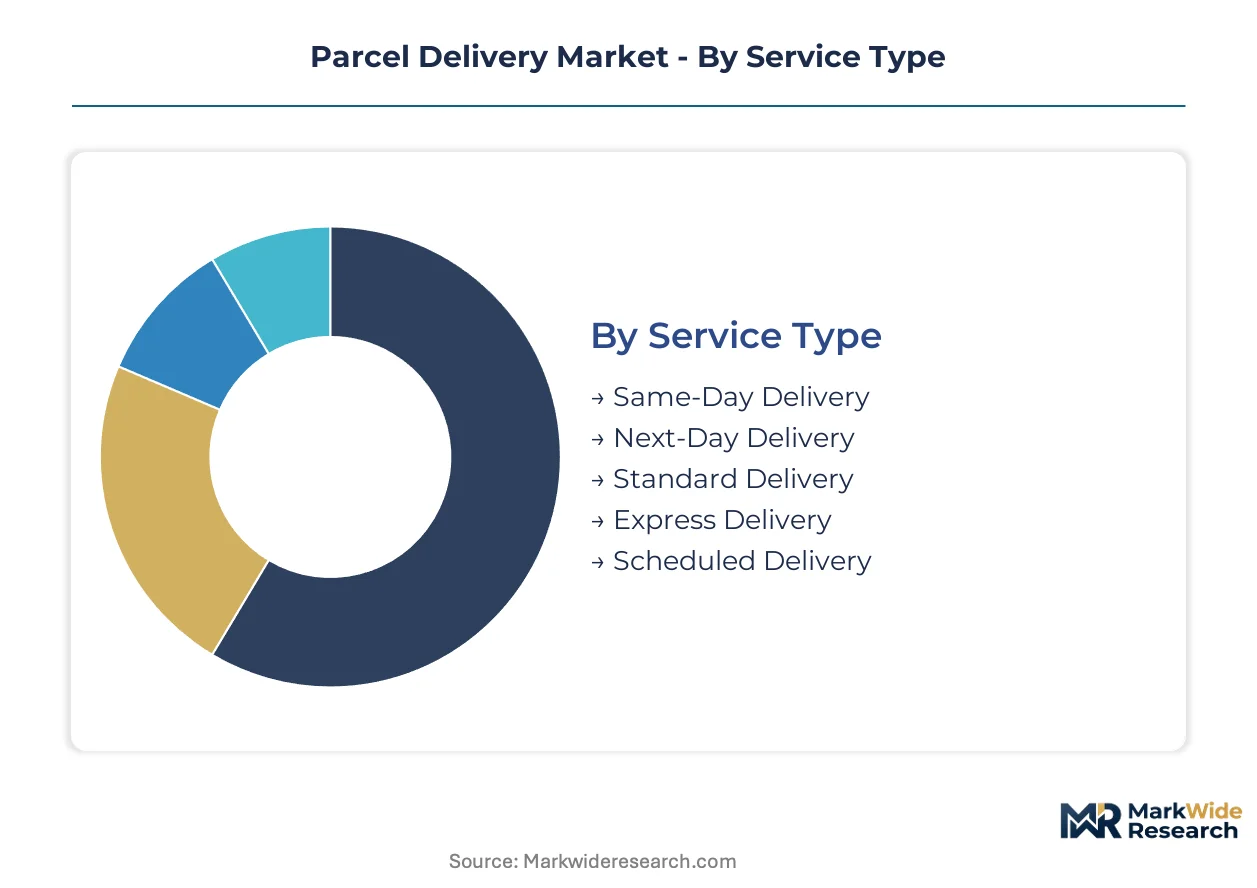
Parcel delivery segmentation reveals how service architecture, fleet composition, and customer economics divide competitive terrain. Each dimension exposes distinct margin profiles and capital requirements that reshape carrier strategy across urban, suburban, and intercontinental lanes.
Service Type:
Domestic same-day networks concentrate in dense metropolitan corridors, while express and standard services span export-led intercontinental corridors.
- Same-Day Delivery:Urban micro-fulfillment nodes and courier density enable two-to-four-hour windows for electronics and fashion retailers. China and India absorb the steepest investment flows as instant gratification expectations harden.
- Express Delivery:Time-definite morning delivery with chain-of-custody documentation commands premium pricing from healthcare and aerospace shippers. Temperature-controlled biologics traffic drives specialized fleet specifications in Germany and Switzerland.
- Next-Day Delivery:Overnight sortation hub operations with guaranteed morning arrival. E-commerce retailers absorb the majority of volume through free-shipping threshold engineering.
- Standard Delivery:Two-to-five-day ground networks optimizing load consolidation and hub-and-spoke efficiency. Free-shipping economics dominate customer acquisition strategy.
- Scheduled Delivery:Appointment-based arrival windows for furniture, appliances, and bulky goods requiring white-glove handling. Real estate access and two-person crew availability constrain scalability.
Standard delivery commands the established base. The steepest expansion runs through same-day delivery.
Delivery Mode:
Cost tier stratification separates capital-light human-powered fleets from infrastructure-heavy automation bets.
- Van Distribution:Diesel and electric panel vans handle 70-plus percent of parcel volume through depot-based routing. EU Green Deal mandates in France and the Netherlands are forcing zero-emission fleet conversions with charging infrastructure contracts.
- Bike Courier:Cargo bicycles and e-bikes navigate congestion-charged city centers with sub-kilogram payload limits. Copenhagen and Amsterdam regulatory frameworks favor lane infrastructure investment.
- Drone Delivery:Beyond-visual-line-of-sight autonomous aircraft for remote and urgent medical shipments. FAA altitude restrictions and fragmented national airspace rules block scalable deployment.
- Automated Lockers:Secure pickup points in retail parking lots and transit stations reduce failed delivery attempts. Property access agreements and municipal zoning create rollout friction.
- Freight Shipping:Palletized less-than-truckload and full-truckload movements for B2B replenishment. Intermodal rail integration cuts fuel exposure on long-haul lanes.
Van distribution commands the established base. The steepest expansion runs through automated lockers.
Customer Type:
Volume concentration separates high-frequency e-commerce platforms from sporadic individual shippers with divergent price sensitivity.
- E-commerce Retailers:Direct-to-consumer platforms generating daily parcel flows exceeding millions of units. Inventory positioning algorithms and free-shipping thresholds compress carrier margins through volume concentration.
- Small Businesses:Fragmented merchants with irregular shipping patterns and limited negotiation leverage. Aggregator platforms and postal partnerships provide access to commercial rates.
- Government Agencies:Contracted mail delivery and procurement logistics with congressional or parliamentary pricing oversight. Universal service obligations constrain profit extraction.
- Individual Consumers:Peer-to-peer shipments and returns with highest per-unit cost tolerance. Mobile app interfaces and drop-off point density drive platform selection.
- Wholesalers:B2B pallet consolidation and cross-dock operations with scheduled replenishment cycles. Freight brokerage relationships dominate procurement patterns.
E-commerce retailers command the established base. The steepest expansion runs through small businesses.
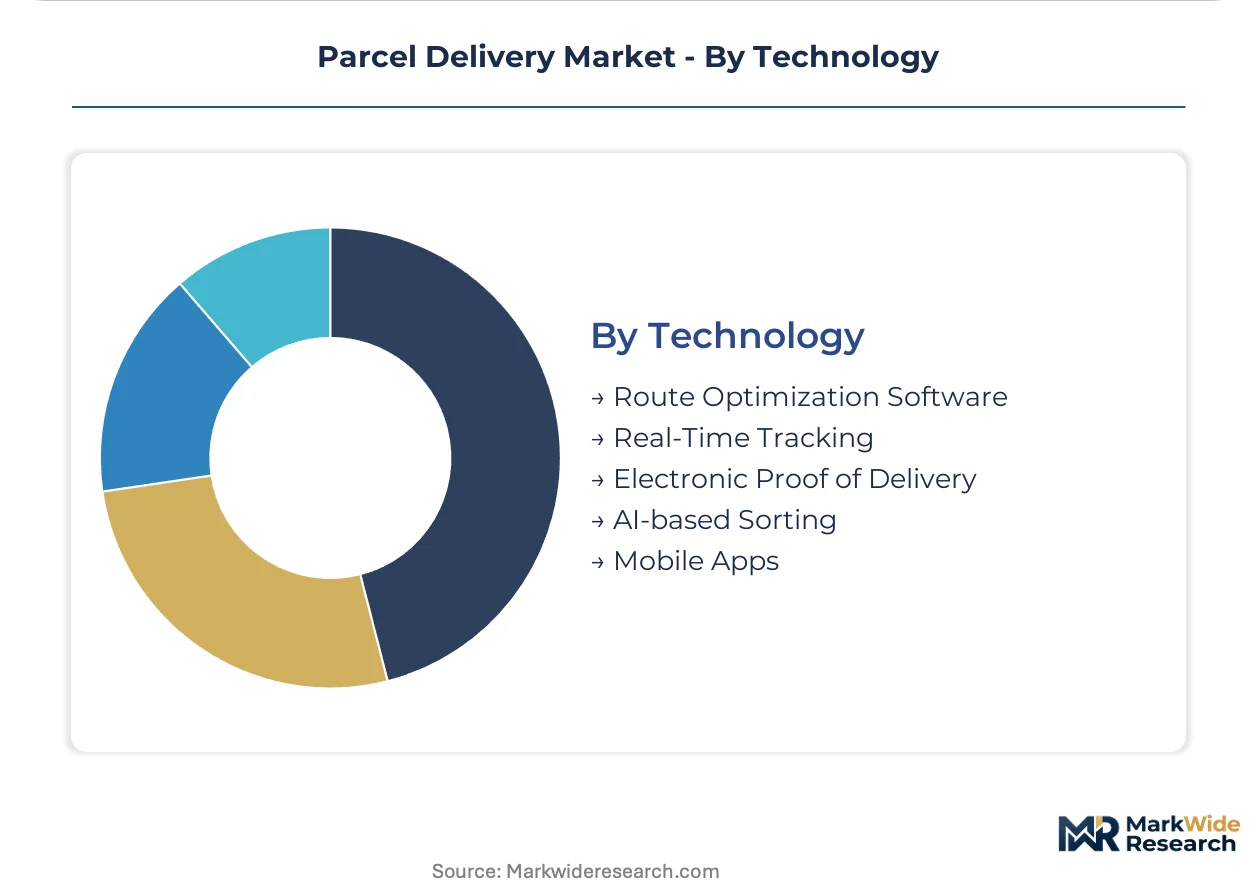
Technology:
Maturity gradients separate legacy barcode scanning from AI-native sortation and predictive routing systems.
- AI-based Sorting:Computer vision and robotic arms processing thousands of parcels hourly through automated hubs. Chinese operators set throughput benchmarks compressing unit costs.
- Route Optimization Software:Dynamic algorithms recalculating sequences based on traffic, weather, and delivery density. Real-time data feeds from municipal traffic management systems improve accuracy.
- Real-Time Tracking:GPS and cellular telemetry providing minute-by-minute location visibility. Customer expectation inflation is making this a baseline hygiene factor.
- Electronic Proof of Delivery:Signature capture, photo verification, and timestamped geolocation reducing dispute liability. Insurance and claims processing workflows depend on this data layer.
- Mobile Apps:Customer-facing interfaces for scheduling, redirection, and pickup coordination. Retention economics favor platforms with superior UX density.
Route optimization software commands the established base. The steepest expansion runs through AI-based sorting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Chinese e-commerce consumers demand free shipping thresholds that compress carrier margins, while Swiss pharmaceutical shippers accept premium express rates for temperature-controlled chain-of-custody documentation. This elasticity divergence shapes infrastructure investment patterns and fleet specification decisions.
China
SF Express and domestic platforms process extraordinary daily volumes through automated sorting hubs in the Yangtze River Delta. MIIT dual carbon goals accelerate electric van fleet conversions across last-mile networks. Shenzhen and Hangzhou host the densest concentrations of robotics-enabled facilities, compressing unit costs and setting throughput benchmarks for global operators.
United States
Amazon Logistics controls captive last-mile density in major metropolitan zones, forcing traditional carriers to defend market position through speed differentiation. FAA beyond-visual-line-of-sight rules govern commercial drone altitude and block scalable autonomous delivery deployment. Memphis anchors North American overnight capacity through superhub operations that integrate air-and-ground networks.
Germany
EU Green Deal mandates enforce zero-emission last-mile requirements that force fleet conversions and open charging infrastructure contracts. KBA vehicle-type approval processes govern electric van homologation timelines. The Rhine-Ruhr corridor concentrates automated sortation investments as DHL Express leverages integrated networks to sustain premium express margins across intercontinental lanes.
India
Underpenetrated tier-2 and tier-3 cities present white-space for automated hub investments and franchise last-mile models as e-commerce penetration deepens. BIS standards govern lithium-ion battery safety certification for electric two-wheeler and three-wheeler delivery fleets. Mumbai and Delhi-NCR absorb the steepest capital flows as Flipkart and Amazon India expand same-day coverage.
Netherlands
National low-emission zones in Amsterdam and Rotterdam mandate zero-emission last-mile fleets by specified deadlines that compress carrier economics. EU battery-sourcing rules under the Critical Raw Materials Act tighten supply chain disclosure requirements for electric vehicle cells. Eindhoven and the Randstad cluster pilot swappable battery architectures that eliminate dwell time and enable 22-hour vehicle utilization.
Parcel Delivery Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence separating automated hub operators from asset-light intermediaries. The upper tier commands premium pricing through network density and time-definite service guarantees. Three archetypes dominate: integrated express carriers with owned air fleets, e-commerce captive logistics divisions, and regional last-mile specialists. Competitive moves concentrate on fleet electrification partnerships and automated sortation capacity expansion.
Within the integrated express tier, DHL Express and FedEx exemplify network-scale operators that combine intercontinental air lift with ground distribution density. SF Express anchors the China-centric archetype of domestic platform-integrated logistics. These entities occupy positions where automated hub investments and regulatory compliance capabilities create defensive moats against asset-light challengers.
| Leading Market Players |
|---|
| DHL Express |
| Aramex |
| United Parcel Service (UPS) |
| XPO Logistics |
| SF Express |
| FedEx |
| Amazon Logistics |
| LaserShip/OnTrac |
| United States Postal Service (USPS) |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts with automated hub operators lock in both sortation throughput access and multi-year price visibility for e-commerce retailers facing EU Green Deal fleet conversion deadlines. These arrangements tether pricing stability to electrification infrastructure buildout timelines across Germany, France, and the Netherlands.
Pricing Analysis
After-sales revenue from extended service contracts and maintenance agreements drives lifetime value for automated sortation systems. Three-tier pricing structure across premium express, standard ground, and economy deferred delivery segments separates time-definite guarantees from consolidated load efficiency. Pricing pressure stems from e-commerce retailers engineering free-shipping thresholds that compress carrier margins. Small businesses exhibit highest price sensitivity due to fragmented volume concentration, while pharmaceutical shippers accept premium rates for temperature-controlled chain-of-custody documentation.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific trade lanes through Rotterdam and Hamburg anchor total landed cost for automated sortation equipment and electric van components. Supply concentrates in China for lithium-ion battery cells, Germany for precision robotics, and South Korea for power electronics. Raw material dependencies span cobalt cathodes, rare-earth magnets, and high-grade aluminum extrusions. Single-source vulnerability in battery cell processing creates structural risk. Distribution runs through regional hub-and-spoke networks with last-mile depot saturation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU fleet electrification mandates and automated sortation investments are disrupting competitive moats across parcel delivery, creating asymmetric opportunities for capital-rich operators.
For Market Incumbents: Fortify network density through captive charging infrastructure partnerships in Amsterdam and Rotterdam low-emission zones. Accelerate technician training capacity for high-voltage fleet maintenance to preempt electrification rollout bottlenecks. Defend against asset-light intermediaries by embedding AI-driven route optimization as a baseline service layer. For New Entrants and Emerging Players: Anchor in India's tier-2 and tier-3 city white-space where automated hub penetration remains underdeveloped. Target franchise last-mile models with localized fleet ownership structures. Pursue healthcare cold-chain specialization with temperature-controlled biologics credentials to bypass commodity pricing. For Investors and Strategic Acquirers: Regional last-mile specialists with integrated locker networks and municipal property access agreements offer consolidation value. Long-term viability hinges on electrification compliance timelines and automated sortation throughput scalability. Monitor EU battery-sourcing audit completion rates as an inflection indicator for fleet conversion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | EU Green Deal mandates in Germany and the Netherlands force zero-emission vehicle procurement with charging infrastructure lock-in. |
| Automated Sortation Expansion | Robotics-enabled hubs in Shenzhen and Hangzhou set throughput benchmarks that compress unit costs for e-commerce volume. |
| Healthcare Cold-Chain Certification | Temperature-controlled biologics traffic commands premium pricing with stringent FDA and EMA chain-of-custody requirements. |
| Micro-Fulfillment Network Buildout | Urban dark stores displace centralized distribution for same-day electronics and fashion delivery in dense metropolitan zones. |
| Swappable Battery Architecture Pilot | Hot-swap stations in California and the Netherlands eliminate dwell time and enable 22-hour vehicle utilization rates. |
Research Approach
The analysis maps same-day, express, next-day, standard, and scheduled delivery segments, each validated through fleet operations directors, e-commerce logistics procurement managers, automated hub engineers, and last-mile franchise operators. Primary interview findings triangulate against customs trade data, EU Green Deal regulatory filings, FAA airspace rule dockets, SEC carrier 10-K disclosures, and MIIT dual carbon policy documents. Bottom-up volume modeling and top-down market sizing cross-validate through independent analyst estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions span service type, delivery mode, customer archetype, and technology maturity tier. CAGRs derive from historical trajectory analysis adjusted for electrification mandate compliance curves and automated sortation deployment schedules. Forecast inputs incorporate e-commerce penetration rates and battery cell supply availability.
Decision-makers should treat outputs as directional under assumptions of regulatory timeline adherence and lithium-ion supply chain stability; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Middle-East and North Africa Taxi Market
Transportation & Logistics
Trade-In and Buy-Back Logistics Programs Management Market
Transportation & Logistics
Pipeline Transportation Software Market
Transportation & Logistics
GCC Refrigerated Transport Market
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
France Road Freight Transport Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
Latin America Customs Brokerage Market
Transportation & Logistics
China Road Freight Transport Market
Transportation & Logistics
Germany Cold Chain Logistics Market
Transportation & Logistics
Railcar Unloader Market
Transportation & Logistics
US Tolling Market
Transportation & Logistics
Hungary Road Freight Transport Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Fuel Management Systems (FMS) Market