
 China Road Freight Transport Market | 2026-2036
China Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
China Road Freight Transport Market Outlook
Express parcel networks is fragmenting as e-commerce volumes force dedicated lane structures alongside traditional less-than-truckload corridors. JD Logistics leverages its captive warehouse footprint to control last-mile scheduling density. SF Express sustains premium positioning through integrated air-road capacity. ZTO Express (Cayman) Inc. anchors volume leadership in automated sortation infrastructure across county-level nodes.
China road freight transport encompasses the movement of goods via motor vehicles on national highway and provincial road networks, utilizing vehicles ranging from light commercial vans to heavy-duty diesel and electric tractors with gross vehicle weights exceeding 49 tonnes, primarily serving manufacturing supply chains, retail distribution, and agricultural commodity flows. Full Truck Load operations dominate tonnage moved but carry thinner margins, while Same-Day Delivery commands premium pricing through time-definite service guarantees. Heavy-Duty Trucks constitute the fleet backbone for interprovincial haulage, though Refrigerated Trucks represent the fastest-expanding vehicle category as cold-chain food safety standards tighten.
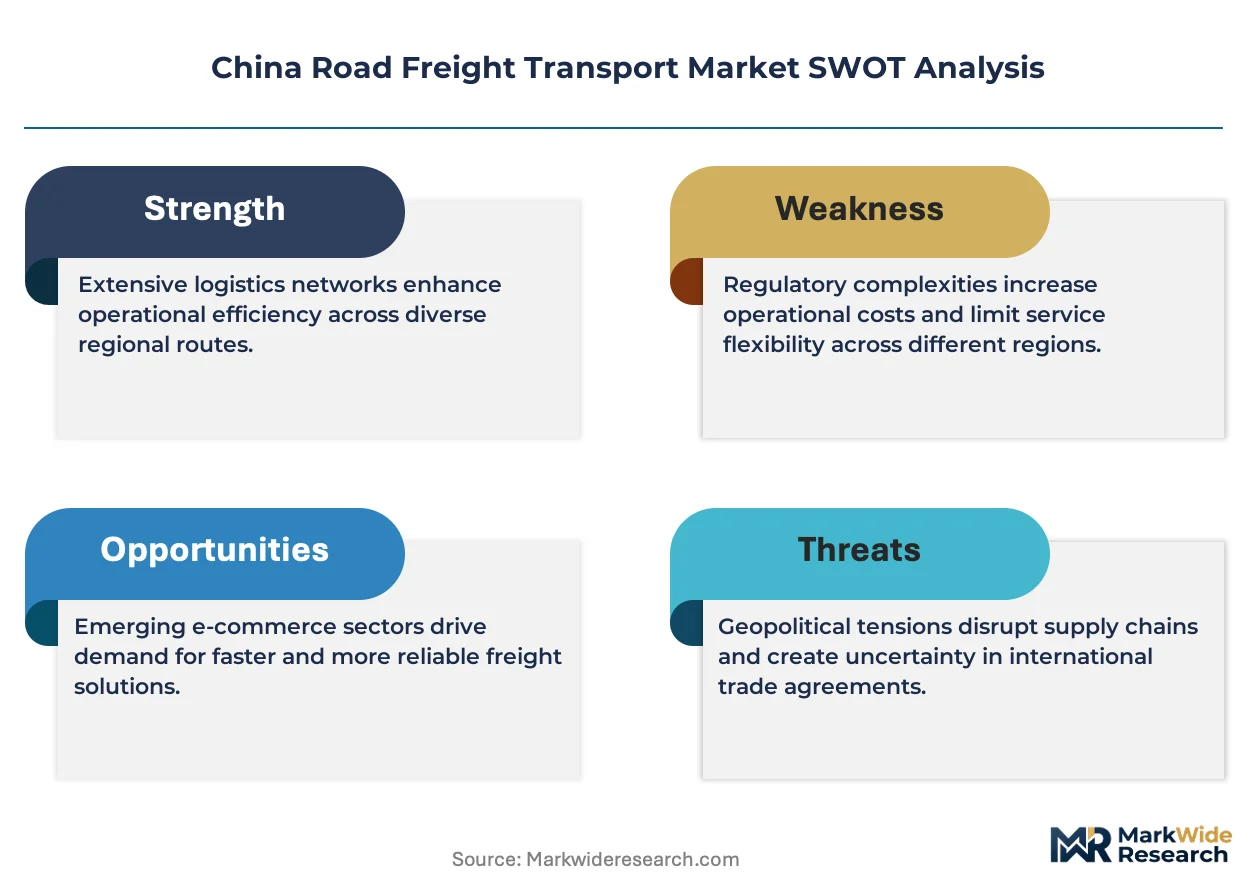
MIIT establishes vehicle fuel consumption limits and NEV production quotas that directly shape OEM product planning and operator procurement cycles, while SAMR enforces road freight pricing transparency rules that constrain arbitrary surcharge practices. GB standards mandate braking performance and dimensional limits that filter non-compliant equipment from national expressways. Fleet operators and logistics platforms must monitor how MEE emissions enforcement timelines interact with provincial NEV subsidy phase-outs to time capital deployment.
Market Dynamics
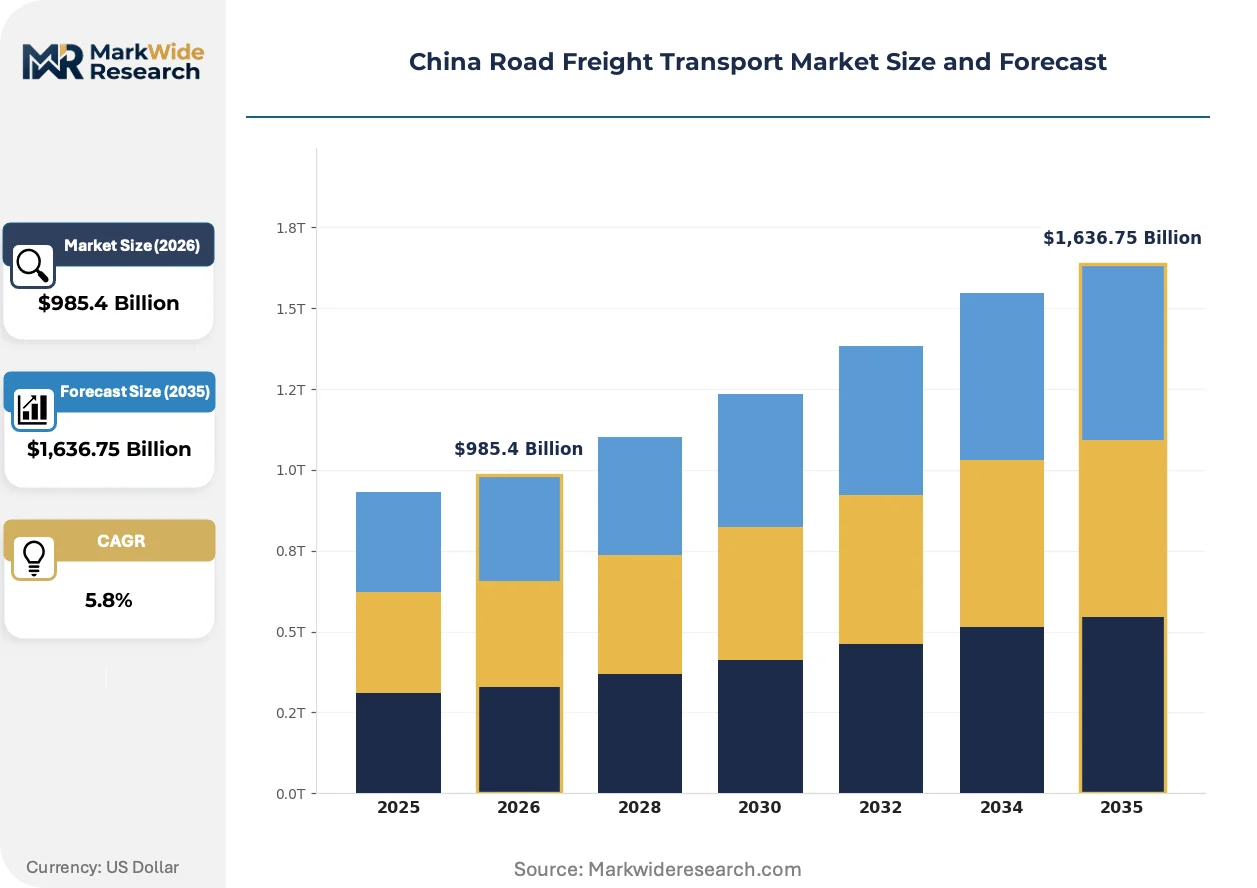
MIIT fuel-efficiency mandates and NEV production quotas are compressing diesel truck replacement cycles while e-commerce fulfillment density reshapes lane economics across China's expressway network.
Growth Catalysts
- Dual Carbon Policy Framework:China's national carbon neutrality targets accelerate fleet electrification through provincial subsidy tiers and charging infrastructure deployment along major corridors.
- Cold-Chain Regulatory Expansion:SAMR enforcement of food safety traceability standards drives refrigerated truck procurement across agricultural wholesale and pharmaceutical distribution networks.
- Yangtze River Delta Manufacturing Cluster:Concentrated electronics and automotive production in Jiangsu and Zhejiang generates sustained FTL demand for interprovincial component movements.
Market Restraints
- Lithium-Ion Battery Cost Volatility:Raw material price swings for cathode minerals constrain NEV truck total cost of ownership parity against diesel equivalents.
- Charging Infrastructure Asymmetry:Western provinces lack high-power charging stations along long-haul routes, limiting electric heavy-duty tractor deployment to urban and regional circuits.
- Driver Labor Pool Contraction:Aging demographics and vocational preference shifts reduce qualified heavy-duty license holders available for overnight haulage.
Strategic Opportunities
- Autonomous Hub-to-Hub Corridors:Beijing-Tianjin-Hebei and Chengdu-Chongqing expressway segments offer closed-environment testing for platooning and driver-out pilot programs.
- Rural County-Level Consolidation:Underpenetrated western county nodes present automated sortation infrastructure deployment potential for e-commerce parcel aggregation.
- Hydrogen Fuel Cell Integration:MEE pilot zones in Foshan and Zhengzhou subsidize fuel-cell heavy trucks for routes exceeding electric range thresholds.
Industry Challenges
- Telematics System Interoperability:Fleet operators face integration complexity when merging legacy diesel vehicle monitoring platforms with NEV battery management and charging optimization software.
- GB Standard Compliance Timeline:Braking performance and dimensional limit updates require mid-life fleet retrofitting or accelerated replacement decisions ahead of enforcement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Road Freight Transport Market |
| Market Size in 2026 | $985.4 Billion |
| Market Size in 2035 | $1,636.75 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less Than Truck Load, Same-Day Delivery, Freight Brokerage Vehicle Type: Light Commercial Vehicles, Heavy-Duty Trucks, Refrigerated Trucks, Flatbed Trucks End User: Manufacturing, Retail, E-Commerce, Agriculture Pricing Model: Fixed Rate, Distance-Based, Subscription-Based, Spot Market |
| Companies Covered | STO Express Co., Ltd., JD Logistics, Deppon Logistics Co., Ltd., SINO Shipping, Manbang, SF Express, ZTO Express (Cayman) Inc., Kuehne+Nagel, Shanghai YTO Express (Logistics) Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Road Freight Transport Market Strategic Shifts
Digital freight matching platforms are restructuring spot-market price discovery while automated warehouse-to-vehicle handoff systems compress dwell times at distribution centers.
Intelligent trailer telematics is migrating from basic GPS tracking to integrated cargo sensing, temperature logging, and door-seal monitoring. Pharmaceutical distributors and fresh-food retailers are adopting these systems fastest. The technology is migrating from premium fleet segments toward standard equipment on new refrigerated builds, compressing differentiation timelines for mid-tier operators.
MIIT's Phase IV fuel consumption limits tighten heavy-duty truck efficiency thresholds through model-year 2025. OEM product planning cycles now prioritize aerodynamic optimization and mild-hybrid architectures alongside full-electric platforms. Long-haul tractor segments face the steepest engineering investment requirements, with manufacturers accelerating wind-tunnel testing partnerships.
Consolidated procurement by e-commerce platforms concentrates volume commitments with select logistics providers, displacing fragmented shipper-carrier spot relationships. Tier-one express networks now secure dedicated lane capacity through multi-year contracts with guaranteed volume floors. This concentration is most visible in Yangtze Delta corridors serving Shanghai Pudong and Hangzhou Xiaoshan airport cargo zones.
China Road Freight Transport Market Segmentation
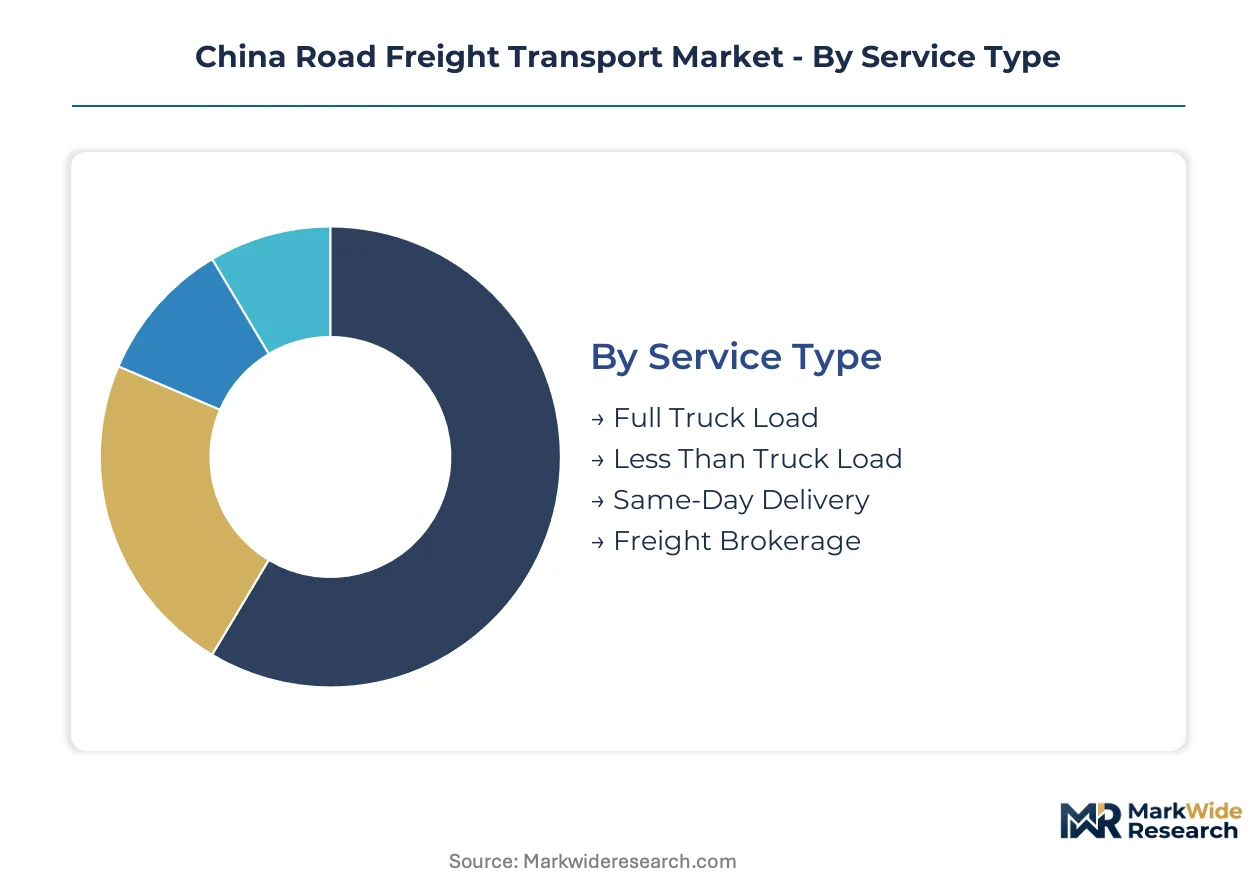
Segmentation in China's road freight market reveals how service specialization, vehicle technology, and pricing mechanisms diverge across customer requirements. Each dimension captures distinct operational economics and regulatory exposure that shape carrier strategy and capital allocation priorities.
Service Type:
Mature corridor operations coexist with emerging time-definite services as e-commerce density reshapes lane economics across China's expressway network.
- Full Truck Load:Dedicated vehicle capacity for single-shipper movements dominates interprovincial manufacturing supply chains. Yangtze River Delta electronics clusters generate sustained FTL demand for component movements between Jiangsu assembly plants and Zhejiang distribution hubs.
- Less Than Truck Load:Consolidated shipments from multiple shippers share trailer space through hub-and-spoke terminal networks. Traditional LTL corridors face margin compression as express parcel networks capture mid-size freight volumes with faster transit guarantees.
- Same-Day Delivery:Time-definite urban distribution commands premium pricing through guaranteed delivery windows.
- Freight Brokerage:Digital platforms match spot capacity with shipper demand, restructuring price discovery in fragmented lanes.
Full Truck Load retains volume leadership; Same-Day Delivery holds the steepest expansion curve.
Vehicle Type:
Cost tier stratification separates standardized diesel platforms from premium electric and temperature-controlled specifications facing divergent regulatory timelines.
- Heavy-Duty Trucks:Diesel and electric tractors exceeding 49 tonnes GVW form the backbone of long-haul interprovincial movements. MIIT Phase IV fuel consumption limits and NEV subsidies are compressing replacement cycles toward electrified platforms in coastal provinces.
- Refrigerated Trucks:Insulated bodies with integrated cooling units maintain temperature-controlled cargo environments. SAMR enforcement of food safety traceability standards drives procurement across agricultural wholesale networks and pharmaceutical distribution chains.
- Light Commercial Vehicles:Urban last-mile delivery platforms operate under stricter emissions zones in Beijing and Shanghai.
- Flatbed Trucks:Open-deck configurations handle oversized industrial equipment and construction materials.
Heavy-Duty Trucks retain volume leadership; Refrigerated Trucks are gaining share fastest.
End User:
Application concentration varies sharply between contract-driven manufacturing logistics and volatile e-commerce fulfillment patterns.
- E-Commerce:Parcel networks serving JD.com and Alibaba platforms pull capacity toward automated sortation infrastructure and dedicated express lanes. County-level node penetration remains underdeveloped in western provinces, presenting consolidation opportunities.
- Manufacturing:Just-in-time component movements for automotive and electronics production require scheduled reliability over cost minimization. Jiangsu and Zhejiang industrial clusters sustain dedicated lane contracts with guaranteed volume floors.
- Retail:Traditional distribution networks face channel shift pressure as direct-to-consumer fulfillment displaces store replenishment models.
- Agriculture:Seasonal harvest movements and cold-chain compliance requirements create irregular demand spikes.
Manufacturing retains volume leadership; E-Commerce is climbing the fastest.
Pricing Model:
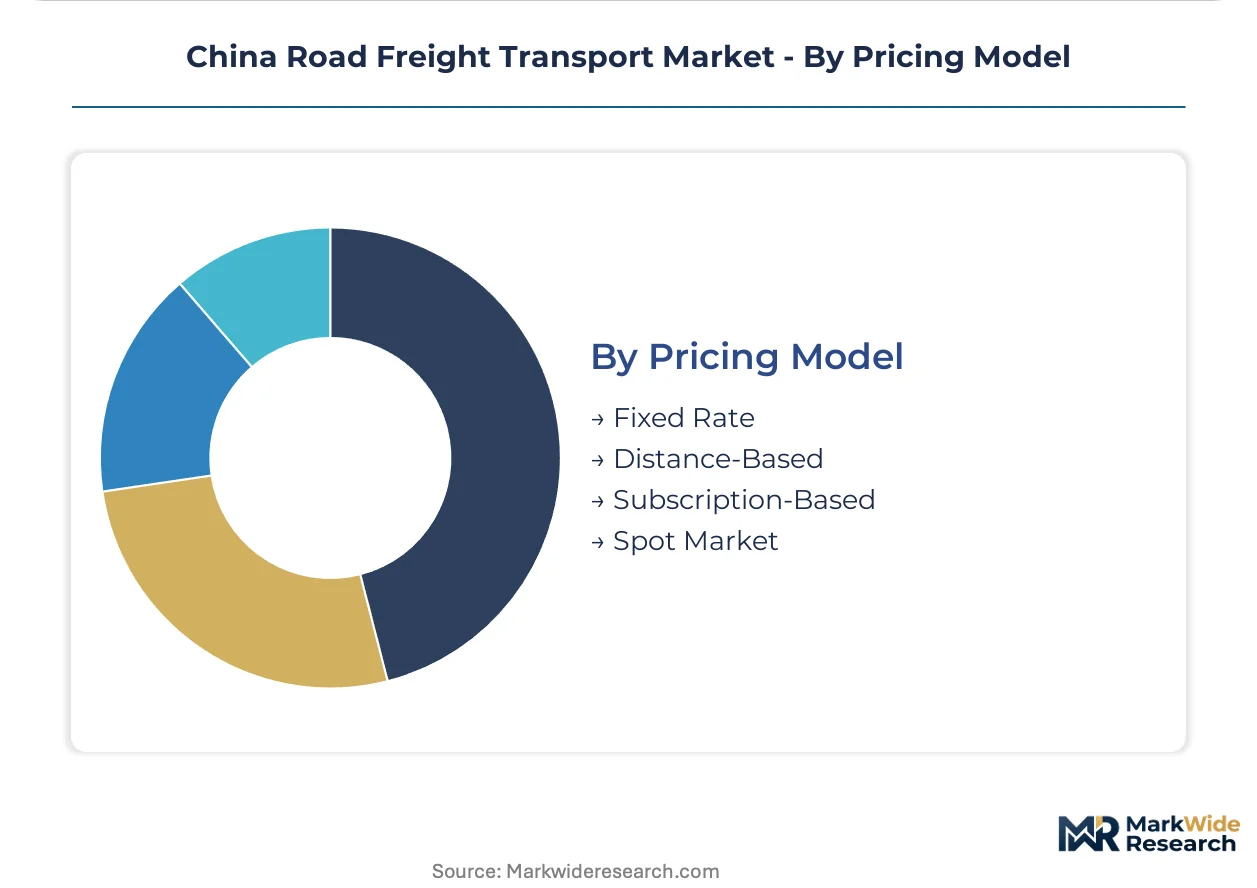
Customer type and volume commitment determine whether shippers absorb rate volatility or transfer risk to carriers through structured contracts.
- Spot Market:Real-time price discovery through digital freight platforms matches immediate capacity with urgent shipments. Telematics integration enables dynamic pricing based on lane congestion and backhaul availability.
- Fixed Rate:Contractual price certainty for predictable volume flows allows shippers to budget logistics costs across annual planning cycles.
- Distance-Based:Per-kilometer tariffs align costs with actual movement economics on long-haul corridors.
- Subscription-Based:Flat-fee structures for regular shippers prioritize capacity reservation over marginal cost pricing.
Fixed Rate retains volume leadership; Spot Market shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal provinces command premium freight rates through manufacturing density and port proximity, while interior regions absorb thinner margins on longer-haul corridors with weaker backhaul economics.
Yangtze River Delta
Electronics and automotive component flows between Shanghai, Jiangsu, and Zhejiang sustain dedicated FTL contracts with volume guarantees. MIIT Phase IV fuel standards accelerate fleet turnover toward electric tractors in this corridor. Hangzhou Xiaoshan and Shanghai Pudong airport cargo zones concentrate express parcel sortation infrastructure.
Pearl River Delta
Cross-border e-commerce fulfillment through Shenzhen and Guangzhou pulls refrigerated capacity toward fresh-food export processing. SAMR cold-chain traceability enforcement drives pharmaceutical distributor fleet upgrades. Dongguan manufacturing clusters generate sustained demand for interprovincial component haulage to central China.
Beijing-Tianjin-Hebei
Capital region emissions zones restrict diesel truck access, compressing replacement cycles toward NEV platforms. MEE enforcement timelines interact with municipal subsidy programs to shape procurement decisions. Tianjin port container drayage and Beijing last-mile delivery create distinct operational sub-markets with diverging vehicle specifications.
Sichuan-Chongqing
Western manufacturing relocation and consumer market expansion generate rising freight volumes on east-west corridors. Provincial NEV subsidy tiers support electric heavy-duty deployment on Chengdu-Chongqing expressway segments. Chongqing automotive plants and Chengdu electronics assembly sustain scheduled component movements with reliability requirements.
Western China
Xinjiang and Gansu agricultural commodity flows face seasonal demand spikes and cold-chain compliance requirements. Charging infrastructure asymmetry limits electric tractor deployment to urban circuits around Xi'an and Lanzhou. Belt and Road corridor development reshapes cross-border freight routing through Khorgos and Alashankou.
China Road Freight Transport Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in vehicle supply and terminal equipment. The market structure concentrates around e-commerce-aligned express networks and digital freight matching platforms, with traditional LTL operators defending corridor positions through dedicated manufacturing contracts. Three archetypes dominate: captive logistics arms of retail platforms, independent express networks with automated infrastructure, and asset-light digital brokers. Competitive moves center on multi-year volume commitments with guaranteed lane capacity and backward integration into warehouse-to-vehicle handoff systems.
Among platform-captive operators, JD Logistics exemplifies warehouse-network control over scheduling density. SF Express and ZTO Express (Cayman) Inc. occupy positions within the independent express tier, differentiated by air-road integration depth versus automated sortation scale. These three entities represent divergent strategic bets on infrastructure ownership versus asset-light platform economics.
| Leading Market Players |
|---|
| STO Express Co., Ltd. |
| JD Logistics |
| Deppon Logistics Co., Ltd. |
| SINO Shipping |
| Manbang |
| SF Express |
| ZTO Express (Cayman) Inc. |
| Kuehne+Nagel |
| Shanghai YTO Express (Logistics) Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta manufacturing clusters concentrate heavy-duty tractor procurement power, translating fleet-scale volume commitments into preferential rate negotiations with OEMs and downstream lane pricing leverage against fragmented shippers. MIIT Phase IV compliance costs and NEV subsidy tiers feed directly into contract rate escalators, compressing margin buffers for operators lacking scale.
Pricing Analysis
The customization-premium spread separates dedicated FTL contracts with guaranteed volume floors from volatile spot-market transactions. Fixed-rate multi-year agreements dominate Yangtze Delta electronics corridors, while digital freight platforms enable dynamic spot pricing based on backhaul availability and lane congestion. Price differentiation rests on service reliability tiers and cold-chain certification levels. Cost compression in standard LTL segments is intensifying because express parcel networks capture mid-size freight with faster transit guarantees. E-commerce platforms exhibit lowest price sensitivity due to captive logistics integration; agricultural shippers face highest sensitivity amid seasonal volume spikes.
Supply Chain Analysis
Extended payment terms from consolidated e-commerce platforms strain working capital for mid-tier fleet operators, accelerating consolidation toward asset-heavy integrators. Vehicle manufacturing draws from Jiangsu and Shandong assembly plants, with battery cell supply anchored in Fujian and Hubei production bases. Raw material dependencies include lithium carbonate cathodes, high-strength steel chassis components, and semiconductor-based telematics modules. Single-source vulnerability concentrates in battery management system controllers from limited qualified suppliers. Distribution runs through provincial dealership networks with direct OEM relationships for large fleet accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward consolidated e-commerce platforms, with JD Logistics and Alibaba ecosystem volume commitments displacing fragmented shipper-carrier relationships across Yangtze Delta corridors.
For Market Incumbents: Harden defensive positions through backward integration into automated sortation infrastructure at county-level nodes, countering ZTO Express scale advantages. Secure multi-year FTL contracts with Jiangsu and Zhejiang manufacturing clusters featuring guaranteed volume floors and MIIT-compliant NEV transition clauses. Prioritize certification investment in SAMR cold-chain traceability standards to defend pharmaceutical distribution margins against refrigerated truck entrants. For New Entrants and Emerging Players: Build out automated consolidation hubs in underpenetrated western county nodes across Sichuan and Shaanxi, capturing e-commerce parcel aggregation demand that incumbent networks underserve. Target hydrogen fuel cell pilot zones in Foshan and Zhengzhou for heavy-duty tractor deployment on routes exceeding electric range thresholds. Pursue go-to-market partnerships with agricultural wholesale networks requiring seasonal cold-chain surge capacity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors asset-heavy integrators with captive warehouse networks over asset-light digital brokers during NEV transition capex intensity. Long-term viability through the electrification and automation window favors operators controlling terminal infrastructure and dedicated lane contracts. Acquisition target archetype: regional LTL operators with manufacturing corridor density and SAMR-compliant refrigerated fleets. The signal to watch is MIIT subsidy phase-out timelines intersecting with MEE emissions enforcement windows, which will accelerate distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| NEV Fleet Transition | MIIT Phase IV compliance and provincial subsidy tiers accelerate electric heavy-duty tractor procurement in coastal provinces. |
| Automated Sortation Deployment | County-level node penetration in western provinces captures e-commerce parcel aggregation demand from Alibaba and JD platforms. |
| Cold-Chain Infrastructure Expansion | SAMR food safety traceability enforcement drives refrigerated truck procurement across agricultural and pharmaceutical networks. |
| Hub-to-Hub Autonomous Corridor Development | Beijing-Tianjin-Hebei and Chengdu-Chongqing expressway segments offer closed-environment testing for platooning pilot programs. |
| Hydrogen Fuel Cell Integration | MEE pilot zones in Foshan and Zhengzhou subsidize fuel-cell heavy trucks for long-haul routes beyond electric range. |
Study Parameters
Cross-validation between fleet operator interviews and MIIT regulatory filings anchors the qualitative findings on NEV transition timelines and subsidy program structures. Primary discussions with logistics platform executives, OEM product planners, SAMR compliance officers, and provincial transport bureau officials combined with secondary validation through GB standards documentation, customs trade data, and SEC filings from listed express networks. Bottom-up carrier capacity modeling and top-down GDP-corridor demand estimation provide triangulation.
Calibration against historical fleet turnover patterns and e-commerce volume growth trajectories shapes the projection framework across the analysis window. Segmentation dimensions include service type, vehicle technology tier, end-use industry concentration, and regional regulatory cluster. CAGRs derive from slope-matching between observed adoption S-curves and policy-mandated transition deadlines. Key inputs include charging infrastructure deployment schedules and lithium-ion battery cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by platform-captive operators or accelerated MIIT subsidy withdrawal would shift outcomes. Macroeconomic deviation, regulatory enforcement timeline changes, or autonomous vehicle technology breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Indonesia Road Freight Transport Market
Transportation & Logistics
Thailand Road Freight Transport Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
Europe Customs Brokerage Market
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
Spain Road Freight Transport Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
United States Customs Brokerage Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
Weigh in Motion Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Latin America Customs Brokerage Market