
 Global White Glove Service in Delivery Market | 2026-2036
Global White Glove Service in Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Global White Glove Service in Delivery Market Foresight
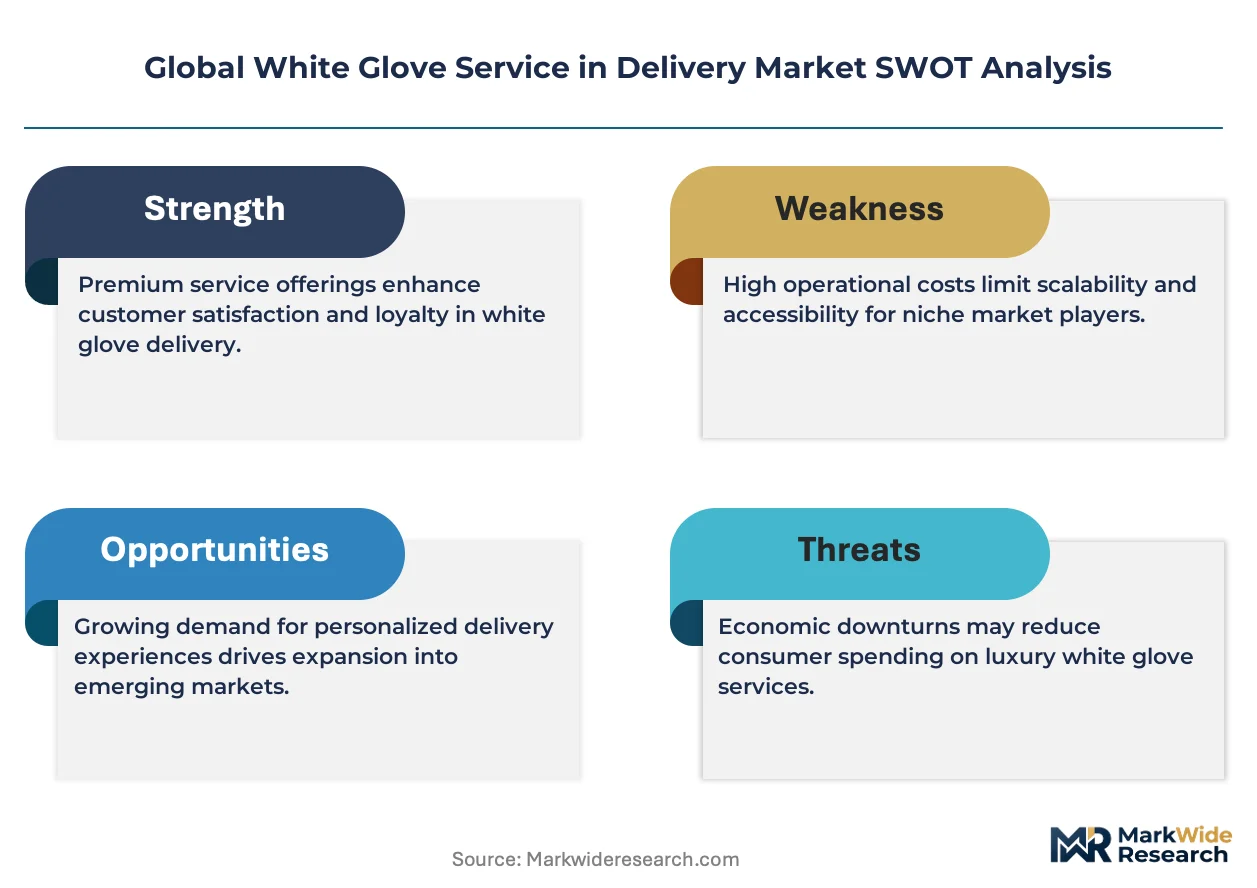
Last-mile fulfillment networks is reconfiguring around premium handling protocols as oversized and fragile shipments multiply. XPO Logistics dominates dedicated white-glove infrastructure through specialized final-mile hubs. FedEx competes via integrated tracking platforms that coordinate appointment-based delivery windows. JD.com anchors Asia-Pacific capacity with robotics-enabled sortation and in-home installation crews.
White glove service in delivery encompasses scheduled, attended final-mile handling where trained technicians execute unpacking, assembly, placement, debris removal, and functional verification against customer-specified parameters. Temperature-controlled compartments, padded lift-gate vehicles, and two-person crew minimums distinguish this tier from standard parcel distribution. Installation services and assembly services command the deepest margin pools due to skill premiums and liability coverage requirements. Electronics distributors and furniture providers represent the fastest-growing end-user cohorts as unboxing experience becomes a brand differentiator.
FAA regulations govern drone-enabled last-mile trials in the United States, while OSHA standards mandate crew lifting protocols and vehicle safety equipment. The EU Green Deal packaging rules and REACH chemical restrictions on protective foams shape material choices across European operations. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs increasingly determine network design and service tier availability.
Market Dynamics
E-commerce furniture fulfillment is forcing logistics networks to absorb specialized handling capabilities as oversized, damage-sensitive shipments outpace standard parcel infrastructure. This structural pressure is compressing delivery timelines while elevating technician skill requirements.
Growth Catalysts
- EU Green Deal packaging directives:Reusable crating mandates in Germany and France are accelerating investment in circular logistics infrastructure, creating captive demand for premium handling services.
- Robotics-enabled sortation:Automated handling systems in China are expanding throughput capacity for fragile electronics, enabling same-day white-glove fulfillment at scale.
- Furniture e-commerce penetration:Online mattress and modular sofa purchases in the United States now routinely require in-home assembly, converting standard freight into white-glove revenue pools.
Market Restraints
- Diesel fuel price volatility:Lift-gate vehicles and two-person crews consume disproportionate fuel per unit versus standard delivery, compressing margins when energy markets spike.
- Specialized technician scarcity:Certified installation crews concentrate in metropolitan Germany, leaving rural European corridors underserved and forcing premium wage arbitrage.
- REACH foam restrictions:Protective packaging material compliance costs in European operations are diverting capital from fleet expansion into chemical substitution R&D.
Strategic Opportunities
- India's BIS appliance standards:Mandatory installation verification for high-efficiency air conditioners is creating regulatory tailwinds for trained technician networks.
- Medical device home delivery:Hospital-at-home programs in Japan are converging temperature-controlled transport with patient education protocols, opening clinical white-glove segments.
- Reverse logistics integration:Consolidated pickup of packaging debris and old product removal during installation visits is unlocking ancillary revenue streams in United States urban corridors.
Industry Challenges
- OSHA lifting protocol compliance:Two-person crew minimums for items exceeding specified weight thresholds are constraining route density and inflating per-stop labor costs.
- FAA drone integration timelines:Regulatory uncertainty around autonomous last-mile trials is freezing capital allocation for aerial white-glove pilots in suburban United States markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global White Glove Service in Delivery Market |
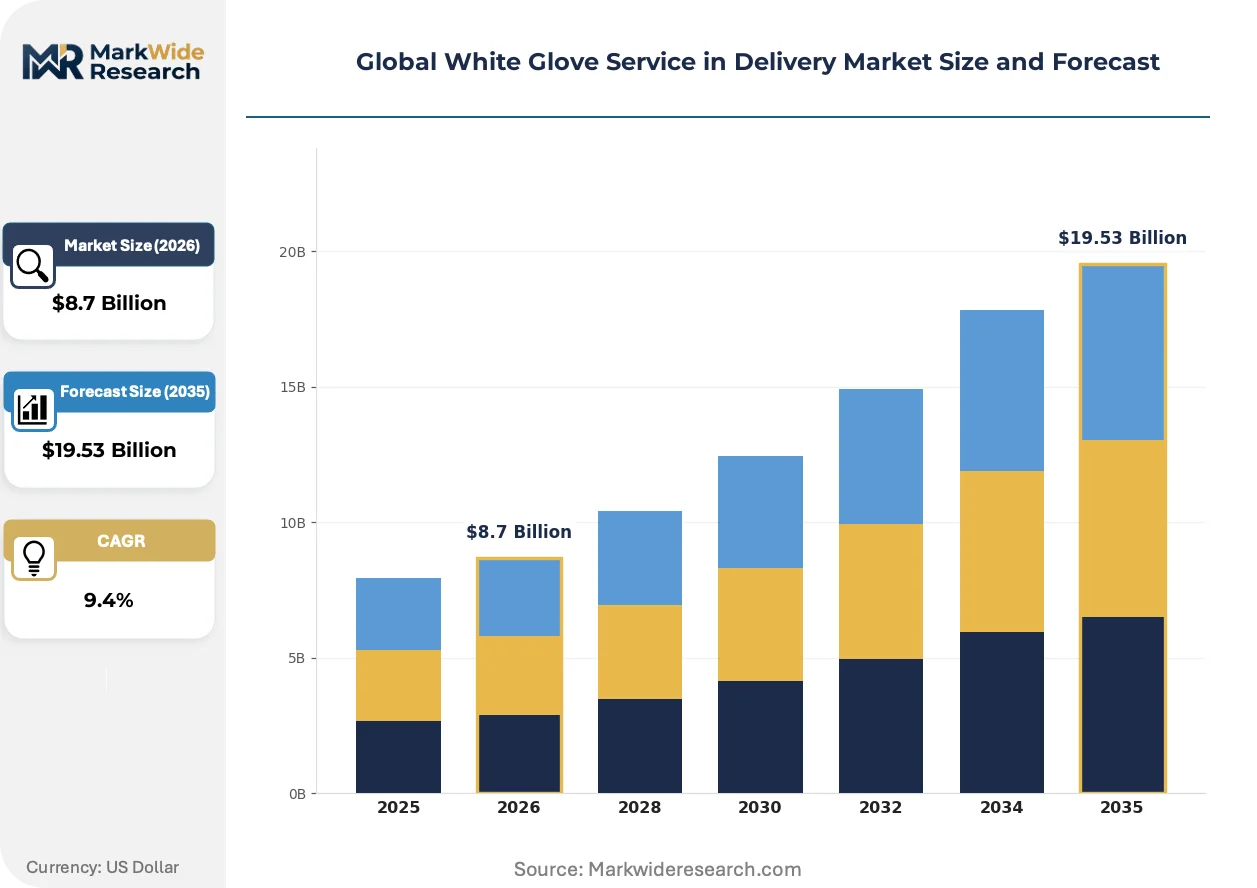
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Installation Services, Assembly Services, Packaging Management, Product Setup, Removal Services, Post-Delivery Support End User: Luxury Retailers, Electronics Distributors, Furniture Providers, Healthcare Equipment Suppliers, Art Dealers, Corporate Offices Delivery Mode: Scheduled Delivery, On-Demand Delivery, White Label Delivery, Same-Day Delivery, Next-Day Delivery, Time-Definite Delivery Customer Type: Residential Clients, Small Businesses, Large Enterprises, Government Agencies, Non-Profit Organizations, Educational Institutions |
| Companies Covered | XPO Logistics, Ryder System, SEKO Logistics, Fidelitone Last Mile, JD.com, United Parcel Service, FedEx, Wayfair, Werner Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global White Glove Service in Delivery Market Shifts & Advancements
Autonomous scheduling platforms and predictive damage detection are compressing the coordination overhead that historically constrained white-glove scalability. These tools are shifting competitive advantage from fleet size toward data-driven appointment precision.
Computer vision-based damage assessment is rendering obsolete manual pre-delivery inspection protocols that required technician presence at distribution hubs. Furniture retailers in Germany are deploying edge-mounted cameras on lift-gate vehicles to document condition at pickup, compressing liability resolution cycles from weeks to hours. This automation is enabling centralized dispatch of installation crews without warehouse staging delays.
REACH chemical restrictions on expanded polystyrene protective foams are mandating material substitutions across European white-glove operations. Molded pulp and corrugated honeycomb structures are displacing legacy cushioning in cross-border furniture shipments, requiring retraining of packing technicians and redesign of vehicle load configurations. German logistics providers are absorbing these compliance costs into premium service tiers.
Scheduled delivery windows are displacing on-demand convenience as the dominant procurement preference for high-value electronics purchases. United States consumers purchasing premium televisions and appliances now prioritize precise arrival slots over speed, accepting multi-day lead times for guaranteed technician availability. This behavioral shift is enabling density-based route optimization that improves per-stop economics for specialized carriers.
Global White Glove Service in Delivery Market Segmentation
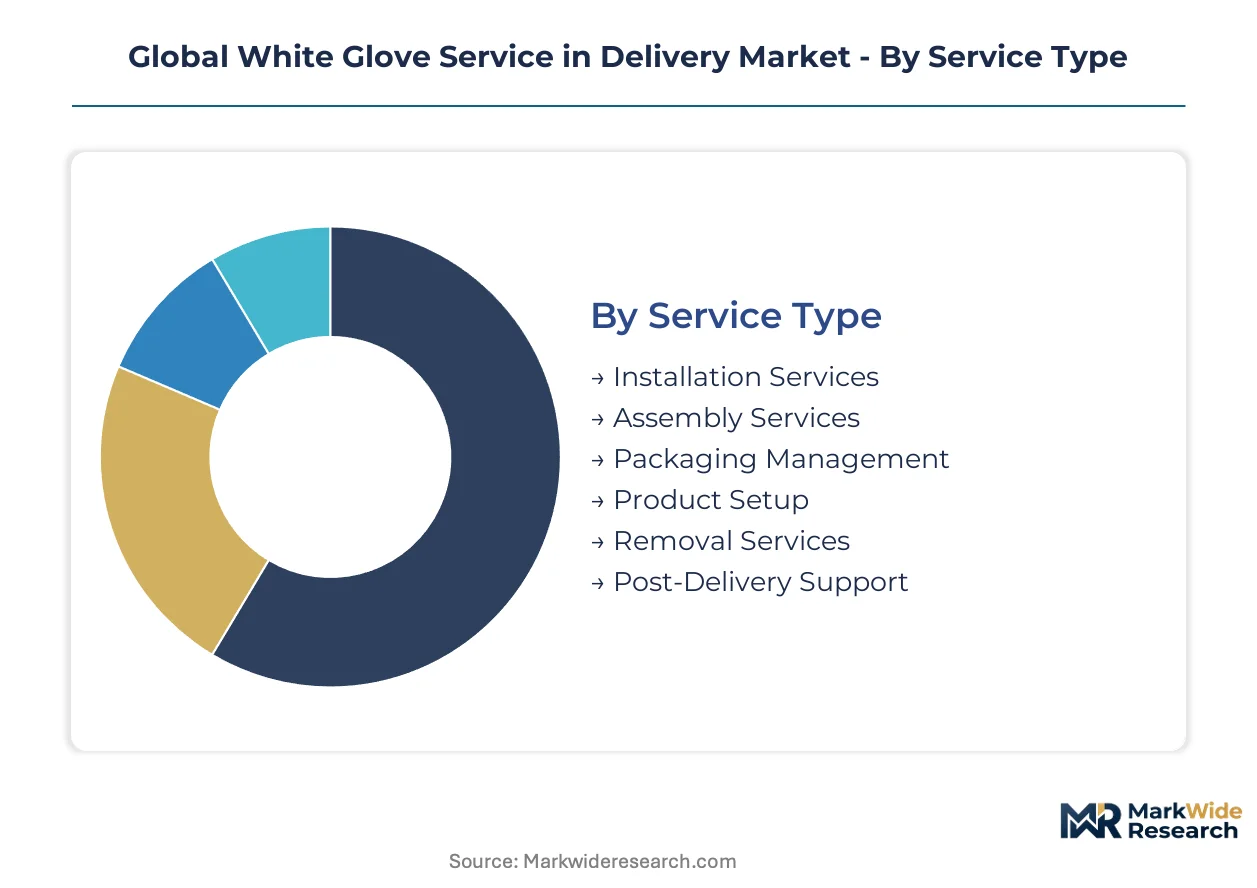
White glove delivery economics vary sharply across service tiers and customer profiles. Cycle times for installation crews differ from debris removal teams by a factor of three, reshaping how carriers allocate specialized labor pools and vehicle assets across network nodes.
Service Type:
Installation and assembly crews turn inventory fastest where furniture e-commerce penetration is deepest, while packaging management and removal services operate on longer replenishment cycles tied to circular logistics infrastructure buildout.
- Installation Services:Trained technicians execute electrical, plumbing, and mounting work inside customer premises. Demand concentrates in Germany and the United States where modular kitchen and bathroom fixture e-commerce has normalized in-home completion.
- Assembly Services:Crews construct furniture, fitness equipment, and outdoor structures without permanent fixture requirements. China's robotics-enabled sortation hubs are expanding same-day assembly capacity for electronics retailers, compressing traditional multi-day windows.
- Packaging Management:Reusable crating and protective material recovery under EU Green Deal mandates. German logistics providers absorb compliance costs into premium tiers as molded pulp displaces expanded polystyrene.
- Product Setup:Device configuration and network integration for smart home ecosystems. United States consumer electronics distributors require technician certification for Wi-Fi mesh and security system commissioning.
- Removal Services:Consolidated pickup of debris and old product during installation visits. Ancillary revenue streams are unlocking in United States urban corridors through reverse logistics integration.
- Post-Delivery Support:Warranty activation, damage claims processing, and follow-up service scheduling. Japanese medical device home delivery programs are converging patient education with this tier.
Installation Services dominates installed base. Assembly Services is where expansion concentrates.
End User:
Margin pools stratify sharply between luxury retail's white-glove baseline expectations and healthcare equipment's regulatory-driven compliance premiums.
- Electronics Distributors:Unboxing experience has become a brand differentiator for premium televisions and appliances. United States consumers now prioritize precise arrival slots over speed, enabling density-based route optimization.
- Furniture Providers:Online mattress and modular sofa purchases routinely require in-home assembly, converting standard freight into white-glove revenue pools. German retailers deploy edge-mounted cameras on lift-gate vehicles to document condition at pickup.
- Luxury Retailers:High-value apparel, jewelry, and timepiece delivery with biometric verification protocols. Metropolitan concentration supports dedicated fleet economics.
- Healthcare Equipment Suppliers:Hospital-at-home programs in Japan are converging temperature-controlled transport with patient education protocols, opening clinical white-glove segments.
- Art Dealers:Climate-controlled transport with condition documentation and insurance-aligned handling protocols. Specialized scarcity limits carrier participation.
- Corporate Offices:Scheduled workstation deployment and IT infrastructure installation. Volume concentration supports enterprise contract structures.
Furniture Providers anchor current revenue. Electronics Distributors are climbing the fastest as unboxing experience becomes decisive in purchase decisions.
Delivery Mode:
Network design diverges between appointment-based density optimization and on-demand labor arbitrage models.
- Scheduled Delivery:Precision arrival slots with guaranteed technician availability. FedEx coordinates these windows through integrated tracking platforms that compress coordination overhead.
- Same-Day Delivery:Robotics-enabled sortation in China is expanding throughput capacity for fragile electronics, enabling white-glove fulfillment at speed previously reserved for standard parcel.
- On-Demand Delivery:Immediate response protocols for urgent replacement and repair scenarios. Premium pricing reflects crew dispatch inefficiency.
- White Label Delivery:Third-party execution under retailer brand identity. XPO Logistics operates dedicated final-mile hubs supporting this model for furniture marketplaces.
- Next-Day Delivery:Balanced speed-certainty positioning for mid-market consumer electronics. Route density improves with accepted lead time extension.
- Time-Definite Delivery:Guaranteed arrival within specified hour windows for commercial contracts. Penalty structures enforce operational discipline.
Scheduled Delivery commands the deepest margin pools. Same-Day Delivery is gaining share fastest as automation reduces the cost premium against standard service tiers.
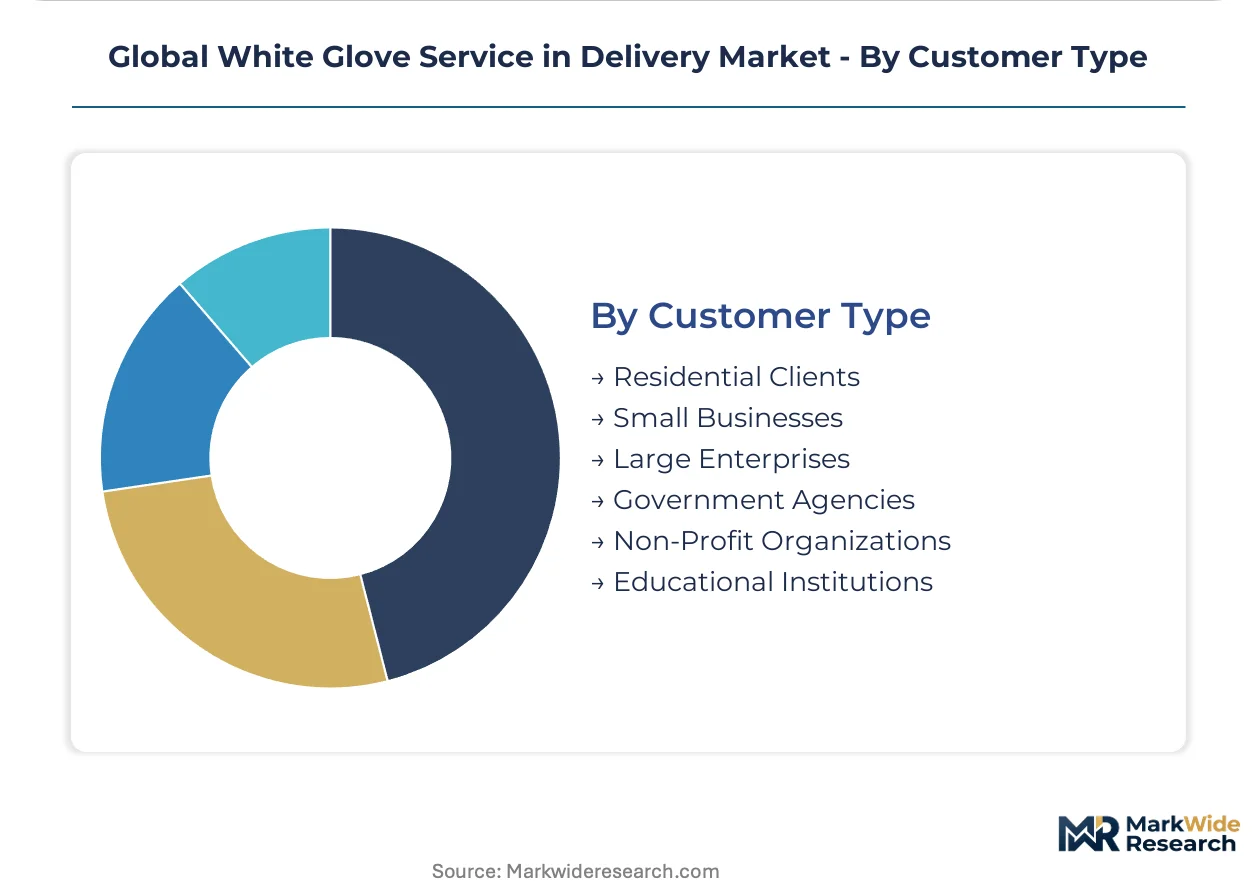
Customer Type:
Procurement authority and volume concentration determine whether white-glove services are bundled into product pricing or itemized as separate line items.
- Residential Clients:Individual consumers purchasing high-value goods through e-commerce channels. India's BIS appliance standards are creating regulatory tailwinds for trained technician networks in this segment.
- Large Enterprises:Volume contracts with standardized service level agreements and centralized billing. Corporate office relocations and technology refreshes drive recurring demand.
- Small Businesses:Limited procurement sophistication favors bundled delivery-installation pricing. Fragmented demand complicates route density.
- Government Agencies:Formal tender processes with certified vendor requirements and audit trails. Procurement cycles extend service engagement timelines.
- Educational Institutions:Seasonal concentration around academic calendar with dormitory and laboratory equipment deployment. Summer installation windows strain crew availability.
- Non-Profit Organizations:Grant-funded equipment donations with donor-mandated delivery documentation. Compliance overhead elevates per-stop costs.
Residential Clients represent the broadest addressable base. Large Enterprises are where pricing power concentrates through multi-year contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex anchors trans-Pacific white-glove capacity, channeling furniture and electronics into dedicated final-mile networks. Germany's Rhine-Alpine freight corridor feeds automated sortation hubs serving Central European e-commerce corridors.
United States
Online mattress and modular sofa purchases now routinely require in-home assembly, converting standard freight into white-glove revenue pools. FAA regulations govern drone-enabled last-mile trials, freezing capital allocation for aerial pilots in suburban markets. Furniture retailers in Los Angeles deploy edge-mounted cameras on lift-gate vehicles to document condition at pickup.
Germany
Modular kitchen and bathroom fixture e-commerce has normalized in-home completion, concentrating demand in metropolitan corridors. EU Green Deal packaging rules and REACH chemical restrictions on protective foams mandate material substitutions across operations. Logistics providers in the Rhine-Ruhr region absorb compliance costs into premium service tiers.
China
Robotics-enabled sortation hubs are expanding same-day assembly capacity for electronics retailers, compressing traditional multi-day windows. MIIT standards govern smart home device commissioning protocols. JD.com anchors Asia-Pacific capacity with robotics-enabled sortation in the Yangtze River Delta.
Japan
Hospital-at-home programs are converging temperature-controlled transport with patient education protocols, opening clinical white-glove segments. METI guidelines shape medical device home delivery certification requirements. Tokyo-Osaka corridor operators specialize in warranty activation and follow-up service scheduling.
India
BIS appliance standards mandate installation verification for high-efficiency air conditioners, creating regulatory tailwinds for trained technician networks. CDSCO oversight extends to home medical equipment delivery protocols. Mumbai and Delhi-NCR clusters absorb specialized crew training costs into premium pricing.
Global White Glove Service in Delivery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base concentrates around three distinct tiers: dedicated final-mile carriers with captive hub infrastructure, integrated parcel networks with appointment-scheduling overlays, and retailer-captive logistics operations. Strategic archetypes include automation-heavy sortation platforms, white-label execution specialists, and clinical-grade temperature-control operators. Competitive moves center on reverse logistics integration and circular packaging infrastructure buildout.
Among North American platform operators, XPO Logistics and FedEx occupy distinct positioning vectors. XPO exemplifies the dedicated final-mile hub archetype through specialized infrastructure supporting furniture marketplace fulfillment. FedEx represents integrated tracking platform coordination of appointment-based delivery windows. JD.com anchors Asia-Pacific automation scale with robotics-enabled sortation and in-home installation crew deployment.
| Leading Market Players |
|---|
| XPO Logistics |
| Ryder System |
| SEKO Logistics |
| Fidelitone Last Mile |
| JD.com |
| United Parcel Service |
| FedEx |
| Wayfair |
| Werner Enterprises |
| Others |
Supply & Pricing Matrix
Undercapacity in rural European corridors is forcing metropolitan wage arbitrage that elevates per-stop labor costs and compresses route density economics. This utilization squeeze simultaneously pressures pricing postures in underserved regions while incentivizing fleet consolidation around automated sortation hubs.
Pricing Analysis
Volume-discount tiering structures separate white-label execution from direct premium service contracts. Pricing stratifies across installation-heavy, assembly-only, and debris-removal tiers based on technician certification level and liability coverage depth. Cost compression in standard assembly tiers is intensifying because robotics-enabled sortation reduces skill premiums. Residential clients exhibit highest price sensitivity, while healthcare equipment suppliers accept premium positioning for regulatory compliance.
Supply Chain Analysis
Contract-manufacturing concentration rests with specialized final-mile carriers operating captive hub infrastructure in the United States, Germany, and China. Vehicle chassis and temperature-control units draw from automotive and refrigeration component networks. Single-source vulnerability concentrates in certified technician training pipelines. Distribution runs through dedicated final-mile hubs rather than parcel sortation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
White glove delivery functions as a service-attach opportunity where installation and assembly revenue layers expand faster than underlying freight movement. Post-delivery support and warranty activation are climbing fastest as smart home device penetration deepens technician dependency.
For Market Incumbents: Harden route density through reverse logistics integration that consolidates debris pickup with installation visits. Fortify technician certification pipelines against specialized crew scarcity in rural European corridors. Vertical integration into reusable crating infrastructure under EU Green Deal mandates captures circular logistics premiums.
For New Entrants and Emerging Players: Establish a beachhead in India's BIS-mandated appliance installation verification segment where regulatory tailwinds outpace incumbent coverage. Target hospital-at-home medical device delivery in Japan as clinical white-glove protocols converge with patient education requirements. Lead with temperature-controlled transport certification to differentiate from standard freight competitors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform integrators with automated scheduling and predictive damage detection capabilities. Five-to-ten year viability favors carriers with robotics-enabled sortation scale and circular packaging infrastructure. Monitor FAA drone integration rulings as an inflection signal for aerial white-glove pilot capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotics-Enabled Sortation Deployment | JD.com's Yangtze River Delta hubs compress same-day assembly windows for electronics retailers. |
| Reverse Logistics Integration | Consolidated debris and old-product pickup unlocks ancillary revenue in United States urban corridors. |
| Circular Packaging Infrastructure | EU Green Deal reusable crating mandates in Germany accelerate captive demand for premium handling tiers. |
| Clinical White-Glove Certification | Japan's hospital-at-home programs converge temperature control with patient education protocols. |
| Autonomous Scheduling Platform | FedEx coordinates precision arrival slots through integrated tracking that compresses coordination overhead. |
Research Methodology
Initial hypotheses were tested against primary input from final-mile operations directors, installation crew supervisors, furniture e-commerce procurement leads, and healthcare logistics coordinators and refined through secondary validation. Customs data on lift-gate vehicle imports, OSHA incident filings, EU packaging directive compliance disclosures, and carrier fleet expansion announcements anchored supply-side modeling. Bottom-up technician wage and route density estimates triangulated against top-down e-commerce furniture penetration forecasts.
Demand-supply-balance framing shaped the analytical framework across the analysis window. Segmentation dimensions modeled include service type tier, end-user vertical, delivery mode architecture, and customer procurement authority. CAGRs derived from technician capacity expansion curves and e-commerce fulfillment volume elasticities. Forecast inputs incorporated REACH chemical substitution timelines and FAA drone integration pathway probabilities.
Sensitivities concentrate around diesel fuel volatility, specialized crew wage inflation, and regulatory divergence between jurisdictions. Forecasts reflect assumptions on e-commerce penetration saturation and automation cost reduction curves. Quarterly review of fleet utilization rates and technician certification pipeline throughput is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Ship Management Software Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Middle East Car Rental Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
Canada White Glove Delivery Service Market
Transportation Services
India Car Rental Market
Transportation Services
Vietnam Car Rental Market
Transportation Services
Full-Service Carrier Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
Taxi and Ride-Hailing Services Market
Transportation Services
Compact Road Sweepers Market
Transportation Services
Poland Car Rental Market
Transportation Services
MUV Rental Market
Transportation Services
Car Rental Market
Transportation Services
Russia Car Rental Market
Transportation Services
India Taxi Market