
 Australia Road Freight Transport Market | 2026-2036
Australia Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Road Freight Transport Market Outlook
Multi-sourced fleet procurement among bulk commodity exporters is broadening contract structures beyond traditional single-carrier arrangements. Toll Group leverages its intermodal terminal network to sustain long-haul density across the eastern seaboard. Linfox anchors cold-chain and retail distribution through controlled warehouse-to-supermarket routing. K&S Group dominates mining logistics in Western Australia's Pilbara region with specialized heavy-haul equipment.
Australia road freight transport encompasses the movement of goods via registered motor vehicles over public road infrastructure, with heavy trucks governed by mass limits up to 68.5 tonnes under Higher Mass Limit permits and subject to fatigue-management protocols through accredited operator schemes. Full truckload services command the largest revenue pool due to mining and agricultural bulk movements, while express delivery segments capture premium margins from e-commerce time-definite requirements. Less than truckload networks face structural pressure from terminal cost inflation, though dedicated transport contracts with manufacturing clients provide stable yield floors.
The National Heavy Vehicle Regulator enforces chain-of-responsibility laws that extend liability to consignees and loaders, reshaping risk allocation across the sector. Australia's Design and Distribution Obligations under Treasury regulations, alongside state-based environmental standards for vehicle emissions, are tightening fleet specification requirements. Stakeholders must monitor how biometric fatigue-monitoring mandates and alternative-fuel infrastructure investments will reshape capital deployment decisions across operator portfolios.
Market Dynamics
The Heavy Vehicle National Law is compressing fleet renewal timelines as operators absorb biometric fatigue-monitoring mandates and chain-of-responsibility liability expansion across Western Australia's mining corridors and Queensland's resource belts.
Growth Catalysts
- Higher Mass Limit permits:The National Heavy Vehicle Regulator's 68.5-tonne allowance for approved routes is pulling investment into specialized heavy-haul equipment for Pilbara iron ore movements.
- E-commerce time-definite requirements:Express delivery segments are capturing premium yield from supermarket chains and pharmaceutical distributors demanding controlled-temperature, next-day road freight across the Melbourne-Sydney-Brisbane triangle.
- Mining sector procurement:Bulk commodity exporters are broadening contract structures beyond single-carrier arrangements, creating dedicated fleet opportunities for operators with specialized equipment pools.
Market Restraints
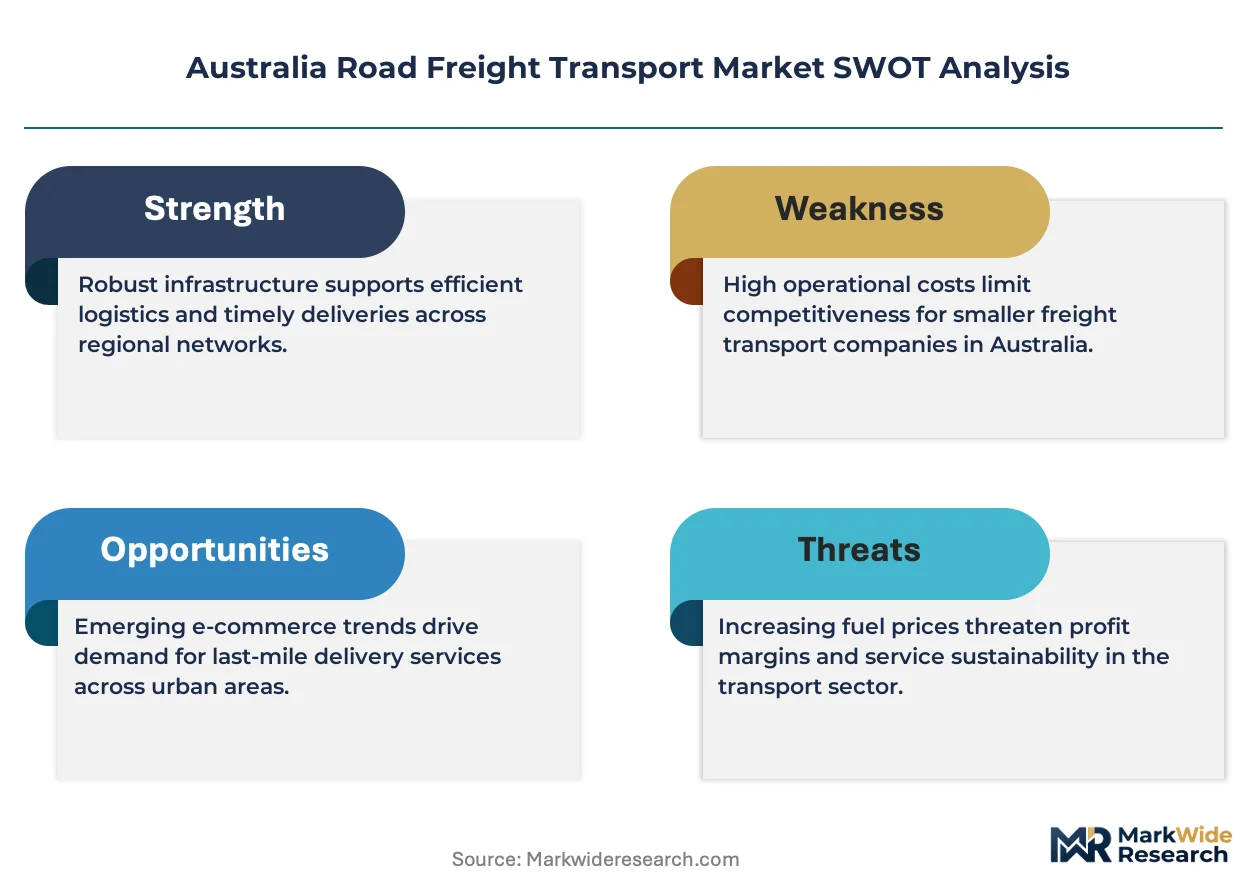
- Diesel price volatility:Fuel represents 35-40% of operating costs for long-haul operators, with limited hedging instruments available to mid-tier fleet owners.
- Terminal cost inflation:Less-than-truckload networks face structural pressure from rising real estate and labor costs at consolidation facilities in Sydney and Melbourne.
- Alternative-fuel infrastructure gaps:Hydrogen and battery-electric refueling networks remain concentrated on coastal corridors, leaving interstate routes underserved.
Strategic Opportunities
- Western Australia's Pilbara region:Mining logistics contracts for specialized heavy-haul equipment are consolidating around operators with captive maintenance facilities and driver accommodation infrastructure.
- Cold-chain warehouse-to-supermarket routing:Controlled-temperature distribution from regional processing centers to retail networks is creating yield premiums for operators with integrated warehousing assets.
- Queensland's resource corridors:Coal and LNG export expansion is generating dedicated fleet demand for overweight permit movements between Bowen Basin mines and Gladstone port facilities.
Industry Challenges
- Biometric fatigue-monitoring integration:Fleet operators must retrofit cab-mounted cameras and telematics systems to comply with Heavy Vehicle National Law amendments, compressing capital deployment timelines.
- Heavy-vehicle mechanic shortages:Specialized technicians for automated transmissions and emission-control systems are concentrated in Perth and Brisbane, constraining maintenance capacity in remote mining regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Road Freight Transport Market |
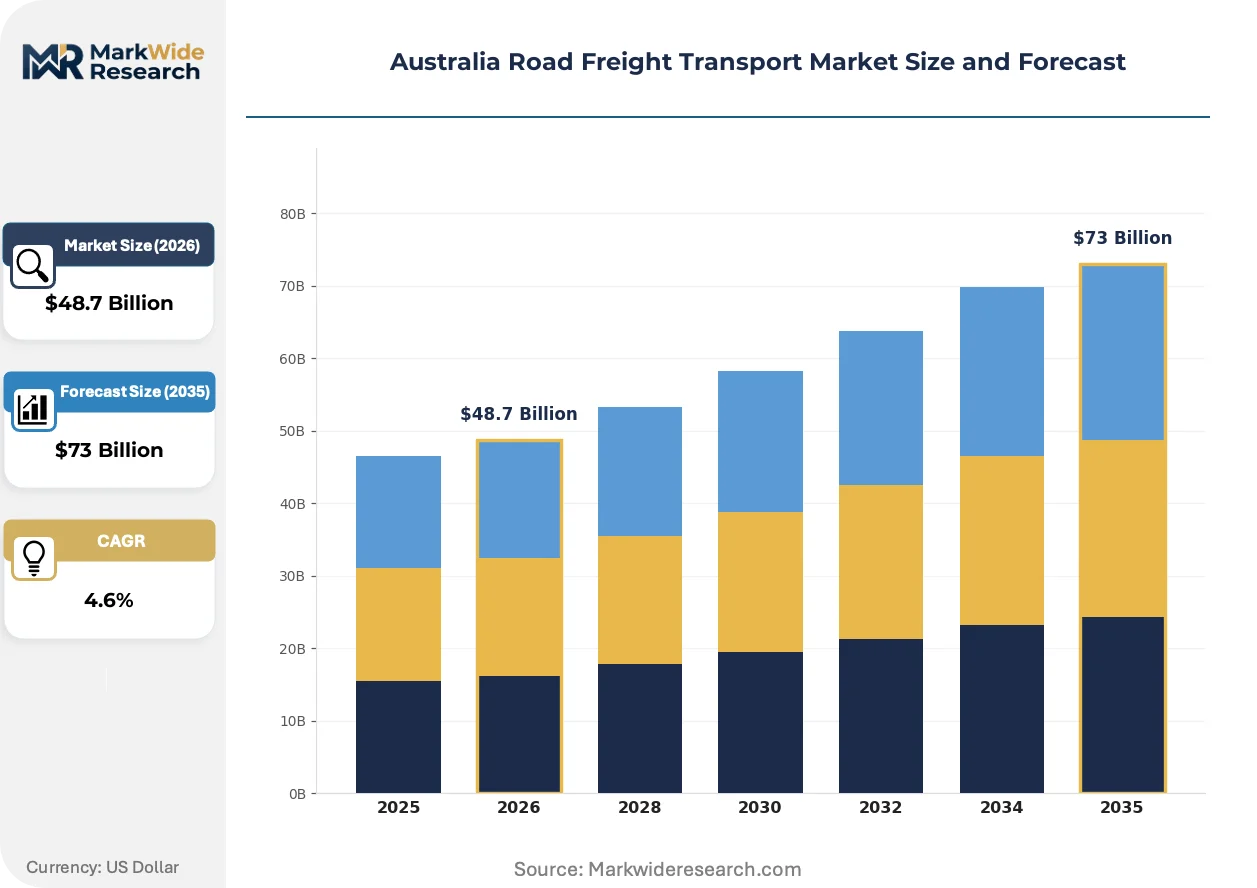
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Heavy Trucks, Light Trucks, Vans, Trailers Service Type: Full Truckload, Less than Truckload, Express Delivery, Dedicated Transport End User: Retail, Manufacturing, Construction, E-commerce Delivery Model: Door-to-Door, Terminal-to-Terminal, Curbside Delivery, Distribution Center |
| Companies Covered | K&S Group, Maersk, Linfox, Crawfords Freightlines, Couriers & Freight, Toll Group, LINX Cargo Care Group, McColl's Transport, Team Global Express, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Road Freight Transport Market Strategic Shifts
Telematics and alternative-powertrain technologies are redistributing competitive advantage toward operators with capital depth for fleet modernization and data infrastructure.
Platooning and cooperative adaptive cruise control systems are decentralizing dispatch authority from centralized fleet managers to in-cab automation. Mining haulage contractors in Western Australia are piloting these technologies on private road segments. The shift is compressing driver headcount requirements while raising minimum fleet scale thresholds for viable deployment.
Australia's Design and Distribution Obligations under Treasury regulations are tightening vehicle specification requirements for emission compliance. Fleet procurement departments must now document fuel-efficiency projections across asset lifecycles. Heavy-haul operators serving Queensland's resource corridors are responding with compressed replacement cycles for older powertrains.
Consignees are consolidating carrier panels around operators with integrated warehouse assets and real-time visibility platforms. Manufacturing clients in Victoria's industrial west are displacing pure-transport contracts with bundled logistics agreements. This concentration is most visible in food processing and pharmaceutical verticals where temperature integrity and traceability requirements dominate supplier selection.
Australia Road Freight Transport Market Segmentation
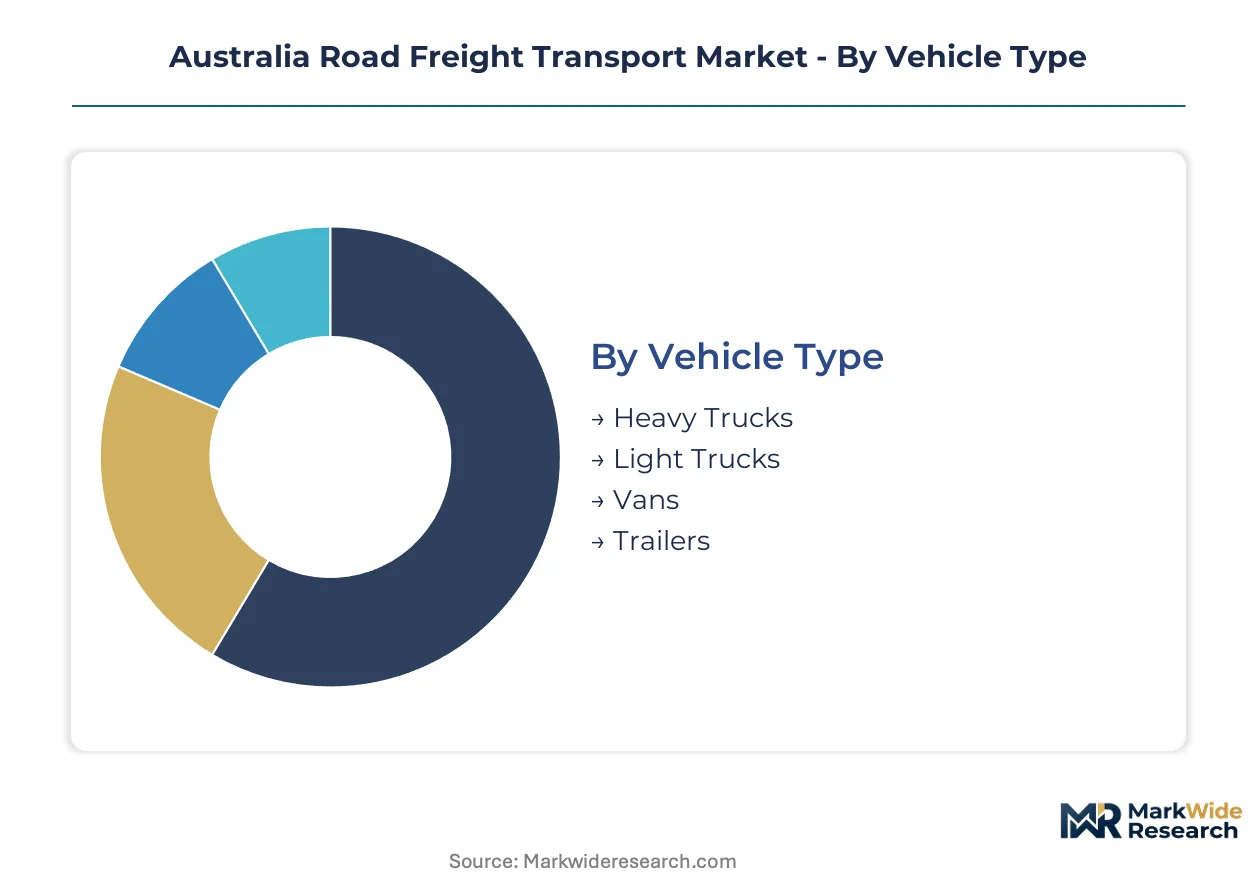
Segmentation in Australian road freight reveals how procurement patterns diverge across equipment scale, service architecture, and customer operational requirements. Mining bulk movements, retail replenishment cycles, and e-commerce velocity demands each command distinct fleet configurations and contract structures. Understanding these divides clarifies where capital deployment and compliance investments concentrate.
Vehicle Type:
Equipment selection hinges on payload economics against route access permissions and driver licensing thresholds.
- Heavy Trucks:Prime movers and rigid configurations rated above 4.5 tonnes gross vehicle mass dominate Pilbara iron ore haulage and Queensland coal corridor movements. The National Heavy Vehicle Regulator's 68.5-tonne Higher Mass Limit permits pull investment toward specialized B-double and road train equipment for approved heavy-haul routes.
- Light Trucks:Two-axle configurations between 3.5 and 4.5 tonnes GVM handle last-mile urban distribution and metropolitan parcel networks. E-commerce fulfillment centers in Sydney's west and Melbourne's northern suburbs are compressing turnaround times for these assets through automated loading systems.
- Vans:Commercial vehicles under 3.5 tonnes GVM serve pharmaceutical distributors and high-value electronics couriers requiring unbroken chain-of-custody documentation. Temperature-controlled van fleets are expanding for clinical trial specimen transport between Melbourne biomedical precincts and regional collection points.
- Trailers:Skeletal, flat-top, and refrigerated semi-trailers extend fleet flexibility without additional power unit investment. Trailer pooling arrangements are proliferating among mid-tier operators seeking to match variable demand across agricultural harvest windows without captive asset ownership.
Heavy Trucks lead on scale; Light Trucks lead on momentum.
Service Type:
Contract structures align with shipment predictability, cargo value density, and customer inventory carrying cost tolerance.
- Full Truckload:Dedicated vehicle allocation for single consignor movements captures mining sector procurement and agricultural bulk exports. Western Australia's grain handlers and Queensland's cattle exporters are extending contract durations to secure equipment availability through seasonal peaks.
- Less than Truckload:Consolidated cargo from multiple shippers through hub-and-spoke terminal networks serves manufacturing parts suppliers and small wholesale distributors. Rising real estate costs at Sydney and Melbourne consolidation facilities are compressing margins for pure LTL operators without integrated warehousing assets.
- Express Delivery:Time-definite service with guaranteed transit windows commands premium pricing from supermarket chains and pharmaceutical distributors. Next-day road freight across the Melbourne-Sydney-Brisbane triangle is displacing air freight for non-perishable high-value goods.
- Dedicated Transport:Captive fleet provision under multi-year agreements provides manufacturing clients with guaranteed capacity and branded vehicle livery. Victorian food processors are bundling dedicated transport with warehouse management services to secure temperature integrity through controlled routing.
Full Truckload dominates revenue concentration; Express Delivery shows the steepest expansion trajectory.
End User:
Vertical demand patterns shape equipment specification, scheduling intensity, and regulatory compliance exposure.
- Retail:Supermarket chains and department store networks demand synchronized replenishment with warehouse-to-store routing precision. Controlled-temperature distribution from regional processing centers is creating yield premiums for operators with integrated cold-chain assets.
- Manufacturing:Just-in-time parts supply and finished goods distribution require scheduled lane density and electronic proof-of-delivery integration. Automotive component suppliers in Adelaide's northern industrial zone are displacing pure-transport contracts with bundled logistics agreements.
- Construction:Project-based movements of bulk materials, prefabricated modules, and heavy equipment demand permit-managed overweight configurations. Infrastructure stimulus in Southeast Queensland is generating dedicated fleet demand for crane-liftable container movements.
- E-commerce:Parcel networks with next-day or same-day delivery promises are compressing sortation timelines and expanding van fleet deployment. Pharmaceutical e-commerce platforms are driving controlled-temperature last-mile requirements beyond traditional courier capabilities.
Retail anchors volume throughput; E-commerce is gaining share fastest.
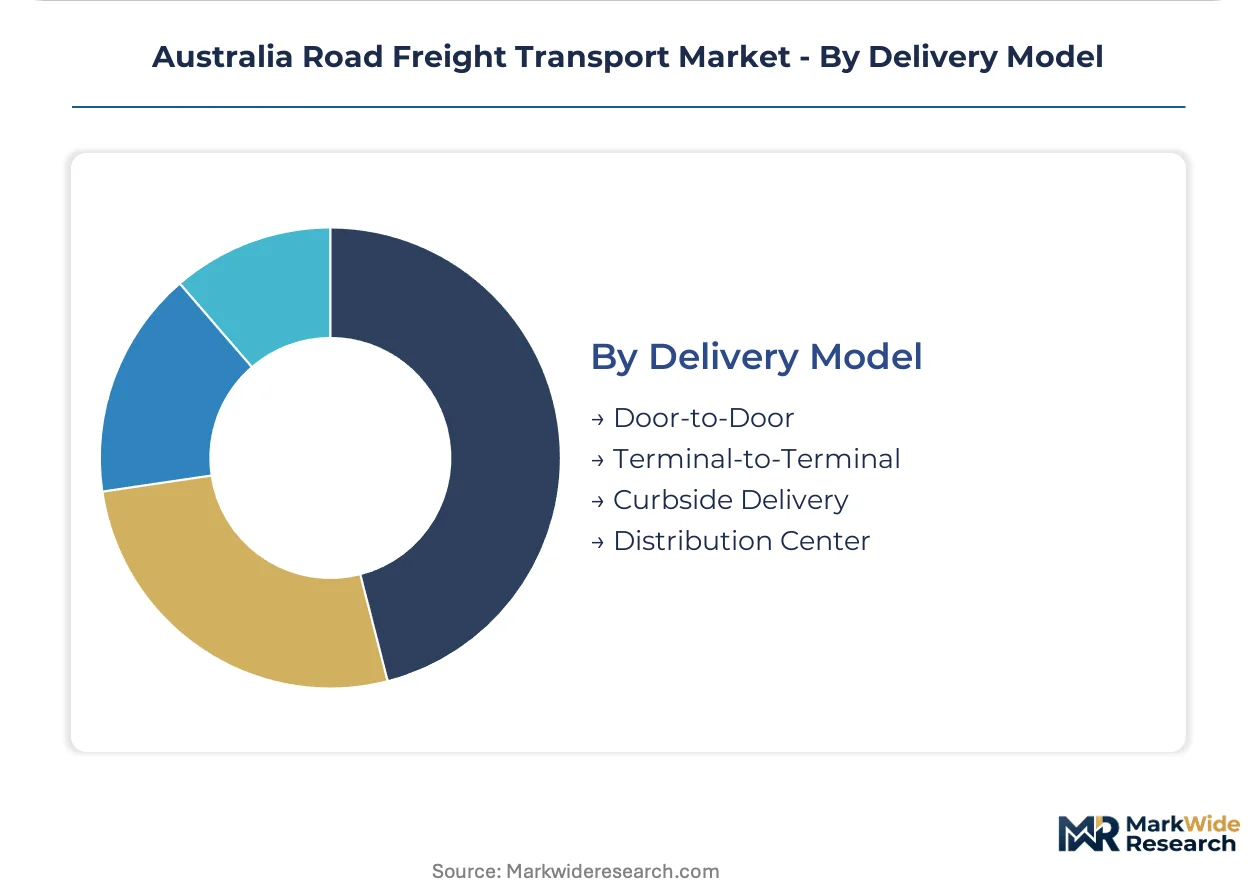
Delivery Model:
Final-mile configuration determines labor intensity, customer interface requirements, and real estate positioning.
- Door-to-Door:Direct consignee delivery without intermediary handling serves high-value electronics, clinical specimens, and premium furniture. White-glove service requirements are expanding crew size and delivery window negotiation for metropolitan residential addresses.
- Terminal-to-Terminal:Shipper and consignee each manage first and last mile, with operator handling line-haul consolidation. This model persists in agricultural bulk where farm gate loading and port receival are customer-managed.
- Curbside Delivery:Kerbside drop without unpacking or installation labor reduces dwell time for parcel couriers and building materials suppliers. Construction site deliveries in Perth's suburban expansion corridors are standardizing on this model to minimize driver exposure to site safety protocols.
- Distribution Center:Delivery to customer-controlled facilities with cross-dock or storage integration supports retail replenishment and manufacturing supply chains. Melbourne's west and Sydney's southwest are concentrating DC development, reshaping line-haul lane economics toward these gravity centers.
Distribution Center dominates commercial contract value; Door-to-Door commands the highest yield per shipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Melbourne-Sydney-Brisbane triangle concentrates Australia's highest freight density, with mining corridors in Queensland and Western Australia pulling specialized heavy-haul investment toward resource export infrastructure.
New South Wales
Sydney's southwestern distribution center cluster anchors retail replenishment networks serving supermarket chains and e-commerce fulfillment platforms. The National Heavy Vehicle Regulator enforces Higher Mass Limit permit compliance across the Hume Highway corridor, compressing fleet specification timelines for interstate operators. Port Botany's container throughput is generating dedicated transport contracts for road-rail intermodal connectors.
Victoria
Manufacturing supply chains in Melbourne's western industrial zone demand just-in-time parts distribution with electronic proof-of-delivery integration. Victoria's state-based environmental standards for vehicle emissions are tightening diesel powertrain replacement cycles among captive fleet operators. The Laverton-Derrimut logistics precinct is concentrating cold-chain warehouse assets for pharmaceutical and food processing clients.
Queensland
Bowen Basin coal exports and Gladstone LNG expansion are generating overweight permit movements requiring specialized B-double configurations. Biometric fatigue-monitoring mandates under Heavy Vehicle National Law amendments are raising compliance costs for Pilbara-serving contractors with Queensland staging facilities. The Brisbane-Gladstone transport corridor is consolidating around operators with captive maintenance infrastructure.
Western Australia
Pilbara iron ore haulage dominates heavy-haul procurement, with mining logistics contracts consolidating around operators with driver accommodation and remote maintenance capabilities. Chain-of-responsibility liability expansion is reshaping risk allocation between consignees and transport providers across the Port Hedland-Newman route. Perth's concentration of heavy-vehicle mechanics is constraining maintenance capacity in remote mining regions.
South Australia
Adelaide's northern industrial zone anchors automotive component distribution with bundled logistics agreements displacing pure-transport contracts. The state's integration into Melbourne-Sydney-Brisbane triangle networks is raising terminal cost pressures for less-than-truckload operators without integrated warehousing assets. The Port Adelaide logistics precinct is developing cold-chain capacity for wine and agricultural export consolidation.
Australia Road Freight Transport Market Competitive Environment
Established operators occupy the standard tier; emerging entrants pursue specialized heavy-haul and cold-chain niches. The market structures around three tiers: national integrated logistics providers with intermodal assets, regional mining specialists with captive equipment pools, and e-commerce-focused parcel networks with last-mile density. Consolidation is accelerating through dedicated fleet contract awards in Queensland's resource corridors and Western Australia's Pilbara region.
Among diversified national operators, Toll Group and Linfox exemplify the integrated logistics archetype with controlled warehouse-to-supermarket routing capabilities. K&S Group occupies a position within the mining-specialist tier, anchoring heavy-haul service provision in Western Australia's resource corridors. These three entities represent distinct competitive positioning vectors: intermodal network density, cold-chain integration, and remote-region heavy-haul specialization.
| Leading Market Players |
|---|
| K&S Group |
| Maersk |
| Linfox |
| Crawfords Freightlines |
| Couriers & Freight |
| Toll Group |
| LINX Cargo Care Group |
| McColl's Transport |
| Team Global Express |
| Others |
Value Chain & Pricing Dynamics
Mining sector procurement consolidation among Pilbara iron ore exporters and Queensland coal producers anchors contract-based long-term offtake as the dominant pricing model across Australia's heavy-haul corridors. These bulk commodity buyers leverage dedicated fleet agreements to lock capacity through seasonal peaks, compressing spot market liquidity and amplifying price premiums for operators with Higher Mass Limit permit compliance.
Pricing Analysis
Diesel cost pass-through clauses dominate contract structures, with fuel representing the largest variable cost component for interstate operators. Pricing stratifies across premium, standard, and economy tiers based on equipment specification grade and real-time visibility integration. Cost compression in the less-than-truckload segment is intensifying because terminal real estate inflation in Sydney and Melbourne outpaces yield recovery. Small wholesale distributors show highest price sensitivity, while pharmaceutical and supermarket chains prioritize temperature integrity over rate negotiation.
Supply Chain Analysis
Higher Mass Limit permit accreditation and chain-of-responsibility certification under the National Heavy Vehicle Regulator gate operator participation in heavy-haul mining contracts. Equipment manufacturing draws from Germany, Japan, and the United States for prime mover powertrains and automated transmission systems. Single-source vulnerability concentrates in Perth's heavy-vehicle mechanic pool, constraining maintenance capacity across remote Western Australian mining regions. Distribution runs through captive fleet arrangements with integrated warehousing assets rather than open brokerage networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's road freight market represents a late-cycle quality story as mining logistics contracts shift toward biometric fatigue-monitoring compliance and alternative-fuel fleet specifications. E-commerce cold-chain demands and pharmaceutical time-definite requirements are pulling premium yield toward operators with integrated warehouse-to-supermarket routing capabilities.
For Market Incumbents: Extend captive maintenance infrastructure into Queensland's Bowen Basin and Western Australia's Pilbara region to defend contract renewal rates against emerging heavy-haul specialists. Biometric fatigue-monitoring retrofit mandates under Heavy Vehicle National Law amendments compress capital deployment timelines, favoring operators with existing telematics platforms. Vertical integration into driver accommodation assets secures labor availability in remote corridors where housing scarcity constrains fleet expansion. For New Entrants and Emerging Players: Capture cold-chain warehouse-to-supermarket routing contracts in Victoria's Laverton-Derrimut precinct and Sydney's southwestern distribution cluster, where supermarket chains are displacing pure-transport agreements with bundled logistics partnerships. Pharmaceutical e-commerce platforms present the most penetrable segment, requiring temperature-controlled van fleets and unbroken chain-of-custody documentation that incumbent parcel networks lack. A go-to-market angle anchored in clinical trial specimen transport between Melbourne biomedical precincts and regional collection points bypasses direct competition with established retail distributors. For Investors and Strategic Acquirers: Mining logistics contractors with Pilbara heavy-haul specialization are the most active acquirer in this space, consolidating around operators with Higher Mass Limit permit portfolios and remote maintenance capabilities. The long-term viability window favors vertically integrated mid-tier fleets with captive warehousing assets over pure-transport operators exposed to terminal cost inflation. Watch biometric fatigue-monitoring mandate enforcement timelines as the inflection indicator for accelerated fleet modernization capital requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Higher Mass Limit Permit Portfolio Expansion | Unlocks 68.5-tonne movements on approved Pilbara and Queensland coal corridor routes. |
| Biometric Fatigue-Monitoring Platform Deployment | Secures Heavy Vehicle National Law compliance ahead of NHVR enforcement phase-in. |
| Cold-Chain Warehouse Integration | Captures pharmaceutical and supermarket yield premiums through controlled-temperature routing. |
| Driver Accommodation Infrastructure Buildout | Resolves labor scarcity constraints in remote Western Australian mining regions. |
| Alternative-Fuel Pilot Fleet Investment | Positions operators for Queensland and New South Wales emission standard tightening. |
Study Parameters
Coverage spans New South Wales, Victoria, Queensland, Western Australia, and South Australia, with primary inputs from each jurisdiction's freight corridor operators. Fleet managers, mining logistics procurement officers, supermarket chain distribution directors, and National Heavy Vehicle Regulator compliance leads contributed interview data. Secondary validation drew from NHVR permit issuance databases, state environmental standard filings, ABS freight movement statistics, and operator fleet registration records. Bottom-up equipment deployment estimates and top-down commodity export volume projections were triangulated against contract award announcements.
Rate-of-change decomposition across the analysis window separated volume growth from yield compression effects in each segment. Vehicle type, service architecture, end-use vertical, and delivery model dimensions structured the segmentation framework. CAGRs were derived from equipment procurement pipeline analysis and commodity export forecast linkages. Heavy-haul contract duration trends and e-commerce fulfillment center expansion timelines informed corridor-specific growth assumptions.
Commodity price volatility, regulatory enforcement acceleration, and alternative-fuel infrastructure deployment delays are the dominant revision risks to the forecast framework. Forecasts reflect assumptions regarding Higher Mass Limit permit approval rates and mining sector capital commitment cycles. A model refresh is warranted upon material change in Heavy Vehicle National Law amendment implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Malaysia Domestic CEP Market
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
United States less than-Truck-Load (LTL) Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Global Automotive 3PL Market
Transportation & Logistics
Intermodal Freight Transportation Market
Transportation & Logistics
Europe Customs Brokerage Market
Transportation & Logistics
Nordics Road Freight Transport Market
Transportation & Logistics
Canada Customs Brokerage Market
Transportation & Logistics
Global Fourth Party Logistics Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
Slovakia Road Freight Transport Market
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
United Kingdom Warehousing and Distribution Logistics Market
Transportation & Logistics
United States Retail Reverse Logistics Market