
 Romania Road Freight Transport Market | 2026-2036
Romania Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Romania Road Freight Transport Market Insights
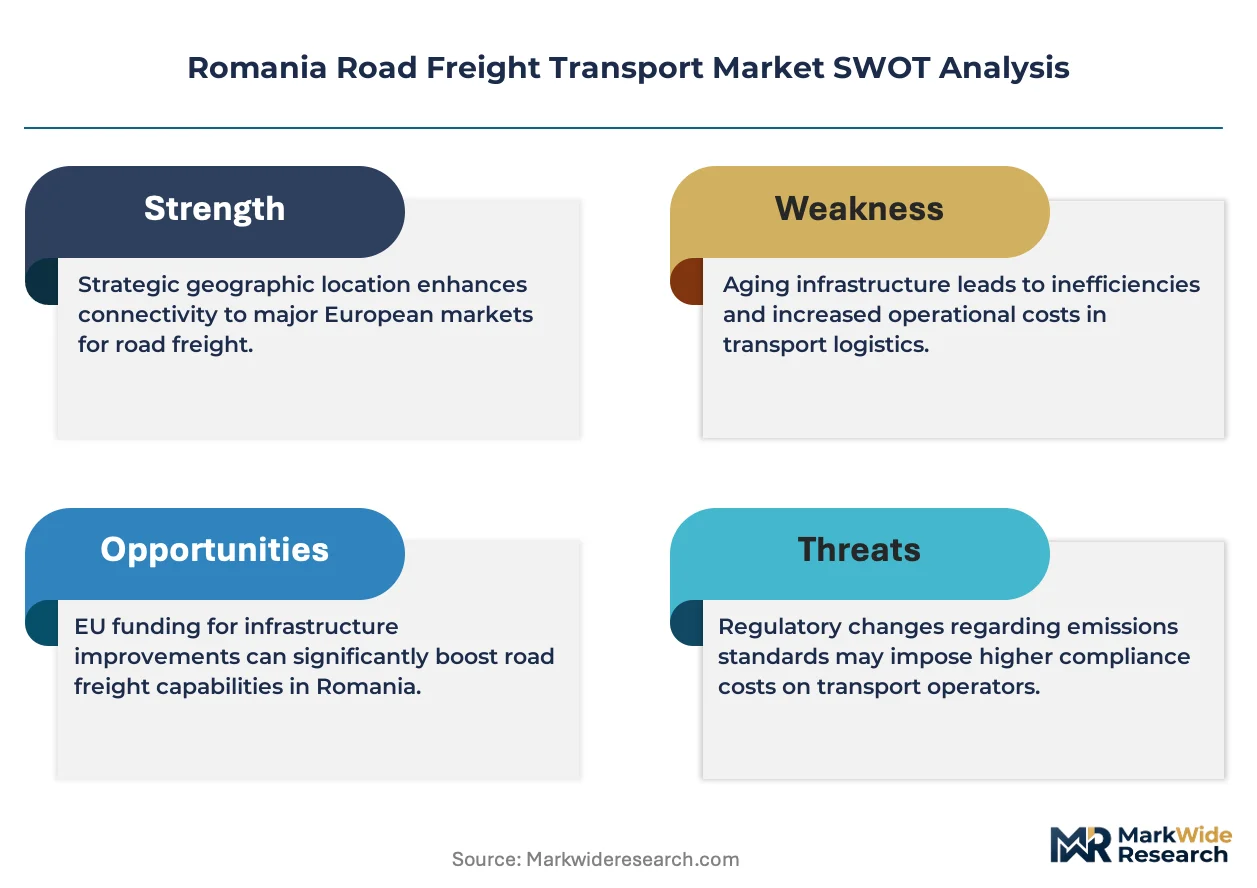
EU driver certification standards under the Mobility Package is bifurcating the Romanian carrier landscape into compliant fleet operators and marginal players. DSV A/S leverages its pan-European network density to sustain cross-border volumes through Romanian hubs. DHL Group anchors its regional position with integrated warehousing and last-mile capabilities near Bucharest. Raben Group differentiates through temperature-controlled specialization serving automotive and pharmaceutical shippers.
Romania road freight transport encompasses the commercial movement of goods via motorized vehicles on public road networks, utilizing tractor trailers, refrigerated trucks, flatbed trucks, and box trucks with payloads typically ranging from 3.5 to 44 tonnes gross vehicle weight. The sector functions as the dominant domestic logistics mode, handling approximately three-quarters of inland freight tonnage while connecting Black Sea ports to Central European manufacturing corridors. Full truck load services dominate revenue pools due to automotive and industrial contract volumes, while less than truck load segments capture fragmented SME demand with higher per-kilometer yields. E-commerce end users represent the fastest-growing demand channel, though manufacturers retain the largest absolute freight spend.
Romania's road freight sector operates under the EU Mobility Package enforced by the European Commission, national transport licensing administered by the Romanian Road Authority (AR), and vehicle emissions standards aligned with Euro VI regulations through the Ministry of Environment. These frameworks elevate operating costs for non-compliant carriers while creating barriers to market entry for unlicensed operators. Fleet operators and logistics buyers must monitor regulatory enforcement intensity and alternative fuel infrastructure deployment to align capital commitments with compliance trajectories.
Market Dynamics
The EU Mobility Package is compressing fleet operating margins while simultaneously bifurcating the Romanian carrier landscape into compliant operators and marginal players unable to absorb certification costs. This regulatory pressure is reshaping capital allocation across the sector.
Growth Catalysts
- Automotive production expansion:Vehicle manufacturers in the Transylvania industrial triangle are scaling component sourcing volumes. This concentrates contract freight demand around Cluj-Napoca and Sibiu logistics corridors.
- EU Green Deal alignment:Alternative fuel infrastructure deployment is accelerating fleet renewal timelines. Euro VI compliance requirements are pulling forward replacement cycles for aging tractor-trailer assets.
- E-commerce fulfillment density:Last-mile service requirements are expanding warehousing footprints near Bucharest-Ilfov. Parcel consolidation hubs are multiplying across secondary cities.
Market Restraints
- Driver labor scarcity:EU Mobility Package working-time rules are constraining available driving hours per operator. Romanian carriers face recruitment competition from Western European wage premiums.
- Depot infrastructure concentration:Temperature-controlled storage capacity clusters disproportionately around Bucharest and Timișoara. Pharmaceutical shippers encounter capacity bottlenecks during peak seasonal demand.
- Diesel price volatility:Fuel represents the largest variable cost component for fleet operators. Margin compression intensifies when crude benchmarks spike without corresponding freight rate adjustments.
Strategic Opportunities
- Cross-border consolidation:Hungarian and Bulgarian corridor integration offers network density gains for Romanian operators with EU operating licenses. Cabotage rights expansion enables triangular route optimization.
- Pharmaceutical cold chain specialization:Temperature-controlled transport certification opens premium-rate segments. GDP-compliant fleets command yield premiums from biologics manufacturers.
- Digital freight matching platforms:Real-time load-board adoption is reducing empty-backhaul kilometers. SME shippers gain access to spot-market capacity previously captured by contract relationships.
Industry Challenges
- Tachograph compliance enforcement:Romanian Road Authority roadside inspections are intensifying driver-hour verification. Non-compliant operators face license suspension and cargo seizure penalties.
- Telematics integration complexity:Legacy fleet management systems resist seamless connection with EU-mandated digital reporting tools. Carriers must bridge proprietary platforms with standardized government interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Romania Road Freight Transport Market |
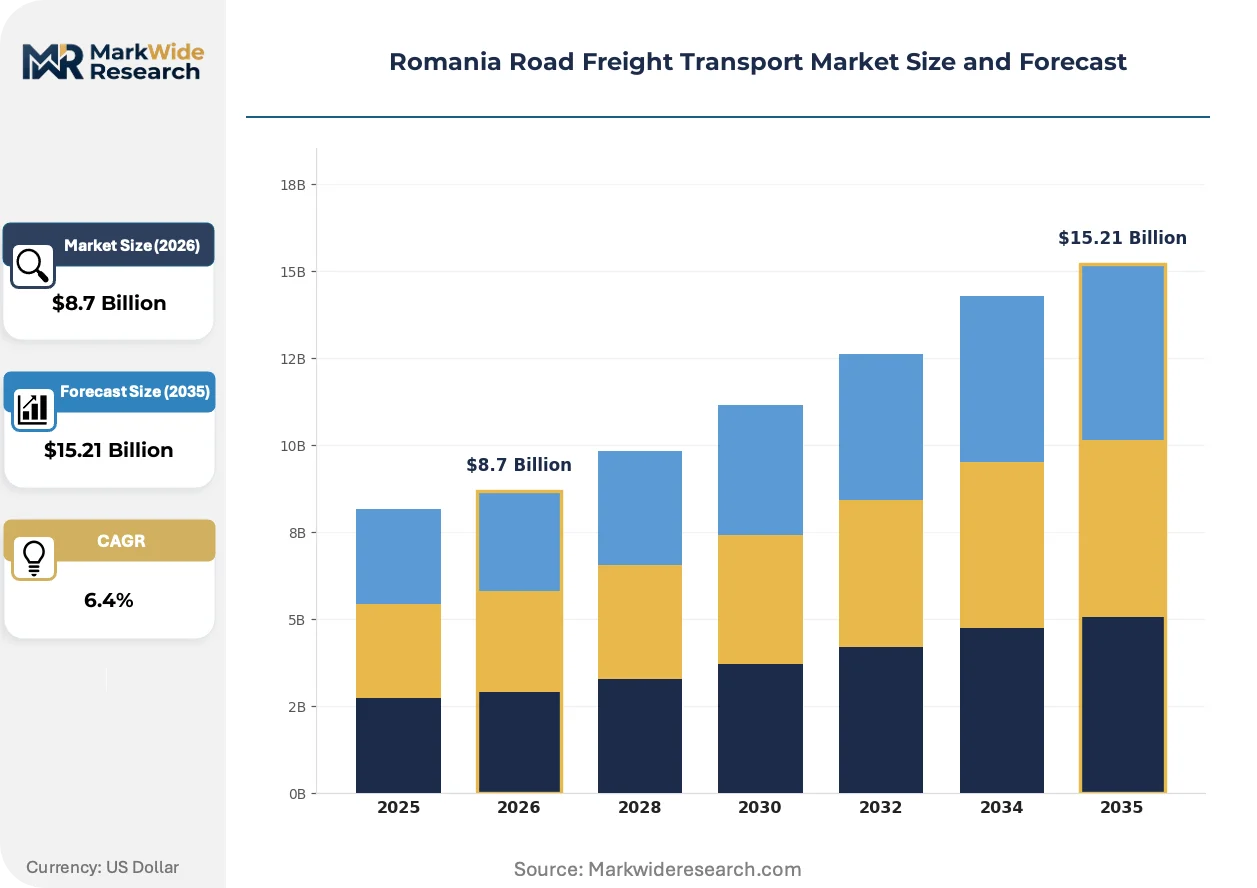
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less Than Truck Load, Dedicated Freight, Expedited Shipping Vehicle Type: Tractor Trailers, Refrigerated Trucks, Flatbed Trucks, Box Trucks End User: Manufacturers, Retailers, Wholesalers, E-commerce Distribution Channel: Direct Sales, Freight Brokers, Online Platforms, Third-Party Logistics |
| Companies Covered | DSV A/S, DHL Group, Kuehne + Nagel, AQUILA PART PROD COM SA, International Lazar Company, Raben Group, DACHSER, Dolo Trans Olimp, International Alexander SRL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Romania Road Freight Transport Market Trends and Innovations
Telematics and alternative drivetrain technologies are compressing operational decision cycles while regulatory digitization mandates force infrastructure investment. These forces are reconfiguring competitive advantage around data integration capabilities.
On-board diagnostic systems with real-time fuel consumption monitoring are miniaturizing. Automotive contract shippers in the Brașov-Sibiu corridor are deploying these sensors fleet-wide. This technology is miniaturizing route-planning optimization from dispatch-center functions to driver-level decision support.
EU Mobility Package cabotage restrictions are tightening cross-border operational flexibility. Romanian carriers with pan-European licenses face reduced monthly cabotage allowances within single member states. Full-truckload operators serving German manufacturing clients are restructuring hub networks to maintain service frequency.
Shippers are unbundling warehousing from transport contracts to optimize working capital. Automotive manufacturers near Pitești are separating inventory holding from line-haul services. This pattern is most visible in the Bucharest-Ilfov corridor where third-party logistics providers compete for standalone storage mandates.
Romania Road Freight Transport Market Segmentation
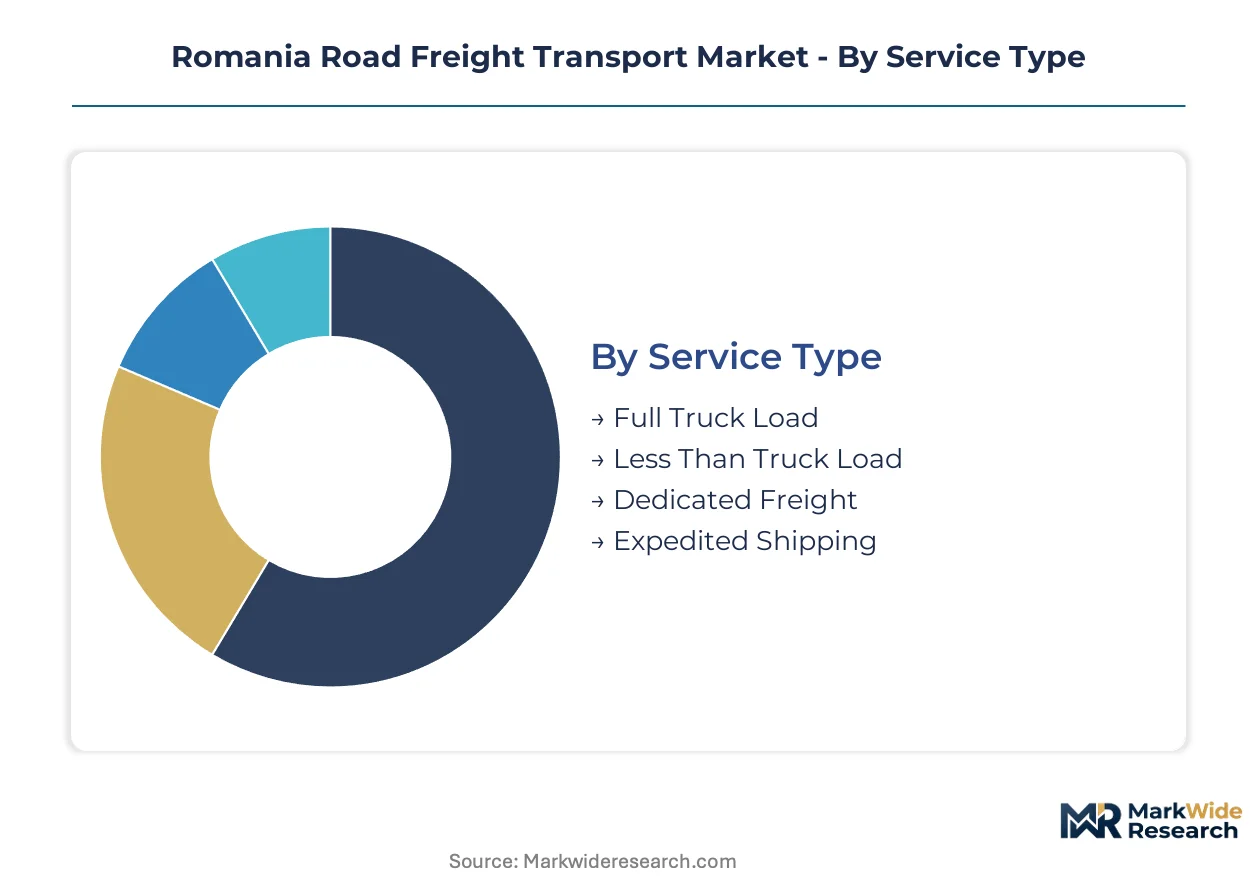
Romania's road freight market fragments across service configurations, vehicle specifications, and customer procurement patterns. Each segmentation axis carries distinct margin profiles and capital intensity requirements. Understanding substitution dynamics between adjacent segments reveals where carriers face the most acute competitive pressure.
Service Type:
Substitution pressure runs strongest between Dedicated Freight and Expedited Shipping, as automotive shippers in the Transylvania triangle increasingly blur urgency premiums against contracted capacity guarantees.
- Full Truck Load:Consolidated shipments occupying complete vehicle capacity from single origin to destination. Automotive manufacturers near Pitești and Sibiu dominate contract volumes, with component sourcing cycles driving predictable lane density. Fleet operators amortize tractor-trailer assets across high-frequency corridors.
- Less Than Truck Load:Aggregated partial shipments from multiple shippers sharing vehicle space. SME manufacturers in secondary cities generate fragmented demand with per-kilometer yield premiums, though hub-and-spoke infrastructure concentrates around Bucharest-Ilfov.
- Dedicated Freight:Exclusive vehicle allocation for single shipper on fixed routes. Pharmaceutical distributors near Timișoara deploy temperature-controlled dedicated fleets for GDP-compliant lane security.
- Expedited Shipping:Time-definite delivery with premium rate structures. E-commerce fulfillment centers in Brașov corridor absorb capacity for next-day delivery commitments.
Full Truck Load anchors the volume base while Expedited Shipping gains share at the steepest rate.
Vehicle Type:
Cost tier differentiation separates premium refrigerated assets from standard box truck deployments, with Euro VI compliance timelines compressing residual values for aging diesel fleets.
- Tractor Trailers:Articulated combinations with 40-tonne-plus gross weight ratings for long-haul corridor movements. Automotive contract lanes between Cluj-Napoca and Central European borders maximize utilization.
- Refrigerated Trucks:Insulated bodies with mechanical refrigeration for temperature-sensitive cargo. Biologics manufacturers command GDP-certified capacity with yield premiums covering higher fuel consumption.
- Flatbed Trucks:Open-deck configurations for oversized or non-containerized industrial loads. Construction material distributors in Brașov-Sibiu corridor deploy specialized securing equipment.
- Box Trucks:Rigid-body vehicles with enclosed cargo space for urban distribution. Last-mile e-commerce fulfillment in Bucharest-Ilfov relies on 3.5-7.5 tonne rigid configurations.
Tractor Trailers carry the revenue weight while Refrigerated Trucks command the widest margin spread.
End User:
Procurement sophistication varies sharply across customer type, with E-commerce platforms forcing digital integration requirements that marginal carriers cannot satisfy.
- Manufacturers:Industrial shippers with contracted lane requirements and integrated supply chain planning. Vehicle producers in Transylvania triangle negotiate multi-year capacity agreements.
- Retailers:Store replenishment networks with seasonal volume spikes. Grocery chains in Bucharest-Ilfov corridor demand flexible fleet scaling.
- Wholesalers:Intermediate distributors consolidating fragmented supplier bases. Regional trading companies in Timișoara hub serve cross-border Balkan markets.
- E-commerce:Pure-play and omnichannel fulfillment operators with parcel-level tracking requirements. Marketplace sellers drive demand for real-time visibility integration.
Manufacturers lock in the contract base while E-commerce expands most quickly.
Distribution Channel:
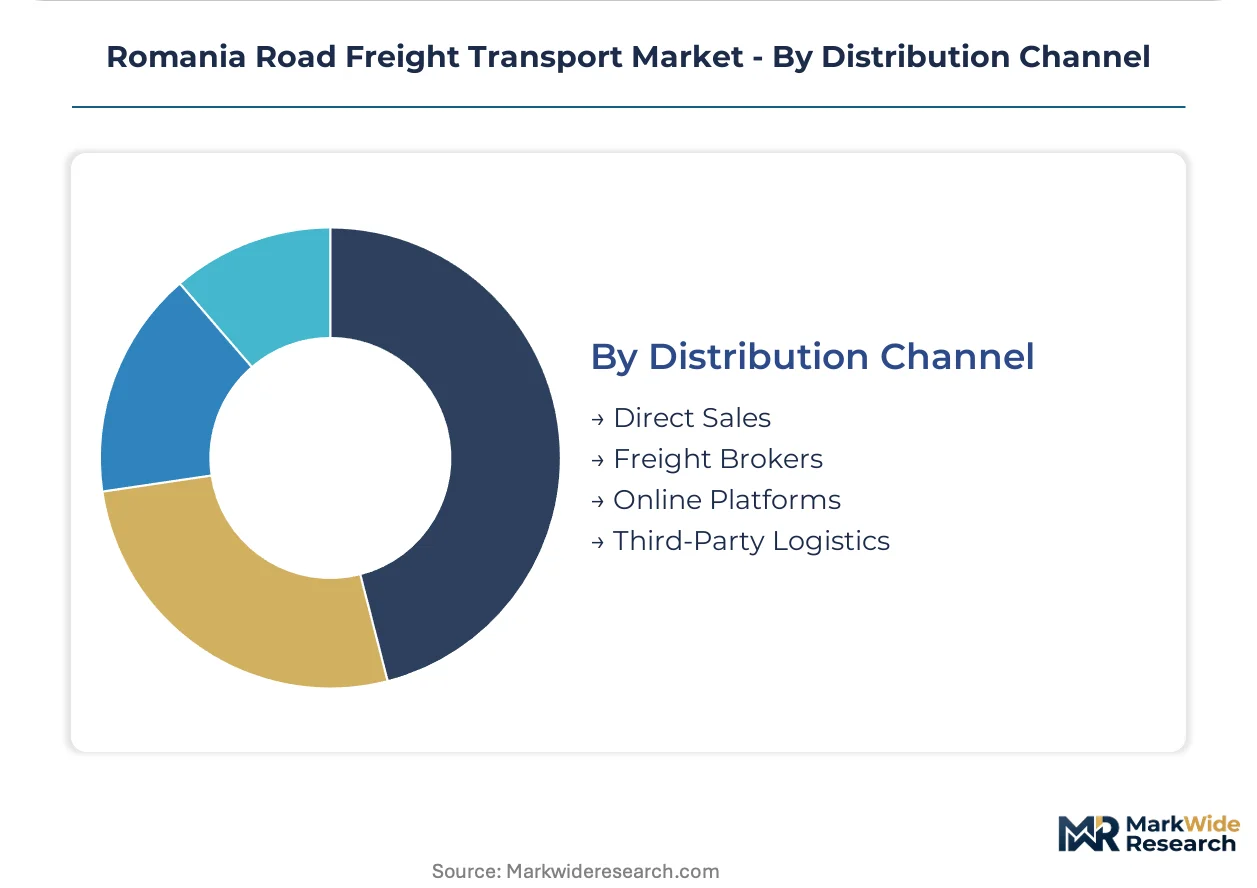
Channel concentration reflects shipper size and complexity tolerance, with large manufacturers bypassing intermediaries while SMEs rely on brokered capacity.
- Direct Sales:Carrier-shipper relationships without intermediary markup. Major automotive OEMs near Pitești negotiate directly with licensed fleet operators.
- Freight Brokers:Intermediaries matching spot market demand with available capacity. Regional brokers in Cluj-Napoca corridor aggregate SME manufacturing demand.
- Online Platforms:Digital freight matching with algorithmic pricing. Real-time load boards reduce empty-backhaul kilometers for owner-operators.
- Third-Party Logistics:Integrated transport and warehousing service bundles. DHL Group and Raben Group anchor regional 3PL presence near Bucharest.
Third-Party Logistics captures the integrated service premium while Online Platforms climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Mobility Package incentives are redrawing operational boundaries across Eastern European freight corridors. Romanian carriers navigate divergent national enforcement intensities while competing for cross-border contract volumes.
Poland
Polish fleet operators absorb the heaviest EU Mobility Package compliance costs in the region. The country's national transport regulator enforces driver working-time rules with roadside inspection density exceeding Romanian levels. Warsaw and Łódź logistics clusters concentrate temperature-controlled capacity serving German automotive clients.
Hungary
Hungarian carriers exploit triangular route optimization through Budapest-Debrecen corridor positioning. The national transport authority administers cabotage permits under stricter monthly allowance frameworks than Romania. Győr automotive suppliers generate dedicated freight demand linking to Austrian and Slovak assembly plants.
Bulgaria
Bulgarian operators compete aggressively on spot-market pricing along Black Sea corridor lanes. The Ministry of Transport enforces tachograph compliance with digital reporting mandates aligned to EU standards. Sofia and Plovdiv hubs consolidate Balkan peninsula freight for Romanian transit connections.
Czech Republic
Czech carriers leverage advanced telematics adoption rates to differentiate service offerings. The country's trade inspection authority coordinates cross-border enforcement with German and Austrian regulators. Brno and Ostrava industrial zones anchor component supply chains feeding Romanian automotive assembly.
Slovakia
Slovak logistics providers specialize in just-in-time sequences for premium automotive brands. The national transport office issues operating licenses with accelerated processing timelines relative to Romanian counterparts. Bratislava and Žilina manufacturing clusters demand precise delivery windows from Romanian subcontract hauliers.
Romania Road Freight Transport Market Competitive Landscape
Player mix skews toward pan-European network operators with integrated service capabilities. Market structure concentrates contract volumes among licensed carriers possessing EU-wide operating authority. Three archetypes dominate: multinational 3PL platforms with warehousing integration, regional specialists commanding temperature-controlled certification, and asset-light brokers aggregating SME spot demand. Competitive moves center on cross-border hub consolidation and digital freight-matching platform deployment.
Within the multinational 3PL tier, DSV A/S and DHL Group exemplify network-density strategies that sustain cross-border volumes through Romanian hubs. Raben Group occupies a position among temperature-controlled specialists serving automotive and pharmaceutical shippers with GDP-compliant fleet assets. Regional brokers including AQUILA PART PROD COM SA and International Lazar Company anchor the fragmented mid-market segment connecting SME manufacturing demand to available capacity.
| Leading Market Players |
|---|
| DSV A/S |
| DHL Group |
| Kuehne + Nagel |
| AQUILA PART PROD COM SA |
| International Lazar Company |
| Raben Group |
| DACHSER |
| Dolo Trans Olimp |
| International Alexander SRL |
| Others |
Pricing and Supply Chain Analysis
EU Mobility Package compliance costs are displacing non-certified capacity as shippers consolidate contracts with licensed operators, simultaneously compressing spot-market rates in Bucharest-Ilfov while elevating contract premiums for GDP-certified fleets serving pharmaceutical corridors.
Pricing Analysis
Certification level under EU Mobility Package and GDP standards creates the primary spread between premium and economy rate tiers. Three-tier pricing structure separates compliant dedicated fleets from standard contract carriers and spot-market brokers. Cost compression in the spot tier intensifies because diesel volatility and driver scarcity squeeze owner-operator margins. SME manufacturers in secondary cities exhibit highest price sensitivity, while biologics shippers near Timișoara accept yield premiums for temperature-validated lane security.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive component flows between Cluj-Napoca and Central European assembly plants, while pharmaceutical distributors maintain strategic stockpiles near Bucharest to buffer seasonal demand spikes. Fleet assets concentrate in Romania, Hungary, and Poland, with cross-border cabotage rights determining effective supply radius. Diesel fuel, refrigerated unit components, and telematics hardware constitute critical input dependencies. Single-source vulnerability runs through EU-approved tachograph suppliers. Distribution runs through hub-and-spoke networks anchored by Bucharest-Ilfov consolidation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among automotive OEMs and pharmaceutical distributors, with contract volumes consolidating toward fewer carriers possessing integrated warehousing and cross-border licensing.
For Market Incumbents: Secure GDP certification expansion and telematics integration ahead of EU Mobility Package enforcement intensification. Defensive consolidation should prioritize temperature-controlled capacity additions near Timișoara and Brașov corridors. Driver retention programs constitute the critical lever against Western European wage competition. For New Entrants and Emerging Players: Digital freight matching platforms represent the service-layer gap where legacy operators under-serve SME spot demand. The most penetrable segment sits among fragmented manufacturers in secondary cities lacking direct carrier relationships. A go-to-market angle anchored by real-time visibility APIs can capture owner-operator capacity outside contract networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional brokers lacking EU-wide operating authority. Long-term viability favors carriers with backward integration into warehousing and alternative fuel infrastructure deployment. The signal to watch is AR enforcement intensity against non-compliant operators as a consolidation catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| EU Mobility Package Compliance Investment | AR licensing requirements bifurcate carrier landscape into compliant and marginal players. |
| Temperature-Controlled Fleet Expansion | GDP-certified capacity commands yield premiums from biologics manufacturers near Timișoara. |
| Cross-Border Hub Consolidation | Hungarian and Bulgarian corridor integration enables triangular route optimization under cabotage rules. |
| Digital Freight Platform Deployment | Real-time load boards reduce empty-backhaul kilometers for owner-operators in secondary cities. |
| Alternative Fuel Infrastructure Partnership | Euro VI compliance timelines accelerate fleet renewal cycles across diesel-dependent operators. |
Research Methodology
A standing panel of fleet operations directors, AR licensing officers, pharmaceutical supply chain managers, and automotive procurement leads provided ongoing calibration across primary fieldwork. Secondary validation drew from EU Mobility Package regulatory filings, Romanian Road Authority enforcement statistics, customs transit data, and carrier financial disclosures. Bottom-up route-density modeling and top-down sector revenue estimates were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, vehicle specification, end-user procurement pattern, and regional corridor density. CAGRs were derived from historical lane volume trajectories and contract renewal rate analysis. Forecast inputs incorporated EU Green Deal infrastructure deployment timelines and diesel price scenario modeling.
Forecasts assume regulatory continuity in EU Mobility Package enforcement and AR licensing regimes; material policy shifts would require re-modeling. Specific risk factors include abrupt diesel taxation changes, driver wage inflation spikes, and alternative fuel infrastructure delays. Revision becomes warranted when AR inspection intensity or cabotage rule modifications cross thresholds that alter carrier compliance economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Canada Customs Brokerage Market
Transportation & Logistics
Saudi Arabia Road Freight Transport Market
Transportation & Logistics
Europe Customs Brokerage Market
Transportation & Logistics
Cross-Border Road Transport Market
Transportation & Logistics
Slovakia Road Freight Transport Market
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
Russia Road Freight Transport Market
Transportation & Logistics
United States less than-Truck-Load (LTL) Market
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
Inland Water Freight Transport Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
China Road Freight Transport Market
Transportation & Logistics
Train Collision Avoidance System Market
Transportation & Logistics
Colombia Road Freight Transport Market