
 Latin America Customs Brokerage Market | 2026-2036
Latin America Customs Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Customs Brokerage Market Foresight
The EU Green Deal's extraterritorial carbon border adjustment requirements is pivoting Latin American exporters toward customs brokers with embedded emissions documentation capabilities. Livingston International leverages integrated trade consulting platforms to sustain competitive positioning across Mexican automotive corridors. Grupo Ei anchors its presence through deep port relationships in Brazilian southeastern logistics clusters. Rota Brasil differentiates via specialized perishables handling protocols for Mercosur agricultural exporters.
Latin America customs brokerage encompasses licensed intermediary services managing tariff classification, duty calculation, and regulatory compliance for goods crossing sovereign borders, typically operating through electronic data interchange systems integrated with national customs platforms such as Brazil's Siscomex or Mexico's VUCEM. The primary commercial purpose centers on minimizing cargo dwell time while ensuring accurate fiscal and sanitary compliance for shippers. Import clearance services dominate transaction volumes due to complex local content rules and deferred duty regimes, while e-commerce end users represent the fastest-expanding segment as cross-border parcel volumes strain last-mile customs infrastructure. Warehousing services capture disproportionate margins by bundling inventory management with in-bond storage solutions near manufacturing zones.
Brazil's Receita Federal administers Siscomex declarations under strict penalty frameworks, while Mexico's SAT enforces VUCEM electronic filing mandates that reshape broker technology investments. ANVISA in Brazil and COFEPRIS in Mexico impose parallel sanitary registration requirements that compound documentation complexity for pharmaceutical and food imports. Stakeholders must evaluate broker digital maturity against accelerating real-time customs data exchange mandates before selecting regional partners.
Market Dynamics
Cross-border e-commerce parcel volumes are straining Latin American customs infrastructure, forcing brokers to reengineer clearance workflows for de minimis thresholds and real-time duty calculation at scale.
Growth Catalysts
- Brazil's REPETRO customs regime:Streamlined temporary import procedures for oil and gas equipment are reducing dwell times and attracting specialized broker investment into Macaé and Rio de Janeiro port clusters.
- Mexican automotive manufacturing corridors:Tijuana and Monterrey assembly plants demand expedited customs clearance for just-in-time component flows, concentrating broker capacity near maquiladora zones.
- Electronic data interchange mandates:Brazil's Siscomex and Mexico's VUCEM platforms are digitizing declarations and creating competitive differentiation for brokers with native API integration capabilities.
Market Restraints
- Input cost volatility:Fuel and last-mile trucking rates fluctuate with diesel subsidies and currency movements, compressing margins on bonded warehouse operations.
- Supply concentration risk:Port infrastructure bottlenecks at Santos and Manzanillo create single-point-of-failure exposure for clearance-dependent supply chains.
- Regulatory friction:Parallel sanitary registration requirements from ANVISA and COFEPRIS compound documentation complexity for pharmaceutical and food imports, extending clearance timelines.
Strategic Opportunities
- Colombian Pacific corridor expansion:Buenaventura port modernization and Pacific Alliance trade integration create underpenetrated demand for customs brokerage serving Andean agricultural exporters.
- Emissions documentation capabilities:EU Green Deal carbon border adjustment requirements are pivoting Latin American exporters toward brokers with embedded carbon accounting and certificate-of-origin verification services.
- Perishables handling protocols:Specialized cold-chain customs clearance for Mercosur agricultural exporters represents a service white space distinct from general freight forwarding.
Industry Challenges
- Customs technology talent scarcity:Siscomex and VUCEM platform expertise remains concentrated among legacy operators, constraining scaling for mid-tier brokers.
- Legacy system integration friction:Real-time data exchange mandates require API connectivity with shipper ERP systems that many regional freight forwarders lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Customs Brokerage Market |
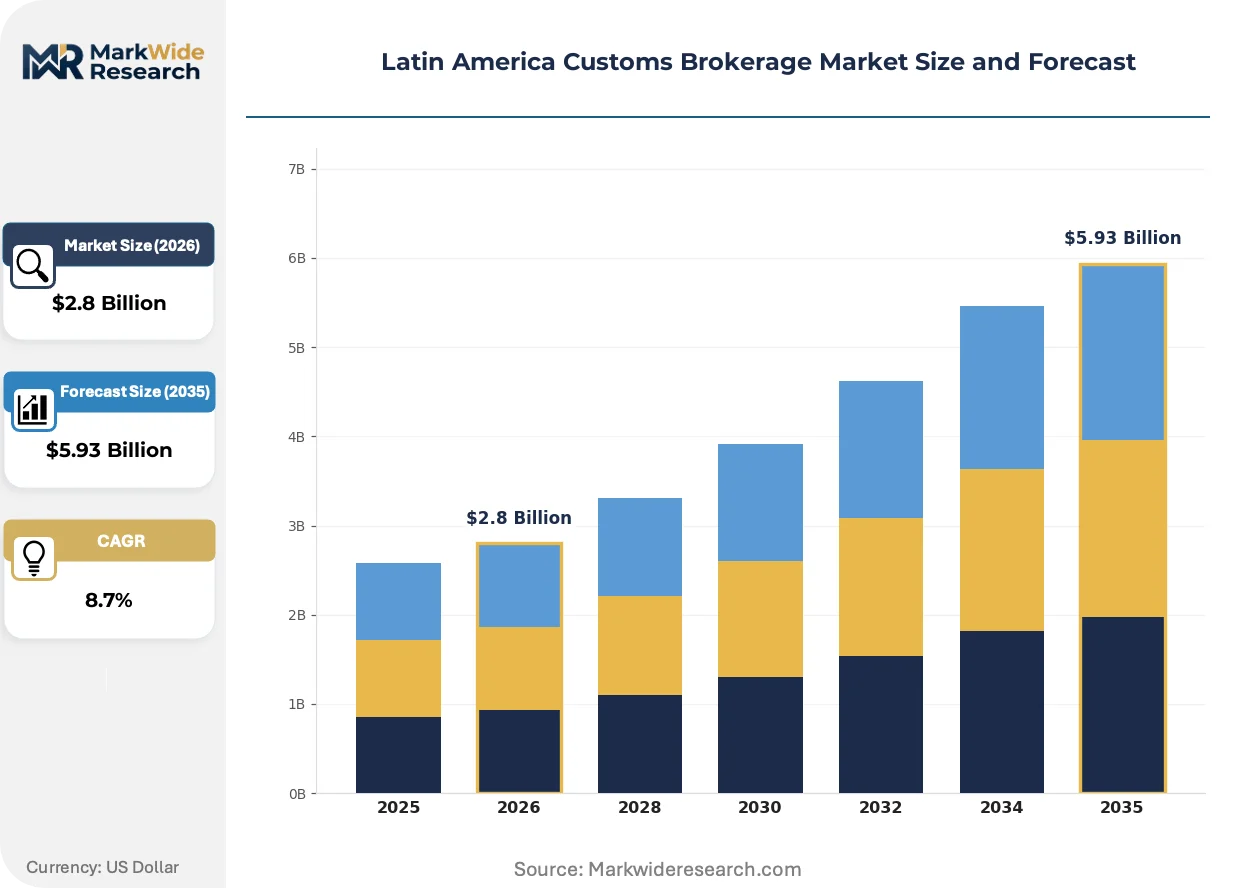
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Forwarding, Import Clearance, Export Clearance, Warehousing End User: Manufacturers, Retailers, Distributors, E-commerce Industry Vertical: Automotive, Pharmaceuticals, Electronics, Textiles Delivery Model: On-Demand, Subscription, Pay-Per-Use, Annual Contracts |
| Companies Covered | Grupo Ei, Livingston International, Farrow, Rota Brasil, Ibercondor Forwarding SA de CV, Elemar, Grupo Coex, Servicios de Aduanas Jiménez, Aduana Cordero, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Customs Brokerage Market Shifts & Advancements
Digital customs platforms are converging with trade finance and supply chain visibility tools, creating integrated service stacks that redefine broker value propositions beyond clearance execution.
Blockchain-enabled certificate-of-origin verification is converging with automated tariff classification engines. Agricultural exporters in Brazil and Argentina are piloting these systems for preferential trade claims under Mercosur agreements. The technology is converging with customs broker service offerings to compress documentation audit cycles and reduce penalty exposure from misclassification errors.
EU Green Deal extraterritorial carbon border adjustment requirements are reshaping exporter documentation obligations. Latin American customs brokers must now embed emissions verification into standard clearance workflows for steel, cement, and aluminum shipments. Brazilian metal exporters are responding by pre-qualifying brokers with embedded carbon accounting capabilities before contract renewal cycles.
Shippers are unbundling customs brokerage from freight forwarding relationships and selecting specialists based on platform integration depth. E-commerce platforms in Brazil and Mexico are driving this disintermediation by demanding direct API connectivity for real-time duty calculation at checkout. The shift is most visible in São Paulo and Mexico City logistics clusters where platform-native brokers are displacing traditional forwarder-affiliated clearance desks.
Latin America Customs Brokerage Market Segmentation
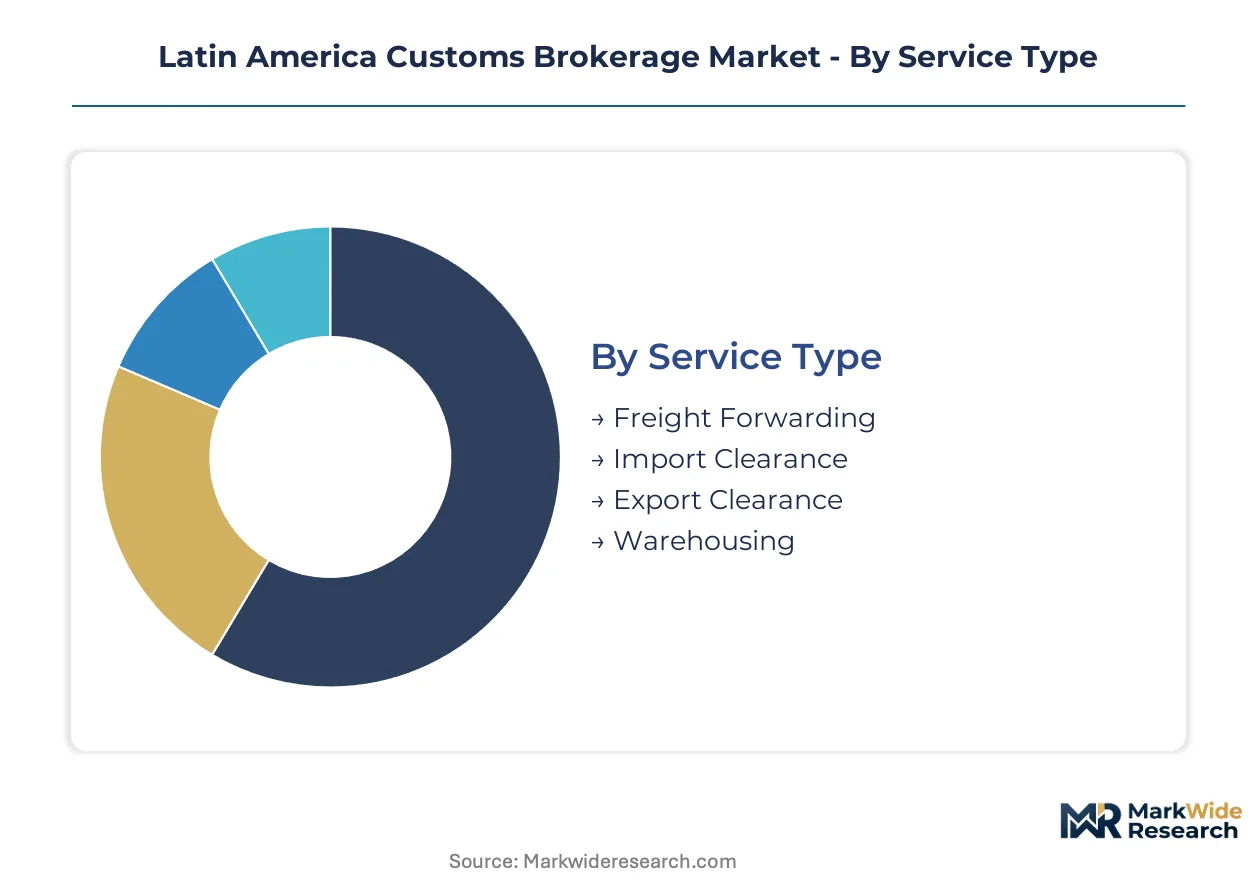
Service differentiation across Latin American customs brokerage determines margin capture and client retention. Brokers segment capabilities to match regulatory complexity, cargo velocity requirements, and compliance risk profiles across Brazilian and Mexican trade corridors.
Service Type:
Import clearance commands the highest transaction volumes while warehousing delivers premium margins through bonded storage bundling.
- Import Clearance:Licensed intermediaries manage Siscomex and VUCEM declarations, tariff classification, and duty calculation under strict penalty frameworks from Receita Federal and SAT. Demand concentrates near São Paulo and Mexico City manufacturing clusters where local content rules and deferred duty regimes multiply documentation touchpoints.
- Warehousing:In-bond storage solutions bundled with inventory management capture disproportionate margins by extending broker relationships beyond clearance events. Facilities near Tijuana and Monterrey maquiladora zones serve just-in-time automotive component flows with expedited release protocols.
- Freight Forwarding:Transportation coordination services increasingly unbundle from brokerage as shippers select specialists based on platform integration depth.
- Export Clearance:Preferential trade claims under Mercosur and Pacific Alliance agreements require certificate-of-origin verification and emissions documentation for EU-bound shipments.
Mature deployment sits with import clearance. Newer deployment is concentrated in warehousing.
End User:
Traditional manufacturing buyers anchor revenue stability while digital-native customers force workflow reinvention.
- E-commerce:Cross-border parcel volumes are straining last-mile customs infrastructure across Brazilian and Mexican urban corridors. Platforms demand direct API connectivity for real-time duty calculation at checkout, displacing traditional forwarder-affiliated clearance desks in São Paulo and Mexico City logistics clusters.
- Manufacturers:Automotive and electronics producers near Tijuana and Monterrey require expedited clearance for just-in-time component flows with minimal dwell time tolerance.
- Retailers:Department store and supermarket chains rely on brokers for seasonal import surges and sanitary compliance coordination with ANVISA and COFEPRIS.
- Distributors:Third-party logistics providers serving fragmented retail networks prioritize brokers with multi-port coverage across Santos, Manzanillo, and Buenaventura.
Established relationships dominate manufacturing. Platform-native engagement is expanding fastest among e-commerce operators.
Industry Vertical:
Regulatory intensity varies sharply across verticals, with pharmaceutical and food imports facing parallel sanitary registration requirements.
- Pharmaceuticals:ANVISA and COFEPRIS impose parallel sanitary registration mandates that compound documentation complexity and extend clearance timelines for temperature-sensitive shipments. Brazilian and Mexican importers pre-qualify brokers with cold-chain custody documentation and batch-specific tracking capabilities.
- Automotive:Maquiladora assembly plants in Tijuana and Monterrey corridors concentrate demand for expedited component clearance with zero-dock-time tolerance.
- Electronics:Consumer device importers leverage deferred duty regimes and temporary admission frameworks for warranty replacement parts.
- Textiles:Apparel shipments from Asian origins face origin verification scrutiny under preferential trade agreements, requiring certificate-of-origin blockchain validation.
Deep specialization anchors pharmaceuticals. Steepest expansion trajectory appears in automotive as nearshoring accelerates.
Delivery Model:
Contract structures align broker capacity commitment with shipper volume predictability and technology integration depth.
- Annual Contracts:Multi-year agreements with dedicated account management and SLA-guaranteed clearance windows anchor revenue for top-tier brokers serving multinational manufacturers.
- Subscription:Flat-fee arrangements for platform access and declaration processing suit mid-market shippers with predictable monthly volumes.
- Pay-Per-Use:Transaction-based pricing attracts seasonal importers and project-driven oil and gas equipment shippers under Brazil's REPETRO regime.
- On-Demand:Spot-market engagement through digital platforms serves e-commerce sellers with irregular shipment patterns and de minimis threshold complexity.
Long-term commitment structures dominate enterprise accounts. Flexible consumption models are gaining share fastest among digital-native shippers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors customs brokerage demand across Latin America, with its southeastern logistics cluster processing the highest declaration volumes through Siscomex. Mexico City's corridor concentrates VUCEM platform traffic for automotive and electronics manufacturers. Buenos Aires, Santiago, and Bogotá complete the pentad of metropolitan customs intensity.
Brazil
Macaé and Rio de Janeiro port clusters attract specialized broker investment under REPETRO temporary import frameworks for oil and gas equipment. ANVISA imposes parallel sanitary registration mandates that extend clearance timelines for pharmaceutical shipments. São Paulo's manufacturing belt generates sustained demand for Siscomex-native API integration capabilities among platform-native brokers.
Mexico
Tijuana and Monterrey maquiladora corridors concentrate demand for expedited clearance with zero-dock-time tolerance for just-in-time automotive components. SAT enforces VUCEM electronic filing mandates that reshape broker technology investments. Mexico City logistics clusters witness platform-native brokers displacing traditional forwarder-affiliated clearance desks through direct API connectivity.
Argentina
Buenos Aires anchors Mercosur agricultural export flows requiring specialized perishables handling protocols and cold-chain customs clearance. The national customs administration maintains strict certificate-of-origin verification for preferential trade claims. Rosario's grain corridor generates seasonal surges in declaration volumes for soybean and wheat exporters.
Chile
Valparaíso and San Antonio port complexes serve as Pacific Alliance trade integration gateways for Andean agricultural exporters. The national customs service digitizes declarations through advanced electronic data interchange platforms. Santiago's distribution networks concentrate demand for bonded warehousing solutions near consumption centers.
Colombia
Buenaventura port modernization creates underpenetrated demand for customs brokerage serving Pacific corridor agricultural exporters. DIAN customs administration enforces real-time data exchange mandates that favor brokers with integrated ERP connectivity. Bogotá's logistics clusters attract investment in emissions documentation capabilities for EU-bound shipments.
Latin America Customs Brokerage Market Competitive Landscape
The competitive structure tilts toward port-affiliated specialists with deep regulatory relationships. Tiered differentiation separates platform-native integrators from legacy forwarder-affiliated desks. Three archetypes dominate: Siscomex/VUCEM-native technology specialists, perishables-focused cold-chain operators, and integrated trade consulting platforms. M&A activity concentrates on acquiring API development capabilities, while strategic partnerships target carbon accounting service bundling.
Within the integrated trade consulting tier, Livingston International represents platform-native positioning across Mexican automotive corridors. Grupo Ei anchors the port-relationship archetype through southeastern Brazilian logistics clusters. Rota Brasil exemplifies specialized perishables differentiation for Mercosur agricultural exporters.
| Leading Market Players |
|---|
| Grupo Ei |
| Livingston International |
| Farrow |
| Rota Brasil |
| Ibercondor Forwarding SA de CV |
| Elemar |
| Grupo Coex |
| Servicios de Aduanas Jiménez |
| Aduana Cordero |
| Others |
Supply & Pricing Matrix
Siscomex-certified clearance specialists concentrated in São Paulo's southeastern logistics cluster command wage premiums that compress margins for mid-tier brokers, widening the spread between platform-native API-integrated service tiers and legacy manual-processing desks.
Pricing Analysis
Clearance velocity guarantees anchor value-based pricing for automotive and pharmaceutical shippers with zero-dock-time tolerance. Three-tier pricing structure across premium, standard, and economy levels separates API-native brokers with real-time VUCEM integration from port-affiliated generalists and spot-market transaction processors. Cost compression in standard-tier bonded warehousing intensifies because fuel subsidy volatility and currency swings erode last-mile trucking margins. E-commerce platforms exhibit highest price sensitivity due to de minimis threshold complexity, while oil and gas equipment shippers under REPETRO frameworks prioritize compliance certainty over rate minimization.
Supply Chain Analysis
Return flows of temporarily admitted oil and gas equipment under Brazil's REPETRO regime create reverse-logistics revenue streams for Macaé and Rio de Janeiro port specialists. Customs brokerage capacity draws from Brazil, Mexico, and Colombia as the dominant geographic concentration. Specialized inputs hinge on diesel fuel for bonded trucking, API development talent, and cold-chain infrastructure for perishables. Single-point-of-failure exposure concentrates at Santos and Manzanillo port bottlenecks. Distribution runs through direct shipper-broker platform integrations displacing traditional forwarder-affiliated clearance desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American customs brokerage is consolidating as real-time data exchange mandates from Siscomex and VUCEM force technology-deficient regional players toward exit or acquisition.
For Market Incumbents: To counter displacement by platform-native brokers with direct API connectivity, deepen Siscomex and VUCEM integration capabilities through targeted developer hiring in São Paulo and Mexico City logistics clusters. Acquire carbon accounting service bundling to capture EU Green Deal documentation demand from steel and aluminum exporters. For New Entrants and Emerging Players: Launch via on-demand digital platforms serving irregular-volume e-commerce sellers with de minimis threshold complexity in underpenetrated Colombian Pacific corridor markets. Target Buenaventura port modernization spillover demand for Andean agricultural exporters lacking integrated ERP customs connectivity. For Investors and Strategic Acquirers: Re-rating potential sits with API-native mid-tier specialists given accelerating real-time customs data exchange mandates across Brazilian and Mexican regulatory frameworks. Acquisition focus should center on brokers with captive Siscomex platform expertise and established ANVISA pharmaceutical registration relationships. Monitor VUCEM mandate enforcement intensity as inflection indicator for technology investment urgency.| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Platform Development | Direct VUCEM and Siscomex integration displaces forwarder-affiliated clearance desks in São Paulo corridors. |
| Carbon Accounting Service Bundling | Embedded emissions verification captures EU Green Deal documentation demand from Brazilian metal exporters. |
| Cold-Chain Infrastructure Investment | Specialized perishables handling protocols secure Mercosur agricultural exporter relationships in Rosario and Buenos Aires. |
| Strategic Port Relationship Deepening | Preferred operator status at Santos and Manzanillo mitigates single-point-of-failure concentration risk. |
| Acquisition of Regulatory Affairs Specialists | ANVISA and COFEPRIS expertise acquisition compresses pharmaceutical clearance timelines for temperature-sensitive shipments. |
Research Methodology
Independent corroboration across customs brokerage operations directors, VUCEM platform integration specialists, pharmaceutical supply chain managers, and automotive logistics procurement leads underwrites the qualitative findings. Secondary validation draws from Receita Federal Siscomex declaration statistics, SAT electronic filing disclosures, ANVISA import registration databases, and Pacific Alliance trade flow records. Bottom-up transaction volume estimates triangulate against top-down customs revenue projections.
Rate-of-change decomposition separates volume growth from value-per-transaction evolution across import clearance, warehousing, freight forwarding, and export clearance service categories. End-user segmentation models e-commerce platform demand, manufacturing just-in-time requirements, retail seasonal surges, and distributor multi-port coverage needs. Industry vertical disaggregation captures pharmaceutical sanitary registration complexity, automotive zero-dock-time tolerance, electronics deferred duty utilization, and textiles origin verification intensity. CAGRs derive from regression against customs modernization investment cycles and trade corridor infrastructure development.
Regulatory enforcement intensity shifts, currency volatility spikes, and port infrastructure disruption are the dominant revision risks. Forecasts reflect underlying assumptions about VUCEM and Siscomex mandate implementation pacing. Practitioners should monitor REPETRO regime modifications, EU carbon border adjustment rollout timing, and maquiladora corridor expansion velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Japan Road Freight Transport Market
Transportation & Logistics
Malaysia Refrigerated Trailer Market
Transportation & Logistics
Cross-Border Road Transport Market
Transportation & Logistics
Hungary Road Freight Transport Market
Transportation & Logistics
Brazil Road Freight Transport Market
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
Asia-Pacific Customs Brokerage Market
Transportation & Logistics
Brazil Cold Chain Logistics Market
Transportation & Logistics
Transportation and Security System Market
Transportation & Logistics
Indonesia Road Freight Transport Market
Transportation & Logistics
Nordics Road Freight Transport Market
Transportation & Logistics
Traction Equipment Market
Transportation & Logistics
Trade-In and Buy-Back Logistics Programs Management Market
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
Global Automotive 3PL Market
Transportation & Logistics
Saudi Arabia Road Freight Transport Market