
 Express Delivery Market | 2026-2036
Express Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Express Delivery Market Intelligence
Buyer concentration among mega-retailers is restructuring contract dynamics across the express delivery sector. United Parcel Service leverages its integrated ground-air network to secure multi-year e-commerce commitments. FedEx anchors trans-Pacific capacity through its Memphis superhub operations. DHL Group differentiates in European cross-border B2B with customs-bonded infrastructure and pharmaceutical certification.
Express delivery encompasses time-definite transportation of parcels and documents through integrated multimodal networks operating on guaranteed service-level agreements, typically within 24-72 hours. Sortation automation, dynamic route optimization, and real-time tracking telemetry enable velocity at scale for industrial supply chains and consumer fulfillment. Same-day delivery commands premium pricing but remains operationally constrained to dense urban corridors, while next-day delivery sustains the volume base across national networks. Temperature-controlled logistics concentrates margin pools in healthcare and biopharma verticals where regulatory compliance creates barriers to entry.
The FAA governs U.S. drone delivery pilot programs through Part 135 air carrier certification, while the EU Green Deal's F-Gas Regulation and emissions trading scheme compel fleet decarbonization across European operations. China's MIIT enforces national EV penetration targets for urban logistics vehicles under dual carbon policy frameworks. Stakeholders must monitor which regulatory jurisdiction sets the binding standard for cross-border carbon accounting and last-mile automation deployment.
Market Dynamics
E-commerce fulfillment velocity requirements are compressing sortation timelines and forcing network reconfiguration across the express delivery sector. The EU Green Deal's emissions mandates and China's MIIT electrification targets are accelerating capital deployment into electric last-mile fleets.
Growth Catalysts
- EU Green Deal decarbonization mandates:The F-Gas Regulation and emissions trading scheme compel European carriers to electrify urban delivery fleets, creating sustained equipment demand and infrastructure investment cycles.
- Biopharma cold-chain certification:Temperature-controlled logistics for pharmaceutical products commands premium service tiers and creates defensible margin pools through regulatory compliance barriers.
- China's domestic express volume concentration:Urban logistics density in tier-one cities enables same-day delivery economics that remain unachievable in comparably sized Western metropolitan areas.
Market Restraints
- Aviation fuel cost volatility:Jet fuel represents the largest variable cost input for integrated air-ground networks, with price spikes immediately compressing express margin structures.
- Sortation equipment supply concentration:Automated parcel handling systems rely on a concentrated German-Japanese vendor base, creating procurement bottlenecks during capacity expansion cycles.
- Last-mile labor availability constraints:Driver recruitment and retention challenges in dense urban corridors limit same-day delivery scalability regardless of capital deployment.
Strategic Opportunities
- India's underpenetrated e-commerce logistics:Fragmented last-mile infrastructure and rising digital commerce adoption create whitespace for express network buildouts beyond tier-one cities.
- Drone delivery air carrier certification:FAA Part 135 pathways and parallel European frameworks are establishing regulatory foundations for autonomous aerial last-mile deployment in suburban corridors.
- Pharmaceutical serialization convergence:Integration of track-and-trace compliance with express visibility systems creates bundled service offerings for healthcare supply chains.
Industry Challenges
- Sortation automation capex intensity:Hub modernization requires nine-figure capital commitments with payback periods stretching across multiple economic cycles.
- Legacy TMS integration friction:Enterprise shippers demand API-native visibility while carriers maintain decades-old transportation management architectures.
- Cross-border customs certification timelines:Authorized economic operator status and pharmaceutical handling licenses require multi-year compliance investments with uncertain approval outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Express Delivery Market |
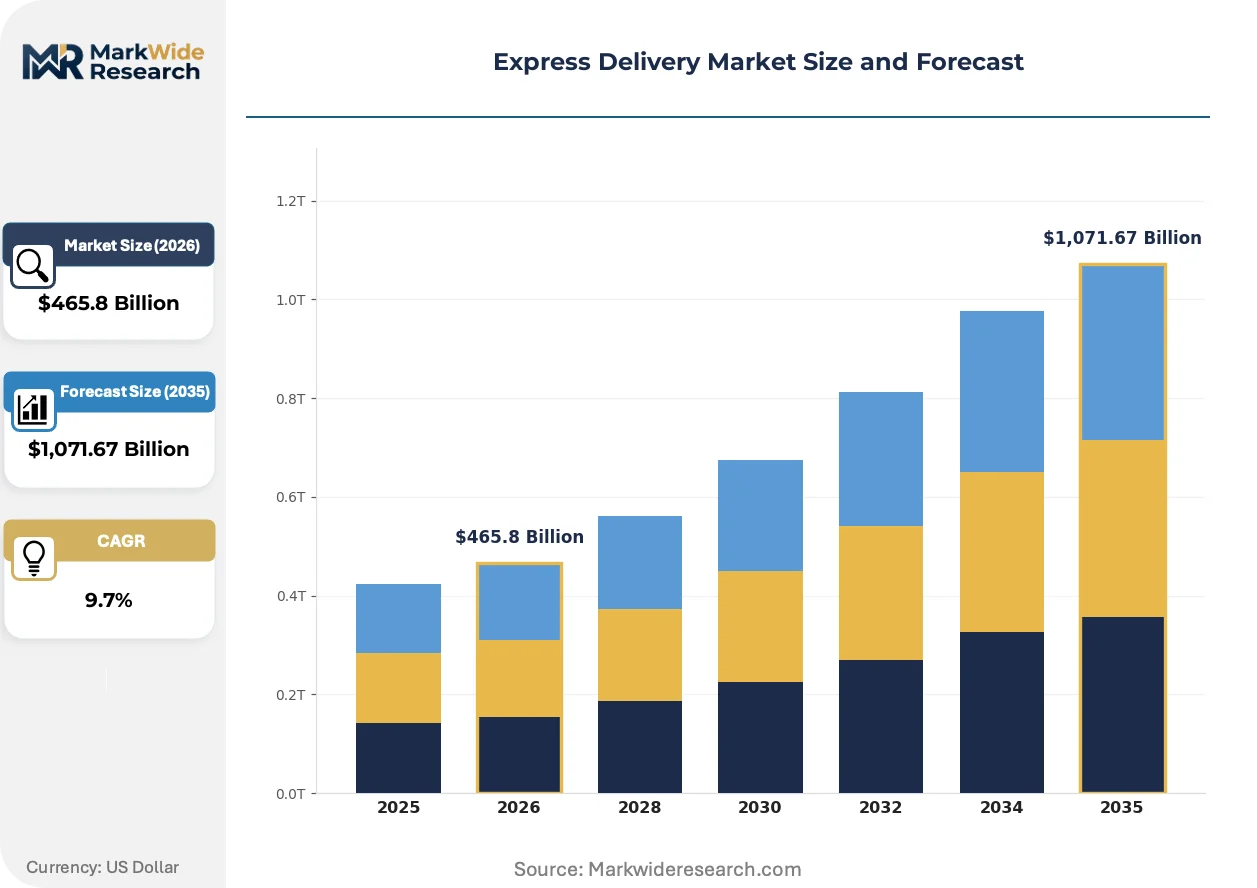
| Market Size in 2026 | $465.8 Billion |
| Market Size in 2035 | $1,071.67 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Scheduled Delivery, On-Demand Delivery End User: E-commerce, Retail, Healthcare, Enterprises Delivery Mode: Ground, Air, Drone, Maritime Package Type: Parcels, Pallets, Document, Temperature-Controlled |
| Companies Covered | FedEx, United Parcel Service, DHL Group, SF Holding, Aramex, Delhivery, Japan Post Holdings, Poste Italiane, ZTO Express, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Express Delivery Market Strategic Shifts & Innovations
Autonomous vehicle deployment and predictive logistics algorithms are compressing delivery windows while redefining labor allocation across express networks. These shifts are reshaping competitive positioning around real-time visibility and dynamic capacity management.
Micro-fulfillment centers positioned within urban cores are decentralizing inventory placement for express carriers. Retailers and grocery chains are deploying automated storage and retrieval systems in sub-10,000-square-foot facilities to enable sub-two-hour delivery promises. This topology is decentralizing the traditional hub-and-spoke model toward distributed node architectures that minimize final-mile transit distance.
The EU Green Deal's F-Gas Regulation is accelerating refrigerant transition in temperature-controlled transport across European express operations. Carriers must retrofit or replace diesel-powered refrigerated units to comply with phased hydrofluorocarbon restrictions. Pharmaceutical and fresh food verticals face the steepest compliance curves, with cold-chain specialists pre-ordering electric refrigeration systems to secure limited manufacturing slots.
Subscription-based delivery commitments are displacing transactional parcel economics among high-volume e-commerce shippers. Merchants are consolidating carrier relationships around annual volume guarantees in exchange for rate stability and capacity allocation priority. This pattern is most visible in China's domestic market, where platform retailers lock multi-year express contracts to secure peak-season throughput during Singles' Day and Lunar New Year surges.
Express Delivery Market Segmentation
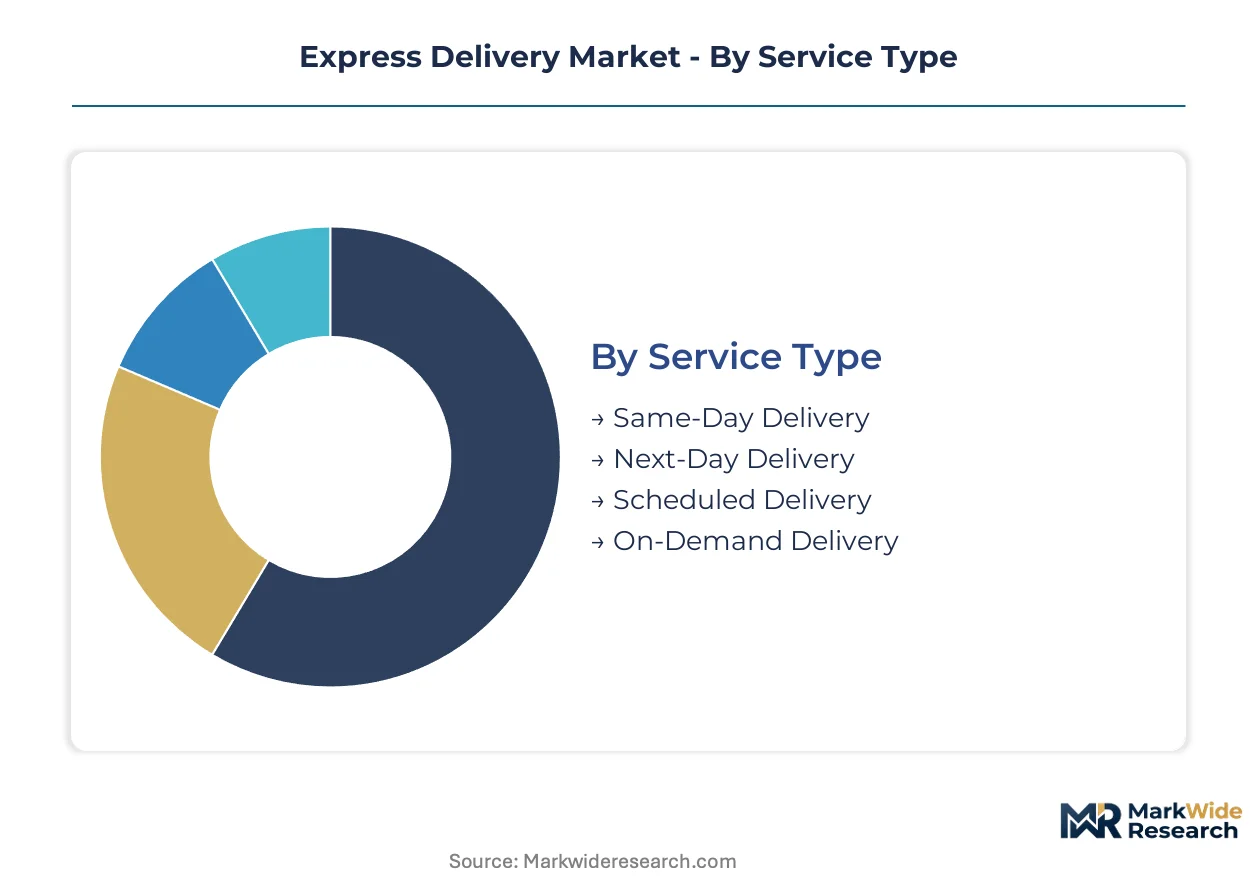
Express delivery segmentation reveals how service velocity requirements, regulatory certification burdens, and modal infrastructure investments partition the market into distinct operational and economic tiers. Each category carries specific compliance obligations that reshape carrier capital allocation and customer contract structures.
Service Type:
Same-day delivery requires FAA Part 135 air carrier certification for drone deployment in the US, while next-day networks face EU Green Deal emissions compliance across European ground fleets.
- Same-Day Delivery:Time-critical fulfillment within 24 hours demands dense urban micro-fulfillment nodes and dynamic route optimization. Demand concentrates in Shanghai, Beijing, and Shenzhen where tier-one city density enables unit economics that remain unachievable in comparably sized Western metropolitan areas, constrained by last-mile labor availability and real estate costs.
- Next-Day Delivery:The volume foundation of integrated carrier networks operates through guaranteed service-level agreements typically spanning 24-48 hours. E-commerce platforms in China lock multi-year contracts to secure peak-season throughput during Singles' Day and Lunar New Year surges, making this the dominant revenue tier across national networks.
- Scheduled Delivery:Pre-arranged time windows for B2B supply chains and subscription commerce. Industrial manufacturers use this tier for just-in-sequence production support.
- On-Demand Delivery:Immediate-response logistics for food, grocery, and urgent document verticals. Gig-economy driver pools enable scalability without fixed labor commitments.
Next-day delivery sits at the top of the volume ranking, with same-day delivery climbing the fastest.
End User:
Customer type determines certification intensity, with healthcare demanding pharmaceutical serialization compliance and temperature-controlled handling licenses that require multi-year approval timelines.
- E-commerce:Platform retailers drive the dominant share of express volume through consumer expectations for fulfillment velocity. Subscription-based commitments displace transactional economics as merchants consolidate carrier relationships around annual volume guarantees.
- Healthcare:Biopharma cold-chain logistics commands premium service tiers through regulatory compliance barriers. Temperature-controlled transport faces steep EU F-Gas Regulation retrofit curves, with carriers pre-ordering electric refrigeration systems to secure limited manufacturing slots.
- Retail:Omnichannel fulfillment networks bridging physical stores and digital orders. Micro-fulfillment centers in urban cores enable sub-two-hour delivery promises.
- Enterprises:B2B document and parts logistics with customized service-level agreements. Authorized economic operator status requirements create procurement friction for cross-border shipments.
E-commerce dominates current volume, while healthcare expands most quickly.
Delivery Mode:
Modal selection hinges on emissions compliance mandates and infrastructure availability, with China's MIIT enforcing national EV penetration targets for urban logistics vehicles.
- Ground:The foundational modal layer for last-mile distribution and intercity trucking. European electrification mandates under the EU Green Deal accelerate capital deployment into battery-electric last-mile fleets.
- Air:Integrated hub-and-spoke networks anchored by Memphis superhub operations for trans-Pacific capacity. Aviation fuel cost volatility represents the largest variable cost input, with price spikes immediately compressing margin structures.
- Drone:Autonomous aerial deployment in suburban corridors requires FAA Part 135 pathways and parallel European regulatory frameworks. Pilot programs establish foundations for scalable last-mile automation.
- Maritime:Coastal and inter-island express corridors where air connectivity remains limited. Island nations and archipelago geographies depend on this modal tier.
Ground transport anchors volume, with drone delivery gaining share fastest.
Package Type:
Physical characteristics determine sortation automation requirements and temperature-control certification, with pharmaceutical and fresh food verticals facing the steepest compliance investment curves.
- Parcels:The standard unit of e-commerce fulfillment moving through automated sortation hubs. Hub modernization requires nine-figure capital commitments with payback periods stretching across multiple economic cycles.
- Pallets:B2B freight units requiring specialized handling equipment and dock infrastructure. Manufacturing supply chains and wholesale distribution depend on this format.
- Document:Lightweight correspondence and contractual materials with distinct customs documentation requirements. Financial and legal sectors sustain demand despite digital displacement.
- Temperature-Controlled:Refrigerated units for pharmaceutical serialization and perishable food logistics. EU F-Gas Regulation accelerates refrigerant transition, with cold-chain specialists retrofitting diesel-powered units to comply with phased hydrofluorocarbon restrictions.
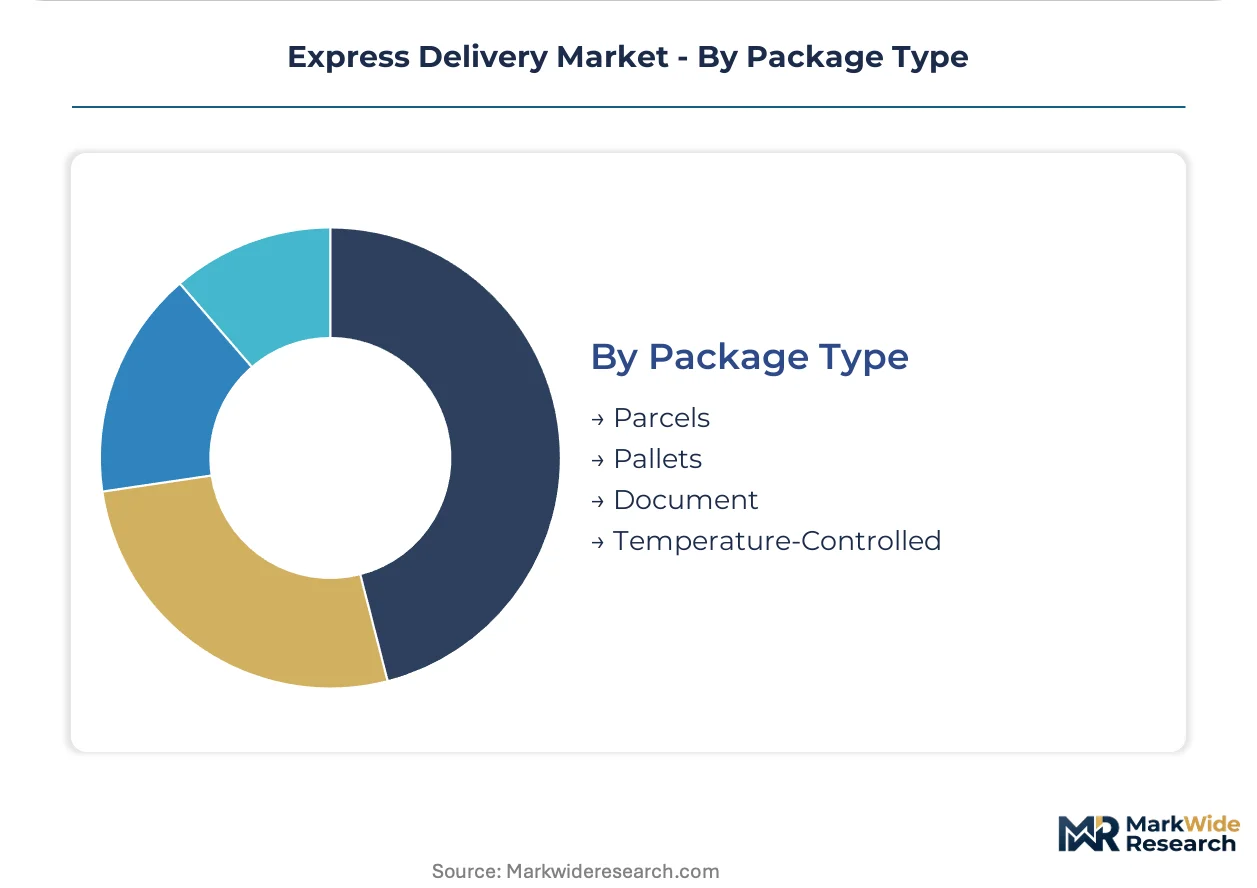
Parcels lead volume, with temperature-controlled logistics showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workforce density in urban logistics corridors anchors competitive positioning across major express delivery markets. Sortation automation specialists and last-mile driver pools concentrate differentially by geography, shaping where carriers can deploy premium service tiers.
United States
E-commerce fulfillment velocity and pharmaceutical cold-chain demand drive network investment. The FAA governs drone delivery pilot programs through Part 135 air carrier certification. Memphis anchors trans-Pacific air cargo capacity through superhub operations that integrate ground-air networks.
China
Domestic express volume exceeds all other national markets combined, concentrated in tier-one city density. The MIIT enforces national EV penetration targets for urban logistics vehicles under dual carbon policy frameworks. Shanghai, Beijing, and Shenzhen enable same-day delivery economics unachievable in comparably sized Western metropolitan areas.
Germany
Cross-border B2B pharmaceutical certification and customs-bonded infrastructure differentiate service offerings. The EU Green Deal's F-Gas Regulation and emissions trading scheme compel fleet decarbonization across European operations. The Rhine-Ruhr corridor hosts automated sortation hub modernization requiring nine-figure capital commitments.
India
Fragmented last-mile infrastructure and rising digital commerce adoption create whitespace for express network buildouts. The PLI scheme and DGFT frameworks shape logistics investment incentives. Mumbai and Delhi-NCR concentrate demand for tier-one express services while tier-two cities remain underpenetrated.
Japan
Precision manufacturing supply chains and aging demographics reshape last-mile labor allocation. METI standards and PMDA pharmaceutical handling licenses require multi-year compliance investments. The Kanto region around Tokyo maintains dense urban logistics networks enabling scheduled delivery windows for industrial customers.
Express Delivery Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across integrated air-ground and regional ground-only tiers. The vendor base organizes around three strategic archetypes: global integrators with owned air fleets, regional specialists with customs-bonded infrastructure, and platform-captive carriers serving single e-commerce ecosystems. Dominant competitive moves include hub automation capex cycles and multi-year volume commitment contracts with mega-retailers.
Among global integrators, FedEx and United Parcel Service exemplify the air-ground network archetype, while DHL Group occupies a position within European cross-border B2B certification tiers. SF Holding and ZTO Express represent the platform-captive model concentrated in China's domestic volume concentration. These anchors illustrate how carrier strategy diverges between premium certification-driven positioning and scale-driven national network density.
| Leading Market Players |
|---|
| FedEx |
| United Parcel Service |
| DHL Group |
| SF Holding |
| Aramex |
| Delhivery |
| Japan Post Holdings |
| Poste Italiane |
| ZTO Express |
| Others |
Cost & Logistics Intelligence
Sovereign-backed postal operators and family-owned regional carriers anchor supply-side discipline across express delivery networks, translating operational density into contract pricing power that resists commoditization pressure from platform-captive competitors.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes subscription-based annual volume commitments from transactional spot pricing in express delivery. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity and velocity guarantees. Cost compression in economy tiers is intensifying because gig-economy driver pools expand supply without fixed labor overhead. E-commerce platform retailers exhibit highest price sensitivity, while healthcare biopharma shippers accept premium tiers for temperature-controlled compliance.
Supply Chain Analysis
China's MIIT domestic-content mandates for electric vehicle components are reshaping sourcing patterns for last-mile fleet procurement across Asian express operations. Automated sortation equipment concentrates in Germany and Japan, while lithium-ion battery cells draw from South Korea and China. Aviation fuel sourcing rests on Middle Eastern and North American refinery output. Single-source vulnerability in semiconductor-dependent route-optimization hardware threatens network resilience. Distribution runs through hub-and-spoke architectures anchored by Memphis, Leipzig, and Shanghai superhub facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Express delivery functions as a regulatory compounder where EU Green Deal emissions mandates and China's dual carbon frameworks continuously expand compliance-driven service demand.
For Market Incumbents: Extend pharmaceutical cold-chain certification portfolios to capture biopharma serialization convergence opportunities. Consolidate customs-bonded infrastructure in European cross-border corridors to defend against platform-captive carriers leveraging volume scale. Vertical integration into electric last-mile fleet manufacturing secures equipment allocation priority during MIIT-mandated procurement surges.
For New Entrants and Emerging Players: The price-point gap between premium healthcare logistics and economy e-commerce fulfillment offers whitespace for mid-tier positioning. India's tier-two cities present the most penetrable geography, with fragmented last-mile infrastructure and rising digital commerce adoption. Partner with regional micro-fulfillment center operators to bypass nine-figure hub automation capex requirements.
For Investors and Strategic Acquirers: E-commerce platform operators are the most active acquirer in this space, consolidating carrier relationships to secure peak-season capacity. Long-term viability centers on regulatory compliance capabilities rather than pure network scale. Target cold-chain specialists with pharmaceutical handling licenses. Monitor FAA Part 135 certification velocity as inflection indicator for drone delivery scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Transition | MIIT EV penetration targets compel capital deployment into battery-electric last-mile vehicles across Chinese urban logistics corridors. |
| Drone Air Carrier Certification | FAA Part 135 pathways establish regulatory foundations for autonomous aerial delivery in suburban US markets. |
| Micro-Fulfillment Network Buildout | Automated storage and retrieval systems in sub-10,000-square-foot urban facilities enable sub-two-hour delivery promises. |
| Pharmaceutical Serialization Integration | Track-and-trace compliance bundled with express visibility systems creates defensible margin pools in healthcare verticals. |
| Cross-Border Customs Infrastructure | Authorized economic operator status investments secure multi-year B2B contracts with industrial manufacturers. |
Research Approach
Bottom-up e-commerce fulfillment modeling reconciled against top-down carrier capacity tracking forms the analytical core of this study. Primary interviews with network operations directors, fleet procurement managers, customs brokerage leads, and pharmaceutical logistics specialists combine with secondary validation from FAA certification databases, EU emissions trading scheme disclosures, MIIT policy filings, and carrier SEC 10-K segment reporting. Top-down trade flow analysis and bottom-up sortation hub capacity assessments triangulate volume estimates.
Historical trendline analysis of express volume growth against e-commerce penetration rates and regulatory compliance investment cycles informs projection frameworks. Segmentation dimensions modeled include service velocity tiers, end-use verticals, modal infrastructure types, and package handling requirements. CAGRs derive from regression analysis across these dimensions, incorporating aviation fuel cost volatility patterns and electrification capex intensity as industry-specific forecast inputs throughout the projection horizon.
Caveats apply where aviation fuel price spikes, sortation equipment procurement bottlenecks, or last-mile labor availability constraints could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement timelines and technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Japan Dangerous Goods Logistics Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
Ukraine Freight and Logistics Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
Mexico Road Freight Transport Market
Logistics and Shipping
Asia-Pacific Courier Market
Logistics and Shipping
Chile Air Freight Transport Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
Hungary Third Party Logistics (3PL) Market
Logistics and Shipping
Liquid Chemical Tanker Shipping Market
Logistics and Shipping
US Retail Logistics Market
Logistics and Shipping
Latin America Container Terminal Operations Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Latin America Contract Logistics Market