
 Germany Cold Chain Logistics Market | 2026-2036
Germany Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Cold Chain Logistics Market Foresight
Market Dynamics
Germany is narrowing its cold storage capacity gap through automated high-bay warehouse expansions near Frankfurt and Hamburg. DHL Group leverages its European pharma logistics hub in Leipzig to sustain temperature-validated air freight dominance. Kuehne + Nagel International AG anchors pharmaceutical distribution through certified GDP facilities across Bavaria and Baden-Württemberg. Lineage Logistics LLC competes with automated frozen warehousing solutions positioned near major German food processing zones.
Segmentation Analysis
Cold chain logistics encompasses the temperature-controlled movement and storage of perishable goods within defined thermal parameters, typically spanning minus 25 degrees Celsius to plus 25 degrees Celsius across refrigerated trucks, cold storage facilities, and active packaging systems. The primary industrial purpose centers on preserving product efficacy, safety, and shelf stability for pharmaceuticals, fresh food, and biotechnology materials throughout distributed supply networks. Warehousing services command structural priority due to Germany's scarcity of automated frozen and deep-frozen pallet positions near consumption centers. IoT Sensors within the Technology segment represent the fastest-advancing category as real-time temperature monitoring becomes mandatory under pharmaceutical distribution rules.
Regulatory Environment
Germany's cold chain sector operates under the EU Good Distribution Practice enforced by the Federal Institute for Drugs and Medical Devices, supplemented by HACCP mandates from the Federal Office of Consumer Protection and Food Safety that govern fresh food logistics. REACH and the F-Gas Regulation constrain refrigerant choices for transport refrigeration units and stationary cold storage installations, elevating compliance costs for fleet operators. Stakeholders must monitor how Germany's transposition of the EU Green Deal industrial emissions standards reshapes energy sourcing decisions for refrigerated warehouses.
Market Dynamics
Germany's cold chain sector faces acute pressure from the F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants, forcing warehouse operators and transport fleets to accelerate capital-intensive retrofits of cooling infrastructure before statutory deadlines tighten.
Growth Catalysts
- EU Good Distribution Practice:Pharmaceutical distributors must deploy validated temperature monitoring across Bavaria and North Rhine-Westphalia, expanding certified storage capacity for biologics.
- Automated high-bay warehousing:Robotics integration near Frankfurt and Hamburg compresses labor costs while doubling pallet density in frozen storage.
- Rhine-Ruhr food processing clusters:Dense meat and dairy operations generate sustained demand for multi-temperature facilities with rapid cross-docking capability.
Market Restraints
- Natural refrigerant conversion costs:Ammonia and CO2 systems require complete infrastructure overhaul, straining mid-sized operators with legacy Freon installations.
- Leipzig air freight concentration:Temperature-validated pharma exports depend heavily on single-hub routing, creating vulnerability to capacity constraints or weather disruptions.
- Grid electricity price volatility:Refrigerated warehouses face margin compression from industrial power tariffs that fluctuate with renewable generation intermittency.
Strategic Opportunities
- Baden-Württemberg vaccine manufacturing:mRNA production facilities under construction will require adjacent cold storage and specialized last-mile distribution networks.
- Battery-electric reefers:Integration of solid-state battery packs with telematics platforms enables zero-emission urban delivery zones in Berlin and Munich.
- EU Green Deal industrial standards:Renewable energy mandates for refrigerated warehouses unlock subsidies for solar-plus-storage installations at distribution centers.
Industry Challenges
- Refrigeration technician scarcity:Germany's dual vocational system produces insufficient ammonia-certified specialists to service converted industrial systems.
- GDP validation timelines:Pharmaceutical clients demand 12-18 month qualification periods for new temperature-controlled lanes, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Cold Chain Logistics Market |
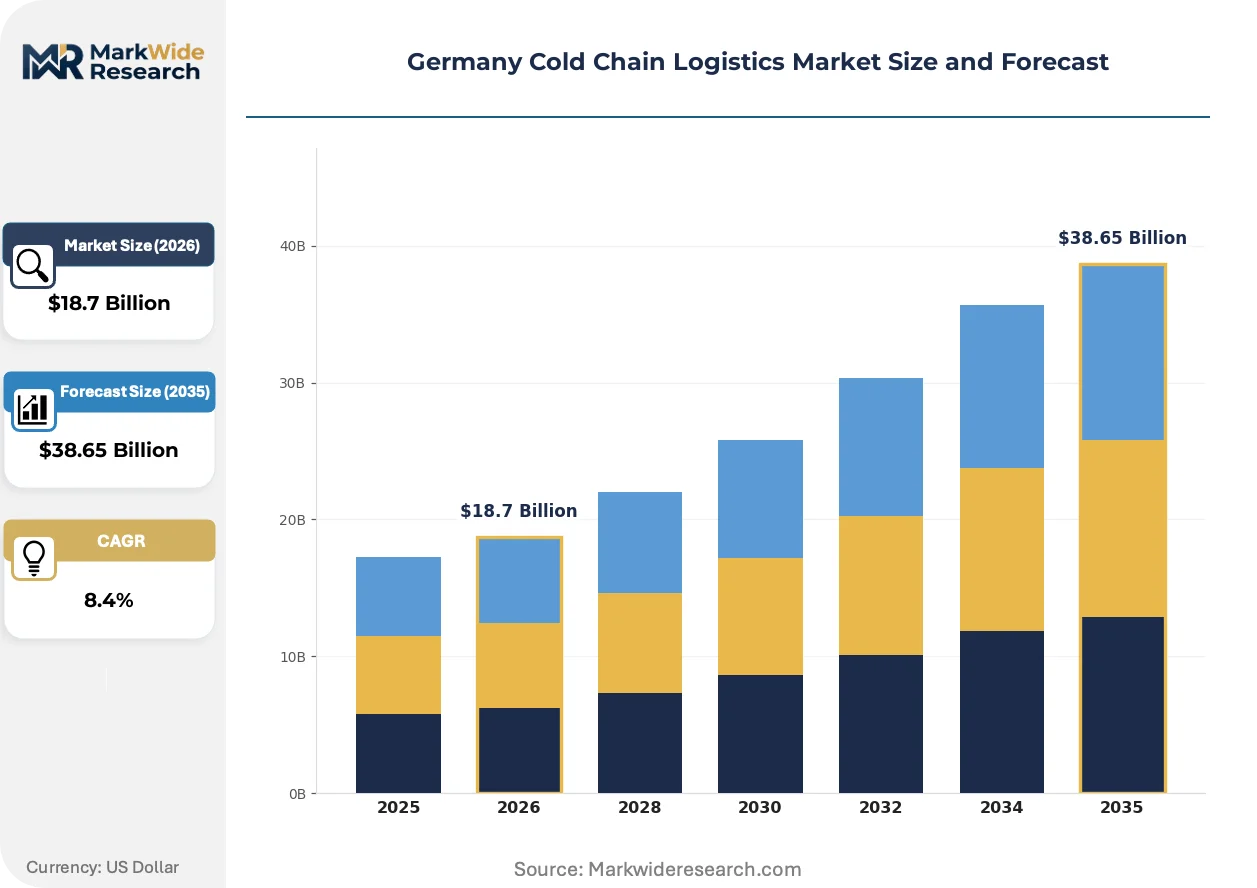
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Monitoring Technology: Refrigerated Trucks, Cold Storage Facilities, IoT Sensors, Temperature Control Systems End User: Pharmaceuticals, Food and Beverage, Biotechnology, Cosmetics Solution: Track and Trace, Management Software, Quality Assurance, Last-Mile Delivery |
| Companies Covered | Lineage Logistics LLC, Pfenning Logistics, Kuehne + Nagel International AG, Scan Global Logistics, Dachser SE, DHL Group, NewCold Advanced Logistics, Frigolanda Cold Logistics, A.P. Moller-Maersk A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Cold Chain Logistics Market Shifts & Advancements
Digital traceability and sustainable cooling chemistries are reconfiguring how German logistics providers design temperature-controlled infrastructure, with capital allocation shifting toward predictive systems and away from passive compliance.
Phase-change materials embedded in thermal packaging are migrating from air freight pharma shipments into overland food distribution. Organic PCM formulations with precise melting points between minus 20 and plus 8 degrees Celsius now protect fresh produce during multi-day truck journeys. Bavarian dairy distributors are adopting these passive systems to reduce mechanical refrigeration runtime and extend delivery radius without compromising HACCP protocols.
Germany's transposition of the EU F-Gas Regulation imposes escalating quotas on hydrofluorocarbon imports, compelling fleet operators to retrofit transport refrigeration units with CO2 or propane alternatives. The Federal Institute for Drugs and Medical Devices now requires documented refrigerant migration plans as part of GDP facility audits. Pharmaceutical-certified warehouses in Hamburg and Frankfurt are prioritizing ammonia-based centralized cooling with brine secondary loops to eliminate synthetic refrigerants entirely.
Consolidation of buying power among Germany's three largest supermarket chains is compressing contract durations with cold storage providers from five-year frameworks to 24-month agreements with performance penalties. Regional meat processors in Lower Saxony report accelerated switching between logistics partners based on real-time temperature scorecard visibility. This procurement volatility rewards operators with IoT-enabled transparency while marginalizing facilities dependent on manual documentation.
Germany Cold Chain Logistics Market Segmentation
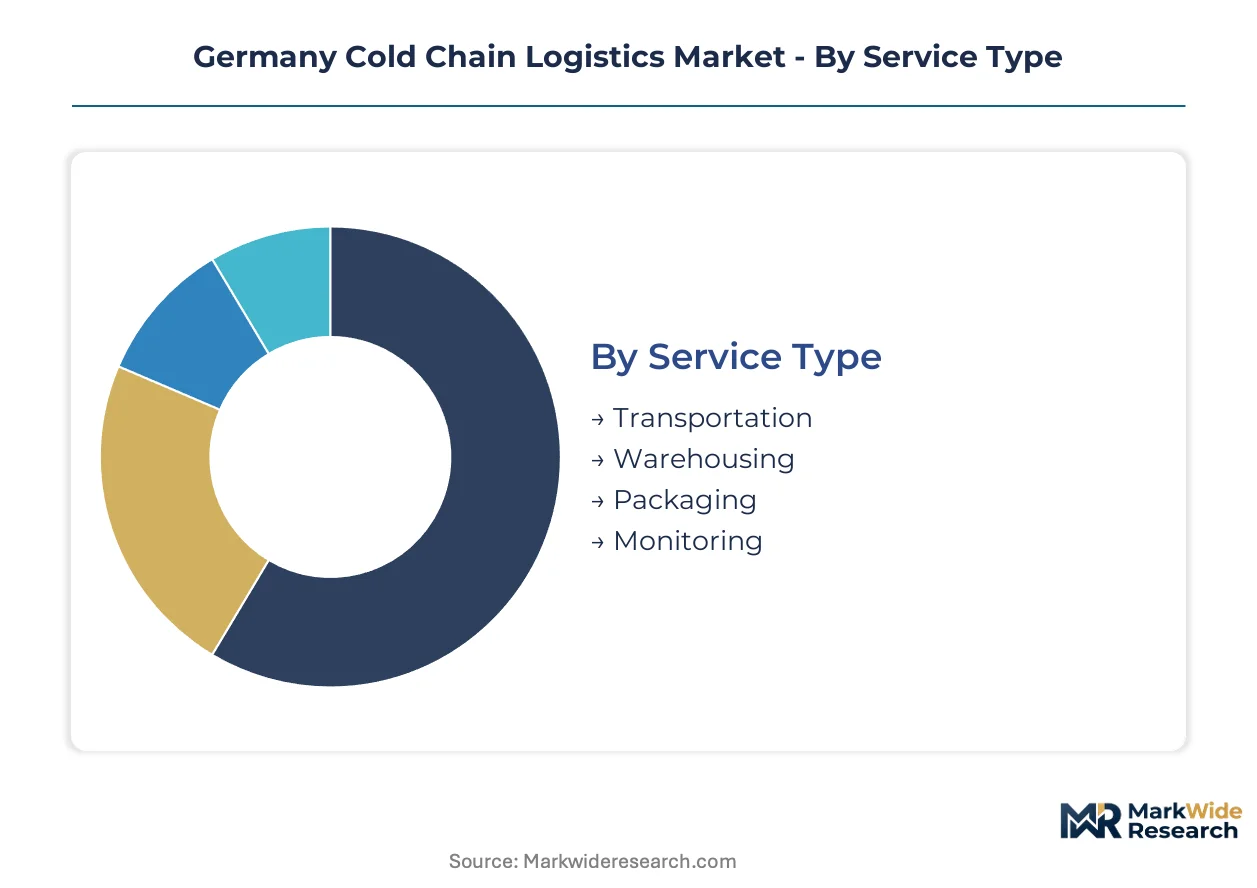
Germany's cold chain logistics market fragments across four operational dimensions that determine capital allocation and margin structure. Service type and technology choices dominate facility investment decisions, while end-user concentration in Bavaria and North Rhine-Westphalia shapes regional capacity deployment.
Service Type:
Cost tier differentiation separates asset-heavy warehousing from variable-cost transportation and value-added monitoring services.
- Transportation:Refrigerated trucking networks span minus 25 to plus 25 degrees Celsius across multi-temperature trailers. Pharmaceutical distributors in the Rhine-Ruhr corridor demand validated thermal lanes with real-time telemetry for biologics.
- Warehousing:Automated high-bay facilities near Frankfurt and Hamburg compress labor costs while doubling frozen pallet density. Scarcity of automated positions near consumption centers commands structural priority in capital planning.
- Packaging:Phase-change materials and active thermal containers protect temperature-sensitive payloads during extended transit windows.
- Monitoring:GDP-mandated temperature documentation drives adoption of cloud-based validation platforms across certified storage networks.
Warehousing holds installed capacity. Monitoring is rotating up the share rankings.
Technology:
Application maturity varies from proven mechanical refrigeration to emerging IoT-enabled predictive systems.
- IoT Sensors:Real-time temperature and humidity tracking with cellular or LoRaWAN connectivity enables immediate deviation alerts. Federal Institute for Drugs and Medical Devices audits now mandate continuous digital records for pharmaceutical GDP compliance.
- Cold Storage Facilities:Ammonia and CO2-based centralized cooling systems eliminate synthetic refrigerants under F-Gas Regulation timelines. Hamburg and Frankfurt operators prioritize brine secondary loops for pharmaceutical certification.
- Refrigerated Trucks:Fleet operators retrofit transport refrigeration units with natural refrigerants ahead of statutory phasedown deadlines.
- Temperature Control Systems:Precision cooling units maintain tight thermal bands for mRNA vaccine storage requirements.
Cold Storage Facilities hold installed capacity. IoT Sensors are climbing the fastest.
End User:
Customer type concentration dictates facility location and certification requirements across German industrial clusters.
- Pharmaceuticals:Bavaria and North Rhine-Westphalia biologics manufacturers require minus 70 to plus 25 degrees Celsius validated storage with 12-18 month qualification timelines.
- Food and Beverage:Rhine-Ruhr meat and dairy processors generate sustained demand for multi-temperature cross-docking capabilities.
- Biotechnology:Baden-Württemberg mRNA production facilities under construction will require adjacent cold storage and specialized distribution networks.
- Cosmetics:Temperature-sensitive active ingredients demand controlled storage below 25 degrees Celsius through summer distribution cycles.
Pharmaceuticals holds installed capacity. Biotechnology is gaining share fastest.
Solution:
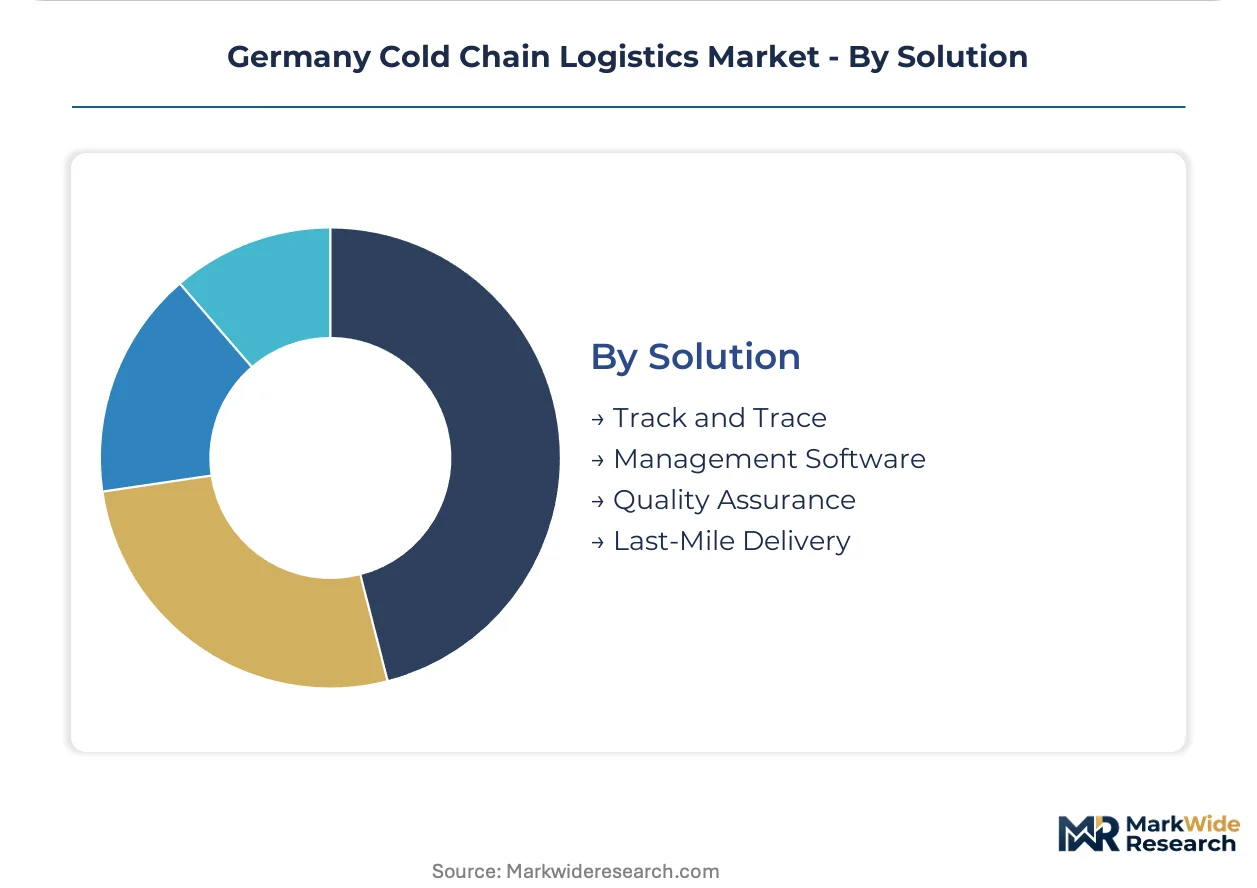
Margin structure separates software-enabled visibility platforms from physical last-mile execution.
- Track and Trace:Blockchain-anchored temperature records create immutable audit trails for EU Good Distribution Practice compliance.
- Management Software:Warehouse execution systems optimize slotting algorithms for multi-temperature zones.
- Quality Assurance:GDP validation protocols and HACCP documentation workflows reduce regulatory risk exposure.
- Last-Mile Delivery:Battery-electric refrigerated vans enable zero-emission urban zones in Berlin and Munich.
Quality Assurance holds installed capacity. Last-Mile Delivery is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's cold storage capacity concentrates along the Rhine-Ruhr corridor and southern industrial belt, where pharmaceutical and food processing clusters generate sustained demand for multi-temperature facilities. The Federal Institute for Drugs and Medical Devices enforces EU Good Distribution Practice standards that shape facility investment patterns across federal states. Regional fragmentation reflects distinct industrial specializations rather than uniform national deployment.
Bavaria
Biologics manufacturers in Munich and Nuremberg require minus 70 to plus 25 degrees Celsius validated storage networks. The Federal Institute for Drugs and Medical Devices mandates 12-18 month qualification timelines for new temperature-controlled lanes. mRNA production facilities under construction near Munich will drive adjacent cold storage and specialized last-mile distribution investments through 2035.
North Rhine-Westphalia
Pharmaceutical distributors in Cologne and Düsseldorf deploy validated thermal lanes with real-time telemetry for vaccine distribution. REACH and the F-Gas Regulation constrain refrigerant choices for transport refrigeration units across the region. Dense meat and dairy processing operations around Dortmund generate sustained demand for multi-temperature cross-docking facilities with rapid throughput capability.
Baden-Württemberg
Vaccine manufacturing investments near Stuttgart and Mannheim require adjacent cold storage infrastructure for mRNA production inputs. The Federal Office for Economic Affairs and Export Control coordinates renewable energy subsidies for refrigerated warehouse operators under EU Green Deal industrial standards. Specialized last-mile distribution networks are emerging around the Stuttgart industrial corridor to serve temperature-sensitive biotechnology materials.
Hesse
Automated high-bay warehouse expansions near Frankfurt compress labor costs while doubling frozen pallet density. Grid electricity price volatility from renewable generation intermittency strains refrigerated warehouse margins across the Rhine-Main metropolitan region. Frankfurt Airport's cargo infrastructure anchors temperature-validated air freight connections for pharmaceutical exports to European and intercontinental markets.
Hamburg
Port-centric cold storage operators prioritize ammonia-based centralized cooling with brine secondary loops to eliminate synthetic refrigerants. The Federal Maritime and Hydrographic Agency coordinates with port authorities on emissions standards for refrigerated container handling. Food processing and seafood import clusters along the Elbe River drive demand for deep-frozen warehousing with automated retrieval systems.
Germany Cold Chain Logistics Market Competitive Landscape
Integrated logistics conglomerates and specialized cold storage operators split the market along asset intensity and certification depth lines. The vendor base clusters around three strategic archetypes: global freight forwarders with pharmaceutical GDP certification, dedicated temperature-controlled warehouse specialists, and diversified supply chain platforms with captive air freight capacity. Consolidation pressure is accelerating as supermarket procurement teams compress contract durations and demand real-time temperature scorecard visibility.
Within the global freight forwarder tier, Kuehne + Nagel International AG and DHL Group exemplify archetypes built on pharmaceutical certification density and air freight hub control. Lineage Logistics LLC occupies a position among dedicated cold storage specialists with automated frozen warehousing solutions. These three entities represent distinct competitive vectors: certification breadth, network scale, and facility automation intensity respectively.
| Leading Market Players |
|---|
| Lineage Logistics LLC |
| Pfenning Logistics |
| Kuehne + Nagel International AG |
| Scan Global Logistics |
| Dachser SE |
| DHL Group |
| NewCold Advanced Logistics |
| Frigolanda Cold Logistics |
| A.P. Moller-Maersk A/S |
| Others |
Supply & Pricing Matrix
The Rhine-Ruhr pharmaceutical corridor compresses logistics costs through dense clustering of GDP-certified facilities, yet this same concentration amplifies price differentiation between validated biologics storage and standard food-grade warehousing. EU Good Distribution Practice mandates create tiered compliance costs that cascade through contract structures, with supermarket procurement teams exploiting transparency differentials to squeeze margins on non-certified capacity.
Pricing Analysis
EU Good Distribution Practice dictates the pricing tier structure across German cold storage markets, separating pharmaceutical-validated facilities commanding premium rates from commodity food-grade positions facing compression. Three-tier pricing stratifies across GDP-certified, HACCP-compliant, and basic refrigerated tiers, with certification grade and geographic delivery cost as primary differentiation drivers. Cost compression in standard food warehousing intensifies because supermarket chains consolidated buying power and shortened contract durations. Mid-sized meat processors exhibit highest price sensitivity, while Bavarian biologics manufacturers accept premium positioning to secure qualification-validated capacity.
Supply Chain Analysis
Single-source vulnerability to ammonia-certified technician scarcity dominates German cold chain risk profiles, constraining fleet retrofit timelines and warehouse conversion schedules. Geographic supply concentration centers on domestic refrigeration equipment manufacturing, with critical compressor and control system components drawing from Italy, Denmark, and China. Raw material dependencies include specialized steel alloys for cryogenic vessels, synthetic refrigerants facing F-Gas phasedown quotas, and solid-state battery cells for electric reefer prototypes. Distribution runs through hub-and-spoke configurations anchored at Leipzig air freight and Frankfurt automated high-bay nodes, with regional cross-docking satellites serving Rhine-Ruhr processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's cold chain logistics sector builds defensive moats through regulatory entrenchment, where GDP certification timelines and F-Gas compliance requirements create switching costs that protect incumbent positions against price-based disruption.
For Market Incumbents: Harden certification density in Bavaria and North Rhine-Westphalia through accelerated ammonia conversion investments ahead of technician scarcity worsening. Deepen backward integration into IoT sensor deployment and cloud-based validation platforms to capture monitoring revenue streams that emerging software entrants threaten. Prioritize capacity addition in Baden-Württemberg adjacent to mRNA manufacturing facilities under construction. For New Entrants and Emerging Players: Eastern German states exhibit underpenetration in automated frozen warehousing relative to western consumption centers, offering white-space entry with lower land and labor costs. Battery-electric last-mile delivery in Berlin and Munich municipal zero-emission zones represents the most penetrable service tier, as incumbents delay fleet electrification due to capital allocation constraints. Pursue partnership-based go-to-market angles with regional food processors seeking alternatives to consolidated supermarket distribution channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive cold storage assets that lack standalone GDP certification or automated infrastructure. Long-term viability favors operators with demonstrated ammonia system expertise and established pharmaceutical client relationships that extend contract durations beyond supermarket volatility. Watch Baden-Württemberg mRNA facility commissioning schedules as inflection indicators for specialized distribution network demand.| Strategic Initiative | Industry Significance |
|---|---|
| Automated High-Bay Warehouse Expansion | Doubled pallet density near Frankfurt compresses labor costs against rising wage pressure. |
| Ammonia-Based Cooling Conversion | Eliminates synthetic refrigerants ahead of F-Gas Regulation phasedown deadlines. |
| IoT Sensor Platform Integration | Federal Institute for Drugs and Medical Devices mandates continuous digital validation records. |
| Battery-Electric Reefer Fleet Deployment | Enables zero-emission urban delivery zones in Berlin and Munich regulatory frameworks. |
| Adjacent Cold Storage Construction | Baden-Württemberg mRNA manufacturing requires proximate minus 70 degrees Celsius capacity. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical logistics directors, cold storage facility managers, fleet procurement officers, and Federal Institute for Drugs and Medical Devices compliance auditors. Secondary validation drew from Bundesnetzagentur energy tariff filings, Federal Office for Consumer Protection and Food Safety HACCP enforcement data, EU F-Gas Regulation quota tracking, and customs records of refrigeration equipment imports. Bottom-up facility capacity assessments and top-down pharmaceutical distribution value chain analysis were triangulated against operator-reported utilization rates.
Calibration against historical capacity additions and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, technology category, end-user industry, and solution architecture, with regional federal state clusters as an additional geographic dimension. CAGRs were derived from elasticity-adjusted demand curves incorporating biologics pipeline expansion and food processing output trends. Industry-specific forecast inputs encompassed ammonia technician graduation rates from Germany's dual vocational system and supermarket procurement contract duration patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-electric vehicle specialists or software-defined logistics platforms would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Indonesia Road Freight Transport Market
Transportation & Logistics
Europe Long Haul Transport Market
Transportation & Logistics
UAE Cold Chain Logistics Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
Europe Customs Brokerage Market
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
Multimodal Transport Market
Transportation & Logistics
Latin America Inland Waterway Transport Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
Saudi Arabia Land-Based Fuel Transportation Market
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
India Direct-To-Consumer (D2C) Logistics Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
Slovakia Road Freight Transport Market
Transportation & Logistics
Traction Equipment Market
Transportation & Logistics
Latin America Cross Border Road Freight Market