
 Railcar Unloader Market | 2026-2036
Railcar Unloader Market Size, Share, and Industry Trends Forecast 2026-2036
Railcar Unloader Market Intelligence
The end-use application mix for railcar unloaders is shifting from a concentration in mining logistics toward greater adoption in cement processing and grain transfer. Nordstrong Equipment Ltd leverages its legacy in heavy-duty systems for bulk material handling applications. Scherzer GmbH specializes in customized pneumatic unloader solutions for European chemical plants. Kinergy Corporation competes on the performance of its vibratory technology for difficult-to-handle materials.
A railcar unloader is mechanical or pneumatic equipment designed to efficiently discharge bulk solids from freight railcars. These systems are specified by their discharge capacity, often measured in tons per hour, and the type of material they can handle. Rotary unloaders, which invert the entire car, dominate high-throughput applications like coal terminals. Pneumatic unloader systems are gaining share in sectors like chemical plants where dust containment and material purity are critical.
Equipment design is shaped by safety regulations, including standards from the US Occupational Safety and Health Administration (OSHA) concerning machine guarding and dust explosion hazards. In the European Union, manufacturers must adhere to the Machinery Directive and relevant CE marking requirements. These regulations mandate specific safety features and performance documentation. Future procurement decisions will balance the need for high throughput with demands for improved automation and workplace safety.
Market Dynamics
The railcar unloader market is defined by the need to balance high-throughput capacity with increasingly stringent safety and environmental regulations. This dynamic shapes equipment design, favoring automated systems that minimize manual intervention and enclosed unloaders that control fugitive dust emissions.
Growth Catalysts
- Agricultural Expansion:Rising global trade in bulk grains and oilseeds stimulates investment in high-capacity unloading systems at port terminals and inland agricultural cooperatives, particularly in the Americas and Australia.
- Automation Integration:The adoption of PLC-based controls and sensor networks enhances operational speed, reduces labor requirements, and improves safety, making automated systems a priority for new capital projects.
- Regulatory Compliance:Stricter air quality standards and workplace safety rules, such as those from OSHA concerning dust hazards, compel operators in the cement and chemical industries to upgrade to contained pneumatic or enclosed mechanical systems.
Market Restraints
- High Capital Cost:The significant upfront investment required for high-capacity systems like rotary car dumpers presents a substantial barrier to entry for smaller operators or facilities with lower volume requirements.
- Material Handling Limitations:Certain unloader technologies, particularly vibratory systems, exhibit reduced performance and potential for clogging when handling cohesive, sticky, or high-moisture bulk materials, limiting their application.
- Alternative Logistics:Competition from other bulk transport modes, including slurry pipelines for minerals and direct-to-silo trucking for agricultural products, can displace the need for rail-based unloading in specific logistical contexts.
Strategic Opportunities
- Emerging Market Infrastructure:Investment in new rail corridors and port facilities across resource-rich nations in Africa and Southeast Asia creates greenfield opportunities for modern unloader installations for minerals and agricultural commodities.
- System Retrofitting:Upgrading existing, manually operated or aging unloader installations with modern automation packages and safety features offers a significant aftermarket and service-related revenue stream for equipment providers.
- Modular and Mobile Designs:Developing mobile or containerized unloading systems provides flexibility for seasonal industries, short-term contracts, or operations at multiple remote sites, addressing a need for non-permanent infrastructure.
Industry Challenges
- Legacy System Integration:Integrating modern, automated unloader controls with disparate and often outdated plant-level SCADA or ERP systems creates significant technical hurdles and potential for operational disruption during commissioning.
- Specialized Skill Gaps:A shortage of technicians with hybrid expertise in heavy mechanical engineering, advanced automation programming, and hydraulic systems complicates the maintenance and troubleshooting of sophisticated unloader equipment.
- Divergent Global Standards:Manufacturers must engineer equipment to comply with a complex matrix of regional safety regulations, including OSHA standards in the United States and CE marking protocols in the European Union, increasing design costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railcar Unloader Market |
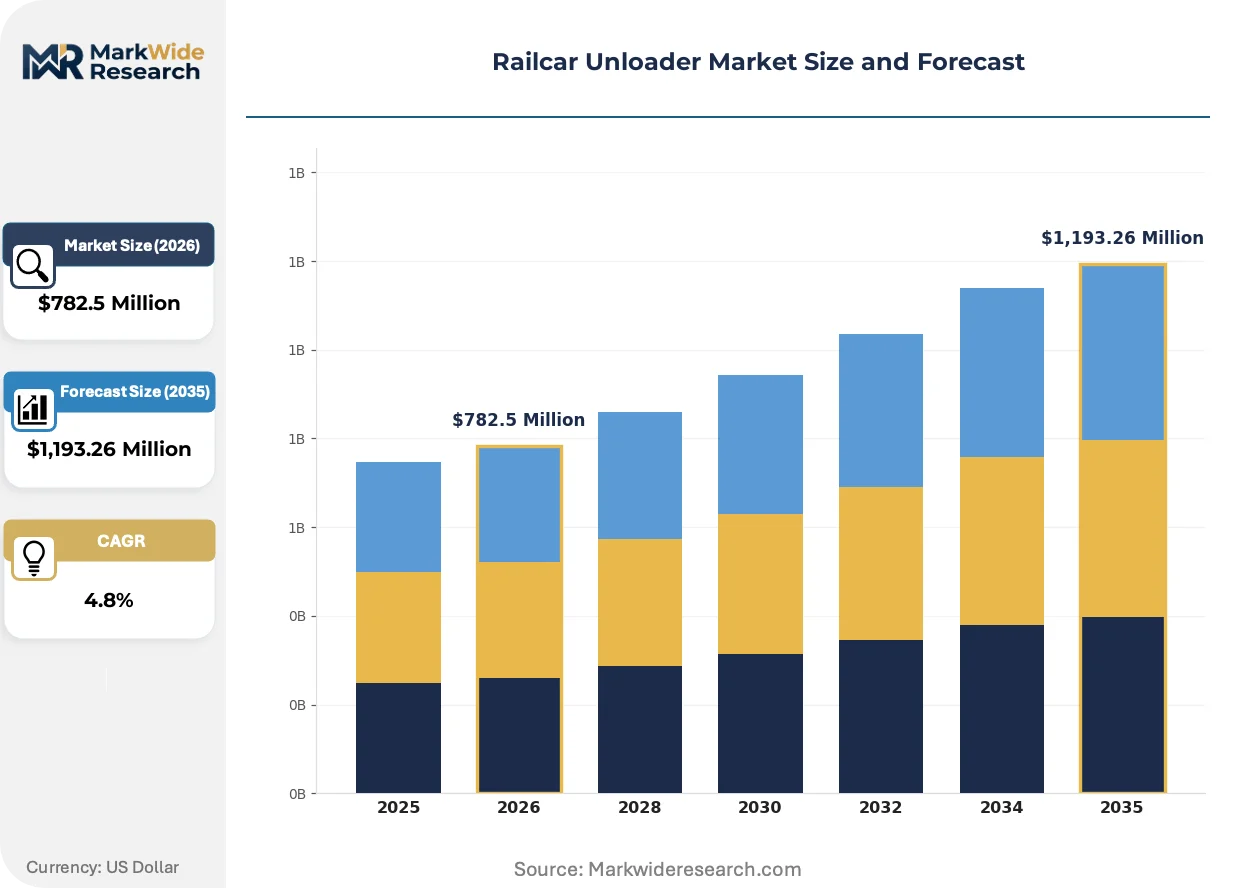
| Market Size in 2026 | $782.5 Million |
| Market Size in 2035 | $1,193.26 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Unloader, Gravitational Unloader, Pneumatic Unloader, Hydraulic Unloader Technology: Mechanical, Pneumatic Conveying, Vacuum, Gravity Discharge Application: Bulk Material Handling, Mining Logistics, Grain Transfer, Cement Processing End User Industry: Mining Operators, Agricultural Cooperatives, Construction Firms, Chemical Plants |
| Companies Covered | Nordstrong Equipment Ltd, Kinergy Corporation, McGill, Kingery Corporation, Jamieson Equipment Co, Process Control Corporation, NPK, Airmatic Inc, Scherzer GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railcar Unloader Market Strategic Shifts & Innovations
The convergence of advanced software with heavy-duty mechanical engineering is driving a shift toward intelligent, autonomous, and safer unloading operations. This evolution prioritizes data-driven decision-making and remote system management to boost efficiency and meet stringent environmental, health, and safety mandates.
Digital twin technology creates a high-fidelity virtual model of the physical unloader and its surrounding environment for simulation and analysis. Major mining corporations and port authorities are adopting this to optimize unloading sequences, train operators in a safe virtual space, and test software updates before deployment. This capability is rewriting the entire approach to asset lifecycle management, enabling predictive maintenance strategies that maximize equipment uptime and operational performance.
Regulatory frameworks like the European Union's Machinery Directive are mandating more comprehensive safety features and risk assessments in equipment design. This directly influences product development, requiring manufacturers to integrate features like light curtains, safety PLCs, and dust mitigation systems that comply with ATEX directives for explosive atmospheres. Consequently, fully enclosed unloader designs, such as pneumatic systems, are seeing increased specification in European chemical and food-grade applications where containment is paramount.
A notable shift in customer behavior involves the preference for comprehensive, turnkey unloading solutions over discrete equipment purchases. End-users now seek a single provider to supply and integrate the unloader with associated dust control, conveying, and weighing systems, transferring project risk. This demand is particularly strong in large-scale greenfield projects, such as new cement plants or export grain terminals, where system-level performance guarantees are critical.
Railcar Unloader Market Segmentation
The railcar unloader market's segmentation reflects diverse operational demands and material characteristics across industries. Understanding these segments allows providers to tailor solutions meeting specific throughput, safety standards, and investment capacities. This analysis categorizes unloaders by design, principles, applications, and end-user industries.
Product Type:
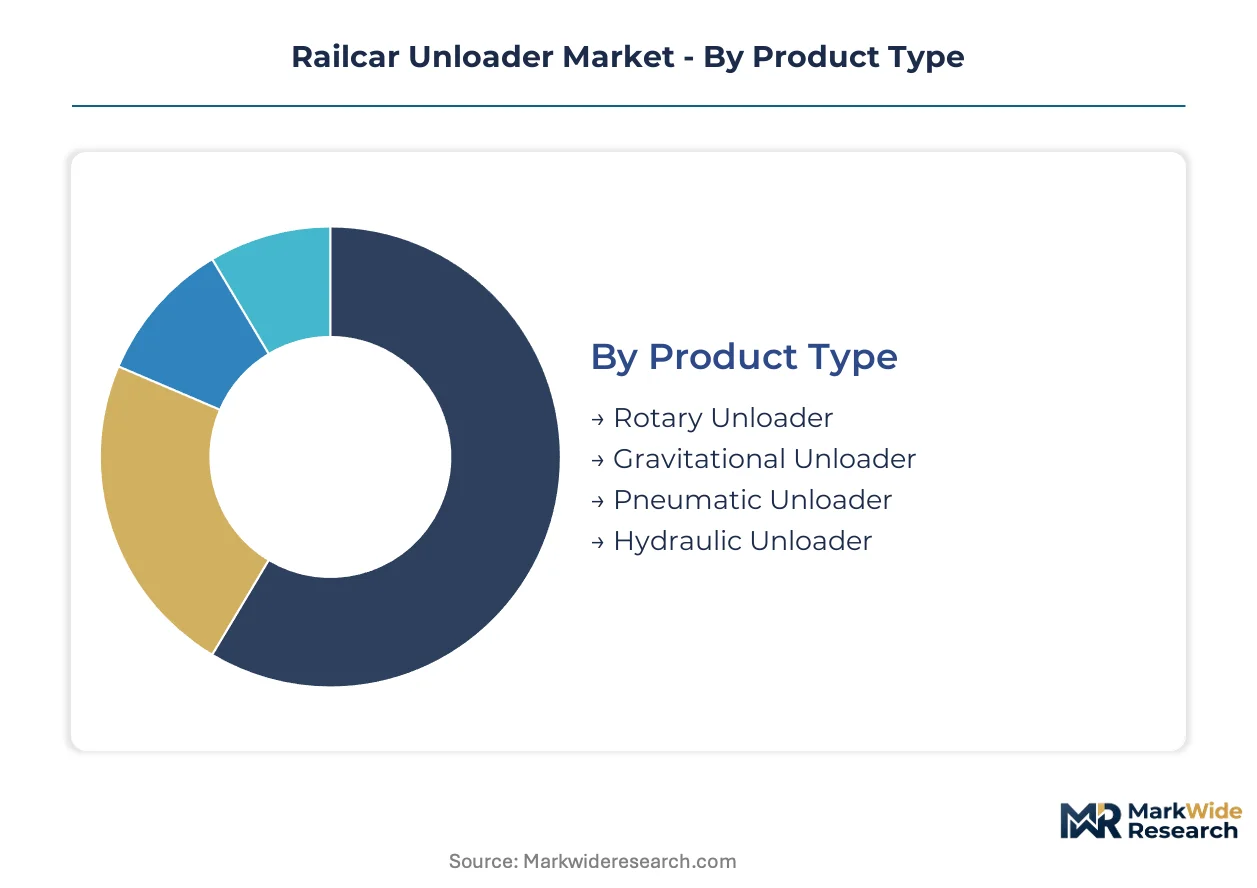
Capital expenditure for railcar unloader systems varies by product type, influencing procurement decisions. High-throughput solutions demand substantial upfront investment, while specialized systems cater to niche needs.
- Rotary Unloader:This mechanical system inverts an entire railcar for unparalleled discharge rates of bulk commodities. Demand concentrates in coal terminals and large mining operations, driven by rapid turnaround.
- Gravitational Unloader:These systems rely on gravity to discharge materials from bottom-dump railcars, often used in agricultural facilities for grain transfer.
- Pneumatic Unloader:Utilizing air pressure to convey materials, these unloaders excel in dust containment and material purity. Demand is strong in European chemical plants due to strict environmental regulations.
- Hydraulic Unloader:These unloaders employ hydraulic power for discharge, suitable for dense or sticky materials in construction aggregate sites.
Rotary Unloader technology absorbs the bulk of installed capacity; Pneumatic Unloader solutions are expanding most quickly.
Technology:
Unloader technology dictates operational performance, including efficiency, dust control, and material handling capabilities. Each approach offers distinct advantages for specific industrial requirements.
- Mechanical:This broad category encompasses systems like rotary dumpers, employing physical force to unload bulk solids. Mechanical systems are dominant in high-throughput applications such as iron ore export terminals in Brazil.
- Pneumatic Conveying:This technology uses airflow to transport material, ensuring enclosed handling that minimizes dust and contamination. It sees significant uptake in food processing and chemical manufacturing.
- Vacuum:Vacuum systems draw material from railcars using suction, ideal for fine powders where spillage must be avoided.
- Gravity Discharge:These methods rely on material weight to flow out of specialized railcars, used for free-flowing commodities like sand or aggregates.
Mechanical technologies currently dominate the installed base for high-volume operations; Pneumatic Conveying solutions are gaining significant market share due to stringent environmental regulations.
Application:
The specific application for a railcar unloader correlates with required discharge volume and material characteristics, influencing system design and capacity. Industries demand tailored solutions.
- Bulk Material Handling:This application covers transfer of various loose materials from railcars to storage or processing, spanning diverse industrial settings.
- Mining Logistics:Unloaders here are engineered for extremely high-volume, continuous operation, handling dense minerals. Major mining corporations in South Africa heavily invest in these systems.
- Grain Transfer:Systems for grain transfer handle large volumes of agricultural commodities, often seasonally, with focus on gentle handling and rapid turnaround.
- Cement Processing:This application requires unloaders for fine, dusty, and abrasive cement powder, emphasizing dust containment and consistent flow.
Mining Logistics applications drive demand for the largest, most robust unloader systems, whereas Grain Transfer applications experience the steepest expansion trajectory.
End User Industry:
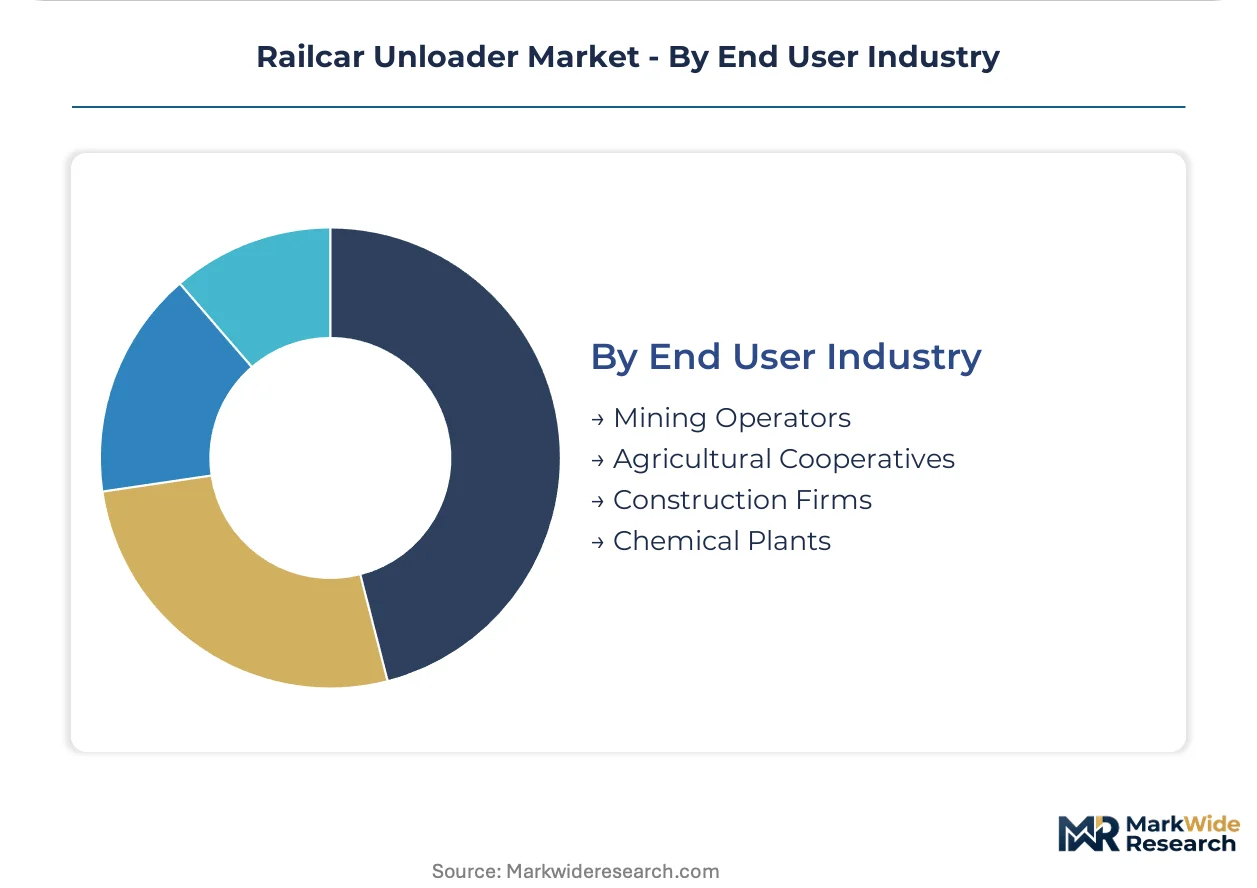
End-user industries specify railcar unloader requirements based on unique operational environments, material types, and adherence to regulatory frameworks. Safety and environmental compliance are paramount.
- Mining Operators:These entities require heavy-duty, high-throughput unloaders for massive volumes of raw minerals. Compliance with mine safety regulations and environmental impact assessments is critical.
- Agricultural Cooperatives:Cooperatives utilize unloaders for efficient transfer of grains and fertilizers, often requiring adaptable systems for seasonal demands.
- Construction Firms:These firms employ unloaders for aggregates and cement, prioritizing robust and often mobile solutions for diverse job sites.
- Chemical Plants:Chemical plants demand specialized unloaders that ensure material purity, prevent cross-contamination, and comply with stringent safety regulations.
Mining Operators represent the largest segment by installed capacity, while Chemical Plants are investing heavily in advanced, contained unloader technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Resource-rich regions with significant agricultural and mining operations drive concentrated demand for railcar unloaders. Specialized economic zones, particularly those supporting export-oriented industries, stimulate investment in high-throughput material handling infrastructure. These areas prioritize efficient logistics to maintain competitive global trade positions.
Australia
Australia's vast mining logistics operations generate substantial demand for robust railcar unloaders, particularly for iron ore and coal exports. The country's national environmental protection acts mandate stringent dust control measures in bulk material handling facilities. Major port expansions in Western Australia's Pilbara region continue to drive procurement for large-scale rotary unloader systems.
United States
The United States agricultural sector requires high-capacity unloaders for grain transfer and fertilizer distribution, especially across the Midwest. OSHA regulations concerning machine guarding and dust explosion hazards directly influence equipment design and upgrades. River ports along the Mississippi River and Gulf Coast terminals are consistently investing in modern, automated unloader systems.
Brazil
Brazil's immense agricultural output and mineral resources create strong demand for railcar unloaders in both grain and mining sectors. National environmental regulations emphasize responsible industrial practices, encouraging enclosed and dust-controlled systems. The state of Minas Gerais, a major iron ore producing region, sees continuous investment in heavy-duty unloader infrastructure.
Germany
Germany's advanced chemical and industrial sectors require specialized pneumatic unloader solutions for sensitive materials and dust containment. The European Union's Machinery Directive and ATEX directives for explosive atmospheres guide equipment specifications. Industrial clusters in the Rhine-Ruhr region frequently upgrade to comply with stringent safety and purity standards.
India
India's expanding infrastructure projects and agricultural growth stimulate demand for railcar unloaders in cement processing, coal, and grain transfer. Bureau of Indian Standards (BIS) certifications ensure quality and safety for industrial machinery. Port facilities in Gujarat and agricultural hubs in Punjab are experiencing increased unloader installations to support logistics efficiency.
Railcar Unloader Market Key Industry Players
Top-tier vendors anchor the high-capacity and custom-engineered segments, while a broader base of specialized manufacturers addresses niche applications. The market structure exhibits a tiered approach, with providers differentiating through technology and service capabilities. Strategic partnerships for system integration and continuous investment in automation capabilities are prevalent competitive moves.
Specialists in heavy-duty material handling, such as Nordstrong Equipment Ltd, exemplify the legacy of robust engineering for bulk applications. Scherzer GmbH, a German-based firm, occupies a position within the customized pneumatic unloader solutions segment, often serving European chemical plants. Kinergy Corporation represents expertise in vibratory technology, catering to difficult-to-handle materials.
| Leading Market Players |
|---|
| Nordstrong Equipment Ltd |
| Kinergy Corporation |
| McGill |
| Kingery Corporation |
| Jamieson Equipment Co |
| Process Control Corporation |
| NPK |
| Airmatic Inc |
| Scherzer GmbH |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up specialists, often focused on specific unloader technologies, balance supply behavior and pricing discipline by optimizing production scale and leveraging proprietary component sourcing.
Pricing Analysis
Premium pricing for short lead times reflects urgent operational needs at port terminals, where equipment downtime is costly. Project-based pricing models dominate for high-capacity systems, integrating design, manufacturing, and installation costs. Customization level and after-sales service quality are primary price differentiation drivers. Pricing softness stems from increasing competition among equipment providers offering standardized modular systems. Mining operators exhibit the least price sensitivity due to critical throughput demands, while smaller agricultural cooperatives are more price-sensitive.
Supply Chain Analysis
Direct-to-client channels handle high-value, custom unloader system sales, particularly for large mining corporations and port authorities. Geographic supply concentration for heavy mechanical components exists in Germany, China, and the United States. Raw material dependencies include heavy-gauge steel, specialized hydraulic components, and advanced programmable logic controllers. Single-source vulnerability for niche automation components represents a structural supply chain risk. Distribution for aftermarket parts often runs through regional service networks and authorized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The railcar unloader market is witnessing a vertical-integration race, with players pursuing upstream control over critical automation component manufacturing to enhance supply resilience.
For Market Incumbents: Deploy strategic partnerships with automation software developers to counter emerging threats from integrated logistics providers. Invest in AI-driven predictive maintenance platforms to offer value-added services, mitigating margin pressure from commoditization. Focus on securing long-term service contracts for high-throughput installations in mining logistics. This strategy defends market share against new entrants offering lower-cost, less integrated solutions.
For New Entrants and Emerging Players: Enter via modular and mobile unloader designs, targeting underpenetrated seasonal agricultural markets in Southeast Asia. Offer flexible lease-to-own models to overcome high capital cost barriers for smaller operators. Focus on specialized pneumatic systems for chemical plants, emphasizing dust containment and material purity compliance. This approach allows market penetration by addressing specific niche requirements with adaptable solutions.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized engineering firms with strong regional service networks in Australia, where mining expansion continues. Long-term viability rests on sustained global demand for bulk commodities and increasing automation mandates. Target specialized engineering firms possessing proprietary dust control technologies or advanced sensor integration capabilities. The signal to watch is increased port infrastructure investment in emerging markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Automation Component Manufacturing | Enhances supply chain resilience and reduces reliance on external vendors for critical electronic controls. |
| Development of AI-Driven Predictive Maintenance Platforms | Improves equipment uptime and offers new recurring revenue streams through advanced service contracts. |
| Strategic Acquisition of Regional Service Providers | Strengthens aftermarket support networks and expands geographic reach for installation and maintenance services. |
| Investment in Modular and Mobile Unloader Designs | Addresses the growing demand for flexible, deployable solutions in seasonal or remote operational environments. |
| Partnerships for Integrated Dust Suppression Technologies | Ensures compliance with increasingly stringent environmental regulations and enhances product safety features. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, providing foundational market sizing. Primary interviews with plant engineers, procurement managers, port authorities, and equipment maintenance leads validated market dynamics. This approach combined bottom-up segment sizing with top-down overall market validation, ensuring data consistency across diverse sources.
Market volume and value were modeled at the product type, technology, application, and end-user industry dimensions, with regional granularity. The analytical framework integrated historical growth trends with projected capital expenditure plans to derive compound annual growth rates over the projection horizon. Key forecast inputs included global commodity price forecasts and projected international trade volumes for bulk materials.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant shifts in global trade policies or unforeseen regulatory changes impacting bulk material handling. All projections reflect a comprehensive set of assumptions regarding technological advancements and economic conditions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Egypt Cold Chain Logistics Market
Transportation & Logistics
Multimodal Transport Market
Transportation & Logistics
North America Road Freight Transportation Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
Rental and Subscription Product Logistics Orchestration Platforms Market
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
United States Short Haul Road Freight Transport Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
Inland Water Freight Transport Market
Transportation & Logistics
India less than-Truck-Load (LTL) Market
Transportation & Logistics
China Road Freight Transport Market
Transportation & Logistics
Refrigerated Trailer Market
Transportation & Logistics
Hong Kong Customs Brokerage Market
Transportation & Logistics
Rail Asset Management Market