
 Europe Customs Brokerage Market | 2026-2036
Europe Customs Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Customs Brokerage Market Foresight
E-commerce retail is hardening as the dominant demand vertical for customs brokerage across Europe. DHL Group Logistics leverages its integrated parcel and customs infrastructure to dominate express clearance corridors. Kuehne + Nagel anchors its position through specialized pharmaceutical and perishables customs consulting. DB Schenker competes by extending rail-sea intermodal customs solutions across Central and Eastern European manufacturing zones.
Europe customs brokerage encompasses licensed intermediary services that manage tariff classification, duty calculation, and regulatory compliance for goods crossing European Union external borders. These operations require precise Harmonized System code assignment, origin certification under EU preferential trade agreements, and real-time interaction with the EU Customs Transit System for duty suspension. Documentation and tariff classification services capture the largest revenue share due to mandatory pre-arrival filing requirements under the Union Customs Code. AI solutions within the technology segment are expanding fastest as machine learning models automate HS code prediction and risk-based cargo profiling, though blockchain-enabled origin verification remains nascent outside pilot programs with select automotive OEMs.
The EU Customs Code, administered by national customs authorities under European Commission oversight, mandates standardized data formats through the Import Control System 2 that reshape broker technology investments. ECHA REACH compliance documentation and EFSA sanitary import requirements add parallel verification layers for chemicals and food shipments. Stakeholders must monitor the phased deployment of the EU Single Customs Window and assess whether their data architecture can consolidate multi-agency filings without fragmenting client service lines.
Market Dynamics
The EU Customs Code reform and Import Control System 2 deployment are forcing brokerages to rebuild data architectures around real-time pre-arrival filing, compressing margins for operators lacking integrated compliance technology stacks.
Growth Catalysts
- Automotive cross-border sourcing:Manufacturers expanding component procurement across Central and Eastern European supplier networks require specialized origin certification and tariff engineering services.
- E-commerce fulfillment networks:Parcel volume concentration in Belgian and Dutch distribution hubs generates sustained demand for deferred duty schemes and consolidated customs entries.
- REACH documentation mandates:ECHA chemical import verification requirements compel shippers to retain licensed brokers for substance volume tracking and safety data sheet alignment.
Market Restraints
- Customs IT infrastructure concentration:Reliance on national single window platforms in Germany and France creates operational vulnerability during system upgrades or cyber incidents.
- Qualified declarer scarcity:Licensed customs specialists require multi-year certification pathways under EU member state professional frameworks, constraining workforce expansion.
- Rail-sea intermodal complexity:Multi-modal cargo handoffs across Polish and Slovak corridors generate documentation mismatches that delay clearance and erode broker margins.
Strategic Opportunities
- Romanian and Bulgarian port expansion:Black Sea container terminal development is opening alternative EU entry points underserved by established brokerage networks.
- EU Single Customs Window integration:Early certification for consolidated multi-agency filing capabilities will differentiate full-service operators from document-only competitors.
- AI-HS code convergence:Machine learning classification tools combined with blockchain origin verification offer premium service tiers for automotive and pharmaceutical verticals.
Industry Challenges
- Union Customs Code transition timelines:Phased ICS2 deployment deadlines force simultaneous legacy system maintenance and new platform investment, straining mid-tier broker IT budgets.
- Perishables clearance velocity:EFSA sanitary import windows measured in hours require 24/7 specialist staffing that conflicts with standard brokerage operating models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Customs Brokerage Market |
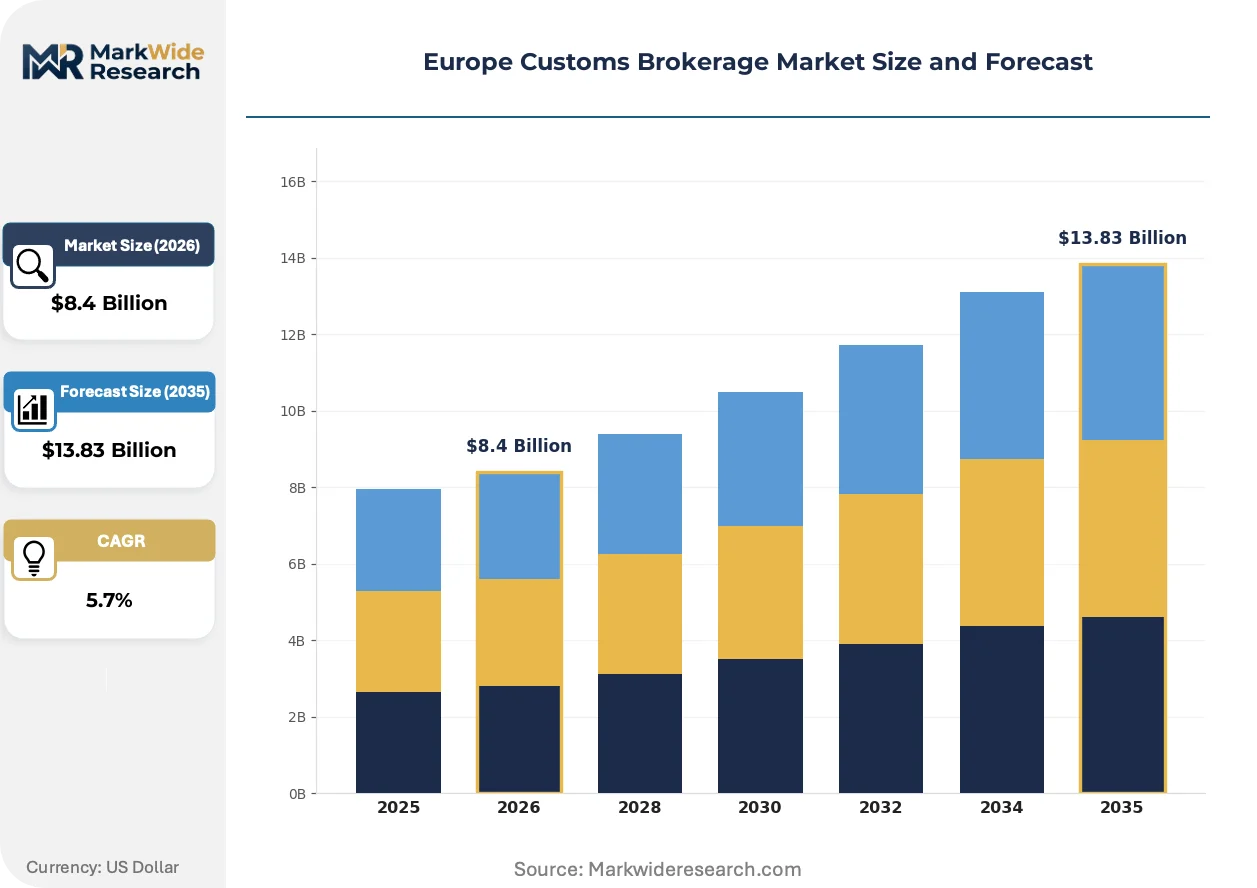
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Documentation, Tariff Classification, Duty Drawback, Consulting End User: Manufacturers, Retailers, Importers, Exporters Technology: AI Solutions, Blockchain, Cloud Computing, Automation Delivery Model: On-Premises, Hybrid, Managed Service, Third-Party Logistics |
| Companies Covered | Maersk Logistics, FedEx, DHL Group Logistics, Gerlach Customs, Rhenus Logistics, Kuehne + Nagel, United Parcel Services, APL Logistics, DB Schenker, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Customs Brokerage Market Shifts & Advancements
Automation of tariff classification and risk profiling is compressing the value of routine documentation services while elevating premium advisory roles for complex regulatory verticals.
Machine learning models trained on historical HS code rulings are rewriting how brokerages handle high-volume, low-complexity shipments. E-commerce logistics providers are deploying these tools across Belgian and Dutch fulfillment corridors to process deferred duty entries without human intervention. The technology is rewriting cost structures by collapsing per-entry processing time from hours to seconds, forcing traditional brokers to retreat toward specialized consulting margins.
EU AI Act risk classification requirements are reshaping how automated customs systems document decision logic. Brokers deploying algorithmic cargo profiling must now maintain explainable audit trails for customs authority review, particularly for pharmaceutical and dual-use goods. German and French national customs administrations are piloting compliance frameworks that demand algorithmic transparency documentation alongside traditional entry filings.
Consolidated service contracts spanning freight forwarding, warehousing, and customs clearance are displacing standalone brokerage relationships among mid-market manufacturers. Industrial shippers in the Czech Republic and Hungary are bundling compliance services with intermodal transport procurement to reduce vendor management overhead. This bundling is most visible in automotive supply chains where just-in-sequence delivery requirements demand synchronized customs and logistics execution.
Europe Customs Brokerage Market Segmentation
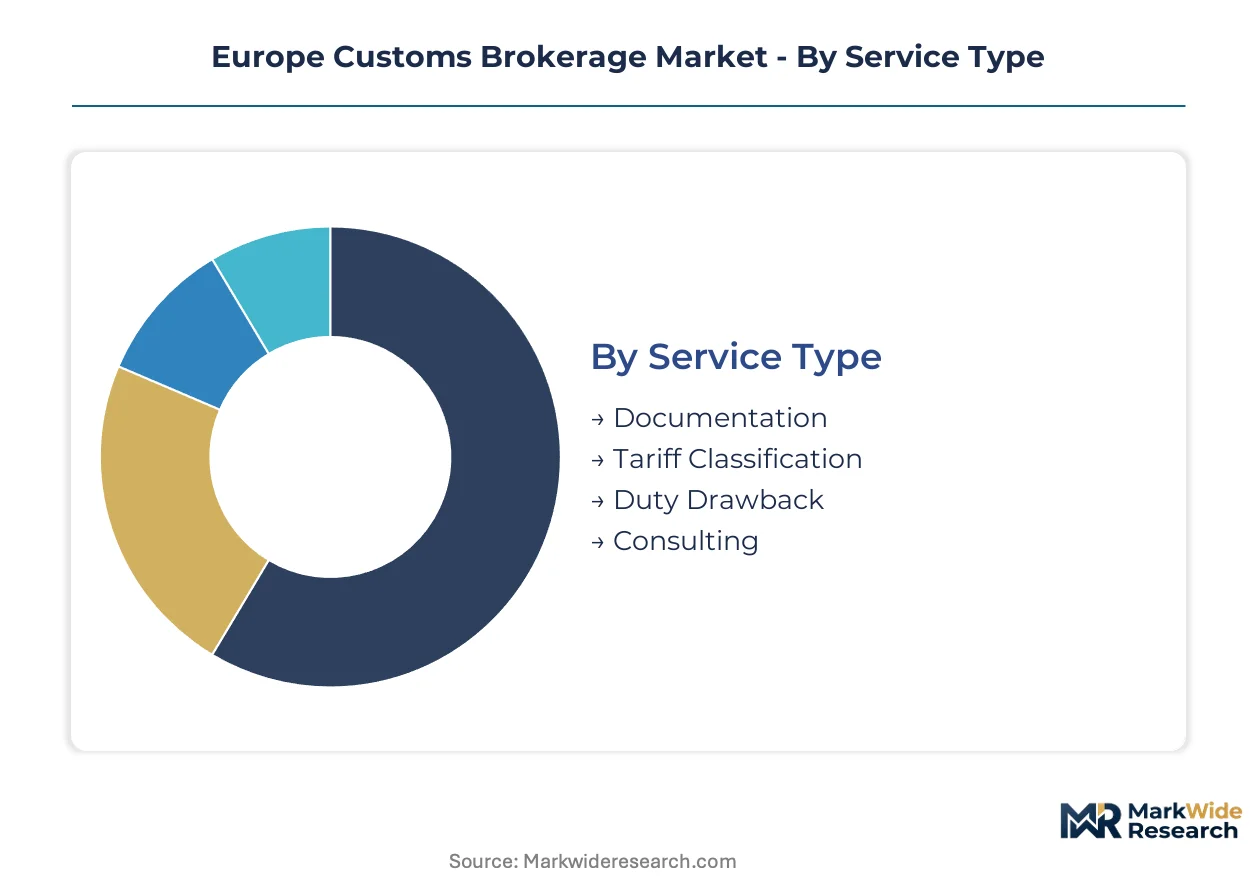
Customs brokerage services fragment across multiple axes that determine technology investment, margin structure, and client retention. Service complexity, regulatory exposure, and data architecture requirements vary dramatically across these dimensions, forcing operators to prioritize capability depth in select categories.
Service Type:
Technology intensity and regulatory specificity separate high-margin advisory roles from commoditized document processing.
- Documentation:Pre-arrival filing under the Union Customs Code mandates electronic submission through national single window platforms. Demand concentrates in German and Dutch port clusters where container volume density justifies dedicated clearance teams and 24/7 staffing for vessel arrival windows.
- Tariff Classification:Harmonized System code assignment requires specialized knowledge of EU TARIC database rulings and binding tariff information procedures. Automotive manufacturers expanding Central and Eastern European supplier networks drive sustained demand for origin certification and engineering services that optimize duty exposure.
- Duty Drawback:Reclaim mechanisms for re-exported goods demand precise tracking of input materials through manufacturing processes.
- Consulting:Advisory services span ECHA REACH compliance, EFSA sanitary import planning, and preferential trade agreement structuring.
Mature deployment sits with Documentation. Newer deployment is concentrated in Consulting.
End User:
Procurement sophistication and compliance risk exposure create distinct service requirements across buyer categories.
- Manufacturers:Industrial shippers require synchronized customs and logistics execution for just-in-sequence delivery. Czech and Hungarian automotive supply chains bundle compliance with intermodal transport procurement to reduce vendor management overhead.
- Retailers:E-commerce fulfillment networks in Belgian and Dutch distribution hubs generate sustained demand for deferred duty schemes and consolidated entries. Parcel volume concentration forces investment in automated classification tools.
- Importers:First-time EU market entrants rely on brokers for establishment of fiscal representation and VAT deferment arrangements.
- Exporters:Outbound shipment compliance focuses on destination country certification and dual-use goods licensing.
Revenue concentration favors Manufacturers. Fastest capability expansion targets Retailers.
Technology:
Automation maturity and regulatory acceptance determine deployment pace across digital infrastructure categories.
- AI Solutions:Machine learning models trained on historical HS code rulings process deferred duty entries without human intervention. Belgian and Dutch e-commerce corridors deploy these tools to collapse per-entry processing from hours to seconds, forcing traditional brokers toward specialized consulting margins.
- Blockchain:Distributed ledger applications for origin verification remain confined to pilot programs with select automotive OEMs. EU AI Act risk classification requirements demand explainable audit trails for algorithmic cargo profiling, particularly for pharmaceutical and dual-use goods.
- Cloud Computing:Scalable infrastructure supports real-time interaction with the EU Customs Transit System for duty suspension.
- Automation:Robotic process handling of repetitive filing tasks reduces headcount in high-volume operations.
Commercial traction concentrates in AI Solutions. Regulatory validation is furthest along for Cloud Computing.
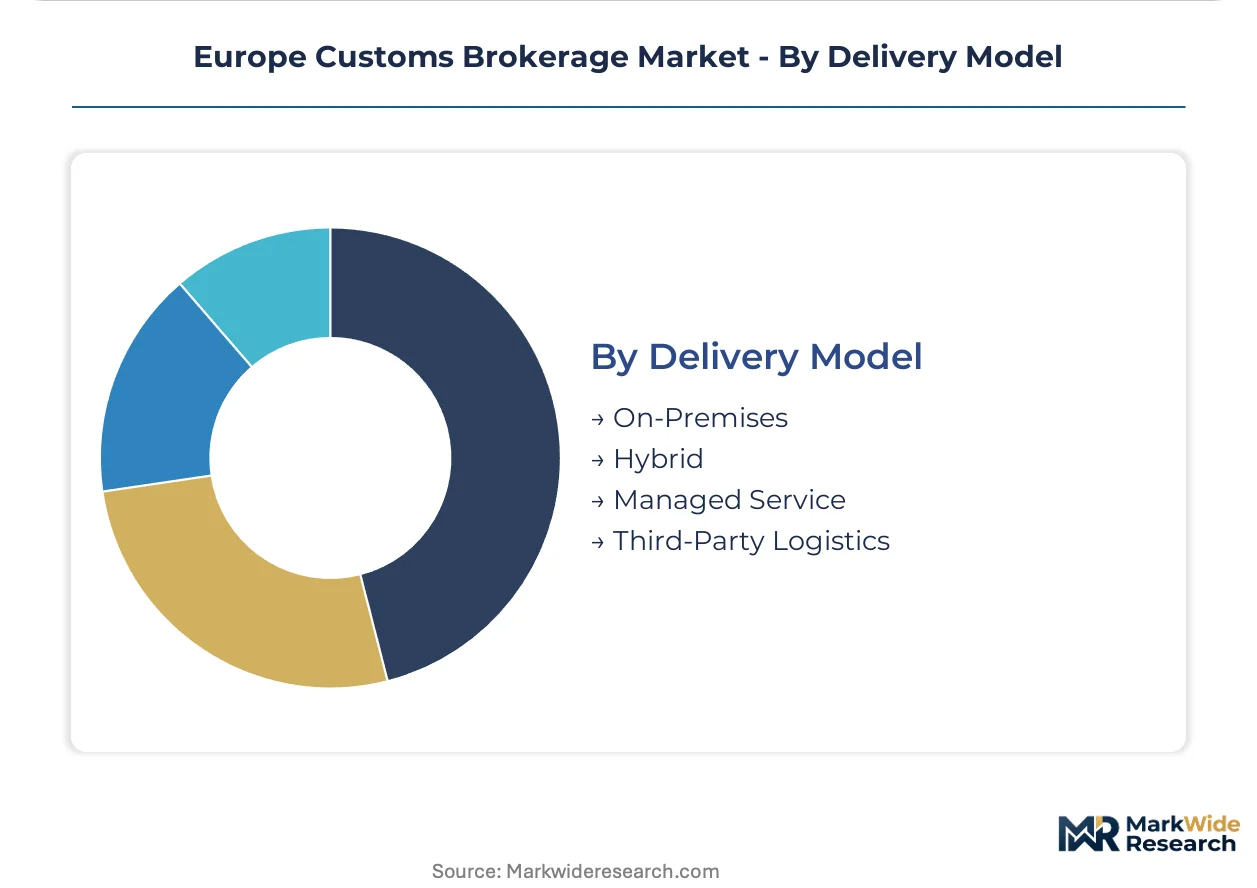
Delivery Model:
Control retention and capital intensity shape broker decisions on infrastructure ownership.
- On-Premises:Legacy installations persist among operators serving defense and dual-use goods clients with data sovereignty requirements. German customs authorities mandate localized processing for certain controlled technology shipments.
- Hybrid:Split architectures allow sensitive classification logic to remain on-site while leveraging cloud scale for transaction processing. Mid-tier brokers in Poland and Slovakia adopt this model to manage ICS2 transition without full platform replacement.
- Managed Service:Outsourced IT and compliance operations appeal to smaller brokers lacking dedicated technology teams.
- Third-Party Logistics:Bundled freight-custody arrangements displace standalone brokerage among industrial shippers seeking vendor consolidation.
Established presence sits with On-Premises. Migration momentum favors Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian customs-free zones around the Port of Antwerp-Bruges and Dutch VAT deferment arrangements at Rotterdam attract e-commerce fulfillment concentration. These fiscal incentives reshape brokerage demand geography across northwest Europe.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg drive specialized origin certification demand for Central and Eastern European supplier networks. The KBA enforces strict documentation for vehicle component imports under EU preferential trade agreements. Hamburg's port cluster processes the highest container volumes, requiring 24/7 broker staffing for vessel arrival windows.
Netherlands
E-commerce parcel concentration in Venlo and Rotterdam distribution hubs generates sustained demand for deferred duty schemes. ECHA REACH compliance documentation mandates reshape chemical import verification requirements. The Port of Rotterdam's single window platform integration forces broker technology investments around real-time pre-arrival filing.
Belgium
Belgian customs-free zones surrounding Antwerp-Bruges attract Amazon and Alibaba fulfillment network expansion. EFSA sanitary import requirements for perishables create 24/7 specialist staffing demands that conflict with standard brokerage models. The Brussels corridor anchors pharmaceutical customs consulting for temperature-controlled shipments.
Poland
Rail-sea intermodal cargo handoffs across Polish corridors generate documentation mismatches that delay clearance. The phased ICS2 deployment forces simultaneous legacy system maintenance and new platform investment. Silesian manufacturing zones bundle compliance services with intermodal transport procurement to reduce vendor management overhead.
Romania
Black Sea container terminal development at Constanța opens alternative EU entry points underserved by established brokerage networks. The EU Single Customs Window integration creates differentiation opportunities for early-certified operators. Bucharest-based brokers are expanding into Bulgarian corridors to capture emerging manufacturing demand.
Europe Customs Brokerage Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated logistics providers capturing bundled freight-custody arrangements while standalone brokers retreat toward specialized advisory roles. The vendor base concentrates around three tiers: global freight forwarders with captive customs operations, regional specialists with deep EU regulatory expertise, and technology-enabled disruptors automating high-volume documentation. Competitive positioning hardens through M&A consolidation of mid-tier operators and accelerated investment in AI-HS code classification capabilities.
Within the integrated logistics tier, DHL Group Logistics, Kuehne + Nagel, and DB Schenker occupy positions that exemplify divergent specialization strategies. DHL Group Logistics represents the e-commerce corridor dominance archetype through its integrated parcel and customs infrastructure across Belgian and Dutch fulfillment hubs. Kuehne + Nagel anchors the premium advisory segment with specialized pharmaceutical and perishables customs consulting capabilities. DB Schenker exemplifies the intermodal bundling approach through rail-sea customs solutions across Central and Eastern European manufacturing zones.
| Leading Market Players |
|---|
| Maersk Logistics |
| FedEx |
| DHL Group Logistics |
| Gerlach Customs |
| Rhenus Logistics |
| Kuehne + Nagel |
| United Parcel Services |
| APL Logistics |
| DB Schenker |
| Others |
Supply & Pricing Matrix
Mid-market automotive manufacturers bundling compliance with intermodal procurement dominate pricing power in European customs brokerage, forcing tiered service structures that separate premium advisory from commoditized documentation tiers. This buyer concentration rewards operators with integrated technology stacks while squeezing standalone brokers into narrow margin corridors.
Pricing Analysis
Expedited clearance premiums for perishables and just-in-sequence automotive shipments command substantial markups over standard deferred-duty processing windows. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with ECHA REACH-compliant consulting and 24/7 specialist staffing anchoring the top tier. Pricing pressure stems from AI-automated HS code classification collapsing per-entry processing economics in Belgian and Dutch e-commerce corridors. Small importers establishing fiscal representation prove most price-sensitive, while pharmaceutical manufacturers prioritize compliance assurance over rate negotiation.
Supply Chain Analysis
Reverse-logistics flows for duty drawback reclamation and re-exported goods create specialized documentation demands that few brokers service profitably. Supply concentrates in Germany, the Netherlands, and Belgium where port clusters and inland clearance hubs process the highest freight volumes. Licensed declarer talent and ICS2-compliant IT infrastructure constitute critical input dependencies. Single-source vulnerability to national single-window platform outages in Germany and France elevates operational risk. Distribution runs through integrated logistics providers bundling freight forwarding with customs clearance, displacing standalone brokerage relationships among industrial shippers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe customs brokerage market sits in a technology-transition phase where machine learning classification tools are displacing legacy manual HS code assignment workflows. This shift compresses margins for document-only operators while elevating premium advisory roles.
For Market Incumbents: To counter AI-enabled entrants automating high-volume e-commerce corridors, incumbents must deepen vertical integration into freight forwarding and warehousing to capture bundled service contracts. Prioritize certification investment for EU Single Customs Window early-adopter status, which differentiates full-service operators from document-only competitors. Defensive consolidation of mid-tier operators with complementary geographic footprints preserves scale economics against technology disruptors. For New Entrants and Emerging Players: Begin with Black Sea corridor expansion at Constanța and Bulgarian manufacturing zones where established brokerage networks remain underdeveloped. Target Romanian automotive supplier networks requiring origin certification and tariff engineering services underserved by incumbent presence. Deploy cloud-native ICS2-compliant platforms without legacy system maintenance burdens to outmaneuver mid-tier brokers straining under simultaneous old and new platform investment. For Investors and Strategic Acquirers: The window for entry favors technology-enabled specialists with proven AI-HS code classification capabilities and established pharmaceutical or perishables vertical expertise. Mid-tier brokers with fragmented IT architectures face stranded asset risk as ICS2 deadlines compress. Watch for EU AI Act compliance framework finalization as an inflection signal—early algorithmic transparency documentation capabilities will separate acquirable premium assets from distressed legacy operators.| Strategic Initiative | Industry Significance |
|---|---|
| AI-HS Code Classification Deployment | Machine learning automation collapses processing economics in Belgian and Dutch e-commerce corridors. |
| EU Single Customs Window Certification | Early multi-agency filing capabilities differentiate full-service operators from document-only competitors. |
| Black Sea Geographic Expansion | Constanța terminal development opens alternative EU entry points underserved by established networks. |
| Pharmaceutical Vertical Specialization | Temperature-controlled shipment consulting and EFSA 24/7 staffing requirements command premium margins. |
| Mid-Tier Broker Consolidation | M&A of fragmented operators preserves scale economics against technology-enabled disruptors. |
Research Methodology
Document review covered EU Customs Code implementation guidelines, ECHA REACH compliance documentation, and national customs authority filings, complemented by interviews with licensed customs declarers, freight forwarding operations directors, and e-commerce logistics procurement managers. Secondary validation drew from EU Customs Transit System deployment reports, ICS2 technical specifications, and trade association regulatory updates. Bottom-up service provider revenue modeling and top-down market sizing triangulated volume and value estimates across the analysis window.
Cross-referencing historical brokerage service adoption patterns against expert panel input on ICS2 transition timelines shaped the analytical framework. Segmentation dimensions modeled include service type complexity, end-user procurement sophistication, technology automation maturity, and delivery model control retention. CAGRs were derived from trend extrapolation adjusted for regulatory deadline impacts and technology diffusion curves. Forecast inputs incorporated EFSA sanitary import window requirements and ECHA chemical verification mandate expansion trajectories.
Underlying measurement precision varies by segment; AI Solutions and Consulting services carry tighter precision than commoditized Documentation due to clearer technology deployment visibility and regulatory mandate timelines. Forecasts reflect assumptions about ICS2 phased deployment adherence and qualified declarer workforce expansion rates. Practitioners should monitor EU AI Act algorithmic transparency finalization and Romanian port infrastructure completion for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Canada Customs Brokerage Market
Transportation & Logistics
Transportation Condensing Units Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
Thailand Road Freight Transport Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
Europe Road Feeder Services Market
Transportation & Logistics
Reverse Logistics Market
Transportation & Logistics
Inland Water Freight Transport Market
Transportation & Logistics
Brazil Cold Chain Logistics Market
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
UAE Cold Chain Logistics Market
Transportation & Logistics
Intermodal Freight Transportation Market
Transportation & Logistics
Refrigerated Trailer Market
Transportation & Logistics
Latin America Customs Brokerage Market
Transportation & Logistics
United Kingdom Road Freight Transport Market
Transportation & Logistics
Malaysia Refrigerated Trailer Market