
 Pipeline Transportation Software Market | 2026-2036
Pipeline Transportation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Transportation Software Market Analytics
Aftermarket service revenue is narrowing toward embedded analytics and predictive maintenance modules as operators seek to reduce total cost of ownership. Siemens AG leverages its digital twin portfolio to anchor long-term service contracts across European pipeline networks. Schneider Electric SE competes through its EcoStruxure platform, which integrates edge computing with legacy SCADA architectures. Emerson Electric Co. specializes in flow assurance software, sustaining its position in deepwater and unconventional transport corridors.
Pipeline transportation software encompasses SCADA-enabled platforms, GIS mapping tools, and IoT-driven asset monitoring systems that manage hydrocarbon and fluid flow across transmission and distribution networks. These systems typically process real-time pressure, temperature, and flow-rate data at millisecond intervals to trigger automated valve control and leak detection responses. Monitoring Solutions and SCADA Systems represent mature, high-margin segments where incumbents have built decades of installed-base loyalty. Cloud-Based and SaaS deployment models are expanding fastest among midstream logistics firms seeking to avoid capital-intensive on-premise infrastructure. Asset Management integrated with GIS functionality captures disproportionate R&D investment as operators prioritize geospatial risk visualization for corridor integrity.
The US PHMSA mandates integrity management programs under 49 CFR Part 195, forcing operators to adopt traceable, auditable software workflows for hazard identification and risk assessment. In Europe, the EU Green Deal and F-Gas Regulation pressure methane-intensive transport networks to deploy emissions-monitoring modules within their control systems. Operators must weigh regulatory compliance spend against the operational flexibility that modular, API-first architectures provide for future carbon-accounting integration.
Market Dynamics
Midstream operators face mounting pressure from the US PHMSA's integrity management mandates under 49 CFR Part 195, which compels widespread replacement of legacy SCADA architectures with auditable, traceable software workflows. This regulatory compression is the dominant force restructuring vendor relationships and procurement priorities across the sector.
Growth Catalysts
- 49 CFR Part 195 Compliance Mandates:US operators must deploy automated hazard identification and risk assessment modules, creating immediate replacement demand for non-compliant legacy systems.
- Methane Emissions Monitoring:The EU Green Deal and F-Gas Regulation force European pipeline networks to integrate emissions-tracking functionality directly into control system software.
- Deepwater Unconventional Expansion:Flow assurance software adoption accelerates in offshore Brazil and US Gulf corridors where subsea infrastructure complexity demands predictive modeling capabilities.
Market Restraints
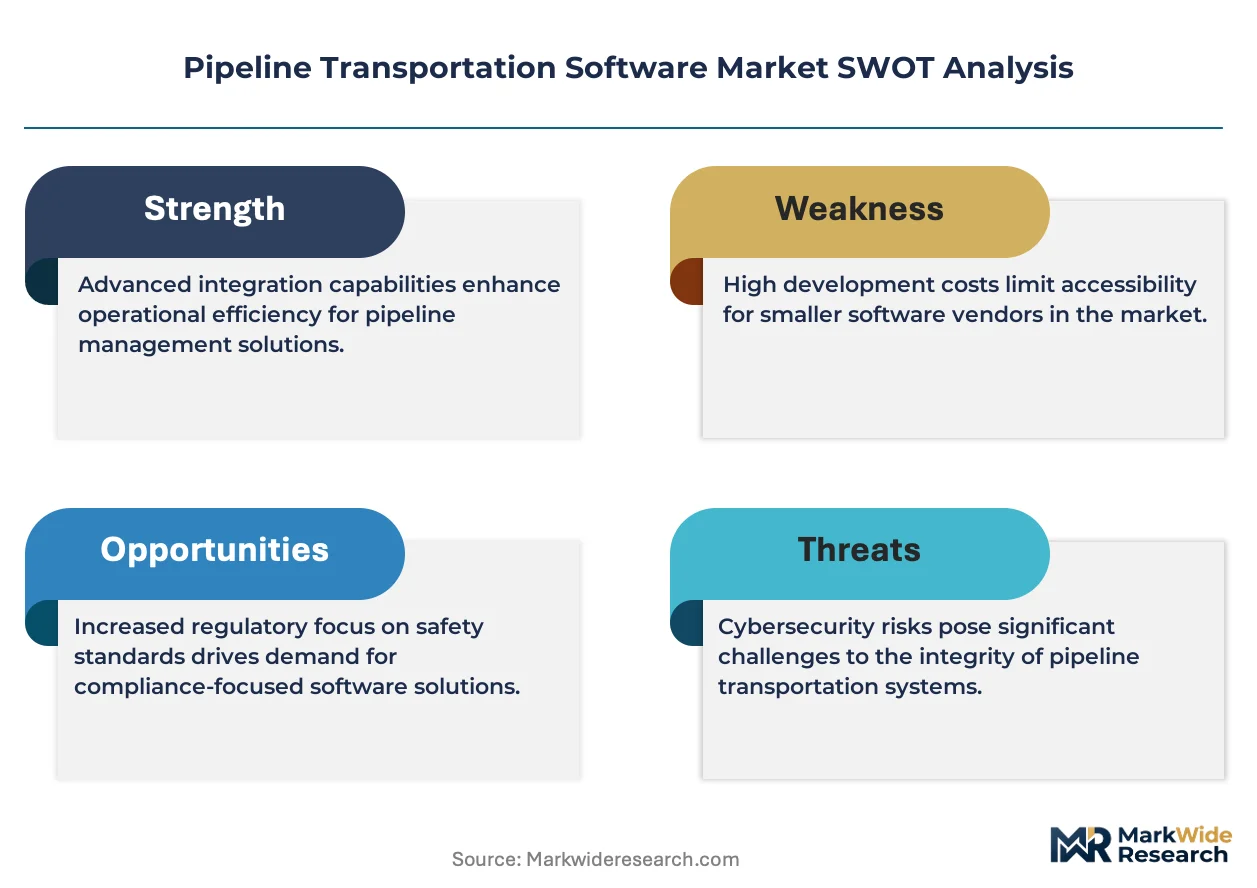
- Legacy System Entrenchment:Decades-old SCADA installations create path dependency, with retrofit costs often exceeding greenfield deployment economics for smaller operators.
- Cybersecurity Certification Delays:NERC CIP compliance timelines for critical infrastructure software extend procurement cycles by 12-18 months in North American markets.
- Specialized Talent Scarcity:Pipeline control systems engineering expertise concentrates among aging workforces in Houston, Calgary, and Aberdeen, constraining implementation velocity.
Strategic Opportunities
- Cloud-Native SaaS Migration:Midstream logistics firms seek subscription-based deployment to avoid capital-intensive on-premise infrastructure, opening recurring revenue streams for platform vendors.
- Carbon Accounting Integration:API-first architectures that embed Scope 3 emissions tracking position vendors for EU CSRD and emerging SEC climate disclosure requirements.
- GIS-Enabled Asset Management:Geospatial risk visualization for corridor integrity captures disproportionate R&D investment as operators prioritize predictive maintenance.
Industry Challenges
- Interoperability Fragmentation:Proprietary protocols from decades of vendor lock-in impede seamless data exchange between SCADA, GIS, and IoT monitoring layers.
- Real-Time Processing Constraints:Millisecond-interval pressure and flow-rate data processing demands edge computing infrastructure that many operators lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Transportation Software Market |
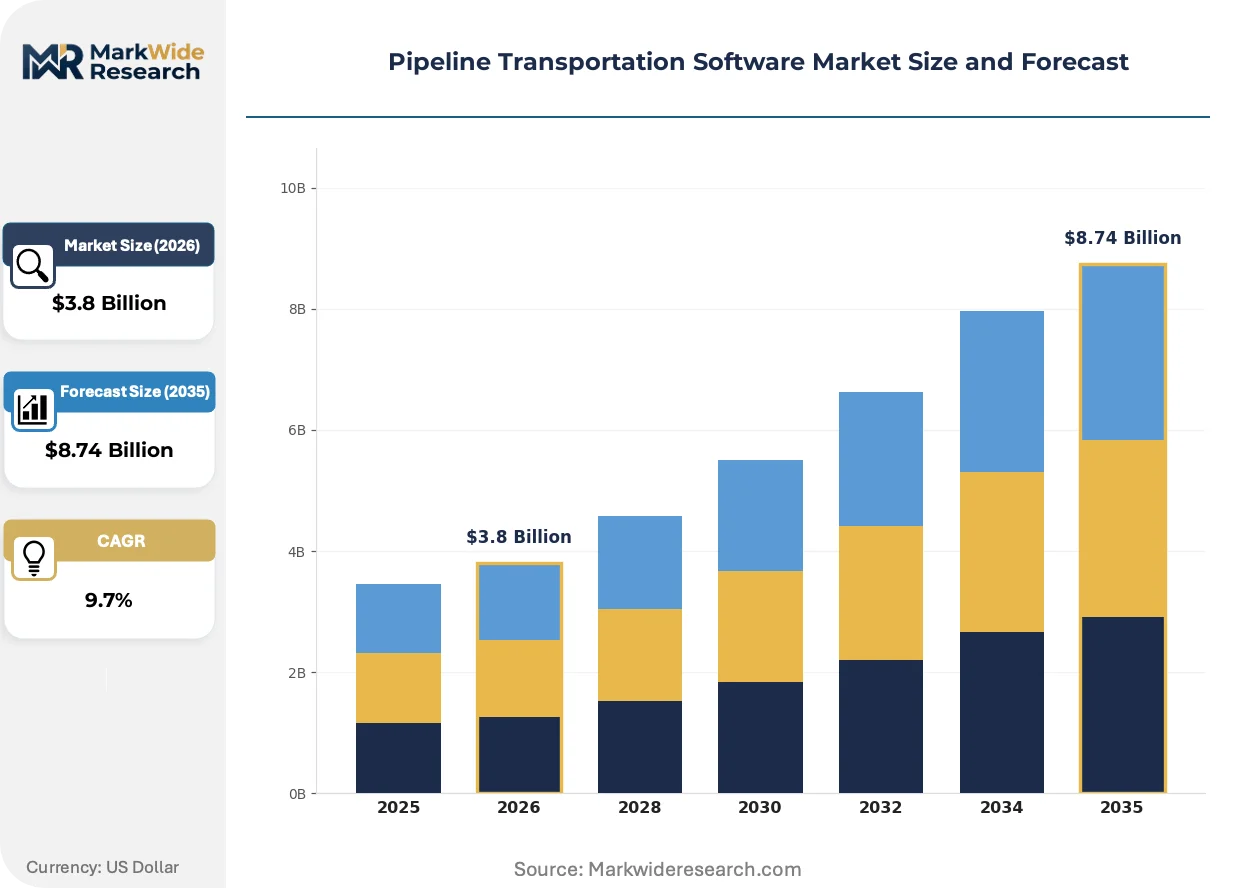
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compliance Management, Monitoring Solutions, Asset Management, Dispatch Systems End User: Oil & Gas Companies, Utility Providers, Logistics Firms, Third-Party Operators Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Technology: GIS Integration, SCADA Systems, Data Analytics, IoT Solutions |
| Companies Covered | Siemens AG, Schneider Electric SE, ABB Ltd., Emerson Electric Co., Trimble Inc., Esri, Alstom SA, Rockwell Automation, Inc., FMC Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Transportation Software Market Evolving Landscape
Digital twin technology is hybridizing with pipeline control architectures, compressing the boundary between physical asset management and virtual simulation environments. This convergence is redefining how operators approach predictive maintenance and throughput optimization.
Edge computing is hybridizing with legacy SCADA systems to process pressure, temperature, and flow-rate data at source rather than centralized servers. Midstream operators in the Permian Basin and North Sea corridors are deploying these architectures to reduce latency for automated valve control responses. The structural consequence is a shift toward distributed intelligence that reduces dependence on cloud connectivity for critical safety functions.
The EU F-Gas Regulation and companion methane performance standards are forcing emissions-monitoring module integration into control system software. European operators must now deploy continuous leak detection with quantified reporting capabilities. Deepwater and subsea transport corridors face the steepest compliance costs, driving demand for integrated sensor-software packages.
Subscription-based procurement models are displacing perpetual license structures among midstream logistics firms seeking operational expenditure treatment. This shift compresses upfront vendor revenue but extends customer lifetime value through embedded analytics and predictive maintenance service tiers. The transformation is most visible among US-based master limited partnerships optimizing cash flow profiles.
Pipeline Transportation Software Market Segmentation
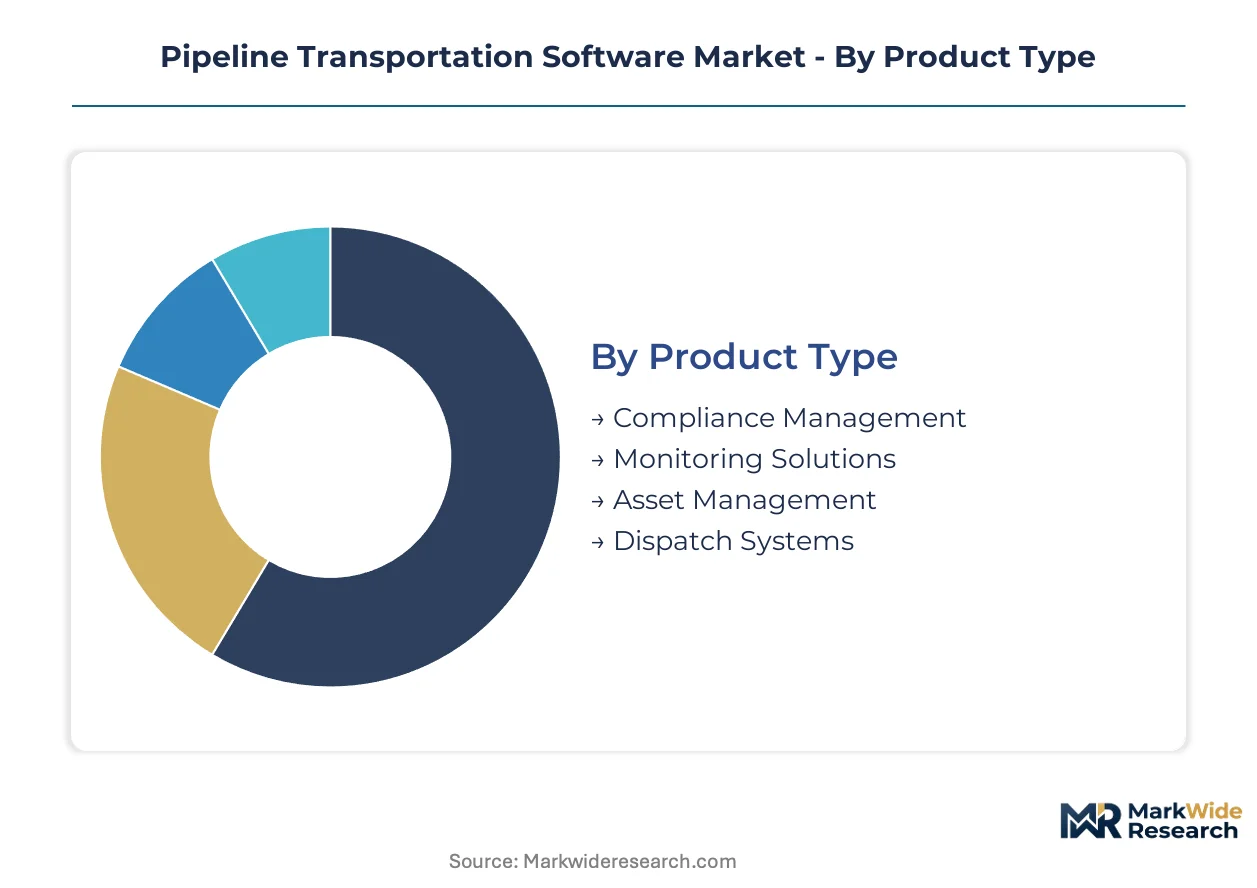
Pipeline operators select software modules based on regulatory exposure, infrastructure age, and capital structure. Segmentation reveals how compliance mandates, cloud economics, and legacy system constraints fragment procurement patterns across the midstream sector.
Product Type:
Use-case spectrum spans reactive compliance tools to predictive asset optimization platforms.
- Compliance Management:Automated hazard identification and auditable risk assessment workflows process integrity data under 49 CFR Part 195 mandates. US operators in the Permian Basin and Gulf Coast corridors deploy these modules to satisfy PHMSA inspection protocols and reduce manual documentation burden.
- Monitoring Solutions:Real-time pressure, temperature, and flow-rate surveillance systems trigger millisecond-interval valve control responses. Demand concentrates in North Dakota's Bakken formation and Alberta's oil sands, where remote infrastructure requires continuous leak detection and rupture mitigation.
- Asset Management:Lifecycle tracking platforms integrate maintenance schedules with replacement forecasting for pipeline integrity.
- Dispatch Systems:Logistics coordination software optimizes batch sequencing and throughput scheduling across multi-product corridors.
Established volume favors Monitoring Solutions; emerging adoption favors Compliance Management.
End User:
Customer archetypes differ in regulatory scrutiny depth and software integration sophistication.
- Oil & Gas Companies:Integrated majors and independents operate the most complex SCADA-legacy hybrid architectures. Supermajors in the US Gulf of Mexico and Norwegian North Sea drive demand for digital twin-enabled predictive maintenance suites.
- Logistics Firms:Midstream master limited partnerships prioritize SaaS procurement models to preserve cash flow. These operators in Texas and Oklahoma seek subscription-based dispatch optimization without capital-intensive infrastructure builds.
- Utility Providers:Natural gas distribution utilities manage municipal and industrial delivery networks with standardized pressure regulation requirements.
- Third-Party Operators:Contract pipeline managers serving multiple shippers require modular, API-first platforms for rapid tenant onboarding.
Procurement scale tilts toward Oil & Gas Companies; contract flexibility favors Third-Party Operators.
Deployment:
Infrastructure location and connectivity reliability determine architecture selection.
- Cloud-Based:Centralized processing platforms eliminate on-premise server maintenance for midstream logistics firms. Adoption accelerates among Permian Basin operators seeking to avoid capital expenditure classification while maintaining SCADA data accessibility.
- SaaS:Subscription-native delivery embeds continuous updates and predictive analytics modules without version migration costs. US-based MLPs in the Marcellus and Utica shale regions favor this model for operational expenditure treatment and rapid scaling.
- On-Premise:Air-gapped installations persist in critical infrastructure segments requiring NERC CIP cybersecurity isolation.
- Hybrid:Edge-cloud combinations process safety-critical data locally while archiving analytics workloads remotely.
Capital efficiency drives Cloud-Based preference; security certification delays sustain On-Premise retention.
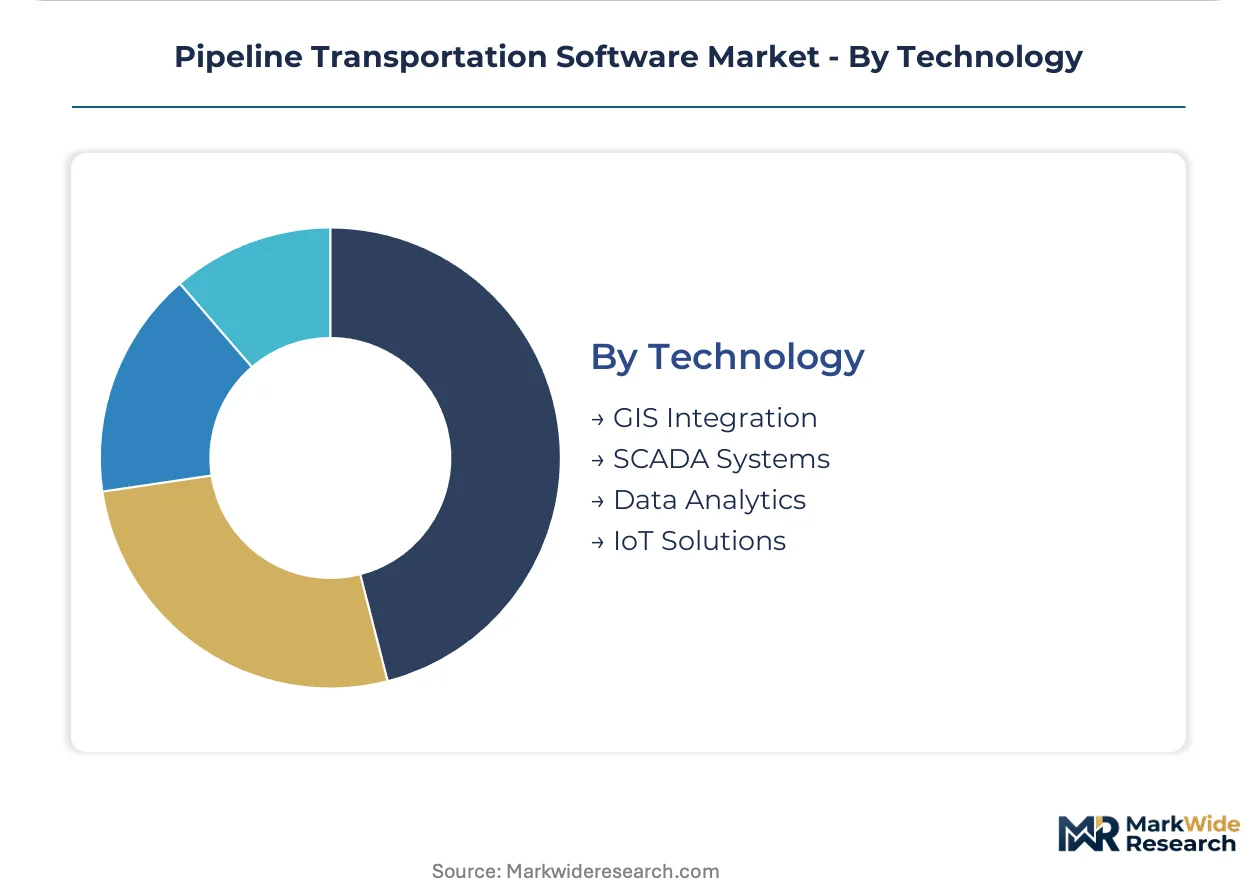
Technology:
Functional layer integration determines system interoperability and data latency performance.
- SCADA Systems:Decades-old supervisory control architectures remain the operational backbone for pressure and flow management. Incumbent loyalty concentrates in Calgary and Aberdeen, where specialized engineering workforces maintain legacy protocol expertise.
- GIS Integration:Geospatial risk visualization layers correlate pipeline corridor integrity with terrain, population density, and environmental sensitivity. European operators under EU Green Deal methane monitoring mandates deploy these modules for emissions-source localization.
- Data Analytics:Predictive algorithms process historical failure patterns to forecast maintenance intervals and replacement priorities.
- IoT Solutions:Distributed sensor networks transmit pressure, temperature, and acoustic data from remote valve stations and pump complexes.
Installed-base entrenchment protects SCADA Systems; regulatory pressure accelerates GIS Integration deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in mature North American corridors exhibit low price elasticity where regulatory compliance mandates override cost concerns, while emerging market operators in Latin America and Southeast Asia demonstrate acute sensitivity to total cost of ownership and financing structure.
United States
The Permian Basin and Gulf Coast corridor generate concentrated demand for integrity management platforms as operators retrofit aging midstream infrastructure. PHMSA enforcement of 49 CFR Part 195 compels automated hazard identification workflows across Texas and Louisiana pipeline networks. Houston anchors the domestic vendor ecosystem where specialized engineering workforces maintain decades of SCADA protocol expertise.
Germany
Industrial operators along the Rhine corridor prioritize emissions-monitoring module integration under EU Green Deal methane performance standards. The F-Gas Regulation forces continuous leak detection with quantified reporting capabilities across Bavarian and North Rhine-Westphalian transmission networks. Munich-based engineering consultancies drive adoption of digital twin-enabled predictive maintenance suites for cross-border gas interconnectors.
Canada
Alberta's oil sands and British Columbia's coastal export terminals require remote infrastructure monitoring solutions for rupture mitigation in isolated terrain. The country's national energy regulator mandates traceable software workflows for hazard identification comparable to US PHMSA standards. Calgary concentrates specialized control systems engineering talent that sustains legacy protocol maintenance for SCADA-dependent operators.
Brazil
Deepwater pre-salt development off Rio de Janeiro accelerates flow assurance software adoption where subsea infrastructure complexity demands predictive modeling. The national petroleum regulator imposes integrity management requirements that mirror international best practices for offshore pipeline safety. The Campos Basin serves as the primary demand cluster where integrated majors deploy sensor-software packages for subsea transport corridors.
Saudi Arabia
Master gas system expansion and strategic storage initiatives drive demand for dispatch optimization and batch sequencing software across the Eastern Province. The national hydrocarbon regulator enforces pipeline integrity standards aligned with API recommended practices for high-pressure transmission networks. Dhahran and Jubail Industrial City anchor deployment of GIS-enabled asset management for corridor integrity visualization in arid terrain.
Pipeline Transportation Software Market Competitive Landscape
Capability concentration sits with engineering-heavy incumbents possessing decades of installed-base loyalty; scale advantage sits with diversified industrial conglomerates leveraging cross-sector digital portfolios. The vendor base stratifies into three tiers: legacy SCADA specialists defending maintenance revenue, diversified automation platforms bundling pipeline modules, and cloud-native entrants attacking midstream logistics SaaS. Consolidation pressure intensifies as compliance mandates favor vendors with certified cybersecurity frameworks and established regulator relationships. Dominant competitive moves include strategic partnerships between automation hardware suppliers and cloud infrastructure providers, plus portfolio diversification into adjacent water and chemical transport verticals.
Within the diversified industrial tier, Siemens AG and Schneider Electric SE exemplify platform-scale competitors leveraging cross-sector digital portfolios to anchor long-term service contracts. Emerson Electric Co. occupies a specialized position representing the flow assurance archetype in deepwater and unconventional transport corridors. These three companies illustrate how vendor positioning fragments between comprehensive automation platforms and targeted engineering specialties.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric SE |
| ABB Ltd. |
| Emerson Electric Co. |
| Trimble Inc. |
| Esri |
| Alstom SA |
| Rockwell Automation, Inc. |
| FMC Technologies, Inc. |
| Others |
Value Network & Pricing Analysis
Houston's concentration of SCADA engineering talent and legacy protocol expertise anchors North American pricing power for pipeline control systems, compressing margins for vendors without established service footprints while elevating premiums for compliance-certified platforms.
Pricing Analysis
Embedded predictive maintenance contracts and long-term service agreements drive lifetime value beyond initial software licenses. Three-tier pricing structure across enterprise, mid-market, and entry-level deployments separates operators by integration complexity and regulatory exposure. Pricing pressure stems from cloud-native entrants undercutting perpetual-license incumbents with SaaS alternatives. Midstream logistics firms exhibit highest price sensitivity due to cash-flow constraints, while integrated majors prioritize compliance certification over cost.
Supply Chain Analysis
Flex, Jabil, and Sanmina hold contract manufacturing capacity for industrial edge computing hardware feeding pipeline control deployments. Component sourcing concentrates in Taiwan for semiconductors, Mexico for electromechanical assemblies, and Germany for precision sensors. Single-source vulnerability runs through specialized FPGA suppliers for millisecond-interval processing. Distribution runs through direct vendor-operator relationships and systems integrators serving Permian Basin and North Sea corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring-revenue service layers now expand faster than perpetual license sales, transforming vendor economics toward long-term contract attachment and predictive analytics subscriptions.
For Market Incumbents: Build switching-cost moats through digital twin integration that embeds operators' asset data into proprietary simulation environments. Deepen backward integration into edge hardware manufacturing to secure supply continuity against semiconductor allocation constraints. Defend against cloud-native entrants by certifying hybrid architectures for NERC CIP compliance, leveraging decades of regulator relationships that newcomers cannot replicate. For New Entrants and Emerging Players: Mid-market logistics firms in the Marcellus and Utica shale regions represent the most penetrable entry point, as these operators prioritize operational expenditure treatment over capital-intensive legacy migrations. API-first platforms with rapid tenant onboarding capabilities address third-party operator fragmentation. Lead with carbon-accounting modules that anticipate EU CSRD and emerging SEC climate disclosure requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with established predictive maintenance service tiers and multi-year SCADA maintenance contracts. Long-term viability favors platforms with certified cybersecurity frameworks and documented PHMSA compliance workflows. Monitor NERC CIP certification timelines as an inflection indicator for procurement cycle normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures enable rapid carbon-accounting module deployment for EU Green Deal compliance. |
| Strategic Partnership | Automation hardware suppliers ally with cloud infrastructure providers to accelerate hybrid edge-cloud deployments. |
| Acquisition of Specialist Firm | GIS software specialists add geospatial risk visualization capabilities for corridor integrity management. |
| Geographic Expansion | Deepwater expertise from North Sea corridors transfers to Brazil's pre-salt subsea infrastructure demands. |
| Product Launch | Emissions-monitoring modules address F-Gas Regulation mandates for continuous leak detection reporting. |
Research Methodology
Desk research of regulatory filings from PHMSA and EU agencies, vendor technical documentation, and integrity management program disclosures preceded structured interviews with pipeline control engineers, midstream procurement officers, SCADA integration specialists, and cybersecurity compliance leads. Primary fieldwork across Houston, Calgary, and Aberdeen control centers validated secondary estimates of installed-base loyalty and replacement cycle timing. Bottom-up segmentation modeling triangulated against top-down energy infrastructure spending forecasts.
Assumptions held regulatory enforcement intensity and hydrocarbon transport demand constant across the projection horizon while varying cloud adoption rates and emissions-monitoring module penetration. Segmentation dimensions included deployment architecture, operator type, technology layer integration, and regional regulatory framework. CAGRs derived from fitted growth curves applied to disclosed vendor contract values and operator procurement patterns. Subsea infrastructure complexity and methane performance standard enforcement served as industry-specific demand drivers.
Stress conditions across commodity price volatility, cybersecurity incident frequency, and regulatory timeline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions and risk factors including legacy system entrenchment delays and talent scarcity constraints. Quarterly review of PHMSA enforcement actions, NERC CIP certification backlogs, and EU F-Gas Regulation implementation progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Mexico Cold Chain Logistics Market
Transportation & Logistics
Road Transport Refrigeration Equipment Market
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
Slovakia Road Freight Transport Market
Transportation & Logistics
Japan Cold Chain Logistics Market
Transportation & Logistics
Latin America Cross Border Road Freight Market
Transportation & Logistics
United Kingdom Warehousing and Distribution Logistics Market
Transportation & Logistics
United States Short Haul Road Freight Transport Market
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Asia Pacific Road Freight Transport Market
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
Inland Water Freight Transport Market
Transportation & Logistics
Malaysia Domestic CEP Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
Road Haulage Market
Transportation & Logistics
Colombia Road Freight Transport Market