
 Same Day Delivery Service Market | 2026-2036
Same Day Delivery Service Market Size, Share, and Industry Trends Forecast 2026-2036
Same Day Delivery Service Market Insights
Small and mid-sized retailers is collapsing as the dominant buyer archetype in same-day delivery, with enterprise e-commerce platforms and healthcare systems capturing disproportionate volume growth. Amazon leverages its captive logistics infrastructure to control fulfillment costs across dense metro corridors. FedEx anchors its same-day portfolio through specialized temperature-controlled and time-definite services for healthcare clients. DoorDash competes aggressively in the restaurant and grocery verticals, extending its driver network into non-food retail during off-peak hours.
Same day delivery service constitutes a time-bound logistics operation where parcels move from seller to recipient within a single calendar day, typically requiring real-time route optimization algorithms and distributed micro-fulfillment nodes positioned within fifteen kilometers of target populations. The primary commercial purpose centers on reducing cart abandonment rates and capturing premium willingness-to-pay from convenience-oriented consumers. Express delivery and same-day delivery segments within service type concentrate margin pools where guaranteed delivery windows command surcharges, while standard delivery remains a volume-driven, lower-yield category. Fleet services and crowdsourced delivery dominate delivery method composition, though bicycle couriers occupy niche urban corridors with congestion pricing and low-emission zone regulations.
The EPA and DOT in the United States impose emissions and hours-of-service rules that directly shape fleet composition and driver availability for same-day operators. The EU Green Deal and F-Gas Regulation in Europe mandate progressive decarbonization of commercial transport, forcing logistics providers to accelerate electric vehicle procurement or face zone-based access restrictions. Stakeholders must monitor how divergent national enforcement timelines for zero-emission delivery zones fragment cross-border network planning and capital allocation priorities.
Market Dynamics
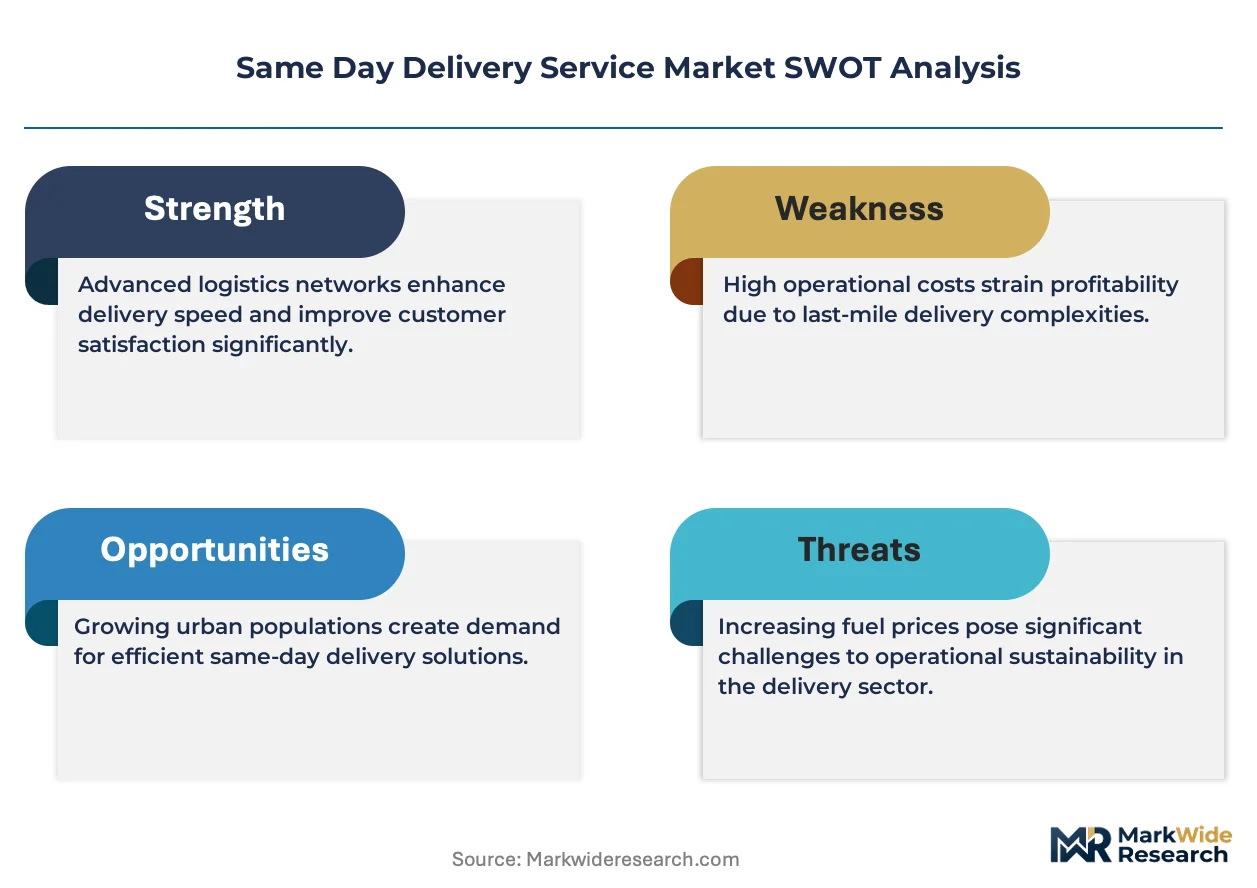
Same-day delivery networks face acute pressure from the EU Green Deal's zero-emission zone mandates, which force fleet operators to accelerate electric vehicle conversion while maintaining cost-competitive service levels in dense urban corridors.
Growth Catalysts
- EU Green Deal decarbonization mandates:National zero-emission delivery zones in Germany, France, and the Netherlands compel logistics providers to electrify fleets, creating demand for charging infrastructure and route optimization software.
- E-commerce platform consolidation:Enterprise marketplaces now capture disproportionate volume growth as small and mid-sized retailers lose share, concentrating demand into fewer high-volume contracts.
- Healthcare cold-chain expansion:Temperature-controlled same-day services for biologics and vaccines generate premium-margin opportunities as hospital systems outsource logistics to specialized operators.
Market Restraints
- Lithium-ion battery supply concentration:Dependence on Chinese cell manufacturers creates input cost volatility and geopolitical exposure for fleet electrification programs.
- Last-mile labor cost inflation:Driver availability constraints in dense European metros push wage rates upward, compressing unit economics for standard delivery tiers.
- Cross-border regulatory fragmentation:Divergent national enforcement timelines for zero-emission zones fragment network planning and capital allocation priorities across EU member states.
Strategic Opportunities
- Micro-fulfillment node densification:Urban real estate within fifteen kilometers of target populations remains underdeveloped in secondary French and Italian cities, offering first-mover positioning.
- Bicycle courier corridor capture:Low-emission zone regulations in London, Amsterdam, and Copenhagen create protected market niches for zero-emission delivery methods.
- Healthcare system outsourcing:Hospital consolidation trends in Germany and Switzerland generate demand for specialized time-definite and temperature-controlled logistics services.
Industry Challenges
- Route algorithm talent scarcity:Real-time optimization systems require machine learning engineers with logistics domain expertise, a skill combination concentrated in Berlin and Amsterdam tech clusters.
- Legacy warehouse management integration:Micro-fulfillment nodes must interface with existing enterprise resource planning systems, creating data synchronization friction and implementation delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Same Day Delivery Service Market |
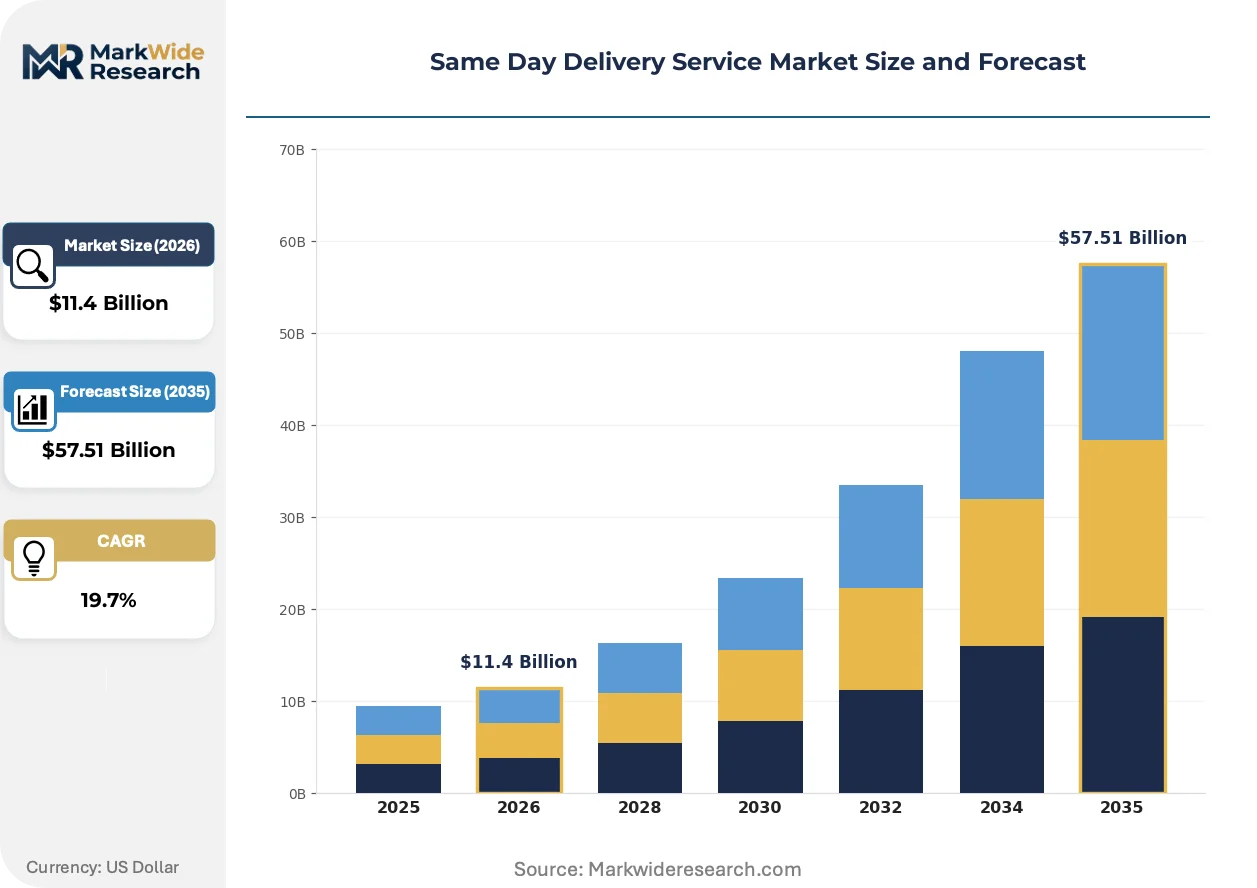
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $57.51 Billion |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Premium Delivery, Standard Delivery, Same Day Delivery End User: E-Commerce, Retailers, Restaurants, Healthcare Delivery Platform: Mobile Apps, Web Platforms, Third-Party Services, In-House Logistics Delivery Method: Crowdsourced Delivery, Fleet Services, Drones, Bicycle Couriers |
| Companies Covered | DHL Express, Instacart, Amazon, Nuro, DoorDash, FedEx, OnTrac, Veho, United Parcel Service of America, Inc. (UPS), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Same Day Delivery Service Market Trends and Innovations
Operational technology in same-day delivery is compressing fulfillment windows through distributed inventory positioning and predictive demand algorithms that anticipate order patterns before purchase completion.
Autonomous sorting robotics is miniaturizing parcel handling equipment for deployment in urban micro-fulfillment nodes. E-commerce platforms with captive logistics infrastructure are adopting these systems fastest, typically achieving full deployment within eighteen months. The technology is miniaturizing the footprint required for same-day processing, enabling conversion of small-format retail spaces into fulfillment points.
The EU F-Gas Regulation and national emissions standards are accelerating refrigerant transitions in temperature-controlled delivery fleets. Cold-chain operators must retrofit or replace vehicles using hydrofluorocarbon-based systems, compressing equipment replacement cycles. Healthcare and grocery verticals face the steepest compliance timelines, with Germany's KBA enforcing the strictest certification requirements.
Hospital procurement departments now unbundle logistics from product purchasing, awarding standalone same-delivery contracts to specialized operators. This displaces traditional distributor-integrated models in Switzerland and the Netherlands. German hospital systems exhibit the fastest adoption, driven by cost transparency mandates in regional healthcare purchasing alliances.
Same Day Delivery Service Market Segmentation
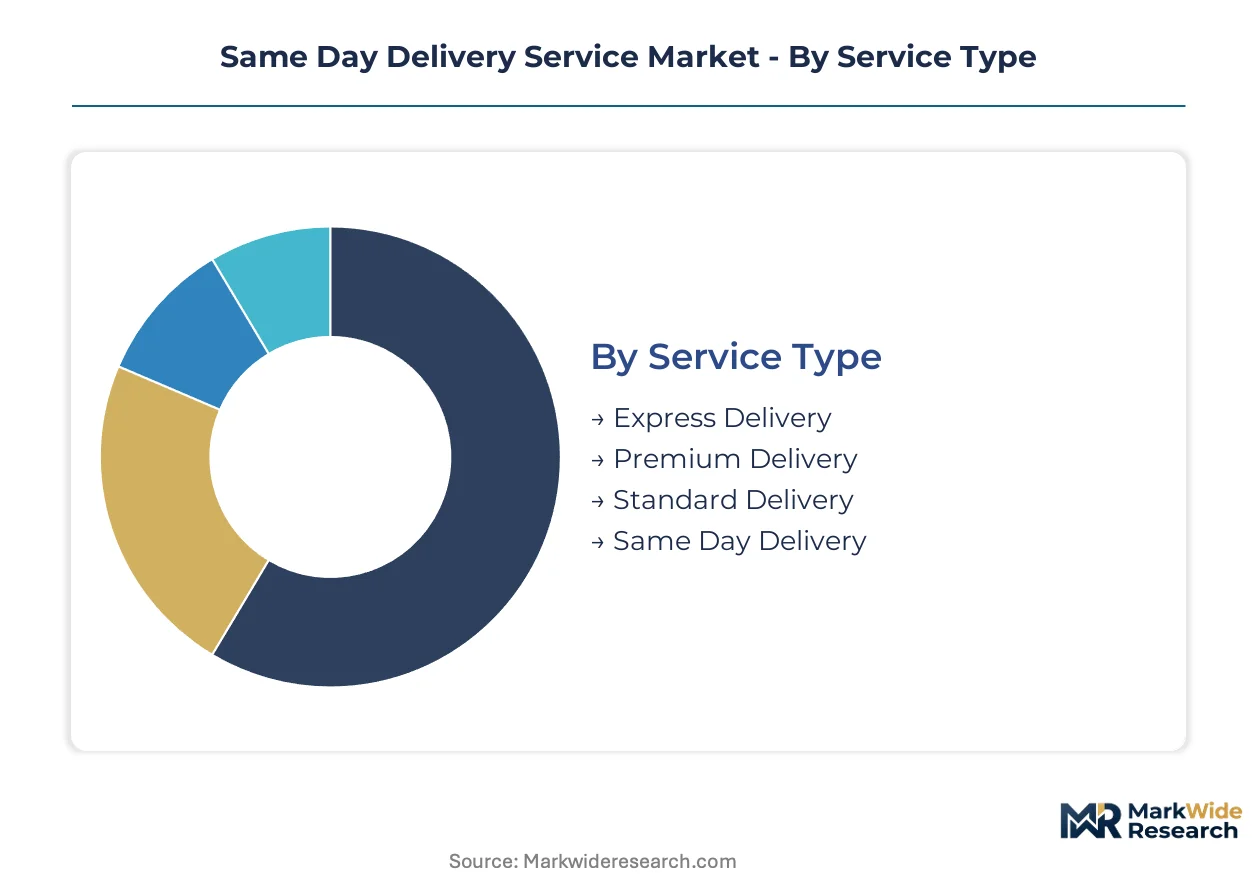
Same-day delivery operators configure service portfolios around regulatory compliance thresholds, customer willingness-to-pay gradients, and fleet technology constraints. Segment boundaries shift as EU emissions mandates force method substitutions and as enterprise buyers consolidate volume into fewer contractual relationships.
Service Type:
EU Green Deal enforcement timelines differentiate service tiers through zone-access privileges and emissions certification requirements, with premium windows commanding surcharges in zero-emission corridors.
- Express Delivery:Time-definite windows under four hours require real-time route optimization and distributed micro-fulfillment positioning. Hospital systems in Germany and Switzerland concentrate demand for biologics transport, where KBA refrigerant certifications and temperature guarantees justify surcharges.
- Same Day Delivery:Calendar-day fulfillment without hour-definite commitment operates through hybrid fleet models balancing cost and speed. E-commerce platforms in dense Dutch and Belgian urban corridors capture volume here, leveraging fifteen-kilometer fulfillment radii to meet consumer immediacy expectations without express infrastructure.
- Premium Delivery:White-glove handling with appointment scheduling and installation support.
- Standard Delivery:Next-day or longer windows without same-day guarantees; volume-driven, lower-yield category.
Established volume favors Standard Delivery; emerging adoption favors Express Delivery.
End User:
Customer procurement sophistication determines contract structure, with healthcare systems unbundling logistics from product purchasing while retailers surrender fulfillment control to platform intermediaries.
- E-Commerce:Enterprise marketplaces with captive logistics infrastructure internalize fulfillment to control cost and data. Amazon's metro corridor density and FedEx's healthcare specialization illustrate divergent strategies for volume capture.
- Healthcare:Hospital consolidation in Germany and Switzerland generates standalone same-day contracts for temperature-controlled biologics and vaccine distribution, displacing traditional distributor-integrated models.
- Retailers:Small and mid-sized merchants losing share to platform consolidation; residual demand concentrates in specialty categories requiring brand-controlled experience.
- Restaurants:DoorDash's driver network extension into off-peak retail delivery illustrates vertical overflow strategies in food-service logistics.
Procurement concentration favors E-Commerce; regulatory compliance complexity favors Healthcare.
Delivery Platform:
Technology ownership structure determines data control and margin retention, with in-house systems requiring capital commitment but capturing optimization value.
- Mobile Apps:Consumer-facing interfaces with real-time tracking and predictive arrival notifications dominate restaurant and grocery verticals. Dense urban adoption in London and Amsterdam supports crowdsourced driver recruitment.
- In-House Logistics:Captive fleet and warehouse networks enable Amazon to compress fulfillment windows without third-party margin leakage. Eighteen-month deployment cycles for autonomous sorting robotics accelerate in this segment.
- Web Platforms:Browser-based ordering interfaces with enterprise procurement integration for healthcare and B2B contracts.
- Third-Party Services:Aggregator models aggregating demand across merchants without asset ownership; margin pressure from platform fees and driver wage inflation.
Margin retention favors In-House Logistics; network scale favors Third-Party Services.
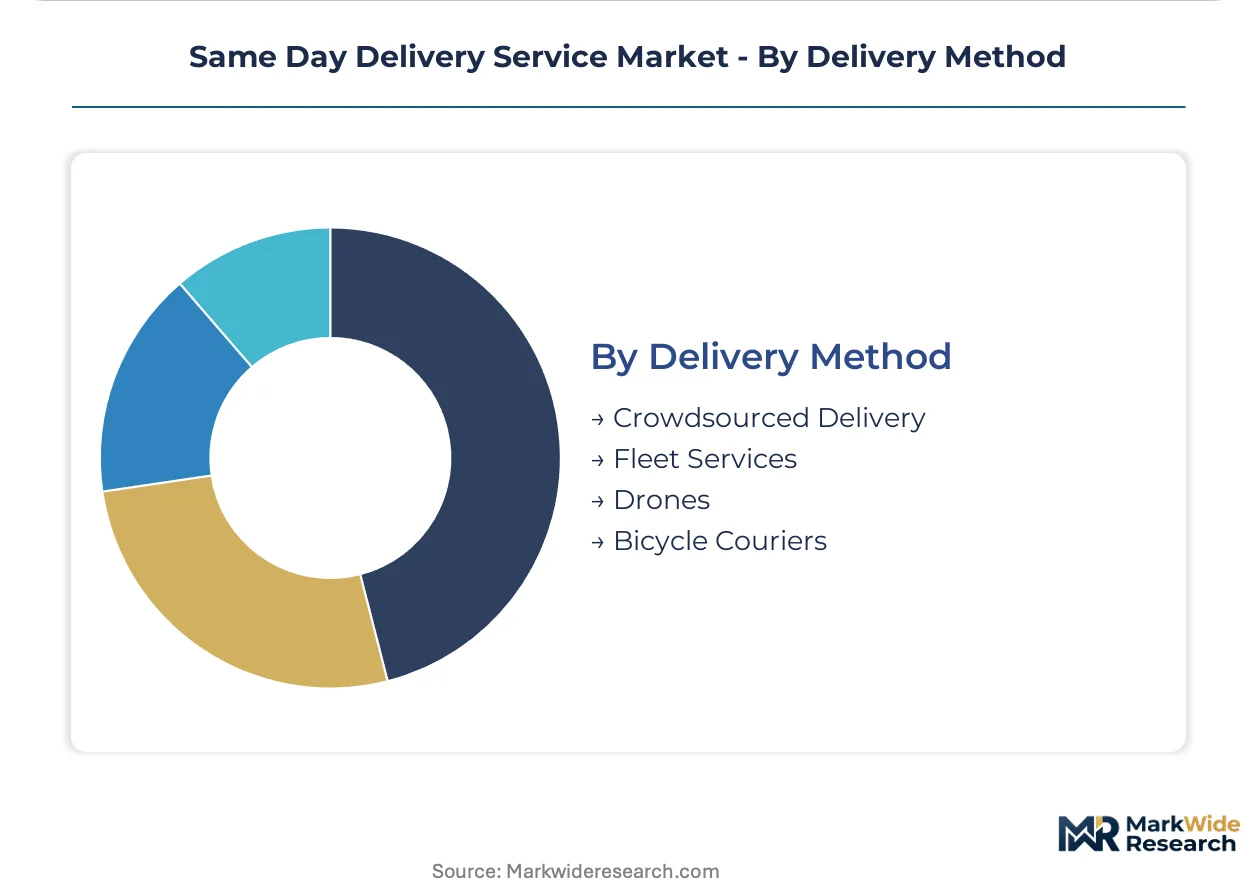
Delivery Method:
EU zero-emission zone mandates and F-Gas refrigerant regulations are forcing method substitutions, with electrification timelines varying by vehicle class and urban access restrictions.
- Fleet Services:Company-owned electric and conventional vehicles operating on scheduled routes. German KBA certification requirements for cold-chain equipment compress replacement cycles in healthcare and grocery verticals.
- Bicycle Couriers:Zero-emission delivery in London, Amsterdam, and Copenhagen low-emission zones with congestion pricing protection. Niche positioning in last-mile segments under fifteen kilometers.
- Crowdsourced Delivery:Gig-economy driver networks scaling flexibly with demand peaks; labor cost inflation in dense European metros compresses unit economics.
- Drones:Experimental deployment for lightweight parcels in regulatory test corridors; FAA and EASA airspace restrictions limit commercial scaling.
Regulatory compliance favors Bicycle Couriers; capacity elasticity favors Crowdsourced Delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise e-commerce platforms and healthcare systems concentrate procurement power in Germany, the United States, the Netherlands, the United Kingdom, and Switzerland, where dense urban networks and strict delivery-time guarantees create favorable unit economics for same-day fulfillment.
Germany
Hospital consolidation and biologics cold-chain expansion drive demand for temperature-controlled same-day services. The KBA enforces strict refrigerant certification requirements under EU F-Gas Regulation, compressing equipment replacement cycles. Berlin and Hamburg anchor the densest micro-fulfillment networks, with fifteen-kilometer fulfillment radii covering majority urban populations.
United States
Enterprise marketplaces with captive logistics infrastructure internalize fulfillment to control cost and data across metro corridors. The EPA and DOT impose emissions and hours-of-service rules that directly shape fleet composition and driver availability. Amazon's distribution density in Seattle and Los Angeles exemplifies metro corridor optimization strategies.
Netherlands
Dutch urban corridors concentrate e-commerce platform volume through hybrid fleet models balancing cost and speed. National zero-emission delivery zones in Amsterdam and Rotterdam compel logistics providers to electrify fleets, creating demand for charging infrastructure. Randstad logistics clusters lead route optimization software deployment for calendar-day fulfillment.
United Kingdom
London's congestion pricing and low-emission zone regulations create protected market niches for bicycle courier networks. The country's national emissions regulator enforces progressive decarbonization timelines for commercial transport. Birmingham and Manchester secondary cities show underdeveloped micro-fulfillment node real estate, offering first-mover positioning.
Switzerland
Hospital procurement departments unbundle logistics from product purchasing, awarding standalone same-day contracts to specialized operators. Swissmedic maintains strict certification requirements for temperature-controlled pharmaceutical transport. Zurich and Geneva healthcare purchasing alliances drive fastest adoption of cost transparency mandates in regional logistics outsourcing.
Same Day Delivery Service Market Competitive Landscape
Player mix skews toward integrated logistics conglomerates and platform-native delivery networks, with tiered specialization across temperature-controlled healthcare, grocery verticals, and general merchandise. The structure concentrates volume into three strategic archetypes: captive infrastructure operators controlling end-to-end fulfillment, specialized healthcare cold-chain providers, and crowdsourced gig-economy networks scaling flexibly with demand peaks. Dominant competitive moves include M&A to secure micro-fulfillment real estate and strategic partnerships to extend driver network coverage into off-peak retail hours.
Within the integrated logistics tier, DHL Express and FedEx exemplify archetypes diverging by vertical focus, with the former anchoring cross-border express infrastructure and the latter specializing in healthcare time-definite services. Amazon occupies a position representing captive platform logistics, compressing fulfillment windows through distributed inventory positioning without third-party margin leakage. DoorDash sits within the crowdsourced network archetype, extending restaurant and grocery driver capacity into non-food retail during off-peak demand periods.
| Leading Market Players |
|---|
| DHL Express |
| Instacart |
| Amazon |
| Nuro |
| DoorDash |
| FedEx |
| OnTrac |
| Veho |
| United Parcel Service of America, Inc. (UPS) |
| Others |
Pricing and Supply Chain Analysis
Electric vehicle fleet conversion replacing diesel vans simultaneously redistributes supply geography toward battery manufacturing clusters and compresses pricing power for legacy operators facing EU Green Deal compliance deadlines. This substitution dynamic forces same-day delivery networks to renegotiate cost structures around charging infrastructure density and zero-emission zone access privileges.
Pricing Analysis
Cost-plus contracts with fuel surcharge indexation dominate enterprise e-commerce agreements, though healthcare cold-chain services command fixed premiums tied to KBA refrigerant certification tiers. Price differentiation hinges on temperature guarantee levels and delivery window definiteness, with express biologics transport showing lowest price sensitivity among hospital procurement departments. Pricing pressure stems from lithium-ion battery input volatility and last-mile wage inflation in dense European metros, squeezing standard delivery margins most acutely.
Supply Chain Analysis
Inventory positioning within fifteen-kilometer fulfillment radii determines lead-time competitiveness across German and Dutch urban corridors. Supply concentration centers on Chinese lithium-ion cell manufacturers, German KBA-certified refrigeration equipment suppliers, and Netherlands-based route optimization software providers. Raw material dependencies include cobalt, lithium carbonate, and rare earth magnets for electric drivetrains. Single-source vulnerability in Chinese battery supply creates tariff and geopolitical exposure. Distribution runs through micro-fulfillment nodes integrated with enterprise resource planning systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Same-day delivery constitutes a defensive-moat market where regulatory entrenchment through zero-emission zone compliance creates switching costs that lock in enterprise healthcare contracts.
For Market Incumbents: Consolidate micro-fulfillment real estate in secondary French and Italian cities before first-mover positioning expires. Acquire route optimization software capabilities to offset machine learning engineer scarcity in Berlin and Amsterdam tech clusters. Defensive urgency centers on lithium-ion supply diversification as Chinese cell manufacturer concentration intensifies input cost volatility. For New Entrants and Emerging Players: Lead with bicycle courier corridor capture in London, Amsterdam, and Copenhagen low-emission zones where congestion pricing protects zero-emission delivery niches. Target underdeveloped secondary city micro-fulfillment positioning in Birmingham and Manchester. White-space penetration runs through healthcare system outsourcing in Germany and Switzerland where hospital consolidation unbundles logistics from product purchasing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional cold-chain specialists holding KBA certifications and German hospital system contracts. Long-term viability over a multi-year horizon favors operators with captive electric fleet infrastructure and healthcare vertical specialization. The signal to watch is EU member state divergence in zero-emission zone enforcement timelines fragmenting cross-border network scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Node Densification | Urban real estate within fifteen-kilometer radii captures same-day fulfillment economics in underserved secondary cities. |
| Electric Fleet Conversion | EU Green Deal zero-emission zone mandates compel logistics providers to electrify or face access restrictions. |
| Healthcare Cold-Chain Specialization | KBA-certified temperature-controlled services capture premium margins from German hospital procurement alliances. |
| Route Optimization Software Acquisition | Machine learning capabilities with logistics domain expertise concentrate competitive advantage in Berlin and Amsterdam clusters. |
| Bicycle Courier Network Expansion | Low-emission zone regulations in London and Copenhagen create protected market niches for zero-emission delivery. |
Research Methodology
The analysis maps express delivery, same-day delivery, and cold-chain service tiers, each validated through fleet operations directors, hospital procurement managers, e-commerce logistics executives, and route optimization software engineers. Primary interview findings triangulate against secondary sources including EU Green Deal regulatory filings, KBA vehicle certification databases, Dutch customs trade data, and SEC filings from listed logistics operators. Bottom-up volume modeling and top-down market sizing cross-validate segment outputs.
Consistency checks against external benchmarks validated volume and value projections across the modeling period. The analytical framework segments by service type, end user archetype, delivery platform ownership structure, and delivery method technology. CAGRs derive from trend extrapolation of fleet electrification timelines, e-commerce platform consolidation patterns, and healthcare outsourcing adoption curves. Industry-specific forecast inputs include zero-emission zone rollout schedules and lithium-ion battery cost trajectories.
The analysis sits within stated boundaries; outcomes outside EU regulatory enforcement timelines or Chinese supply chain stability assumptions would require recalibration. Forecasts reflect documented assumptions about electrification capital deployment and hospital procurement unbundling velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
Kazakhstan Freight and Logistics Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
Turkey Third Party Logistics (3PL) Market
Logistics and Shipping
Renewable Resources Logistics Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
Dry Van Container Market
Logistics and Shipping
Australia Mining Logistics Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
Middle East and Africa Courier Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
South America Freight and Logistics Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United States Courier, Express and Parcel (CEP) Market