
 Trade-In and Buy-Back Logistics Programs Management Market | 2026-2036
Trade-In and Buy-Back Logistics Programs Management Market Size, Share, and Industry Trends Forecast 2026-2036
Trade-In and Buy-Back Logistics Programs Management Market Insights
Market Context
Multi-source outsourcing of reverse logistics is hardening as the dominant sourcing pattern among OEMs and telecom operators seeking to decouple device recovery from core manufacturing. Assurant leverages its insurance-backed asset protection model to secure long-term operator contracts across North America and Europe. Ingram Micro Lifecycle anchors global scale through facility networks that process millions of units annually for enterprise and consumer channels. Foxway competes on Nordic and Central European density where carrier trade-in volumes sustain specialized refurbishment operations.
Technical Definition and Segment Structure
Trade-In and Buy-Back Logistics Programs Management encompasses the end-to-end coordination of device recovery, condition assessment, data sanitization, refurbishment grading, and channel redistribution for pre-owned electronics, typically processing units through ISO 14001-certified facilities with chain-of-custody documentation. The practice serves consumer electronics brands and telecom operators seeking to recover residual value from returned hardware while meeting extended producer responsibility obligations. Service model segmentation shows end-to-end management commanding premium engagement terms due to single-accountability risk transfer, while reverse logistics as a standalone module attracts price-sensitive retailers with existing refurbishment partnerships. Client type dynamics reveal telecom operators generating the highest unit velocity through subsidized upgrade cycles, whereas e-commerce platforms represent the fastest-growing intake channel as marketplace recommerce integrations expand.
Regulatory Framework and Outlook
The EU WEEE directive and REACH substance restrictions shape product design and recycling protocols across European operations, while the EPA's R2 and e-Stewards certification frameworks govern domestic U.S. processing standards for responsible electronics recycling. Japan's METI promotes resource circulation through its Home Appliance Recycling Law, creating compliance-driven demand for documented reverse logistics in East Asian supply chains. Stakeholders must monitor evolving extended producer responsibility expansions into battery-containing devices and the interoperability demands these regulations place on tracking systems across multi-national program footprints.
Market Dynamics
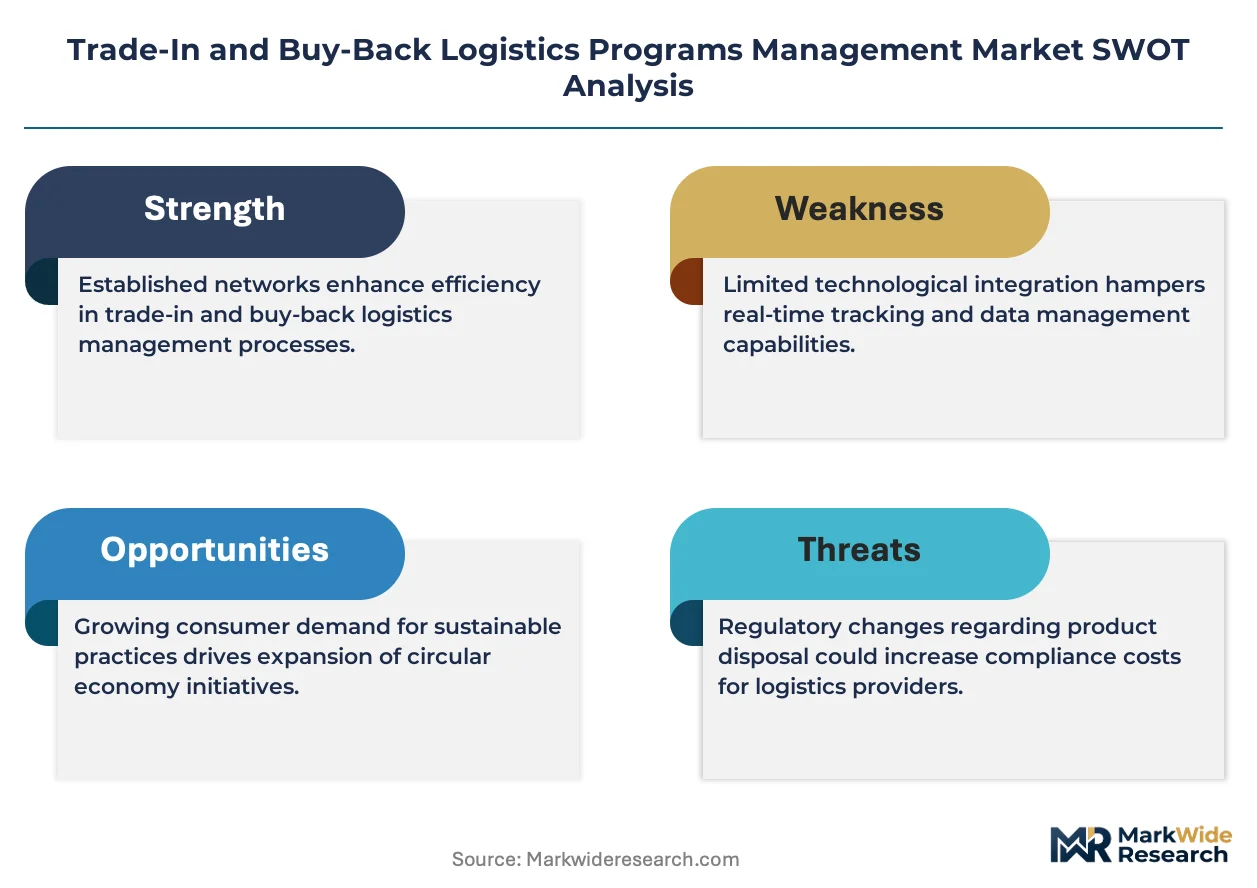
Carrier-subsidized upgrade cycles are compressing device replacement timelines, forcing OEMs and operators to externalize reverse logistics to specialized providers capable of processing millions of units through certified refurbishment pipelines.
Growth Catalysts
- EU WEEE Directive:Extended producer responsibility mandates compel electronics manufacturers to fund collection infrastructure, creating guaranteed revenue streams for logistics providers managing compliance documentation and chain-of-custody tracking.
- 5G handset refresh:Telecom operators in Germany, Japan, and the United States are accelerating trade-in volumes as consumers upgrade to 5G-compatible devices, requiring grading and resale pipeline management at industrial scale.
- Recommerce platform integration:E-commerce marketplaces are embedding device recovery APIs directly into checkout flows, generating new intake channels that bypass traditional retail collection points.
Market Restraints
- Refurbishment labor costs:Skilled technician wages in Central European processing hubs are rising faster than automation can offset, squeezing margins on mid-grade device restoration.
- Component supply concentration:Replacement display and battery sourcing depends heavily on Chinese manufacturing clusters, exposing refurbishment operations to tariff volatility and logistics disruption.
- Data sanitization certification delays:NIST 800-88 and ADISA accreditation timelines stretch 6-12 months, creating bottlenecks for providers seeking to handle enterprise device returns with liability protection.
Strategic Opportunities
- India's informal sector formalization:The country's emerging e-waste rules and PLI scheme for electronics manufacturing create openings for certified reverse logistics operators to replace unregulated collection networks.
- Battery-containing device expansion:E-scooters, power tools, and IoT hardware are entering trade-in programs, requiring new grading protocols and hazardous material handling capabilities that incumbent processors can monetize.
- Blockchain-IoT convergence:Immutable device history tracking combined with sensor-based condition verification enables premium pricing for certified pre-owned electronics with documented provenance.
Industry Challenges
- Automated grading accuracy:Machine vision systems still fail to detect subtle cosmetic damage and functional degradation that human technicians catch, requiring hybrid processing models that limit throughput scaling.
- Legacy ERP integration:Carrier billing systems and OEM warranty databases use incompatible data formats, forcing expensive middleware development to synchronize trade-in credit issuance with inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trade-In and Buy-Back Logistics Programs Management Market |
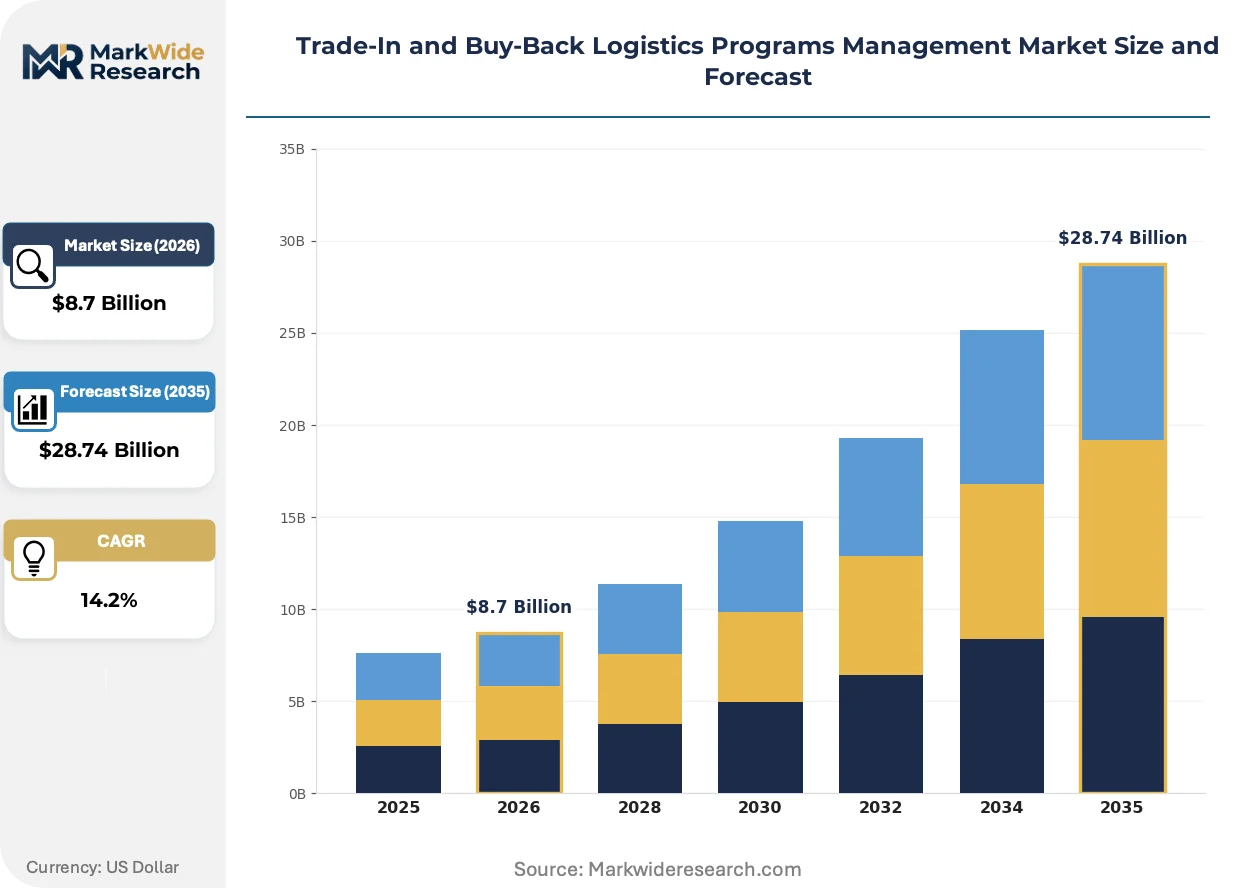
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Program Type: Trade-In, Buy-Back, Recommerce, Return Management, Refurbishment, Warranty Exchange Service Model: End-to-End Management, Reverse Logistics, Inventory Optimization, Asset Recovery, Performance Analytics, Customer Support Client Type: Consumer Electronics Brands, Telecom Operators, Retail Chains, E-Commerce Platforms, Warranty Providers, Leasing Agencies Technology Utilization: Blockchain, IoT Tracking, AI Analytics, Cloud Platforms, Mobile Integration, Automated Processing |
| Companies Covered | Assurant, Ingram Micro Lifecycle, Foxway, Recommerce Group, PCS Wireless, Likewize, Alchemy, UPS, CEVA Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trade-In and Buy-Back Logistics Programs Management Market Trends and Innovations
Artificial intelligence is transforming condition assessment from manual technician review to automated optical and functional testing, compressing processing times while standardizing grading consistency across high-volume facilities.
Machine vision systems paired with robotic handling arms are electrifying refurbishment throughput at European and North American processing centers. Ingram Micro and Assurant are deploying these configurations across their facility networks to handle carrier trade-in volumes that exceed 10 million units annually. The technology is electrifying competitive positioning by enabling same-day grading turnaround that manual operations cannot match.
Japan's METI is tightening resource circulation requirements under revised Home Appliance Recycling Law implementing regulations, mandating serialized tracking of precious metal recovery rates. Electronics manufacturers must now submit verified mass-balance documentation for gold, silver, and rare earth elements extracted from returned devices. High-volume smartphone processors in East Asia are responding by investing in automated disassembly lines capable of component-level material accounting.
Enterprise procurement departments are unbundling device lifecycle management from hardware acquisition contracts, creating standalone reverse logistics RFPs with performance-based pricing tied to residual value recovery rates. Financial services and healthcare verticals in Germany and the United States are leading this transition, replacing bundled OEM services with specialist provider relationships that guarantee data destruction certification and environmental compliance documentation.
Trade-In and Buy-Back Logistics Programs Management Market Segmentation
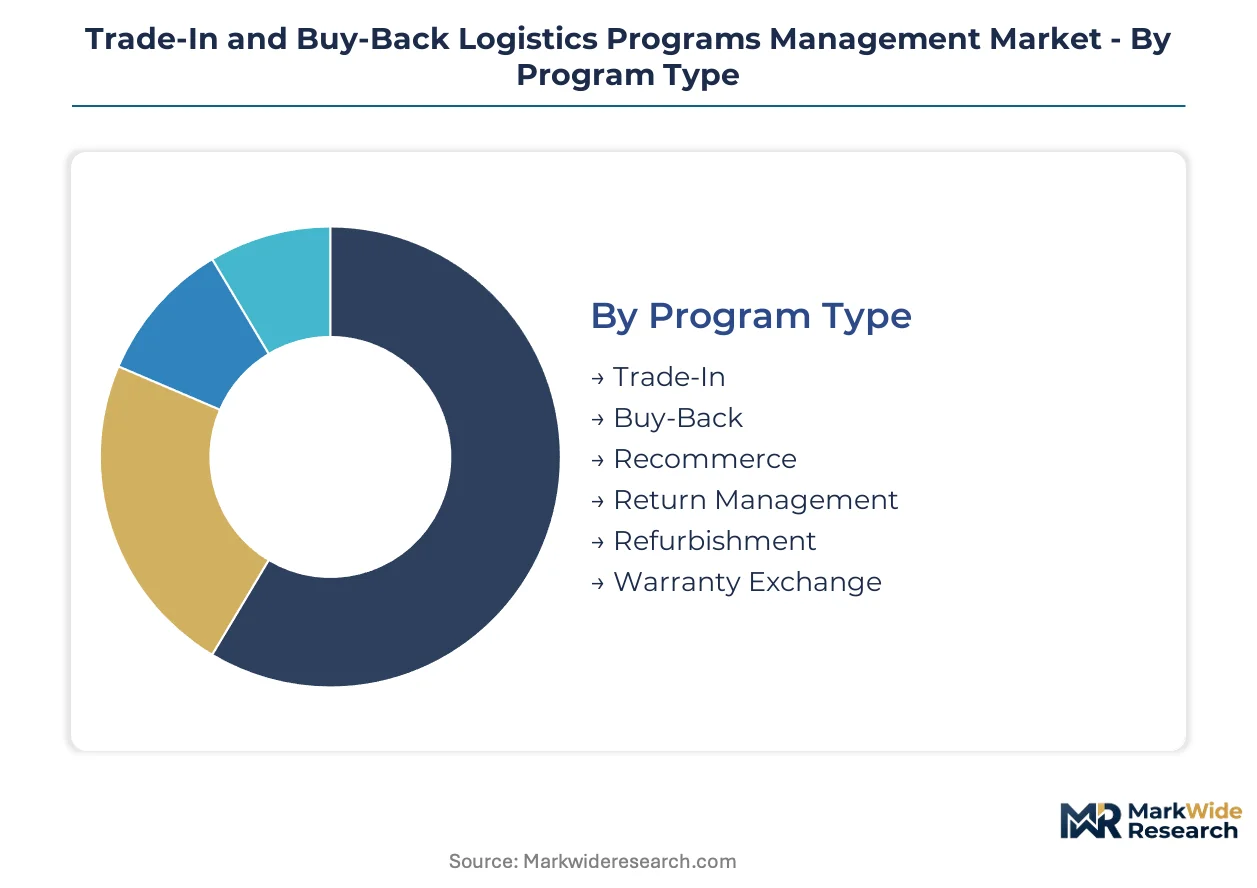
Segmentation in trade-in and buy-back logistics reveals how service providers align capabilities with distinct client risk profiles and operational complexity. Each dimension—program design, service depth, buyer category, and technology deployment—creates specialized competitive arenas with diverging margin structures and contract tenures.
Program Type:
Program architecture separates high-frequency consumer transactions from enterprise asset recovery with vastly different processing economics and compliance documentation requirements.
- Trade-In:Carrier-subsidized upgrade cycles in Germany, Japan, and the United States generate continuous device flows requiring same-day grading turnaround and instant credit issuance. Demand concentrates among telecom operators seeking to lock subscribers into renewal contracts while recovering residual hardware value through certified refurbishment pipelines.
- Buy-Back:Direct OEM purchase programs for end-of-lease enterprise fleets and consumer direct sales impose stricter data sanitization protocols under NIST 800-88 and ADISA standards. Financial services and healthcare verticals in the United States and Germany are unbundling these services from hardware acquisition contracts.
- Recommerce:Marketplace-integrated resale channels embedding recovery APIs into checkout flows.
- Return Management:Reverse logistics for e-commerce platform remorse returns and defective merchandise.
- Refurbishment:Component-level restoration to certified pre-owned standards for channel redistribution.
- Warranty Exchange:Defective unit replacement programs requiring rapid advance-exchange fulfillment.
Trade-In leads volumes today; Recommerce is gaining share fastest.
Service Model:
Service depth determines whether providers capture full program economics or compete as modular specialists in price-sensitive procurement environments.
- End-to-End Management:Single-accountability contracts covering intake through resale with performance-based pricing tied to residual value recovery rates. Enterprise procurement departments in Germany and the United States are issuing standalone RFPs for these arrangements, replacing bundled OEM services with specialist relationships that guarantee data destruction certification and environmental compliance documentation.
- Reverse Logistics:Standalone transportation and warehousing modules attracting retailers with existing refurbishment partnerships but fragmented geographic coverage.
- Inventory Optimization:Dynamic pricing and channel allocation algorithms for secondary market velocity maximization.
- Asset Recovery:Precious metal extraction and component harvesting with serialized mass-balance tracking for Japan's METI reporting requirements.
- Performance Analytics:Residual value forecasting and program ROI measurement dashboards.
- Customer Support:Multi-channel inquiry handling and dispute resolution for trade-in credit issuance.
End-to-End Management commands premium pricing; Reverse Logistics faces steepest price compression.
Client Type:
Buyer sophistication and contract scale vary dramatically between volume-driven telecom operators and emerging e-commerce channel partners.
- Telecom Operators:Subsidized upgrade cycles in Germany, the United States, and Japan generate the highest unit velocity with long-term exclusive contracts. These clients demand industrial-scale processing exceeding 10 million units annually with ISO 14001-certified facilities and chain-of-custody documentation.
- E-Commerce Platforms:Marketplace recommerce integrations are expanding intake channels fastest, bypassing traditional retail collection points through embedded checkout APIs and logistics network partnerships.
- Consumer Electronics Brands:OEM outsourcing of device recovery to decouple reverse logistics from core manufacturing operations.
- Retail Chains:Brick-and-mortar collection points with varying refurbishment capabilities and regional coverage gaps.
- Warranty Providers:Insurance-backed asset protection programs requiring rapid replacement fulfillment and fraud detection.
- Leasing Agencies:Enterprise fleet refresh cycles with structured end-of-term return obligations and residual value guarantees.
Telecom Operators anchor contract value today; E-Commerce Platforms are expanding most quickly.
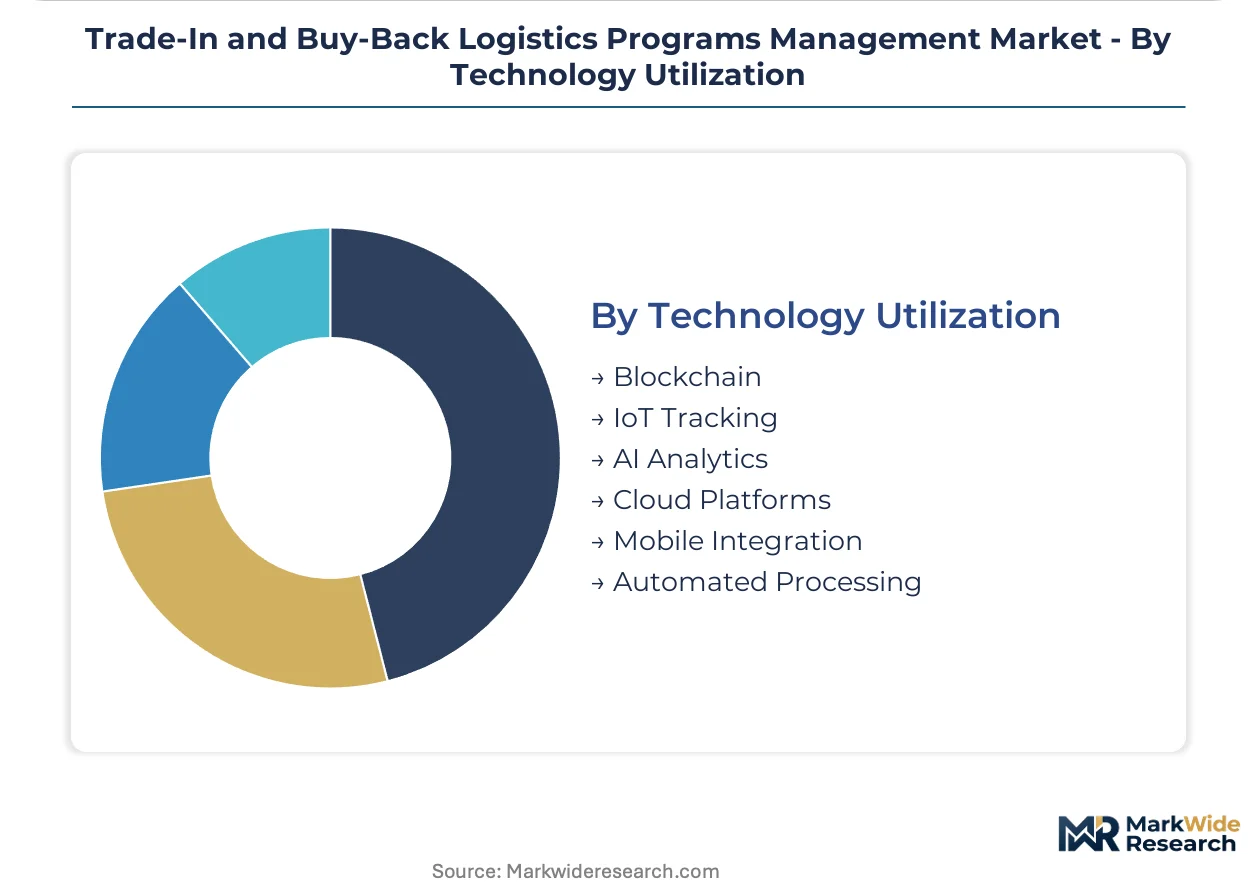
Technology Utilization:
Technology deployment separates automated high-throughput operations from labor-intensive processing with diverging scalability and margin profiles.
- AI Analytics:Machine vision systems paired with robotic handling arms are electrifying refurbishment throughput at European and North American processing centers, enabling same-day grading turnaround that manual operations cannot match. Ingram Micro and Assurant are deploying these configurations across facility networks handling carrier trade-in volumes.
- Blockchain:Immutable device history tracking combined with sensor-based condition verification enables premium pricing for certified pre-owned electronics with documented provenance.
- IoT Tracking:Real-time location and environmental monitoring for high-value enterprise device shipments.
- Cloud Platforms:Centralized program management dashboards integrating carrier billing systems and OEM warranty databases.
- Mobile Integration:Consumer-facing apps for condition self-assessment and trade-in initiation.
- Automated Processing:Robotic disassembly lines for component-level material accounting under Japan's METI resource circulation requirements.
AI Analytics dominates capital deployment today; Blockchain is climbing the fastest as provenance certification gains premium pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier-subsidized upgrade cycles in Germany, Japan, and the United States generate concentrated device flows requiring certified refurbishment infrastructure. National regulations and industrial clustering patterns shape where specialized reverse logistics providers establish processing density.
United States
Telecom operators drive volume through accelerated 5G handset refresh programs. EPA's R2 and e-Stewards certification frameworks govern processing standards for responsible electronics recycling. Dallas-Fort Worth and Atlanta host major grading facilities serving carrier trade-in pipelines exceeding 10 million units annually.
Germany
Extended producer responsibility mandates under the EU WEEE directive compel OEMs to fund collection infrastructure. REACH substance restrictions shape refurbishment protocols and material recovery documentation. Berlin and Munich anchor Central European processing networks with ISO 14001-certified facilities.
Japan
METI's Home Appliance Recycling Law mandates serialized tracking of precious metal recovery rates from returned devices. Resource circulation requirements are tightening under revised implementing regulations. Osaka and Nagoya processing centers invest in automated disassembly lines for component-level material accounting.
India
Emerging e-waste rules and the PLI scheme for electronics manufacturing create formalization opportunities for certified operators. The country's national environmental regulator is expanding compliance documentation requirements. Bengaluru and Delhi-NCR clusters see rising investment in chain-of-custody tracking systems.
United Kingdom
Enterprise procurement departments unbundle device lifecycle management from hardware acquisition contracts. The national data protection authority influences data sanitization certification requirements for financial services verticals. London and Manchester host specialist providers handling enterprise fleet returns with ADISA-accredited destruction protocols.
Trade-In and Buy-Back Logistics Programs Management Market Competitive Landscape
Global majors compete with regional champions across certification density and carrier relationship depth. The vendor base separates into insurance-backed asset protection specialists, facility-scale processors, and Nordic-centric refurbishment operators. Three archetypes dominate: end-to-end program managers commanding premium single-accountability contracts, modular logistics providers competing on transportation cost, and technology-integrated platforms embedding recovery APIs into e-commerce flows. Competitive moves center on M&A for geographic coverage expansion and automation capital deployment for grading throughput.
Within the end-to-end management tier, Assurant and Ingram Micro Lifecycle exemplify divergent scale strategies. Assurant leverages its insurance-backed model to secure long-term operator contracts across North America and Europe. Ingram Micro Lifecycle anchors global scale through facility networks processing millions of units annually. Foxway occupies a position within the regional champion archetype, competing on Nordic and Central European density where carrier trade-in volumes sustain specialized operations.
| Leading Market Players |
|---|
| Assurant |
| Ingram Micro Lifecycle |
| Foxway |
| Recommerce Group |
| PCS Wireless |
| Likewize |
| Alchemy |
| UPS |
| CEVA Logistics |
| Others |
Pricing and Supply Chain Analysis
Skilled refurbishment technician pools in Poland and the Czech Republic anchor Central European processing economics, where labor-cost differentials between these hubs and Western European facilities drive tiered service pricing spreads. OEMs and telecom operators exploit this geographic arbitrage to balance same-day grading mandates against margin compression in mid-grade device restoration.
Pricing Analysis
Input-cost pass-through from rising technician wages and replacement component tariffs shapes contract structures across the market. Per-unit transactional pricing dominates carrier trade-in programs, with price differentiation resting on ISO 14001 certification tier and volume scale commitments. Pricing pressure stems from automation capital deployment lagging behind wage inflation in European processing hubs. Telecom operators exhibit highest price sensitivity due to thin hardware margins on subsidized devices, while enterprise buy-back clients accept premium rates for ADISA-accredited data destruction documentation.
Supply Chain Analysis
Replacement display and battery supply rests on Chinese manufacturing clusters concentrated in Guangdong and Jiangsu provinces. Component sourcing draws from South Korean semiconductor fabricators and Japanese precision electronics suppliers for sensor modules and memory components. Single-source vulnerability around Chinese battery cell production exposes refurbishment operations to tariff volatility and logistics disruption. Distribution runs through carrier-integrated logistics networks for consumer trade-ins and specialized secure transport for enterprise fleet returns requiring chain-of-custody documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where wage differentials between Central European processing hubs and automated North American facilities create service-tier spreads, while regulatory divergence between EU WEEE compliance costs and India's emerging formalization incentives opens operational relocation opportunities.
For Market Incumbents: To counter margin erosion from rising Central European technician wages, deploy machine vision automation at Polish and Czech facilities to compress grading turnaround times below manual benchmarks. Secure backward integration into replacement battery supply through partnerships with South Korean cell manufacturers to insulate against Chinese tariff exposure.
For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing opens a window for certified reverse logistics operators to displace informal collection networks in Bengaluru and Delhi-NCR clusters. Target e-commerce platform recommerce integrations as the most penetrable intake channel, leveraging API-first program architecture to bypass carrier relationship barriers.
For Investors and Strategic Acquirers: Telecom operators are the most active acquirer in this space, seeking captive reverse logistics capabilities to secure subscriber lock-in and residual value recovery. Long-term viability centers on automation scale and certification density rather than geographic coverage alone. Watch NIST 800-88 accreditation timelines as the signal indicating which processors can capture enterprise device return volumes with liability protection.
| Strategic Initiative | Industry Significance |
|---|---|
| Machine Vision Automation Deployment | Enables same-day grading turnaround that manual operations in Polish facilities cannot match. |
| ADISA Accreditation Investment | Unlocks enterprise buy-back contracts with financial services and healthcare verticals in Germany. |
| Blockchain Provenance Tracking | Supports premium pricing for certified pre-owned electronics with immutable device history documentation. |
| Battery Supply Partnership | Reduces tariff exposure from Chinese component concentration through South Korean cell sourcing. |
| Recommerce API Integration | Captures fastest-growing intake channel through embedded checkout flows on e-commerce platforms. |
Research Methodology
Bottom-up trade-in volume modeling reconciled against top-down carrier shipment tracking forms the analytical core of this study. Primary interviews with reverse logistics operations directors, telecom procurement executives, OEM sustainability officers, and refurbishment facility managers combined with secondary validation against EPA R2 certification databases, EU WEEE compliance registries, and METI resource circulation filings. Trade data from customs authorities and carrier annual sustainability disclosures provided cross-reference points for volume triangulation.
Input-output matrices mapped device flow volumes through grading, refurbishment, and resale channels across program type and service model segments. CAGRs derived from regression analysis against 5G handset refresh cycles and extended producer responsibility expansion timelines. Forecast inputs incorporated carrier subsidy policy shifts, automation capital deployment schedules, and regional regulatory enforcement intensity variations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt tariff escalations or accelerated automation adoption curves. Assumptions reflect current regulatory enforcement patterns and carrier contract structures. A small set of triggers—India's e-waste rule implementation pace, EU battery regulation expansion, and NIST accreditation processing delays—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
United States Road Freight Transport Market
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
United States Customs Brokerage Market
Transportation & Logistics
Europe Freight and Logistics Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
Saudi Arabia Land-Based Fuel Transportation Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
Vietnam Road Freight Transport Market
Transportation & Logistics
Cable Car and Ropeways Market
Transportation & Logistics
United Kingdom Road Freight Transport Market
Transportation & Logistics
Global Fourth Party Logistics Market
Transportation & Logistics
Europe Cross Border Road Freight Transport Market
Transportation & Logistics
Spain Cold Chain Logistics Market
Transportation & Logistics
Japan Cold Chain Logistics Market
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
FMCG Logistics Market