
 Global Automotive Parking Sensors Market | 2026-2036
Global Automotive Parking Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Parking Sensors Market Intelligence
Fleet procurement managers is rotating toward integrated parking assistance packages as a standard specification rather than an optional add-on. Valeo leverages its vertical integration across ultrasonic and camera-based modules to sustain margin control in European supply contracts. Bosch anchors its position through R&D intensity in radar fusion algorithms, while Aptiv competes on manufacturing scale across North American and Asian assembly plant footprints.
Automotive parking sensors detect obstacles through ultrasonic wave emission, electromagnetic field distortion, or radar signal reflection, typically operating at frequencies between 40 kHz and 58 kHz with detection ranges from 0.3 to 2.5 meters to enable low-speed maneuvering safety. Ultrasonic technology dominates unit shipments across passenger car and light truck applications due to mature cost curves, though camera-based segments capture expanding share in luxury and electric vehicle platforms where multi-sensor fusion commands premium positioning. OEM end users concentrate procurement volumes through long-term supply agreements, while aftermarket suppliers occupy fragmented regional channels with shorter replacement cycles.
The EU's General Safety Regulation and the US NHTSA pedestrian safety standards shape product design mandates, compelling sensor redundancy and minimum detection coverage zones in new vehicle certifications. China's MIIT issues GB standards for advanced driver assistance system performance that influence supplier qualification requirements for domestic assembly plants. Stakeholders must monitor divergence between regional testing protocols and the pace at which wireless and hybrid sensor architectures achieve cost parity with established wired ultrasonic systems.
Market Dynamics
Multi-sensor fusion architectures are compressing the dominance of standalone ultrasonic modules as electric vehicle platforms demand redundant obstacle detection across 360-degree coverage zones.
Growth Catalysts
- EU General Safety Regulation:Mandates advanced driver assistance systems including parking sensors in new vehicle types, creating baseline demand across passenger and commercial categories.
- China's MIIT GB standards:Establish performance thresholds for domestic OEM qualification, accelerating supplier consolidation toward certified multi-sensor providers.
- Ultrasonic cost maturation:Decades of manufacturing scale have driven unit economics below camera and radar alternatives, sustaining volume leadership in mass-market segments.
Market Restraints
- Semiconductor input volatility:MEMS microphone and signal processing chip supply concentrates in East Asian foundries, exposing module assemblers to allocation risk.
- Ultrasonic range ceiling:Physical wave propagation limits detection beyond 2.5 meters, constraining applicability in larger vehicle categories and autonomous valet scenarios.
- Substitution from camera-radar fusion:Premium electric vehicle platforms increasingly specify vision-primary architectures with ultrasonic redundancy relegated to cost-engineered trims.
Strategic Opportunities
- India's PLI scheme for auto components:Manufacturing incentives attract sensor module localization for domestic OEMs and export-oriented assembly plants.
- Wireless sensor architectures:Elimination of harness wiring reduces vehicle assembly complexity and enables retrofit aftermarket penetration.
- Commercial fleet telematics integration:Parking sensor data feeds into usage-based insurance and fleet safety scoring, opening recurring revenue streams beyond hardware.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-rated sensor validation extends development cycles 18-24 months, compressing competitive response windows.
- Multi-sensor calibration complexity:Fusion algorithms require precise ultrasonic, camera, and radar alignment that strains dealer service technician training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Parking Sensors Market |
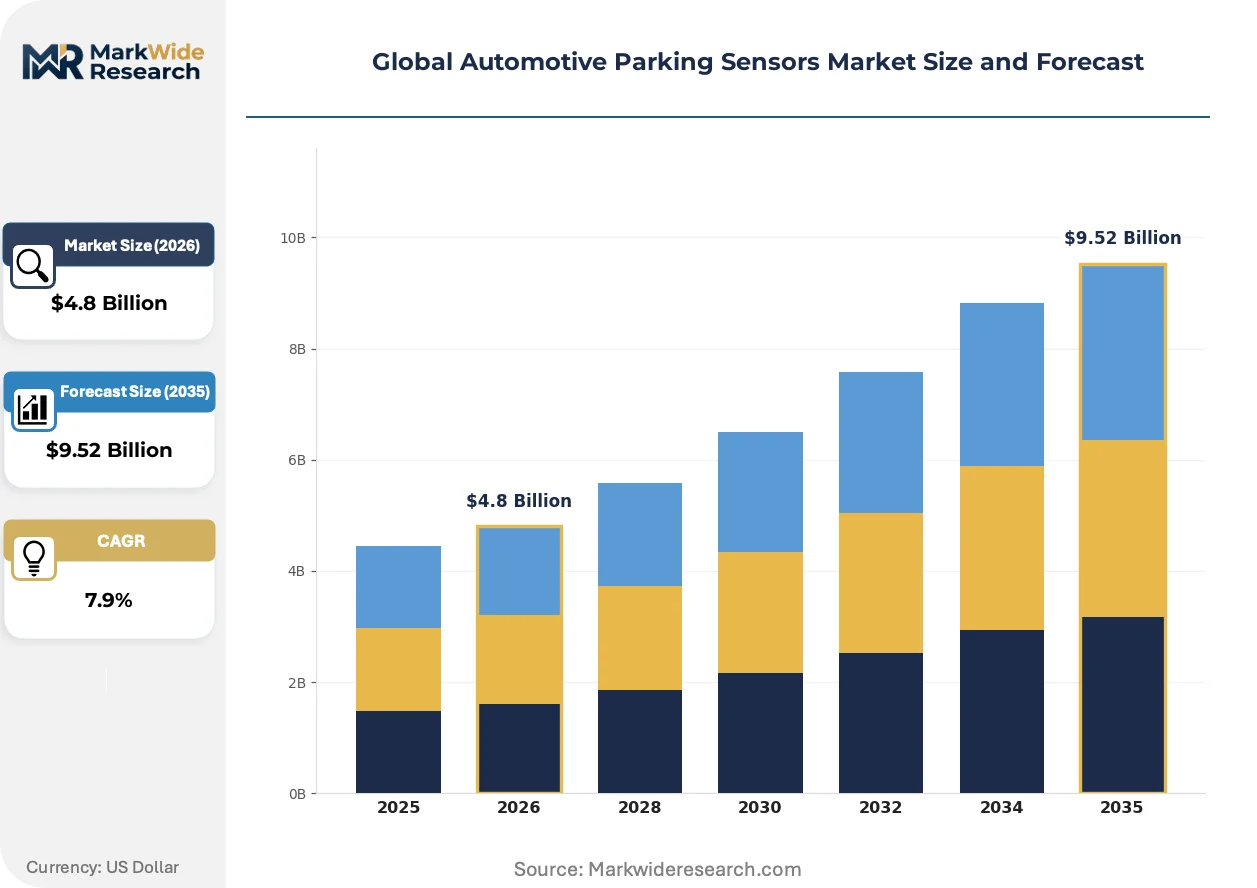
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Electromagnetic, Radar, Camera-Based, Infrared Application: Passenger Cars, Commercial Vehicles, Light Trucks, Electric Vehicles, Luxury Vehicles Technology: Active Sensors, Passive Sensors, Wireless Sensors, Wired Systems, Hybrid Systems End User: OEMs, Aftermarket Suppliers, Vehicle Assembly Plants, Automotive Workshops |
| Companies Covered | Valeo, Hyundai MOBIS, Bosch, NXP Semiconductors, Robert Bosch GmbH, Continental, Aptiv, Magna International, DENSO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Parking Sensors Market Strategic Shifts & Innovations
Sensor modality convergence is redrawing competitive boundaries as module suppliers reposition from single-technology vendors to integrated perception stack providers.
Radar-augmented parking assistance is supplanting pure ultrasonic configurations in mid-range electric vehicle trims. NHTSA pedestrian safety standards elevate detection reliability requirements. Tier-1 suppliers are compressing standalone ultrasonic margins while capturing fusion system premiums.
REACH substance restrictions on piezoelectric ceramics are forcing material substitutions in European-bound sensor modules. Suppliers reformulate transducer compositions to maintain acoustic performance under halogenated compound limits. German KBA type-approval processes now incorporate extended temperature cycling for substituted materials.
Fleet procurement departments now specify integrated parking assistance as standard equipment rather than negotiating option packages. Volume concentration among leasing companies and ride-hail operators displaces fragmented retail aftermarket channels. This pattern concentrates most visibly in China's corporate fleet renewal programs.
Global Automotive Parking Sensors Market Segmentation
Technology modality and installation channel determine margin structure and certification burden across parking sensor supply chains. Regulatory divergence between EU, US, and Chinese testing protocols fragments product specifications and complicates platform standardization for multinational OEMs.
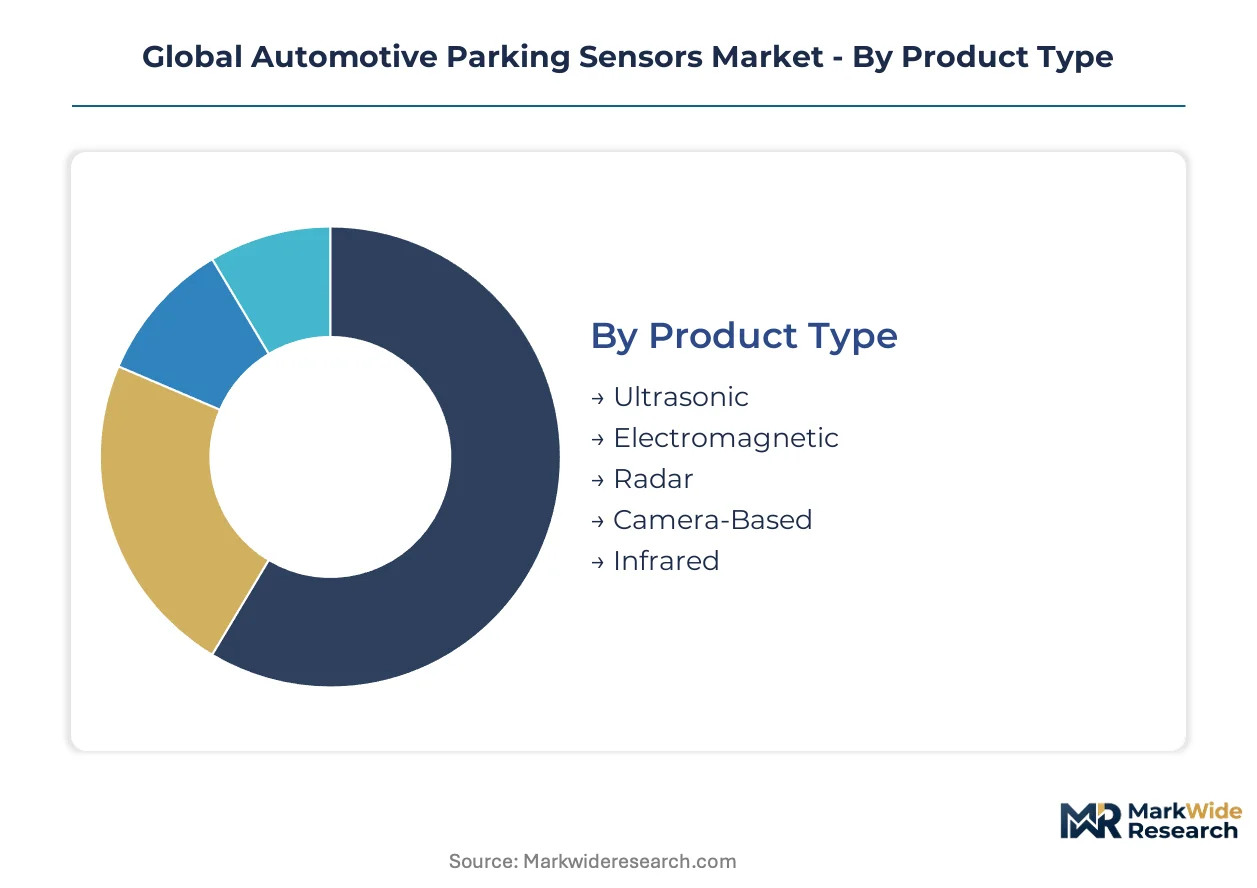
Product Type:
EU REACH substance restrictions on piezoelectric ceramics and US NHTSA pedestrian safety standards create divergent material qualification pathways for transducer manufacturers.
- Ultrasonic:Emits acoustic waves at 40-58 kHz frequencies with detection ranges of 0.3-2.5 meters. Mature cost curves sustain dominance in mass-market passenger cars and light trucks across China and India, though physical range ceilings constrain autonomous valet applications.
- Camera-Based:Captures visual data for computer vision processing with superior object classification capabilities. Premium electric vehicle platforms in Germany and South Korea specify camera-primary architectures with ultrasonic redundancy, commanding higher module ASPs.
- Radar:Utilizes millimeter-wave signal reflection for all-weather performance.
- Electromagnetic:Detects field distortion from metallic obstacles without surface mounting.
- Infrared:Employs thermal detection for low-light scenarios with limited commercial penetration.
Ultrasonic handles the majority of throughput; camera-based is expanding most quickly on share.
Application:
Vehicle category determines sensor count, fusion complexity, and functional safety rating requirements under ISO 26262.
- Passenger Cars:Standard four-to-eight sensor configurations dominate unit economics. Chinese domestic OEMs and European volume manufacturers specify ultrasonic baselines with optional camera upgrades, concentrating procurement through long-term supply agreements.
- Electric Vehicles:Demand redundant 360-degree coverage zones with multi-sensor fusion architectures. MIIT GB standards and EU General Safety Regulation mandate advanced driver assistance inclusion, accelerating specification of radar-augmented systems in premium battery-electric platforms.
- Commercial Vehicles:Require extended detection ranges for blind-spot mitigation.
- Light Trucks:Balance cost sensitivity with parking assistance utility in urban delivery fleets.
- Luxury Vehicles:Specify full fusion stacks with ultrasonic, camera, radar, and infrared modalities.
Passenger cars anchor volume scale; electric vehicles are gaining share fastest as OEMs standardize parking assistance.
Technology:
Signal processing architecture and connectivity method determine assembly integration cost and aftermarket retrofit feasibility.
- Wired Systems:Dominate OEM factory installations with proven electromagnetic compatibility. Vehicle assembly plants in Mexico and Thailand prefer harness-integrated modules for quality control, though wiring complexity extends assembly cycle times.
- Wireless Sensors:Eliminate harness routing and enable battery-powered retrofit kits. European aftermarket channels and Indian independent workshops are piloting Bluetooth Low Energy configurations for used vehicle upgrades.
- Active Sensors:Emit energy pulses for obstacle detection with higher power draw.
- Passive Sensors:Rely on ambient signal reception with limited parking application.
- Hybrid Systems:Combine wired backbone with wireless satellite nodes for flexible coverage.
Wired systems handle the majority of throughput; wireless sensors are climbing the fastest on penetration rate.
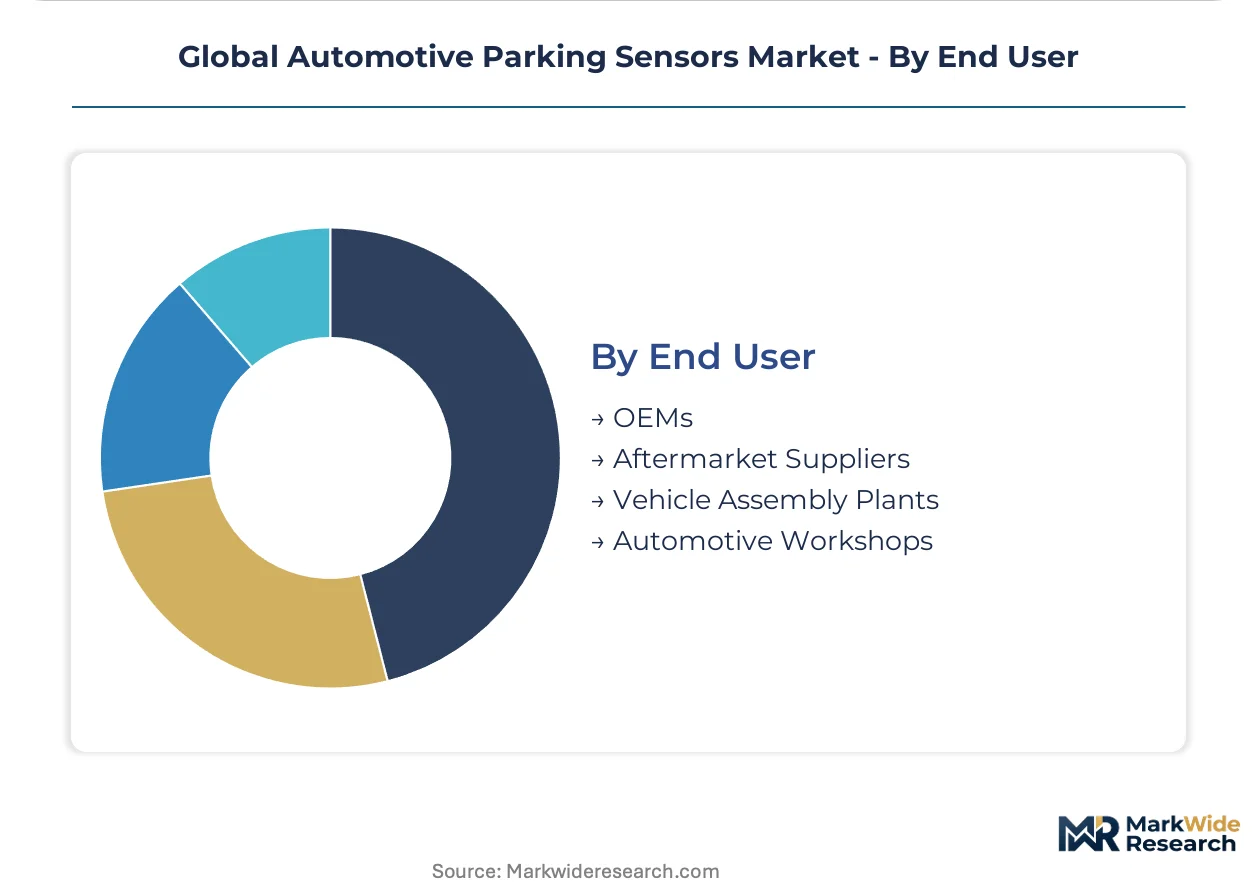
End User:
Procurement concentration and replacement cycle length diverge sharply between factory installation and service channel supply.
- OEMs:Concentrate multi-year supply agreements with tier-1 module suppliers. German and Japanese vehicle manufacturers qualify dual-source strategies for ultrasonic and camera-based systems, leveraging scale for cost-down negotiations.
- Aftermarket Suppliers:Serve fragmented regional channels through distributor networks. China's automotive workshops and US independent repair facilities stock universal-fit sensor kits with shorter inventory turns and higher margin volatility.
- Vehicle Assembly Plants:Execute just-in-sequence module delivery for production integration.
- Automotive Workshops:Perform warranty replacements and collision repair sensor recalibration.
OEMs handle the majority of throughput; aftermarket suppliers are expanding most quickly as vehicle parc ages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan Deep Water Port anchors China's dominance in automotive component exports, processing sensor module shipments bound for European and North American assembly plants. Germany's Rhine-Main corridor and the US Interstate 75 manufacturing belt complete the triad of demand concentration.
China
Domestic OEMs in Beijing and Shanghai specify multi-sensor fusion architectures as standard equipment. MIIT GB standards for advanced driver assistance systems accelerate supplier consolidation toward certified module providers. The Yangtze River Delta cluster around Suzhou and Wuxi concentrates ultrasonic transducer manufacturing for export markets.
Germany
Luxury vehicle manufacturers in Stuttgart and Munich drive premium-tier demand for camera-radar fusion systems. The KBA type-approval process enforces extended temperature cycling for REACH-compliant piezoelectric materials. Bavaria's automotive corridor hosts tier-1 module development centers serving EU General Safety Regulation mandates.
United States
Detroit-based OEMs and Texas-based electric vehicle startups anchor North American procurement volumes. NHTSA pedestrian safety standards elevate detection reliability requirements for new vehicle certifications. The Southeast manufacturing belt spanning Tennessee and South Carolina attracts sensor module localization for export-oriented assembly.
Japan
Precision component suppliers in Aichi Prefecture and Kanagawa maintain captive production of MEMS microphone elements. METI industrial policy supports domestic qualification for ISO 26262 functional safety ratings. The Nagoya automotive cluster integrates parking sensors into just-in-sequence delivery systems for regional OEMs.
India
Tamil Nadu and Maharashtra assembly plants drive procurement for compact passenger car segments. The PLI scheme for auto components attracts sensor module localization for domestic OEMs and export markets. Gurgaon-based tier-1 suppliers pilot wireless sensor architectures for aftermarket retrofit channels.
Global Automotive Parking Sensors Market Key Industry Players
Listed leaders compete with private specialists across technology modality and geographic footprint. The market structure tiers into consolidated tier-1 module suppliers, mid-scale technology licensors, and fragmented aftermarket assemblers. Three archetypes dominate: fusion-stack integrators, ultrasonic cost leaders, and radar-augmented specialists. Competitive moves concentrate on strategic partnerships for sensor calibration software and capacity expansion in Mexico and Thailand.
Within the fusion-stack integrator tier, Valeo exemplifies European vertical control across ultrasonic and camera-based modules. Bosch anchors German engineering intensity in radar fusion algorithms. Aptiv occupies a position spanning North American and Asian manufacturing scale. These three represent distinct strategic postures: Valeo through captive component supply, Bosch through R&D depth, Aptiv through geographic manufacturing footprint.
| Leading Market Players |
|---|
| Valeo |
| Hyundai MOBIS |
| Bosch |
| NXP Semiconductors |
| Robert Bosch GmbH |
| Continental |
| Aptiv |
| Magna International |
| DENSO |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements between tier-1 module suppliers and OEM platform engineers lock in volume commitments across 36-60 month horizons, stabilizing unit economics while constraining spot-market liquidity for semiconductor inputs. These contracts embed annual cost-down mechanisms that compress standalone ultrasonic margins while preserving fusion-stack premiums. China's MIIT GB standards and the EU's General Safety Regulation create divergent certification burdens that fragment pricing power across regional supply clusters.
Pricing Analysis
Volume-discount tiering structures separate full fusion-stack configurations from ultrasonic-baseline modules, with camera-radar augmentation commanding material premiums over pure acoustic systems. Price differentiation hinges on ISO 26262 ASIL certification grade and geographic delivery cost to assembly plants in Mexico versus Southeast Asia. Cost compression in mass-market ultrasonic tiers is intensifying because of MEMS microphone allocation constraints in East Asian foundries. Fleet procurement managers at Chinese leasing companies exhibit highest price sensitivity, while German luxury OEMs prioritize detection reliability over unit cost.
Supply Chain Analysis
Port congestion at Shanghai Yangshan and container availability on Asia-Europe trade lanes strain inbound logistics for piezoelectric ceramic transducers bound for European module assembly. Manufacturing concentrates in China, Germany, and Mexico, with the Yangtze River Delta feeding ultrasonic components and Bavaria's corridor supplying camera-radar fusion systems. The supply chain draws from MEMS foundries in Taiwan, signal processing chip fabricators in South Korea, and REACH-compliant ceramic suppliers in Japan. Single-source vulnerability in 40-58 kHz transducer production exposes assemblers to allocation risk. Distribution runs through just-in-sequence delivery to vehicle assembly plants and aftermarket distributor networks for collision repair channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in automotive parking sensors are shifting toward software-defined perception stacks where sensor calibration algorithms and over-the-air update capabilities determine ecosystem lock-in. Interoperability between ultrasonic, camera, and radar modalities is becoming the primary competitive moat as OEMs consolidate supplier bases.
For Market Incumbents: Secure captive supply of MEMS microphone elements through backward integration or long-term offtake with Taiwanese foundries to defend against semiconductor allocation volatility. Invest in ISO 26262 ASIL-D certification capacity to maintain qualification for EU General Safety Regulation mandates as camera-radar fusion displaces standalone ultrasonic dominance in premium electric vehicle platforms. For New Entrants and Emerging Players: Anchor in India's PLI scheme for auto components to capture localized manufacturing incentives for domestic OEM procurement and export-oriented assembly plant supply. Target wireless sensor retrofit kits for European aftermarket channels and Indian independent workshops, leveraging Bluetooth Low Energy architectures to bypass harness-integrated incumbent positions. For Investors and Strategic Acquirers: Capital is best deployed toward tier-1 fusion-stack integrators with established calibration software platforms and multi-regional manufacturing footprints. Long-term viability over the next decade rests on sensor modality convergence and recurring revenue from telematics data licensing rather than hardware margins alone. Monitor wireless sensor cost parity milestones as the inflection indicator for aftermarket disruption potential.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Fusion Platform Standardization | Reduces OEM supplier qualification burden while locking in tier-1 module providers across German and Chinese assembly networks. |
| Wireless Sensor Architecture Development | Eliminates harness routing complexity and opens retrofit penetration in European and Indian aftermarket channels. |
| Functional Safety Certification Investment | ISO 26262 ASIL ratings extend competitive moats against uncertified entrants under EU General Safety Regulation mandates. |
| Geographic Manufacturing Footprint Expansion | Localization in Mexico and Thailand aligns with just-in-sequence delivery requirements for North American and Southeast Asian vehicle assembly. |
| Fleet Telematics Data Partnership | Parking sensor feeds into usage-based insurance scoring create recurring revenue streams beyond hardware shipment economics. |
Research Approach
Operator-level perspectives from tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership service technicians anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, customs trade records, and MIIT GB standard filings. Bottom-up sensor shipment modeling triangulated against top-down OEM procurement spend estimates to reconcile volume and value outputs.
Sensitivity analysis tested forecast robustness across alternative adoption curves for electric vehicle platform penetration and wireless sensor cost reduction timelines. Segmentation dimensions modeled include technology modality, vehicle propulsion architecture, content per vehicle, OEM tier classification, and regional production cluster. CAGRs were derived from regression-based projection of historical shipment trajectories, adjusted for regulatory mandate phase-in schedules and supplier consolidation patterns. Industry-specific inputs encompassed MEMS foundry capacity utilization rates and REACH substance restriction compliance timelines.
Underlying assumptions cover sustained electric vehicle production growth, stable East Asian semiconductor supply allocation, and gradual wireless sensor cost parity achievement, with deviation risk concentrated in tariff exposure on Chinese-bound ceramic transducers and ISO 26262 certification backlog delays. Recalibration cycles align with material shifts in EU General Safety Regulation enforcement, MIIT GB standard updates, and tier-1 supplier merger activity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Asia Pacific Lane Departure Warning Systems Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
Road Speed Limiter Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Latin America Airbag Systems Market
Automotive Safety and Security Systems
Automotive Smart Security Device Market
Automotive Safety and Security Systems
Automotive Driver State Monitoring Systems Market
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market
Automotive Safety and Security Systems
United States Automotive Airbag Systems Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Terrain Awareness and Warning System Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Global Highway Driving Assist Market
Automotive Safety and Security Systems
Automotive Crash Sensor Market
Automotive Safety and Security Systems
Global Electronic Brake Force Distribution System Market