
 France Road Freight Transport Market | 2026-2036
France Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
France Road Freight Transport Market Foresight
France's Atlantic and northern logistics corridors is tilting capacity toward intermodal hubs at Le Havre and Lille. CEVA Logistics leverages its port-adjacent warehousing to control cross-channel freight flows. Geodis SA anchors domestic full-truckload networks through its Orleans distribution campus. STEF SA specializes in temperature-controlled chains, sustaining margin pools in pharmaceutical and fresh-food segments.
Road freight transport encompasses the movement of goods by motorized vehicles over paved infrastructure, utilizing diesel, electric, or hydrogen powertrains with gross vehicle weights ranging from 3.5 tonnes to 44 tonnes depending on axle configuration and French highway code limits. Its primary purpose is to connect manufacturing output, port terminals, and consumption centers within continental supply chains. Heavy-duty trucks dominate long-haul logistics between the Calais-Dunkirk cluster and Mediterranean ports, while refrigerated trucks capture expanding margin pools in e-commerce fulfillment and pharmaceutical cold chains. Light commercial vehicles lead urban deliveries in dense municipal zones where access regulations tighten.
France's national transport regulator enforces EU-wide cabotage rules under the Mobility Package, while domestic application of the CSRD compels large fleet operators to disclose Scope 1 emissions from diesel and alternative powertrains. The F-Gas Regulation constrains refrigerant choices in temperature-controlled vehicles, reshaping equipment procurement timelines. ANSM oversight of pharmaceutical distribution adds compliance layers to cold-chain service contracts. Stakeholders must weigh hydrogen infrastructure deployment against battery-electric range limits when renewing heavy-duty fleets serving trans-Alpine routes.
Market Dynamics
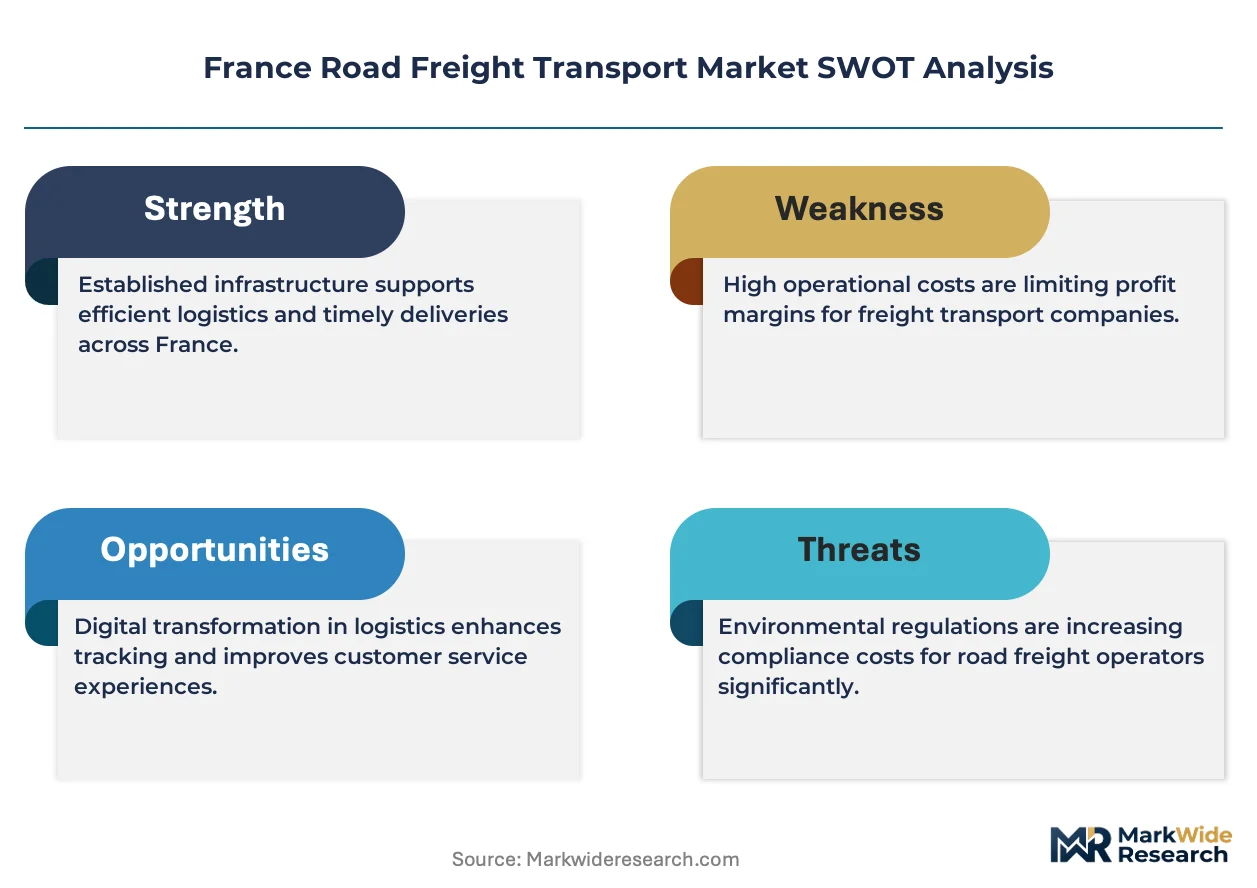
France's road freight sector confronts a structural squeeze between EU Green Deal mandates and the operational limits of available alternative powertrains. Fleet operators must decarbonize heavy-duty corridors while hydrogen refueling infrastructure remains sparse along trans-Alpine routes.
Growth Catalysts
- EU Green Deal's Fit for 55 package:Tightening CO2 emission standards for heavy-duty vehicles are forcing fleet renewal cycles, pulling forward demand for low-emission trucks and retrofit services.
- E-commerce fulfillment clusters:Concentrated warehouse development around Paris and Lyon is generating sustained refrigerated truck demand for last-mile cold chain distribution.
- Île-de-France logistics corridor:The capital-to-Le Havre-to-Lille axis concentrates manufacturing output and port throughput, anchoring full-truckload volume growth.
Market Restraints
- Battery-electric range constraints:Current heavy-duty electric trucks face payload-distance tradeoffs that limit deployment on France's longest domestic hauls.
- Hydrogen infrastructure gaps:Sparse refueling networks along the A6 and A7 motorways strand fuel-cell truck investments in pilot phases.
- F-Gas Regulation compliance costs:Refrigerant phase-down mandates are accelerating equipment obsolescence in temperature-controlled fleets before full cost recovery.
Strategic Opportunities
- Intermodal hub development:Port-adjacent warehousing at Le Havre and Lille offers modal shift capture for cross-channel freight flows.
- Pharmaceutical cold chain expansion:ANSM oversight requirements are segmenting high-margin temperature-controlled services from commodity trucking.
- CSRD disclosure mandates:Scope 1 emissions reporting requirements are creating advisory and fleet optimization service demand among mid-size operators.
Industry Challenges
- Driver qualification pipeline:France's vocational training capacity lags fleet electrification skill requirements, particularly for high-voltage maintenance certification.
- Dual powertrain fleet complexity:Operators managing mixed diesel, battery-electric, and hydrogen assets face fragmented maintenance protocols and spare parts inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Road Freight Transport Market |
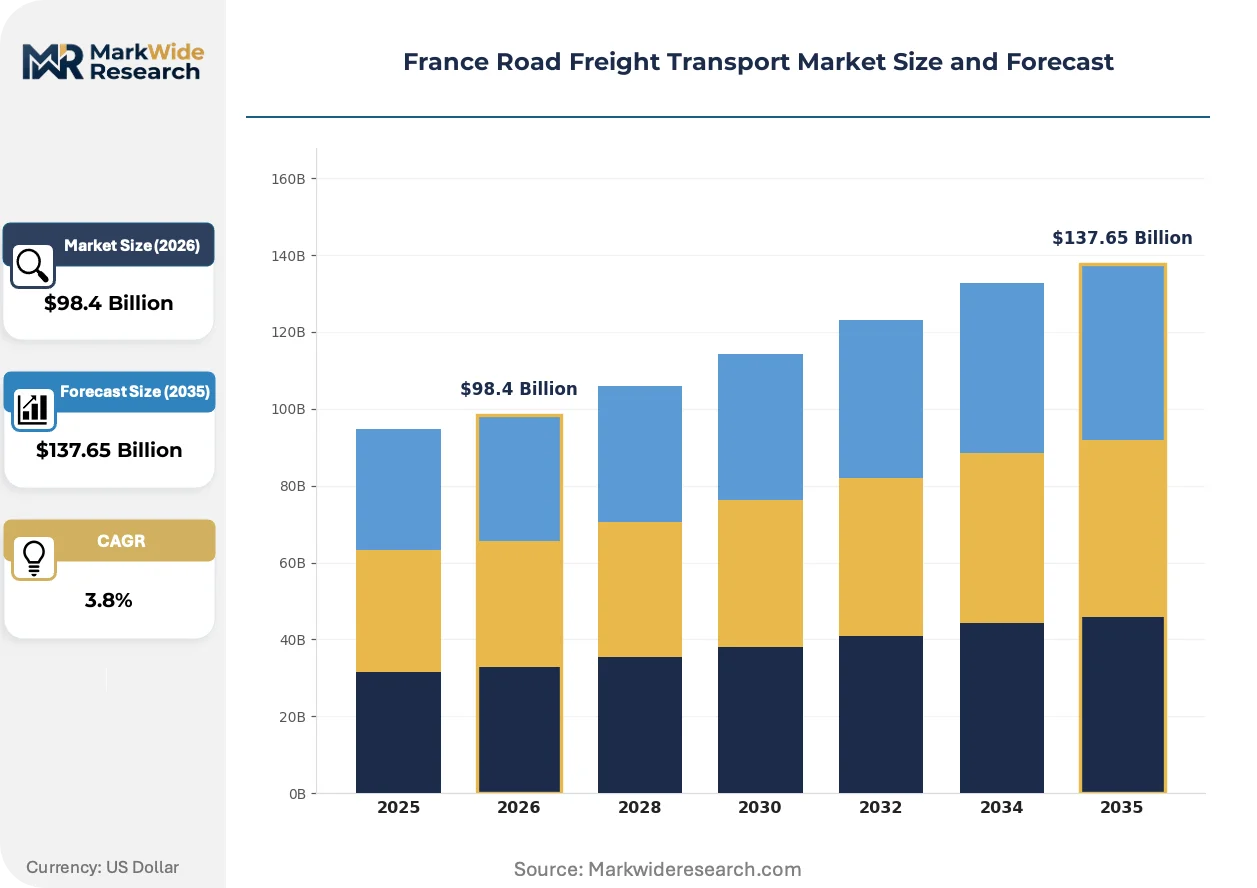
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $137.65 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Heavy-Duty Trucks, Light Commercial Vehicles, Trailers, Tankers, Refrigerated Trucks Service Type: Full Truckload, Less Than Truckload, Intermodal, Dedicated Contract Carriage, Expedited Delivery Customer Type: Manufacturers, Wholesalers, Importers, Exporters, Distributors Application: Long-Haul Logistics, Urban Deliveries, Cross-Docking, E-commerce Fulfillment, Construction Materials Transport |
| Companies Covered | CEVA Logistics, GEFCO SA, Geodis SA, Groupe CAT, Dimotrans Group, STEF SA, Bolloré Logistics, TC-transports, XPO Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Road Freight Transport Market Shifts & Advancements
France's freight ecosystem is rewiring around energy transition imperatives and digital freight matching platforms. Technology deployment is compressing traditional dispatch hierarchies while regulatory pressure accelerates equipment turnover cycles.
Battery-electric powertrains are collapsing total cost of ownership calculations for urban and regional delivery routes. Major retail distributors operating Île-de-France depots are electrifying light commercial vehicle pools ahead of regulatory mandates. This technology shift is compressing diesel truck residual values in metropolitan zones where access restrictions tighten.
The EU's Mobility Package cabotage enforcement is restructuring driver posting and rest rules for international operators. French fleet managers now face compliance complexity when routing through neighboring jurisdictions with divergent enforcement calendars. Cross-border hauliers serving the Calais-Dunkirk cluster are consolidating dispatch functions to manage multi-country regulatory overlays.
Digital freight platforms are fragmenting traditional shipper-carrier relationships through spot-market price transparency. Large manufacturing accounts in the Lyon corridor are unbundling contracted capacity from ad-hoc volume, forcing asset-heavy operators to compete on utilization metrics. This procurement evolution concentrates price pressure on mid-size fleets lacking scale economies in backhaul optimization.
France Road Freight Transport Market Segmentation
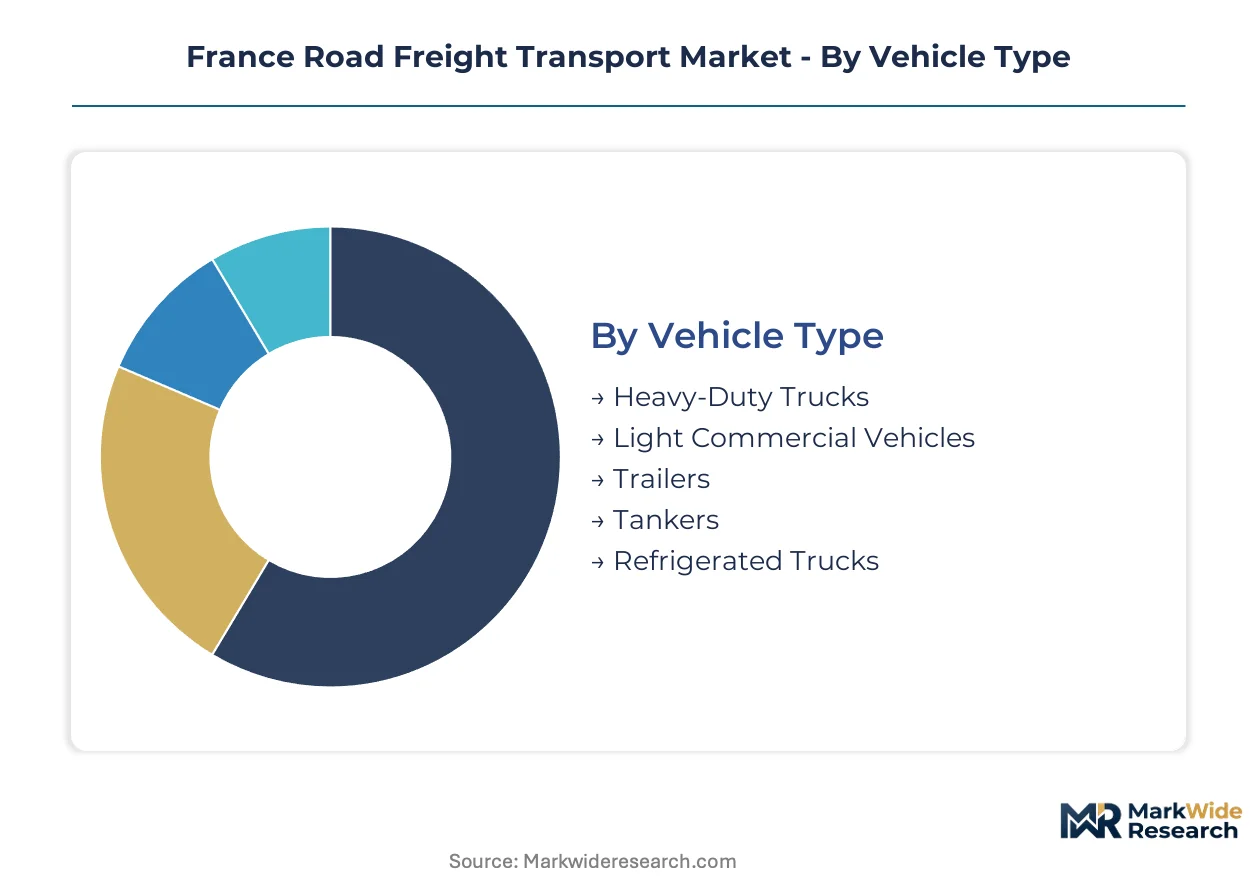
Segmentation in France's road freight market reveals how fleet composition, service models, and customer structures interact with regulatory pressure and infrastructure constraints. Distinct equipment and service tiers face divergent replacement cycles and margin pressures under the EU Green Deal.
Vehicle Type:
Replacement cycles vary dramatically across vehicle categories, with urban-duty assets turning over fastest and long-haul heavy-duty platforms requiring decade-long amortization periods.
- Heavy-Duty Trucks:These 16-44 tonne diesel, battery-electric, or hydrogen-powered tractors dominate trans-Alpine corridors and the Calais-Dunkirk cluster. Fleet operators face compressed renewal timelines as EU CO2 standards tighten, though hydrogen refueling gaps along the A6 and A7 motorways stall fuel-cell deployment.
- Light Commercial Vehicles:Urban delivery vans under 3.5 tonnes GVW are electrifying fastest as Île-de-France access restrictions tighten and total cost of ownership calculations favor battery powertrains for depot-based distribution loops.
- Trailers:Semitrailers and drawbar combinations extend fleet flexibility without powertrain complexity, serving as the modular backbone for intermodal transfers at Le Havre and Lille.
- Tankers:Specialized liquid and dry bulk containers face extended procurement timelines due to ADR hazardous materials certification requirements and stainless steel fabrication bottlenecks.
- Refrigerated Trucks:Temperature-controlled units with multi-zone cooling are expanding most quickly around Paris and Lyon e-commerce fulfillment centers, though F-Gas Regulation refrigerant phase-downs accelerate equipment obsolescence.
Heavy-duty trucks dominate installed base. Refrigerated trucks are where expansion concentrates.
Service Type:
Service differentiation tracks customer scale and predictability, with contracted capacity commanding premium pricing against volatile spot-market exposure.
- Full Truckload:Dedicated vehicle allocation for single-shipper volumes anchors the Île-de-France corridor linking manufacturing output to Le Havre port terminals. CEVA Logistics and Geodis SA compete on fleet scale and backhaul optimization.
- Less Than Truckload:Consolidated multi-shipper shipments through hub-and-spoke networks capture mid-size manufacturers lacking volume for dedicated capacity, though digital freight platforms fragment traditional pricing power.
- Intermodal:Road-rail and road-sea combinations leverage port-adjacent warehousing at Le Havre and Lille to reduce carbon intensity on cross-channel routes.
- Dedicated Contract Carriage:Long-term fleet outsourcing agreements with pharmaceutical and fresh-food shippers sustain STEF SA's margin pools through ANSM cold-chain compliance integration.
- Expedited Delivery:Time-critical shipments command surcharge pricing for automotive just-in-sequence and aerospace AOG requirements, though volume remains concentrated in Rhine-Rhône manufacturing belts.
Full truckload commands revenue concentration. Intermodal is gaining share fastest as shippers seek emission reductions without sacrificing reliability.
Customer Type:
Customer scale determines procurement sophistication, with large accounts unbundling contracted and spot capacity while smaller shippers rely on freight forwarder aggregation.
- Manufacturers:Automotive, aerospace, and industrial goods producers in the Lyon corridor and northern Hauts-de-France region drive scheduled full-truckload demand with stringent delivery window requirements.
- Wholesalers:Food and consumer goods distributors generate recurring refrigerated volume to retail depots, with consolidation pressure from supermarket chain captive fleets.
- Importers:Containerized cargo owners routing through Le Havre demand first-mile drayage and inland distribution, with customs clearance speed determining carrier selection.
- Exporters:Wine, pharmaceutical, and luxury goods shippers require temperature-controlled and secure transport for cross-channel and trans-Alpine destinations.
- Distributors:Third-party logistics providers aggregate fragmented shipper demand, facing margin compression from digital freight platform price transparency.
Manufacturers anchor volume stability. Importers are where service innovation concentrates as port competition intensifies.
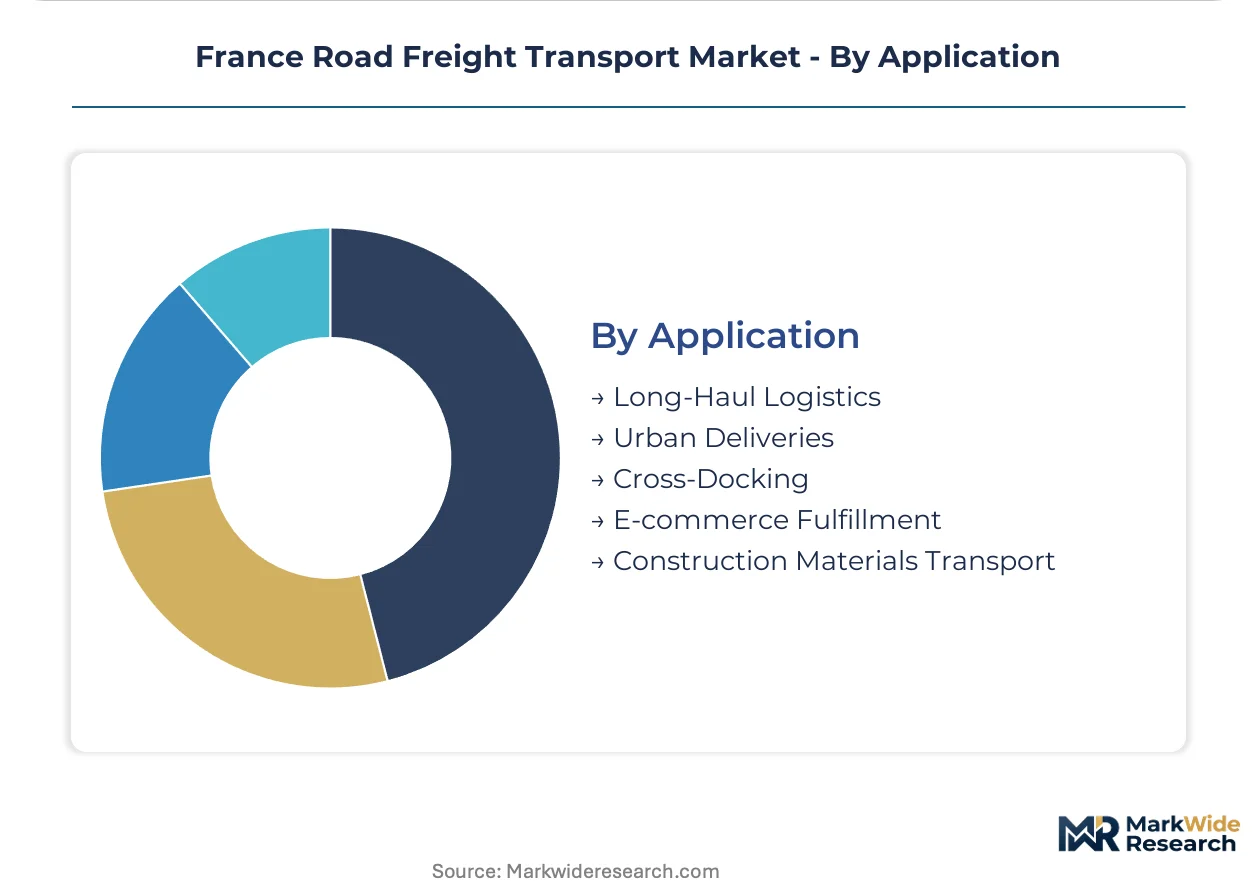
Application:
Application segmentation maps directly to infrastructure access and regulatory treatment, with urban zones facing the strictest emission and operating hour constraints.
- Long-Haul Logistics:Domestic and international corridors exceeding 300 kilometers dominate heavy-duty diesel deployment, though battery-electric range constraints limit electric adoption on France's longest domestic hauls.
- Urban Deliveries:Last-mile distribution in Paris, Lyon, and Marseille municipal zones is electrifying fastest as low-emission zones expand and access permits tighten for combustion vehicles.
- Cross-Docking:Hub transfer operations at Orleans and Lille distribution campuses minimize inventory holding while maximizing trailer utilization through synchronized inbound-outbound flows.
- E-commerce Fulfillment:Warehouse-to-consumer cold chain segments around Paris and Lyon are pulling refrigerated truck demand upward with strict time-window compliance requirements.
- Construction Materials Transport:Heavy-haul specialized trailers for aggregates and cement face cyclical demand tied to public infrastructure spending and residential construction permits.
Long-haul logistics dominates fleet asset value. E-commerce fulfillment is climbing the fastest as channel shift accelerates cold-chain infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANSM oversight of pharmaceutical distribution anchors compliance requirements across France's cold-chain corridors. The EU Green Deal's Fit for 55 package applies uniformly, though regional infrastructure density creates divergent electrification timelines.
Île-de-France
E-commerce fulfillment centers around Paris generate sustained refrigerated truck demand for last-mile cold chain distribution. The CSRD compels large fleet operators headquartered in the capital region to disclose Scope 1 emissions from diesel and alternative powertrains. Le Bourget and Roissy logistics clusters concentrate cross-docking facilities serving the capital-to-Le Havre manufacturing corridor.
Auvergne-Rhône-Alpes
Pharmaceutical manufacturing in Lyon drives dedicated contract carriage demand for temperature-controlled transport. The F-Gas Regulation constrains refrigerant choices in vehicles serving ANSM-regulated distribution networks. Saint-Étienne and Grenoble automotive suppliers anchor just-in-sequence expedited delivery requirements.
Hauts-de-France
The Calais-Dunkirk cluster dominates cross-channel freight flows to British markets. EU Mobility Package cabotage enforcement restructures driver posting rules for international operators routing through northern ports. Lille distribution campuses capture modal shift volume through intermodal road-rail combinations.
Provence-Alpes-Côte d'Azur
Marseille-Fos port terminals generate first-mile drayage demand for containerized imports. Battery-electric range constraints limit heavy-duty electric deployment on trans-Alpine corridors connecting to Italian markets. Aix-en-Provence logistics zones specialize in wine and luxury goods export consolidation.
France Road Freight Transport Market Competitive Landscape
Capability concentration sits with temperature-controlled specialists; scale advantage sits with diversified logistics conglomerates. The market structures around three tiers: port-adjacent operators controlling cross-channel flows, domestic full-truckload networks anchored at distribution campuses, and cold-chain specialists capturing pharmaceutical margin pools. Dominant competitive moves include intermodal hub development at Le Havre and Lille, plus fleet electrification pilots targeting urban access zones.
Within the diversified logistics tier, CEVA Logistics and Geodis SA occupy positions exemplifying scale-driven consolidation. STEF SA represents the specialized cold-chain archetype, anchoring temperature-controlled service segmentation under ANSM compliance frameworks. These three entities collectively illustrate how French road freight competition stratifies between commodity capacity provision and regulated pharmaceutical distribution.
| Leading Market Players |
|---|
| CEVA Logistics |
| GEFCO SA |
| Geodis SA |
| Groupe CAT |
| Dimotrans Group |
| STEF SA |
| Bolloré Logistics |
| TC-transports |
| XPO Logistics |
| Others |
Supply & Pricing Matrix
Hydrogen infrastructure gaps along trans-Alpine corridors create stranded asset risk that compresses pricing spreads between diesel-reliant long-haul tiers and emerging low-emission alternatives. This single-source dependency on fossil fuel powertrains for cross-border hauls concentrates margin pressure on mid-size fleet operators lacking scale to absorb dual-powertrain complexity.
Pricing Analysis
Paris-to-Lyon rate spreads now diverge sharply from Calais-Dunkirk corridor pricing as EU Mobility Package enforcement adds compliance cost layers to international routes. Three-tier pricing structure across premium cold-chain, standard full-truckload, and economy spot-market levels stratifies around ANSM certification and backhaul optimization capabilities. Cost compression in economy spot tiers is intensifying because digital freight platforms fragment traditional pricing power. Small wholesalers and regional distributors exhibit highest price sensitivity, while pharmaceutical manufacturers under ANSM oversight accept premium tiers for compliance-integrated service.
Supply Chain Analysis
Tariff exposure between UK and EU customs regimes dominates supply chain risk calculus for operators serving the Calais-Dunkirk cluster. Manufacturing inputs for trailer fabrication concentrate in Germany, Poland, and Spain, while battery-electric powertrain components draw from South Korea, China, and Hungary. Single-source vulnerability in high-voltage charging infrastructure stalls fleet electrification timelines. Distribution runs through port-adjacent warehousing at Le Havre and Lille, with final-mile legs subcontracted to regional carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's road freight sector sits at a platform-economics inflection where digital freight matching interoperability threatens to commoditize traditional carrier-shipper relationships. Ecosystem consolidation around port-centric logistics campuses is rewiring competitive moats.
For Market Incumbents: Insulate contracted pharmaceutical and fresh-food carriage relationships through deeper ANSM compliance integration and captive temperature-controlled asset pools. Consolidate dispatch functions across multi-country regulatory overlays to absorb EU Mobility Package complexity. Vertical integration into port-adjacent warehousing at Le Havre anchors cross-channel flow control against digital platform disintermediation. For New Entrants and Emerging Players: Auvergne-Rhône-Alpes pharmaceutical corridors present underpenetrated white space for specialized cold-chain operators lacking legacy diesel fleet overhead. Target mid-size manufacturers in Saint-Étienne and Grenoble automotive supplier clusters with expedited just-in-sequence offerings. Lead with battery-electric light commercial vehicle pools to capture tightening Île-de-France access permit advantages. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified logistics conglomerates with intermodal hub control. Long-term viability across the analysis window hinges on hydrogen infrastructure timing and CSRD disclosure service attach rates. Acquisition target archetype: temperature-controlled specialists with ANSM-integrated compliance layers. The signal to watch is F-Gas Regulation refrigerant phase-down acceleration forcing equipment refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Intermodal Hub Development | Port-adjacent warehousing at Le Havre captures modal shift volume from cross-channel shippers. |
| Fleet Electrification Pilot | Battery-electric light commercial vehicle deployment secures Île-de-France low-emission zone access permits. |
| CSRD Advisory Service Launch | Scope 1 emissions disclosure support creates recurring revenue from mid-size operator compliance mandates. |
| Pharmaceutical Cold Chain Expansion | ANSM-integrated temperature-controlled service segmentation captures margin pools from generic trucking. |
| Digital Freight Platform Integration | API connectivity to spot-market exchanges improves backhaul utilization for asset-heavy operators. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with fleet operations directors, logistics procurement managers, port authority planners, and EU regulatory compliance officers; and secondary validation through French national transport regulator filings, EU Mobility Package implementation schedules, ANSM pharmaceutical distribution guidance, and customs trade flow databases. Bottom-up fleet composition modeling triangulated against top-down corridor volume estimates from port throughput statistics.
Forecast inputs span vehicle type replacement cycles, service type margin evolution, customer procurement sophistication tiers, and application-specific infrastructure constraints across the projection horizon. Segmentation dimensions modeled include powertrain architecture, service contract duration, customer scale tier, and regional regulatory cluster. CAGRs derive from equipment procurement pipeline analysis and emission standard compliance cost absorption rates.
Macroeconomic conditions sit as an overlay; deviation in diesel price volatility, hydrogen subsidy allocation, and EU carbon border adjustment timing would shift the trajectory. Forecasts reflect documented assumptions about infrastructure deployment schedules and regulatory enforcement calendars. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Chile Road Freight Transport Market
Transportation & Logistics
India Intra-City Logistics Market
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
Brazil Road Freight Transport Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
Germany Road Freight Transport Market
Transportation & Logistics
Global Automotive 3PL Market
Transportation & Logistics
Pipeline Transportation Software Market
Transportation & Logistics
Asia-Pacific Customs Brokerage Market
Transportation & Logistics
ASEAN Road Freight Transport Market
Transportation & Logistics
Weigh in Motion Market
Transportation & Logistics
Spain Road Freight Transport Market
Transportation & Logistics
United Kingdom Warehousing and Distribution Logistics Market
Transportation & Logistics
Traction Equipment Market