
 Middle-East and North Africa Taxi Market | 2026-2036
Middle-East and North Africa Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and North Africa Taxi Market Foresight
The street-hail channel is narrowing across Middle-East and North Africa urban centers as smartphone penetration redirects volume toward app-based dispatch. Careem Networks FZ LLC leverages its super-app ecosystem to sustain customer stickiness beyond pure ride transactions. Uber Technologies Inc. competes through technology leadership in dynamic pricing algorithms and driver incentive structures. Dubai Taxi Corporation anchors conventional fleet operations while navigating digital transformation pressures from platform entrants.
The Middle-East and North Africa taxi sector comprises licensed vehicle-for-hire services operating across combustion and electric powertrains, typically governed by municipal or national transport authorities through permit quotas, fare regulation, and safety inspection regimes. These services primarily facilitate intra-urban passenger movement for commuters, tourists, and corporate travelers across dense metropolitan corridors. Sedan and SUV vehicle types dominate current fleet composition due to passenger capacity preferences and airport transfer demand, while electric vehicle penetration remains nascent but receives policy tailwinds from Gulf state decarbonization commitments. Mobile app booking methods capture the fastest-growing transaction share as smartphone ownership saturates younger demographics, though street hail and phone call channels retain substantial volume in Moroccan and Egyptian markets where digital payment infrastructure lags.
Saudi Arabia's Transport General Authority, the UAE's Roads and Transport Authority, and Egypt's Ministry of Transport collectively shape market access through licensing caps, driver background verification mandates, and fare ceiling regulations that vary by emirate or governorate. Compliance with these fragmented regulatory frameworks determines operational geography and cost structures for platform and traditional operators alike. Stakeholders must monitor evolving electric vehicle mandates and data localization requirements as Gulf regulators tighten environmental and consumer protection standards.
Market Dynamics
Smartphone penetration across Gulf Cooperation Council states is compressing booking friction and redirecting trip volume from street hails toward algorithmic dispatch platforms, forcing fleet operators to restructure driver recruitment and vehicle financing around app-based utilization metrics.
Growth Catalysts
- Saudi Arabia's Transport General Authority formalization mandates:Regulatory clarity around ride-hailing permits is accelerating fleet modernization and attracting institutional capital into vehicle procurement.
- Smart city mobility integration:Dubai and Riyadh are embedding taxi services into multimodal transit apps, creating seamless first-mile-last-mile connectivity that expands addressable trip occasions.
- Young demographic smartphone saturation:Egypt and Morocco's under-35 population is bypassing traditional phone-booking habits entirely, driving native app adoption without legacy channel transition costs.
Market Restraints
- Fragmented municipal licensing regimes:Egypt's governorate-level permit variations and the UAE's emirate-specific fare ceilings create compliance complexity that inflates back-office overhead for multi-city operators.
- Petroleum price volatility exposure:Combustion-dominant fleets across Algeria and Libya remain vulnerable to subsidy reduction scenarios that would compress driver net earnings.
- Digital payment infrastructure gaps:Cash-prevalent Moroccan and Egyptian markets delay real-time revenue recognition and complicate dynamic pricing algorithm calibration.
Strategic Opportunities
- Electric vehicle mandate alignment:Saudi Arabia and UAE net-zero commitments are creating preferential licensing queues and subsidized charging infrastructure for zero-emission fleet conversions.
- Corporate mobility account expansion:Unbundled enterprise travel programs across Doha and Kuwait City are consolidating vendor relationships toward platform providers with integrated expense management.
- Tourism corridor specialization:Egypt's Red Sea resort zones and Oman's heritage circuits present underpenetrated demand for pre-booked, multi-language driver services outside urban cores.
Industry Challenges
- Algorithmic wage transparency pressures:Driver protests against opaque earnings calculations are forcing platforms to disclose commission structures and surge pricing mechanics.
- Legacy fleet telematics integration:Traditional taxi cooperatives in Casablanca and Alexandria face capital-intensive retrofits to meet real-time location tracking mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and North Africa Taxi Market |
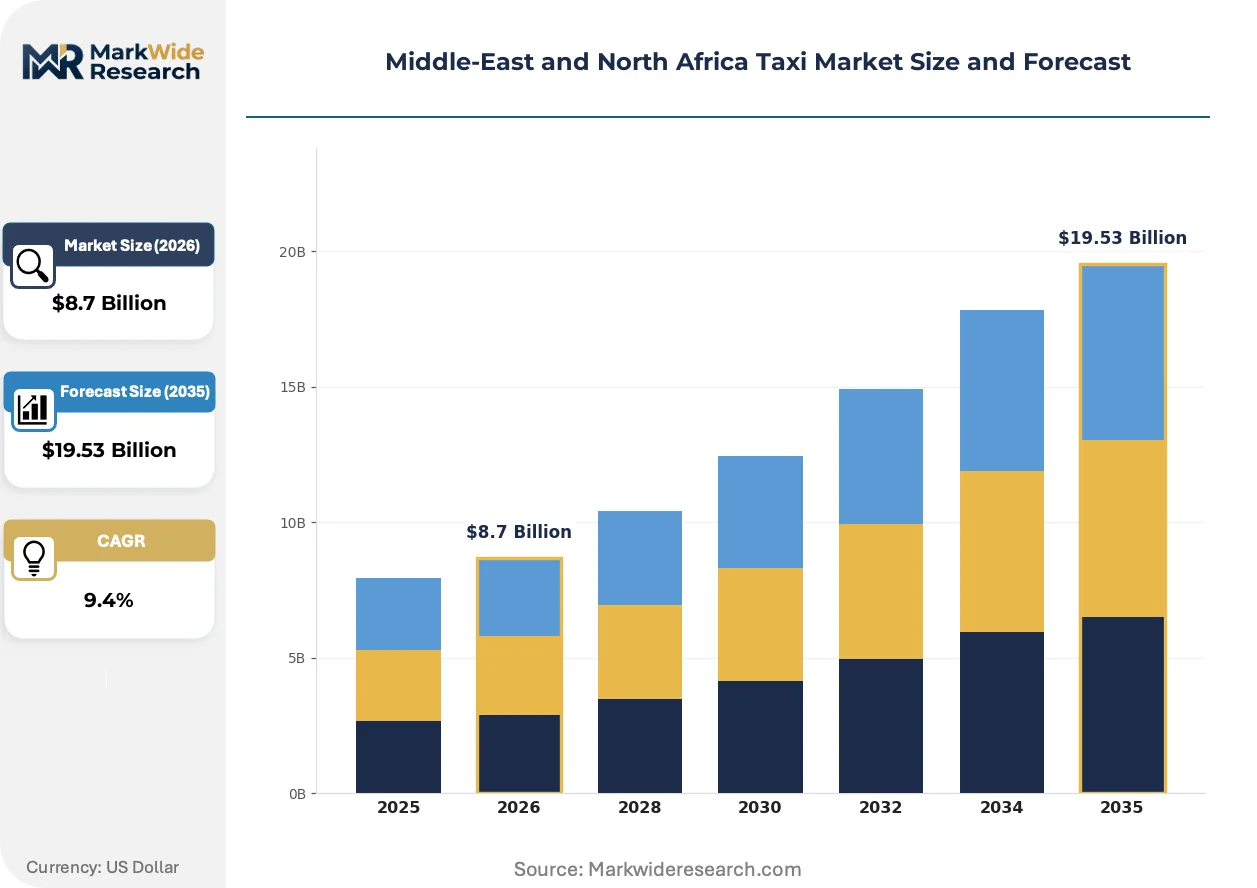
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, Minivan, SUV, Electric Booking Method: Mobile App, Phone Call, Street Hail, Website Payment Mode: Cash, Credit Card, Mobile Wallet, Prepaid Service Model: Ride-Hailing, Taxi Stand, Corporate Account, Shared Ride |
| Companies Covered | Uber Technologies Inc., Careem Networks FZ LLC, Bolt Technology OU, Dubai Taxi Corporation, Gett, inDrive, Hala Taxi, Saudi Limousine Service, Jeeny, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and North Africa Taxi Market Shifts & Advancements
Dispatch algorithms are compressing driver idle time and passenger wait intervals, restructuring competitive advantage around data infrastructure rather than vehicle scale alone.
Artificial intelligence-powered demand forecasting is digitizing fleet deployment patterns across Riyadh and Jeddah. Saudi fleet managers are adopting predictive models that position vehicles before surge events materialize. This capability is compressing the competitive gap between asset-heavy incumbents and lean platform intermediaries.
The UAE's Roads and Transport Authority has mandated real-time emissions monitoring for all licensed vehicles operating within Dubai's metropolitan boundary. This requirement is accelerating onboard diagnostic hardware retrofits and creating compliance differentiation between modernized fleets and aging cooperative vehicles. Operators are responding by front-loading electric vehicle procurement to bypass ongoing monitoring obligations entirely.
Corporate travel managers are consolidating ground transportation spend toward bundled platform subscriptions with integrated carbon accounting. This procurement evolution is displacing fragmented local taxi relationships across Doha, Manama, and Kuwait City finance districts. The shift is most pronounced in energy sector headquarters where ESG reporting requirements demand trip-level emissions traceability.
Middle-East and North Africa Taxi Market Segmentation
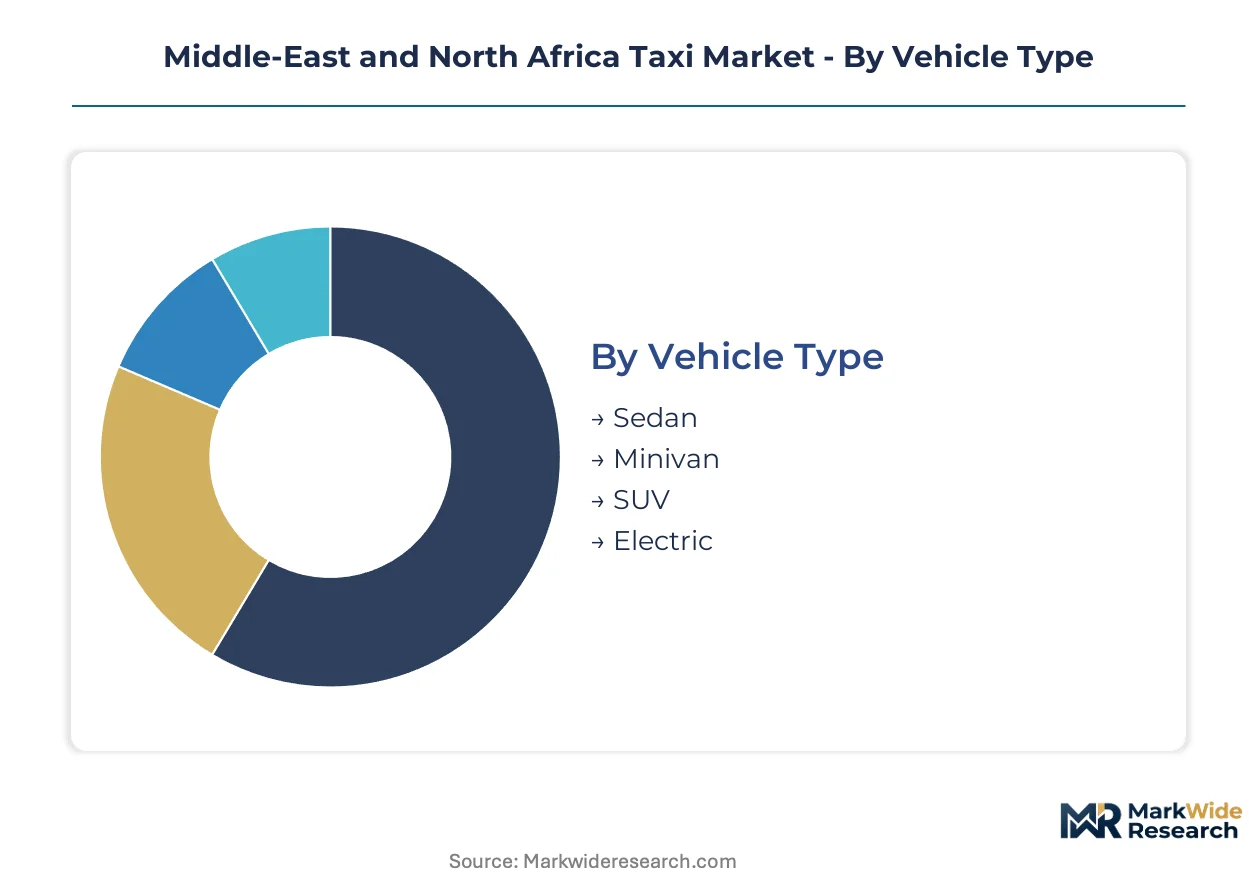
Segmentation in the Middle-East and North Africa taxi market reveals divergent growth vectors across vehicle technology, booking interfaces, and payment infrastructure. Fleet operators and platform providers calibrate capital allocation differently across these dimensions based on regulatory exposure and demographic readiness.
Vehicle Type:
Cost tier differentiation shapes fleet procurement strategies across Gulf and North African markets, with vehicle selection directly determining permit eligibility and fuel subsidy access.
- Sedan:Standard four-door passenger vehicles dominate airport transfer corridors and business district routes. Cairo and Riyadh operators favor sedans for their balanced passenger capacity and fuel efficiency under municipal fare ceilings that compress per-kilometer margins.
- SUV:Higher-clearance vehicles with expanded seating configurations capture premium pricing in Jeddah's resort zones and Dubai's corporate hospitality circuits. Family-sized groups and luggage-intensive airport runs drive sustained demand despite elevated fuel consumption.
- Minivan:Multi-passenger configurations serve pilgrimage logistics and hotel shuttle contracts across Mecca and Medina.
- Electric:Zero-emission powertrains access preferential licensing queues in Abu Dhabi and Dubai under Roads and Transport Authority decarbonization mandates.
Sedan fleets command the established base. The steepest expansion runs through Electric conversions aligned with Gulf state net-zero commitments.
Booking Method:
Application maturity across customer demographics determines channel migration speed, with smartphone saturation creating divergent adoption curves between Gulf Cooperation Council states and North African markets.
- Mobile App:Algorithmic dispatch platforms capture trip volume from younger demographics bypassing legacy booking habits entirely. Egypt's under-35 population and Saudi Arabia's urban centers drive native app adoption without transitional friction from phone-based systems.
- Street Hail:Curbside flag-down retains substantial volume in Casablanca and Alexandria where digital payment infrastructure lags and driver cooperative structures resist platform intermediation.
- Phone Call:Voice-based dispatch persists among older demographics and rural Moroccan markets with intermittent mobile data coverage.
- Website:Browser-based pre-booking serves corporate travel managers consolidating ground transportation spend across Doha and Kuwait City finance districts.
Street Hail retains volume in cash-prevalent North African metros. Mobile App booking gains share fastest where smartphone penetration compresses transaction friction.
Payment Mode:
Financial infrastructure maturity across national banking systems creates payment fragmentation that complicates revenue recognition and algorithmic pricing calibration for cross-border operators.
- Cash:Physical currency dominates Moroccan and Egyptian transactions, delaying real-time settlement and exposing drivers to security risks in high-volume corridors.
- Mobile Wallet:Smartphone-linked payment platforms accelerate in Saudi Arabia and UAE markets where digital identity verification integrates with Transport General Authority licensing systems.
- Credit Card:Card-present and card-not-present transactions concentrate in Dubai's tourism corridors and corporate account relationships requiring expense documentation.
- Prepaid:Stored-value instruments serve unbanked segments and pilgrimage package operators managing group transportation budgets.
Cash handling anchors North African operations. Mobile Wallet adoption climbs fastest where regulatory frameworks mandate driver financial inclusion.
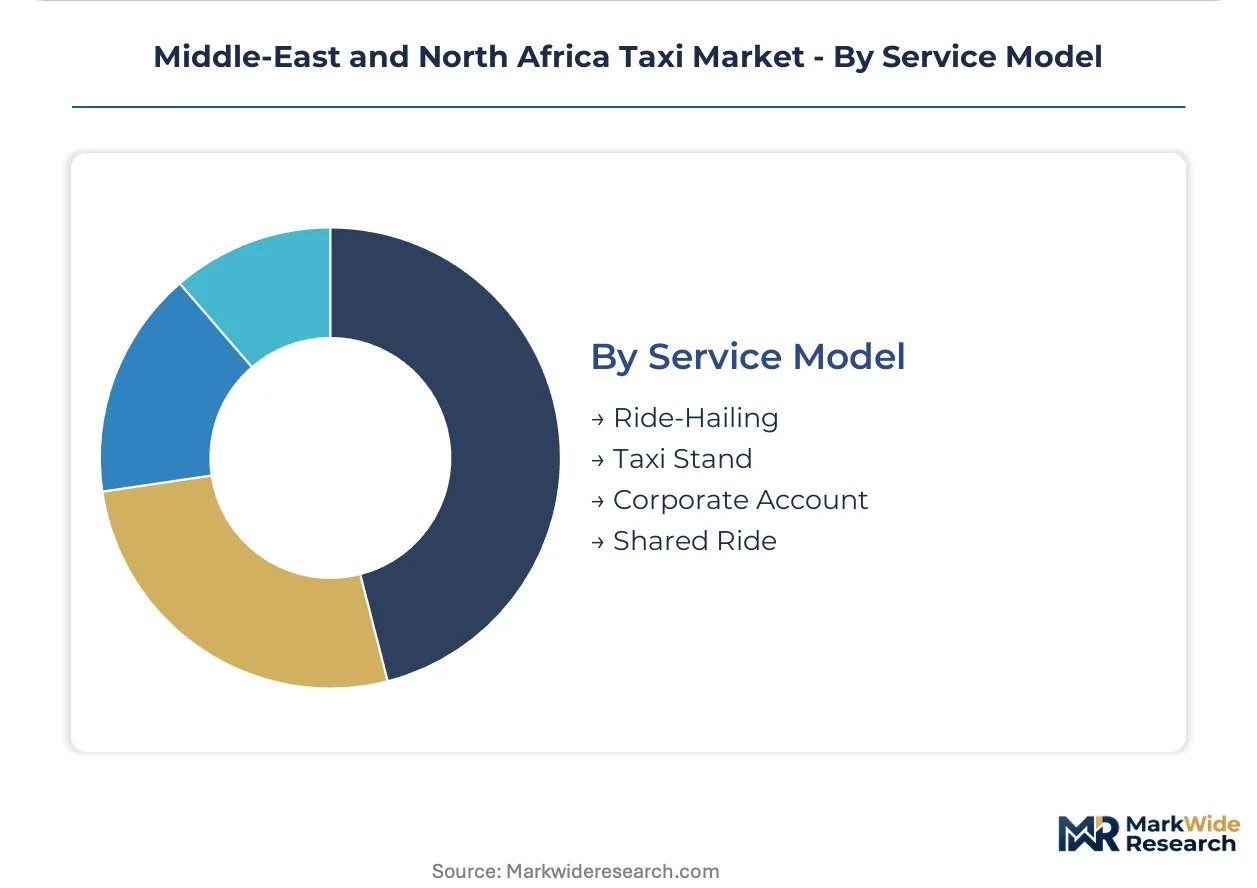
Service Model:
Customer relationship structure determines revenue predictability and capital intensity, with contractual models offering volume certainty against spot-market volatility.
- Ride-Hailing:On-demand platform dispatch aggregates fragmented driver supply through dynamic pricing algorithms, restructuring competitive advantage around data infrastructure rather than owned fleet scale.
- Corporate Account:Billed enterprise relationships consolidate vendor selection toward platform providers with integrated carbon accounting and ESG reporting capabilities demanded by energy sector headquarters.
- Taxi Stand:Fixed-location rank operations persist at transport hubs and religious sites where queue management systems allocate trips through municipal oversight.
- Shared Ride:Multi-passenger pooling configurations reduce per-trip fares in price-sensitive Egyptian and Algerian urban corridors while increasing vehicle utilization rates.
Taxi Stand operations command established infrastructure at regulated hubs. Corporate Account expansion runs through platform subscriptions with embedded compliance reporting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
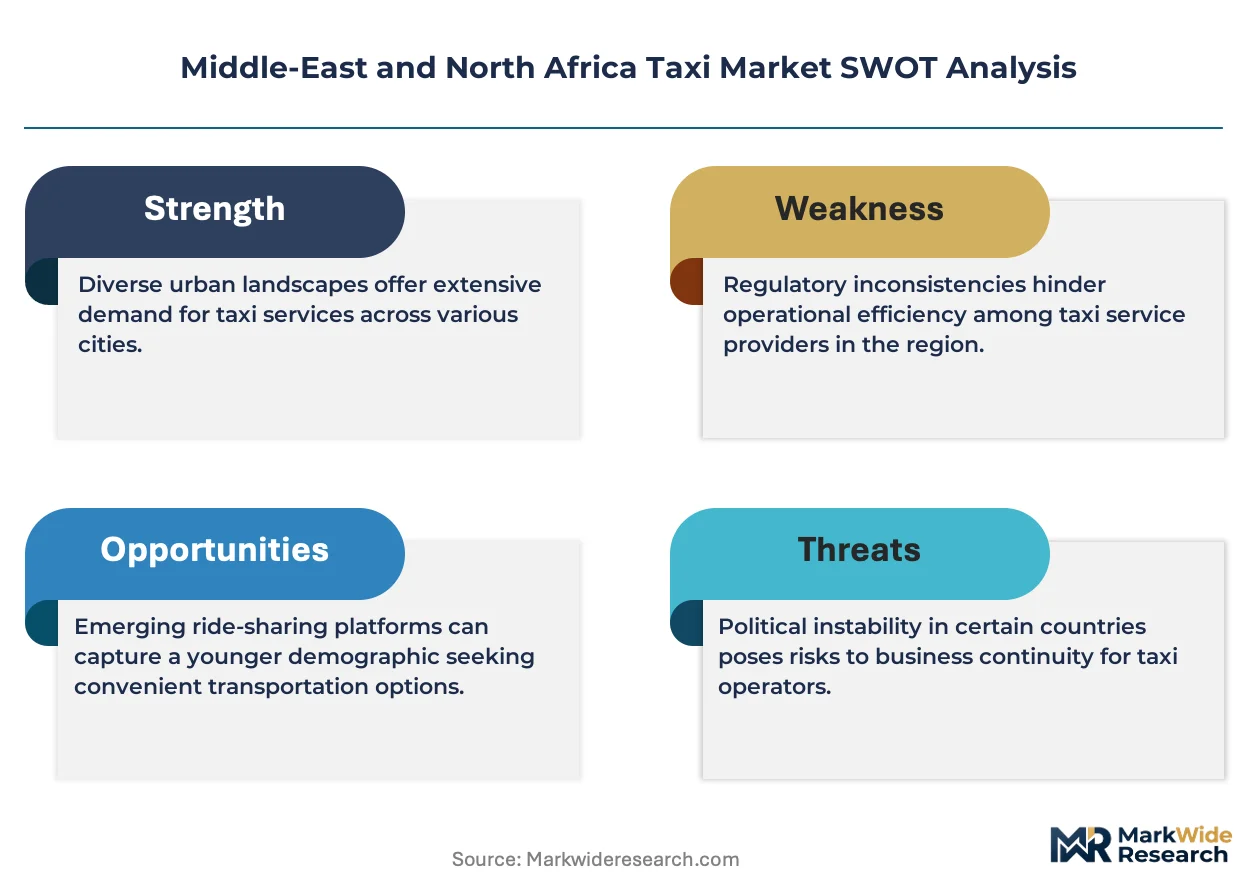
Pricing power concentrates in Gulf Cooperation Council capitals while North African metros absorb fare compression from informal competition. Saudi Arabia and the UAE command premium per-kilometer rates through regulatory scarcity and corporate demand density. Egypt and Morocco operate under municipal fare ceilings that compress operator margins despite higher trip volumes.
Saudi Arabia
Riyadh and Jeddah generate the region's highest per-trip revenue from corporate hospitality and pilgrimage logistics. The Transport General Authority's permit formalization mandates are consolidating fragmented driver supply into licensed fleet structures. Fleet modernization accelerates in the Eastern Province where Aramco-contracted operators replace aging sedans with SUV configurations.
United Arab Emirates
Dubai's tourism corridor and Abu Dhabi's government district sustain premium pricing through demand inelasticity. The Roads and Transport Authority's real-time emissions monitoring mandate is forcing onboard diagnostic retrofits across Dubai Taxi Corporation vehicles. Sharjah operators face compressed margins from emirate-specific fare ceilings that trail Dubai benchmarks.
Egypt
Cairo's street-hail density and Alexandria's port-worker commutes sustain volume despite cash-prevalent payment friction. The Ministry of Transport's governorate-level permit variations create compliance overhead for operators spanning Greater Cairo and the Red Sea resort zone. New Valley governorate remains underpenetrated by app-based platforms due to intermittent mobile data coverage.
Morocco
Casablanca's industrial workforce and Marrakech's tourism circuits generate divergent demand profiles with minimal cross-subsidy. The country's national transport regulator maintains municipal taxi cooperative structures that resist platform intermediation. Tangier-Med port logistics and Agadir resort shuttles present specialized fleet requirements outside standard sedan configurations.
Qatar
Doha's diplomatic and energy-sector headquarters concentrate corporate account demand with integrated expense management requirements. The country's central municipal authority embeds taxi services within multimodal transit apps serving Lusail's smart city development. Hamad International Airport's queue management system allocates trips through municipal oversight rather than algorithmic dispatch.
Middle-East and North Africa Taxi Market Competitive Landscape
Platform intermediaries and asset-heavy incumbents split the market along technology-versus-fleet fault lines. Careem Networks FZ LLC leverages super-app ecosystem integration to sustain customer stickiness beyond pure ride transactions. Uber Technologies Inc. competes through dynamic pricing algorithms and driver incentive structures that optimize utilization rates. Dubai Taxi Corporation anchors conventional fleet operations while navigating digital transformation pressures from platform entrants. Dominant competitive moves include regulatory compliance investments to secure permit queues and strategic partnerships with charging infrastructure providers for electric fleet conversion.
Within the platform intermediary tier, Careem Networks FZ LLC and Uber Technologies Inc. exemplify technology-led market entry strategies that restructure competitive advantage around data infrastructure rather than owned vehicle scale. Dubai Taxi Corporation occupies a transitional position between legacy fleet operations and mandated digital integration. These three entities collectively represent the strategic archetypes shaping competitive dynamics: super-app ecosystem builders, algorithmic pricing specialists, and incumbent fleet operators navigating regulatory modernization.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| Careem Networks FZ LLC |
| Bolt Technology OU |
| Dubai Taxi Corporation |
| Gett |
| inDrive |
| Hala Taxi |
| Saudi Limousine Service |
| Jeeny |
| Others |
Supply & Pricing Matrix
Petroleum price volatility exposure determines both fleet operator margin spreads and supply chain configuration across Middle-East and North Africa taxi markets. Fuel subsidy reduction scenarios in Algeria and Libya compress per-kilometer earnings while simultaneously forcing vehicle procurement shifts toward more efficient powertrains.
Pricing Analysis
The customization-premium spread separates standard sedan configurations from SUV and electric vehicle tiers across Riyadh and Dubai corridors. Three-tier pricing structure across premium, standard, and economy levels reflects vehicle type, corporate account bundling, and after-sales service inclusion. Pricing pressure stems from informal competition in Cairo and Casablanca street-hail markets. Corporate travel managers in Doha and Kuwait City exhibit lowest price sensitivity due to integrated expense management requirements.
Supply Chain Analysis
Export-control regimes on automotive semiconductor components limit fleet telematics hardware flows into Gulf Cooperation Council states. Vehicle assembly concentrates in Japan, South Korea, and China for combustion fleets, with battery cell supply anchored in China and South Korea for electric conversions. Raw material dependencies span lithium carbonate, rare earth magnets, and advanced driver-assistance system chipsets. Single-source vulnerability in semiconductor supply creates procurement risk. Distribution runs through authorized dealer networks and direct fleet procurement contracts with Dubai Taxi Corporation and Saudi Limousine Service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across booking channels, payment infrastructure, and regulatory jurisdictions creates niche entry points for specialized operators. Smartphone penetration divergence between Gulf states and North African metros splinters addressable demand into distinct service models.
For Market Incumbents: Pre-empt platform encroachment by accelerating electric fleet conversion ahead of Roads and Transport Authority mandates in Dubai and Abu Dhabi. Secure preferential licensing queues through Transport General Authority compliance investments. Consolidate driver supply through captive financing structures that match Uber's incentive algorithms.
For New Entrants and Emerging Players: Build out tourism corridor specialization across Egypt's Red Sea resort zones and Oman's heritage circuits where pre-booked multi-language services remain underpenetrated. Target corporate mobility accounts in Doha energy sector headquarters requiring carbon accounting integration. Deploy website-based pre-booking with embedded expense management to bypass app-store saturation.
For Investors and Strategic Acquirers: The market sits at a regulatory formalization phase that favors platform intermediaries with compliance infrastructure over asset-heavy cooperatives. Long-term viability centers on data infrastructure ownership rather than vehicle scale. Acquisition targets should demonstrate real-time dispatch algorithm capability and Transport General Authority permit holdings. Watch for driver protest movements demanding wage transparency as inflection indicators of platform margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | Secures preferential licensing queues under UAE and Saudi decarbonization mandates. |
| Super-App Ecosystem Integration | Extends customer stickiness beyond ride transactions into payments and delivery. |
| Corporate Account Expansion | Captures consolidated ground transportation spend from energy sector headquarters. |
| Real-Time Emissions Monitoring Compliance | Differentiates modernized fleets from aging cooperative vehicles under Dubai mandates. |
| Tourism Corridor Specialization | Addresses underpenetrated demand in Red Sea resorts outside urban platform saturation. |
Research Methodology
A spread of perspectives from fleet operations managers, Transport General Authority licensing officers, platform algorithm engineers, corporate travel procurement leads, and driver cooperative representatives converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through Roads and Transport Authority regulatory filings, Ministry of Transport permit databases, smartphone penetration statistics from national telecom regulators, and customs vehicle import records. Bottom-up trip volume estimates triangulated against top-down fleet size and utilization assumptions.
Demand-supply balance dynamics across vehicle procurement lead times, driver supply elasticity, and booking channel migration rates structured the analytical framework. Segmentation dimensions modeled include vehicle type, booking method, payment mode, and service model across the projection horizon. CAGRs derived from historical fleet expansion patterns and smartphone adoption curves. Industry-specific forecast inputs incorporated pilgrimage logistics seasonality and corporate hospitality demand cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed fleet consolidators or foreign platform entrants would shift outcomes. Material shifts in fuel subsidy regimes, driver unionization movements, or electric vehicle mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Europe Cross Border Road Freight Transport Market
Transportation & Logistics
Road Haulage Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
Transportation Aggregators Market
Transportation & Logistics
Saudi Arabia Land-Based Fuel Transportation Market
Transportation & Logistics
Poland Road Freight Transport Market
Transportation & Logistics
Cable Car and Ropeways Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
Trade-In and Buy-Back Logistics Programs Management Market
Transportation & Logistics
Traction Equipment Market
Transportation & Logistics
Global Fourth Party Logistics Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
ASEAN Road Freight Transport Market
Transportation & Logistics
United Kingdom Warehousing and Distribution Logistics Market