
 GCC Refrigerated Transport Market | 2026-2036
GCC Refrigerated Transport Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Refrigerated Transport Market Intelligence
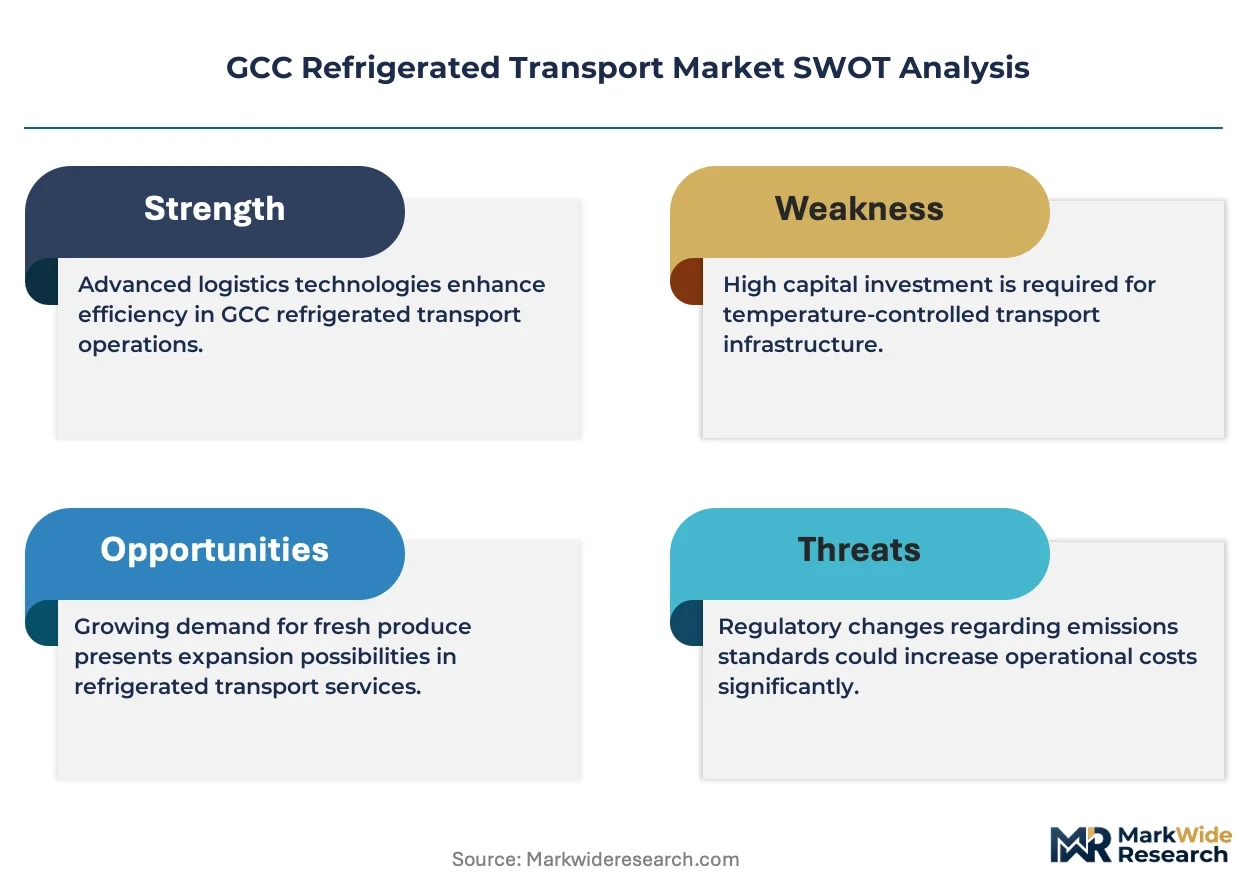
Temperature-controlled fleet management software is restructuring how logistics providers monetize refrigerated capacity across the GCC. Lineage Logistics leverages its automated warehouse network to extend cold-chain control into last-mile truck operations. Americold Logistics anchors regional presence through bonded cold-storage facilities at Jebel Ali and King Abdullah Port. Agility Logistics competes via integrated customs-clearance and temperature-monitoring services spanning Kuwait, Saudi Arabia, and the UAE.
Refrigerated transport encompasses the movement of temperature-sensitive goods using insulated vehicles and active cooling systems maintaining precise thermal thresholds, typically between minus twenty-five and plus twenty-five degrees Celsius depending on cargo type. The primary purpose centers on preserving pharmaceutical efficacy, food safety, and biotechnology material integrity across arid climates where ambient temperatures routinely exceed forty degrees Celsius. Truck transport dominates GCC refrigerated volume due to highway infrastructure connecting Saudi Arabia, UAE, Qatar, and Kuwait, while air freight commands premium margins for pharmaceutical urgency. Active temperature control systems lead equipment investment as Gulf regulators mandate real-time monitoring, though passive and hybrid configurations retain share in short-haul produce distribution.
SFDA in Saudi Arabia and MOHAP in the UAE enforce cold-chain documentation and temperature-validation protocols that elevate compliance costs but also consolidate demand toward certified fleet operators. Saudi Standards, Metrology and Quality Organization (SASO) technical regulations for vehicle insulation and refrigeration unit performance create entry barriers for uncertified equipment imports. Stakeholders must monitor evolving Gulf Cooperation Council harmonization of food safety and pharmaceutical distribution standards, as regulatory alignment between Saudi Arabia, UAE, Qatar, and Kuwait will determine whether pan-Gulf fleet operators achieve scale economies or remain fragmented by national compliance variations.
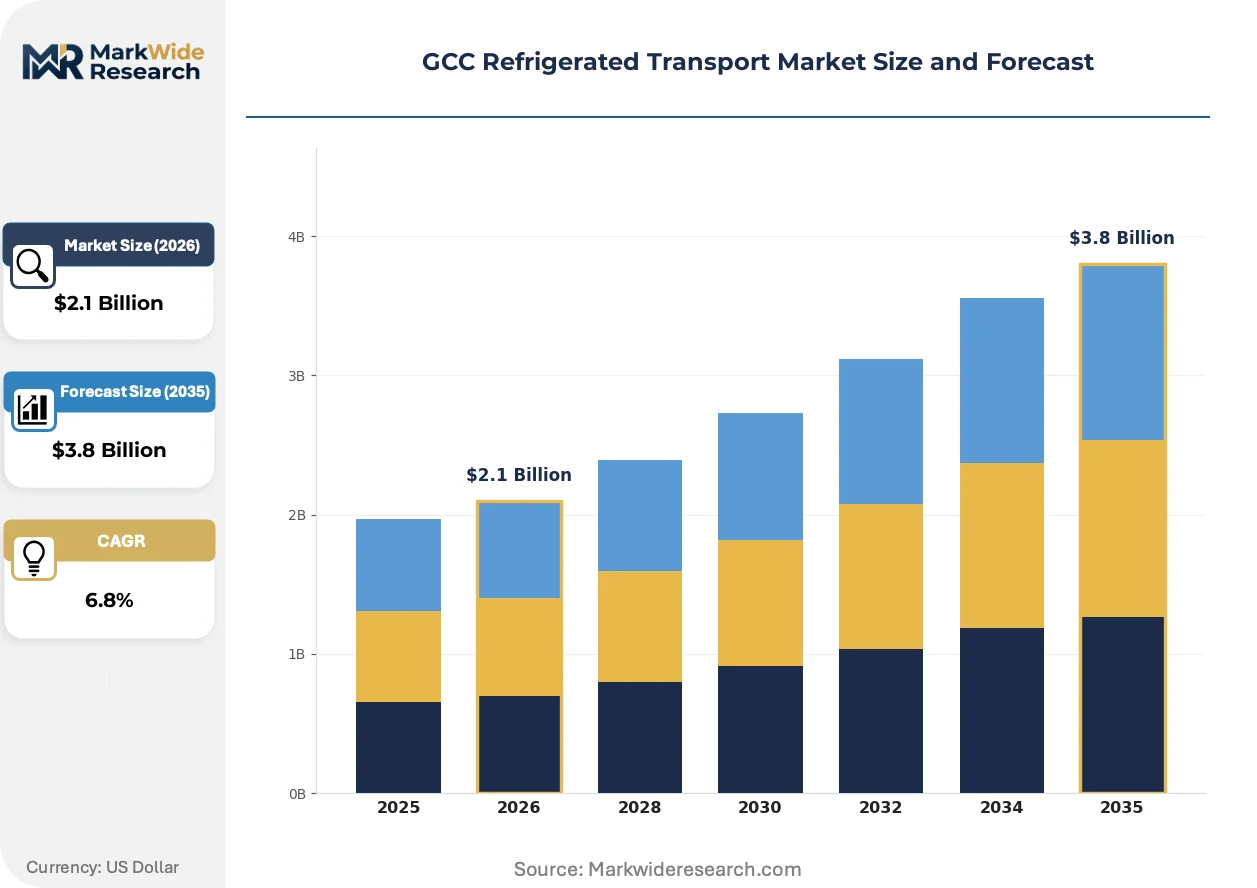
Market Dynamics
SFDA and MOHAP cold-chain mandates are forcing fleet operators to retrofit temperature-monitoring infrastructure across Saudi Arabia and the UAE, compressing margins for uncertified carriers while consolidating demand toward compliant logistics providers.
Growth Catalysts
- Pharmaceutical Distribution Mandates:SFDA temperature-validation protocols for biologics and vaccines require real-time tracking, pulling investment into certified refrigerated fleets across the Riyadh-Jeddah corridor.
- Food Import Dependency:GCC states import over eighty percent of food consumption, creating structural demand for temperature-controlled logistics at ports and inland distribution centers.
- Hybrid Cooling Systems:Solar-assisted refrigeration units are gaining traction in short-haul produce distribution, reducing diesel dependency for Kuwaiti and Qatari fleet operators.
Market Restraints
- Refrigerant Cost Volatility:Synthetic refrigerant prices fluctuate with petrochemical feedstock costs, squeezing maintenance budgets for independent Saudi Arabian carriers.
- Equipment Import Concentration:European and East Asian manufacturers dominate refrigeration unit supply, exposing GCC fleet operators to currency and shipping cost risks.
- Passive Cooling Limitations:Eutectic plate systems lack precision for pharmaceutical payloads, restricting their deployment to low-value produce routes.
Strategic Opportunities
- Bahrain and Oman Expansion:Underdeveloped cold-chain infrastructure in Manama and Muscat offers first-mover positioning for pan-GCC fleet operators seeking geographic diversification.
- Biotechnology Logistics:Cell and gene therapy shipments require cryogenic transport capabilities, opening premium service tiers beyond conventional pharmaceutical cold-chain.
- Customs-Temperature Integration:Bonded cold-storage facilities at Jebel Ali and King Abdullah Port enable seamless customs clearance with continuous thermal monitoring, reducing dwell time.
Industry Challenges
- Certified Technician Scarcity:Refrigeration system maintenance and IoT sensor calibration require specialized training that outpaces GCC vocational program output.
- Multi-Modal Integration Complexity:Seaport-to-airport pharmaceutical transfers demand protocol alignment between maritime and aviation cold-chain standards, creating handoff vulnerabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Refrigerated Transport Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transport Type: Truck, Rail, Ship, Air Temperature Control: Active, Passive, Hybrid, Thermo-insulated Cooling Equipment: Refrigerated Trucks, Containers, Cold Storage Units, X-ray Inspections End User: Food Industry, Pharmaceuticals, Biotechnology, Others |
| Companies Covered | Lineage Logistics, Americold Logistics, Ryder System, Inc., TIP Group, Agility Logistics, Penske Truck Leasing, DHL Supply Chain, Preferred Freezer Services, Fraikin, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Refrigerated Transport Market Strategic Shifts & Innovations
Telematics and predictive maintenance systems are restructuring fleet economics across Gulf logistics corridors, compressing downtime and enabling dynamic route optimization in extreme ambient conditions.
IoT-enabled temperature loggers with satellite connectivity are consolidating control over pharmaceutical cargo integrity. Saudi Arabian and Emirati third-party logistics providers are deploying these devices across reefer fleets to satisfy SFDA and MOHAP documentation requirements. Real-time alerts now trigger intervention protocols before thermal excursions breach validation thresholds, reducing spoilage liability.
SFDA's Good Distribution Practice guidelines and MOHAP's pharmaceutical storage regulations are tightening documentation burdens on cross-border shipments. Fleet operators must maintain continuous temperature records from manufacturer to dispensary, elevating compliance costs but also creating differentiation for certified carriers. The Riyadh-Jeddah corridor and Dubai-Abu Dhabi axis see the strictest enforcement, pushing consolidation toward integrated logistics platforms.
Pharmaceutical procurement departments are unbundling transport from warehousing contracts, awarding refrigerated lane capacity to specialized carriers rather than bundled 3PL agreements. This disintermediation pressures generalist logistics providers to acquire temperature-control certifications or exit high-value pharmaceutical segments. The shift is most pronounced among Saudi Arabian hospital group purchasing organizations and UAE-based specialty pharmacy distributors.
GCC Refrigerated Transport Market Segmentation
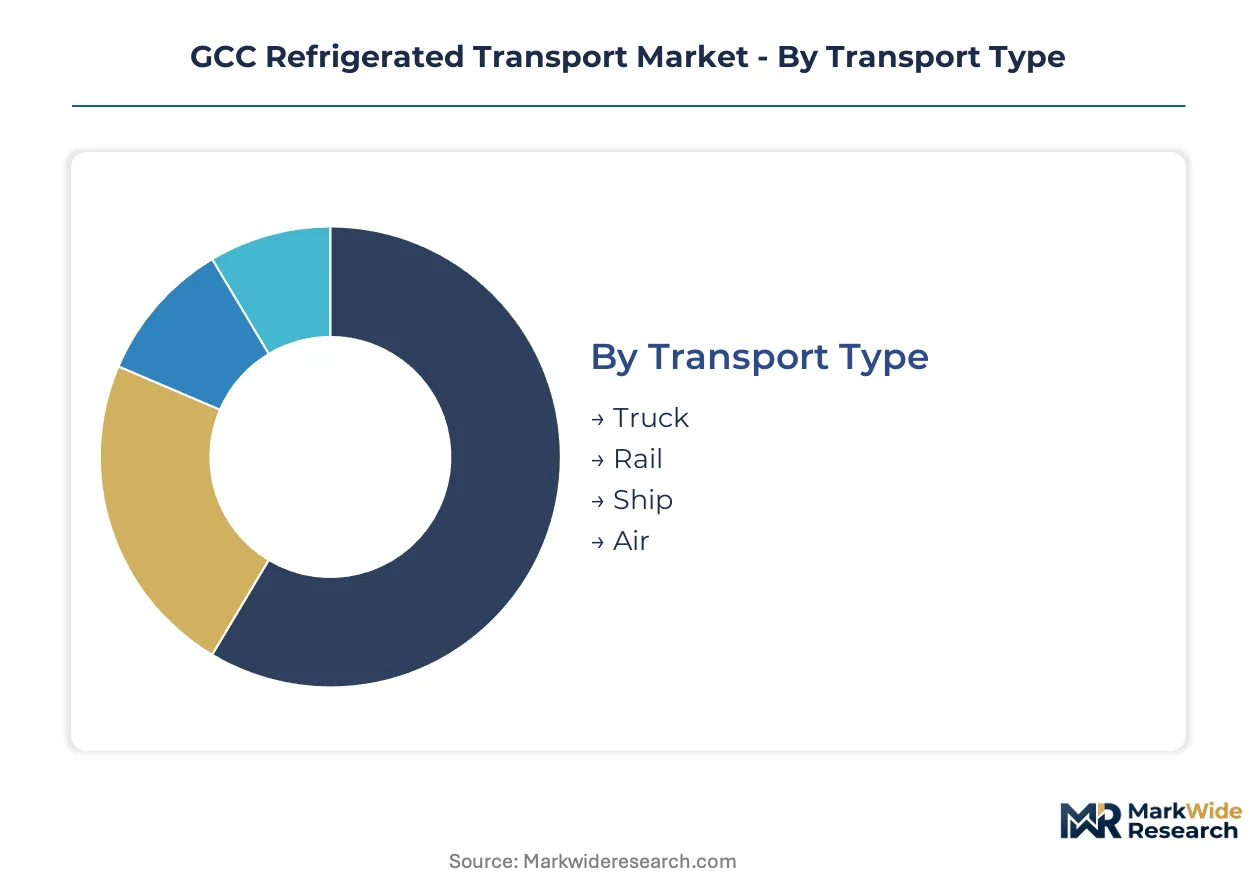
Segmentation in GCC refrigerated transport reveals how regulatory mandates and cargo sensitivity reshape equipment procurement and fleet configuration across Saudi Arabia, the UAE, and neighboring Gulf states.
Transport Type:
Standalone road transport dominates Gulf logistics corridors, while embedded multi-modal integration handles pharmaceutical urgency and perishable imports.
- Truck:Highway infrastructure connecting Riyadh-Jeddah and Dubai-Abu Dhabi corridors carries the majority of temperature-controlled volume. SFDA and MOHAP mandates for real-time tracking have accelerated investment in telematics-equipped reefer fleets across Saudi Arabia and the UAE.
- Air:Pharmaceutical urgency commands premium positioning for biologics and vaccines requiring rapid transit. Emirates SkyCargo and Saudia Cargo maintain dedicated cool-chain facilities at Dubai International and King Abdulaziz International airports.
- Ship:Maritime reefer containers handle bulk food imports through Jebel Ali and King Abdullah Port, though dwell-time risks at Gulf seaports limit pharmaceutical deployment.
- Rail:Etihad Rail's developing freight network offers intermodal potential for Saudi Arabian produce distribution, but temperature-control infrastructure remains nascent.
Volume placements concentrate in Truck; the faster expansion belongs to Air.
Temperature Control:
Cost tiers separate precision pharmaceutical applications from commodity produce distribution, with mid-tier hybrid systems capturing short-haul experimentation.
- Active:Compressor-driven refrigeration units with continuous power supply maintain precise thermal thresholds between minus twenty-five and plus twenty-five degrees Celsius. Saudi Arabian and Emirati regulators mandate these systems for vaccine distribution, consolidating demand toward certified fleet operators.
- Hybrid:Solar-assisted diesel-electric configurations reduce fuel dependency for Kuwaiti and Qatari carriers serving intra-Gulf produce routes. King Fahd Causeway crossings and Qatar-Saudi land corridors see early adoption.
- Passive:Eutectic plate systems without active cooling suit low-value produce over short durations. Temperature precision limitations exclude pharmaceutical use.
- Thermo-insulated:Insulated box bodies without mechanical refrigeration handle frozen cargo over brief transits. GCC customs authorities restrict these to bonded short-haul movements.
Cost concentration sits with Active systems; hybrid configurations are gaining share fastest.
Cooling Equipment:
Application-specific equipment separates integrated fleet operations from standalone asset deployment across port and inland logistics nodes.
- Refrigerated Trucks:Purpose-built vehicle units with integrated cooling systems form the backbone of GCC pharmaceutical distribution. SFDA Good Distribution Practice guidelines require validated performance documentation for biologics transport.
- Cold Storage Units:Fixed-site warehouse refrigeration at bonded facilities enables customs-temperature integration. Jebel Ali Free Zone and King Abdullah Economic City anchor regional capacity.
- Containers:Intermodal reefer boxes standardize maritime-airport handoffs for imported perishables. Equipment import concentration toward European and East Asian manufacturers exposes operators to currency risk.
- X-ray Inspections:Cold-chain compatible screening systems maintain thermal continuity during customs security protocols. Dubai Customs and Saudi Customs deploy these at primary pharmaceutical entry points.
Asset deployment concentrates in Refrigerated Trucks; Cold Storage Units are climbing the fastest.
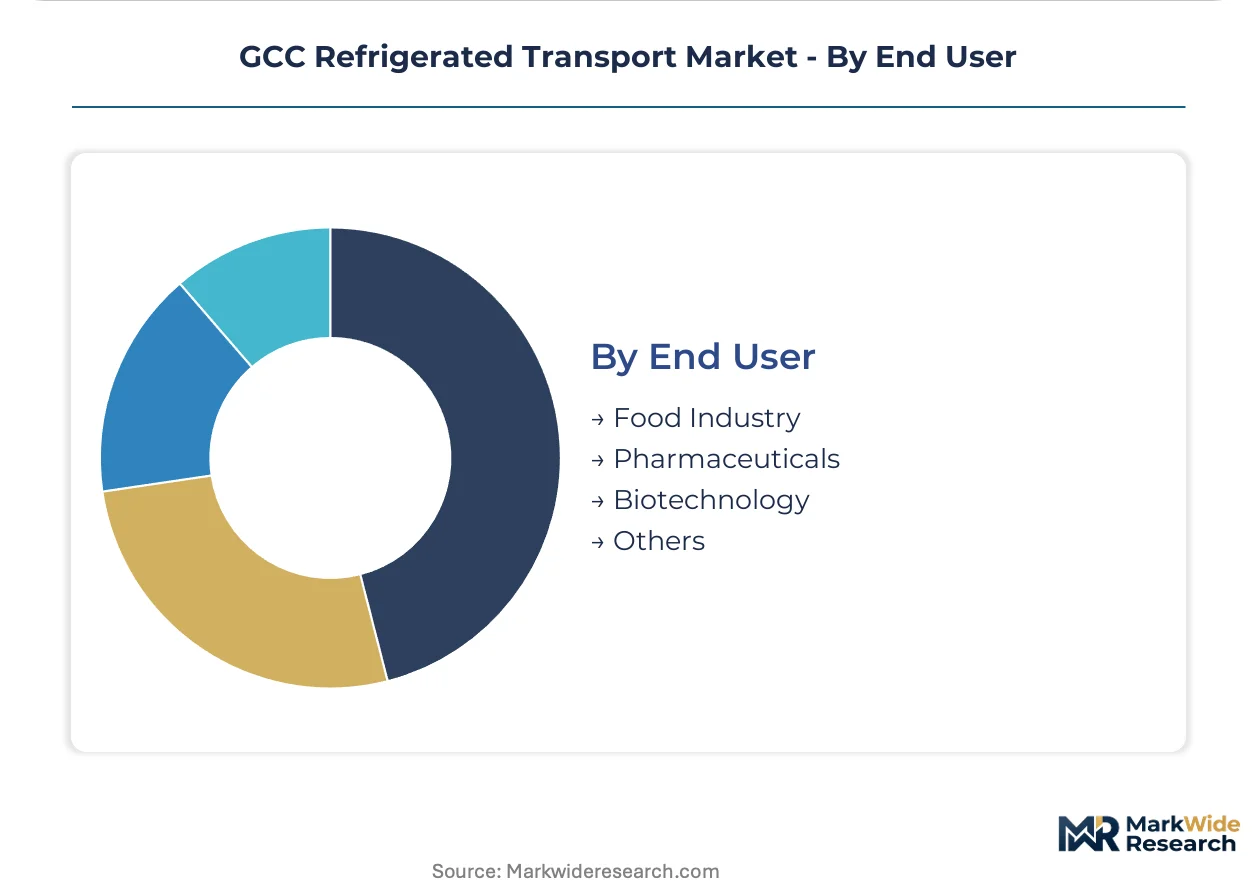
End User:
Customer type determines compliance burden and margin structure, with certified pharmaceutical carriers commanding pricing premiums over commodity food distributors.
- Pharmaceuticals:Biologics, vaccines, and temperature-sensitive therapeutics demand continuous validation from manufacturer to dispensary. Saudi hospital group purchasing organizations and UAE specialty pharmacy distributors unbundle transport from warehousing contracts.
- Biotechnology:Cell and gene therapy shipments require cryogenic capabilities below conventional pharmaceutical ranges. Premium service tiers open for operators investing in liquid nitrogen transport infrastructure.
- Food Industry:Imported meat, dairy, and fresh produce account for structural demand given GCC food import dependency exceeding eighty percent. SASO technical regulations govern vehicle insulation standards.
- Others:Floral products, chemicals, and specialized industrial materials occupy niche positioning with variable temperature requirements.
Revenue concentration rests with Pharmaceuticals; Biotechnology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Cooperation Council states consume far more temperature-sensitive goods than they produce, creating import-dependent cold-chain corridors that concentrate fleet investment around seaports and pharmaceutical distribution hubs.
Saudi Arabia
Pharmaceutical import volumes and domestic vaccine distribution networks drive refrigerated fleet expansion across the Kingdom. SFDA Good Distribution Practice mandates enforce continuous temperature validation from port to dispensary. The Riyadh-Jeddah corridor anchors certified reefer capacity, with King Abdullah Port bonded cold-storage facilities enabling customs-temperature integration for biologics.
United Arab Emirates
Specialty pharmacy distributors and hospital group purchasing organizations unbundle transport contracts from warehousing agreements. MOHAP pharmaceutical storage regulations require real-time tracking documentation for temperature-sensitive therapeutics. Dubai-Abu Dhabi logistics axis concentrates telematics-equipped fleets, with Jebel Ali Free Zone serving as the regional hub for maritime-airport cold-chain handoffs.
Kuwait
Food import dependency and short-haul produce distribution sustain demand for hybrid cooling configurations. Solar-assisted diesel-electric units reduce fuel costs for carriers serving intra-Gulf routes across the King Fahd Causeway. Kuwait City logistics clusters experiment with passive cooling for low-value agricultural imports from regional trading partners.
Qatar
Biotechnology logistics and cell therapy shipments open premium service tiers requiring cryogenic transport capabilities below conventional pharmaceutical ranges. The national pharmaceutical regulator enforces cold-chain documentation alignment with neighboring Gulf standards. Doha pharmaceutical free zones attract specialized carriers investing in liquid nitrogen infrastructure.
Bahrain and Oman
Underdeveloped cold-chain infrastructure in Manama and Muscat offers first-mover positioning for pan-GCC fleet operators. Produce import volumes through Port Sultan Qaboos and Khalifa Bin Salman Port create baseline demand for temperature-controlled trucking. Regulatory harmonization discussions with Saudi Arabia and the UAE determine whether certified operators achieve scale economies or remain fragmented by national compliance variations.
GCC Refrigerated Transport Market Key Industry Players
Capital-heavy asset owners compete with asset-light logistics orchestrators across Gulf cold-chain corridors. Fleet operators with owned refrigeration units and bonded warehouse infrastructure command pricing premiums in pharmaceutical segments, while third-party logistics platforms aggregate capacity without fixed-asset exposure. Three archetypes dominate: integrated cold-storage and transport operators, specialized pharmaceutical carriers, and multi-modal freight forwarders. Consolidation pressures favor acquisition of certified fleets by warehousing incumbents, while technology partnerships embed IoT monitoring into legacy equipment.
Within the integrated infrastructure tier, Lineage Logistics and Americold Logistics exemplify operators extending automated warehouse control into last-mile transport. Agility Logistics occupies a position spanning customs-clearance integration and temperature-monitoring services across Kuwait, Saudi Arabia, and the UAE. These three entities anchor competitive positioning through bonded facility networks at Jebel Ali and King Abdullah Port.
| Leading Market Players |
|---|
| Lineage Logistics |
| Americold Logistics |
| Ryder System, Inc. |
| TIP Group |
| Agility Logistics |
| Penske Truck Leasing |
| DHL Supply Chain |
| Preferred Freezer Services |
| Fraikin |
| Others |
Cost & Logistics Intelligence
Captive cold-storage infrastructure at Jebel Ali and King Abdullah Port anchors both supply positioning and pricing power for integrated operators, while asset-light carriers face margin compression from certification burdens and equipment import costs. Bonded warehouse ownership enables customs-temperature integration that commands premium rates from pharmaceutical shippers, whereas independent fleets compete on spot-market food logistics with thinner returns.
Pricing Analysis
Margin tightening in pharmaceutical tiers reflects unbundling of transport from warehousing contracts by Saudi hospital group purchasing organizations and UAE specialty pharmacy distributors. Three-tier pricing structure across certified pharmaceutical, standard food-grade, and economy produce levels separates SFDA-validated biologics carriers from SASO-compliant food distributors and short-haul passive cooling operators. Cost-down pressure on commodity food transport accelerates because diesel price volatility and refrigerant feedstock costs squeeze independent Saudi Arabian carriers serving import-dependent distribution networks. Pharmaceutical procurement departments demonstrate lowest price sensitivity due to compliance mandates, while produce importers exhibit highest sensitivity to per-kilometer rates.
Supply Chain Analysis
Refrigeration unit refurbishment flows from European and East Asian manufacturers back to GCC fleet operators concentrate service dependencies and spare parts availability across the Riyadh-Jeddah and Dubai-Abu Dhabi corridors. Equipment supply draws from Germany, Japan, and South Korea for compressor systems, while telematics hardware sources from Chinese and Taiwanese sensor manufacturers. Single-source vulnerability around SFDA-certified validation equipment creates procurement bottlenecks for Saudi carriers expanding biologics capacity. Distribution runs through bonded cold-storage facilities at King Abdullah Port and Jebel Ali Free Zone, with last-mile trucking completing pharmaceutical delivery to hospital dispensaries and specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into bonded warehouse ownership represents the decisive competitive lever across GCC cold-chain corridors, as control over customs-temperature handoffs determines pharmaceutical pricing power and compliance differentiation.
For Market Incumbents: To counter disintermediation pressures from pharmaceutical procurement departments unbundling transport contracts, Lineage Logistics and Americold Logistics should deepen backward integration into IoT-enabled fleet assets while securing additional bonded capacity at emerging port zones. Certification investment in SFDA Good Distribution Practice and MOHAP temperature-validation protocols remains essential for margin defense against asset-light digital freight platforms aggregating spot capacity.
For New Entrants and Emerging Players: SFDA cold-chain mandates in Saudi Arabia open a window for specialized biotechnology carriers investing in cryogenic transport infrastructure below conventional pharmaceutical ranges. Bahrain and Oman present the most penetrable geographies given underdeveloped cold-chain infrastructure in Manama and Muscat, with first-mover positioning achievable through solar-assisted hybrid cooling configurations for intra-Gulf produce routes. A go-to-market angle anchored in customs-clearance integration with continuous thermal monitoring addresses the dwell-time vulnerabilities that fragment incumbent service quality.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated warehousing incumbents seeking certified fleet assets to complete vertical control over pharmaceutical distribution. Long-term viability favors operators with captive bonded storage at Jebel Ali or King Abdullah Port combined with telematics-equipped reefer capacity serving the Riyadh-Jeddah and Dubai-Abu Dhabi axes. The signal to watch is regulatory harmonization progress between Saudi Arabia, UAE, Qatar, and Kuwait, as pan-GCC compliance standards would trigger consolidation premiums for certified operators with cross-border scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Cold-Storage Expansion | Ownership of customs-integrated facilities at King Abdullah Port commands pharmaceutical pricing premiums. |
| IoT Telematics Fleet Deployment | Real-time temperature validation satisfies SFDA and MOHAP documentation mandates for biologics carriers. |
| Cryogenic Transport Capability Investment | Liquid nitrogen infrastructure opens premium service tiers for cell and gene therapy shipments in Qatar. |
| Solar-Assisted Hybrid Cooling Adoption | Diesel-electric configurations reduce fuel dependency for Kuwaiti carriers on King Fahd Causeway routes. |
| Cross-Border Regulatory Harmonization | Alignment of Saudi, Emirati, Qatari, and Kuwaiti standards enables pan-GCC fleet scale economies. |
Research Approach
Independent corroboration across fleet operator interviews, pharmaceutical logistics directors, and customs authority documentation underwrites the qualitative findings on regulatory enforcement patterns. Primary fieldwork engaged cold-chain managers at Saudi and Emirati third-party logistics providers, SFDA compliance officers, hospital procurement committees, and refrigeration equipment distributors. Secondary validation drew from SASO technical regulations, MOHAP pharmaceutical storage guidelines, bonded facility operating disclosures, and customs trade data on reefer container throughput. Bottom-up fleet capacity estimates triangulate against top-down pharmaceutical import value projections.
Historical reference periods spanning pre-pandemic baseline through post-SFDA mandate implementation anchor the forecast window across the projection horizon. Segmentation modeling incorporates transport mode, temperature control system type, cooling equipment category, and end-user compliance tier. CAGRs derive from slope analysis of certified fleet expansion rates and pharmaceutical logistics outsourcing trends. Industry-specific inputs include SFDA validation protocol adoption curves and solar-assisted refrigeration penetration in short-haul produce distribution.
The model assumes a particular technology adoption path; alternative pathways for cryogenic transport infrastructure or hydrogen-powered refrigeration units would alter the outlook. Forecasts reflect assumptions around regulatory enforcement continuity and equipment import cost stability. Practitioners should monitor Gulf Cooperation Council harmonization negotiations and European refrigerant export policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Indonesia Road Freight Transport Market
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
Transportation Condensing Units Market
Transportation & Logistics
North America Road Freight Transportation Market
Transportation & Logistics
Japan Road Freight Transport Market
Transportation & Logistics
Spain Cold Chain Logistics Market
Transportation & Logistics
Europe Road Freight Transport Market
Transportation & Logistics
Hazardous Chemicals Transportation Solution Market
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
Europe Freight and Logistics Market
Transportation & Logistics
Malaysia Domestic CEP Market
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Refrigerated Trailer Market
Transportation & Logistics
Traction Equipment Market
Transportation & Logistics
Digital Shipment Market
Transportation & Logistics
Cold Chain Vehicles Market