
 Padded Mailers Market | 2026-2036
Padded Mailers Market Size, Share, and Industry Trends Forecast 2026-2036
Padded Mailers Market Intelligence
E-commerce retailers are unwinding the dominance of traditional B2B procurement channels in padded mailer demand. Sealed Air Corporation leverages its global manufacturing footprint to supply automated fulfillment lines. Pregis LLC differentiates through specialized cushioning technologies for fragile goods. Mondi plc anchors European demand with integrated kraft paper sourcing from its forestry operations.
Padded mailers are protective shipping envelopes constructed with internal cushioning layers—typically bubble wrap, foam, or fiber padding—sealed between outer sheets of paper or plastic to absorb impact during transit. Standard burst strengths range from 30 to 60 psi depending on material construction, with paper-based variants using 90-140 gsm kraft facings to balance puncture resistance with recyclability. Kraft mailers lead in regulatory-compliant regions where extended producer responsibility schemes penalize plastic content, while bubble mailers retain share in cost-sensitive logistics corridors. E-commerce shipping drives volume across all material types, though subscription services represent the fastest-growing application as curated box services specify branded, damage-resistant presentation packaging.
The EPA regulates mailer material disposal under municipal solid waste frameworks, while the EU Green Deal and F-Gas Regulation indirectly shape demand by restricting plastic film specifications. ECHA's REACH compliance requirements for chemical additives in polyethylene and polypropylene films raise reformulation costs for non-compliant suppliers. Stakeholders must monitor how California's SB 54 extended producer responsibility implementation reshapes material specifications before other US states adopt parallel frameworks.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing virgin plastic use across fulfillment networks, forcing material substitution toward fiber-based cushioning and recycled-content films. This regulatory pressure cascades through procurement specifications at major e-commerce platforms.
Growth Catalysts
- E-commerce order volume expansion:Third-party logistics providers in Germany and the Netherlands are scaling automated sortation systems that require standardized mailer dimensions, driving bulk purchasing agreements with integrated cushioning suppliers.
- REACH compliance reformulation:ECHA's tightening restrictions on chemical additives in polyethylene films are accelerating migration toward bio-based barrier coatings that maintain moisture resistance without persistent organic pollutants.
- Subscription box specification:Curated delivery services demand branded, damage-resistant presentation packaging with tear-strip openings, creating specification pull for premium kraft-bubble hybrid constructions.
Market Restraints
- Pulp price volatility:Kraft paper facing costs fluctuate with Nordic softwood supply disruptions, compressing margins for European converters dependent on integrated paper sourcing.
- Recycling infrastructure gaps:Multi-material laminates combining polyethylene bubble layers with paper exteriors face limited municipal sorting capacity in Italy and Spain, creating disposal friction for end-users.
- Plastic film substitution:Rigid corrugated inserts and molded fiber cushioning are capturing share in high-value electronics shipping, displacing padded mailers in damage-sensitive applications.
Strategic Opportunities
- Extended producer responsibility expansion:California's SB 54 implementation creates precedent for state-level packaging fees that reward recycled-content mailers, opening specification windows for compliant suppliers before federal harmonization.
- Pharmaceutical cold-chain adaptation:Insulated padded envelopes with phase-change material integration are penetrating temperature-sensitive generic drug distribution, replacing expanded polystyrene shippers in last-mile delivery.
- Direct-to-consumer brand packaging:Unboxing experience specifications from digitally native vertical brands are driving demand for custom-printed, recyclable cushioning with water-based inks and adhesive-free closure systems.
Industry Challenges
- Automated packaging line integration:Fulfilment centers retrofitting legacy equipment for variable-dimension mailers face downtime costs and technician shortages during mechanical conversion.
- Multi-jurisdiction certification timelines:Suppliers seeking simultaneous ASTM D642 burst strength validation and EU harmonized EN 13432 compostability claims encounter conflicting test protocols and extended approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Padded Mailers Market |
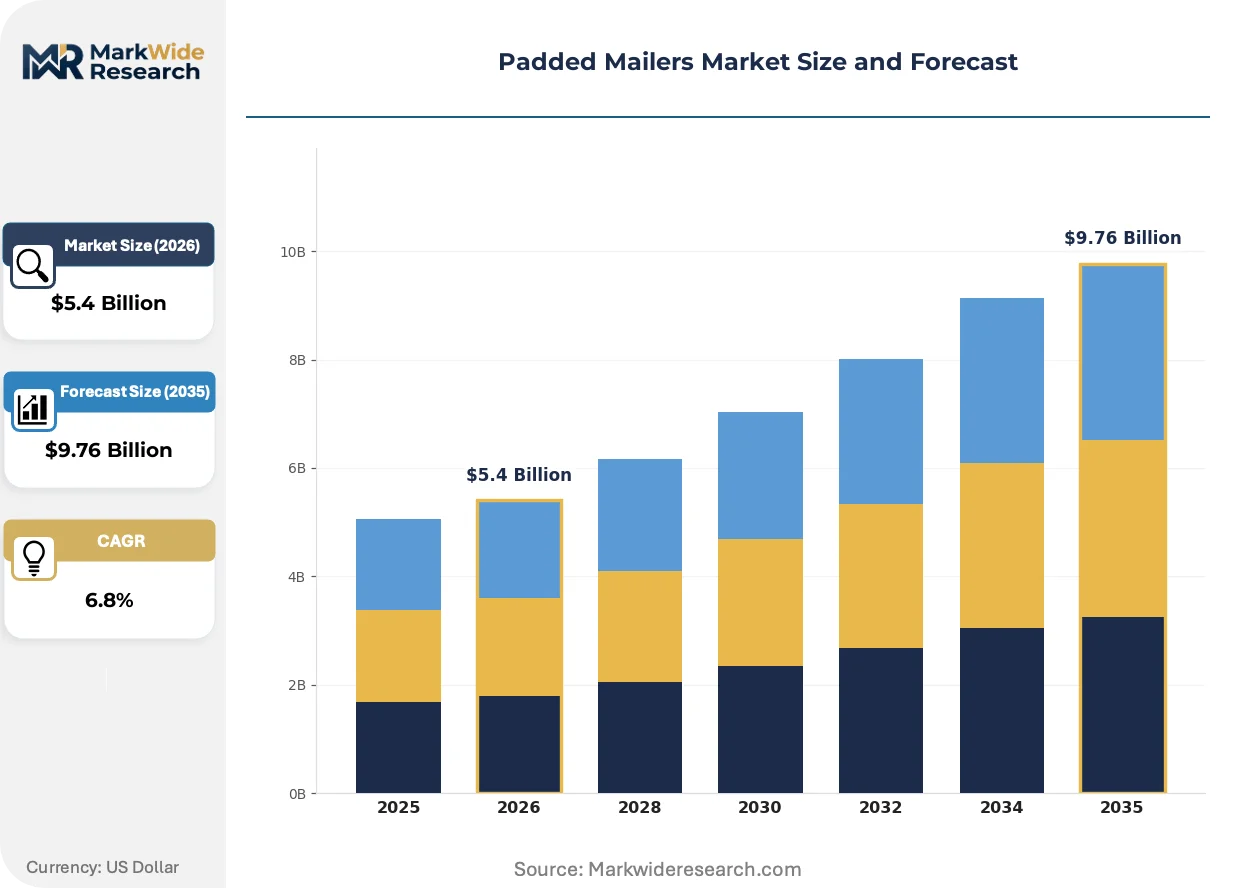
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bubble Mailers, Foam Mailers, Paper Mailers, Plastic Mailers, Kraft Mailers Material: Polyethylene, Kraft Paper, Bubble Wrap, Foam, Polypropylene Application: E-commerce Shipping, Subscription Services, Document Protection, Gift Packaging, Retail Fulfillment End User: Online Retailers, Logistics Providers, Publishing Houses, Promotional Companies, Courier Services |
| Companies Covered | Sealed Air Corporation, Pregis LLC, PAC Worldwide Corporation, ProAmpac Holdings Inc., Mondi plc, Intertape Polymer Group Inc., International Paper, Smurfit Kappa, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Padded Mailers Market Strategic Shifts & Innovations
Material science advances and regulatory sequencing are restructuring competitive advantage around circularity credentials rather than unit cost alone. Three developments are compressing incumbent positioning.
Molded pulp cushioning inserts are displacing polyethylene bubble layers in mid-weight electronics shipping. Dell and HP procurement teams have specified fiber-based protection for laptop deliveries under 2kg. This shift is compressing demand for traditional bubble mailers in business-to-consumer channels while expanding pulp molding equipment orders at European converters.
REACH Annex XVII restrictions on microplastics are tightening specifications for sheddable polyethylene films in cushioning applications. Industrial consequence includes mandatory reformulation of bubble wrap additives by 2027. German mailer manufacturers are accelerating bio-based barrier coating development to maintain moisture resistance without restricted polymer grades.
Consolidated buying by platform aggregators is compressing supplier margins while expanding volume commitments. Amazon's Frustration-Free Packaging certification now mandates 100% recyclable materials for vendor-supplied mailers, displacing multi-material laminates from approved supplier lists. This specification shift is most visible in North American and Western European fulfillment networks where platform procurement teams centralize packaging decisions across third-party sellers.
Padded Mailers Market Segmentation
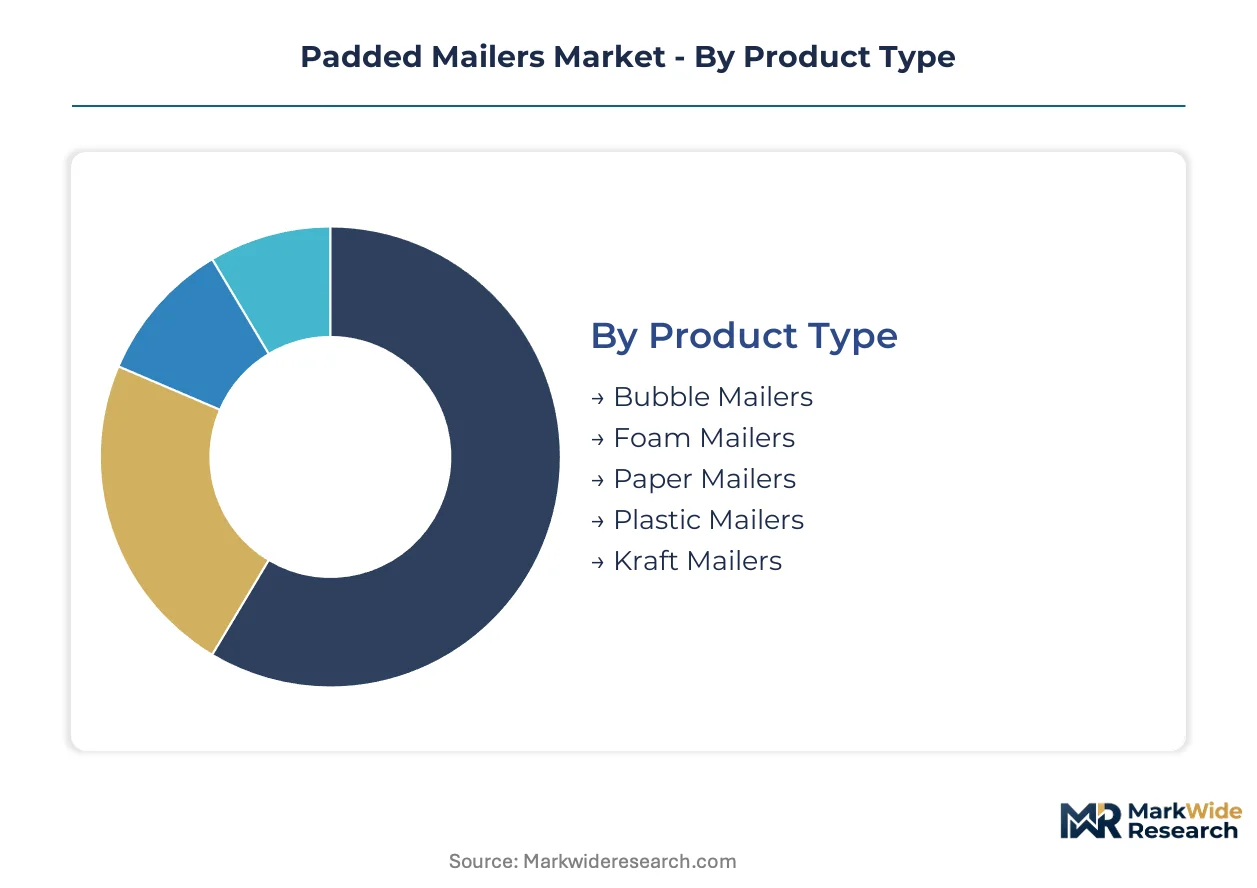
Padded mailer specifications diverge sharply across procurement channels. E-commerce platforms enforce dimensional standardization while subscription services prioritize branded presentation. Material selection tracks regulatory pressure zones rather than pure cost optimization.
Product Type:
REACH Annex XVII restrictions on microplastics and the EU Packaging and Packaging Waste Regulation are fragmenting product specifications by compliance zone. Kraft-based constructions gain procurement share where extended producer responsibility schemes penalize plastic content, while bubble laminates retain volume in cost-driven logistics corridors.
- Kraft Mailers:Constructed from 90-140 gsm unbleached kraft paper with internal fiber padding or corrugated flute cushioning. German fulfillment centers drive bulk procurement under the EU Green Deal's material recovery mandates, with Amazon's Frustration-Free Packaging certification now mandating 100% recyclable constructions for vendor-supplied units.
- Bubble Mailers:Polyethylene film exterior bonded to air-cell cushioning layers delivering 30-60 psi burst resistance. Logistics providers in the Netherlands specify these for automated sortation compatibility, though ECHA's 2027 microplastic restrictions are forcing additive reformulation toward bio-based barrier coatings.
- Foam Mailers:Expanded polyethylene or polyurethane cushioning for high-impact protection.
- Paper Mailers:Lightweight fiber-based protection without air-cell layers for document-grade shipments.
- Plastic Mailers:Mono-material polyethylene constructions for moisture-critical applications.
Kraft mailers handle the majority of throughput in regulatory-compliant European markets; subscription box specifications are expanding fastest for hybrid kraft-bubble constructions with tear-strip openings.
Material:
Cost tiers separate commodity feedstocks from certified sustainable alternatives. Virgin polyethylene competes with post-consumer recycled grades and agricultural fiber substitutes as procurement teams balance unit economics against circularity credentials.
- Kraft Paper:Unbleached softwood pulp facing sourced from Nordic forestry operations. Mondi plc anchors European supply through integrated paper production, though pulp price volatility compresses converter margins during supply disruptions.
- Polyethylene:Virgin and recycled-content films for bubble layer production. California's SB 54 extended producer responsibility implementation creates specification windows for recycled-content grades before federal harmonization.
- Bubble Wrap:Air-entrapment films requiring additive reformulation under REACH restrictions.
- Foam:Expanded polystyrene and polyurethane alternatives for temperature-sensitive applications.
- Polypropylene:Higher-stiffness films for puncture-resistant exterior layers.
Polyethylene retains volume leadership across cost-sensitive channels; kraft paper is climbing fastest where platform procurement centralizes packaging decisions.
Application:
Customer type determines performance specifications and margin structure. Automated fulfillment lines demand dimensional consistency while direct-to-consumer brands prioritize unboxing experience.
- E-commerce Shipping:Standardized dimensions for high-velocity sortation systems. Third-party logistics providers in Germany scale automated packaging equipment requiring precise mailer tolerances, with downtime costs during mechanical conversion creating supplier stickiness.
- Subscription Services:Curated box services specify branded, damage-resistant presentation packaging with water-based inks and adhesive-free closure systems. Digitally native vertical brands drive custom-printed cushioning demand.
- Document Protection:Lightweight fiber-based mailers for publishing and legal sector shipments.
- Gift Packaging:Premium finishing and decorative closures for seasonal retail peaks.
- Retail Fulfillment:Store-to-customer direct shipping from brick-and-mortar inventory.
E-commerce shipping commands the highest absolute volume; subscription services are expanding most quickly on specification pull from curated delivery platforms.
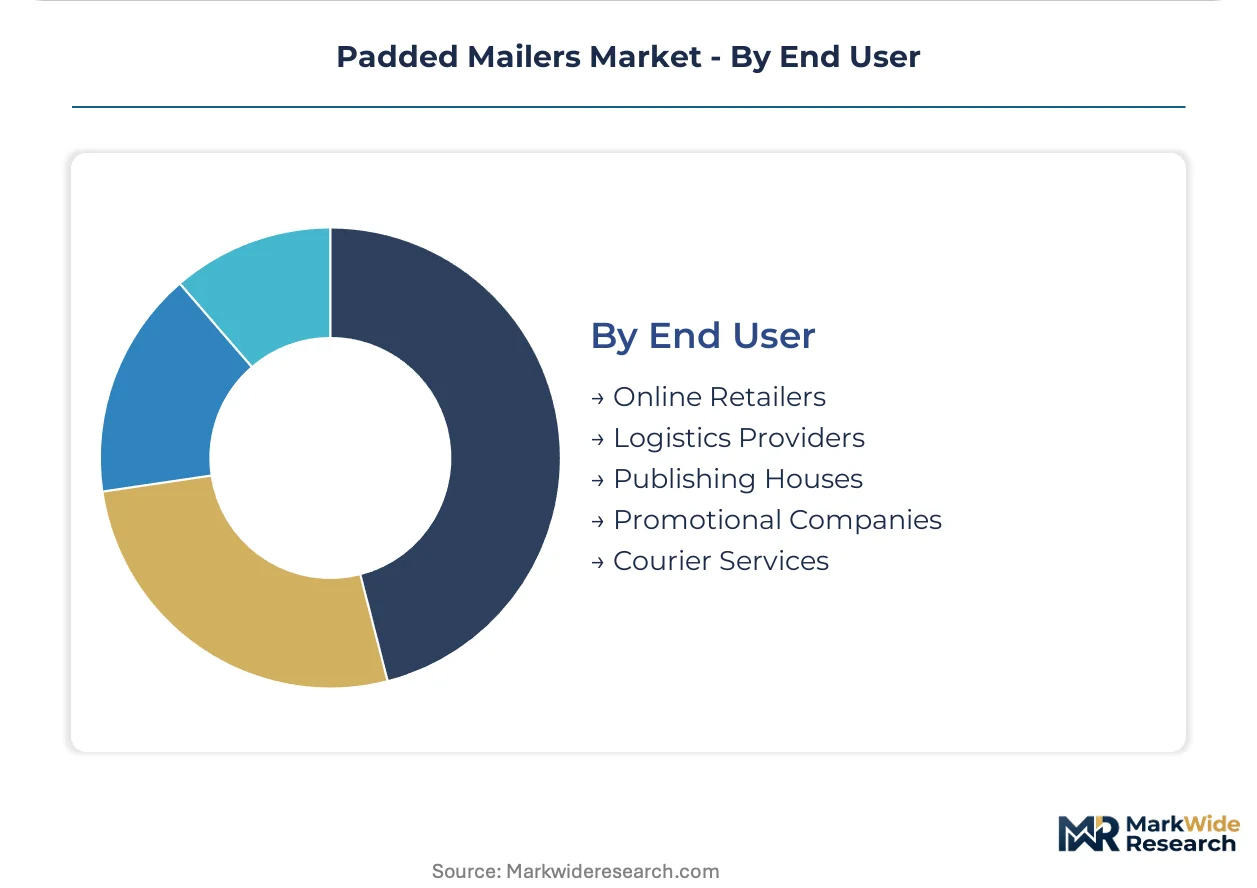
End User:
Procurement concentration varies by fulfillment network density. Platform aggregators consolidate buying power while fragmented courier services negotiate spot purchasing.
- Online Retailers:Amazon, Zalando, and Otto Group centralize packaging specifications across third-party seller networks. Frustration-Free Packaging certification mandates displace multi-material laminates from approved supplier lists.
- Logistics Providers:DHL, DPD, and GLS negotiate bulk agreements with integrated cushioning suppliers. Automated sortation investments in the Netherlands and Germany require standardized mailer dimensions.
- Courier Services:Fragmented last-mile operators with variable specification requirements.
- Publishing Houses:Document-grade protection for periodical and book distribution.
- Promotional Companies:Branded mailers for direct marketing campaigns.
Online retailers consolidate the largest procurement volumes; logistics providers are gaining specification influence fastest through automated fulfillment investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-commerce fulfillment networks concentrate procurement power among third-party logistics providers and platform aggregators. Germany, the United States, China, the Netherlands, and Japan represent the dominant demand centers where automated sortation investments and regulatory sequencing reshape material specifications.
Germany
Fulfillment center density in North Rhine-Westphalia and Bavaria drives bulk procurement of kraft mailers under the EU Packaging and Packaging Waste Regulation. ECHA's REACH compliance deadlines for 2027 are accelerating additive reformulation among polyethylene film suppliers. The Duisburg logistics corridor hosts automated packaging equipment retrofits requiring standardized mailer tolerances.
United States
Amazon's Frustration-Free Packaging certification mandates 100% recyclable materials across third-party seller networks. California's SB 54 extended producer responsibility implementation creates specification windows for recycled-content grades before federal harmonization. The Inland Empire distribution cluster in Southern California scales automated sortation systems requiring precise dimensional consistency.
China
Cross-border e-commerce expansion through Alibaba and JD.com drives volume for protective shipping envelopes. The MIIT's dual carbon goals and GB standards for packaging recyclability are tightening virgin plastic specifications. The Yangtze River Delta manufacturing belt concentrates converter capacity for export-oriented mailer production.
Netherlands
Rotterdam-Europoort logistics providers negotiate bulk agreements with integrated cushioning suppliers for automated fulfillment lines. The EU Green Deal's material recovery mandates penalize multi-material laminates in procurement specifications. Eindhoven's distribution technology cluster pilots variable-dimension mailer handling equipment.
Japan
Subscription box services from Rakuten and curated delivery platforms specify branded presentation packaging with tear-strip openings. METI's packaging waste reduction targets and JIS standards for recyclability favor fiber-based cushioning alternatives. The Kanto region's Tokyo-Osaka fulfillment corridor concentrates demand for premium kraft-bubble hybrid constructions.
Padded Mailers Market Key Industry Players
Player mix skews toward integrated paper producers and specialized protective packaging fabricators. Tiered structure separates scale-driven multinationals with captive forestry operations from regional converters dependent on spot pulp purchasing. Strategic archetypes include backward-integrated kraft paper suppliers, automated equipment-aligned film specialists, and pharmaceutical cold-chain adapters. Dominant competitive moves center on forestry asset control and bio-based barrier coating development.
Among integrated paper producers, Mondi plc anchors European supply through captive forestry operations. Sealed Air Corporation occupies a position exemplifying global manufacturing footprint alignment with automated fulfillment lines. Pregis LLC represents the specialized cushioning technology archetype for fragile goods applications. These three fabricators sit within distinct competitive vectors—forestry integration, automation scale, and technical specialization—rather than direct product overlap.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis LLC |
| PAC Worldwide Corporation |
| ProAmpac Holdings Inc. |
| Mondi plc |
| Intertape Polymer Group Inc. |
| International Paper |
| Smurfit Kappa |
| 3M |
| Others |
Cost & Logistics Intelligence
Sixty-day kraft paper inventory cycles at Nordic mills directly shape converter pricing power, as extended producer responsibility schemes in Germany and California compress margins for non-compliant suppliers while rewarding recycled-content grades with specification access.
Pricing Analysis
Current-generation bio-based barrier coatings command premium positioning against prior-generation polyethylene films and next-generation molded pulp alternatives. Three-tier pricing structure across premium, standard, and economy levels separates Amazon Frustration-Free certified mailers from commodity bubble laminates and unbranded kraft constructions. Price differentiation rests on REACH compliance tier and volume scale, with subscription box specifications tolerating higher unit costs for branded presentation. Cost compression in standard-grade bubble mailers is intensifying because ECHA's 2027 microplastic restrictions force additive reformulation. Third-party logistics providers exhibit highest price sensitivity; curated delivery platforms show lowest.
Supply Chain Analysis
Sweden and Finland anchor unbleached softwood pulp production for kraft facing, while Germany and the Netherlands concentrate converter capacity for automated fulfillment integration. Raw material dependencies draw from Nordic forestry operations, recycled polyethylene feedstocks, and bio-based barrier coating chemicals. Supply chain risk centers on single-source vulnerability in integrated paper sourcing where Mondi plc controls captive forestry assets. Distribution runs through platform aggregator procurement teams at Amazon and Zalando, with third-party sellers locked into approved supplier lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where REACH compliance timelines and extended producer responsibility schemes create sticky specification relationships that resist price-based displacement.
For Market Incumbents: Compound forestry asset control with bio-based barrier coating R&D to defend against molded pulp substitution in electronics shipping. Sealed Air Corporation's global manufacturing footprint exemplifies the automation-scale moat; replicate through capacity addition in the Duisburg logistics corridor. Certification investment in EU harmonized EN 13432 compostability claims locks out regional converters dependent on spot pulp purchasing. For New Entrants and Emerging Players: California SB 54 fast-track certification opens specification windows before federal harmonization spreads extended producer responsibility frameworks. White-space targets concentrate in pharmaceutical cold-chain adaptation for temperature-sensitive generic drug distribution, and in direct-to-consumer brand packaging for digitally native vertical brands seeking unboxing differentiation. Go-to-market through water-based ink custom-printing partnerships with curated box services bypasses incumbent automation-scale advantages. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underutilized pulp molding equipment and stranded polyethylene film assets. Long-term viability favors backward-integrated specialists with captive forestry and REACH-compliant coating capabilities over commodity converters. Signal to monitor: Amazon Frustration-Free Packaging certification expansion beyond North America and Western Europe into Asian fulfillment networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestry Assets | Mondi plc's captive Nordic softwood supply insulates margin compression from pulp price volatility. |
| REACH-Compliant Coating Development | Bio-based barrier investments by German manufacturers secure specification access under ECHA's 2027 microplastic restrictions. |
| Automated Fulfillment Line Certification | Precision tolerance validation with DHL and DPD creates supplier stickiness through downtime cost barriers. |
| Pharmaceutical Cold-Chain Adaptation | Phase-change material integration replaces expanded polystyrene shippers in last-mile generic drug distribution. |
| Platform Aggregator Supplier List Placement | Amazon Frustration-Free Packaging certification displaces multi-material laminates from third-party seller procurement. |
Research Approach
The analysis maps kraft mailer, bubble mailer, and foam mailer sub-sectors, each validated through procurement directors at third-party logistics providers, sustainability officers at e-commerce platforms, and plant managers at European converters. Primary interviews with these stakeholders combined with secondary validation against EU Packaging and Packaging Waste Regulation filings, ECHA REACH compliance databases, and SEC 10-K disclosures from integrated paper producers. Bottom-up volume modeling and top-down value triangulation cross-checked against Amazon Frustration-Free Packaging certification lists and automated packaging equipment installation records.
Consistency checks validated volume and value outputs against customs trade data for kraft paper imports and polyethylene film shipments across the analysis window. Segmentation dimensions modeled include material type, product construction, application channel, and end-user procurement concentration. CAGRs derived from regression analysis of e-commerce order volume expansion correlated with fulfillment center automation investment cycles. Industry-specific inputs incorporated pulp price indices and extended producer responsibility fee schedules.
Underlying assumptions cover sustained e-commerce order volume expansion and REACH compliance deadline adherence, with deviation risk concentrated in pulp supply disruptions and platform procurement specification shifts. Recalibration cycles align with material shifts in EU regulatory sequencing and major platform aggregator certification updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Foam Mesh Sleeves Market
Protective Packaging
Corrugated Bubble Wrap Market
Protective Packaging
Insulated Styrofoam Shipping Boxes Market
Protective Packaging
Void Fill Pillows Market
Protective Packaging
Insulated Shippers Market
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Insulated Packaging Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
North America Protective Packaging Market
Protective Packaging
Latin America Protective Packaging Market
Protective Packaging
Global Packaging Inserts and Cushions Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
Protective Wrapping Paper Market
Protective Packaging
Foam Protective Packaging Market
Protective Packaging
Adhesive Bubble Wrap Market