
 Nigeria Plastic Packaging Films Market | 2026-2036
Nigeria Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Plastic Packaging Films Market Insights
Small-scale traders and informal retailers are collapsing as the dominant buyer archetype for commodity-grade films, while organized fast-moving consumer goods manufacturers and supermarket chains are capturing procurement volume. UFlex Limited anchors its position through backward integration into resin handling and blown film extrusion at its Lagos operations. Salamasor Nigeria Limited differentiates via specialized pharmaceutical-grade laminates that comply with NAFDAC serialization requirements. PrimePak Industries competes on manufacturing scale, operating multiple extrusion lines serving industrial packaging accounts across the Southwest.
Nigeria plastic packaging films constitute flexible polymer substrates manufactured through blown or cast extrusion processes, typically ranging from 12 to 150 microns in thickness, engineered for barrier protection, unitization, and shelf-life extension of packaged goods. Polyethylene dominates material consumption due to its cost-performance ratio in food and industrial applications, while polypropylene films command premium positioning in pharmaceutical and personal care segments where clarity and heat resistance matter. Stretch film applications are accelerating fastest among industrial end users seeking pallet stability for export-oriented manufacturing, whereas labels represent a concentrated margin pool as brand owners invest in anti-counterfeiting features and regulatory compliance printing.
NAFDAC mandates material composition disclosures and migration testing for all food-contact films, effectively filtering out uncertified imports and substandard domestic production. SON enforces Nigerian Industrial Standards for polyethylene and polypropylene grades, creating compliance costs that favor established converters with in-house testing laboratories. The Standards Organisation of Nigeria and the National Environmental Standards and Regulations Enforcement Agency jointly shape waste management obligations that will increasingly influence material selection and recycling infrastructure investments. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in mechanical recycling capabilities or partner with emerging waste collection platforms.
Market Dynamics
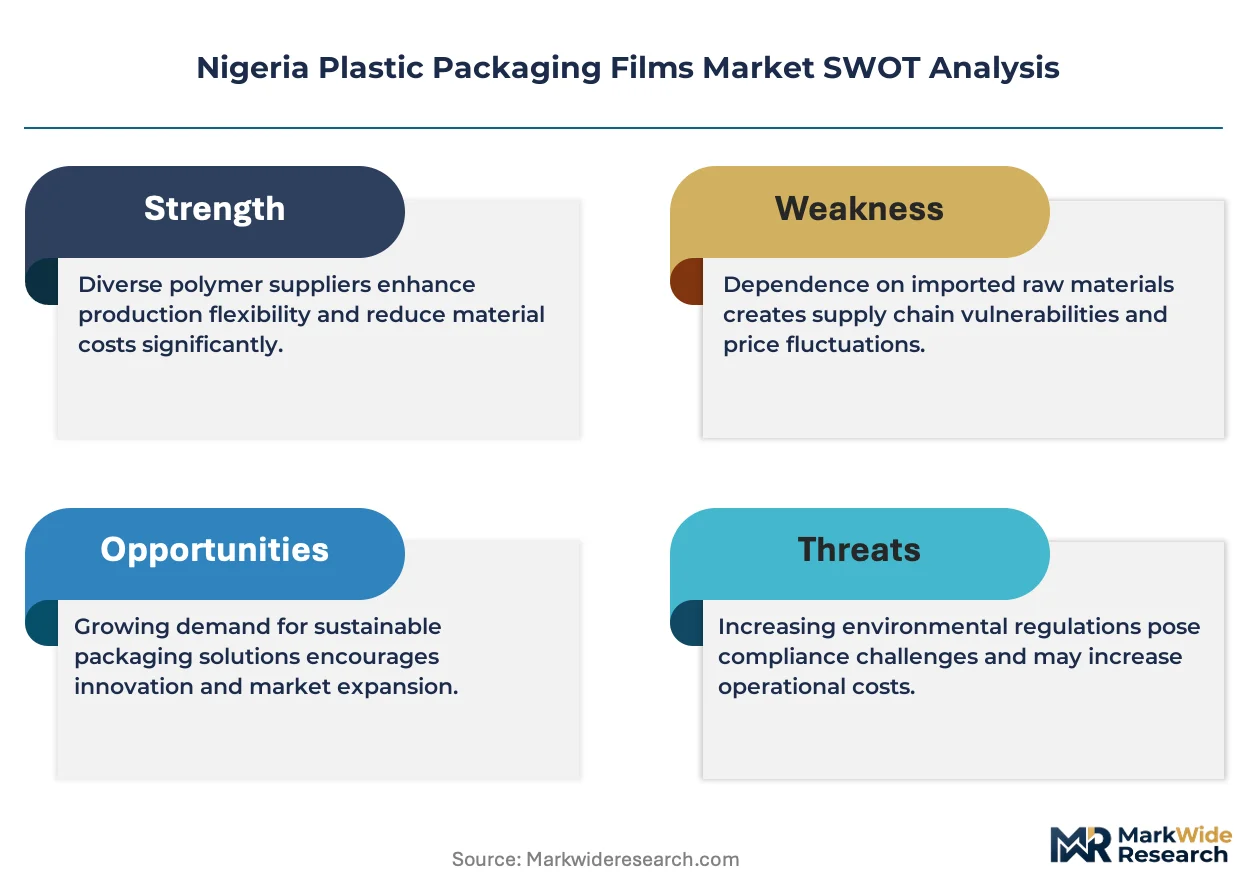
NAFDAC's migration testing mandates and SON's industrial standards enforcement are compressing the supplier base, forcing converters to invest in certified film grades and in-house laboratories while uncertified imports lose market access.
Growth Catalysts
- Modern Retail Penetration:Supermarket chains expanding into secondary cities are standardizing polyethylene shrink wrap specifications, displacing loose bulk packaging in Lagos and Kano.
- Export Manufacturing:Industrial end users in Southwest Nigeria are accelerating stretch film consumption for pallet stability of goods bound for West African markets.
- NAFDAC Serialization:Pharmaceutical-grade laminates with track-and-trace compliance are capturing premium procurement volumes from brand owners.
Market Restraints
- Resin Import Dependence:Naira volatility and forex scarcity inflate polyethylene raw material costs, squeezing converter margins on commodity-grade films.
- Power Infrastructure Deficits:Unreliable grid supply forces extrusion operators to absorb diesel generator costs, disadvantaging smaller blown film producers.
- Mechanical Recycling Gap:Absence of scaled post-industrial collection infrastructure limits circular material feedstock availability for certified recycled content films.
Strategic Opportunities
- Extended Producer Responsibility:Emerging NESREA waste management frameworks will create first-mover advantages for converters partnering with collection platforms or investing in mechanical recycling.
- Pharmaceutical Barrier Films:Underpenetrated demand for high-clarity polypropylene in personal care segments offers margin expansion beyond commodity polyethylene.
- Anti-Counterfeiting Labels:Brand owner investment in regulatory compliance printing and security features is concentrating value in specialized label film production.
Industry Challenges
- Skilled Extrusion Technicians:Shortage of blown film process engineers capable of calibrating multi-layer barrier structures limits production flexibility for complex laminates.
- Certification Timelines:NAFDAC food-contact approval cycles extend six to twelve months, delaying product launches and tying up working capital in compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Plastic Packaging Films Market |
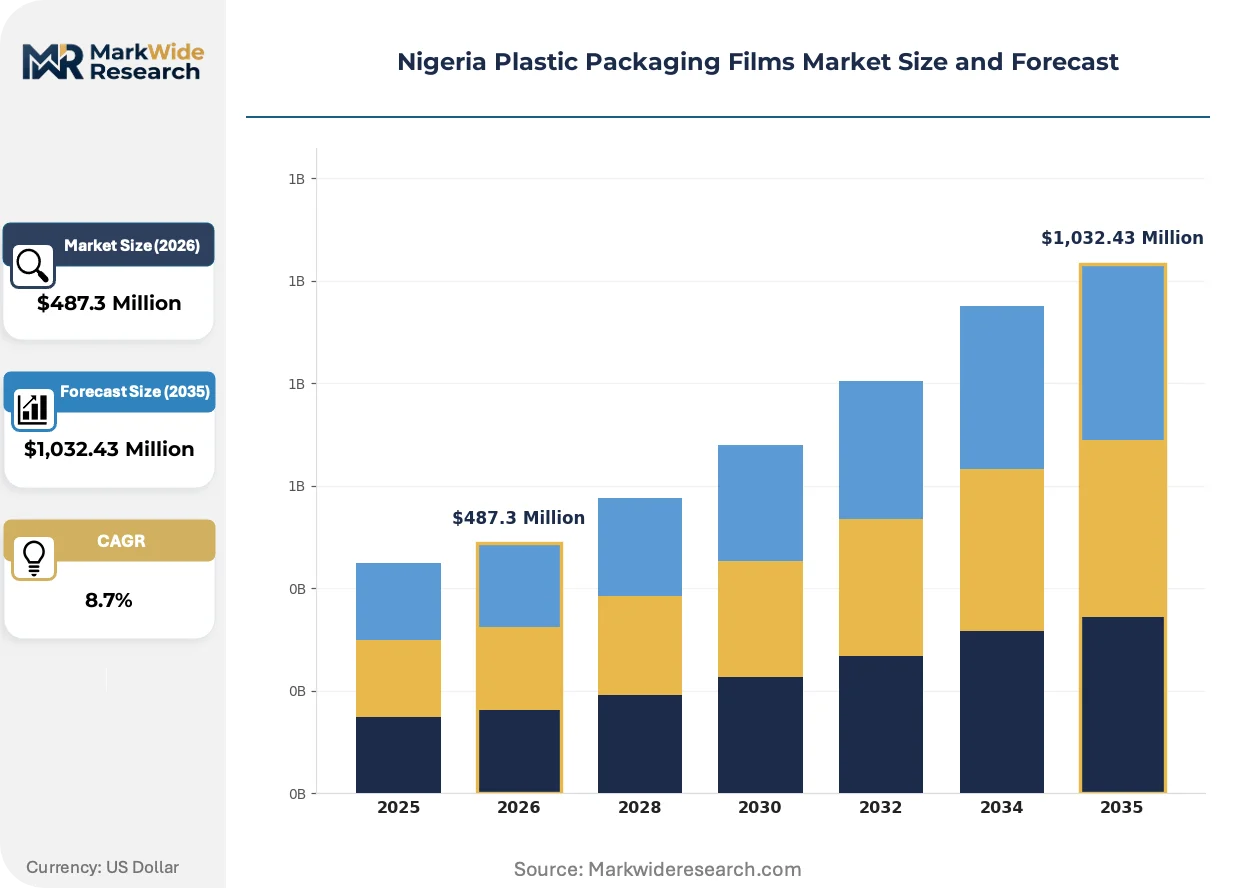
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Shrink Wrap, Stretch Film, Labels Application: Food Packaging, Pharmaceutical Packaging, Industrial Packaging, Consumer Goods Material: Polyethylene, Polypropylene, PVC, PET End User: Food & Beverages, Healthcare, Personal Care, Electronics |
| Companies Covered | UFlex Limited, Luban Packing LLC, Radiant Packaging Industry LLC, Twinstar Industries, PrimePak Industries, Salamasor Nigeria Limited, Quantum Plastic, Victor Osca, Tempo Paper Pulp & Packaging PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Plastic Packaging Films Market Trends and Innovations
Material science advances and regulatory digitization are reconfiguring competitive advantage around certified barrier performance rather than commodity scale, with sustainability mandates accelerating capital allocation toward circular production systems.
Multi-layer coextrusion technology combining EVOH barrier layers with polyethylene substrates is supplanting monolayer films in shelf-life-sensitive food applications. Processed meat and dairy manufacturers in Lagos are specifying these structures for twelve to eighteen month shelf stability. The shift is compressing margins for single-layer converters while rewarding technical specialists with in-house multilayer line capabilities.
NAFDAC's mandatory material composition disclosure rules for all food-contact packaging are forcing label redesigns and supply chain documentation upgrades. Converters must now submit migration test reports with every batch, increasing documentation costs but filtering out informal competitors. Pharmaceutical and infant nutrition segments face the strictest enforcement, driving consolidation toward laboratories with ISO 17025 accreditation.
Buyer concentration among organized FMCG manufacturers is shortening payment cycles and tightening technical specifications for film suppliers. Informal traders in open-air markets are losing procurement volume as formal retail chains centralize purchasing through approved vendor lists. This pattern is most visible in Southwest Nigeria, where supermarket expansion is fastest and supplier qualification requirements are most stringent.
Nigeria Plastic Packaging Films Market Segmentation
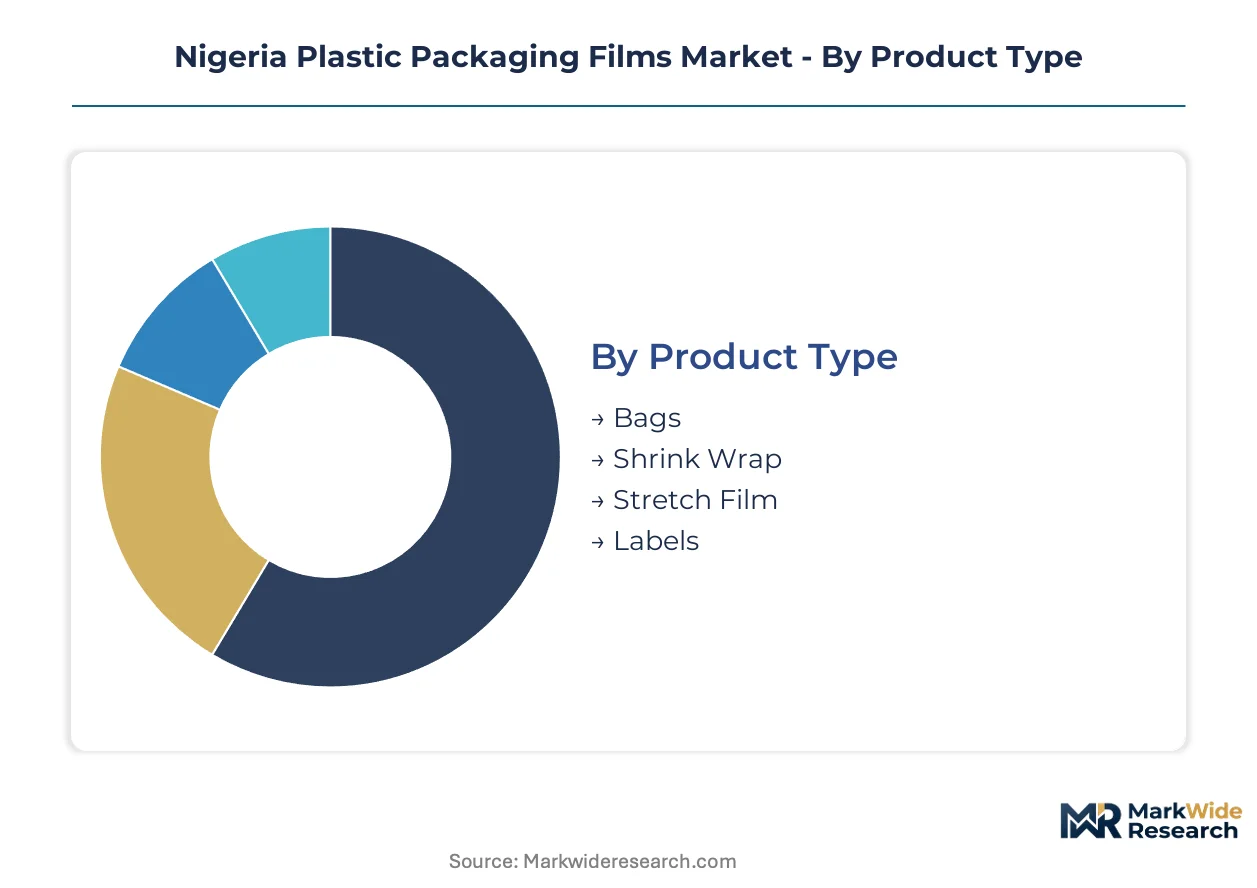
Nigeria's plastic packaging films market fragments across four critical dimensions that determine procurement patterns, margin structures, and regulatory exposure. Understanding these segment boundaries reveals where converters can defend position and where new entrants face barriers.
Product Type:
Domestic demand concentrates in commodity formats serving Lagos and Kano manufacturing clusters, while export-oriented stretch film volumes track cross-border trade flows into Benin and Ghana.
- Bags:Polyethylene carry bags and wicketed formats dominate food retail distribution in open-air markets and formal supermarket chains. NAFDAC's food-contact migration testing mandates are filtering out informal bag converters in Onitsha and Aba, consolidating procurement toward certified Lagos suppliers.
- Shrink Wrap:Polyethylene shrink films specified for unitization of bottled beverages and personal care products are displacing loose bulk packaging as Shoprite and Spar expand into Ibadan and Port Harcourt. Modern retail penetration is standardizing gauge specifications and shortening supplier qualification cycles.
- Stretch Film:Cast and blown stretch wraps for pallet stabilization serve export manufacturers in Ogun State industrial zones shipping to ECOWAS markets.
- Labels:Pressure-sensitive and shrink-sleeve formats with anti-counterfeiting features capture premium margins from pharmaceutical brand owners facing NAFDAC serialization deadlines.
Bags hold the largest share; momentum sits with stretch film as export manufacturing scales.
Application:
Cost tier stratification separates high-compliance pharmaceutical grades from commodity food and industrial formats, with certification requirements driving margin dispersion.
- Food Packaging:Multi-layer coextrusion with EVOH barrier layers is supplanting monolayer polyethylene in processed meat and dairy applications requiring twelve to eighteen month shelf stability. Lagos-based manufacturers are specifying these structures to meet modern retailer technical standards.
- Pharmaceutical Packaging:High-clarity polypropylene laminates with track-and-trace compliance command premium positioning. NAFDAC's mandatory material composition disclosures and serialization requirements are consolidating supply toward converters with ISO 17025 accredited laboratories.
- Industrial Packaging:Heavy-duty polyethylene formats serve construction materials and agricultural chemical producers with less stringent barrier requirements but high volume scale.
- Consumer Goods:Decorative printed films for personal care and household products balance clarity, seal integrity, and brand differentiation.
Food packaging holds the largest share; pharmaceutical packaging is gaining share fastest on regulatory premiumization.
Material:
Volume concentration favors polyethylene due to resin availability and converter process familiarity, while specialty grades command scarcity rents in pharmaceutical and electronics segments.
- Polyethylene:LDPE, LLDPE, and HDPE grades constitute the material backbone for bags, stretch film, and industrial formats. Naira volatility and forex scarcity inflate resin import costs, squeezing margins on commodity applications while favoring converters with backward integration into resin handling.
- Polypropylene:BOPP and CPP films deliver heat resistance and optical clarity for pharmaceutical blister packs and high-end personal care labels. Heat seal layer engineering and slip additive calibration require skilled process technicians scarce in the domestic labor pool.
- PVC:Rigid and flexible vinyl formats serve pharmaceutical blister packaging and select consumer goods applications with established tooling investments.
- PET:Polyester films with dimensional stability and barrier performance target electronics and premium food segments with specialized coating requirements.
Polyethylene holds the largest share; polypropylene is expanding most quickly on pharmaceutical demand.
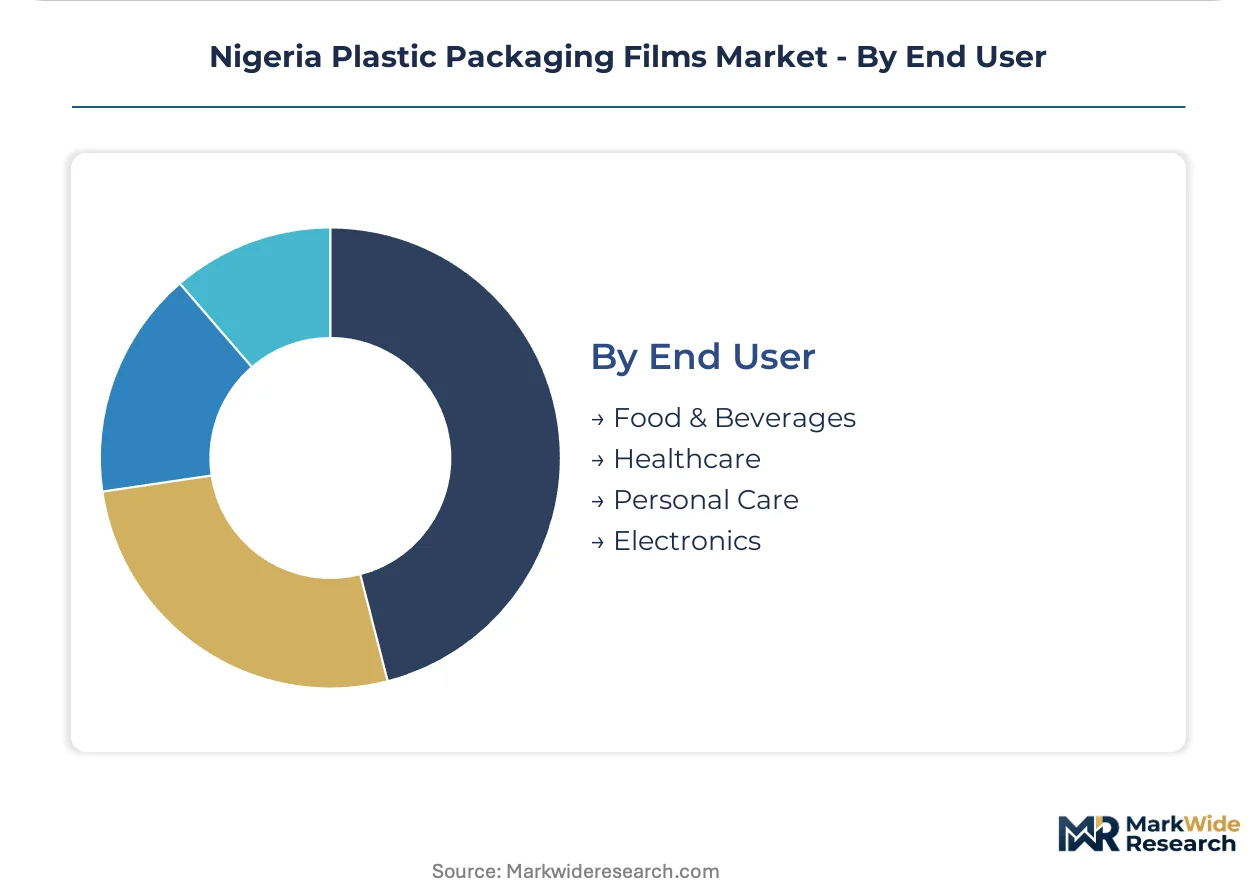
End User:
Customer type stratification separates organized FMCG manufacturers with approved vendor lists from informal traders losing procurement volume to formal retail centralization.
- Food & Beverages:Processed food manufacturers, breweries, and bottled water producers constitute the dominant demand pool. Shelf-life extension specifications from Nestlé Nigeria and Nigerian Breweries are driving technical upgrades in converter capabilities.
- Healthcare:Pharmaceutical manufacturers and medical device distributors require laminates with serialization compatibility and sterile barrier integrity. NAFDAC enforcement timelines are accelerating supplier consolidation toward certified domestic converters.
- Personal Care:Soap, detergent, and cosmetics brand owners specify high-clarity films with decorative printing for retail shelf impact.
- Electronics:Anti-static and moisture barrier films serve mobile phone and consumer electronics distributors with specialized ESD protection requirements.
Food and beverages holds the largest share; healthcare is climbing the fastest on regulatory compliance premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetype concentration varies sharply across Nigeria's economic zones, with organized FMCG procurement centralizing in Lagos-Ibadan corridors while informal trade persists in northern distribution networks. This geographic stratification shapes converter investment priorities and regulatory compliance exposure.
Lagos State
Supermarket chains and beverage manufacturers dominate film procurement, specifying polyethylene shrink wrap for unitized distribution. NAFDAC's food-contact migration testing mandates filter supplier qualification toward certified converters with ISO 17025 laboratories. The Ogun State industrial corridor hosts blown film extrusion clusters serving Nestlé Nigeria and Nigerian Breweries with multi-layer barrier structures.
Kano State
Processed food distributors and agricultural chemical producers drive commodity-grade polyethylene bag demand. The Standards Organisation of Nigeria enforces industrial standards for polyethylene grades, creating compliance costs that disadvantage informal converters in neighboring Jigawa. Sabon Gari market traders are losing procurement volume to formal retail centralization.
Southwest Nigeria
Export-oriented manufacturers in Ogun and Oyo States accelerate stretch film consumption for pallet stability of goods bound for Benin and Ghana. The National Environmental Standards and Regulations Enforcement Agency's emerging waste management frameworks incentivize mechanical recycling partnerships. Ibadan's growing supermarket presence standardizes technical specifications previously fragmented across open-air markets.
Onitsha and Aba
Informal bag converters face NAFDAC compliance pressure as food-contact certification requirements tighten. The city's pharmaceutical distributors increasingly specify pharmaceutical-grade laminates with track-and-trace compatibility. Aba's industrial cluster struggles with power infrastructure deficits that inflate diesel generator costs for extrusion operators.
Port Harcourt
Petrochemical-adjacent manufacturing and food processing create dual demand for industrial and food-contact films. The Niger Delta's unreliable grid supply forces converters to absorb energy costs that squeeze margins on commodity grades. Brewery and bottled water producers in Rivers State are consolidating procurement through approved vendor lists.
Nigeria Plastic Packaging Films Market Competitive Landscape
Player mix skews toward integrated resin handlers and specialized pharmaceutical-grade converters, with scale-driven industrial suppliers occupying a middle tier. Market structure concentrates procurement volume among three to four established operators with backward integration into resin handling and in-house testing capabilities. Strategic archetypes include resin-integrated multilayer specialists, pharmaceutical compliance-focused laminators, and scale-driven commodity extruders. Dominant competitive moves center on laboratory accreditation investments for NAFDAC compliance and partnerships with emerging waste collection platforms for extended producer responsibility positioning.
Among India-based integrated packaging conglomerates, UFlex Limited anchors the resin-integrated tier through blown film extrusion capabilities at its Lagos operations. Salamasor Nigeria Limited exemplifies the pharmaceutical-grade specialization archetype, occupying a position defined by NAFDAC serialization compliance. PrimePak Industries represents the scale-driven industrial vector, serving manufacturing accounts across the Southwest with multiple extrusion lines. These three operators collectively illustrate how certification infrastructure and upstream control separate sustainable market position from marginal commodity participation.
| Leading Market Players |
|---|
| UFlex Limited |
| Luban Packing LLC |
| Radiant Packaging Industry LLC |
| Twinstar Industries |
| PrimePak Industries |
| Salamasor Nigeria Limited |
| Quantum Plastic |
| Victor Osca |
| Tempo Paper Pulp & Packaging PLC |
| Others |
Pricing and Supply Chain Analysis
Long-term resin offtake contracts with Singapore and Middle East suppliers lock in polyethylene feedstock access for Lagos-based converters while capping price volatility exposure against Naira depreciation. These arrangements tie procurement volumes to indexed resin pricing, creating margin predictability for certified film producers serving NAFDAC-regulated food-contact segments.
Pricing Analysis
Cost-plus contracts indexed to ICIS Asian polyethylene benchmarks dominate raw material procurement for Nigerian converters. Three-tier pricing structure across pharmaceutical-grade laminates, food-contact certified films, and commodity-grade bags separates compliance-burdened premiums from undifferentiated polyethylene. Pricing pressure stems from Naira volatility inflating resin import costs, squeezing margins on standard-grade formats. Informal traders in open-air markets exhibit highest price sensitivity, while pharmaceutical manufacturers accept premium positioning for serialization-compliant laminates.
Supply Chain Analysis
Port congestion at Lagos Apapa terminals and container availability constraints on Asia-West Africa trade lanes inflate inbound logistics costs for resin shipments. Raw material sourcing draws from Saudi Arabia, South Korea, and Singapore for polyethylene feedstock, with masterbatch additives and specialty barrier resins imported from Germany and India. Single-source vulnerability concentrates in resin handling infrastructure controlled by backward-integrated operators. Distribution runs through converter-direct relationships with Nestlé Nigeria and Nigerian Breweries, supplemented by distributor networks serving secondary city processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from paper-based flexible packaging and biodegradable alternatives as European export customers impose sustainability mandates on Nigerian suppliers. Defense requires technical differentiation and compliance infrastructure investments that informal competitors cannot replicate.
For Market Incumbents: Compound laboratory accreditation advantages by securing ISO 17025 certification for migration testing, eliminating NAFDAC approval bottlenecks that delay competitor product launches. Deepen captive resin handling capabilities at Lagos and Ogun State facilities to insulate margin structures from forex-driven raw material volatility. Prioritize multi-layer coextrusion capacity additions serving processed meat and dairy manufacturers specifying twelve-to-eighteen month shelf stability.
For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade polypropylene laminates with track-and-trace compliance, where NAFDAC serialization deadlines consolidate procurement toward technical specialists. Target underpenetrated personal care segments in Ibadan and Port Harcourt supermarket channels demanding high-clarity films with decorative printing. Pursue toll manufacturing arrangements with established converters lacking serialization-capable coating lines.
For Investors and Strategic Acquirers: Specialized pharmaceutical compliance converters with NAFDAC-approved laboratories and existing brand owner relationships represent the most defensible acquisition profile. Long-term viability hinges on extended producer responsibility framework positioning, with first-mover mechanical recycling partnerships creating regulatory moats. Watch NESREA waste management enforcement timelines as inflection indicator for circular infrastructure investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Handling | Captive polyethylene supply shields UFlex and PrimePak from Naira-driven import cost volatility. |
| ISO 17025 Laboratory Accreditation | In-house migration testing compresses NAFDAC approval cycles from twelve months to six for Salamasor. |
| Multi-Layer Coextrusion Capacity Addition | EVOH barrier line investments capture processed meat shelf-life specifications from Nestlé Nigeria. |
| Mechanical Recycling Partnership | Waste collection platform alliances position converters for emerging NESREA extended producer responsibility mandates. |
| Pharmaceutical Serialization Compliance | Track-and-trace laminate capabilities secure premium procurement from NAFDAC-regulated drug manufacturers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs import records, SON industrial standards documentation, and NAFDAC regulatory filings. Primary interviews engaged blown film extrusion plant managers, procurement leads at Nestlé Nigeria and Nigerian Breweries, distribution channel partners serving Onitsha and Aba markets, and technical R&D directors at Lagos converter facilities. Secondary validation drew from Standards Organisation of Nigeria certification databases, National Bureau of Statistics trade data, and petrochemical resin import disclosures. Bottom-up demand modeling triangulated against top-down supply capacity assessments across Ogun State industrial corridors.
Segmentation dimensions modeled include product type hierarchy, application-specific barrier requirements, material grade tiers, and end-user procurement sophistication across the projection horizon. CAGRs derived from unit consumption trajectories by film format, layered against resin price elasticity assumptions and modern retail penetration rates. Industry-specific inputs incorporated NAFDAC enforcement intensity indices and supermarket chain expansion timelines into Ibadan and Port Harcourt.
Forecasts assume regulatory continuity in NAFDAC food-contact and SON industrial standards regimes; material policy shifts would require re-modeling. Resin import dependency and Naira volatility represent primary forecast revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Biaxially Oriented Polypropylene (BOPP) Films Market
Poly film
Polyurethane (PU) Film Market
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Global Thermoplastic Films Market
Poly film
Global Polycarbonate Sheets and Films Market
Poly film
Global Cast Polypropylene Packaging Films Market
Poly film
PE Foam Films Market
Poly film
Nylon Films Market
Poly film
PVC Films Market
Poly film
Mexico Plastic Packaging Films Market
Poly film
PVC Film for Medical Market
Poly film
Colombia Plastic Packaging Films Market
Poly film
Surface Printed Film Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
Silicone Release Films Market