
 Insulated Packaging Market | 2026-2036
Insulated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Packaging Market Intelligence
A shift from single-source contracts toward multi-supplier procurement for specialized thermal containers is rebalancing competitive dynamics. Global players like Amcor plc leverage scale to serve large pharmaceutical accounts. Niche specialists such as Cold Chain Technologies focus on qualified, single-use parcel shippers for biologics. Meanwhile, Pelican BioThermal differentiates with its portfolio of reusable, passive temperature-controlled containers, often leased to clients.
Insulated packaging refers to containers engineered to maintain a specific temperature range for their contents during transit. These systems use materials like polyurethane or vacuum insulated panels to achieve thermal stability. Rigid boxes and thermal containers command the pharmaceutical end-user segment due to strict temperature control requirements. The food and beverage sector often utilizes more cost-effective flexible bags for last-mile delivery of perishable goods.
Regulatory bodies like the US FDA and Europe's EMA mandate stringent validation for pharmaceutical packaging, shaping product design. Material choices are further constrained by chemical regulations such as REACH in the EU and various GB standards in China. The critical decision for suppliers involves balancing high-performance thermal insulation with the escalating demand for sustainable and reusable packaging solutions.
Market Dynamics
The insulated packaging market is shaped by a fundamental tension between the pharmaceutical industry's demand for higher-performance thermal protection for biologics and intensifying regulatory pressure, such as the EU's CSRD, for more sustainable, reusable, and circular material lifecycles.
Growth Catalysts
- Pharmaceutical Expansion:The growing pipeline of biologics, cell therapies, and vaccines necessitates advanced cold chain packaging to ensure product efficacy and safety, directly driving demand for qualified thermal shippers.
- Regulatory Mandates:Sustainability-focused regulations, including the EU's Corporate Sustainability Reporting Directive, compel end-users to adopt packaging with lower environmental impact, spurring innovation in recyclable and reusable materials.
- Geographic Concentration:Demand is intensifying within established pharmaceutical manufacturing clusters in Ireland, Switzerland, and the United States, creating concentrated hubs for specialized thermal packaging procurement and logistics services.
Market Restraints
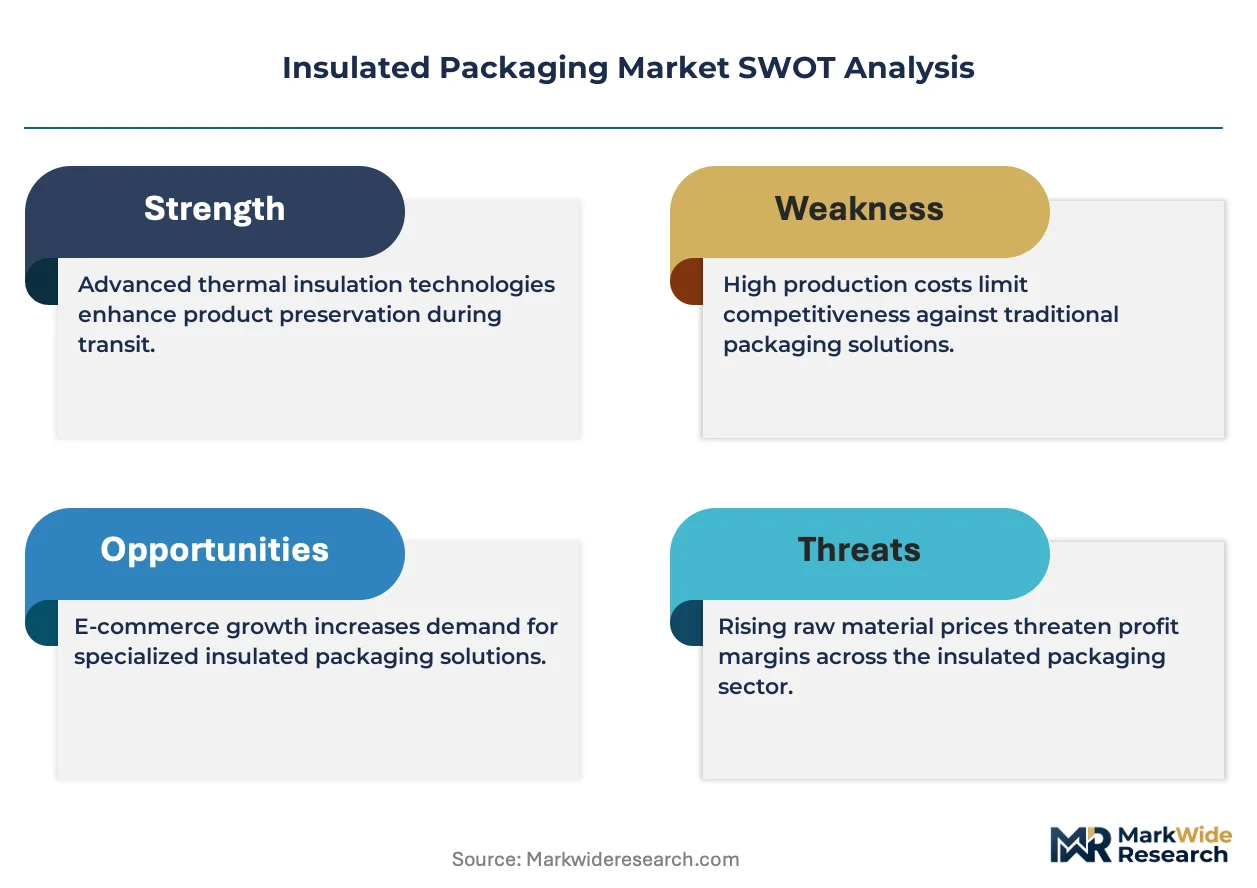
- Material Cost Volatility:The high cost and price instability of core insulation materials, particularly polyurethane foams and vacuum insulated panels, create margin pressure for manufacturers and can hinder adoption.
- Regulatory Fragmentation:Navigating disparate chemical safety regulations, such as REACH in Europe and various GB standards in China, complicates material selection and slows the global rollout of new packaging solutions.
- Weight and Durability Trade-offs:For reusable containers, there is a persistent technical conflict between reducing weight to lower air freight costs and ensuring sufficient durability to withstand multiple reverse logistics cycles.
Strategic Opportunities
- Ultra-Cold Chain Solutions:The rise of cell and gene therapies creates a significant opportunity for developing and validating packaging systems capable of maintaining ultra-low temperatures, such as -80°C, during transit.
- Smart Packaging Integration:Incorporating IoT sensors and data loggers directly into packaging systems offers a new service-based revenue stream through real-time temperature tracking, location monitoring, and compliance reporting.
- Emerging Market Expansion:As pharmaceutical manufacturing capabilities grow in countries across Asia and Latin America, there is a clear opportunity for suppliers to establish local supply and qualification services for cold chain packaging.
Industry Challenges
- Reverse Logistics Complexity:Managing the return, cleaning, inspection, and repositioning of reusable container fleets is operationally complex and capital-intensive, presenting a significant barrier for many suppliers and end-users.
- Validation Timelines:The extensive and costly process of qualifying new packaging designs against stringent pharmaceutical transport standards set by bodies like the US FDA and Europe's EMA can delay innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Packaging Market |
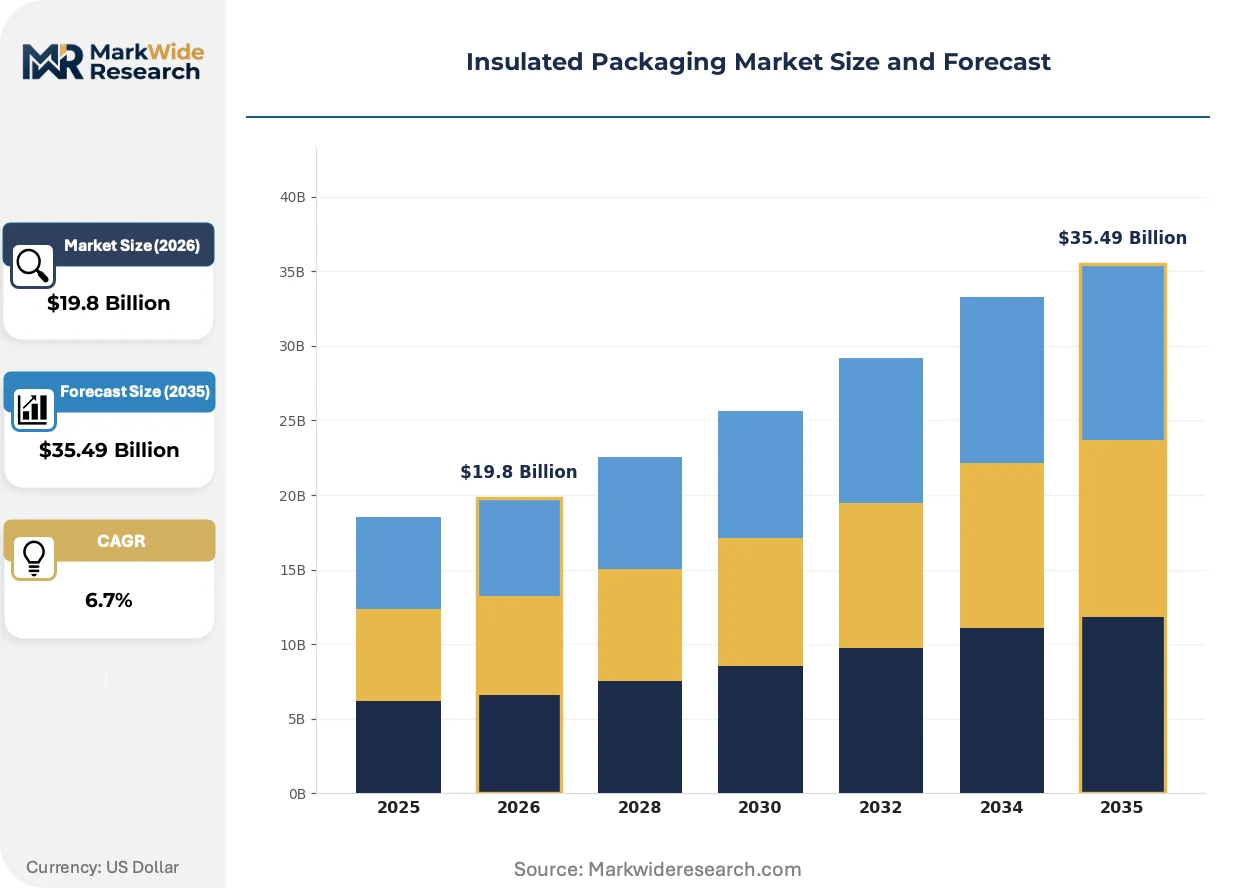
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $35.49 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Boxes, Flexible Bags, Thermal Containers, Insulated Pallets Material: Polyethylene, Polystyrene, Polyurethane, Molded Fiber End User: Pharmaceutical, Food & Beverage, Electronics, Chemical Functionality: Temperature Control, Shock Absorption, Moisture Resistance, Lightweight |
| Companies Covered | Amcor plc, WestRock Company, Sonoco Products Company, Cold Chain Technologies, Pelican BioThermal, Sealed Air Corporation, Mondi plc, Sofrigam, Berry Global, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Packaging Market Strategic Shifts & Innovations
The market is evolving toward integrated systems that must deliver superior thermal performance for sensitive biologics while also meeting new environmental mandates. This dual requirement is pushing innovation in materials, driving adoption of new service models, and altering procurement strategies.
Advanced Insulation Materials: Vacuum insulated panels and advanced phase change materials provide superior thermal stability with significantly thinner profiles compared to traditional foam. Pharmaceutical logistics providers are adopting these materials for high-value, small-volume biologic shipments. This combination of high performance and reduced volumetric weight is rewriting the economics of air freight for temperature-sensitive products.
Sustainability Reporting Directives: The European Union's Corporate Sustainability Reporting Directive (CSRD) is a pivotal policy shift. It requires large corporations to disclose detailed information on their environmental impact, including packaging waste and supply chain carbon footprint. Pharmaceutical shippers are consequently prioritizing packaging suppliers that offer validated reusable programs or solutions made from easily recyclable materials to meet these new disclosure requirements.
Multi-Supplier Sourcing Models: A clear behavioral shift sees large pharmaceutical companies moving from single-source contracts to multi-supplier procurement frameworks for their thermal packaging needs. This de-risking strategy is disrupting the hold of large-scale providers, creating openings for niche specialists to win business based on specific performance criteria or regional service capabilities. This trend is most visible in the North American and European markets where supply chain resilience has become a primary focus.
Insulated Packaging Market Segmentation
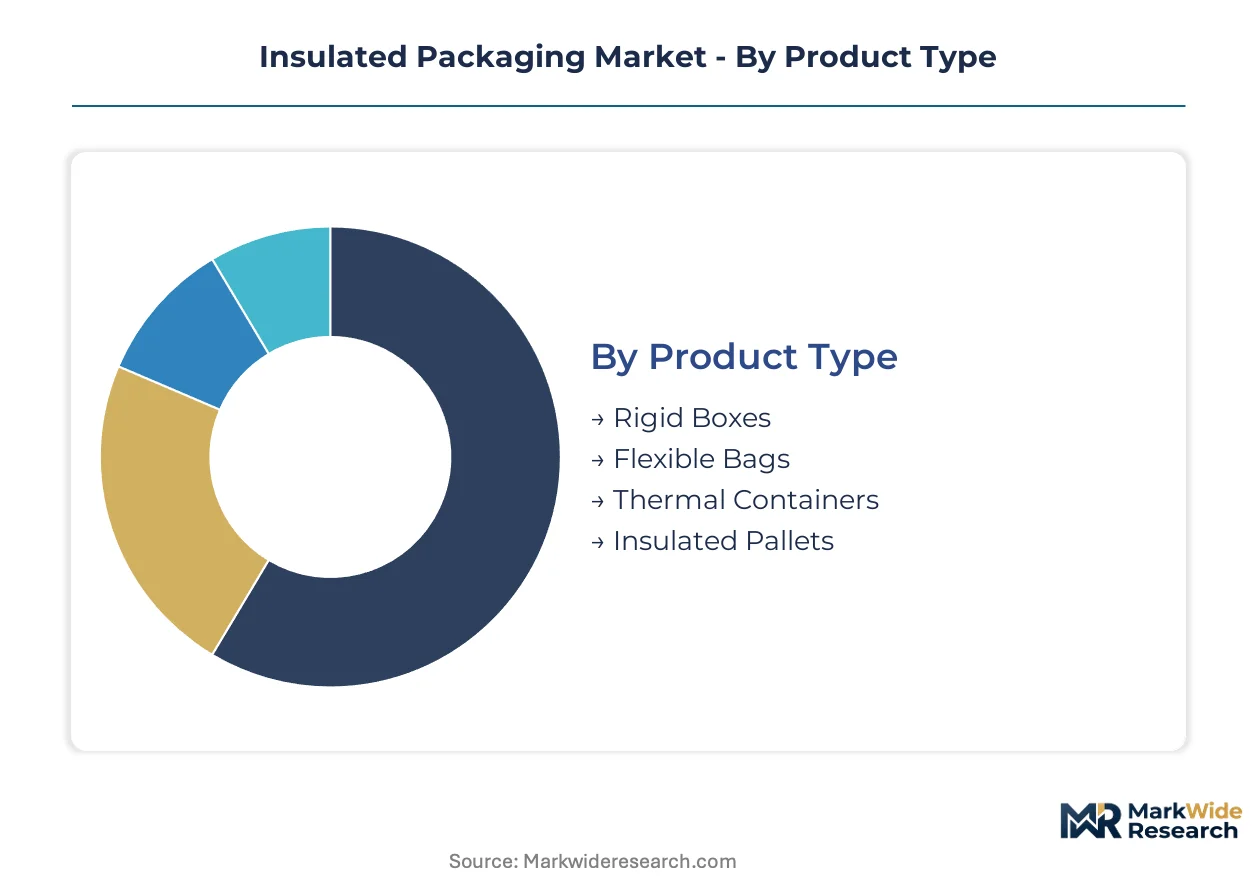
The insulated packaging market exhibits diverse segmentation, driven by varying end-user requirements, material innovations, and functional demands. Understanding these segments is crucial for suppliers to tailor solutions that meet specific performance criteria and cost sensitivities across different industries.
Product Type:
The product type segmentation reveals a clear differentiation between high-volume, cost-effective solutions and premium, performance-driven containers.
- Rigid Boxes:These durable containers, often made from expanded polystyrene or polyurethane, provide robust thermal protection for sensitive contents. Demand concentrates within pharmaceutical manufacturing hubs in Switzerland and Ireland for biologics.
- Thermal Containers:Engineered systems using advanced insulation like vacuum insulated panels, these containers maintain precise temperature ranges over extended transit times. They are frequently leased for high-value pharmaceutical shipments, optimizing cold chain logistics.
- Flexible Bags:Lightweight and adaptable, these bags are typically used for last-mile delivery in the food and beverage sector.
- Insulated Pallets:Designed to protect bulk shipments, these solutions often incorporate thermal blankets or pallet shippers for large-scale logistics.
Mature deployment sits with Rigid Boxes. Newer deployment is concentrated in Thermal Containers.
Material:
Material choices often reflect a balance between insulation performance, cost, and environmental impact across different tiers.
- Polyurethane:Known for its high thermal insulation properties, polyurethane foam is widely used in high-performance rigid boxes and thermal containers. Its adoption is critical for maintaining precise temperatures for pharmaceutical products.
- Molded Fiber:Derived from recycled paper pulp, molded fiber offers a sustainable and cost-effective alternative for less stringent temperature control needs. Its use is expanding in food and beverage applications to meet sustainability mandates.
- Polyethylene:A versatile plastic, polyethylene is common in flexible bags and liners for its moisture resistance and low cost.
- Polystyrene:Expanded polystyrene (EPS) provides good insulation at a lower cost, frequently used in single-use parcel shippers for various industries.
Polyurethane remains a dominant insulation material, while Molded Fiber is expanding most quickly to meet sustainability goals.
End User:
End-user requirements for insulated packaging vary significantly based on product sensitivity and regulatory mandates.
- Pharmaceutical:This sector demands the highest performance and validation for packaging due to strict regulations for biologics and vaccines. Procurement often involves multi-supplier models for specialized thermal solutions.
- Food & Beverage:Focused on maintaining freshness for perishable goods, this segment prioritizes cost-effectiveness and solutions suitable for last-mile delivery. Flexible bags and insulated liners are common here.
- Electronics:Insulated packaging protects sensitive electronic components from temperature fluctuations and condensation during transit.
- Chemical:The chemical industry utilizes specialized insulated containers to maintain stability for temperature-sensitive compounds and hazardous materials.
The Pharmaceutical sector commands the largest share of demand, while the Food & Beverage segment drives high-volume, cost-sensitive applications.
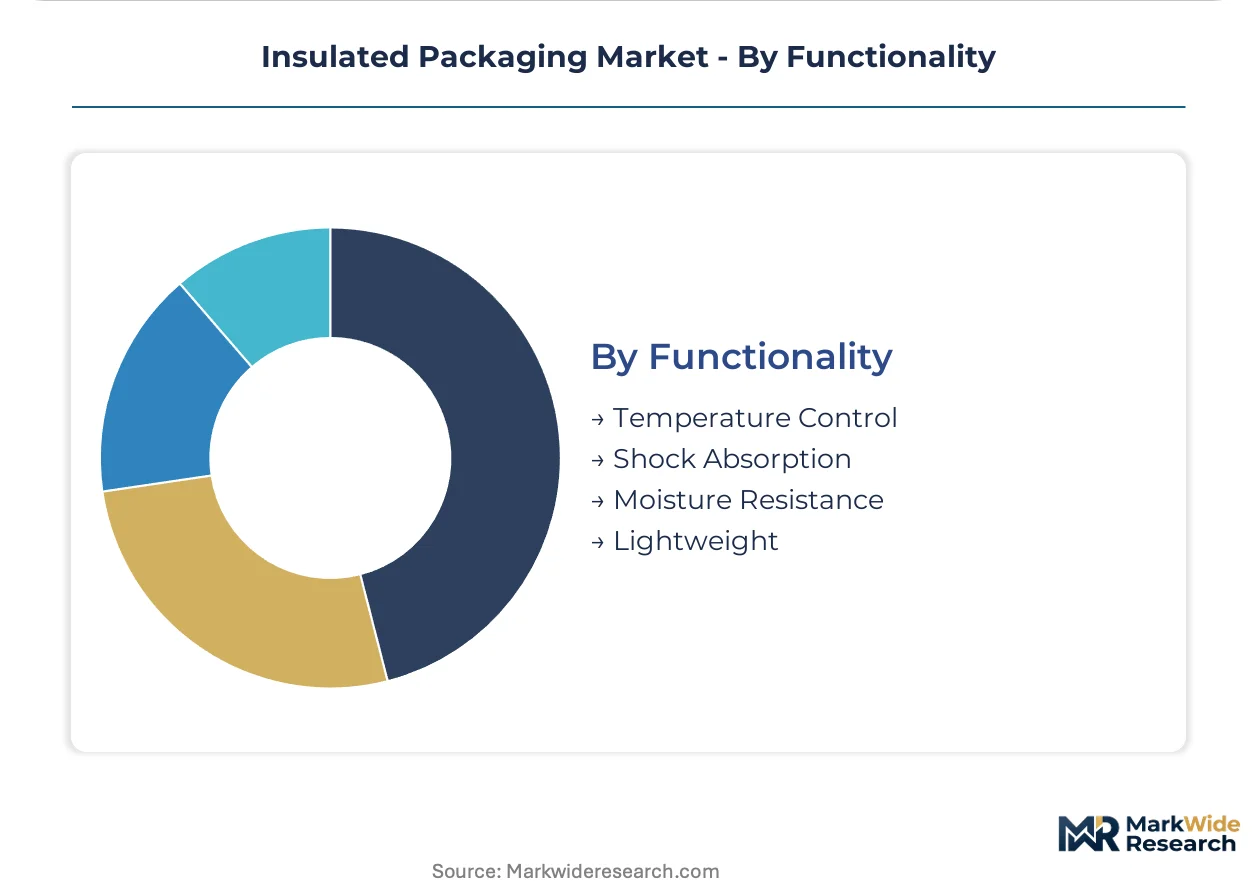
Functionality:
Each functionality addresses a specific need in protecting sensitive goods during transit and storage.
- Temperature Control:The primary function, ensuring contents remain within a specified temperature range, is critical for pharmaceuticals and food products. This functionality is often validated against stringent industry standards.
- Lightweight:Reducing the overall weight of packaging lowers air freight costs, a significant factor for high-value, small-volume biologic shipments. Innovations in materials like VIPs contribute to this.
- Shock Absorption:This feature protects fragile contents from physical damage during handling and transportation.
- Moisture Resistance:Essential for preventing condensation and water damage, particularly for electronics and certain chemical products.
Temperature Control serves as the primary driver for high-value goods, with Lightweight features acting as a critical secondary consideration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized material production for high-performance insulation, particularly polyurethane and vacuum insulated panels, anchors demand across key pharmaceutical manufacturing regions. These regions drive innovation in thermal packaging solutions for sensitive biologics and vaccines. Regulatory frameworks further shape material choices and product design.
United States
The United States market demands advanced thermal packaging for its extensive biologics and vaccine production. US FDA mandates stringent validation processes for pharmaceutical cold chain solutions. Innovation in qualified thermal shippers concentrates around biotech hubs like Boston and Raleigh-Durham. These regions drive ultra-cold chain solutions.
Germany
Germany's pharmaceutical sector requires high-performance insulated packaging for its diverse drug manufacturing. The EU's Corporate Sustainability Reporting Directive (CSRD) compels companies to adopt reusable and recyclable materials. REACH regulations further shape material choices. Pharmaceutical clusters in Frankfurt and Munich lead the adoption of sustainable thermal solutions.
Switzerland
Swiss pharmaceutical companies prioritize precision temperature control for high-value biologics and specialized medicines. Swissmedic upholds rigorous standards for cold chain integrity. Packaging innovation for complex biologics concentrates in major pharmaceutical centers like Basel and Zurich. These hubs require validated thermal containers.
Ireland
Ireland's significant biopharmaceutical manufacturing base drives demand for robust insulated packaging for export logistics. The European Medicines Agency (EMA) guidelines heavily influence packaging design and validation. Compliance with the EU's CSRD also shapes material selection. Biopharma clusters in Dublin and Cork are key procurement points for specialized thermal shippers.
Japan
Japanese pharmaceutical manufacturers require highly reliable insulated packaging for sensitive advanced medicines. The Pharmaceuticals and Medical Devices Agency (PMDA) sets strict quality and validation standards for cold chain products. JIS standards influence material selection. Major pharma research and manufacturing centers in Tokyo and Osaka drive demand for innovative thermal solutions.
Insulated Packaging Market Key Industry Players
Strategic differentiation through specialized offerings dominates the current landscape of insulated packaging. The market exhibits a tiered structure, with global players alongside niche specialists and regional providers. Strategic archetypes include large-scale integrators, dedicated cold chain solution providers, and sustainable packaging innovators. Competitive moves involve portfolio diversification into ultra-cold solutions and geographic expansion into emerging pharmaceutical markets.
Specialists in cold chain logistics include Cold Chain Technologies, exemplifying providers focused on qualified, single-use parcel shippers for sensitive biologics. Pelican BioThermal occupies a distinct position, representing companies that differentiate through reusable, passive temperature-controlled container portfolios, often leased to clients for extended use. Amcor plc anchors the larger-scale segment, representing global players leveraging extensive operational scale to serve major pharmaceutical accounts with diverse packaging needs across multiple geographies.
| Leading Market Players |
|---|
| Amcor plc |
| WestRock Company |
| Sonoco Products Company |
| Cold Chain Technologies |
| Pelican BioThermal |
| Sealed Air Corporation |
| Mondi plc |
| Sofrigam |
| Berry Global, Inc. |
| Others |
Cost & Logistics Intelligence
Advanced insulation materials, such as vacuum insulated panels, are reshaping cost economics by reducing volumetric weight for air freight while simultaneously concentrating supply in specialized manufacturing hubs. This shift introduces both efficiency gains and new dependencies for insulated packaging providers.
Pricing Analysis
Service-level agreements, encompassing container leasing and reverse logistics, frequently bundle into the overall pricing of reusable thermal containers. The dominant pricing model is contract-based long-term offtake for high-volume pharmaceutical accounts. Price differentiation stems from thermal performance validation levels and the integration of IoT-enabled tracking features. Cost compression in single-use parcel shippers intensifies due to material cost volatility, making pharmaceutical end-users less price-sensitive than those in food and beverage.
Supply Chain Analysis
Reverse logistics complexity for reusable containers, involving cleaning, inspection, and repositioning, forms a critical component of the insulated packaging supply chain. Geographic supply concentration for core insulation materials like polyurethane and vacuum insulated panels centers in Germany, the United States, and Japan. Raw material dependencies include specialized polymers and advanced phase change materials. Regulatory fragmentation across chemical safety standards creates a structural risk, while distribution runs through a mix of direct sales and specialized cold chain logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulated packaging market increasingly functions as a cost-of-compliance story, where stringent regulations like the US FDA's validation mandates create significant barriers to entry for non-compliant providers. This dynamic favors established players with proven track records.
For Market Incumbents:Cement relationships with pharmaceutical giants by offering integrated, full-service cold chain solutions, including reverse logistics management. Diversify validated container portfolios to address the ultra-cold chain segment, mitigating the threat from niche specialists focusing solely on biologics. Invest in automated cleaning and inspection systems to reduce operational costs for reusable fleets, enhancing margin stability. Prioritize R&D into next-generation sustainable insulation materials to align with evolving EU CSRD requirements.
For New Entrants and Emerging Players:Capture market share by specializing in sustainable, single-use parcel shippers for specific biologics, leveraging novel molded fiber or recyclable polymer designs. Target underpenetrated pharmaceutical manufacturing clusters in emerging markets across Asia, offering localized qualification services. A go-to-market angle involves partnering with regional logistics providers to offer integrated, last-mile cold chain solutions. Focus on rapid validation for specific temperature ranges, avoiding the broader portfolio approach of larger players.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized cold chain solution providers with strong intellectual property in advanced insulation or smart packaging technologies. Long-term viability hinges on companies demonstrating robust validation capabilities for sensitive biologics and commitment to circular material lifecycles. Acquisition targets should possess established relationships within pharmaceutical manufacturing hubs in Ireland, Switzerland, or the United States. The signal to watch is the increasing adoption of IoT-enabled packaging systems by major pharmaceutical companies.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Expands offerings into ultra-cold chain solutions for cell and gene therapies. |
| Sustainable Material R&D | Develops new insulation from molded fiber to meet EU CSRD requirements. |
| Multi-Supplier Partnership | Secures procurement contracts with multiple pharmaceutical clients, de-risking revenue. |
| IoT Integration | Embeds real-time temperature tracking into containers for compliance reporting. |
| Geographic Expansion | Establishes local qualification services in Asian pharmaceutical manufacturing hubs. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by in-depth primary interviews. Industry stakeholders included pharmaceutical procurement managers, cold chain logistics specialists, packaging engineers, and material scientists. This approach allowed for robust cross-validation of market trends and competitive dynamics. Bottom-up and top-down triangulation ensured data integrity across all market segments.
The market was modeled at a granular level across product type, material, end-user, and functionality segments, including regional regulatory clusters. Compound annual growth rates were derived from historical data analysis and projected demand drivers across the analysis window. Key industry-specific forecast inputs included the biologics pipeline expansion and the adoption rate of reusable packaging solutions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to new sustainability regulations and material cost volatility. Forecasts reflect assumptions regarding technological advancements and global economic stability. Practitioners should monitor new validation standards and reverse logistics infrastructure development for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Thermal Insulated Mailers Market
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Latin America Protective Packaging Market
Protective Packaging
Middle East and Africa Protective Packaging Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
Paper Cushion Systems Market
Protective Packaging
Static Shielding Bags Market
Protective Packaging
Protective Wrapping Paper Market
Protective Packaging
Anti-Corrosive Packaging Market
Protective Packaging
Global Packaging Inserts and Cushions Market
Protective Packaging
Anti-Static Foam Packaging Market
Protective Packaging
Foam Mesh Sleeves Market
Protective Packaging
Corrugated Bubble Wrap Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
Fiber Cushioning Market