
 Kraft Paper Mailer Market | 2026-2036
Kraft Paper Mailer Market Size, Share, and Industry Trends Forecast 2026-2036
Kraft Paper Mailer Market Foresight
Subscription-based replenishment programs for packaging supplies is decoupling mailer procurement from traditional spot-buying cycles. International Paper Company leverages its North American pulp network to sustain cost-advantaged virgin kraft output. Smurfit Westrock anchors European supply through integrated containerboard-to-converted-product operations. Mondi Group competes on specialty coatings that add moisture resistance without compromising recyclability streams.
Kraft paper mailers are fabricated from unbleached sulfate pulp ranging from 90 to 150 gsm, formed into self-sealing envelopes with hot-melt adhesive strips and often lined with corrugated fiber cushioning or expandable paper padding to protect goods in transit. Padded mailers now capture the dominant share of value as premium electronics and cosmetics brands specify protective fiber-based alternatives to bubble mailers. Eco-friendly mailers represent the fastest-growing product type as FSC-certified and carbon-neutral labeled offerings command shelf space in corporate procurement portals. E-commerce companies constitute the deepest end-user margin pool, with annual contract volumes enabling direct mill relationships that bypass distributor markups.
The EPA guides recycled content claims under its Comprehensive Procurement Guidelines while the EU Packaging and Packaging Waste Regulation sets mandatory recyclability performance grades that kraft constructions readily satisfy. California's SB 54 mandates source reduction and recyclability for single-use packaging, creating compliance-driven substitution away from plastic mailers across West Coast fulfillment networks. Stakeholders must monitor how extended producer responsibility fee structures evolve, as these will determine whether virgin or recycled kraft grades achieve lower total cost of ownership in regulated markets.
Market Dynamics
Plastic substitution mandates across fulfillment networks are compressing decision cycles for e-commerce procurement teams, forcing rapid qualification of fiber-based protective packaging at scale.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability thresholds favor unbleached kraft constructions over multi-material plastic alternatives, accelerating specification in continental European logistics networks.
- E-commerce fulfillment standardization:Amazon's European network and DHL's parcel operations have adopted padded kraft mailers as default last-mile packaging, creating template effects across competitor networks.
- FSC-certified fiber sourcing:Corporate procurement portals now filter for chain-of-custody documentation, elevating certified mailers in vendor selection algorithms.
Market Restraints
- Pulp price volatility:Unbleached sulfate pulp fluctuates with energy and freight inputs, compressing converter margins when spot prices spike.
- Regional supply concentration:Integrated containerboard-to-converted-product capacity clusters in Germany and the US Southeast, exposing buyers to single-source risk during mill maintenance cycles.
- Moisture sensitivity gap:Uncoated kraft suffers performance degradation in humid climates versus polyethylene-lined alternatives, limiting adoption in tropical logistics corridors.
Strategic Opportunities
- Subscription-based replenishment programs:Packaging-as-a-service models decouple mailer procurement from spot-buying cycles, enabling multi-year contracts with direct mill relationships.
- Specialty barrier coatings:Water-based formulations that add moisture resistance without compromising recyclability streams open premium electronics and cosmetics segments.
- Extended producer responsibility fee structures:Evolving EPR frameworks in California and the EU may advantage virgin or recycled kraft grades depending on carbon accounting methodologies.
Industry Challenges
- Hot-melt adhesive formulation expertise:Converters face skill gaps in optimizing pressure-sensitive strips for automated insertion lines without seal failure.
- Recyclability certification timelines:Third-party validation for paper stream compatibility requires 6-12 month testing protocols, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kraft Paper Mailer Market |
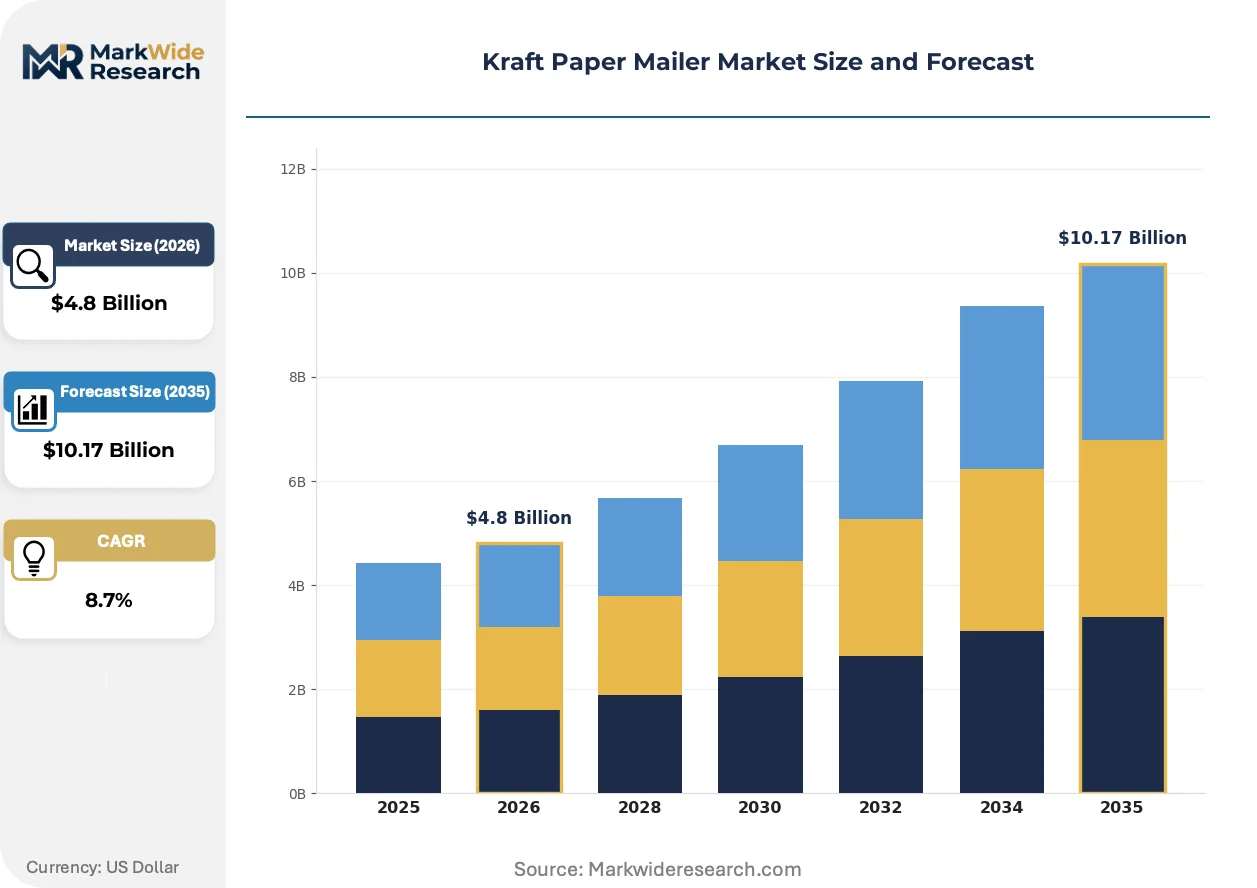
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Mailers, Padded Mailers, Custom Size Mailers, Eco-Friendly Mailers End User: E-commerce Companies, Retailers, Manufacturers, Warehousing Services Application: Shipping, Packaging, Storage, Gift Wrapping Distribution Channel: Online Stores, Wholesale Distributors, Retail Outlets, Direct Sales |
| Companies Covered | International Paper Company, Smurfit Westrock, Mondi Group, Sealed Air Corporation, Pregis LLC, Georgia-Pacific LLC, Stora Enso, Intertape Polymer Group, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kraft Paper Mailer Market Shifts & Advancements
Material science advances and procurement platform digitization are collapsing traditional specification cycles, enabling real-time customization of protective fiber solutions at volume scale.
Expandable paper padding is expanding into premium electronics fulfillment, replacing polyethylene bubble linings in smartphone and tablet shipments. Unboxing experience managers at direct-to-consumer brands now specify fiber-based cushioning for brand alignment with circular economy commitments. This substitution is expanding into cosmetics and luxury goods verticals where tactile presentation carries margin weight.
California's SB 54 mandates source reduction and recyclability for single-use packaging, creating compliance-driven substitution away from plastic mailers across West Coast fulfillment networks. The EPA's Comprehensive Procurement Guidelines reinforce recycled content claims, pushing federal contractors toward documented fiber sourcing. Third-party logistics providers in the Pacific corridor are pre-qualifying kraft mailers to maintain eligibility for state and municipal contracts.
Direct mill relationships are displacing distributor intermediaries as annual contract volumes from large e-commerce platforms enable price discovery at pulp-grade level. Procurement teams now negotiate specifications through digital portals that integrate carbon accounting and chain-of-custody documentation. This channel compression is most visible in Germany, where Amazon's fulfillment network and DHL's parcel operations have standardized vendor qualification protocols.
Kraft Paper Mailer Market Segmentation
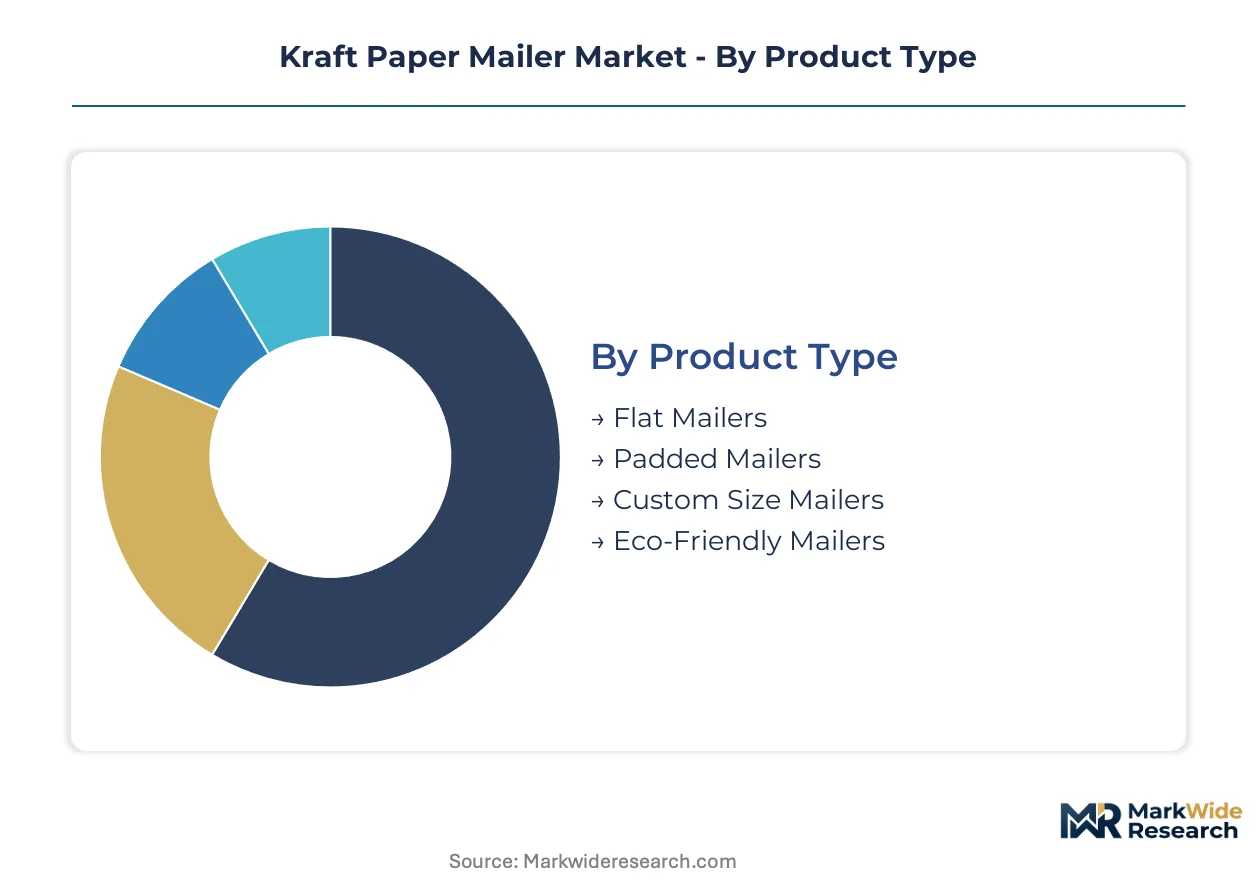
Kraft paper mailer segmentation reveals how converter capacity and end-use specifications align. Product construction, user procurement scale, and channel access each create distinct margin pools and sourcing requirements.
Product Type:
Integrated containerboard-to-converted-product operations concentrate capacity in Germany and the US Southeast, shaping which constructions achieve cost-advantaged scale.
- Padded Mailers:Fabricated from 90-150 gsm unbleached sulfate pulp with corrugated fiber cushioning or expandable paper padding. Amazon's European fulfillment network and DHL's parcel operations in Germany have standardized these as default last-mile packaging, creating template effects for competitor logistics networks.
- Eco-Friendly Mailers:FSC-certified and carbon-neutral labeled constructions that satisfy EU Packaging and Packaging Waste Regulation recyclability thresholds. Corporate procurement portals now filter for chain-of-custody documentation, elevating certified mailers in vendor selection algorithms.
- Flat Mailers:Unlined self-sealing envelopes for documents and flat goods with minimal protection requirements.
- Custom Size Mailers:Bespoke dimensions for irregular product categories, typically sourced through direct mill relationships.
Today's leader: Padded Mailers. Tomorrow's challenger: Eco-Friendly Mailers.
End User:
Contract volume scale determines whether procurement flows through distributor markups or direct mill relationships.
- E-commerce Companies:Annual contract volumes enable direct mill relationships that bypass distributor markups. Subscription-based replenishment programs decouple mailer procurement from spot-buying cycles, with Amazon's network standardizing padded kraft specifications across West Coast and European fulfillment corridors.
- Retailers:Omnichannel operations with mixed volume profiles, typically sourcing through wholesale distributors with shorter procurement cycles.
- Manufacturers:Industrial shipping departments with specification requirements tied to outbound freight optimization.
- Warehousing Services:Third-party logistics providers pre-qualifying kraft mailers to maintain eligibility for California SB 54 compliance and municipal contracts.
Current procurement concentration: E-commerce Companies. Emerging volume source: Warehousing Services.
Application:
Performance requirements in humid versus temperate corridors determine coating specifications and regional adoption ceilings.
- Shipping:Protective transit applications demanding moisture resistance and seal integrity under automated insertion line speeds.
- Packaging:Premium electronics and cosmetics brands specify fiber-based alternatives to bubble mailers, with unboxing experience managers prioritizing tactile presentation.
- Storage:Archival and inventory protection with lower throughput requirements.
- Gift Wrapping:Direct-to-consumer presentation layer where brand alignment with circular economy commitments carries margin weight.
Primary volume driver: Shipping. Fastest-climbing specification: Packaging.
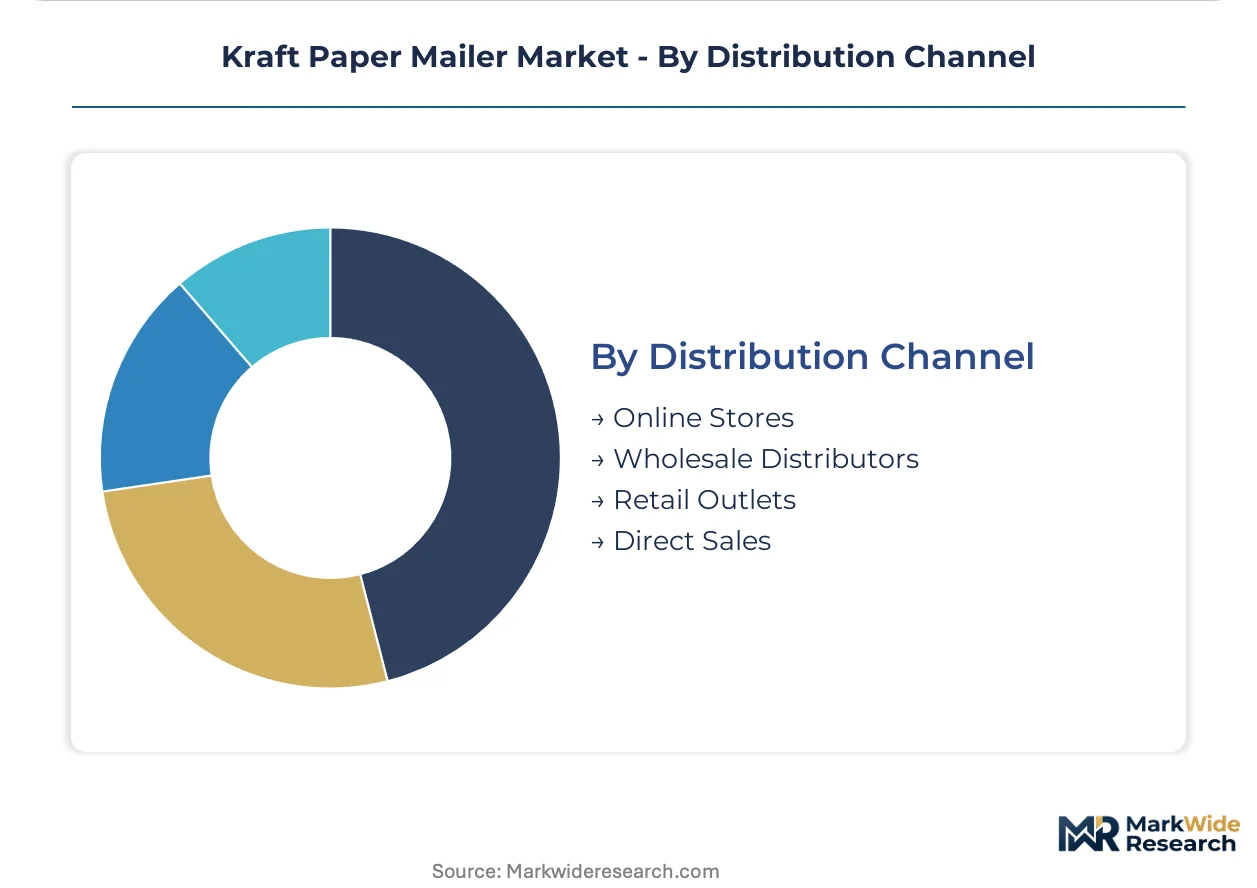
Distribution Channel:
Channel compression is most visible where annual contract volumes enable price discovery at pulp-grade level.
- Direct Sales:Mill-to-end-user relationships negotiated through digital portals integrating carbon accounting and chain-of-custody documentation. International Paper Company and Smurfit Westrock leverage integrated pulp networks to sustain cost-advantaged positions.
- Wholesale Distributors:Traditional intermediaries serving mid-volume accounts with spot-buying cycles.
- Online Stores:Procurement platforms with vendor qualification protocols filtering for FSC certification and EPA Comprehensive Procurement Guidelines compliance.
- Retail Outlets:Small-volume spot purchases for immediate fulfillment needs.
Dominant margin pool: Direct Sales. Channel under pressure: Wholesale Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the deepest procurement concentration in kraft mailers, while the United States drives volume through West Coast compliance mandates. Each geography shapes demand through distinct regulatory and industrial configurations.
United States
California's SB 54 mandates source reduction and recyclability for single-use packaging, forcing West Coast fulfillment networks toward fiber-based alternatives. The EPA's Comprehensive Procurement Guidelines reinforce recycled content claims for federal contractors. Amazon's Pacific corridor operations and third-party logistics providers in Los Angeles have standardized padded kraft specifications to maintain municipal contract eligibility.
Germany
The EU Packaging and Packaging Waste Regulation sets mandatory recyclability thresholds that unbleached kraft constructions readily satisfy. Amazon's European fulfillment network and DHL's parcel operations have adopted padded kraft mailers as default last-mile packaging. The Rhine-Ruhr industrial cluster anchors integrated containerboard-to-converted-product capacity, concentrating converter operations near major logistics hubs.
China
E-commerce platforms and cross-border fulfillment networks drive specification shifts toward fiber-based protective packaging. The country's national environmental regulator enforces circular economy targets that disadvantage multi-material plastic alternatives. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta now produce expandable paper padding for premium electronics exports.
India
Domestic e-commerce expansion and export-oriented logistics services create dual demand channels for protective fiber packaging. The Bureau of Indian Standards and central environmental directives promote recyclability in packaging materials. Industrial corridors in Maharashtra and Gujarat host emerging converter capacity serving both local fulfillment networks and international shipping operations.
United Kingdom
Omnichannel retail operations and direct-to-consumer brands accelerate specification of FSC-certified mailers for brand alignment. Post-Brexit regulatory divergence from EU frameworks creates compliance complexity for cross-border fulfillment. The Midlands logistics cluster and London-area fulfillment centers drive concentrated procurement volume for certified fiber constructions.
Kraft Paper Mailer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pulp-to-converted-product operations commanding margin in high-volume channels and regional converters capturing spot-buying accounts. The market presents a tiered structure where multinational paper companies with captive fiber supply compete against specialized packaging fabricators focused on coating and conversion expertise. Two strategic archetypes dominate: vertically integrated forest products companies with cost-advantaged virgin kraft output, and specialty converters competing on barrier coatings and certification documentation. Competitive dynamics center on direct mill relationship cultivation and multi-year subscription contract capture.
Among North American forest products companies, International Paper Company and Georgia-Pacific LLC exemplify the integrated archetype with upstream pulp network control. Mondi Group occupies a position bridging European supply integration and specialty coating development. These three entities anchor distinct competitive vectors—cost structure, geographic coverage, and technical differentiation—without overlapping strategic positioning.
| Leading Market Players |
|---|
| International Paper Company |
| Smurfit Westrock |
| Mondi Group |
| Sealed Air Corporation |
| Pregis LLC |
| Georgia-Pacific LLC |
| Stora Enso |
| Intertape Polymer Group |
| ProAmpac |
| Others |
Supply & Pricing Matrix
EU Packaging and Packaging Waste Regulation recyclability thresholds gate qualified supply for premium-tier kraft mailers, restricting certified converter access to buyers with documented chain-of-custody compliance and enabling FSC-labeled products to command sustained price premiums over standard grades.
Pricing Analysis
Capacity additions in Germany and the US Southeast are reshaping price floors for unbleached sulfate pulp constructions. Three-tier pricing structure across FSC-certified premium, standard recycled-content, and economy virgin grades dominates contract negotiations. Price differentiation hinges on certification tier and volume scale, with annual subscription contracts securing pulp-grade-level discovery. Cost compression in standard grades is intensifying because spot pulp buyers face energy-linked volatility. E-commerce platforms with direct mill relationships exhibit lowest price sensitivity, while mid-volume retailers sourcing through distributors face margin pressure.
Supply Chain Analysis
Unbleached sulfate pulp supply rests on integrated containerboard operations concentrated in Germany, the United States, and Sweden. Raw material flows draw from Nordic softwood forests, recycled fiber collection networks, and specialty chemical inputs for hot-melt adhesive formulations. Single-source vulnerability during mill maintenance cycles creates disruption risk for buyers locked into Rhine-Ruhr or US Southeast production clusters. Distribution runs through direct mill portals for high-volume accounts and wholesale distributors for spot-buying intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where California SB 54 compliance costs on the US West Coast exceed EU EPR fee structures, favoring European export-oriented converters.
For Market Incumbents: Deploy captive pulp network expansion to defend against specialty coating specialists encroaching on premium electronics segments. Secure multi-year subscription contracts with Amazon and DHL to lock in volume corridors. Invest in water-based barrier R&D to close the moisture-sensitivity gap limiting tropical adoption. For New Entrants and Emerging Players: Begin with expandable paper padding production for premium cosmetics unboxing experiences, a segment where tactile presentation commands brand premiums. Target warehousing services pre-qualifying for California municipal contracts as the most penetrable volume source. Pursue FSC chain-of-custody certification as the essential go-to-market credential. For Investors and Strategic Acquirers: Roll-up economics work for regional converters with coating expertise because certification documentation creates customer switching costs that sustain acquisition premiums. Five-to-ten year viability hinges on EPR framework evolution favoring fiber over plastic alternatives. Watch California's SB 54 enforcement intensity as the signal for West Coast contract volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | International Paper and Smurfit Westrock leverage captive fiber to sustain cost-advantaged virgin kraft output. |
| Specialty Barrier Coating Development | Mondi Group competes on water-based formulations adding moisture resistance without compromising recyclability streams. |
| Subscription-Based Replenishment Programs | Amazon's annual contract volumes enable direct mill relationships that bypass distributor markups entirely. |
| FSC Certification Investment | Corporate procurement portals now filter for chain-of-custody documentation, elevating certified mailers in vendor selection. |
| Geographic Expansion to West Coast Fulfillment | Third-party logistics providers in Los Angeles pre-qualify kraft mailers to maintain California SB 54 compliance eligibility. |
Research Methodology
Bottom-up e-commerce procurement modeling reconciled against top-down pulp production tracking forms the analytical core. Primary interviews with converter operations managers, e-commerce packaging procurement leads, FSC certification auditors, and hot-melt adhesive formulation specialists combined with secondary validation. Secondary sources include customs trade data for unbleached sulfate pulp flows, EPA Comprehensive Procurement Guidelines documentation, EU Packaging and Packaging Waste Regulation filings, and SEC 10-K disclosures from integrated forest products companies. Triangulation between demand-side contract volume analysis and supply-side capacity utilization rates ensures cross-verified outputs.
Historical trendline analysis of padded mailer adoption rates across Amazon's European and North American fulfillment networks established baseline growth patterns. Segmentation dimensions modeled include product construction type, end-user procurement scale, application performance requirements, and distribution channel access. CAGRs were derived through regression analysis of annual contract volume trajectories. Forecast inputs incorporate EU EPR fee structure evolution and California SB 54 enforcement timelines.
Several conditions sit outside the modeled scope, including breakthrough plastic-alternative materials achieving cost parity, abrupt pulp price spikes from energy market disruptions, and regulatory divergence in post-Brexit UK frameworks. Forecasts reflect documented assumptions about substitution elasticity and certification adoption curves. A small set of named triggers warrants ongoing watch: tropical logistics corridor expansion, hot-melt adhesive automation compatibility breakthroughs, and third-party recyclability certification timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Global Folding Boxboards Market
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
Corrugated Board Market
Paper & Paperboard Packaging
Asia-Pacific Coated Paper Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market
Paper & Paperboard Packaging
Box Liners Market
Paper & Paperboard Packaging
Secondary Paper and Paperboard Luxury Packaging Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
Disposable Paper Cups Market
Paper & Paperboard Packaging
Foam Cups Market
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market