
 Protective Wrapping Paper Market | 2026-2036
Protective Wrapping Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Wrapping Paper Market Analytics
A shortage of pulp-processing technicians is redrawing where capacity additions can proceed. Mondi Group leverages its integrated forestry and mill network to sustain cost advantages across Central Europe. Sealed Air Corporation differentiates through engineered paper-film hybrid structures that occupy premium tiers in electronics shipping.
Protective wrapping paper denotes engineered paper-based materials, typically 30–150 gsm in basis weight, manufactured through kraft pulping or recycled fiber processing to absorb shock and prevent surface abrasion during transit. Its primary purpose is to substitute plastic cushioning in B2B and direct-to-consumer supply chains while maintaining drop-test performance. Kraft paper leads in volume across the product type dimension due to its compatibility with existing fanfold and dispenser systems in warehouse automation. E-commerce dominates the end user category as fulfillment velocity requirements favor lightweight, curbside-recyclable dunnage over multi-material alternatives.
The EU Packaging and Packaging Waste Regulation and REACH chemical compliance frameworks shape material composition rules across the European market, while the EPA's recycled content guidelines influence procurement specifications in the United States. These standards force reformulation of sizing agents and barrier coatings, raising technical barriers for non-specialized converters. Stakeholders must track how extended producer responsibility fee structures evolve to determine whether regional manufacturing or import sourcing minimizes total compliance cost exposure.
Market Dynamics
Pulp-processing technician shortages are constraining where new kraft paper capacity can be built, forcing converters to prioritize brownfield expansions over greenfield mills despite rising e-commerce demand.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets are accelerating warehouse transitions from plastic air pillows to fanfold kraft dunnage across German and French fulfillment networks.
- Automotive parts distribution:Just-in-time component shipping from Stuttgart and Wolfsburg hubs requires abrasion-resistant wrapping that withstands multi-modal handoffs without surface damage.
- Kraft pulping technology:Modified continuous digesters now produce 90-120 gsm cushioning grades with tear resistance matching polyethylene foam at comparable unit costs.
Market Restraints
- Softwood pulp price volatility:Nordic spruce and pine fiber costs swing with energy-intensive chemical recovery cycles, compressing converter margins unpredictably.
- Barrier coating reformulation costs:REACH-compliant sizing agents require 18-24 month validation cycles before achieving food-contact approval, delaying product launches.
- Recycled fiber contamination thresholds:Post-consumer OCC streams contain adhesive residues that weaken tensile strength below 35 Nm/g, limiting high-performance applications.
Strategic Opportunities
- Polish and Czech e-commerce corridors:Underdeveloped last-mile infrastructure in Central European markets creates first-mover advantage for automated dispenser system deployments.
- Paper-film hybrid structures:Laminated kraft-polyethylene webs combine moisture barrier properties with curbside recyclability, unlocking pharmaceutical cold-chain applications.
- Extended producer responsibility fee arbitrage:Producers locating conversion assets in Portugal or Spain face lower modulated fees under national packaging schemes than German counterparts.
Industry Challenges
- Drop-test certification bottlenecks:ISTA 3A validation protocols require 6-8 week turnaround at accredited laboratories, stalling customer approvals.
- Legacy warehouse management system integration:Fanfold dispensers must interface with WMS pick-path algorithms originally configured for air pillow workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protective Wrapping Paper Market |
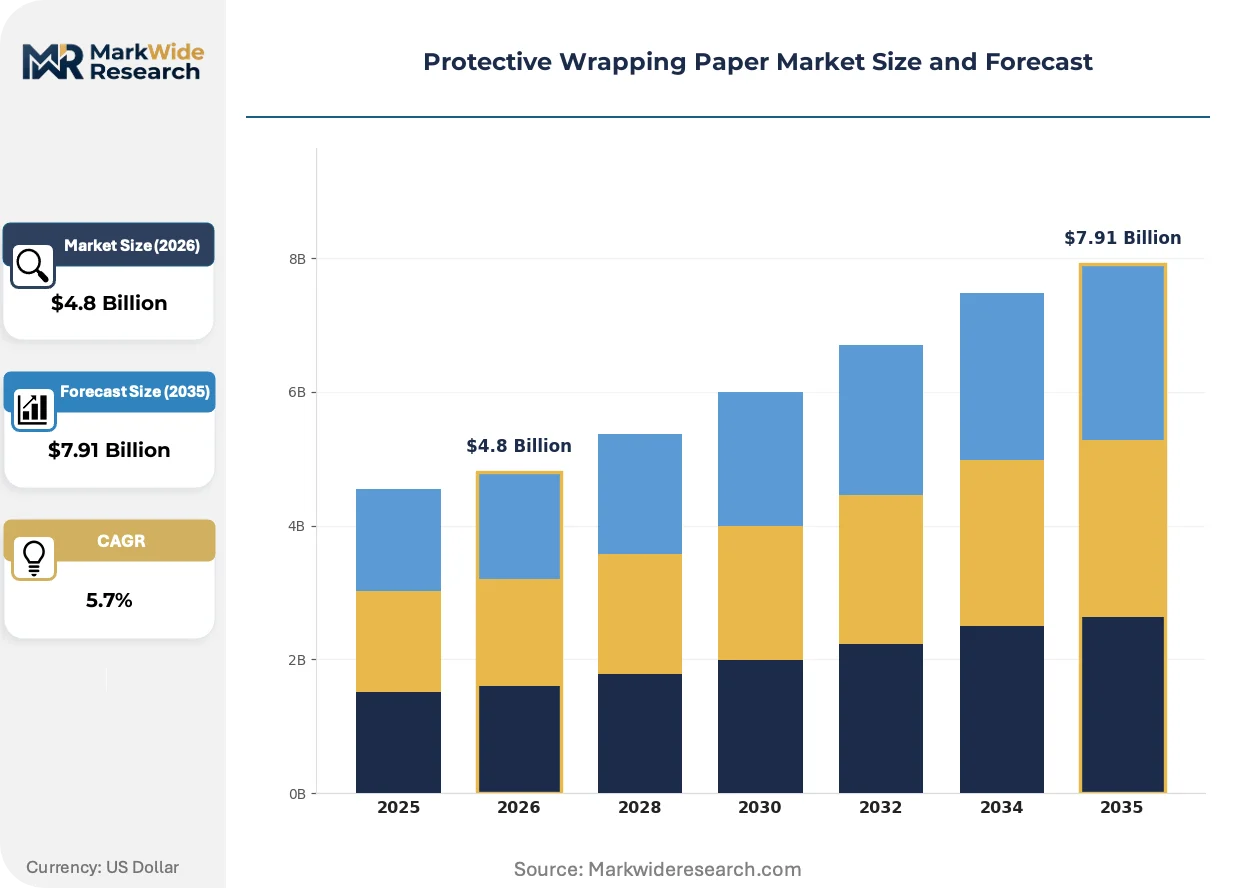
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bubble Wrap, Kraft Paper, Foam Sheets, Paperboard End User: Retail, E-Commerce, Manufacturing, Logistics Material: Recycled Paper, Polyethylene, Biodegradable Materials, Plastics Application: Shipping, Packing, Storage, Moving |
| Companies Covered | Amcor Plc, Sonoco Products Company, Sealed Air Corporation, International Paper Company, WestRock Company, ProAmpac Holdings Inc., Mondi Group, DS Smith Plc, Smurfit Kappa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Wrapping Paper Market Evolving Landscape
Active coating deposition and fiber engineering are compressing performance gaps between paper-based cushioning and synthetic alternatives, while regulatory compliance costs are reshaping where conversion assets locate.
Micro-encapsulated moisture-activated adhesives are miniaturizing the bonding interface between plies in multi-layer kraft structures. Electronics shippers in the Netherlands and Belgium are adopting these grades for semiconductor wafer transport. The technology is miniaturizing the effective cushioning thickness required for equivalent drop protection from 12mm to 6mm, reducing freight cube and dunnage weight simultaneously.
REACH chemical compliance frameworks are forcing reformulation of fluorocarbon-based grease barriers in food-contact wrapping grades. Industrial consequence includes 15-20% raw material cost premiums for bio-based alternatives during qualification periods. German automotive suppliers are most affected, accelerating partnerships with Finnish pulp mills possessing in-house barrier R&D capabilities.
Buyer consolidation among pan-European third-party logistics providers is compressing supplier rosters from twelve to three approved vendors per warehouse network. Direct contracting with mill groups is replacing distributor intermediation in Rotterdam and Hamburg port zones. French and Italian fashion e-tailers are driving this shift, demanding lot-traceable fiber sourcing for scope 3 emissions reporting.
Protective Wrapping Paper Market Segmentation
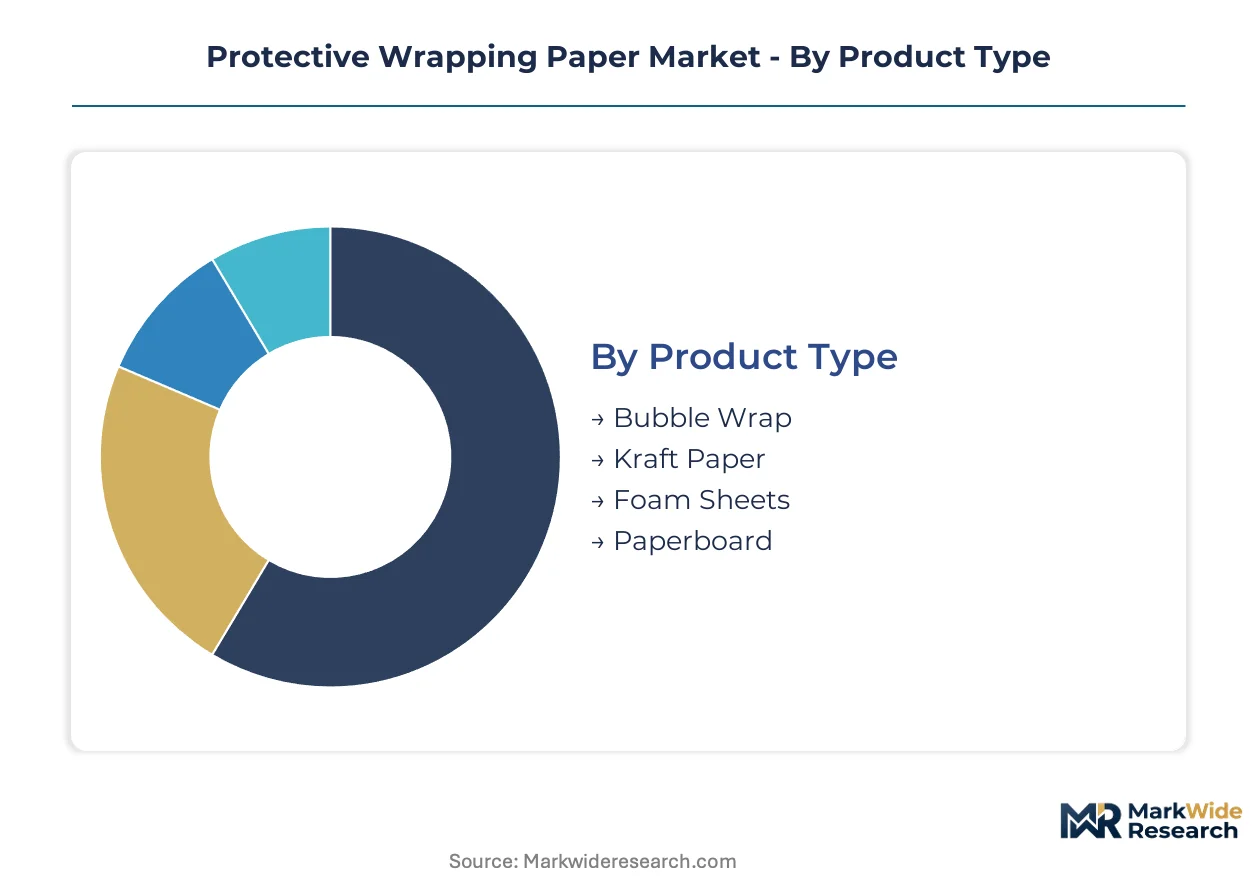
Segmentation in protective wrapping paper reveals where substitution economics favor paper over plastic and where legacy materials retain defensive positions. Understanding these fault lines helps converters prioritize R&D spending and capacity investments.
Product Type:
Kraft paper faces the most intense substitution pressure from plastic alternatives in high-volume e-commerce dunnage, while bubble wrap defends its position in fragile electronics where air-cell performance is non-negotiable.
- Kraft Paper:Engineered from sulfate pulp in 30-150 gsm weights, this grade absorbs shock through fiber crimp and ply layering. Demand concentrates in German and French fulfillment centers where EU Packaging and Packaging Waste Regulation recyclability mandates have accelerated warehouse transitions from plastic air pillows. Modified continuous digesters now produce cushioning grades matching polyethylene foam tear resistance.
- Bubble Wrap:Polyethylene film extruded with entrapped air cells provides superior drop protection for semiconductor wafers and glass components. Electronics shippers in the Netherlands and Belgium retain this material where 6mm effective cushioning thickness is insufficient. REACH chemical compliance is forcing bio-based barrier qualification cycles that delay paper alternatives.
- Foam Sheets:Expanded polystyrene or polyurethane slabs protect heavy automotive parts from Stuttgart and Wolfsburg distribution hubs during multi-modal handoffs.
- Paperboard:Rigid fiberboard structures in 200-400 gsm range edge-protect palletized goods in B2B manufacturing supply chains.
Kraft paper retains volume leadership; bubble wrap holds the steepest defensive margin in premium electronics applications.
End User:
Customer procurement power varies sharply across this dimension, with pan-European third-party logistics providers consolidating supplier rosters while fragmented retail maintains distributor intermediation.
- E-Commerce:Fulfillment velocity requirements in Rotterdam and Hamburg port zones favor lightweight, curbside-recyclable dunnage compatible with automated fanfold dispensers. French and Italian fashion e-tailers drive direct mill contracting for lot-traceable fiber sourcing.
- Logistics:Third-party warehouse networks in Poland and Czech corridors present first-mover opportunities for dispenser system deployments where last-mile infrastructure remains underdeveloped.
- Manufacturing:Just-in-time component shipping from automotive clusters demands abrasion-resistant wrapping validated to ISTA 3A protocols.
- Retail:Brick-and-mortar distribution maintains legacy air pillow workflows with slower WMS integration timelines.
E-Commerce commands the largest share of new capacity investment; logistics corridors in Central Europe are climbing the fastest.
Material:
Raw material sourcing strategy determines compliance cost exposure under extended producer responsibility fee structures that vary by national packaging scheme.
- Recycled Paper:Post-consumer OCC streams face contamination thresholds that weaken tensile strength below 35 Nm/g, limiting high-performance cushioning applications. Finnish pulp mills with in-house barrier R&D capabilities are securing partnerships with German automotive suppliers.
- Biodegradable Materials:Starch-based and cellulosic alternatives carry 15-20% raw material cost premiums during REACH qualification periods for food-contact approval.
- Polyethylene:Virgin and recycled film grades persist where moisture barrier properties are mandatory.
- Plastics:Multi-material laminates face tightening modulated fees under national packaging schemes.
Recycled paper dominates tonnage; biodegradable materials are gaining share fastest in food-contact and pharmaceutical cold-chain segments.
Application:
Use-case severity determines whether paper-based cushioning can achieve performance parity with synthetic alternatives through active coating deposition and fiber engineering.
- Shipping:Transit shock protection for parcel post and freight requires drop-test certification at accredited laboratories with 6-8 week validation turnaround.
- Packing:Void-fill and surface wrapping in warehouse operations drives dispenser system deployment decisions.
- Storage:Long-term humidity exposure necessitates moisture-activated adhesive barriers in multi-layer kraft structures.
- Moving:Consumer rental and professional relocation services favor low-cost, single-use dunnage with minimal specification requirements.
Shipping absorbs the majority of specification-grade volume; packing applications are expanding most quickly through warehouse automation retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH framework governs chemical compliance across the European market that dominates protective wrapping paper procurement. The EU Packaging and Packaging Waste Regulation shapes material mandates in Germany, France, and neighboring states. E-commerce fulfillment networks in Rotterdam and Hamburg drive cross-border demand patterns.
Germany
Automotive parts distribution from Stuttgart and Wolfsburg hubs requires abrasion-resistant wrapping for just-in-time component shipping. The national packaging scheme imposes modulated extended producer responsibility fees that favor domestic mill sourcing over imports. Dense fulfillment networks in North Rhine-Westphalia and Bavaria process fanfold kraft dunnage at automated dispenser density unmatched elsewhere in Europe.
France
Fashion e-tailers in Paris and Lyon demand lot-traceable fiber sourcing for scope 3 emissions reporting compliance. ANSM oversees pharmaceutical cold-chain packaging standards that paper-film hybrid structures must satisfy. The Île-de-France logistics corridor concentrates third-party warehouse networks consolidating supplier rosters from twelve to three approved vendors.
Netherlands
Rotterdam port zone operations favor lightweight, curbside-recyclable dunnage compatible with high-velocity pick-path algorithms. The Dutch national packaging scheme applies lower modulated fees for recyclable mono-materials versus multi-layer laminates. Electronics shippers in Eindhoven and Amsterdam adopt micro-encapsulated moisture-activated adhesives for semiconductor wafer transport.
Poland
Underdeveloped last-mile infrastructure in Central European corridors creates first-mover advantage for automated dispenser system deployments. Polish e-commerce growth outpaces warehouse automation retrofit rates, extending replacement windows for legacy air pillow workflows. Warsaw and Krakow fulfillment centers source kraft cushioning from brownfield expansions rather than greenfield mills due to pulp-processing technician shortages.
Spain
Lower extended producer responsibility fees under the national packaging scheme attract conversion asset relocation from higher-fee jurisdictions. Barcelona and Valencia port zones serve as alternative sourcing points for EU-wide distribution networks. REACH-compliant barrier coating reformulation cycles of 18-24 months delay food-contact grade launches for starch-based alternatives.
Protective Wrapping Paper Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the protective wrapping paper value chain. Integrated forestry-to-mill operators sustain input cost advantages through captive pulp supply. Specialized converters compete on engineered structures and barrier coating capabilities. Strategic moves concentrate on brownfield capacity expansions and direct mill-to-warehouse contracting that eliminates distributor intermediation.
Among integrated pulp and paper groups, Mondi Group anchors the cost-efficient supply tier through Central European mill network density. Sealed Air Corporation occupies the engineered-structure premium position with paper-film hybrid capabilities. International Paper Company exemplifies the scale-driven archetype with broad geographic manufacturing footprint. These three representations illustrate how competitive positioning splits between upstream resource control and downstream application engineering.
| Leading Market Players |
|---|
| Amcor Plc |
| Sonoco Products Company |
| Sealed Air Corporation |
| International Paper Company |
| WestRock Company |
| ProAmpac Holdings Inc. |
| Mondi Group |
| DS Smith Plc |
| Smurfit Kappa Group |
| Others |
Value Network & Pricing Analysis
ISTA 3A drop-test certification gates both supplier qualification and price tiering simultaneously, as uncertified converters cannot access German automotive or Dutch electronics contracts regardless of unit cost position. This creates a bifurcated market where validated mills command premium positioning while non-specialized producers compete on commodity fanfold grades.
Pricing Analysis
Polish and Czech corridor pricing runs 12-18% below German North Rhine-Westphalia levels for equivalent kraft basis weights, reflecting lower extended producer responsibility fees and labor costs. Three-tier pricing structure across premium, standard, and economy levels separates ISTA-validated grades from generic cushioning and imported recycled fiber alternatives. Pricing pressure stems from Nordic softwood pulp cost volatility compressing converter margins unpredictably. Third-party logistics providers exhibit highest price sensitivity due to consolidated supplier rosters, while pharmaceutical cold-chain buyers prioritize barrier performance over unit economics.
Supply Chain Analysis
Pulp-processing technician shortages in Finland, Sweden, and Germany constrain greenfield mill construction, forcing capacity additions toward brownfield expansions with shorter commissioning timelines. Nordic spruce and pine fiber, REACH-compliant sizing agents, and automated fanfold dispenser systems anchor the critical input stack. Single-source vulnerability concentrates in Finnish integrated forestry-to-mill operators controlling specialty barrier R&D capabilities. Distribution runs through Rotterdam and Hamburg port zones for cross-border fulfillment, with secondary consolidation at Warsaw and Krakow hubs serving Central European e-commerce corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation recyclability mandates fragment procurement specifications across member states, creating niche openings for converters with national-scheme expertise and certified product portfolios.
For Market Incumbents: Fortify barrier coating R&D partnerships with Finnish pulp mills to defend against bio-based substitute entrants. Prioritize brownfield expansions in Portugal and Spain where extended producer responsibility fees undercut German cost structures. Secure direct contracting relationships with pan-European third-party logistics providers consolidating supplier rosters. For New Entrants and Emerging Players: Lead with automated dispenser system deployments in Polish and Czech corridors where warehouse automation retrofit rates lag e-commerce growth. Target pharmaceutical cold-chain applications requiring paper-film hybrid structures with moisture barrier properties. Position through REACH-compliant sizing agent qualification services that accelerate customer product launches. For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation implementation reshapes the acquisition landscape toward converters with in-house ISTA validation capabilities and national packaging scheme registration breadth. Five-to-ten year viability favors integrated players with captive pulp supply and Central European mill network density. Monitor modulated fee structure announcements as the primary signal for asset relocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Brownfield Capacity Expansion | Polish and Czech mills bypass pulp-processing technician shortages constraining greenfield projects. |
| Backward Integration into Forestry | Nordic spruce supply control insulates against fiber cost volatility affecting converter margins. |
| REACH-Compliant Barrier Development | Bio-based sizing agent portfolios unlock pharmaceutical cold-chain applications beyond commodity dunnage. |
| Direct Warehouse Contracting | Eliminating distributor intermediation captures margin from Rotterdam and Hamburg port zone consolidation. |
| Automated Dispenser Deployment | Fanfold system installations in underdeveloped Central European corridors establish first-mover positioning. |
Research Methodology
A standing panel of pulp mill operations directors, converter procurement leads, third-party logistics warehouse managers, and EU regulatory compliance officers provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against customs trade data, national packaging scheme fee schedules, SEC filings from listed paper groups, and ECHA REACH substance registration databases. Bottom-up volume estimates triangulated against top-down demand models derived from e-commerce fulfillment center expansion announcements.
Consistency checks validated volume and value outputs against external benchmarks including trade association production statistics and port authority throughput disclosures. The analytical framework modeled product type, end user category, material composition, and application severity across the projection horizon. CAGRs derived from segment-level demand elasticities and substitution rate assumptions, with specific inputs including EU Packaging and Packaging Waste Regulation implementation timelines and automotive parts distribution hub expansion plans.
Forecasts assume regulatory continuity in EU Packaging and Packaging Waste Regulation and REACH frameworks; material policy shifts would require re-modeling of compliance cost exposure and substitution economics. Practitioners should keep alternative scenarios live as extended producer responsibility fee modulation schedules and pulp-processing technician training pipeline outputs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Fiber Cushioning Market
Protective Packaging
Corrugated Bubble Wrap Market
Protective Packaging
Insulated Packaging Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Inflatable Packaging Market
Protective Packaging
North America Insulated Packaging Market
Protective Packaging
Static Shielding Bags Market
Protective Packaging
Thermal Insulated Bubble Wrap Market
Protective Packaging
Insulated Shipping Boxes Market
Protective Packaging
Foam Edge Protectors Market
Protective Packaging
Packaging and Protective Packaging Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
Paper Cushion Systems Market
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Foam Packaging Inserts Market