
 Void Fill Pillows Market | 2026-2036
Void Fill Pillows Market Size, Share, and Industry Trends Forecast 2026-2036
Void Fill Pillows Market Analytics
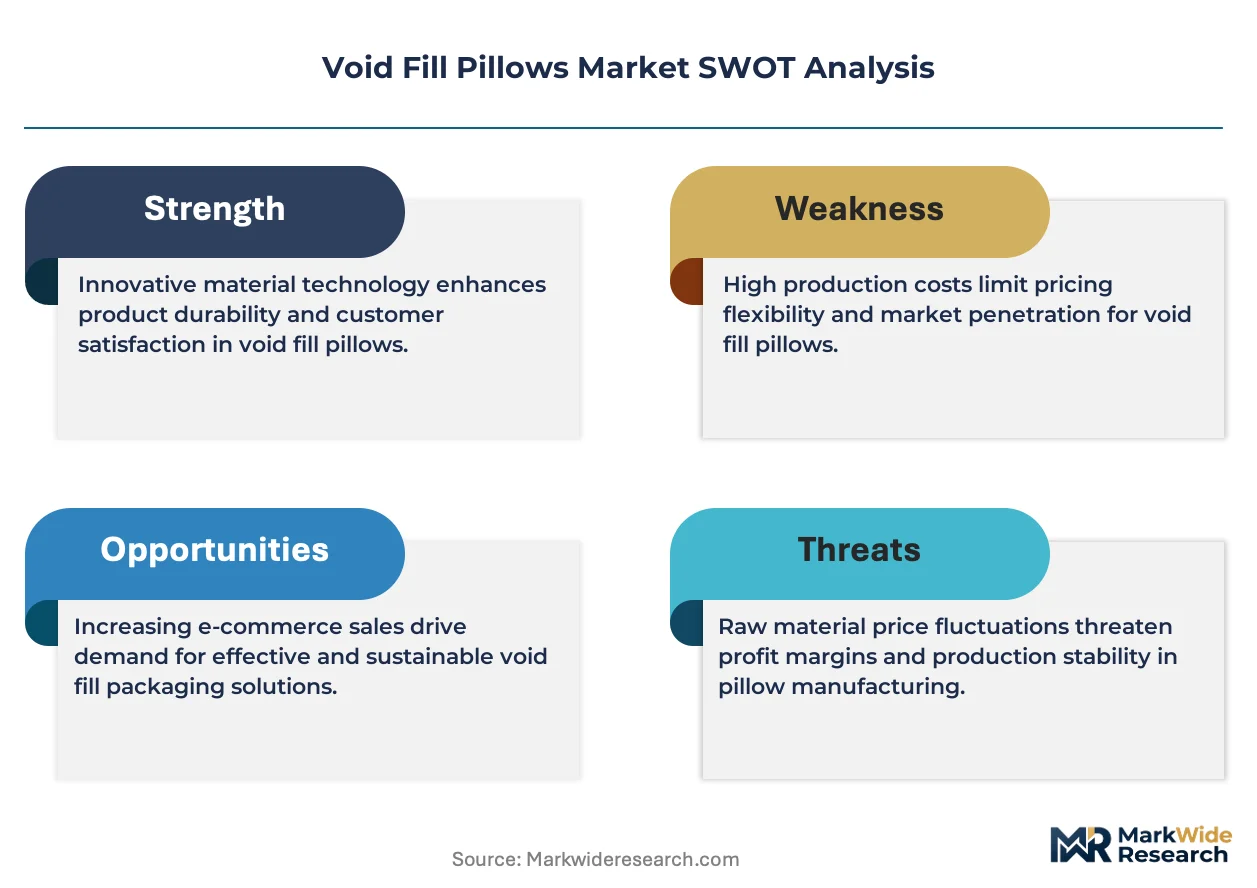
E-commerce fulfillment channels is rewriting procurement patterns for protective packaging. Ranpak leverages sustainable paper-based systems to anchor its position in European logistics networks. Sealed Air competes through automated inflatable platforms that integrate with high-speed warehouse lines. DS Smith sustains market presence via corrugated-integrated void fill solutions that reduce dimensional weight penalties for parcel carriers.
Void fill pillows are inflatable or pre-formed cushioning elements, typically fabricated from polyethylene film or kraft paper substrates, engineered to occupy empty space within shipping containers and absorb shock during transit. Air pillows deploy through on-demand inflation systems that minimize storage footprint versus pre-expanded alternatives. Paper pillows command premium positioning in applications where plastic elimination drives purchasing decisions, while biodegradable variants from cornstarch substrates represent the fastest-growing material trajectory as landfill diversion mandates intensify. E-commerce packaging absorbs the dominant volume share, though medical packaging generates disproportionate margin contribution due to validated sterility requirements.
FDA regulates void fill materials contacting pharmaceutical products through biocompatibility and particulate standards that limit supplier qualification pools. EPA guidelines on recycled content and disposal pathways shape polyethylene sourcing decisions for US manufacturers, while REACH chemical registration requirements in Europe constrain polyurethane additive formulations. Stakeholders must monitor evolving extended producer responsibility frameworks that transfer end-of-life collection costs directly to packaging producers.
Market Dynamics
E-commerce fulfillment networks are compressing packaging procurement cycles while EU Packaging and Packaging Waste Regulation mandates force material transitions across European distribution corridors. Warehouse operators now prioritize on-site inflatable systems that eliminate pre-expanded storage overhead.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:The directive tightens recycled content thresholds and extended producer responsibility frameworks, accelerating biodegradable substrate adoption across German and French logistics hubs.
- Automotive parts distribution:Just-in-time component networks in Germany generate concentrated demand for high-volume protective packaging that withstands multi-modal transit vibration profiles.
- On-demand inflation systems:Film-based air pillow technology reduces warehouse footprint requirements by eliminating pre-expanded cushion inventory, reshaping fulfillment center layout economics.
Market Restraints
- Polyethylene resin volatility:Fossil-derived film substrates expose converters to petrochemical price swings that compress margin stability in high-volume contract manufacturing.
- REACH chemical registration:Additive formulations for polyurethane-based films face ECHA compliance timelines that extend new product qualification cycles by 18-24 months.
- Paper-based substitution pressure:Kraft pillow alternatives capture sustainability-driven accounts despite 40% higher unit costs and moisture sensitivity limitations in humid climates.
Strategic Opportunities
- Medical device packaging:Validated sterility requirements in pharmaceutical distribution create premium positioning for FDA-compliant film grades with biocompatibility certification.
- Cornstarch biodegradable substrates:Landfill diversion mandates in California and New York jurisdictions accelerate demand for compostable alternatives to conventional polyethylene.
- Direct-to-consumer subscription channels:Unboxing experience requirements drive branded void fill specifications that command 15-20% price premiums over commodity grades.
Industry Challenges
- Automated line integration complexity:Retrofitting legacy warehouse conveyor systems with high-speed inflatable dispensers requires specialized mechanical engineering capabilities scarce in mid-tier 3PL operations.
- FDA biocompatibility validation:Pharmaceutical contact applications demand particulate testing and extractables documentation that extends supplier onboarding timelines beyond standard industrial qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Void Fill Pillows Market |
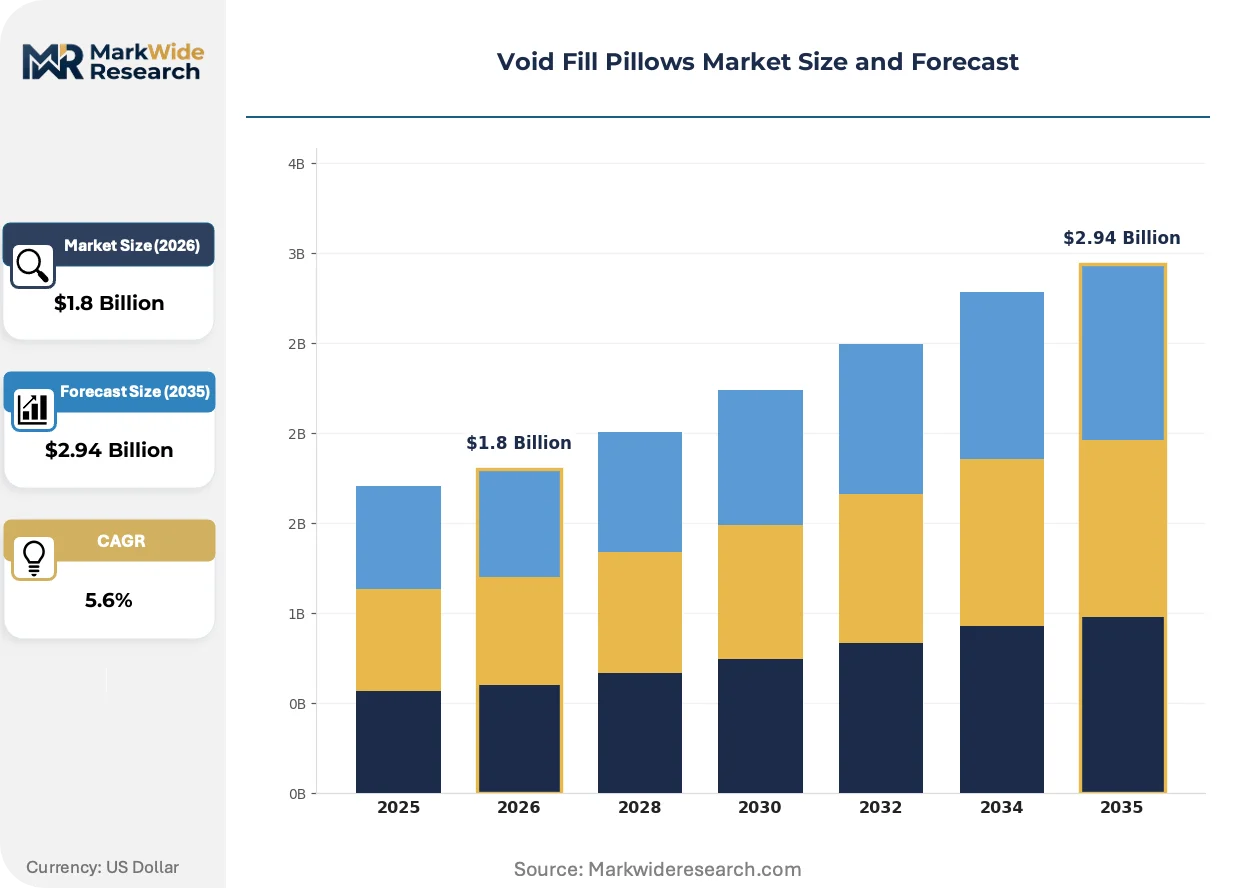
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Pillows, Foam Pillows, Paper Pillows, Biodegradable Pillows Material: Polyethylene, Polyurethane, Paper, Cornstarch Application: E-commerce Packaging, Industrial Packaging, Food Packaging, Medical Packaging End User: Retail, Logistics, Pharmaceuticals, Electronics |
| Companies Covered | Ranpak, Free-Flow Packaging, Sealed Air, DS Smith, Mondi Group, Pregis, Intertape Polymer Group, Huhtamaki, Storopack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Void Fill Pillows Market Evolving Landscape
Material science advances and regulatory pressure are converging to reshape substrate preferences across protective packaging tiers. Three distinct trajectories now dominate strategic planning conversations among converters and end-users.
Biodegradable film formulations derived from cornstarch and polylactic acid blends are migrating from niche sustainability showcases to mainstream e-commerce specifications. Major fulfillment operators in California and Germany now mandate compostable alternatives for consumer-facing shipments. This substrate transition is compressing conventional polyethylene volumes in premium branded packaging segments while opening qualification pathways for European converters with industrial composting certifications.
REACH chemical registration requirements in Europe are constraining additive portfolios for polyurethane film production, forcing reformulation investments across German and French manufacturing bases. The regulation's downstream consequence extends new product development timelines and elevates compliance costs for specialty grades. Medical packaging suppliers with pre-validated biocompatibility dossiers capture disproportionate share in pharmaceutical distribution networks where regulatory documentation carries procurement weight.
Subscription box operators now specify branded void fill aesthetics as unboxing experience investments rather than commodity procurement. This behavioral shift elevates print-quality requirements and color consistency standards that disqualify generic inflatable suppliers. The specification tightening concentrates volume with integrated converters capable of in-house flexographic printing and rapid design iteration cycles.
Void Fill Pillows Market Segmentation
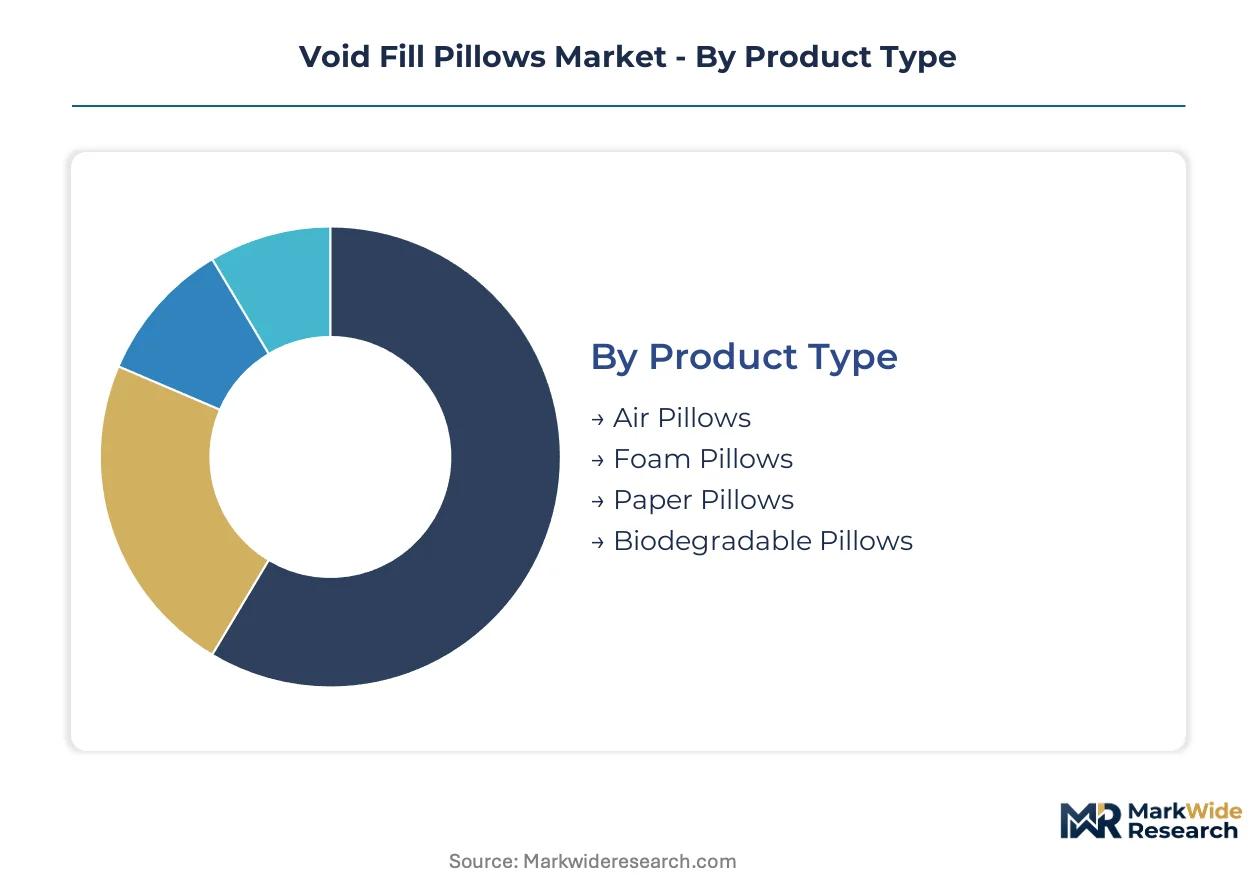
Segmentation in void fill pillows reveals divergent procurement rhythms across material and application boundaries. E-commerce fulfillment networks rotate inventory faster than pharmaceutical validation cycles, creating tiered supplier strategies.
Product Type:
Air pillows turn inventory fastest through on-demand inflation systems, while foam pillows sit longest due to bulk storage requirements.
- Air Pillows:Polyethylene film substrates inflate at point-of-use through automated dispensers, eliminating pre-expanded cushion warehousing. E-commerce fulfillment centers in Germany and California drive concentrated adoption as operators compress storage footprints.
- Paper Pillows:Kraft-based cushioning delivers moisture-sensitive protection with plastic-free positioning for sustainability mandates. European automotive parts distributors in Stuttgart and Wolfsburg specify these for intra-continental shipments under EU Packaging and Packaging Waste Regulation compliance timelines.
- Foam Pillows:Pre-expanded polyurethane or polyethylene foam blocks provide crush-resistant protection for heavy industrial components.
- Biodegradable Pillows:Cornstarch and polylactic acid formulations decompose in industrial composting environments.
Air pillows anchor the volume base while biodegradable pillows gain share at the steepest rate.
Material:
Polyethylene dominates contract manufacturing volumes, whereas cornstarch substrates command premium positioning through landfill diversion credits.
- Polyethylene:Low-density film grades extrude into inflatable chambers with heat-sealed seams, offering the lowest unit cost for high-velocity e-commerce operations. Petrochemical price volatility exposes converters to margin compression during oil market swings.
- Cornstarch:Thermoplastic starch blends biodegrade within 180 days under industrial composting conditions, satisfying California SB 54 and New York extended producer responsibility mandates for plastic reduction.
- Polyurethane:Flexible foam formulations deliver superior vibration damping for precision electronics shipments.
- Paper:Recycled kraft pulp structures provide rigid cushioning with established recycling infrastructure.
Polyethylene carries the heaviest volume load, though cornstarch exhibits the most rapid specification expansion.
Application:
E-commerce packaging cycles weekly purchase orders, while medical packaging extends to annual contracts with validation documentation.
- E-commerce Packaging:Direct-to-consumer fulfillment networks consume inflatable void fill at machine-paced throughput rates, with unboxing experience requirements driving branded print specifications and color consistency standards.
- Medical Packaging:FDA biocompatibility validation and particulate testing requirements restrict supplier pools for pharmaceutical contact applications, generating disproportionate margin contribution despite lower absolute volumes.
- Industrial Packaging:Heavy machinery and automotive component distribution demands crush-resistant cushioning for multi-modal transit.
- Food Packaging:FDA and EFSA compliance for incidental food contact limits approved substrate formulations.
E-commerce packaging underpins total demand scale, while medical packaging delivers the highest margin realization per unit.
End User:
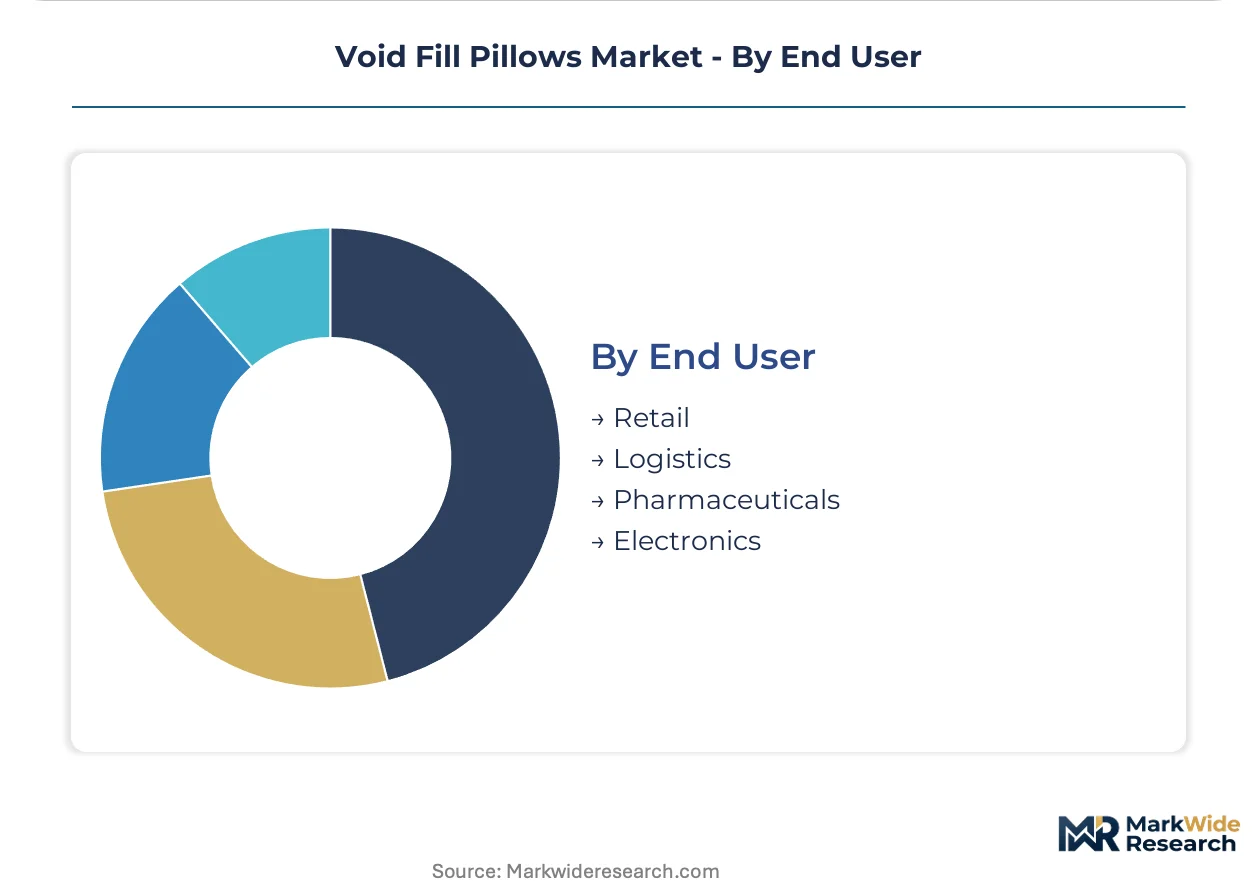
Logistics providers rotate suppliers quarterly on price, whereas pharmaceutical procurement locks in multi-year validated relationships.
- Logistics:Third-party fulfillment operators prioritize total cost-per-package metrics, driving adoption of on-site inflation systems that eliminate pre-expanded inventory carrying costs across warehouse networks.
- Pharmaceuticals:Sterility validation requirements and extractables documentation extend supplier onboarding timelines, creating defensive moats for converters with pre-established FDA master files.
- Retail:Omnichannel distribution networks balance brick-and-mortar restocking with direct-to-consumer parcel protection.
- Electronics:Precision component manufacturers specify anti-static and vibration-damping grades for semiconductor and display shipments.
Logistics commands the largest absolute volume, while pharmaceuticals demonstrate the stickiest supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling infrastructure underwrites the Netherlands' role as the European distribution gateway for protective packaging materials. German rail corridors connect this hub to Stuttgart and Wolfsburg automotive clusters. US West Coast port complexes in Los Angeles and Long Beach anchor trans-Pacific e-commerce fulfillment networks.
Germany
Automotive parts distribution from Stuttgart and Wolfsburg generates concentrated demand for high-volume protective packaging. The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds that accelerate biodegradable substrate qualification. Warehouse operators in Bavaria deploy on-demand inflation systems to compress storage footprints.
United States
E-commerce fulfillment networks in California and New York drive specification shifts toward compostable alternatives. EPA guidelines on recycled content shape polyethylene sourcing decisions for domestic converters. Los Angeles basin distribution centers integrate automated inflatable dispensers with high-speed conveyor lines.
China
Export manufacturing clusters in the Yangtze River Delta consume bulk volumes of inflatable void fill for cross-border e-commerce shipments. The country's dual carbon goals constrain fossil-derived film substrate expansion. Shenzhen logistics hubs prioritize space-efficient on-demand systems for last-mile parcel protection.
France
Pharmaceutical distribution networks in Lyon and Paris require FDA-compliant film grades with biocompatibility certification. ANSM pharmaceutical packaging standards restrict supplier qualification pools for medical contact applications. Île-de-France fulfillment operators balance EU regulatory timelines with unboxing experience investments.
India
Domestic e-commerce expansion in Maharashtra and Karnataka drives adoption of cost-optimized inflatable systems. BIS packaging standards create compliance entry barriers for imported substrate formulations. Mumbai logistics corridors integrate void fill automation with rapid inventory turnover requirements.
Void Fill Pillows Market Competitive Landscape
On the supply side, the industry is structured around tiered specialization with distinct capability clusters dominating separate value chain segments. Consolidated film extruders and diversified packaging conglomerates occupy parallel competitive spaces with limited direct overlap. Three strategic archetypes dominate: automated system integrators, sustainable substrate specialists, and corrugated-integrated solution providers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure warehouse automation integration capabilities.
Within the sustainable substrate tier, Ranpak and DS Smith exemplify divergent approaches to plastic elimination mandates. Sealed Air occupies a position at the automated system integration end, anchoring the technology-intensive segment where conveyor compatibility determines procurement decisions. These three entities collectively represent the strategic spectrum from paper-based sustainability positioning through film-based automation platforms.
| Leading Market Players |
|---|
| Ranpak |
| Free-Flow Packaging |
| Sealed Air |
| DS Smith |
| Mondi Group |
| Pregis |
| Intertape Polymer Group |
| Huhtamaki |
| Storopack |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta extrusion cluster anchors global polyethylene film supply, with capacity utilization swings directly transmitting to downstream void fill pillow contract pricing. German automotive parts distributors face 40% higher unit costs for kraft paper alternatives, yet EU Packaging and Packaging Waste Regulation compliance timelines compress polyethylene's cost advantage as landfill diversion mandates intensify.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement contracts, with FDA biocompatibility certification and branded flexographic print specifications commanding 15-20% premiums over commodity grades. Price differentiation hinges on sterility validation documentation and volume scale, with logistics providers rotating suppliers quarterly on total cost-per-package metrics while pharmaceutical procurement locks in multi-year validated relationships. Cost compression in standard-tier polyethylene film is intensifying because petrochemical price volatility exposes converters to margin instability during oil market swings. Third-party fulfillment operators demonstrate the highest price sensitivity, whereas medical device manufacturers accept premium positioning for regulatory documentation security.
Supply Chain Analysis
Sealed Air, Ranpak, and DS Smith concentrate contract manufacturing capacity across Germany, the United States, and China, with each hub serving distinct regulatory and end-use specifications. Raw material flows draw from fossil-derived polyethylene resin, cornstarch thermoplastic blends, and recycled kraft pulp, with additive formulations for polyurethane films facing ECHA compliance timelines that extend qualification cycles. Single-source vulnerability concentrates in German automotive corridor supply, where just-in-time component networks tolerate minimal inventory buffers. Distribution runs through third-party logistics networks that prioritize on-site inflation systems to eliminate pre-expanded cushion warehousing overhead.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation constitutes a structural inflection, forcing material transitions that favor converters with pre-validated biodegradable substrate portfolios and industrial composting certifications.
For Market Incumbents: Pre-empt paper-based substitution pressure by accelerating cornstarch formulation R&D and securing industrial composting certifications in California and New York jurisdictions before landfill diversion mandates tighten. Defensive consolidation through captive supply of polyethylene resin or backward integration into film extrusion buffers margin exposure to petrochemical volatility. Certification investment in FDA master files creates defensive moats against emerging substrate specialists threatening pharmaceutical distribution networks. For New Entrants and Emerging Players: Establish a beachhead in medical device packaging, where sterility validation requirements restrict supplier pools and generate disproportionate margin contribution despite lower absolute volumes. White-space targets include FDA-compliant film grades with biocompatibility certification and branded void fill specifications for subscription box operators prioritizing unboxing experience investments. A direct-to-consumer unboxing angle bypasses entrenched logistics provider relationships that rotate on price. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because extended producer responsibility frameworks transfer end-of-life collection costs directly to packaging producers, favoring converters with diversified substrate portfolios and pre-established composting infrastructure. Acquisition targets should display industrial composting certifications and validated biocompatibility dossiers. The signal to watch is California SB 54 implementation velocity and New York extended producer responsibility rulemaking timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Scale-Up | Industrial composting certification secures preferential positioning under EU Packaging and Packaging Waste Regulation timelines. |
| Backward Integration into Film Extrusion | Captive polyethylene supply buffers margin compression from petrochemical price volatility in high-volume contracts. |
| FDA Master File Investment | Pre-validated biocompatibility documentation accelerates pharmaceutical supplier onboarding against 18-24 month qualification cycles. |
| Automated Dispenser Integration Partnership | Conveyor compatibility with Sealed Air platforms determines procurement decisions in high-velocity fulfillment networks. |
| Branded Flexographic Capability Expansion | In-house print quality and color consistency captures subscription box specifications commanding 15-20% price premiums. |
Research Methodology
A spread of perspectives from warehouse operations directors, packaging procurement managers at third-party logistics providers, regulatory affairs leads at film converters, and sustainability officers at e-commerce fulfillment operators converged on the working assumptions. Primary interviews combined with secondary validation from EPA recycled content guidelines, ECHA REACH registration databases, FDA 510(k) filings, and EU Packaging and Packaging Waste Regulation impact assessments. Bottom-up demand modeling across e-commerce, medical, and industrial packaging segments triangulated against top-down polyethylene resin consumption data.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning material substrate, product inflation mechanism, application sterility requirements, and end-user procurement rhythm. CAGRs derived from volume trajectory modeling incorporating EU regulatory compliance timelines, California SB 54 implementation schedules, and automotive parts distribution network expansion patterns. Industry-specific forecast inputs included petrochemical price volatility indices and industrial composting facility capacity buildout rates.
Stress conditions across polyethylene resin price bands, REACH chemical registration delays, and biodegradable substrate qualification timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions around EU Packaging and Packaging Waste Regulation enforcement consistency and landfill diversion mandate adoption velocity. Quarterly review of ECHA substance registration updates, California SB 54 rulemaking progress, and German automotive production forecasts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Thermal Insulated Bubble Wrap Market
Protective Packaging
Latin America Protective Packaging Market
Protective Packaging
Secondary Containment Trays Market
Protective Packaging
Insulated Packaging Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
Middle East and Africa Protective Packaging Market
Protective Packaging
Insulated Shippers Market
Protective Packaging
Insulated Shipping Boxes Market
Protective Packaging
Anti-Static Foam Packaging Market
Protective Packaging
Global Packaging Inserts and Cushions Market
Protective Packaging
Inflatable Packaging Market
Protective Packaging
Padded Mailers Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
North America Protective Packaging Market
Protective Packaging
Paper Cushion Systems Market