
 Foam Protective Packaging Market | 2026-2036
Foam Protective Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Protective Packaging Market Analysis
Expanded polystyrene alternatives with higher recycled content is rotating through procurement specifications across European electronics supply chains. Sealed Air Corporation leverages closed-loop recycling infrastructure to sustain premium positioning in healthcare cold-chain applications. BASF SE anchors industrial-grade polyurethane foam supply through backward integration into polyol chemistry. UFP Technologies specializes in medical device cushioning, competing on FDA-validated cleanroom manufacturing protocols.
Foam protective packaging comprises cellular polymer structures engineered with controlled density profiles between 16 kg/m³ and 200 kg/m³, manufactured through extrusion, expansion, or molding processes to absorb mechanical shock and thermal variance during product transit. Polyethylene foam dominates unit volume in consumer goods logistics due to its closed-cell moisture resistance and repeated-use durability, while polyurethane foam captures margin concentration in aerospace vibration-dampening applications where MIL-STD-810 compliance commands price premiums. Custom shapes represent the fastest-growing form category as automated cutting and CNC hot-wire systems enable lot-size-one production for robotics and drone OEMs.
EPA hazardous substance reporting under TSCA Section 8(a) shapes polystyrene feedstock disclosure requirements for US manufacturers, while REACH Annex XVII restrictions on persistent organic pollutants constrain flame-retardant additive selection across EU supply chains. China's GB standards for packaging material recyclability mandate labeling transparency that affects export-bound foam specifications. Stakeholders must monitor emerging extended producer responsibility frameworks in California and New York that will redefine cost allocation between packaging converters and brand owners.
Market Dynamics
REACH Annex XVII restrictions on persistent organic pollutants and California's extended producer responsibility frameworks are forcing converters to redesign flame-retardant chemistries and cost allocation models simultaneously.
Growth Catalysts
- E-commerce fulfillment automation:Robotic picking systems in German and Chinese distribution centers require precision-molded polyethylene foam inserts with exact dimensional tolerances.
- EU Green Deal packaging mandates:Bio-based polyurethane feedstocks gain procurement preference across European electronics supply chains as virgin polystyrene faces phasedown timelines.
- Cold-chain pharmaceutical expansion:Insulin and vaccine distribution networks in India and Brazil are adopting multi-use temperature-stable foam shippers validated to WHO performance standards.
Market Restraints
- Polyol feedstock volatility:Propylene oxide and toluene diisocyanate price swings compress margin predictability for polyurethane foam converters.
- Chinese supply concentration:Over 60 percent of global expandable polystyrene bead capacity sits in Shandong and Jiangsu provinces, creating single-point vulnerability.
- Recycling infrastructure gaps:Cross-linked polyethylene foam lacks mechanical reprocessing pathways at commercial scale, limiting circular economy claims.
Strategic Opportunities
- India electronics manufacturing clusters:Tamil Nadu and Karnataka special economic zones offer tariff advantages for foam converters serving smartphone and laptop OEMs.
- Aerospace vibration damping:MIL-STD-810 compliant polyurethane systems command price premiums in satellite and drone payload protection.
- Digital print-on-foam customization:Direct-to-substrate branding enables lot-size-one production for influencer-commerce subscription boxes.
Industry Challenges
- Cleanroom certification timelines:FDA-validated medical device foam manufacturing requires 18-24 month qualification cycles that delay revenue recognition.
- Legacy ERP integration:Batch-oriented foam converters struggle to connect inventory systems with real-time e-commerce fulfillment APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Protective Packaging Market |
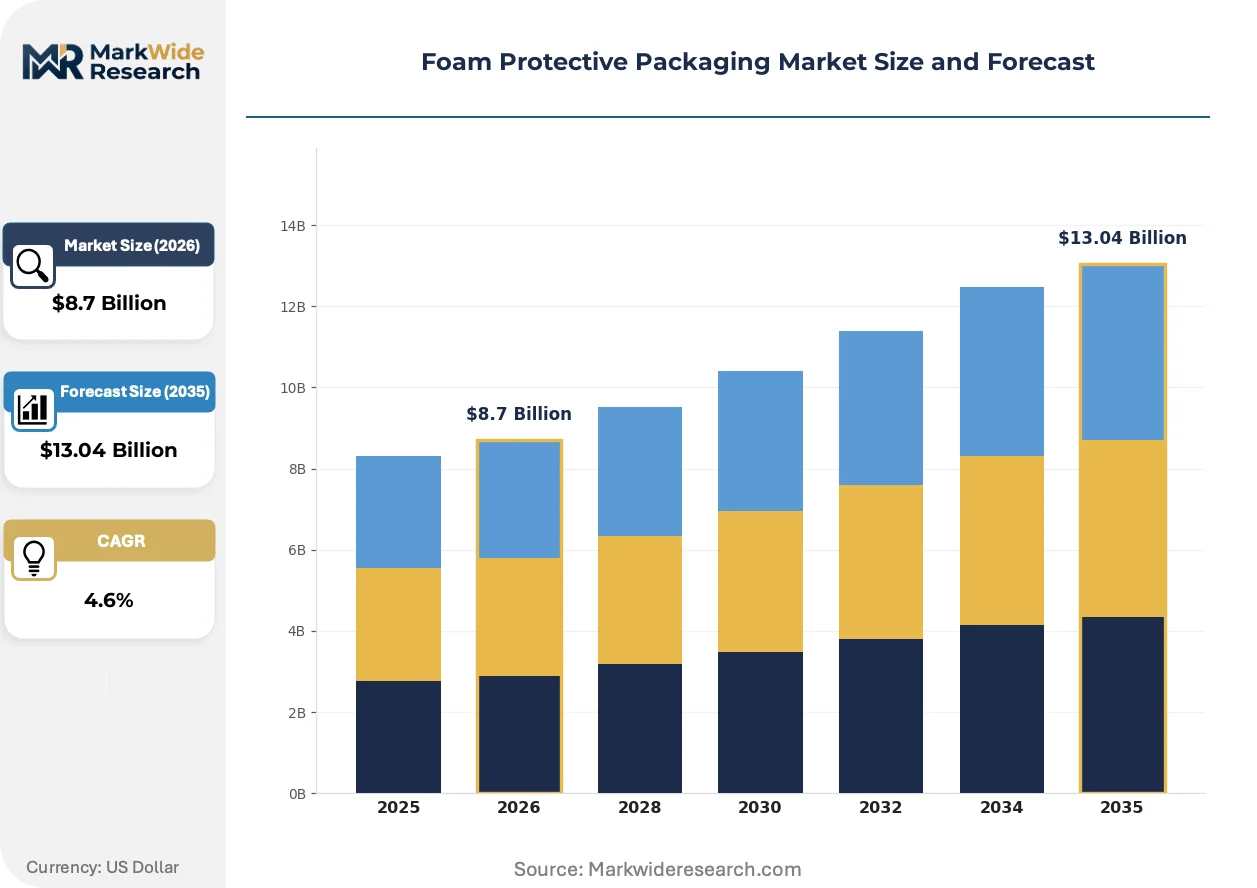
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Foam, Polyurethane Foam, Expanded Polystyrene, Polypropylene Foam Application: Aerospace, Electronics, Automotive, Consumer Goods End User: Retail, Manufacturing, Logistics, Healthcare Form: Rolls, Sheets, Custom Shapes, Blocks |
| Companies Covered | Pregis Corporation, UFP Technologies, Sealed Air Corporation, Storopack Hans Reichenecker GmbH, BASF SE, Smurfit Kappa Group, DS Smith PLC, Zotefoams plc, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Protective Packaging Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are compressing traditional polymer hierarchies while opening niches for bio-based and recycled-content alternatives.
Water-blown polyurethane formulations are fragmenting the blowing-agent landscape as HFC phase-down schedules under the F-Gas Regulation force converters toward lower-GWP alternatives. Appliance and HVAC OEMs in Poland and Italy are qualifying these systems for compressor packaging. The shift is fragmenting supplier tiers between legacy HFC-equipped plants and capital-intensive water-blown retrofits.
REACH authorization requirements for halogenated flame retardants are compelling additive reformulation across EU-bound electronics foam. Converter technical service teams are testing phosphorus-nitrogen synergists in polyethylene and polypropylene systems. Medical device and automotive interior segments face the steepest retesting burdens.
Direct-to-brand procurement platforms are compressing distributor margins as Amazon, IKEA, and Zalando build private-label foam specifications with Asian toll manufacturers. These arrangements bypass traditional packaging distributors in Germany and the Netherlands. Quality assurance and lot traceability requirements are rising in parallel.
Foam Protective Packaging Market Segmentation
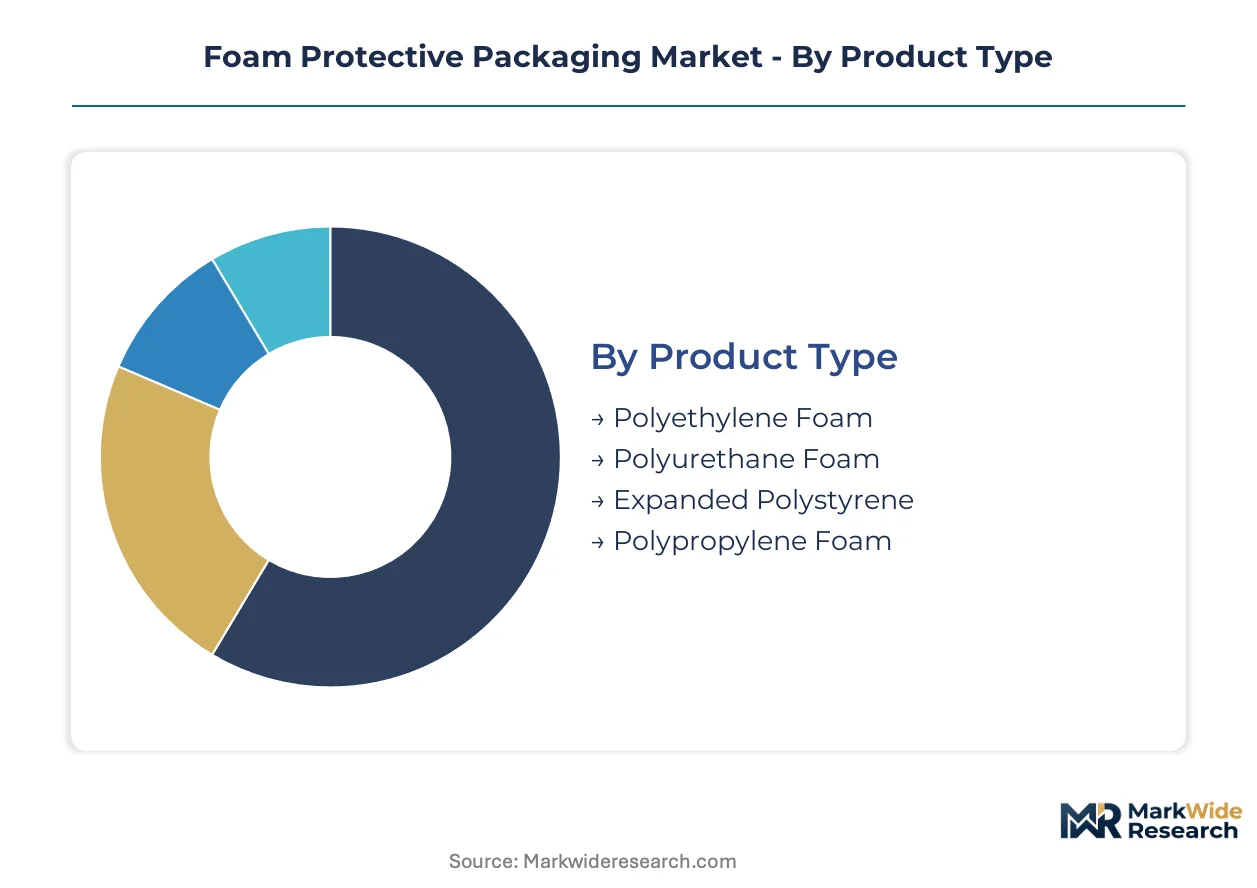
Foam protective packaging segments fragment along material chemistry lines that determine recyclability pathways and regulatory exposure. Procurement specifications now weight substitution risk as heavily as unit cost, reshaping converter investment priorities across polymer categories.
Product Type:
Substitution pressure from bio-based alternatives and recycled-content mandates hits polymer segments unevenly, with fossil-derived feedstocks facing the steepest procurement headwinds.
- Polyethylene Foam:Closed-cell cross-linked structure delivers moisture resistance and repeated-use durability in consumer goods logistics. E-commerce fulfillment centers in Germany and China specify this material for robotic picking system compatibility, though mechanical recycling limitations constrain circular economy claims.
- Polyurethane Foam:Open-cell or rigid formulations engineered through polyol-isocyanate reactions achieve density profiles from 16 kg/m³ to 200 kg/m³. Aerospace vibration-dampening applications in satellite and drone payload protection command price premiums where MIL-STD-810 compliance is mandatory.
- Expanded Polystyrene:Bead-expansion process creates lightweight cellular structures with thermal insulation properties; REACH restrictions and EU Green Deal phasedown timelines accelerate material displacement in electronics supply chains.
- Polypropylene Foam:Extruded or molded bead formats offer higher service temperatures than polyethylene; automotive interior applications in Germany's manufacturing corridor drive qualification programs for this segment.
Polyethylene foam retains volume leadership; polyurethane foam holds the steepest expansion curve.
Application:
Margin concentration varies sharply by end-use certification burden, with aerospace and healthcare applications extracting premiums that consumer goods volumes cannot support.
- Aerospace:Vibration-dampening and thermal protection systems for satellite payloads, avionics modules, and drone components require MIL-STD-810 and RTCA-DO-160 compliance. Polyurethane foam converters capture sustained margin premiums through material qualification programs that lock out commodity competitors.
- Electronics:Static-dissipative and cleanroom-compatible foam inserts protect semiconductors, displays, and batteries during transit. China's export zones and Tamil Nadu's special economic zones concentrate procurement volume for smartphone and laptop OEM specifications.
- Automotive:Interior trim components, battery pack cushioning, and powertrain protection utilize molded foam with flame-retardant additive packages; REACH Annex XVII reformulation requirements are compelling phosphorus-nitrogen synergist testing across EU-bound supply chains.
- Consumer Goods:Appliance, furniture, and household product packaging emphasizes cost minimization over performance specification; direct-to-brand procurement platforms are compressing traditional distributor margins in this price-sensitive tier.
Electronics applications dominate procurement volume; aerospace commands the highest margin realization per unit.
End User:
Customer type determines service intensity, with healthcare and retail segments presenting opposing requirements for traceability versus cost minimization.
- Retail:Direct-to-consumer e-commerce operations require lot-size-one foam customization for subscription boxes and influencer-commerce branding; digital print-on-foam capabilities are becoming a procurement differentiator.
- Manufacturing:OEM inbound material protection and finished goods outbound packaging demand JIT delivery coordination; automotive and electronics manufacturers in Germany and China specify exact dimensional tolerances for automated assembly line compatibility.
- Logistics:Third-party fulfillment providers and parcel carriers optimize for cube utilization and damage-rate reduction; multi-use temperature-stable foam shippers are gaining adoption in pharmaceutical distribution networks.
- Healthcare:FDA-validated cleanroom manufacturing protocols govern medical device cushioning and pharmaceutical cold-chain protection; 18-24 month qualification cycles delay revenue recognition but sustain premium positioning.
Logistics end users drive aggregate volume; healthcare delivers the longest contract tenures and highest switching costs.
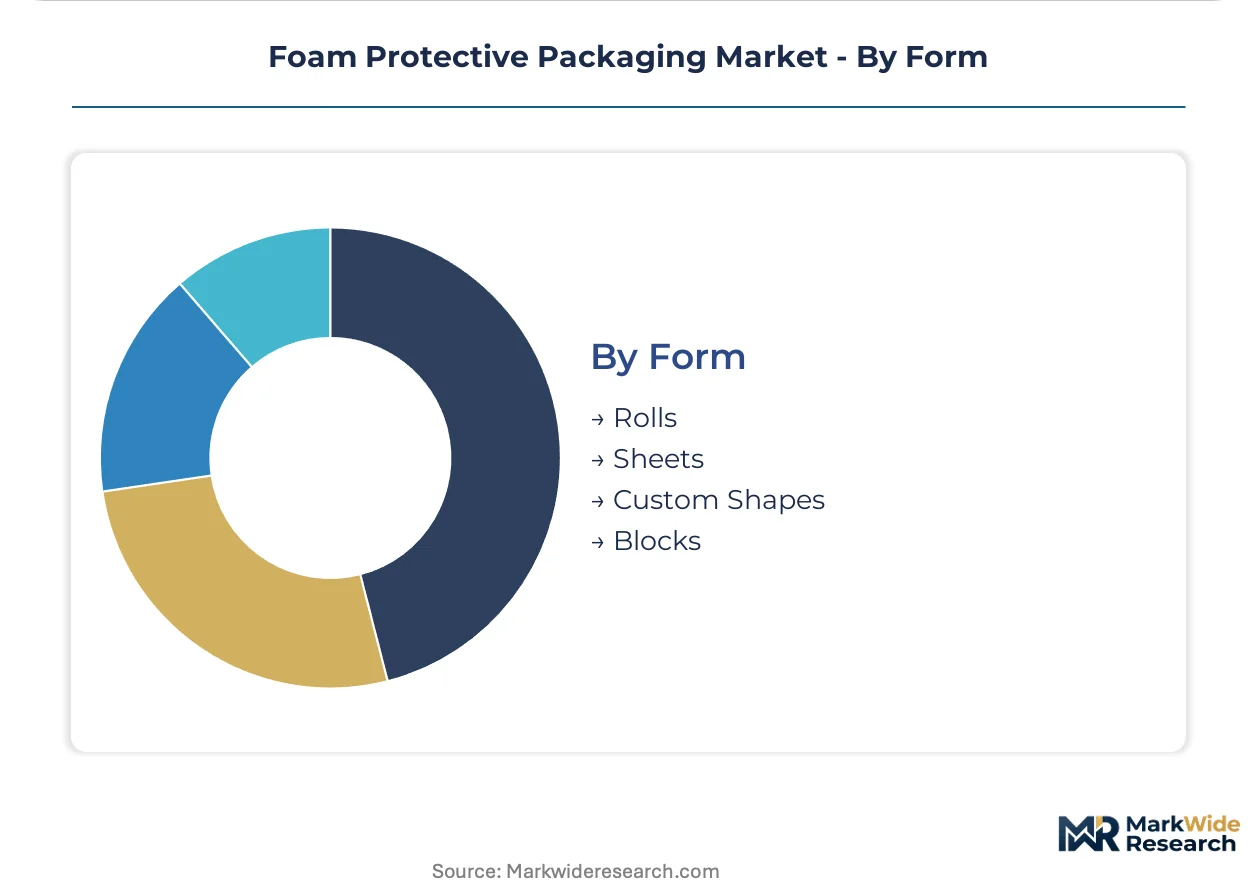
Form:
Production technology investment separates commodity roll and sheet formats from value-added custom fabrication capabilities.
- Rolls:Continuous extrusion output wound for automated cutting operations; high-volume consumer goods and logistics applications in distribution centers favor this format for processing efficiency.
- Sheets:Flat-panel formats in standardized thicknesses serve manufacturing and retail segments with moderate customization requirements; water-blown polyurethane sheet systems are fragmenting supplier tiers in appliance packaging.
- Custom Shapes:CNC hot-wire cutting, die-cutting, and thermoforming enable lot-size-one production for robotics, drone, and medical device OEMs; automated cutting systems are compressing minimum order quantities and lead times for this expanding category.
- Blocks:Bun or billet formats feed downstream fabrication operations or serve heavy-equipment cushioning directly; construction and industrial machinery segments in China's manufacturing zones absorb block volume.
Rolls and sheets retain manufacturing volume concentration; custom shapes are climbing the fastest as automation enables economically viable lot-size-one production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing clusters in Germany, China, and the United States generate disproportionate foam packaging demand relative to domestic consumption, creating trade-flow dependencies that shape regional converter strategies. Import-dependent markets in India and Brazil rely on cold-chain infrastructure buildouts to capture pharmaceutical distribution value.
United States
E-commerce fulfillment automation and pharmaceutical cold-chain expansion drive specification intensity. EPA hazardous substance reporting under TSCA Section 8(a) shapes polystyrene feedstock disclosure requirements for domestic manufacturers. The Southeast manufacturing corridor, spanning Georgia and Tennessee, concentrates molded polyethylene capacity serving appliance and automotive OEMs.
Germany
Automotive manufacturing and precision electronics exports anchor polyurethane and polyethylene foam procurement volumes. REACH Annex XVII restrictions on persistent organic pollutants compel flame-retardant additive reformulation across EU-bound supply chains. Bavaria's automotive manufacturing corridor hosts qualification programs for polypropylene foam in battery pack cushioning applications.
China
Electronics export zones in Guangdong and Jiangsu provinces absorb expanded polystyrene and polyethylene foam volumes for smartphone and laptop OEM specifications. GB standards for packaging material recyclability mandate labeling transparency affecting export-bound foam specifications. Shandong and Jiangsu provinces concentrate over sixty percent of global expandable polystyrene bead capacity.
India
Electronics manufacturing clusters in Tamil Nadu and Karnataka special economic zones offer tariff advantages for foam converters serving smartphone and laptop OEMs. Insulin and vaccine distribution networks adopt multi-use temperature-stable foam shippers validated to WHO performance standards. Tamil Nadu's Sriperumbudur electronics cluster drives custom-shape foam demand for robotics and drone OEMs.
Brazil
Pharmaceutical cold-chain infrastructure gaps create adoption headwinds for temperature-stable foam shippers despite WHO validation requirements. ANVISA regulatory alignment with international standards accelerates gradually. São Paulo state's logistics corridor concentrates third-party fulfillment provider demand for consumer goods protective packaging.
Foam Protective Packaging Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and certification depth, producing a tiered structure where scale advantages clash with agility premiums. Publicly traded packaging conglomerates leverage balance sheet capacity for automated cutting system investments. Three archetypes dominate: diversified materials conglomerates with captive chemistry, medical device specialists with FDA-validated cleanroom protocols, and regional fabricators with toll manufacturing relationships. M&A activity concentrates in automated cutting capabilities and water-blown polyurethane retrofit assets.
Among diversified materials conglomerates, BASF SE anchors industrial-grade polyurethane foam supply through backward integration into polyol chemistry. Sealed Air Corporation exemplifies the premium healthcare cold-chain specialist archetype. UFP Technologies occupies a position within the medical device cushioning tier. These three entities represent distinct competitive vectors: chemistry control, closed-loop recycling infrastructure, and FDA-validated manufacturing protocols respectively.
| Leading Market Players |
|---|
| Pregis Corporation |
| UFP Technologies |
| Sealed Air Corporation |
| Storopack Hans Reichenecker GmbH |
| BASF SE |
| Smurfit Kappa Group |
| DS Smith PLC |
| Zotefoams plc |
| Sonoco Products Company |
| Others |
Supply Flow & Price Mechanics
Ninety-day polyol inventory cycles in polyurethane foam manufacturing tether working capital exposure to propylene oxide price volatility, compressing margin predictability for converters while amplifying pricing power among backward-integrated suppliers with captive polyol chemistry. This inventory-risk asymmetry stratifies the competitive landscape between integrated majors and toll-dependent fabricators.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with three-tier pricing differentiation across premium, standard, and economy certification grades. Price differentiation rests on FDA validation tier and MIL-STD-810 compliance level, with aerospace and healthcare segments extracting premiums that consumer goods volumes cannot support. Cost compression in the consumer goods tier is intensifying because direct-to-brand procurement platforms bypass traditional distributor markups. Third-party logistics providers exhibit the highest price sensitivity due to cube-utilization optimization mandates, while pharmaceutical cold-chain operators accept premium positioning for WHO-validated temperature stability.
Supply Chain Analysis
Just-in-time delivery coordination dominates automotive and electronics manufacturing procurement, though strategic stockpiling of expandable polystyrene beads persists among converters hedging against Shandong and Jiangsu province supply disruptions. Raw material dependencies center on propylene oxide, toluene diisocyanate, and polyethylene resin feedstocks. Single-source vulnerability concentrates in Chinese expandable polystyrene bead capacity, where over sixty percent of global supply sits in two provinces. Distribution runs through converter-fabricator networks with toll manufacturing relationships in Germany, China, and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The foam protective packaging market functions as a regulatory-entrenchment defensive moat, where FDA-validated cleanroom protocols and REACH-compliant flame-retardant formulations create eighteen-to-twenty-four month qualification barriers that lock out commodity competitors.
For Market Incumbents: Consolidate automated cutting capabilities and water-blown polyurethane retrofit assets to defend against bio-based substitute encroachment. Acquire regional fabricators in Tamil Nadu and Karnataka special economic zones to anchor electronics manufacturing cluster proximity. Deepen backward integration into polyol chemistry to offset propylene oxide feedstock volatility. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for medical device cushioning applications open white-space entry with lower regulatory burden than PMA routes. Target aerospace vibration-dampening segments in satellite and drone payload protection where MIL-STD-810 compliance commands price premiums. Pursue direct-to-brand procurement platform relationships with e-commerce fulfillment operators seeking lot-size-one customization capabilities. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because M&A activity concentrates in automated fabrication assets and regulatory-validated manufacturing footprints that sustain premium positioning. Acquisition target archetype: mid-cap medical device foam specialists with FDA-validated cleanroom protocols and established OEM qualification programs. Watch for REACH Annex XVII flame-retardant reformulation deadlines as inflection indicators for additive chemistry substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Chemistry | BASF SE anchors industrial-grade polyurethane supply through captive feedstock control. |
| Water-Blown Polyurethane Retrofit | F-Gas Regulation phase-down schedules force converter capital deployment toward lower-GWP alternatives. |
| Automated Cutting System Investment | CNC hot-wire and die-cutting capabilities compress minimum order quantities for custom-shape production. |
| FDA-Validated Cleanroom Expansion | Eighteen-to-twenty-four month qualification cycles sustain premium positioning in medical device cushioning. |
| Direct-to-Brand Procurement Platform | Amazon and IKEA private-label specifications bypass traditional packaging distributors in Germany. |
Methodological Framework
A spread of perspectives from foam converter plant managers, automotive OEM procurement leads, pharmaceutical distribution channel partners, and technical R&D directors converged on the working assumptions underlying demand segmentation. Primary interview intelligence combined with customs and trade data, SEC 10-K filings from listed packaging conglomerates, and ECHA REACH registration databases. Bottom-up volume builds across material chemistry categories triangulated against top-down macroeconomic demand drivers.
Segmentation dimensions modeled include material chemistry type, application vertical, end-user category, and production form factor across the projection horizon. CAGRs derived from historical shipment data, capacity utilization rates, and substitution elasticity parameters. Industry-specific forecast inputs incorporated EU Green Deal phasedown timelines for virgin polystyrene and WHO performance standard adoption curves for pharmaceutical cold-chain infrastructure.
Underlying assumptions cover polyol feedstock price stability and REACH regulatory enforcement continuity, with deviation risk concentrated in Chinese supply concentration and extended producer responsibility framework implementation timelines. Revision becomes warranted when bio-based polyurethane cost parity thresholds cross commercial viability breakpoints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
High Pressure Protective Packaging Film Market
Protective Packaging
Paper Cushion Systems Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
Protective Wrapping Paper Market
Protective Packaging
Packaging and Protective Packaging Market
Protective Packaging
Middle East and Africa Protective Packaging Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Fiber Cushioning Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Thermal Insulated Mailers Market
Protective Packaging
Anti-Static Foam Packaging Market
Protective Packaging
North America Protective Packaging Market
Protective Packaging
Thermal Insulated Bubble Wrap Market
Protective Packaging
Static Shielding Bags Market