
 Adhesive Bubble Wrap Market | 2026-2036
Adhesive Bubble Wrap Market Size, Share, and Industry Trends Forecast 2026-2036
Adhesive Bubble Wrap Market Analysis
High-tack acrylic adhesive grades is rotating toward the center of procurement specifications as fulfillment operations prioritize auto-applied seals that eliminate tape redundancy. Sealed Air Corporation leverages its Instapak automation ecosystem to anchor premium positioning in electronics fulfillment. Pregis LLC sustains North American manufacturing scale through regional blown-film capacity. Smurfit Kappa Group differentiates via integrated paper-bubble hybrid formats that compete with pure polymer alternatives.
Adhesive bubble wrap consists of polyethylene film extruded with trapped air hemispheres and coated on one face with pressure-sensitive adhesive, typically formulated from synthetic rubber or acrylic resin with release-liner backing for manual or automated dispensing. The structure delivers shock absorption and surface protection during transit while the adhesive layer eliminates secondary securing materials in high-velocity packing environments. Anti-static bubble wrap commands attention from semiconductor and consumer electronics channels where electrostatic discharge risks void component warranties. E-commerce end users represent the fastest-expanding demand pool as carton-sealing automation spreads through third-party logistics networks. Reinforced bubble wrap with laminated scrim layers occupies the margin-rich tier for heavy-goods industrial shipments where puncture resistance determines carrier acceptance.
EPA guidelines on volatile organic compound emissions from adhesive manufacturing shape formulation choices for domestic producers, while REACH registration requirements in Europe restrict certain phthalate plasticizers in pressure-sensitive coatings. FDA indirect food contact regulations govern adhesive bubble wrap deployed in agricultural and food-service distribution where incidental material contact occurs. Stakeholders must monitor evolving extended producer responsibility frameworks that assign end-of-life collection costs to original packaging manufacturers across multiple jurisdictions.
Market Dynamics
E-commerce fulfillment automation is compressing packaging cycle times and forcing adhesive bubble wrap specifications toward machine-applied formats that eliminate secondary taping operations. This structural shift reconfigures procurement relationships between converters and third-party logistics operators.
Growth Catalysts
- REACH Chemicals Framework:Europe's phased restrictions on conventional plasticizers are accelerating converter investment in bio-based adhesive formulations that qualify for premium tender participation.
- Semiconductor Channel Requirements:Anti-static bubble wrap specifications are tightening across electronics fulfillment as component warranties increasingly exclude electrostatic discharge damage.
- Germany's Automotive Corridor:Specification-grade protective materials demand from Stuttgart-to-Munich parts exporters is pulling technical-grade capacity toward puncture-resistant laminated formats.
Market Restraints
- Ethylene Feedstock Volatility:Polyethylene resin input costs swing with naphtha-cracker economics, squeezing converter margins during upstream petrochemical tightness.
- Release Liner Supply Concentration:Silicone-coated paper backing production clusters in Scandinavian pulp-to-paper integrated mills, creating single-source vulnerability for mid-tier converters.
- Competing Paper-Based Formats:Honeycomb board and molded pulp cushions displace polymer bubble wrap in heavy-goods segments where carrier puncture rules have relaxed.
Strategic Opportunities
- India's E-commerce Infrastructure Buildout:Third-party logistics networks in Mumbai and Bangalore corridors remain underpenetrated by automated adhesive-backed cushioning systems.
- Dual Carbon Goals Convergence:China's MEE emissions targets and corporate Scope 3 accounting are creating pull for carbon-footprint-certified adhesive formulations in export packaging.
- Food-Service Distribution Channel:FDA indirect food contact compliance positions adhesive bubble wrap for agricultural cold-chain applications where incidental material contact occurs.
Industry Challenges
- Adhesive Formulation Chemistry Expertise:Shortage of pressure-sensitive coating engineers with REACH and EPA VOC compliance experience delays new product qualification timelines.
- Automation Integration Complexity:Legacy carton-sealing lines require mechanical retrofitting to handle adhesive-backed roll formats, extending pilot-to-production cycles for fulfillment operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adhesive Bubble Wrap Market |
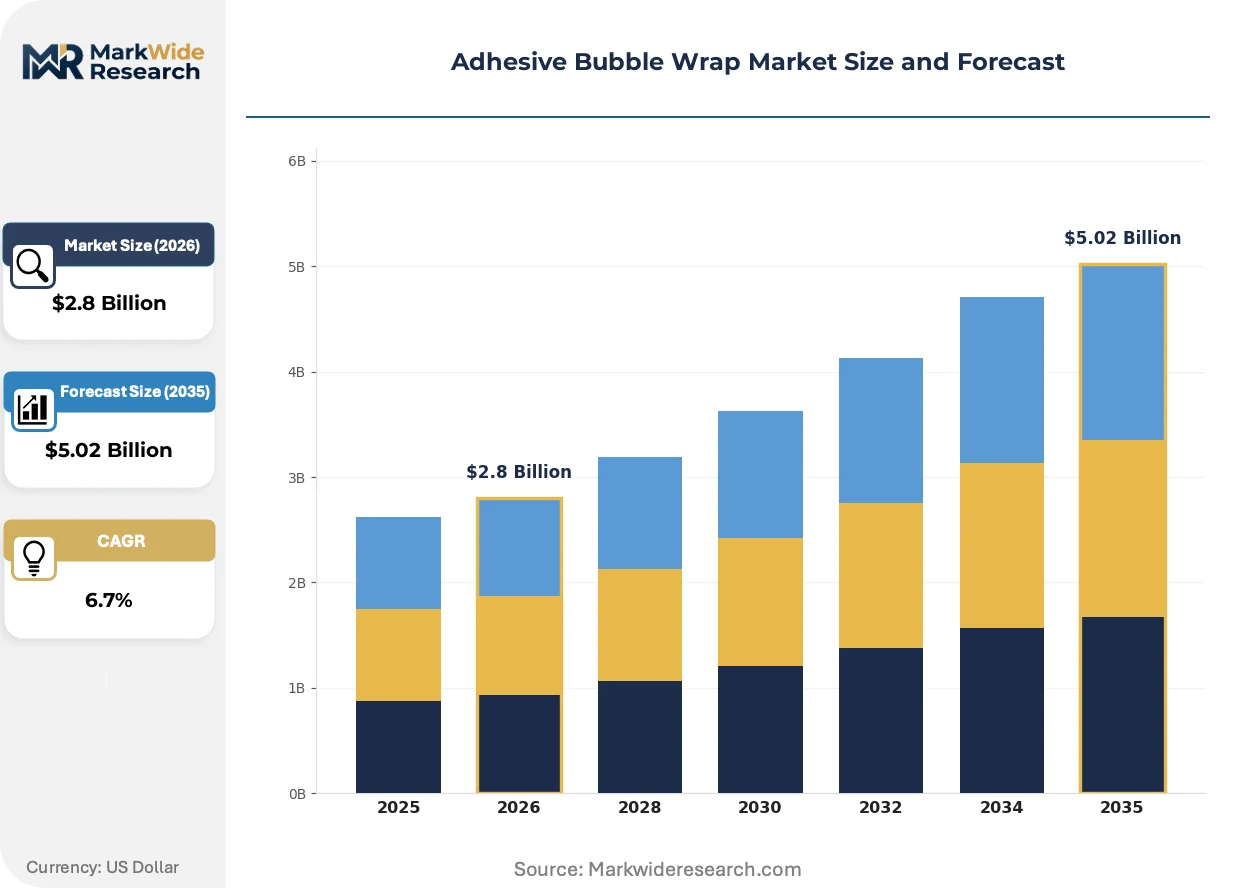
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Bubbles, Large Bubbles, Anti-Static Bubble Wrap, Reinforced Bubble Wrap End User: Retailers, E-Commerce, Manufacturing, Packaging Companies Application: Electronics Packaging, Fragile Goods Shipping, Protective Wrapping, Moving Supplies Distribution Channel: Online Retail, Wholesale Distributors, Direct Sales, Specialty Stores |
| Companies Covered | Sealed Air Corporation, Pregis LLC, Smurfit Kappa Group, Storopack Hans Reichenecker GmbH, Polyair Inter Pack Inc., Automated Packaging Systems, Jiffy Packaging Co., Barton Jones Packaging Ltd, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adhesive Bubble Wrap Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are splitting adhesive bubble wrap development along performance-versus-sustainability axes. Converter R&D budgets are reallocating toward bio-based formulations that maintain auto-apply machine compatibility.
High-tack acrylic adhesive chemistry is bifurcating the specification landscape. Electronics fulfillment centers in Taiwan and South Korea are specifying these grades for auto-applied seals that eliminate tape redundancy entirely. This technology is compressing demand for conventional synthetic-rubber formulations in premium segments while economy tiers retain older chemistry.
EPA volatile organic compound emission guidelines are reshaping domestic manufacturing processes. Adhesive coating operations in Ohio and Texas corridors are installing solvent-recovery systems to maintain formulation flexibility. Consumer electronics channels with California Air Resources Board exposure are most affected, pushing suppliers toward waterborne coating alternatives.
Buyer consolidation among third-party logistics operators is compressing supplier qualification cycles. Regional fulfillment networks are centralizing packaging procurement through national framework agreements that specify performance metrics over brand loyalty. This pattern is most visible in Germany's Ruhr logistics cluster, where DHL and DB Schenker hubs are standardizing on interoperable roll formats.
Adhesive Bubble Wrap Market Segmentation
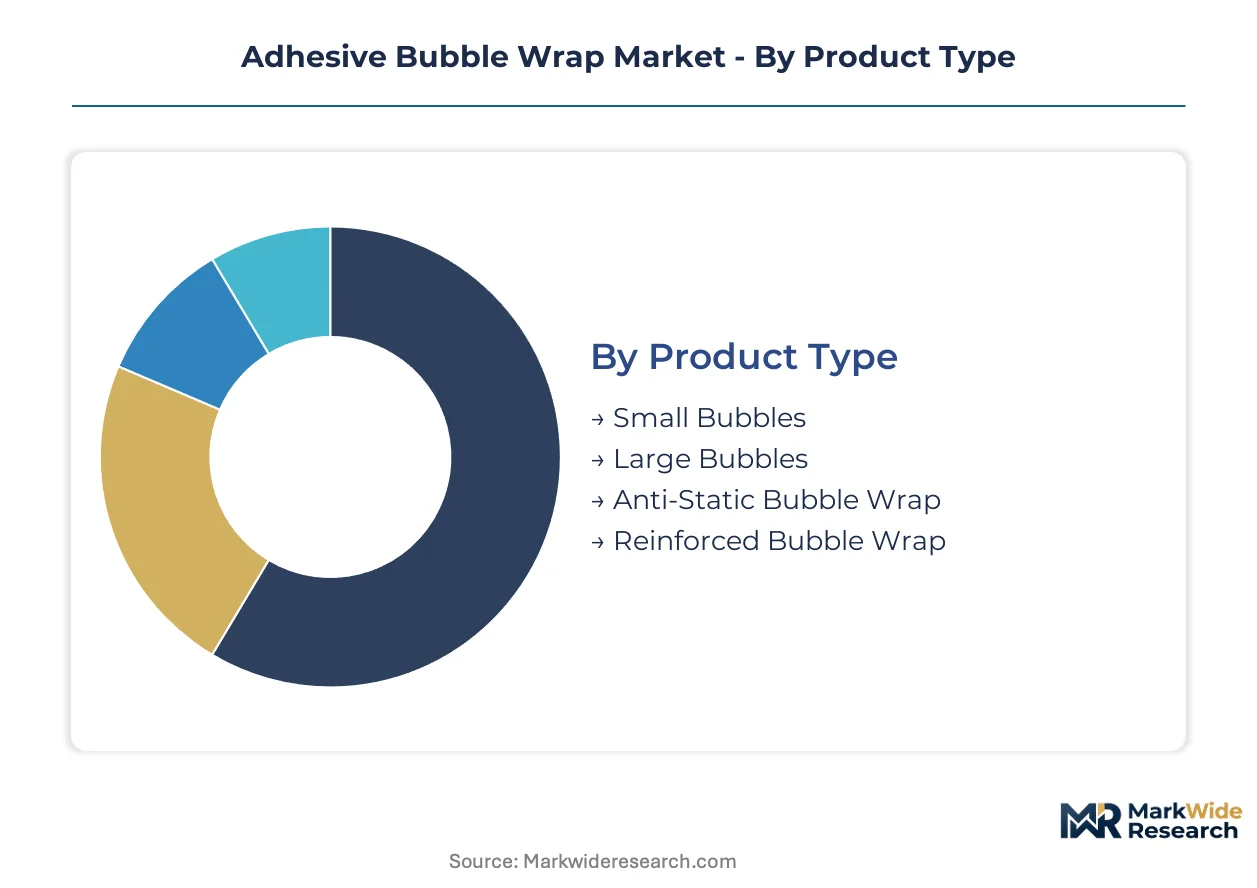
Segmentation in adhesive bubble wrap reveals how specification requirements diverge between automated fulfillment environments and manual packing operations. Product format, end-use channel, and distribution pathway each impose distinct performance thresholds that reshape converter capacity allocation.
Product Type:
Domestic consumption of standard bubble formats dominates North American and European volume, while anti-static and reinforced grades flow disproportionately toward export-oriented electronics and automotive corridors in Asia-Pacific.
- Small Bubbles:Extruded hemispheres measuring 3/16-inch diameter provide surface conformability for flat-screen displays and consumer electronics. E-commerce fulfillment centers in Germany's Ruhr logistics cluster specify these grades for auto-applied cushioning on high-velocity packing lines where tape elimination drives throughput.
- Anti-Static Bubble Wrap:Carbon-loaded polyethylene formulation dissipates electrostatic discharge risks during semiconductor transit. Taiwan and South Korea electronics exporters require REACH-compliant pink-tinted grades for component warranty protection, pulling technical capacity toward carbon-black masterbatch compounding expertise.
- Large Bubbles:1/2-inch hemispheres deliver volumetric cushioning for furniture and appliance segments where puncture resistance matters less than compression recovery.
- Reinforced Bubble Wrap:Laminated scrim layers between bubble plies serve heavy-goods industrial shipments where carrier acceptance rules mandate puncture resistance certification.
Small bubbles command the established base. The steepest expansion runs through anti-static formulations.
End User:
Cost-tier differentiation separates specification-grade procurement by multinational manufacturers from price-sensitive spot buying by regional packaging intermediaries.
- E-Commerce:Third-party logistics operators in Mumbai and Bangalore corridors drive automated adhesive-backed cushioning adoption. Machine-applied roll formats eliminate secondary taping operations, compressing packaging cycle times in fulfillment automation buildouts.
- Manufacturing:Automotive parts exporters along Germany's Stuttgart-to-Munich corridor require puncture-resistant laminated formats with documented performance specifications for carrier liability coverage.
- Retailers:Brick-and-mortar chains with captive distribution networks favor manual-dispensing formats with release-liner backing for store-level packing operations.
- Packaging Companies:Independent converters serving fragmented local markets concentrate procurement on standard synthetic-rubber adhesive grades without premium auto-apply compatibility.
Manufacturing anchors margin-rich specification demand. E-commerce channels are gaining share fastest.
Application:
Volume concentration tracks electronics fulfillment automation density, while protective wrapping for moving supplies remains geographically dispersed and price-elastic.
- Electronics Packaging:Anti-static specifications with surface resistivity between 10^9 and 10^11 ohms per square protect semiconductor components from electrostatic discharge damage. Consumer electronics channels with California Air Resources Board exposure push suppliers toward waterborne coating alternatives.
- Fragile Goods Shipping:Artisanal and specialty retail segments in France and Italy require hand-tearable formats with aesthetic presentation for unboxing experience differentiation.
- Protective Wrapping:General industrial applications favor economy-grade large-bubble formats without adhesive coating for bulk cushioning where secondary securing is acceptable.
- Moving Supplies:Consumer rental and self-storage markets in US Sun Belt states drive seasonal demand spikes for perforated roll formats in retail-ready packaging.
Electronics packaging leads technology development investment. Fragile goods shipping climbs fastest on premium unboxing trends.
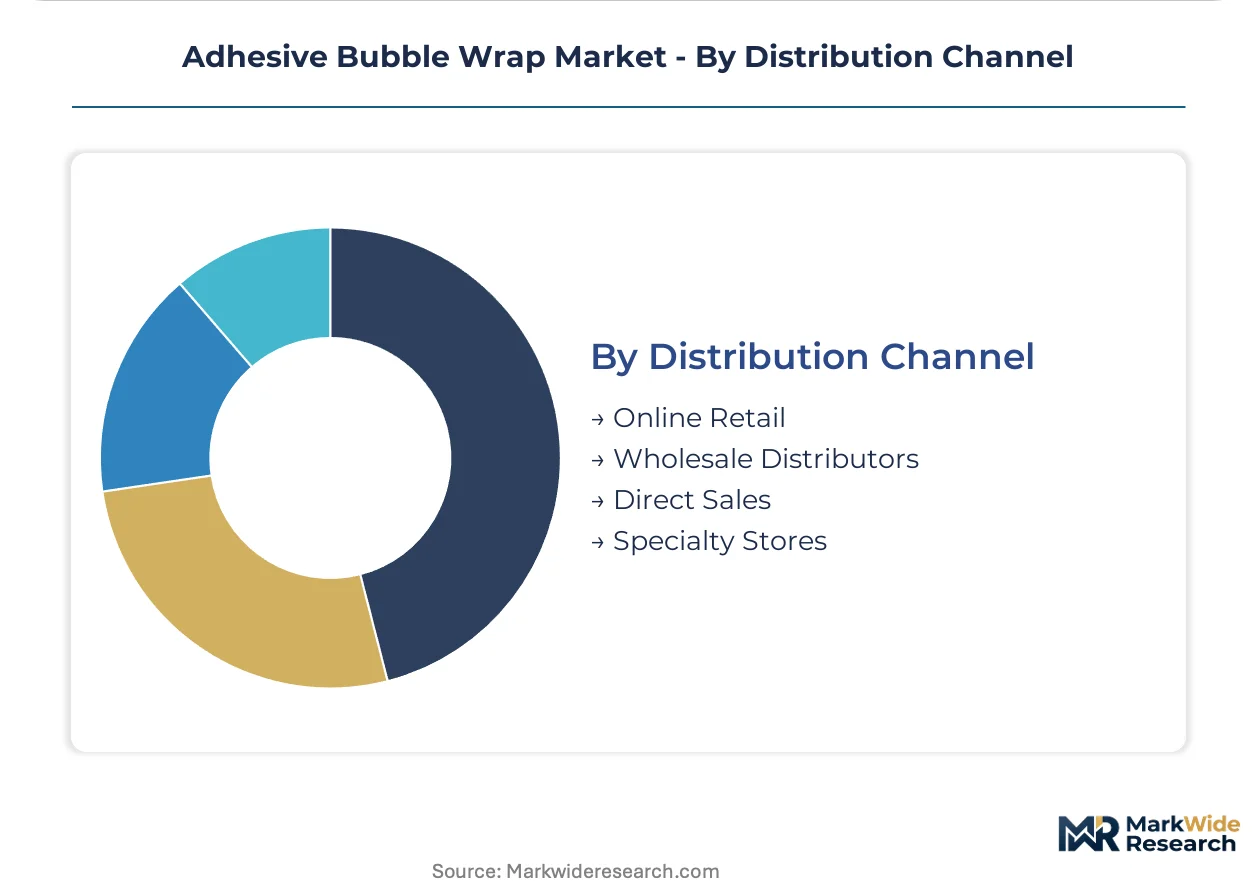
Distribution Channel:
Supply concentration in wholesale distributor networks creates margin pressure, while direct sales relationships with national fulfillment operators sustain premium positioning.
- Wholesale Distributors:Regional paper and packaging merchants in Ohio and Texas corridors aggregate demand from mid-tier converters, consolidating procurement volume for standard adhesive formulations.
- Direct Sales:National framework agreements with DHL and DB Schenker hubs in Germany standardize on interoperable roll formats, compressing supplier qualification cycles through performance-metric specifications.
- Online Retail:Amazon Business and Alibaba procurement platforms expose price transparency for commoditized small-bubble grades, accelerating spot-market purchasing behavior.
- Specialty Stores:Local packaging supply retailers serve emergency replenishment needs for small commercial accounts with limited inventory carrying capacity.
Wholesale distributors command the established base. Direct sales channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's emerging e-commerce corridors exhibit acute price sensitivity, while German automotive exporters absorb premium pricing for specification-grade materials without volume elasticity. This demand bifurcation shapes regional capacity allocation and converter investment priorities.
United States
Third-party logistics operators in Ohio and Texas corridors drive automated adhesive-backed cushioning procurement for high-velocity fulfillment lines. EPA volatile organic compound guidelines pressure coating operations toward solvent-recovery system investments. Consumer electronics channels with California Air Resources Board exposure accelerate waterborne adhesive qualification timelines.
Germany
Automotive parts exporters along the Stuttgart-to-Munich corridor require puncture-resistant laminated formats with documented carrier liability specifications. REACH chemicals framework restrictions on conventional plasticizers accelerate converter migration toward bio-based adhesive formulations. The Ruhr logistics cluster hosts DHL and DB Schenker hubs standardizing on interoperable roll formats for national framework agreements.
China
Dual carbon goals under MEE emissions targets and corporate Scope 3 accounting create demand pull for carbon-footprint-certified adhesive formulations in export packaging. Electronics fulfillment centers in Yangtze River Delta and Pearl River Delta regions specify high-tack acrylic grades for auto-applied seals. Silicone-coated paper backing supply concentrates in Scandinavian integrated mills, creating import dependency for mid-tier converters.
India
Third-party logistics networks in Mumbai and Bangalore corridors remain underpenetrated by automated adhesive-backed cushioning systems, presenting greenfield automation opportunities. BIS standards for packaging materials shape domestic procurement specifications. Regional fulfillment operators prioritize economy-grade synthetic-rubber formulations over premium acrylic chemistry due to capital constraints.
South Korea
Electronics exporters in Seoul Capital Area and Busan-Ulsan corridors specify REACH-compliant anti-static grades for semiconductor component warranty protection. MFDS regulatory frameworks for indirect food contact applications open agricultural cold-chain channels. Carbon-black masterbatch compounding expertise concentrates around Daegu-Gyeongbuk industrial zones serving Taiwan and South Korea electronics channels.
Adhesive Bubble Wrap Market Vendor Landscape
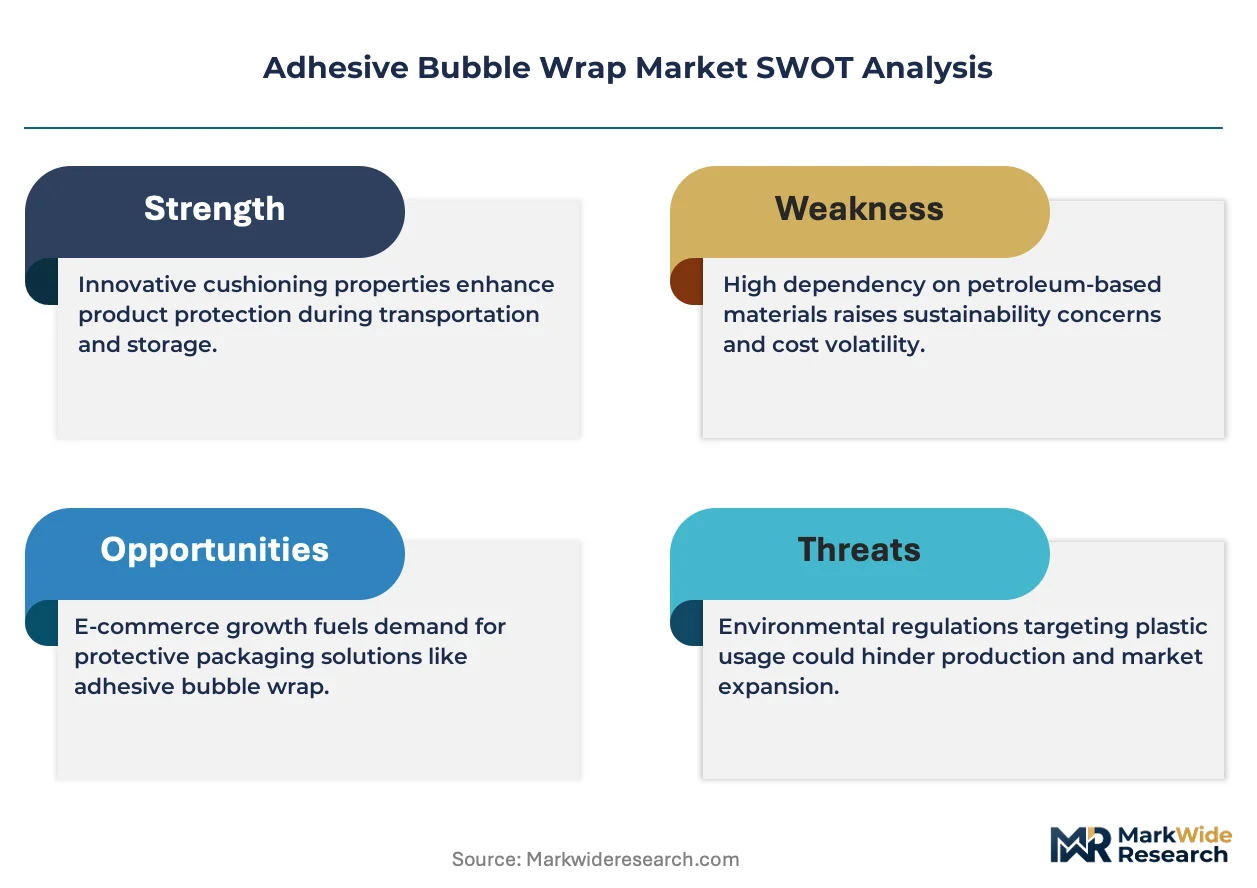
Technology leadership and cost leadership are held by different player archetypes across the adhesive bubble wrap market. The vendor base organizes around three strategic groupings: integrated packaging conglomerates with automation ecosystems, regional blown-film specialists with captive resin processing, and niche converters serving specification-grade industrial segments. Dominant competitive moves include capacity expansion in bio-based adhesive formulations and strategic partnerships with third-party logistics operators for national framework agreement positioning.
Within the integrated packaging tier, Sealed Air Corporation and Pregis LLC exemplify archetypes combining blown-film manufacturing scale with automation ecosystem integration. Smurfit Kappa Group occupies a hybrid position bridging paper-based and polymer protective formats. These three entities anchor competitive dynamics around specification-grade procurement relationships with multinational fulfillment operators and automotive exporters.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis LLC |
| Smurfit Kappa Group |
| Storopack Hans Reichenecker GmbH |
| Polyair Inter Pack Inc. |
| Automated Packaging Systems |
| Jiffy Packaging Co. |
| Barton Jones Packaging Ltd |
| Berry Global Inc. |
| Others |
Supply Flow & Price Mechanics
Blown-film capacity utilization above 85 percent in Germany's industrial packaging corridor anchors pricing power for specification-grade adhesive bubble wrap, compressing margin recovery for mid-tier converters serving spot-market buyers. REACH chemicals framework compliance costs feed directly into premium tier price floors, while ethylene feedstock volatility propagates unevenly across synthetic-rubber and acrylic adhesive formulations.
Pricing Analysis
REACH chemicals framework dictates the pricing tier structure across European procurement specifications, separating bio-based compliant formulations from conventional plasticizer grades. Price differentiation rests on certification tier and volume scale, with automotive exporters in Germany's Stuttgart-to-Munich corridor absorbing premium positioning for puncture-resistant laminated formats. Cost compression in economy-grade synthetic-rubber tiers is intensifying because of ethylene feedstock volatility and release liner supply bottlenecks. Third-party logistics operators in India's Mumbai corridor exhibit acute price sensitivity, while semiconductor channels in Taiwan and South Korea prioritize performance over unit cost.
Supply Chain Analysis
China and Germany anchor blown-film extrusion capacity for polyethylene bubble substrates, while Scandinavian integrated mills concentrate silicone-coated paper release liner production. Raw material dependencies draw from naphtha-cracker ethylene, carbon-black masterbatch for anti-static grades, and acrylic resin for high-tack adhesive formulations. Single-source vulnerability in release liner supply creates procurement risk for mid-tier converters lacking backward integration into paper backing. Distribution runs through wholesale distributor networks in Ohio and Texas corridors, with direct sales relationships gaining share among national fulfillment operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through third-party logistics network consolidation, with DHL and DB Schenker hubs in Germany's Ruhr cluster standardizing procurement through national framework agreements that compress supplier qualification cycles.
For Market Incumbents: Shield specification-grade positioning by deepening captive supply of REACH-compliant bio-based adhesive formulations and securing national framework agreements with consolidating third-party logistics operators. Incumbents must retrofit legacy coating lines with solvent-recovery systems to defend margin position against EPA volatile organic compound enforcement in Ohio and Texas corridors.
For New Entrants and Emerging Players: Automation integration services for legacy carton-sealing lines represent a service-layer gap where incumbents under-serve mid-tier fulfillment operators. New entrants should target India's Mumbai and Bangalore corridors with economy-grade synthetic-rubber formulations paired with mechanical retrofitting expertise, using pilot-to-production cycle compression as the go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with national framework agreements and captive blown-film capacity. Long-term viability across the analysis window favors acquisition targets with integrated adhesive coating operations and bio-based formulation pipelines. The signal to watch is framework agreement renewal timing among Germany's automotive parts exporters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Release Liner Production | Scandinavian mill supply concentration creates vulnerability for mid-tier converters serving spot markets. |
| Bio-Based Adhesive Formulation Certification | REACH chemicals framework compliance unlocks premium tender participation in Germany's automotive corridor. |
| Automation Ecosystem Partnership | Sealed Air Corporation's Instapak integration demonstrates value capture in electronics fulfillment channels. |
| Regional Capacity Expansion | India's underpenetrated Mumbai and Bangalore corridors offer greenfield automation deployment opportunities. |
| Anti-Static Grade Technical Investment | Taiwan and South Korea semiconductor channels require carbon-black masterbatch compounding expertise for warranty protection. |
Methodological Framework
Initial hypotheses were tested against primary input from blown-film plant managers, procurement leads at third-party logistics operators, distribution channel partners in Ohio and Texas corridors, and technical R&D directors specializing in pressure-sensitive coatings, then refined against customs and trade data, SEC filings from packaging conglomerates, EPA emission disclosure records, and REACH registration databases. Bottom-up segment sizing and top-down macroeconomic anchoring were cross-validated across the modeling period.
Variance decomposition across bubble diameter tiers, adhesive chemistry types, end-use automation levels, and regional regulatory clusters shaped the analytical framework. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions, with ethylene feedstock cost curves and e-commerce fulfillment automation penetration rates serving as industry-specific forecast inputs throughout the projection horizon.
Material uncertainties — ethylene cracker economics, REACH chemical restriction phase-ins, and third-party logistics buyer consolidation velocity — sit outside the modeled envelope. Forecasts reflect assumptions about bio-based formulation cost parity timelines and automation retrofit adoption curves. Recalibration cycles align with material shifts in regulatory enforcement intensity and fulfillment operator capital expenditure announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Static Shielding Bags Market
Protective Packaging
Inflatable Packaging Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
High Pressure Protective Packaging Film Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Secondary Containment Trays Market
Protective Packaging
Asia-Pacific Protective Packaging Market
Protective Packaging
Packaging and Protective Packaging Market
Protective Packaging
Thermal Insulated Bubble Wrap Market
Protective Packaging
Insulated Shippers Market
Protective Packaging
Insulated Shipping Boxes Market
Protective Packaging
Thermal Insulated Mailers Market
Protective Packaging
Global Packaging Inserts and Cushions Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
Paper Cushion Systems Market
Protective Packaging
Insulated Styrofoam Shipping Boxes Market