
 Tamper Proof Packaging Market | 2026-2036
Tamper Proof Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Tamper Proof Packaging Market Analytics
Biodegradable polymer films is realigning cost structures across the tamper proof packaging value chain as converters absorb higher resin prices to meet sustainability targets. Amcor plc leverages its global manufacturing footprint to sustain multi-material production lines at scale. Berry Global Inc. anchors North American supply through vertical control over blown film extrusion. Sealed Air Corporation differentiates via active and intelligent packaging integration with tamper-evident layers.
Tamper proof packaging denotes closure systems, seals, labels, or wraps engineered to reveal visible evidence of unauthorized opening through fracture patterns, color change, or adhesive destruction. Specifications include break-strength thresholds, adhesive shear resistance, and compatibility with autoclave or gamma sterilization cycles for pharmaceutical and food sterilization requirements. Plastic material type dominates unit volume due to thermoformability and cost efficiency in high-speed filling operations. Labels and seals capture expanding share in pharmaceutical serialization where track-and-trace compliance demands machine-readable tamper evidence. Food and beverage application leads absolute consumption, though electronics application posts accelerated growth from anti-counterfeit demands in semiconductor logistics.
The FDA enforces tamper-evident requirements under 21 CFR 211 for over-the-counter and prescription drug packaging, directly mandating breakable cap bands or sealed blister formats. The EPA regulates volatile organic compound emissions from adhesive and coating processes used in seal and label manufacturing, raising compliance capital requirements for domestic converters. ISO 21976 provides international test protocols for child-resistant and tamper-evident packaging performance validation. Stakeholders must weigh material substitution timelines against regulatory grandfathering provisions as biodegradability mandates tighten across multiple jurisdictions.
Market Dynamics
Serialization mandates under the FDA Drug Supply Chain Security Act are forcing pharmaceutical manufacturers to retrofit entire packaging lines with track-and-trace infrastructure, converting tamper-evident seals from passive security features into active data-capture nodes.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Mandates unit-level traceability for prescription drugs, requiring tamper-evident layers with integrated serialization codes by 2023 enforcement deadlines.
- Biodegradable polymer films:European healthcare converters are accelerating material transitions to meet EU Green Deal packaging waste reduction targets ahead of 2030 milestones.
- Germany:The KBA enforces pharmaceutical traceability standards across Bavaria and North Rhine-Westphalia, creating concentrated demand for certified tamper-evident systems.
Market Restraints
- Resin price volatility:Biodegradable polymer feedstocks command 40-60% premiums over conventional multilayer plastics, compressing converter margins.
- Adhesive supply concentration:Specialty pressure-sensitive adhesive production clusters in Germany and Japan, exposing packaging firms to single-source risk.
- Gamma sterilization compatibility:Many biodegradable films degrade under radiation doses required for pharmaceutical sterile barrier validation.
Strategic Opportunities
- India:CDSCO serialization requirements for exported pharmaceuticals create retrofit demand for track-and-trace tamper-evident labels.
- Electronics logistics:Semiconductor anti-counterfeit protocols are expanding tamper-evident adoption beyond traditional pharmaceutical and food verticals.
- Intelligent packaging convergence:Integration of NFC and RFID with tamper-evident layers enables real-time breach detection in cold-chain pharmaceutical distribution.
Industry Challenges
- Serialization equipment retrofit:Pharmaceutical packagers face 18-24 month validation timelines to integrate track-and-trace hardware with existing filling lines.
- Multi-material recycling:Complex tamper-evident constructions combining films, adhesives, and printed electronics complicate circular economy compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tamper Proof Packaging Market |
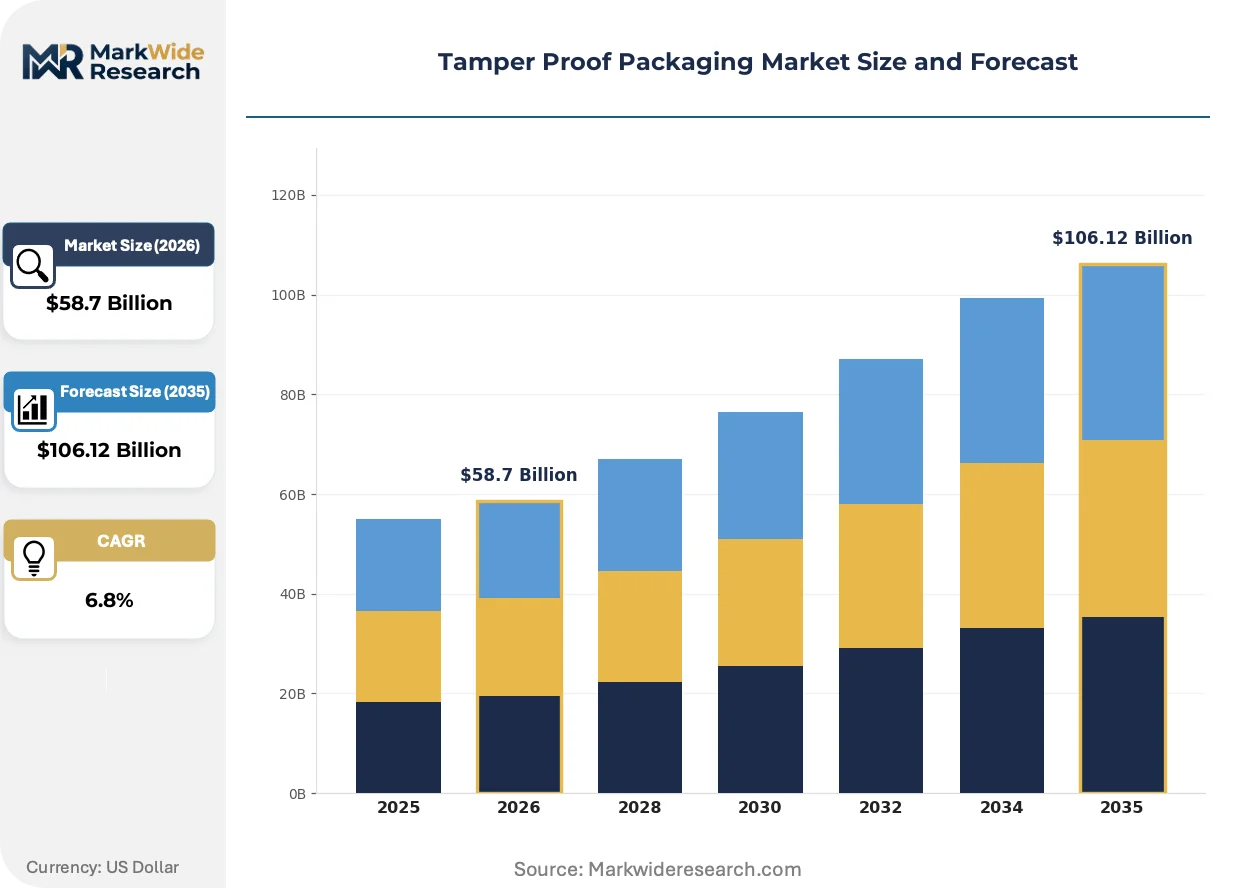
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seals, Labels, Caps, Wraps Material Type: Plastic, Glass, Metal, Paper Application: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics End User: Manufacturers, Distributors, Retailers, Consumers |
| Companies Covered | Amcor plc, Berry Global Inc., Sealed Air Corporation, Coveris Holdings, CCL Industries, Avery Dennison, ProAmpac, Sonoco Products Company, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tamper Proof Packaging Market Evolving Landscape
Active and intelligent packaging integration is converting tamper-evident systems from passive visual indicators into real-time monitoring infrastructure, with sensor-enabled layers now capturing temperature, shock, and breach events throughout distribution.
Biodegradable polymer films is rewriting material specifications across European healthcare packaging. Thermoplastic starch and polylactic acid formulations now achieve break-strength thresholds comparable to conventional multilayer plastics. German and Swiss pharmaceutical contract manufacturers are qualifying these films for blister and pouch formats. The technology is rewriting supplier relationships as resin producers bypass traditional converters to offer direct formulation services.
REACH restrictions on persistent organic pollutants in adhesives are eliminating solvent-based chemistries from seal manufacturing. The European Chemicals Agency enforcement is accelerating water-based and UV-cured adhesive adoption. Pharmaceutical label converters in the Netherlands and Belgium are absorbing capital costs for coating line retrofits to maintain CE-marked product access.
Consolidated buying by national pharmaceutical distributors is compressing supplier negotiation cycles from annual to quarterly frameworks. Procurement teams at major European pharmacy chains now bundle tamper-evident label contracts with serialization software subscriptions. This concentration is most visible in Germany, where three wholesale distributors control 70% of pharmaceutical logistics infrastructure and demand integrated security-printing services.
Tamper Proof Packaging Market Segmentation
Tamper proof packaging segmentation reveals how specification requirements diverge across sterilization protocols, serialization mandates, and sustainability targets. Material choices and product formats align with end-use validation standards rather than interchangeable commodity selection.
Product Type:
Thermoformability, break-strength thresholds, and machine-readability specifications distinguish closure architectures across high-speed filling operations.
- Seals:Breakable cap bands and membrane formats engineered for adhesive shear resistance under autoclave cycles. Pharmaceutical blister lines in Germany and North Rhine-Westphalia concentrate demand for gamma-sterilizable seal configurations under KBA traceability enforcement.
- Labels:Pressure-sensitive constructions with integrated serialization codes serving as active data-capture nodes under FDA Drug Supply Chain Security Act mandates. Track-and-trace compliance is converting labels from passive security features into intelligent packaging infrastructure.
- Caps:Child-resistant and tamper-evident dual-function closures validated against ISO 21976 protocols for prescription drug containment.
- Wraps:Shrink and stretch formats revealing fracture patterns upon unauthorized opening for palletized pharmaceutical distribution.
Labels lead on scale; seals lead on momentum.
Material Type:
Cost tier positioning and sterilization compatibility govern resin selection across converter portfolios.
- Plastic:Thermoplastic starch and polylactic acid formulations achieving break-strength parity with conventional multilayer films. European healthcare converters absorb 40-60% resin premiums to meet EU Green Deal packaging waste targets ahead of 2030 milestones.
- Glass:Borosilicate and soda-lime formats for parenteral drug containment requiring visible contamination detection. Swissmedic and EMA validation protocols sustain premium positioning despite weight and fragility constraints.
- Metal:Aluminum induction seals providing hermetic barrier properties for moisture-sensitive pharmaceutical formulations.
- Paper:Fiber-based constructions gaining traction in food service disposables under biodegradability mandates; limited penetration in sterile barrier applications due to moisture vulnerability.
Plastic dominates volume throughput; glass commands margin premiums.
Application:
End-use regulatory intensity and counterfeiting exposure determine tamper-evident feature complexity.
- Food & Beverage:Break-strength bands and shrink wraps for jarred and bottled formats. FDA 21 CFR 110 compliance requirements sustain baseline adoption across high-volume filling operations.
- Pharmaceuticals:Unit-level serialization with tamper-evident layers mandated under FDA Drug Supply Chain Security Act and EMA Falsified Medicines Directive. CDSCO requirements for Indian pharmaceutical exports extend retrofit demand to track-and-trace label integration.
- Cosmetics:Premium positioning through visible seal destruction and authentication holograms; lower regulatory pressure permits design flexibility over sterilization validation.
- Electronics:Anti-counterfeit protocols for semiconductor logistics accelerating adoption beyond traditional verticals. NFC-enabled tamper-evident layers enable real-time breach detection in high-value component distribution.
Food & Beverage anchors absolute consumption; Electronics climbs fastest on security protocol expansion.
End User:
Procurement scale and technical specification authority concentrate across supply chain tiers.
- Manufacturers:Pharmaceutical packagers face 18-24 month validation timelines to integrate track-and-trace hardware with existing filling lines. Serialization equipment retrofits convert capital expenditure decisions into multi-year vendor relationships.
- Distributors:German wholesale distributors controlling 70% of pharmaceutical logistics infrastructure bundle tamper-evident label contracts with serialization software subscriptions.
- Retailers:Pharmacy chains consolidating buying cycles from annual to quarterly frameworks; procurement teams demand integrated security-printing services.
- Consumers:Visible tamper evidence as purchase decision factor in over-the-counter segments; limited direct specification authority.
Manufacturers drive specification standards; distributors concentrate contract leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria and North Rhine-Westphalia concentrate European pharmaceutical packaging demand under Germany's federal traceability enforcement. The FDA Drug Supply Chain Security Act drives North American retrofit cycles. CDSCO mandates in India and China's NMPA serialization rules extend compliance requirements across export-oriented manufacturing hubs.
United States
Pharmaceutical contract manufacturers in New Jersey and Puerto Rico retrofit filling lines with track-and-trace hardware to meet FDA Drug Supply Chain Security Act unit-level serialization deadlines. The EPA regulates volatile organic compound emissions from adhesive coating processes, raising capital requirements for domestic seal converters. Boston-area biotech clusters demand gamma-sterilizable tamper-evident formats for parenteral drug containment.
Germany
The KBA enforces pharmaceutical traceability standards across Bavaria and North Rhine-Westphalia, creating concentrated demand for certified tamper-evident systems. REACH restrictions on persistent organic pollutants eliminate solvent-based adhesive chemistries from seal manufacturing. Stuttgart-based pharmaceutical contract manufacturers qualify biodegradable polymer films for blister formats ahead of EU Green Deal packaging waste targets.
India
CDSCO serialization requirements for exported pharmaceuticals create retrofit demand for track-and-trace tamper-evident labels among Mumbai and Ahmedabad packaging converters. The country's national pharmaceutical regulator aligns export documentation with EU Falsified Medicines Directive standards. Hyderabad's vaccine manufacturing corridor drives sterile barrier validation requirements for induction seal configurations.
China
NMPA serialization mandates for domestic pharmaceutical distribution expand machine-readable tamper-evident label adoption across Shanghai and Jiangsu province filling operations. The country's national medical products administration enforces track-and-trace compliance for imported drug registration. Suzhou's medical device packaging cluster integrates NFC-enabled tamper-evident layers for high-value component distribution.
Switzerland
Swissmedic validation protocols sustain premium positioning for glass and polymer tamper-evident formats in Basel's pharmaceutical headquarters economy. The national pharmaceutical regulator maintains stricter sterile barrier standards than EMA baseline requirements. Zurich-area precision converters specialize in dual-function child-resistant and tamper-evident closures for oncology drug containment.
Tamper Proof Packaging Market Competitive Landscape
Global majors compete with regional champions across material technology and serialization integration capabilities. The vendor base separates into three tiers: integrated multinationals with captive resin supply, mid-scale converters with vertical control over blown film extrusion, and specialized label printers with track-and-trace software partnerships. Dominant competitive moves include capacity expansion in biodegradable polymer formulations and strategic partnerships between packaging converters and serialization software providers.
Within the integrated multinational tier, Amcor plc and Berry Global Inc. exemplify scale-driven positioning through global manufacturing footprints and multi-material production capabilities. Sealed Air Corporation occupies a distinct position at the convergence of active packaging and tamper-evident layer integration. These three companies anchor the premium tier through sustained capital deployment in intelligent packaging infrastructure.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Sealed Air Corporation |
| Coveris Holdings |
| CCL Industries |
| Avery Dennison |
| ProAmpac |
| Sonoco Products Company |
| WestRock Company |
| Others |
Value Network & Pricing Analysis
Quarterly procurement bundling by German pharmaceutical distributors is compressing supplier margins and forcing converters to absorb biodegradable resin premiums or risk contract cancellation. This buyer concentration reshapes upstream sourcing decisions as seal manufacturers seek captive adhesive supply to defend position.
Pricing Analysis
Input-cost pass-through dominates tamper-evident packaging economics, with biodegradable polymer feedstock premiums of 40-60% over conventional multilayer plastics flowing directly to converter quotations. Three-tier pricing structure across premium gamma-sterilizable formats, standard pharmaceutical-grade seals, and economy food-service bands reflects certification tier and sterilization compatibility. Price differentiation hinges on EU Green Deal compliance status and serialization code integration capability. Cost compression in standard tiers is intensifying as Indian and Chinese converters enter European qualification pipelines. Small pharmaceutical contract manufacturers exhibit highest price sensitivity; Swiss oncology drug packagers show lowest.
Supply Chain Analysis
Reverse-logistics flows for pharmaceutical serialization equipment create secondary refurbishment markets in New Jersey and Stuttgart, extending hardware depreciation cycles and delaying new equipment demand. Raw material supply concentrates in Germany, Japan, and China, with specialty pressure-sensitive adhesive production clustering around Düsseldorf and Osaka. Feedstock dependencies span thermoplastic starch from Italian biopolymer plants, polylactic acid from Nebraska fermentation facilities, and induction seal aluminum from Russian smelters. Single-source vulnerability in gamma-sterilizable adhesive chemistry exposes packagers to KBA qualification delays. Distribution runs through three German wholesale distributors controlling 70% of pharmaceutical logistics infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tamper proof packaging market functions as a stable compounder, with regulatory serialization mandates creating recurring retrofit demand that smooths cyclicality.
For Market Incumbents: Cement multi-year vendor relationships with pharmaceutical packagers by financing 18-24 month validation timelines and embedding serialization software subscriptions into hardware contracts. Defend against biodegradable film substitution by acquiring direct formulation capabilities from bypassing resin producers. Prioritize CE-marked product access through water-based adhesive coating line retrofits ahead of REACH enforcement deadlines. For New Entrants and Emerging Players: Begin with electronics logistics applications in Suzhou and Shenzhen, where semiconductor anti-counterfeit protocols expand tamper-evident adoption beyond saturated pharmaceutical verticals. Target NFC-enabled intelligent packaging integration as the most penetrable white space, with real-time breach detection commanding premium positioning. Pursue strategic partnerships with serialization software providers to bypass 18-24 month standalone validation barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale converters possessing vertical control over blown film extrusion and established KBA certification relationships. Five-to-ten year viability rests on EU Green Deal packaging waste target compliance and FDA Drug Supply Chain Security Act enforcement continuity. Monitor CDSCO serialization requirement expansion for Indian pharmaceutical exports as inflection indicator for emerging market retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer Capacity Expansion | European converters absorb resin premiums to maintain CE-marked access under EU Green Deal targets. |
| Serialization Software Integration | Hardware vendors bundle track-and-trace platforms to capture recurring subscription revenue from German distributors. |
| Gamma-Sterilizable Adhesive Backward Integration | Seal manufacturers acquire coating capabilities to eliminate single-source exposure to Düsseldorf and Osaka suppliers. |
| NFC-Enabled Intelligent Packaging Launch | Real-time breach detection penetrates electronics logistics and cold-chain pharmaceutical distribution. |
| Indian Export Qualification Partnership | Converters align with CDSCO requirements to capture Mumbai and Ahmedabad pharmaceutical packaging retrofit demand. |
Research Methodology
Multiple input streams — primary interviews with pharmaceutical packaging executives, regulatory affairs specialists, and blown film extrusion plant managers; secondary validation through FDA Drug Supply Chain Security Act filings, EMA Falsified Medicines Directive submissions, and EU Green Deal packaging waste target documentation; customs and trade data from German KBA enforcement regions — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from pharmaceutical contract manufacturers and serialization equipment vendors to construct analytical framework across material type, product format, sterilization protocol, and regional regulatory cluster dimensions. CAGRs were derived from segmented growth rate reconciliation with industry-specific inputs including resin price elasticity and validation timeline distributions.
Several conditions sit outside the modeled scope, including sudden biodegradable polymer feedstock supply disruptions, accelerated REACH adhesive chemistry bans, and pharmaceutical distributor consolidation beyond current three-player German concentration. Practitioners should monitor CDSCO enforcement intensity, KBA traceability standard revisions, and gamma sterilization protocol modifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Anti-Corrosive Packaging Market
Protective Packaging
Protective Wrapping Paper Market
Protective Packaging
Void Fill Pillows Market
Protective Packaging
Secondary Containment Trays Market
Protective Packaging
Paper Cushion Systems Market
Protective Packaging
Foam Edge Protectors Market
Protective Packaging
Insulated Styrofoam Shipping Boxes Market
Protective Packaging
Molded Fiber Pulp Edge Protectors Market
Protective Packaging
Corrugated Bubble Wrap Market
Protective Packaging
Asia-Pacific Protective Packaging Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
Latin America Protective Packaging Market
Protective Packaging
Foam Protective Packaging Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Thermal Insulated Bubble Wrap Market