
 Insulated Shippers Market | 2026-2036
Insulated Shippers Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Shippers Market Intelligence
IATA CEIV Pharma certification is bifurcating the competitive landscape into qualified and non-qualified suppliers. Sonoco Products Company leverages its Sonoco ThermoSafe acquisition to sustain pharmaceutical-grade container production across North American and European manufacturing nodes. Cold Chain Technologies anchors its position through reusable parcel shipper systems designed for high-value biologics distribution. Pelican BioThermal differentiates via temperature-controlled rental pool services that reduce capital burden for emerging therapy developers.
Insulated shippers are engineered thermal protection systems combining multi-layer insulation, phase-change materials, and vacuum-insulated panels to maintain specified temperature bands during transit. Wall thicknesses typically range from 25 mm to 100 mm depending on payload duration requirements, with polyurethane foam and expanded polystyrene serving as core insulating substrates. The product type dimension shows pallet shippers capturing the highest absolute value as oncology drug bulk distribution scales, while thermal packs grow fastest in last-mile gene therapy delivery where parcel-level protection dominates. Material selection increasingly favors composite constructions that merge foam structural integrity with plastic moisture barriers, displacing single-material cardboard solutions in regulated pharmaceutical lanes.
FDA 21 CFR Part 211 and EU GDP guidelines mandate documented temperature validation for all pharmaceutical distribution packaging, forcing suppliers to invest in thermal chamber testing and qualification protocols. IATA's Temperature Control Regulations and the WHO PQS prequalification scheme further constrain market access to manufacturers with certified quality management systems. Stakeholders must monitor evolving pharmacopeia standards for ultra-low temperature ranges as cryogenic cell therapies commercialize, since current passive shipper portfolios may require fundamental redesign to maintain minus 150 degrees Celsius stability.
Market Dynamics
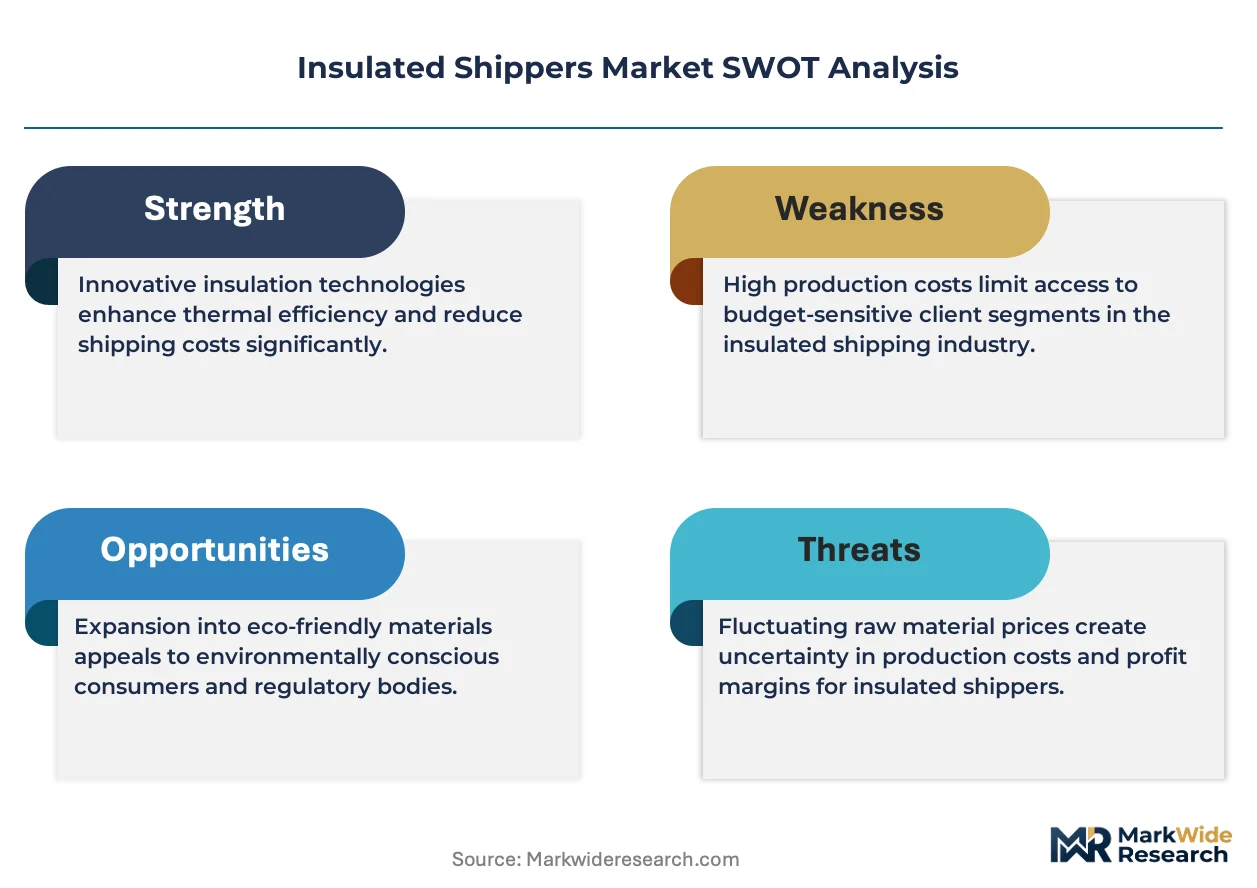
The insulated shippers sector is reconfiguring around ultra-low temperature requirements as cell-and-gene therapies commercialize, forcing manufacturers to abandon legacy passive cooling architectures in favor of cryogenic-compatible vacuum-insulated panel systems.
Growth Catalysts
- mRNA cold chain expansion:Biopharmaceutical manufacturers are scaling temperature-validated distribution networks for nucleic acid therapeutics, creating sustained demand for qualified thermal packaging across clinical and commercial lanes.
- EU MDR validation mandates:The Medical Device Regulation's documentation requirements for temperature-controlled transport are compelling healthcare distributors to upgrade from unqualified cardboard solutions to certified insulated systems.
- Phase-change material advances:Eutectic salt formulations engineered for precise temperature bands are extending passive protection duration without active refrigeration, enabling cost-effective last-mile delivery of high-value biologics.
Market Restraints
- Petrochemical input volatility:Polyurethane foam and expanded polystyrene substrates depend on crude oil derivatives, exposing manufacturers to feedstock price swings that compress margin stability.
- Qualified supplier concentration:IATA CEIV Pharma certification has consolidated validated manufacturing capacity among a limited pool of European and North American facilities, creating bottleneck risk for emerging market access.
- Passive thermal limits:Current multi-layer insulation architectures cannot maintain minus 150 degrees Celsius stability required for cryogenic cell therapies, constraining addressable market scope.
Strategic Opportunities
- Indian biologics manufacturing:CDSCO's accelerated approval pathways for biosimilars are attracting contract development organizations that require temperature-validated export packaging to European and North American markets.
- Rental pool services:Asset-light temperature-controlled container leasing is reducing capital barriers for emerging therapy developers, creating recurring revenue streams distinct from equipment sales.
- WHO PQS prequalification:The World Health Organization's performance standards for vaccine distribution packaging are opening procurement channels for qualified suppliers into national immunization programs across low-income countries.
Industry Challenges
- Thermal engineering talent scarcity:Qualified professionals capable of modeling phase-change kinetics and vacuum panel performance are concentrated among a handful of specialized consultancies, constraining R&D velocity.
- Qualification timeline compression:IATA's Temperature Control Regulations require extensive chamber testing protocols that extend product development cycles, delaying revenue recognition for new shipper designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Shippers Market |
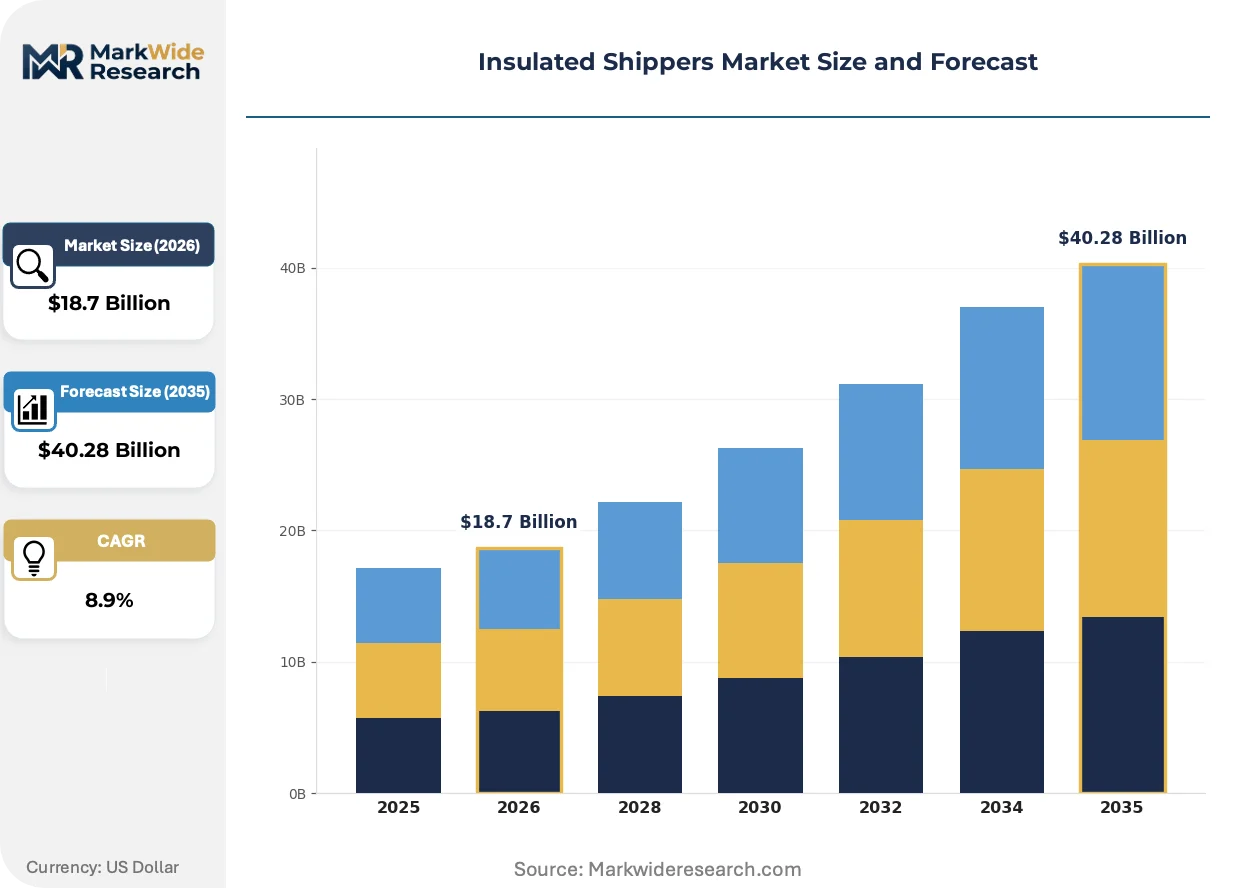
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $40.28 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coolers, Insulated Boxes, Pallet Shippers, Thermal Packs Material: Foam, Plastic, Cardboard, Composite Temperature Control Method: Active, Passive, Refrigerated, Cryogenic End User: Pharmaceuticals, Food & Beverage, Biotechnology, Chemicals |
| Companies Covered | Sonoco Products Company, Cold Chain Technologies, Sealed Air Corporation, Pelican BioThermal, Cryopak, Snyder Industries, Berry Global, Amcor plc, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Shippers Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory digitization are converging to redefine thermal protection performance standards, with passive systems gaining active monitoring capabilities and reusable architectures displacing single-use alternatives.
Vacuum-insulated panels incorporating aerogel composites are supplanting conventional polyurethane foam in premium pharmaceutical lanes. Oncology drug distributors are adopting these systems for 120-hour protection durations. The technology is compressing total cost of ownership for high-value biologics by reducing refrigerant mass and dimensional weight charges.
EU GDP guidelines now mandate electronic temperature logging for all pharmaceutical distribution packaging, eliminating paper-based validation records. Cold chain operators must integrate Bluetooth-enabled data loggers into shipper designs. Parcel-level biologics distribution in Germany and France is experiencing the steepest compliance adaptation curves.
Leasing arrangements for qualified thermal containers are displacing capital purchase models among mid-sized gene therapy developers. Contract manufacturers are consolidating procurement through third-party logistics providers who maintain certified rental pools. This shift is most pronounced in the Boston and San Diego biotech clusters where facility footprints constrain on-site inventory holding.
Insulated Shippers Market Segmentation
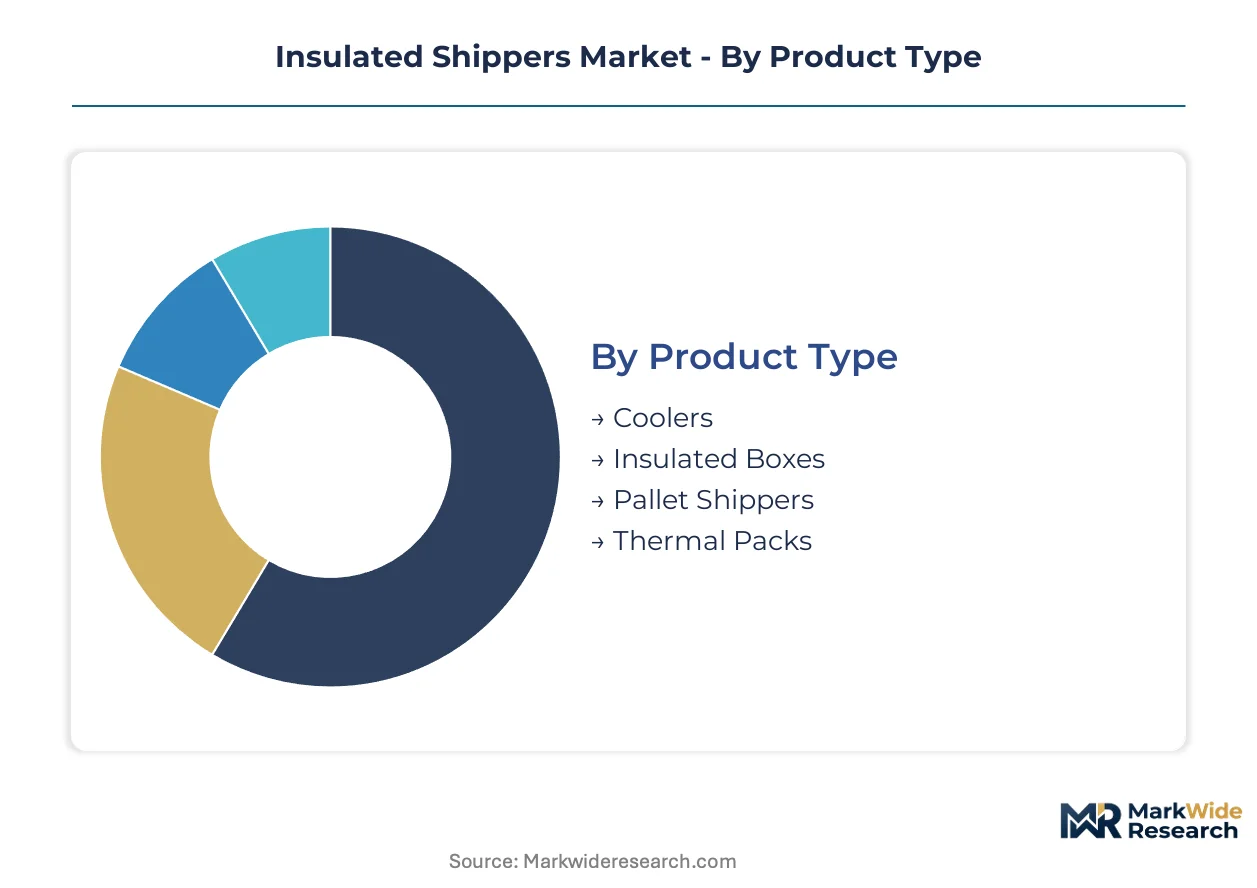
Insulated shipper selection hinges on payload value, duration requirements, and regulatory validation tiers. Pharmaceutical distributors navigate trade-offs between capital expenditure and qualification status, while food and chemical sectors prioritize cost efficiency over certified performance. Understanding substitution pressures across product architectures reveals where commoditization threatens margin stability.
Product Type:
Coolers and insulated boxes face intensifying substitution from reusable rental containers in high-value pharmaceutical lanes, forcing single-use suppliers toward food service and diagnostic kit applications.
- Pallet Shippers:These large-format thermal protection systems integrate vacuum-insulated panels and phase-change materials to maintain temperature bands across 96-120 hour transit windows. Oncology drug bulk distribution concentrates demand around Frankfurt and Munich logistics hubs, where centralized vaccine storage facilities require qualified pallet-scale solutions. EU MDR documentation mandates are compelling distributors to abandon unqualified alternatives.
- Thermal Packs:Parcel-level passive protection systems engineered for last-mile gene therapy delivery employ multi-layer insulation with eutectic salt formulations. Cell-and-gene therapy developers in Boston and San Diego biotech clusters are scaling procurement of these systems for patient-specific treatment distribution. Compact dimensional profiles reduce freight charges while maintaining validated temperature bands.
- Coolers:Rotomolded polyethylene containers with polyurethane foam cores serve food service and diagnostic specimen transport where IATA CEIV Pharma certification is not required.
- Insulated Boxes:Expanded polystyrene or polyurethane constructions dominate e-commerce perishables and meal kit delivery, competing primarily on unit cost against passive alternatives.
Pallet shippers retain volume leadership; thermal packs hold the steepest expansion curve.
Material:
Cost tier stratification separates premium pharmaceutical-grade substrates from commodity packaging inputs, with composite constructions commanding price premiums in regulated lanes.
- Composite:Hybrid constructions merging foam structural integrity with plastic moisture barriers are displacing single-material cardboard in pharmaceutical distribution. These systems combine polyurethane or expanded polystyrene cores with polyethylene film laminates to prevent moisture ingress during extended transit. Germany's pharmaceutical logistics corridors are experiencing the fastest adoption as EU GDP guidelines tighten validation requirements.
- Foam:Polyurethane and expanded polystyrene substrates provide core thermal resistance across passive shipper architectures. Petrochemical input volatility exposes manufacturers to margin compression, though scale economies sustain competitiveness in food and beverage applications.
- Plastic:Rotomolded polyethylene and injection-molded polypropylene shells enable reusable container designs favored by rental pool operators serving gene therapy developers.
- Cardboard:Corrugated fiberboard with foil-faced insulation faces rapid displacement from composite alternatives in regulated pharmaceutical lanes, retreating toward non-validated food and chemical applications.
Foam substrates dominate unit volume; composite materials are climbing the fastest.
Temperature Control Method:
Application requirements dictate method selection, with cryogenic capabilities emerging as the critical differentiator for next-generation cell therapies.
- Passive:Multi-layer insulation with phase-change materials maintains specified temperature bands without active refrigeration, enabling cost-effective distribution of high-value biologics. Eutectic salt formulations engineered for precise temperature bands are extending protection duration while reducing refrigerant mass. Last-mile gene therapy delivery in France and Germany relies heavily on these systems.
- Cryogenic:Vacuum-insulated panel systems with liquid nitrogen or dry ice payloads maintain ultra-low temperatures required for cryogenic cell therapies. Current passive architectures cannot sustain minus 150 degrees Celsius stability, constraining addressable market scope as these therapies commercialize.
- Active:Battery-powered compressor or thermoelectric systems provide precise temperature control for extended durations, deployed primarily in high-value oncology drug distribution.
- Refrigerated:Gel pack and ice-based cooling serves short-duration food and diagnostic applications where precise temperature maintenance is less critical.
Passive systems retain volume leadership; cryogenic methods hold the steepest expansion curve.
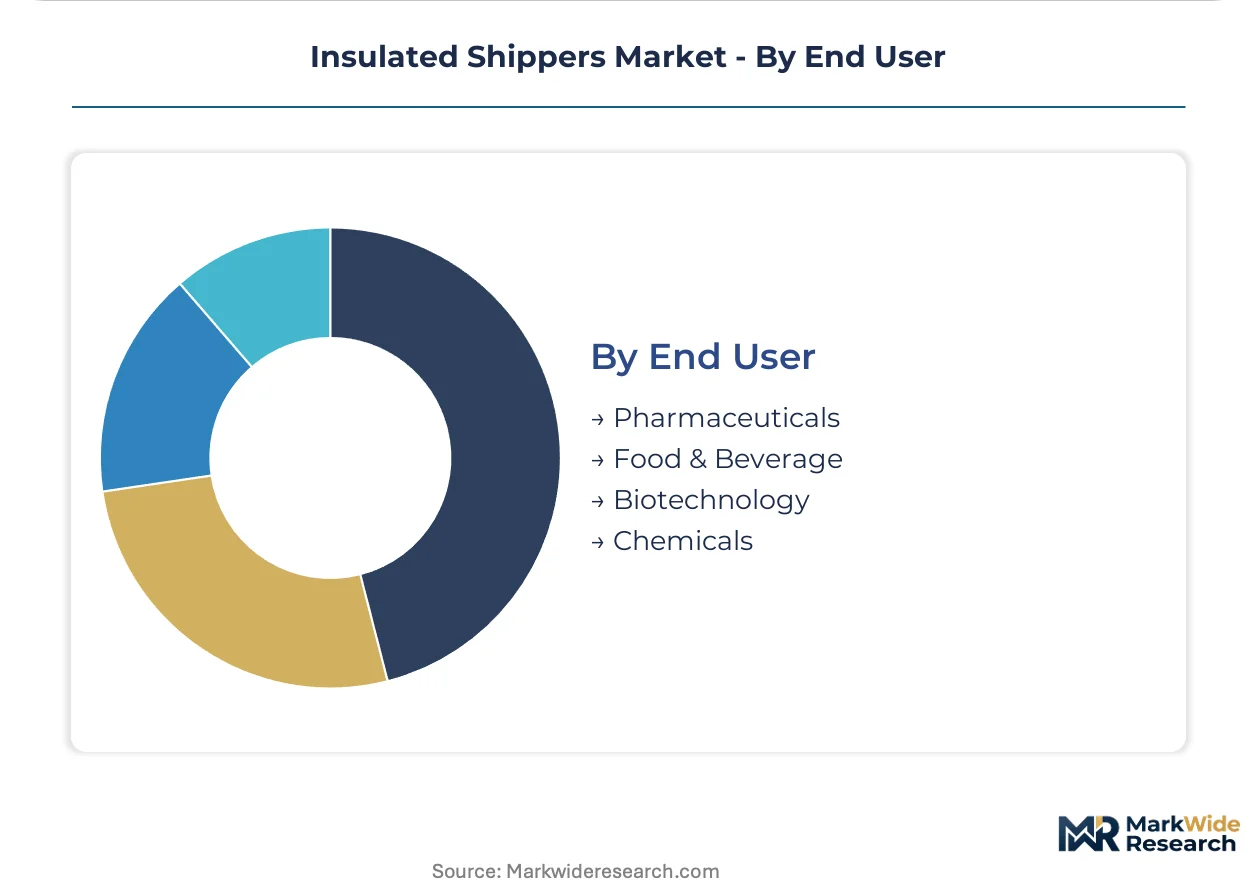
End User:
Customer type segmentation separates validated pharmaceutical procurement from price-sensitive industrial applications, with biotechnology emerging as the fastest-growing demand pool.
- Pharmaceuticals:Temperature-validated distribution networks for nucleic acid therapeutics and biologics require IATA CEIV Pharma-certified packaging with documented thermal qualification. FDA 21 CFR Part 211 and EU GDP guidelines mandate electronic temperature logging, eliminating paper-based validation records. mRNA therapy commercialization is sustaining demand across North American and European manufacturing nodes.
- Biotechnology:Cell-and-gene therapy developers require ultra-low temperature stability for cryogenic preservation of patient-specific treatments. Contract manufacturers are consolidating procurement through third-party logistics providers who maintain certified rental pools, reducing capital barriers for emerging developers.
- Food & Beverage:E-commerce perishables and meal kit delivery prioritize cost efficiency over qualification status, driving procurement toward foam and cardboard constructions.
- Chemicals:Temperature-sensitive reagents and diagnostic materials require moderate thermal protection without pharmaceutical-grade validation, occupying a mid-tier price segment.
Pharmaceuticals retain volume leadership; biotechnology holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical distributors and biotechnology developers concentrate procurement decisions in jurisdictions with stringent cold chain validation requirements. Germany, the United States, India, Japan, and Switzerland anchor regional demand patterns through distinct regulatory frameworks and industrial clustering.
Germany
Centralized vaccine storage facilities and oncology drug distribution hubs cluster around Frankfurt and Munich logistics corridors. EU MDR documentation mandates and GDP guidelines compel healthcare distributors to upgrade from unqualified cardboard solutions to certified insulated systems. Bavaria and Hesse host the densest concentration of qualified thermal packaging procurement in Europe.
United States
mRNA therapy commercialization and cell-and-gene therapy development in Boston and San Diego biotech clusters sustain demand for temperature-validated distribution networks. FDA 21 CFR Part 211 mandates documented temperature validation for all pharmaceutical distribution packaging. The FDA's enforcement posture on electronic temperature logging eliminates paper-based validation records across domestic lanes.
India
CDSCO's accelerated approval pathways for biosimilars attract contract development organizations requiring temperature-validated export packaging to European and North American markets. The national pharmaceutical regulator's harmonization with ICH guidelines facilitates cross-border qualification of thermal packaging systems. Maharashtra and Gujarat host emerging biologics manufacturing capacity with outbound cold chain requirements.
Japan
PMDA's stringent stability testing requirements for biologics distribution create sustained demand for qualified thermal packaging with extended duration capabilities. METI's industrial policy supports domestic manufacturing of advanced phase-change materials. The Kanto region around Tokyo concentrates pharmaceutical logistics procurement decisions for Asia-Pacific distribution.
Switzerland
Swissmedic's regulatory framework for advanced therapy medicinal products demands cryogenic-compatible thermal protection systems for cell therapy distribution. The country's precision logistics infrastructure supports high-value biologics transit between European manufacturing nodes and global markets. Basel and Zurich anchor pharmaceutical distribution procurement with exacting qualification standards.
Insulated Shippers Market Key Industry Players
Player mix skews toward diversified packaging conglomerates with pharmaceutical-grade certification capabilities and specialized cold chain technology providers. Market structure concentrates validated manufacturing capacity among a limited pool of European and North American facilities with IATA CEIV Pharma credentials. Strategic archetypes include integrated packaging conglomerates with multi-material capabilities, dedicated cold chain technology specialists, and rental pool operators offering asset-light service models. Dominant competitive moves encompass M&A activity targeting thermal packaging technology assets and strategic partnerships with third-party logistics providers to secure distribution channel access.
Within the integrated packaging tier, Sonoco Products Company exemplifies the conglomerate archetype through its acquisition-based expansion into temperature-controlled container production. Cold Chain Technologies and Pelican BioThermal occupy positions as dedicated cold chain specialists, with the former representing reusable parcel shipper capabilities and the latter anchoring rental pool service models. These three entities collectively illustrate the strategic segmentation between equipment ownership and asset-light operational models in high-value biologics distribution.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Cold Chain Technologies |
| Sealed Air Corporation |
| Pelican BioThermal |
| Cryopak |
| Snyder Industries |
| Berry Global |
| Amcor plc |
| WestRock Company |
| Others |
Cost & Logistics Intelligence
Ninety-day qualification timelines for IATA CEIV Pharma certification compress inventory turns for European manufacturers while concentrating pricing power among German and North American facilities with pre-certified thermal chamber capacity. This lead-time rigidity feeds directly into contract structures that pass petrochemical volatility through to buyers.
Pricing Analysis
Cost-plus contracts indexed to polyol and isocyanate feedstock indices dominate long-term agreements between pallet shipper manufacturers and oncology distributors. Three-tier pricing structure across premium, standard, and economy levels separates IATA-certified vacuum-insulated panel systems from GDP-compliant foam-core alternatives and unvalidated cardboard solutions. Pricing pressure stems from Indian biologics exporters demanding European-equivalent validation at Asian manufacturing cost bases. Contract manufacturers in Boston and San Diego biotech clusters exhibit lowest price sensitivity due to patient-specific therapy value; food service distributors face acute margin compression.
Supply Chain Analysis
Strait of Malacca transit exposure for vacuum-insulated panel raw materials underwrites supply vulnerability for cryogenic shipper architectures. Manufacturing concentrates in Germany, the United States, and China, with polyurethane foam substrates drawing from Saudi and Korean petrochemical complexes. Phase-change material precursors hinge on Chinese rare earth processing capacity. Single-source vulnerability concentrates in aerogel composite supply. Distribution runs through Frankfurt, Munich, and Boston logistics hubs serving pharmaceutical cold chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among third-party logistics providers who consolidate procurement for mid-sized gene therapy developers, fragmenting direct manufacturer relationships. This consolidation forces suppliers toward rental pool service models.
For Market Incumbents: Consolidate thermal engineering talent through targeted acquisition of specialized consultancies in Germany and Switzerland. Add cryogenic-compatible vacuum-insulated panel capacity in Bavaria before cell-and-gene therapy commercialization accelerates. Defend against emerging Indian composite manufacturers by embedding Bluetooth-enabled data loggers as standard features under EU GDP electronic logging mandates. For New Entrants and Emerging Players: Anchor in WHO PQS prequalification pathways for vaccine distribution packaging across low-income country national immunization programs. Target CDSCO-registered Indian biosimilar exporters requiring temperature-validated European export documentation. Lead with asset-light rental pool positioning to bypass capital barriers that constrain direct equipment sales. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because IATA CEIV Pharma certification creates durable moats around qualified manufacturing capacity. Target acquisition archetypes include specialized cold chain technology providers with existing thermal chamber infrastructure and phase-change material formulation IP. Watch for inflection when cryogenic cell therapy approvals trigger fundamental shipper architecture redesign requirements.| Strategic Initiative | Industry Significance |
|---|---|
| IATA CEIV Pharma Certification Investment | Unlocks procurement access to oncology drug bulk distribution networks in Frankfurt and Munich logistics corridors. |
| Phase-Change Material Formulation Partnership | Secures eutectic salt supply chains for extended-duration gene therapy last-mile delivery applications. |
| Rental Pool Service Launch | Reduces capital barriers for Boston and San Diego biotech cluster contract manufacturers. |
| Bluetooth Data Logger Integration | Enables EU GDP electronic temperature logging compliance for pharmaceutical distribution packaging. |
| Cryogenic Vacuum-Insulated Panel Development | Addresses minus 150 degrees Celsius stability requirements for commercializing cell-and-gene therapies. |
Research Approach
A standing panel of cold chain logistics directors, pharmaceutical procurement managers, thermal packaging engineers, and regulatory affairs specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from IATA Temperature Control Regulations documentation, EU MDR technical files, WHO PQS prequalification databases, and FDA 21 CFR Part 211 guidance documents. Bottom-up segmentation modeling triangulated against top-down market sizing from customs trade flows and pharmaceutical distribution infrastructure investments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, material substrate, temperature control method, and end-user industry vertical. CAGRs derived from slope analysis of adoption curves for mRNA and cell-and-gene therapy commercialization. Industry-specific inputs encompassed IATA CEIV Pharma certification timelines and phase-change material performance testing protocols.
Material uncertainties — cryogenic therapy approval trajectories, petrochemical price volatility, and IATA regulatory amendments — sit outside the modeled envelope. Forecasts reflect assumptions about sustained biopharmaceutical cold chain investment and stable qualification standards. Practitioners should keep alternative scenarios live as EU GDP electronic logging enforcement postures and Indian biologics export volumes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Thermal Insulated Bubble Wrap Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
Foam Edge Protectors Market
Protective Packaging
Latin America Protective Packaging Market
Protective Packaging
Global Packaging Inserts and Cushions Market
Protective Packaging
Insulated Styrofoam Shipping Boxes Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Void Fill Pillows Market
Protective Packaging
Paper Cushion Systems Market
Protective Packaging
Middle East and Africa Protective Packaging Market
Protective Packaging
Padded Mailers Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
Molded Fiber Pulp Edge Protectors Market
Protective Packaging
High Pressure Protective Packaging Film Market
Protective Packaging
Insulated Packaging Market
Protective Packaging
Static Shielding Bags Market