
 Europe Protective Packaging Market | 2026-2036
Europe Protective Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Protective Packaging Market Foresight
The EU Green Deal is rebalancing material preferences across European protective packaging. Smurfit Kappa Group leverages its integrated containerboard mills to supply lightweight corrugated solutions at scale. DS Smith anchors its competitive position through circular design protocols that align with EFSA food-contact standards. Sealed Air Corporation differentiates via automated inflatable systems that cut void fill volumes for third-party logistics providers.
Protective packaging encompasses engineered materials and structures designed to absorb mechanical shock, control moisture ingress, and maintain dimensional stability during transit, typically incorporating corrugated fiberboard fluting profiles, expanded polyethylene foam densities, or multi-chamber air-cell configurations. Its primary purpose is to reduce product damage rates in supply chains handling fragile, high-value, or temperature-sensitive goods. Corrugated fiberboard occupies the largest share of material spend due to recyclability mandates and established collection infrastructure. Foam sheets lead growth in electronics and automotive components where anti-static and vibration-damping specifications are non-negotiable. Inflatable packaging captures margin pools in e-commerce fulfillment, where dimensional weight pricing from carriers rewards minimal material usage.
REACH regulates chemical constituents in foam blowing agents and surface coatings, while the EU Packaging and Packaging Waste Directive sets binding recycling targets that reshape material selection timelines. CE marking requirements under the Construction Products Regulation extend to certain transit packaging used for building materials. Stakeholders must monitor how the EU AI Act and incoming digital product passport rules will trace packaging origin data across multinational supply chains.
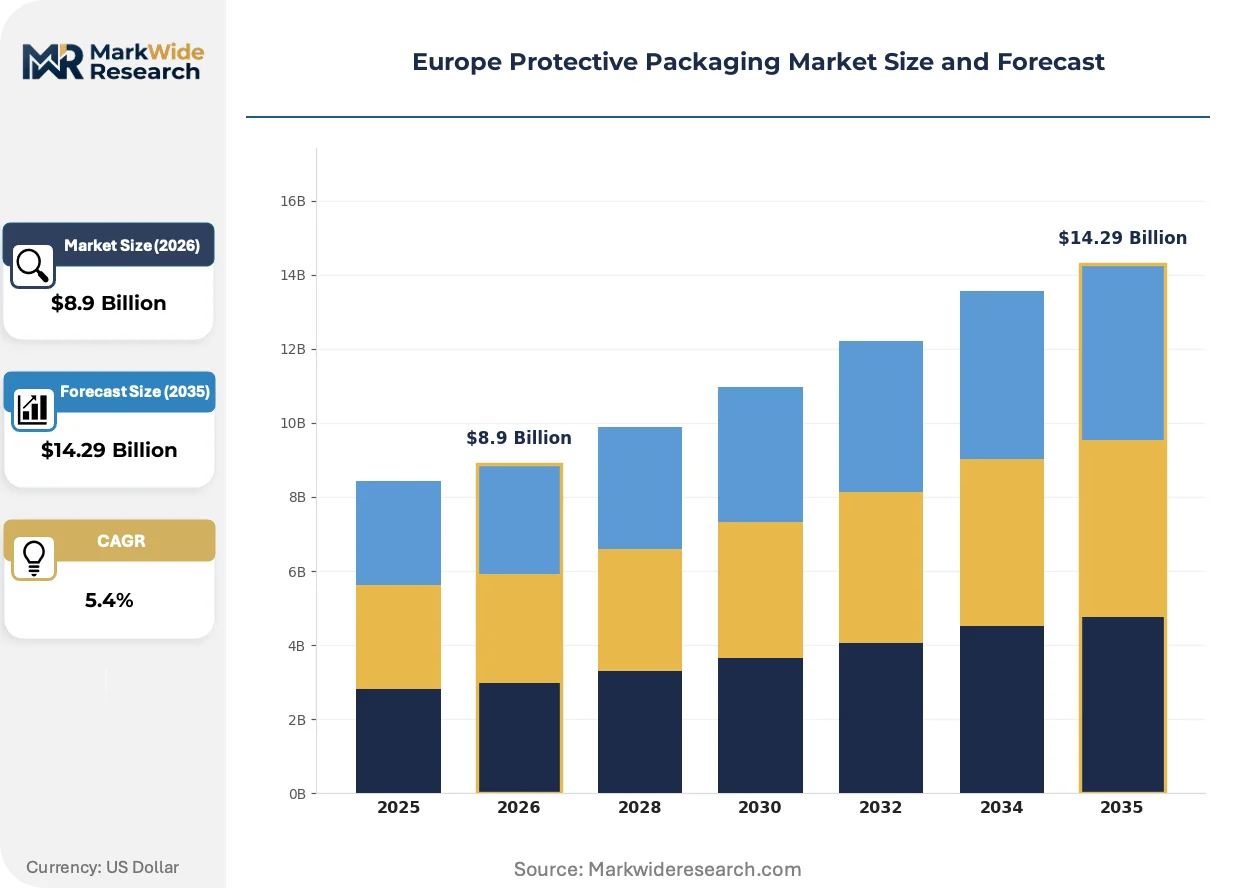
Market Dynamics
The EU Green Deal's binding plastic reduction targets are forcing a wholesale material transition across European protective packaging, with fiber-based substitutes capturing share from expanded polystyrene and polyethylene formats in fulfillment and industrial applications.
Growth Catalysts
- REACH chemical restrictions:Phasedowns in fluorinated blowing agents for foam production accelerate bio-based and mechanical alternatives in cushioning applications. German converters lead pilot programs.
- E-commerce fulfillment density:Parcel volume concentration in automated sorting hubs demands void-fill systems that compress dimensional weight. Inflatable and paper-based solutions displace loose-fill polystyrene.
- Benelux corrugated infrastructure:Integrated containerboard mills and cross-border converter networks enable just-in-time supply to distribution centers serving pan-European retail.
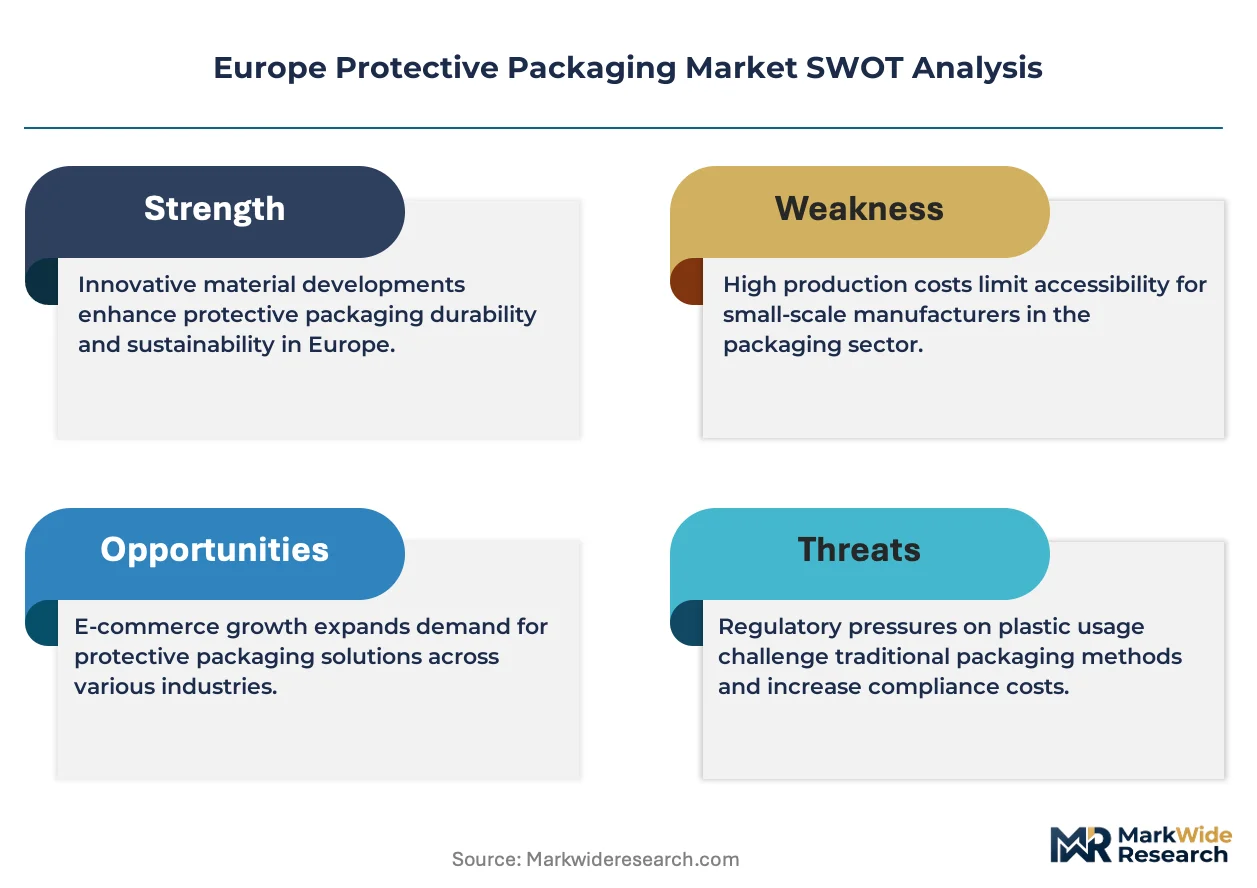
Market Restraints
- Recycled pulp cost volatility:Old corrugated container feedstock prices fluctuate with Chinese import policy shifts, squeezing converter margins on lightweight board grades.
- Foam formulation complexity:Bio-based polyols and CO2 blowing systems require capital retooling that mid-tier foam fabricators in Eastern Europe cannot finance.
- Single-use plastic directives:National transposition variations create compliance fragmentation, with France enforcing stricter timelines than Poland on banned cushioning formats.
Strategic Opportunities
- Digital product passport mandates:Upcoming EU traceability rules reward packaging suppliers with embedded RFID and blockchain origin verification. Early adopters capture premium positioning.
- Temperature-sensitive pharma logistics:Cell and gene therapy cold chains in Belgium and the Netherlands need qualified thermal packaging with validated phase-change materials.
- Romanian and Bulgarian manufacturing:Greenfield converter sites near Black Sea ports access lower energy costs and EU structural funds for circular economy investments.
Industry Challenges
- Food-contact migration testing:EFSA compliance for recycled fiberboard in direct-contact applications extends certification timelines by 8-14 months, delaying new product launches.
- Automation integration:Legacy corrugated plants face retrofit costs for robotic palletizing and AI-driven cut optimization that greenfield competitors embed from inception.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Protective Packaging Market |
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $14.29 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Bubble Wrap, Corrugated Fiberboard, Foam Sheets, Inflatable Packaging Packaging Form: Boxes, Pouches, Wraps, Pallet Covers, Tubes Application: Electronics, Pharmaceuticals, Food & Beverage, Automotive Components End User: Manufacturers, Distributors, E-commerce Fulfillment, Third-Party Logistics |
| Companies Covered | Smurfit Kappa Group, DS Smith, Sealed Air Corporation, Sonoco Products Company, Intertape Polymer Group, Huhtamaki Group, International Paper Company, Storopack Hans Reichenecker GmbH, Crown Holdings, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Protective Packaging Market Shifts & Advancements
Material science advances and regulatory data requirements are compressing development cycles across European protective packaging, with pilot-to-scale timelines halving for qualified fiber-based solutions.
Barrier-coated molded fiber is converging with high-resolution thermoforming to produce rigid cushioning that matches expanded polystyrene drop-test performance. Swedish appliance manufacturers are qualifying these formats for dishwasher and oven shipments. The technology is converging with automated nesting software that minimizes material usage per unit protected.
The EU AI Act's risk classification system extends to packaging machinery with embedded machine vision for defect detection. Equipment vendors must document algorithmic transparency and training data provenance. French and German OEMs are restructuring software architectures to isolate AI modules for third-party audit, adding 6-9 months to product release schedules.
Consolidated buying desks at pan-European retailers now mandate packaging data sharing through standardized EDI protocols. Tier-2 suppliers without API-connected inventory systems face exclusion from approved vendor lists. The Netherlands and Denmark show the highest compliance penetration, with supermarket chains requiring real-time carbon footprint disclosure at the SKU level.
Europe Protective Packaging Market Segmentation
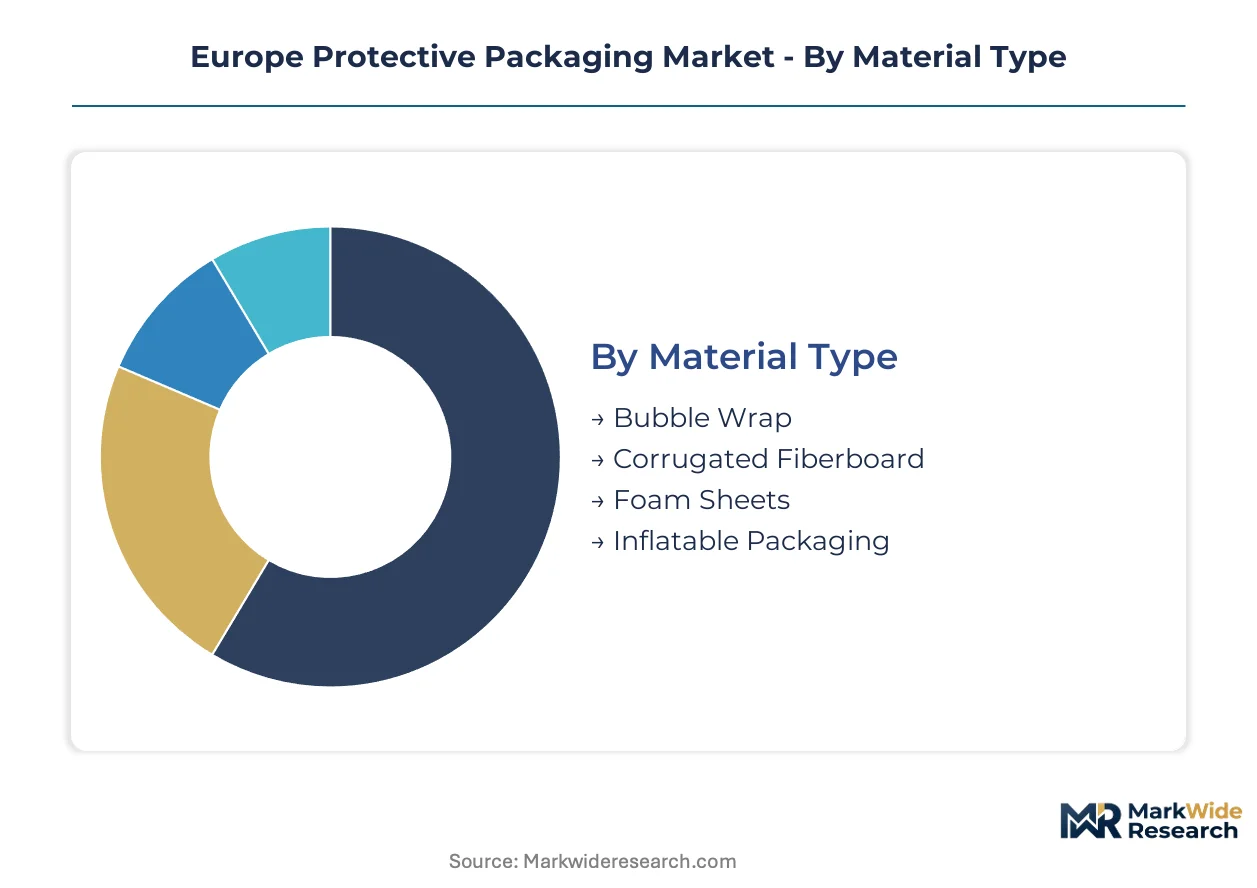
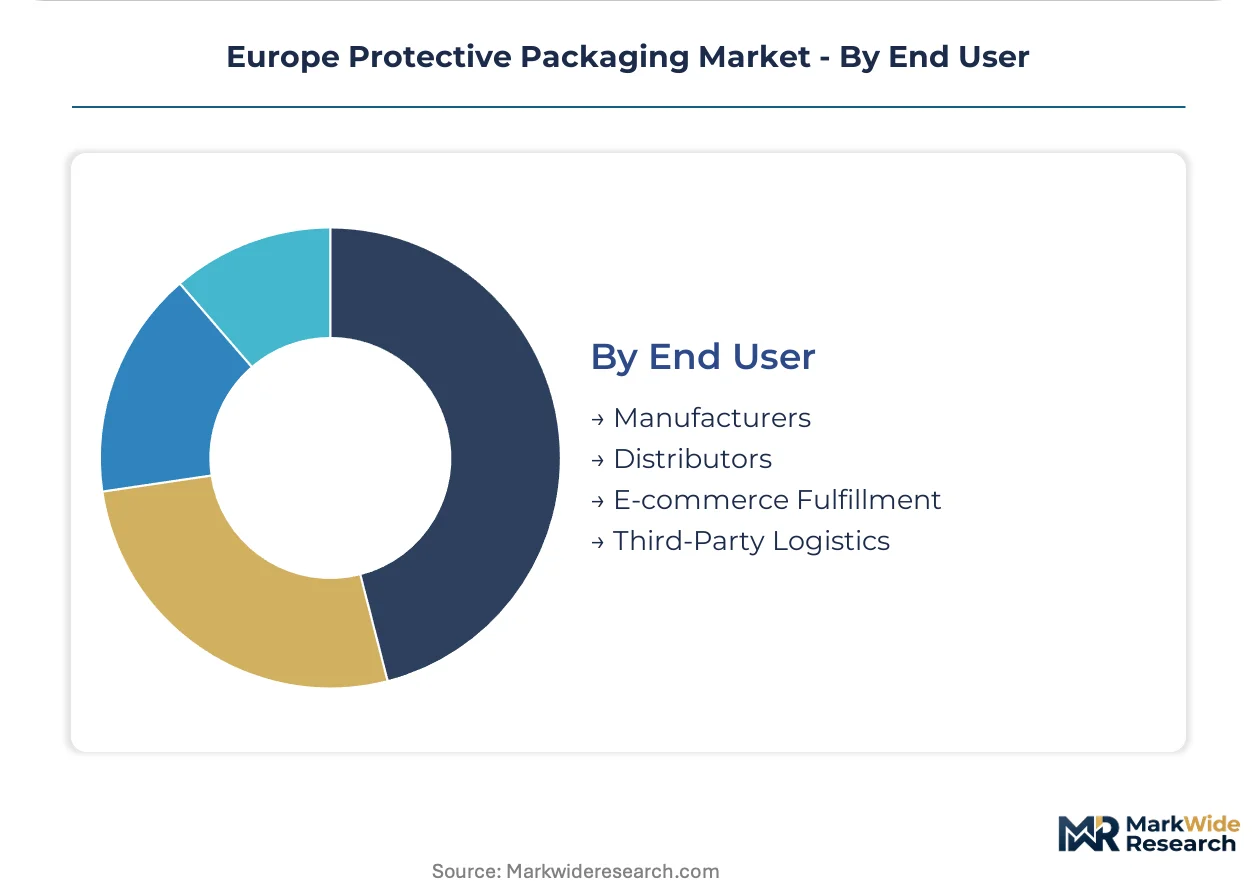
Protective packaging purchasing patterns diverge sharply between bulk industrial procurement and precision fulfillment requirements. Material specifications, form factor geometries, and end-use damage tolerances each create distinct margin pools that suppliers must navigate.
Material Type:
Corrugated fiberboard dominates tonnage shipped, while inflatable packaging commands the highest unit margins in parcel fulfillment.
- Corrugated Fiberboard:Engineered fluting profiles (B-flute, C-flute, double-wall) provide crush resistance and stacking strength for palletized distribution. German and Benelux converters supply lightweight board grades to cross-border retail distribution centers facing EU Packaging and Packaging Waste Directive recycling mandates.
- Inflatable Packaging:Multi-chamber air-cell films with variable burst strengths allow on-demand void fill generation at packing stations. E-commerce fulfillment centers in France and the Netherlands deploy automated inflation systems to minimize dimensional weight charges from parcel carriers.
- Foam Sheets:Expanded polyethylene and polyurethane densities with anti-static additives protect electronics and automotive components from vibration damage during multimodal transit.
- Bubble Wrap:Co-extruded polyethylene air retention films serve secondary cushioning and surface protection roles in consumer goods fulfillment.
Mature deployment sits with corrugated fiberboard. Newer deployment is concentrated in inflatable packaging systems.
Packaging Form:
Structural rigidity requirements separate industrial transit formats from flexible fulfillment solutions.
- Boxes:RSC (regular slotted container) and die-cut designs with integrated cushioning inserts protect high-value appliances and electronics. Swedish manufacturers qualify molded fiber inserts for dishwasher and oven shipments to replace expanded polystyrene.
- Wraps:Stretch film and paper-based wrapping systems secure palletized loads and individual items for automated sorting hub compatibility. Distributors in the Netherlands favor paper wraps meeting CSRD carbon disclosure requirements.
- Pouches:Barrier-coated flexible formats with bubble or foam linings protect small electronics and pharmaceutical samples from moisture ingress.
- Pallet Covers:Weather-resistant laminated films and insulated quilts shield temperature-sensitive shipments during yard storage and cross-docking.
- Tubes:Spiral-wound fiberboard cylinders with end caps protect rolled textiles, posters, and industrial films from edge damage.
Established volume flows through boxes. Tubes are gaining share fastest in specialized industrial applications.
Application:
Damage cost exposure determines specification stringency across end-use verticals.
- Electronics:Anti-static foam, conductive corrugated, and moisture barrier bags protect semiconductors, displays, and finished devices from electrostatic discharge and humidity. German automotive electronics suppliers enforce IPC-STD packaging protocols.
- Pharmaceuticals:Validated thermal packaging with phase-change materials maintains cold chain integrity for cell and gene therapies. Belgian and Dutch logistics hubs demand EMA-compliant qualification documentation.
- Food & Beverage:Recycled fiberboard with EFSA food-contact certification protects chilled and ambient grocery shipments. French retailers mandate recycled content thresholds under national plastic reduction timelines.
- Automotive Components:Precision-molded foam and VCI (vapor corrosion inhibitor) films protect machined parts and electronics modules from oxidation and impact during just-in-sequence delivery.
Electronics drives premium specification development. Pharmaceuticals represents the fastest-growing trajectory as biologics cold chains expand.
End User:
Procurement scale and technical capability separate self-service packaging from engineered solutions.
- E-commerce Fulfillment:Automated packing lines demand void-fill systems with minimal material usage and maximum throughput. Amazon and Zalando facilities in Germany and Poland deploy AI-driven box sizing to reduce air shipment.
- Third-Party Logistics:Multi-client operations require flexible packaging inventories and real-time SKU-level carbon footprint tracking. Dutch 3PLs lead API-connected inventory system adoption.
- Manufacturers:Captive packaging engineering teams design product-specific protection for high-value industrial goods. German appliance OEMs integrate packaging design with product development cycles.
- Distributors:Consolidated buying desks at pan-European wholesalers negotiate standardized packaging specifications across supplier portfolios.
Manufacturer procurement is most mature. E-commerce fulfillment is concentrating investment in automation-compatible formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors European protective packaging demand through its dense concentration of automotive electronics suppliers and third-party logistics hubs serving pan-European distribution.
Germany
Automotive electronics suppliers in Baden-Württemberg and Bavaria enforce IPC-STD packaging protocols for semiconductors and control modules. REACH chemical restrictions on fluorinated blowing agents accelerate bio-based foam pilot programs among German converters. The Rhine-Main logistics cluster around Frankfurt operates automated fulfillment centers deploying AI-driven box sizing to minimize dimensional weight charges.
France
French appliance manufacturers in Île-de-France and Auvergne-Rhône-Alpes qualify molded fiber cushioning for dishwasher and oven shipments to replace expanded polystyrene. National plastic reduction timelines enforce stricter recycled content thresholds than EU baseline requirements. The Parisian e-commerce fulfillment belt concentrates investment in automated inflatable systems for parcel optimization.
Netherlands
Belgian and Dutch pharma logistics hubs in the Randstad demand EMA-compliant thermal packaging with validated phase-change materials for cell and gene therapy cold chains. CSRD carbon disclosure requirements drive paper wrap adoption over plastic stretch film. Rotterdam port operations serve as the primary entry point for containerboard imports feeding Benelux converter networks.
Belgium
Cross-border distribution centers in Flanders source lightweight corrugated grades from integrated mills meeting EU Packaging and Packaging Waste Directive recycling mandates. The country's central geographic position enables just-in-time supply to French, German, and Dutch retail networks. Brussels-based regulatory affairs teams monitor EFSA food-contact certification timelines for recycled fiberboard applications.
Poland
E-commerce fulfillment centers in the Warsaw and Wrocław metropolitan areas deploy high-throughput void-fill systems for Amazon and Zalando operations. National transposition of single-use plastic directives follows more lenient timelines than France or Germany, creating compliance arbitrage for certain cushioning formats. Silesian manufacturing corridors attract greenfield converter investments accessing lower energy costs and EU structural funds.
Europe Protective Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material innovation and circular design capabilities, with integrated containerboard mills commanding structural advantages over standalone converters. The vendor base organizes into three tiers: multinational paperboard conglomerates with captive pulp supply, specialized foam and film fabricators serving electronics and pharma verticals, and regional corrugated converters competing on logistics proximity. Dominant competitive moves include backward integration into recycled pulp processing and strategic partnerships with automated packaging machinery OEMs.
Within the integrated paperboard tier, Smurfit Kappa Group and DS Smith exemplify scale-driven positions anchored by European mill networks. Sealed Air Corporation occupies a distinct archetype as a specialist in automated inflatable systems. These three entities represent divergent strategic postures: captive fiber supply, circular design protocols, and on-demand void-fill automation respectively.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| DS Smith |
| Sealed Air Corporation |
| Sonoco Products Company |
| Intertape Polymer Group |
| Huhtamaki Group |
| International Paper Company |
| Storopack Hans Reichenecker GmbH |
| Crown Holdings |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap converters in Eastern Europe anchor supply discipline through generational capital structures that resist margin compression, while their pricing power hinges on proximity to German automotive electronics clusters and Benelux distribution networks. This ownership pattern insulates fiberboard specialists from quarterly earnings pressure, allowing sustained investment in lightweight board grades despite recycled pulp cost volatility.
Pricing Analysis
Throughput-linked pricing for automated inflatable systems dominates the premium tier, with Sealed Air-style equipment vendors capturing value from dimensional weight savings passed through parcel carrier contracts. Price differentiation separates EFSA-certified food-contact fiberboard from industrial-grade alternatives, while volume-scale discounts concentrate among pan-European retail buying desks. Cost compression in commodity corrugated runs through Chinese import policy shifts on old corrugated container feedstock. Third-party logistics providers show highest price sensitivity due to multi-client procurement mandates, whereas pharmaceutical cold-chain specialists accept premium positioning for validated thermal packaging.
Supply Chain Analysis
Domestic-content mandates under the EU Green Deal's plastic reduction timelines reshape sourcing toward Benelux and German integrated mills, displacing Eastern European foam fabricators dependent on imported polyols. Geographic supply concentration centers on Germany, the Netherlands, and Belgium for containerboard, with Poland and Romania emerging for greenfield converter investments. Raw material dependencies draw from Swedish pulp, recycled OCC streams, and bio-based polyol pilot programs. Single-source vulnerability sits with fluorinated blowing agent phaseouts under REACH. Distribution runs through Rhine-Ruhr logistics clusters serving pan-European retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU Packaging and Packaging Waste Directive recycling mandates is forcing smaller converters into acquisition pipelines or exit, as compliance capital requirements outstrip standalone balance sheets.
For Market Incumbents: Deepen backward integration into recycled pulp processing to offset OCC feedstock volatility, while embedding RFID traceability modules ahead of digital product passport mandates. Threat substitution from barrier-coated molded fiber demands accelerated EFSA certification timelines. Capacity addition in Romanian greenfield sites captures EU structural fund access and Black Sea port logistics. For New Entrants and Emerging Players: Automated nesting software for fiber-based cushioning offers a technology-first wedge into Swedish appliance manufacturer supply chains, displacing expanded polystyrene for dishwasher and oven shipments. White-space targets include Bulgarian converter sites near low-energy manufacturing corridors and AI-driven cut optimization for legacy plant retrofits. Go-to-market positioning should anchor on CSRD-compliant carbon disclosure APIs for Dutch supermarket chains. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier foam fabricators in Poland facing REACH retooling costs beyond their capital access, particularly those with established automotive electronics relationships. Long-term viability hinges on five-to-ten year fiber substitution trajectories and circular design protocol adoption. The signal to watch is EFSA food-contact certification backlog duration as a proxy for new product launch velocity across the competitive set.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Pulp | Captive OCC supply insulates German converters from Chinese import policy volatility. |
| Digital Product Passport Enablement | RFID and blockchain origin verification captures premium positioning under upcoming EU traceability rules. |
| Greenfield Converter Investment | Romanian and Bulgarian sites access EU structural funds and lower energy costs for circular economy capex. |
| Automated Inflatable System Deployment | On-demand void fill minimizes dimensional weight charges from parcel carriers in French fulfillment centers. |
| EFSA Food-Contact Certification Acceleration | Recycled fiberboard qualification for direct-contact applications unlocks French retailer procurement mandates. |
Research Methodology
Multi-period observation of corrugated fiberboard tonnage flows, inflatable packaging system deployments, and EFSA certification timelines anchored the trend analysis, supplemented by interviews with plant managers at Benelux integrated mills, procurement leads at German automotive electronics suppliers, sustainability officers at pan-European retailers, and regulatory affairs specialists monitoring EU Green Deal implementation. Secondary validation drew from ECHA REACH substance registrations, EU Packaging and Packaging Waste Directive national transposition documents, SEC filings of listed paperboard conglomerates, and customs data on OCC cross-border movements. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for manufacturing output and e-commerce parcel volumes.
Segment-weighting approaches distributed value estimates across material type, packaging form, end-use application, and geographic production cluster, with growth rates derived from elasticity modeling against industrial production indices and fulfillment center automation capex cycles. Modeled dimensions included corrugated flute specifications, foam density grades, inflation system throughput tiers, and country-level regulatory compliance timelines. Forecast inputs incorporated phase-change material adoption curves for pharmaceutical cold chains and fiber substitution elasticities under plastic reduction mandates.
Several conditions sit outside the modeled scope, including unforeseen disruptions to Swedish pulp supply, accelerated EU AI Act enforcement timelines for packaging machinery, and national transposition variations beyond currently observed patterns. Forecasts reflect documented assumptions regarding REACH chemical restriction phaseout schedules and carrier dimensional weight pricing stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Padded Dividers Market
Protective Packaging
Padded Mailers Market
Protective Packaging
Anti-Corrosive Packaging Market
Protective Packaging
Thermal Insulated Mailers Market
Protective Packaging
Void Fill Pillows Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
Adhesive Bubble Wrap Market
Protective Packaging
North America Protective Packaging Market
Protective Packaging
Fiber Cushioning Market
Protective Packaging
Protective Packaging Market
Protective Packaging
Secondary Containment Trays Market
Protective Packaging
Static Shielding Bags Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Foam Protective Packaging Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
Insulated Shipping Boxes Market