
 Foam Packaging Inserts Market | 2026-2036
Foam Packaging Inserts Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Packaging Inserts Market Foresight
Market Context with Strategic Players
Modularization of protective packaging configurations is hardening as buyers shift from generic cushioning to application-specific foam insert systems. Sealed Air Corporation leverages its global manufacturing footprint to dominate high-volume electronics fulfillment contracts. Sonoco Products Company anchors its position through specialized molded pulp and foam hybrid solutions for medical equipment cushioning. Pregis LLC differentiates via on-demand inflatable and foam systems integrated with e-commerce packaging lines.
Technical Definition and Structural Segments
Foam packaging inserts are engineered cellular structures manufactured from expanded polystyrene, polyurethane, polyethylene, or polypropylene, designed to absorb shock, immobilize products, and distribute impact forces during transit and storage. These inserts typically feature densities ranging from 0.5 to 10 pounds per cubic foot, with compression strengths calibrated to specific payload fragility ratings for electronics, medical devices, and automotive components. Polyethylene foam leads in electronics protection due to its closed-cell moisture resistance and clean-room compatibility, while molded pulp is accelerating fastest in food container inserts as brands eliminate single-use plastics. Polyurethane foam occupies mature margin pools in medical equipment cushioning where sterilization-grade certification creates supplier stickiness and pricing power.
Regulatory Frame and Forward-Looking Close
EPA hazardous air pollutant standards for foam manufacturing, REACH substance restrictions on isocyanates and blowing agents, and China's GB standards for packaging material recyclability collectively elevate compliance costs while favoring producers with certified low-emission formulations. The EU Green Deal packaging waste directives and state-level extended producer responsibility laws in California and New York are tightening post-use recovery requirements for foam materials. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned capital deployment in molding equipment.
Market Dynamics
REACH substance restrictions on isocyanates and blowing agents are forcing rapid reformulation of polyurethane foam production across European manufacturing sites, compressing margins for uncertified producers while rewarding early adopters of low-emission chemistry portfolios.
Growth Catalysts
- E-commerce fulfillment density:Parcel volume concentration in automated distribution centers across Germany, China, and the United States is driving specification of engineered foam insert systems calibrated to robotic handling tolerances.
- REACH chemical compliance:European manufacturers upgrading to certified low-emission formulations are capturing preferential supplier status with multinational electronics brands operating under Scope 3 carbon accounting mandates.
- Closed-cell polyethylene specification:Electronics clean-room protocols are mandating moisture-resistant foam structures for semiconductor component protection, displacing open-cell alternatives in high-value payload segments.
Market Restraints
- Petrochemical input volatility:Styrene monomer and polyol feedstock price swings compress margin predictability for expanded polystyrene and polyurethane foam converters operating on fixed-price annual contracts.
- Supplier concentration in blowing agents:European and Chinese production of HFC alternatives remains concentrated among three chemical conglomerates, creating bottleneck risk for foam manufacturers scaling low-GWP formulations.
- Molded pulp substitution:Food and beverage brands eliminating single-use plastics are accelerating specification of fiber-based cushioning, displacing foam inserts in ambient-temperature consumer goods segments.
Strategic Opportunities
- India precision manufacturing expansion:Electronics and medical device production clusters in Karnataka and Tamil Nadu present underpenetrated demand for sterilization-grade polyurethane foam systems with BIS certification.
- EU Green Deal packaging waste directives:Extended producer responsibility mandates are creating preferential procurement channels for foam insert suppliers with verified closed-loop recycling partnerships and chemical recycling capabilities.
- 3D printing convergence:Fused filament fabrication of custom foam geometries is enabling on-demand insert production co-located with final assembly operations, compressing tooling lead times from weeks to hours.
Industry Challenges
- Reformulation chemistry expertise:Shortage of polymer scientists with cross-functional knowledge of low-emission blowing agents and compression strength calibration is delaying product recertification timelines for mid-tier foam converters.
- Multi-jurisdiction compliance synchronization:Divergent EPA hazardous air pollutant standards, REACH substance restrictions, and China's GB recyclability mandates require parallel certification tracks that fragment R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Packaging Inserts Market |
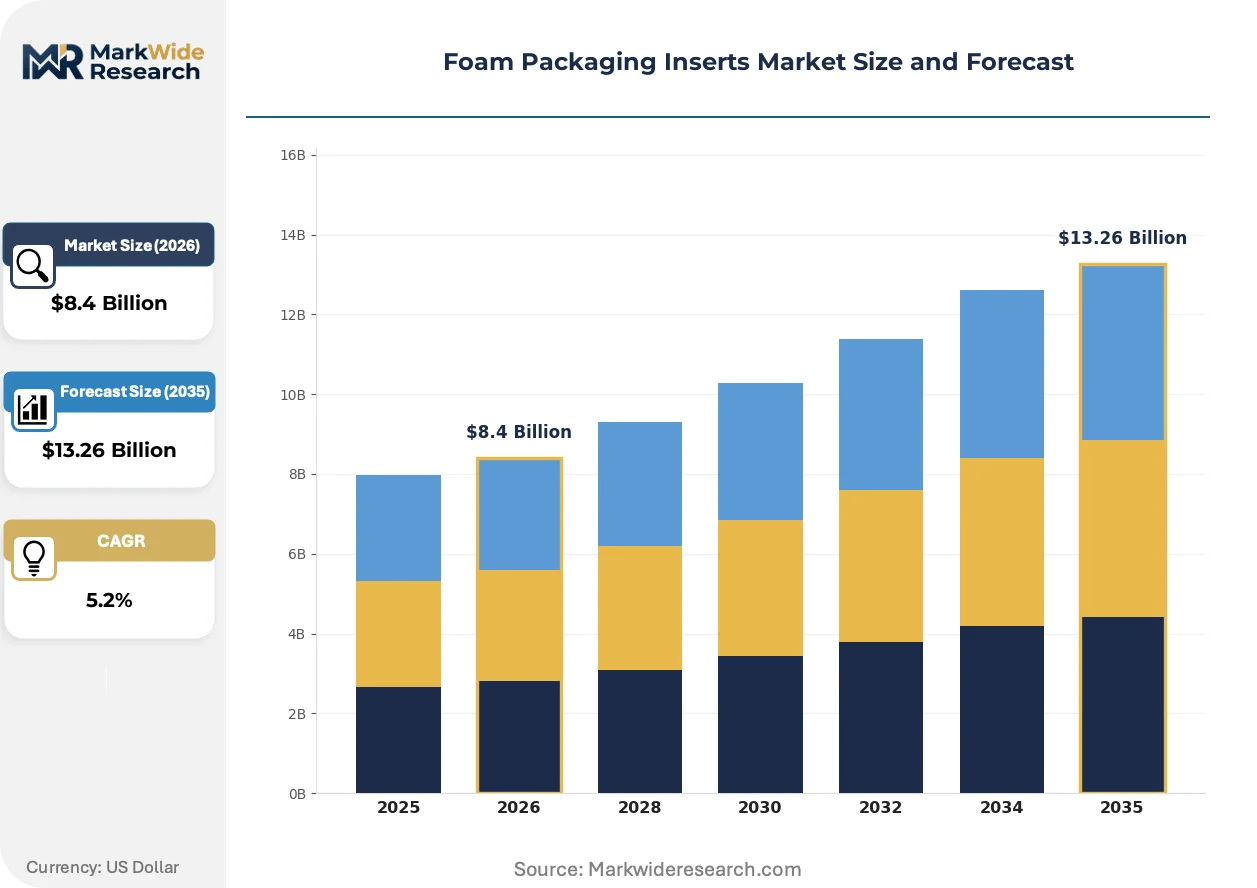
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Expanded Polystyrene, Polyurethane Foam, Polyethylene Foam, Molded Pulp, Polypropylene Foam Application: Electronics Protection, Medical Equipment Cushioning, Automotive Parts Packaging, Food Container Inserts, Consumer Goods Safety End Use Industry: Consumer Electronics, Pharmaceutical Products, Vehicle Components, Food & Beverage, Household Appliances Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Retail Packaging Suppliers, Industrial Supply Chains |
| Companies Covered | Sealed Air Corporation, Sonoco Products Company, Pregis LLC, Storopack Hans Reichenecker GmbH, ACH Foam Technologies, Polyformes Foam Solutions, UFP Technologies, Atlas Molded Products, Rogers Foam Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Packaging Inserts Market Shifts & Advancements
Active materials science breakthroughs and regulatory chemistry mandates are compressing traditional foam manufacturing paradigms while opening white space for bio-based and digitally fabricated alternatives.
Digital foam design platforms integrating topology optimization algorithms with compression simulation are decentralizing insert engineering from centralized OEM packaging departments to regional contract manufacturers. Medical device and automotive component suppliers in Germany and the United States are adopting these cloud-based tools to generate application-specific cellular structures without capital-intensive mold fabrication. This capability shift is compressing the traditional supplier-OEM design collaboration cycle from months to days.
REACH restrictions on isocyanate-based formulations are accelerating industrial adoption of water-blown and bio-polyol polyurethane systems across European foam conversion facilities. Manufacturers in Germany and the Netherlands are retrofitting production lines to handle higher-viscosity alternative chemistries that demand modified temperature and pressure controls. Medical equipment cushioning segments with sterilization-grade certification requirements are experiencing the most acute supplier qualification delays as reformulated products undergo extended biocompatibility testing.
Direct-to-consumer electronics brands are unbundling protective packaging specification from device engineering teams to dedicated sustainability procurement functions with explicit circularity KPIs. These centralized buying groups in California and New York state are consolidating supplier panels around foam insert vendors with verified chemical recycling partnerships and post-consumer content certifications. The shift is compressing vendor counts while elevating compliance documentation burdens for mid-tier foam converters lacking dedicated sustainability engineering staff.
Foam Packaging Inserts Market Segmentation
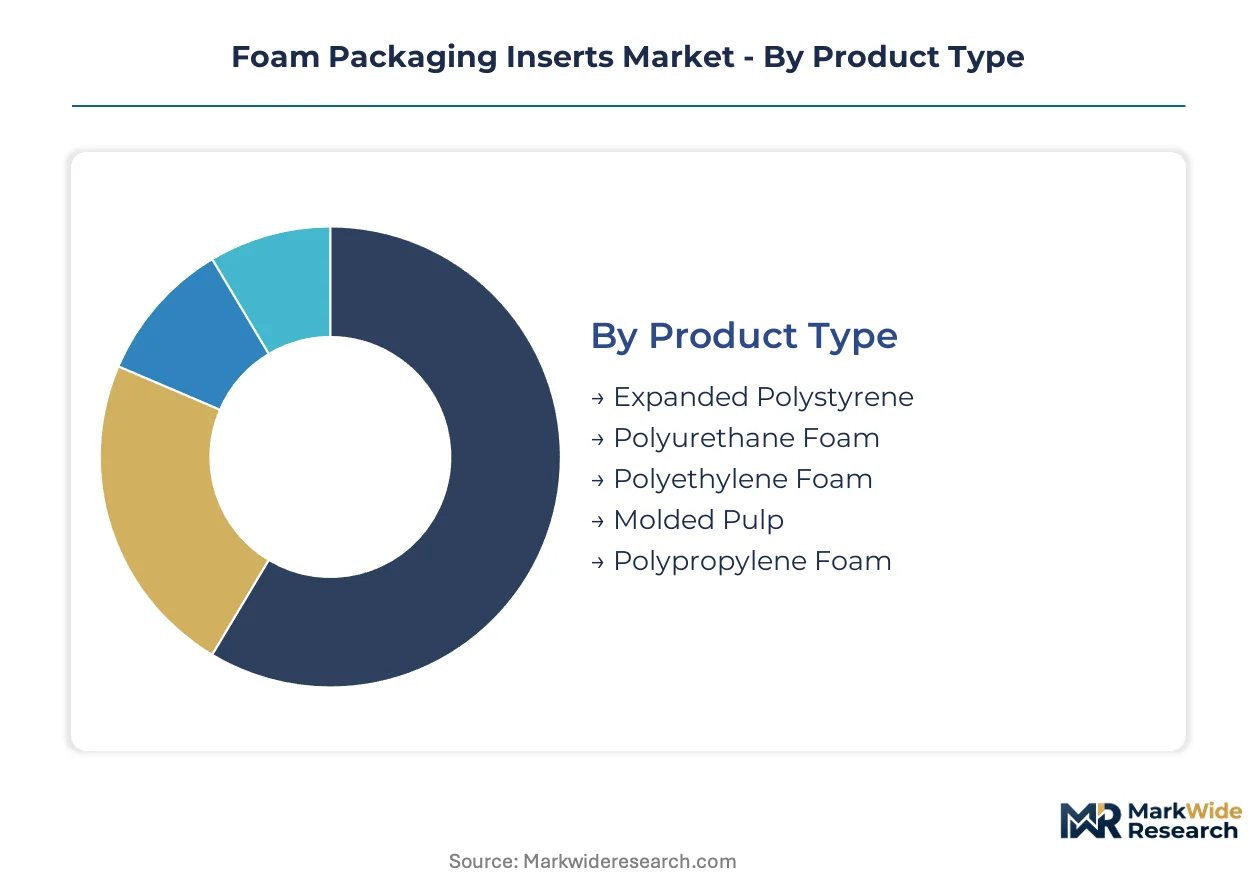
Segmentation in foam packaging inserts reveals how material chemistry, application fragility, and channel economics partition the competitive landscape. Buyers select formulations based on payload value density, sterilization requirements, and moisture exposure protocols rather than unit cost alone.
Product Type:
Volume deployment clusters in commodity-grade expanded polystyrene for low-fragility consumer goods, while premium capture concentrates in certified polyurethane and closed-cell polyethylene systems for medical and electronics segments.
- Expanded Polystyrene:Lightweight cellular structure manufactured from styrene monomer with densities from 0.75 to 3.0 pounds per cubic foot. Demand concentrates in food container inserts and consumer appliance cushioning across automated fulfillment networks in Germany and the United States, where cost-per-unit metrics dominate procurement scorecards. EPS faces margin compression from molded pulp substitution in ambient-temperature food applications.
- Polyurethane Foam:Open-cell and closed-cell formulations manufactured through isocyanate-polyol reactions with tunable compression set properties. Medical equipment cushioning in Germany and the Netherlands drives premium specification, where sterilization-grade certification under EU MDR creates supplier stickiness and pricing power for early REACH-compliant reformulators.
- Polyethylene Foam:Closed-cell cross-linked structure delivering moisture resistance and clean-room compatibility. Electronics protection protocols in semiconductor fabrication facilities specify this material for component immobilization during robotic handling operations.
- Molded Pulp:Fiber-based cellular cushioning manufactured from recycled paperboard and agricultural residues. Food and beverage brands in California and New York state are accelerating specification to meet extended producer responsibility mandates.
- Polypropylene Foam:Semi-rigid closed-cell structure with higher temperature tolerance than polyethylene. Automotive parts packaging for under-hood components in Germany and China utilizes this material for thermal stability during transit.
Mature deployment sits with expanded polystyrene in high-volume consumer goods. Newer deployment is concentrated in molded pulp as brands eliminate single-use plastics from packaging portfolios.
Application:
Application segmentation tracks how payload fragility ratings and handling automation requirements differentiate specification patterns across end-use verticals.
- Electronics Protection:Clean-room-compatible closed-cell foams calibrated to semiconductor component fragility ratings. Procurement concentrates in automated distribution centers across Germany, China, and the United States where robotic handling tolerances demand precise compression strength specification.
- Medical Equipment Cushioning:Sterilization-grade polyurethane systems with biocompatibility certification under EU MDR and FDA 510(k) pathways. German and Dutch manufacturers dominate supplier qualification for imaging equipment and surgical device OEMs.
- Automotive Parts Packaging:Engineered foam systems for powertrain components and interior trim with temperature cycling resistance. Production clusters in Germany, China, and the United States align with final assembly plant proximity requirements.
- Food Container Inserts:Ambient-temperature cushioning for meal kit and prepared food delivery. Molded pulp is gaining share fastest in California and New York state markets under tightening extended producer responsibility frameworks.
- Consumer Goods Safety:General-purpose cushioning for household appliances and personal care products. Specification favors lowest-unit-cost expanded polystyrene in high-volume e-commerce fulfillment contracts.
Established specification patterns dominate medical equipment cushioning where certification timelines lock in incumbent suppliers. Emerging specification concentration appears in food container inserts as fiber-based alternatives achieve cost parity with foam.
End Use Industry:
End-use segmentation reflects how regulatory scrutiny and product liability exposure elevate material performance requirements above commodity selection criteria.
- Consumer Electronics:Clean-room foam systems for smartphone, laptop, and semiconductor component protection. Procurement in Germany, China, and the United States specifies moisture-resistant closed-cell polyethylene for high-value payload segments.
- Pharmaceutical Products:Temperature-validated foam systems for biologic drug distribution with cold-chain integrity documentation. EU GDP guidelines and FDA temperature mapping requirements drive specification toward validated thermal packaging solutions.
- Vehicle Components:Durable foam cushioning for powertrain, battery, and interior trim protection. German automotive OEMs specify polypropylene foam for under-hood thermal stability requirements.
- Food & Beverage:Ambient and chilled distribution cushioning with circularity compliance documentation. California and New York state extended producer responsibility laws favor suppliers with verified post-consumer recycling partnerships.
- Household Appliances:Cost-optimized expanded polystyrene systems for large-format white goods protection. High-volume procurement through industrial supply chains in China and the United States prioritizes unit economics over performance specifications.
Regulatory complexity concentrates in pharmaceutical products where temperature validation and serialization requirements fragment supplier panels. Standardized procurement dominates household appliances where specification commoditization favors scale producers.
Distribution Channel:
Channel segmentation tracks how buyer scale and technical specification requirements partition access between direct manufacturer relationships and intermediated supply.
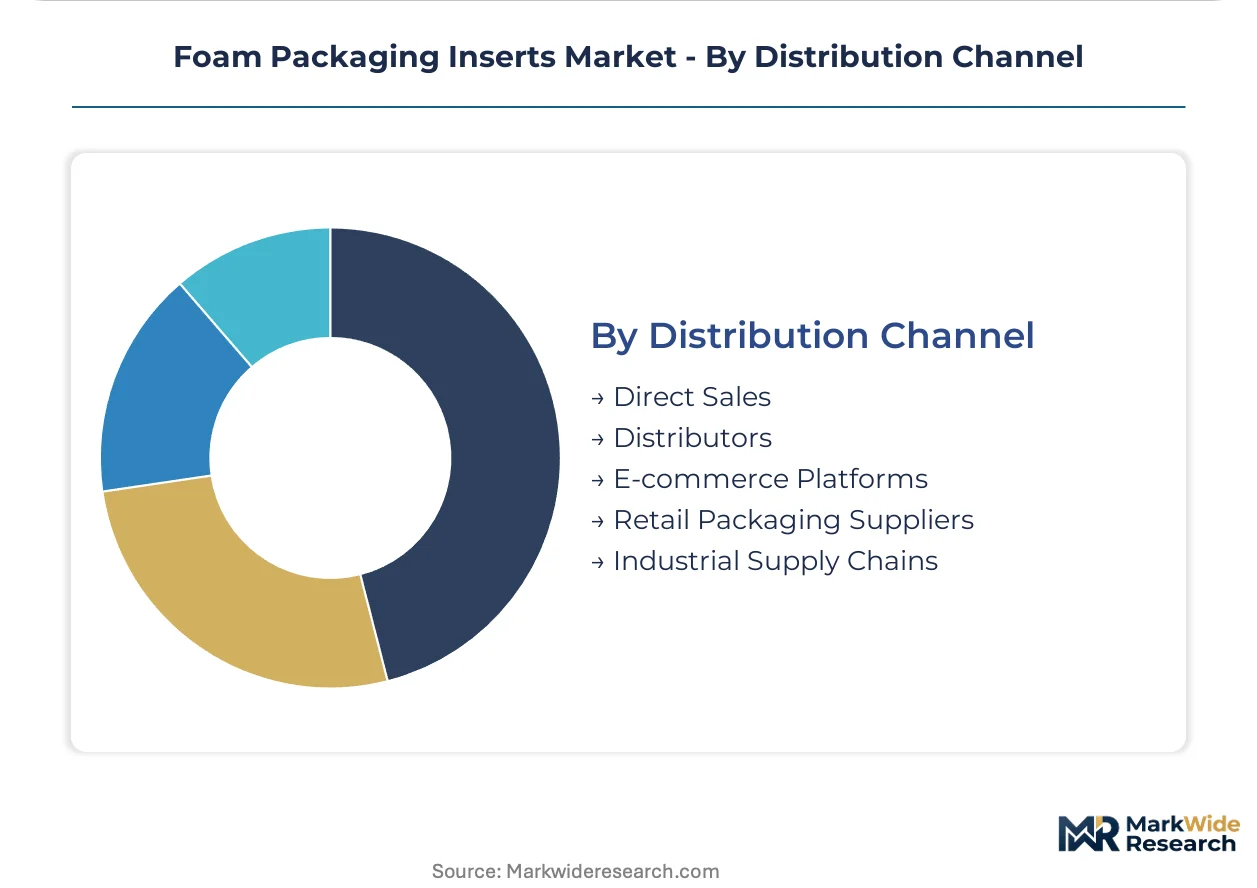
- Direct Sales:Long-term supply agreements between foam converters and multinational electronics or medical device OEMs. These relationships prioritize certified low-emission formulations and dedicated capacity allocation for high-volume fulfillment contracts.
- Distributors:Regional inventory stocking for mid-tier manufacturers with variable demand patterns. Industrial supply distributors in Germany and the United States carry standard-density polyethylene and polyurethane grades for maintenance-of-line procurement.
- E-commerce Platforms:Digital procurement portals for small-batch custom insert specification. Cloud-based foam design platforms enable on-demand topology optimization without capital-intensive mold fabrication.
- Retail Packaging Suppliers:Consolidated procurement for food and beverage brands with sustainability KPIs. These suppliers vet foam vendors for chemical recycling partnerships and post-consumer content certifications.
- Industrial Supply Chains:Tiered supplier integration for automotive and appliance manufacturers with just-in-sequence delivery requirements. Proximity to final assembly plants in Germany, China, and the United States dictates regional foam conversion capacity placement.
Relationship stickiness concentrates in direct sales where multi-year contracts and co-development agreements lock in formulation expertise. Channel expansion is accelerating through e-commerce platforms as digital design tools compress specification cycles from months to days.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany, China, and the United States where precision manufacturing clusters generate concentrated foam insert demand. Consumption patterns diverge as regulatory chemistry mandates in Europe reshape formulation specifications while Asian markets scale volume throughput.
United States
Electronics fulfillment automation in California and New York distribution centers drives specification of robotic-handling-calibrated foam systems. EPA hazardous air pollutant standards for foam manufacturing elevate compliance costs for domestic converters. Precision manufacturing clusters in Austin, Phoenix, and Boston anchor demand for semiconductor-grade polyethylene foam protection.
Germany
Medical equipment OEMs in Baden-Württemberg and Bavaria specify sterilization-grade polyurethane cushioning under EU MDR certification timelines. REACH substance restrictions on isocyanates force rapid reformulation across foam conversion facilities in the Rhine-Ruhr industrial corridor. Stuttgart and Munich host dense concentrations of automotive parts packaging demand requiring temperature-stable polypropylene systems.
China
E-commerce fulfillment infrastructure in the Yangtze River Delta and Pearl River Delta scales engineered foam insert procurement for consumer electronics protection. GB standards for packaging material recyclability mandate verified post-consumer content documentation. Shenzhen and Shanghai electronics manufacturing clusters specify closed-cell polyethylene for clean-room component handling.
India
Electronics and medical device production expansion in Karnataka and Tamil Nadu generates underpenetrated demand for BIS-certified sterilization-grade foam systems. The country's national packaging regulator tightens material safety specifications for pharmaceutical distribution. Bengaluru and Chennai precision manufacturing clusters are accelerating foam insert procurement for fragile component protection.
Netherlands
EU Green Deal packaging waste directives drive extended producer responsibility compliance for foam insert suppliers serving Rotterdam and Amsterdam distribution hubs. ECHA chemical restrictions favor producers with certified low-emission formulation portfolios. The Randstad logistics corridor concentrates demand for circular-economy-verified cushioning systems.
Foam Packaging Inserts Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between scale-driven multinationals with global manufacturing footprints and regional converters serving specialized certification segments. Three archetypes dominate: integrated packaging conglomerates with captive foam divisions, independent foam conversion specialists with formulation expertise, and hybrid molded pulp-foam system providers. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure preferential supplier status with multinational OEMs.
Among integrated packaging conglomerates, Sealed Air Corporation and Sonoco Products Company occupy positions exemplifying scale-driven global fulfillment contracting. Pregis LLC represents the on-demand systems archetype with e-commerce packaging line integration capabilities. Storopack Hans Reichenecker GmbH anchors the European specialist tier with German-engineered molded foam solutions. ACH Foam Technologies and UFP Technologies exemplify North American independent converters competing on regional proximity and specialized certification tracks.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Sonoco Products Company |
| Pregis LLC |
| Storopack Hans Reichenecker GmbH |
| ACH Foam Technologies |
| Polyformes Foam Solutions |
| UFP Technologies |
| Atlas Molded Products |
| Rogers Foam Corporation |
| Others |
Supply & Pricing Matrix
REACH-mandated reformulation of polyurethane foam chemistry in Europe is forcing converters to absorb elevated input costs for certified low-emission polyols and alternative blowing agents, compressing margins for uncertified suppliers while rewarding early chemistry adopters with pricing power in medical equipment segments.
Pricing Analysis
Margin tightening in sterilization-grade polyurethane reflects extended biocompatibility testing timelines under EU MDR certification pathways. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified medical foam from industrial-grade polyethylene and commodity expanded polystyrene. Price differentiation hinges on certification grade and volume scale, with electronics OEMs least sensitive due to payload value density, while appliance manufacturers drive aggressive cost-down pressure.
Supply Chain Analysis
Domestic-content mandates under China's GB standards for packaging recyclability are reshaping sourcing toward verified post-consumer content suppliers within mainland production zones. Feedstock supply concentrates in Germany, China, and the United States, with styrene monomer and polyol inputs drawing from petrochemical complexes in the US Gulf Coast and Rotterdam Antwerp hub. Single-source vulnerability in HFC-alternative blowing agents from three European and Chinese chemical conglomerates elevates bottleneck risk. Distribution runs through direct manufacturer relationships for multinational OEMs and regional distributors for mid-tier converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory chemistry mandates are compressing mid-tier foam converters without reformulation expertise, creating acquisition opportunities for scale players with certified low-emission portfolios and dedicated polymer science teams.
For Market Incumbents: Cement supplier stickiness in medical equipment cushioning through accelerated EU MDR certification timelines for water-blown polyurethane systems, while capturing electronics fulfillment contracts via robotic-handling-calibrated polyethylene foam capacity in Germany and the United States. Molded pulp substitution in food container inserts threatens expanded polystyrene margins; defend via hybrid foam-pulp system development for ambient-temperature applications. For New Entrants and Emerging Players: Launch via e-commerce platform integration for on-demand 3D-printed foam insert specification, targeting precision manufacturing clusters in Karnataka and Tamil Nadu with BIS-certified sterilization-grade polyurethane systems. White space concentrates in India's underpenetrated medical device packaging segment where incumbent qualification backlogs create procurement gaps for certified alternatives. For Investors and Strategic Acquirers: Re-rating potential sits with REACH-compliant foam conversion specialists given preferential supplier status with multinational electronics brands under Scope 3 carbon accounting mandates. Long-term viability favors producers with chemical recycling partnerships and closed-loop material capabilities. Monitor EU Green Deal extended producer responsibility enforcement as the inflection signal for circular-economy-verified packaging demand.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Chemistry Reformulation | EU MDR certification timelines lock in early adopters for medical equipment cushioning contracts. |
| 3D-Printed Foam Insert Capability | Topology optimization platforms compress tooling lead times from weeks to hours for custom geometries. |
| Chemical Recycling Partnership | California and New York extended producer responsibility laws favor verified closed-loop material suppliers. |
| India BIS Certification Investment | Karnataka and Tamil Nadu precision manufacturing clusters generate underpenetrated demand for sterilization-grade systems. |
| Hybrid Foam-Pulp System Development | Food and beverage brands eliminating single-use plastics require ambient-temperature cushioning alternatives. |
Research Methodology
Trade databases, chemical industry association reports, and regulatory filing repositories formed the secondary backbone for this analysis, cross-referenced with primary interviews involving foam conversion plant managers, procurement leads at electronics and medical device OEMs, distribution channel partners, and technical R&D directors specializing in low-emission blowing agent formulations. Bottom-up and top-down triangulation validated volume estimates across material chemistry and application segments.
Bottom-up modeling calibrated penetration rates by payload fragility rating and clean-room protocol requirements, while top-down analysis anchored total addressable market boundaries against e-commerce parcel volume growth in Germany, China, and the United States. Segmentation dimensions included material chemistry grade, end-use industry vertical, sterilization certification tier, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating REACH compliance cost pass-through and molded pulp substitution elasticities.
The model assumes a particular technology adoption path for water-blown and bio-polyol polyurethane systems; alternative pathways for HFC-alternative blowing agent chemistry would alter the outlook for European manufacturing cost structures. Forecasts reflect assumptions regarding regulatory enforcement timelines and feedstock price volatility. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Molded Fiber Pulp Edge Protectors Market
Protective Packaging
Padded Mailers Market
Protective Packaging
Static Shielding Bags Market
Protective Packaging
Insulated Shipping Boxes Market
Protective Packaging
Adhesive Bubble Wrap Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
Thermal Insulated Mailers Market
Protective Packaging
Inflatable Packaging Market
Protective Packaging
North America Insulated Packaging Market
Protective Packaging
Foam Edge Protectors Market
Protective Packaging
Foam Mesh Sleeves Market
Protective Packaging
Foam Protective Packaging Market
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Padded Dividers Market
Protective Packaging
Insulated Shippers Market
Protective Packaging
Secondary Containment Trays Market