
 Mailers Market | 2026-2036
Mailers Market Size, Share, and Industry Trends Forecast 2026-2036
Mailers Market Outlook
Packaging engineer shortages across North American manufacturing zones is redrawing competitive capacity among mailer suppliers. Sealed Air Corporation leverages its blown-film extrusion expertise to sustain high-barrier poly mailer output. Pregis LLC anchors Midwest production networks with automated pillow-and-mailer systems. Mondi competes through integrated kraft paper sourcing from European pulp assets.
Mailers constitute protective shipping enclosures engineered from single or multi-layer substrates including polyethylene coextrusions, kraft paper laminates, and air-retention bubble films, designed to cushion contents against impact and moisture during last-mile distribution. Poly mailers dominate volume throughput in e-commerce packaging due to their weight-efficient freight economics, while biodegradable films represent the fastest-expanding material category as brand sustainability mandates intensify. Bubble wrap mailers retain premium positioning in subscription boxes where unboxing experience justifies unit cost premiums.
EPA guidelines on recycled content thresholds and FDA indirect food contact standards shape material selection for pharmaceutical distributors and food delivery end users. The EU Green Deal and REACH chemical restrictions are accelerating substrate transitions away from conventional multi-layer plastics. Stakeholders must monitor evolving extended producer responsibility frameworks to anticipate compliance-driven reformulation cycles and regional sourcing reconfigurations.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing substrate transitions across mailer supply chains as extended producer responsibility frameworks tighten material recovery mandates. This regulatory compression is redrawing competitive capacity among suppliers while e-commerce parcel volumes surge.
Growth Catalysts
- E-commerce fulfillment expansion:Parcel volumes through centralized distribution hubs are pulling protective mailer procurement upward. Third-party logistics operators in Germany anchor cross-border online retail corridors with sustained volume commitments.
- EU Green Deal acceleration:REACH chemical restrictions and circular economy mandates are driving brand sustainability procurement policies. Biodegradable film categories capture preferential sourcing from pharmaceutical distributors seeking compliance pathways.
- Blown-film extrusion scale economies:High-barrier poly mailer output benefits from process intensification at integrated manufacturing sites. Automated pillow-and-mailer systems compress unit economics for Midwest fulfillment networks.
Market Restraints
- Polyethylene resin price volatility:Crude-linked feedstock swings compress margin predictability for multi-layer coextrusion operations. Hedging costs accumulate for non-integrated converters lacking captive resin supply.
- Kraft pulp supply concentration:European pulp asset control limits independent paper laminate sourcing flexibility. Mondi's integrated fiber position creates asymmetric input cost exposure for competitors.
- Multi-layer plastic technical barriers:Conventional barrier films resist mechanical recycling stream integration. Sorting infrastructure gaps at municipal recovery facilities strand otherwise recoverable substrates.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:Temperature-assured mailer demand from biologics distributors outpaces current insulated packaging supply. FDA indirect food contact standards create certification moats for qualified suppliers.
- Subscription box unboxing premiumization:Bubble wrap mailers justify unit cost premiums through experiential differentiation. Beauty and wellness verticals concentrate procurement authority with specialized converters.
- Air-retention film technology convergence:Barrier coextrusions merge with cushioning geometries to displace rigid corrugated alternatives. Equipment manufacturers retrofit legacy lines for hybrid film structures.
Industry Challenges
- Packaging engineer talent scarcity:North American manufacturing zones face acute shortages of substrate formulation specialists. Technical workforce gaps constrain new product development cycle velocity.
- Extended producer responsibility compliance timelines:Member-state implementation variations under the EU Packaging and Packaging Waste Regulation create fragmented obligation schedules. Reformulation cycle synchronization demands multi-jurisdictional regulatory monitoring.
- Legacy warehouse management system integration:Automated mailer insertion equipment interfaces poorly with incumbent fulfillment software stacks. Capital deployment for line retrofitting encounters IT architecture friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mailers Market |
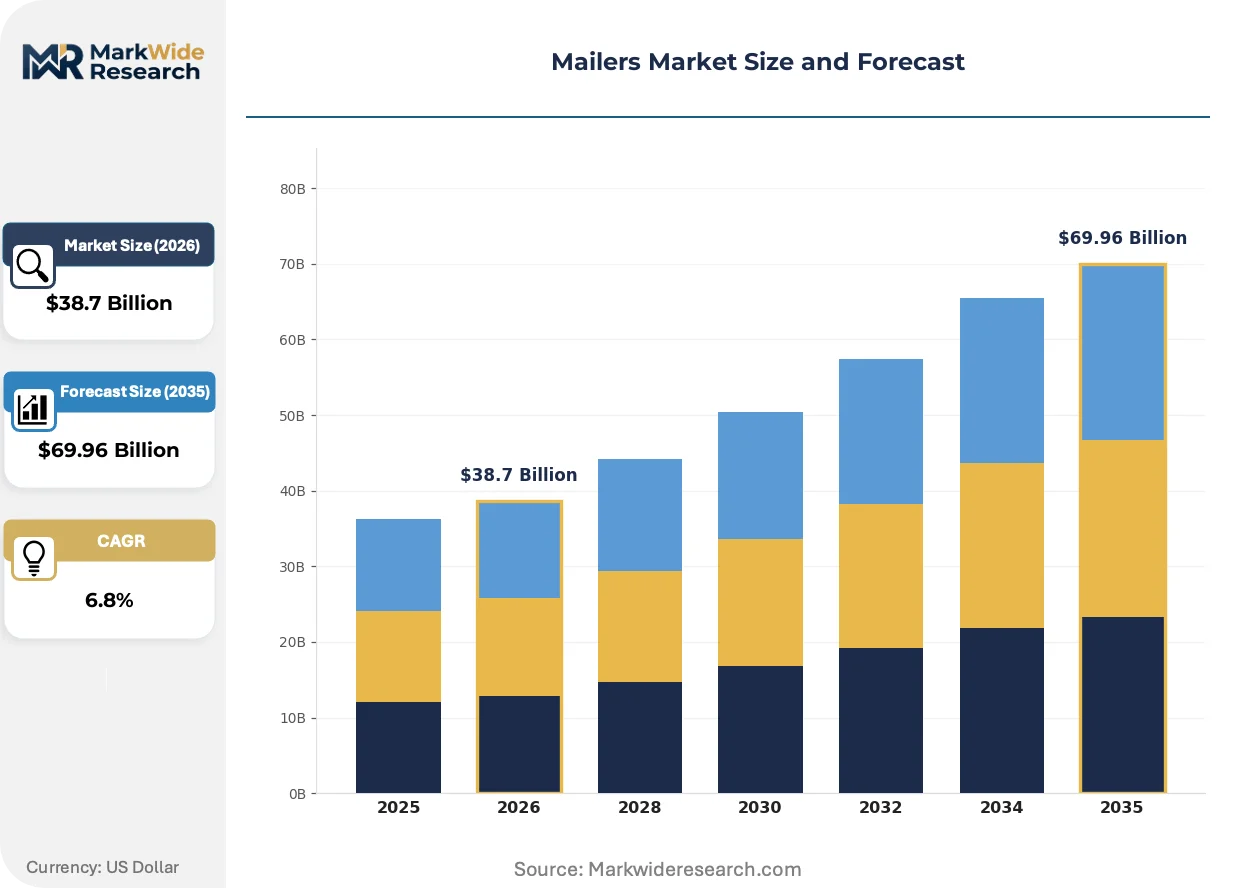
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Kraft Paper, Bubble Wrap, Poly Mailers, Tyvek, Foam Sheets, Biodegradable Films Application: E-commerce Packaging, Document Dispatch, Subscription Boxes, Promotional Kits, Gift Packaging, Postal Services End User: Online Retailers, Courier Services, Print Media, Pharmaceutical Distributors, Food Delivery, Educational Institutions Distribution Channel: Direct Sales, Online Marketplaces, Wholesalers, Distributors, Specialty Packaging Stores, Corporate Procurement |
| Companies Covered | Sealed Air Corporation, Pregis LLC, International Paper, Mondi, ProAmpac, 3M, Uline, Smurfit Kappa, PAC Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mailers Market Strategic Shifts
Substrate innovation is compressing traditional material boundaries as regulatory pressure and performance requirements converge. Three distinct vectors are restructuring competitive positioning across protective packaging value chains.
Biodegradable film formulations are fragmenting established polymer supply relationships. Polylactic acid and polyhydroxyalkanoate blends now cushion electronics and apparel shipments for sustainability-mandated retailers. Compostability certifications from BPI and TUV Austria are becoming gatekeeping criteria for brand procurement committees, displacing conventional polyethylene specifications in premium segments.
REACH chemical restrictions are accelerating substrate transitions across European mailer manufacturing. Substance of very high concern designations for certain plasticizers and stabilizers are forcing reformulation cycles at compounders serving the protective packaging sector. Pharmaceutical distributors and food delivery operators face the tightest compliance windows, with ECHA notification deadlines compressing supplier qualification timelines.
Direct-to-brand procurement models are disintermediating traditional packaging distributors. E-commerce pure-plays and omnichannel retailers now contract directly with film extruders and converters for customized mailer specifications. This channel compression is most visible in Germany and the Netherlands, where centralized fulfillment hubs aggregate sufficient volume to justify dedicated production runs and inventory positions.
Mailers Market Segmentation
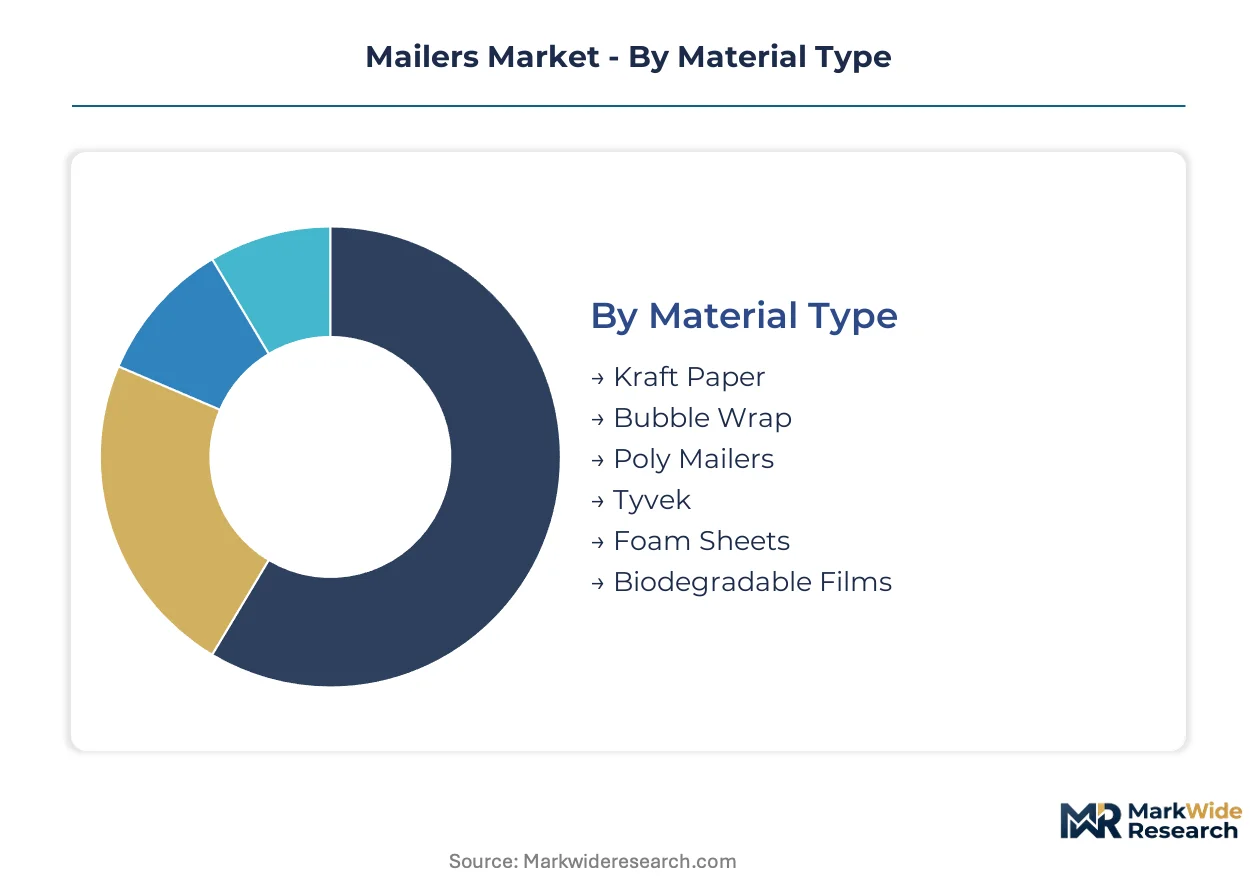
Segmentation in the mailers market reveals how substrate choice, fulfillment channel, and end-use requirements fragment procurement patterns. E-commerce operators source differently than pharmaceutical distributors, while regulatory pressure on material recovery reshapes segment trajectories unevenly.
Material Type:
Channel mix varies sharply by substrate—poly mailers flow through high-volume direct contracts with fulfillment operators, while kraft paper and specialty films move through distributors serving smaller accounts with sustainability mandates.
- Poly Mailers:Multi-layer polyethylene coextrusions deliver moisture barriers and tear resistance at freight-efficient weights. Demand concentrates in German cross-border e-commerce corridors where parcel density justifies bulk procurement from blown-film extruders.
- Biodegradable Films:Polylactic acid and polyhydroxyalkanoate blends achieve compostability certifications from BPI and TUV Austria. Beauty and wellness subscription boxes in the Netherlands drive preferential sourcing as brand sustainability committees displace conventional polyethylene specifications.
- Bubble Wrap:Air-retention cushioning films protect electronics and fragile goods through last-mile distribution networks.
- Kraft Paper:Recyclable fiber-based substrates serve document dispatch and apparel shipments for retailers avoiding plastic taxes.
- Tyvek:High-density polyethylene spunbonded structures provide tear and water resistance for pharmaceutical documentation.
- Foam Sheets:Expanded polyethylene or polyurethane sheets cushion high-value electronics in specialized fulfillment operations.
Poly mailers dominate installed base. Biodegradable films are where expansion concentrates.
Application:
Cost tier separation is pronounced—subscription boxes and promotional kits command unit premiums for experiential unboxing, while postal services and document dispatch operate on razor-thin per-piece economics.
- E-commerce Packaging:Protective enclosures engineered for automated insertion lines and dimensional weight optimization. Third-party logistics operators in centralized European hubs anchor volume procurement with sustained multi-year commitments.
- Subscription Boxes:Curated unboxing experiences justify bubble wrap mailers and printed kraft finishes at 3-5x standard unit costs. Beauty verticals concentrate authority with specialized converters capable of short-run customization.
- Document Dispatch:Lightweight polyethylene or paper sleeves for legal and financial correspondence with minimal cushioning requirements.
- Promotional Kits:Branded mailer assemblies combining product samples, literature, and promotional materials for marketing campaigns.
- Gift Packaging:Premium finishes and decorative elements for direct-to-recipient shipments bypassing retail display.
- Postal Services:Standardized sizes and specifications for national mail carrier interoperability and sorting automation.
E-commerce packaging commands the largest revenue pool. Subscription boxes carry the steepest expansion trajectory.
End User:
Customer type dictates specification complexity—pharmaceutical distributors and food delivery operators face FDA indirect food contact and temperature-assurance requirements that general merchandise retailers bypass.
- Online Retailers:Omnichannel and pure-play e-commerce operators with direct-to-brand procurement models. German and Dutch centralized fulfillment hubs aggregate sufficient volume to justify dedicated production runs and inventory positions.
- Pharmaceutical Distributors:Temperature-assured and tamper-evident mailers for biologics and controlled substances. FDA standards and EMA guidelines create certification moats that constrain qualified supplier pools.
- Courier Services:National and regional parcel carriers with standardized mailer specifications for network interoperability.
- Print Media:Magazine and catalog publishers transitioning to protective wraps as polybag taxes expand across European jurisdictions.
- Food Delivery:Insulated and grease-resistant mailers for meal kits and prepared food shipments with cold-chain requirements.
- Educational Institutions:Bulk procurement of document mailers for transcript and credential distribution with archival specifications.
Online retailers dominate installed base. Pharmaceutical distributors are where expansion concentrates.
Distribution Channel:
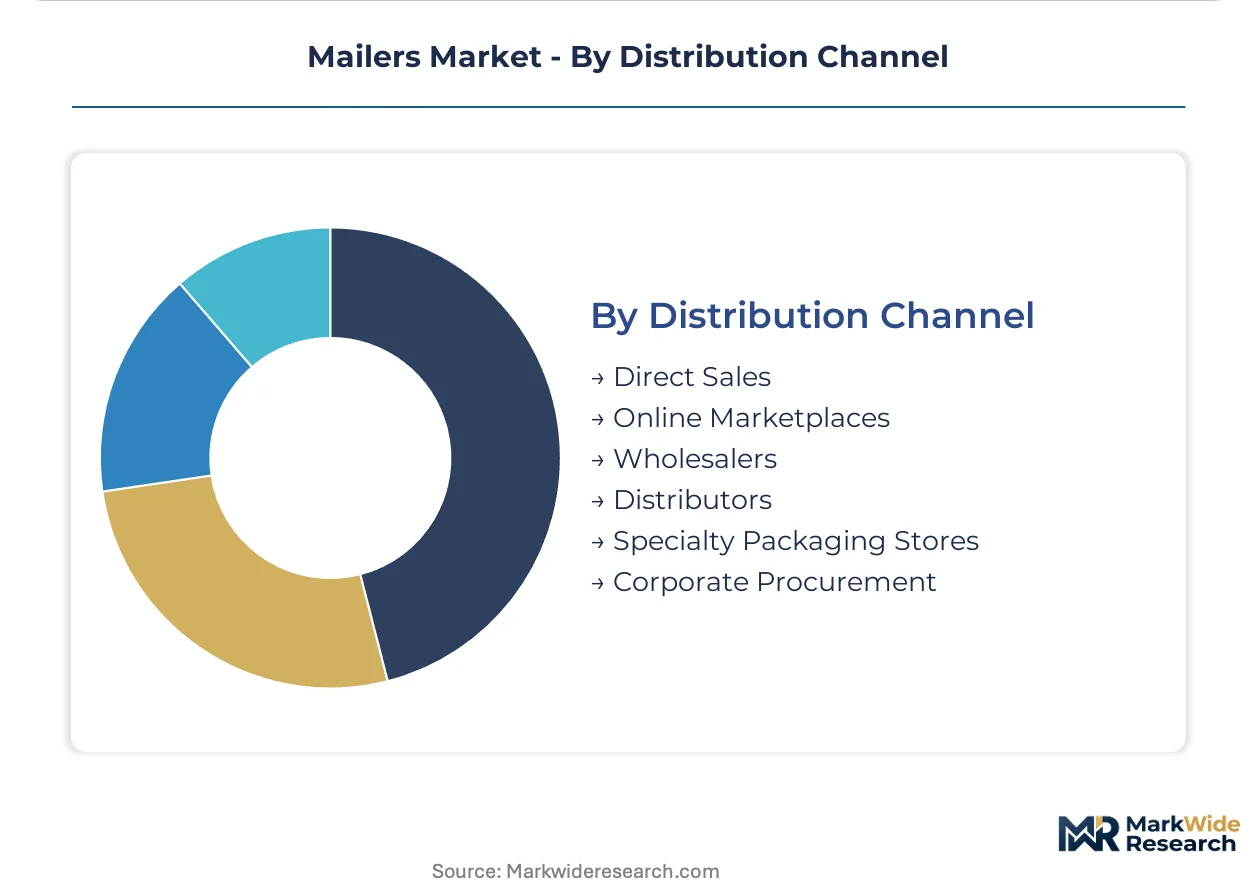
Supply concentration is shifting—direct sales and corporate procurement displace traditional distributors as large accounts internalize specification control and inventory management.
- Direct Sales:Film extruders and converters contract directly with high-volume end users for customized specifications. This channel compression is most visible in Germany and the Netherlands where fulfillment hub density supports dedicated production relationships.
- Corporate Procurement:Centralized purchasing consortia for multi-division enterprises with standardized sustainability and performance criteria.
- Online Marketplaces:Digital platforms aggregating small and mid-sized buyers with limited specification requirements.
- Wholesalers:Inventory intermediaries serving fragmented retail and service business segments.
- Distributors:Traditional packaging distributors losing share to direct channels among large accounts while retaining smaller buyers.
- Specialty Packaging Stores:Local suppliers serving immediate-need and prototype quantities for small businesses.
Direct sales dominate installed base. Corporate procurement is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Packaging and Packaging Waste Regulation enforcement is redrawing procurement geography across member states as extended producer responsibility frameworks tighten material recovery mandates. Parcel volume concentration in German distribution hubs anchors continental supply chain configuration.
Germany
Cross-border e-commerce fulfillment operators in the Ruhr Valley and Bavaria drive poly mailer procurement at scale. The national packaging ordinance implements EU Green Deal circular economy targets with strict recyclability quotas. Berlin-Brandenburg logistics clusters aggregate volume sufficient to justify dedicated blown-film extrusion lines.
United States
Third-party logistics operators in the Midwest and Southeast sustain automated pillow-and-mailer system deployment. EPA recycled content guidelines and state-level plastic bag taxes in California and New York shape material selection. Chicago and Dallas-Fort Worth distribution corridors concentrate procurement authority with direct-to-brand contracting models.
China
Domestic e-commerce platforms and cross-border sellers pull demand for lightweight polyethylene coextrusions. The national dual carbon goals and MEE plastic pollution action plans accelerate substrate transition timelines. Yangtze River Delta manufacturing zones house integrated film extrusion and converter operations serving Asia-Pacific fulfillment networks.
Netherlands
Beauty and wellness subscription box operators in Randstad drive biodegradable film procurement with BPI and TUV Austria certification requirements. REACH chemical restrictions through ECHA notification deadlines compress supplier qualification windows. Rotterdam-The Hague logistics corridor serves as a European entry point for sustainable mailer imports.
India
E-commerce marketplace sellers and courier services expand protective packaging procurement as parcel volumes surge. BIS packaging standards and state-level plastic waste management rules create compliance complexity across jurisdictions. Maharashtra and Karnataka industrial zones concentrate converter capacity for domestic and export fulfillment.
Mailers Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with blown-film extrusion scale and kraft pulp integration creating separation. The upper tier commands direct contracting relationships with high-volume fulfillment operators. Three archetypes define competitive positioning: resin-integrated film extruders, fiber-based paper laminators, and automated system specialists. Capacity expansion and backward integration into captive resin or pulp supply dominate strategic moves as margin pressure intensifies.
Within the integrated film extrusion tier, Sealed Air Corporation and Pregis LLC exemplify scale-driven positioning through process intensification and automated manufacturing systems. Mondi occupies a position anchoring the fiber-integrated segment with European pulp asset control. These three entities represent the competitive archetypes that smaller converters and regional specialists must navigate as direct-to-brand procurement compresses traditional distributor channels.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis LLC |
| International Paper |
| Mondi |
| ProAmpac |
| 3M |
| Uline |
| Smurfit Kappa |
| PAC Worldwide |
| Others |
Value Chain & Pricing Dynamics
Blown-film extrusion scale economies in German and Chinese manufacturing zones compress unit cost floors for high-volume poly mailer output while simultaneously concentrating procurement leverage among integrated resin producers. This capacity clustering creates asymmetric pricing power where captive polyethylene supply insulates Sealed Air Corporation and Pregis LLC from crude-linked feedstock volatility that strains non-integrated converters.
Pricing Analysis
German cross-border e-commerce corridors command 15-25% unit cost premiums over Midwest US fulfillment networks due to EU Green Deal compliance overhead and REACH-certified material specifications. Three-tier pricing structure across premium, standard, and economy levels separates biodegradable film subscriptions from commodity poly mailer spot purchases. Price differentiation hinges on BPI/TUV Austria certification grade and volume-scale contract duration. Pricing pressure stems from kraft pulp supply concentration giving Mondi asymmetric input cost exposure. Small Dutch beauty subscription box operators prove least price-sensitive while Indian courier services exhibit maximum elasticity.
Supply Chain Analysis
Strategic stockpiling of polyethylene resin dominates German and Chinese converter operations while US Midwest networks favor just-in-time inventory synchronized to automated pillow-and-mailer system throughput. Raw material flows draw from Saudi and US Gulf Coast ethylene crackers, European kraft pulp assets, and Yangtze River Delta biopolymer compounders. Single-source vulnerability concentrates in European pulp supply where Mondi's integrated fiber position creates bottleneck risk. Distribution runs through direct-to-brand contracting with third-party logistics operators rather than traditional packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mailer procurement fragmentation across substrate types, certification tiers, and fulfillment channel models creates specialist entry points that integrated incumbents cannot economically defend. Direct-to-brand contracting by German and Dutch e-commerce operators disintermediates legacy distributor relationships and opens niche positioning for qualified converters.
For Market Incumbents: Compound barrier film expertise with backward integration into captive resin supply to offset polyethylene price volatility compressing margin predictability. Extend automated manufacturing system deployment across Southeast Asian fulfillment corridors where parcel density justifies dedicated production lines. Defend against biodegradable film substitution by accelerating BPI certification timelines ahead of EU Packaging and Packaging Waste Regulation enforcement waves. For New Entrants and Emerging Players: Anchor in Indian pharmaceutical cold-chain expansion where temperature-assured mailer supply gaps outpace qualified converter capacity. Target Netherlands beauty subscription box procurement committees seeking short-run customization capabilities that scaled extruders cannot economically serve. Pursue direct contracting models disintermediating traditional distributors in Maharashtra and Karnataka industrial zones. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated system specialists with retrofit capabilities for hybrid film structures merging barrier coextrusions with cushioning geometries. Long-term viability rests on equipment manufacturers serving substrate transition cycles rather than single-material pure-plays. Watch ECHA substance of very high concern designation expansion as inflection signal accelerating reformulation-driven supplier qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Resin Supply | Insulates margin stability from crude-linked polyethylene feedstock volatility affecting non-integrated converters. |
| BPI/TUV Austria Certification Investment | Creates procurement moats with sustainability-mandated retailers displacing conventional polyethylene specifications. |
| Automated Pillow-and-Mailer System Deployment | Compresses unit economics for Midwest and Ruhr Valley fulfillment networks with sustained volume commitments. |
| Direct-to-Brand Contracting Model | Disintermediates traditional distributors in German and Dutch centralized hub corridors with dedicated production runs. |
| Hybrid Film Structure R&D | Merges barrier coextrusions with air-retention cushioning to displace rigid corrugated alternatives in last-mile distribution. |
Study Parameters
Desk research of trade association filings, customs documentation, and regulatory notification databases preceded structured interviews with blown-film extrusion plant managers, third-party logistics procurement leads, pharmaceutical distributor supply chain directors, and EU regulatory affairs specialists. Secondary validation drew from ECHA substance registration data, EPA recycled content guidelines, and BPI certification registries. Bottom-up volume modeling across material type and application segments triangulated against top-down macroeconomic drivers.
Variance decomposition across substrate transition timelines, e-commerce parcel density projections, and extended producer responsibility implementation schedules shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include material type, fulfillment channel, end-use vertical, and geographic regulatory cluster. CAGRs derived from historical volume trajectories adjusted for EU Green Deal acceleration and REACH chemical restriction phase-ins. Forecast inputs incorporated pharmaceutical cold-chain expansion rates and subscription box unboxing premiumization indices.
Material uncertainties — abrupt REACH substance designation expansions, polyethylene resin price spike persistence, and municipal recycling infrastructure deployment delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation synchronization and brand sustainability procurement policy stickiness. Revision becomes warranted when EU member-state packaging ordinance variations exceed modeled fragmentation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Carton Serialization Machine Market
Cartons
Microwaveable Carton Market
Cartons
Pulp Roll Cradles Market
Cartons
Brick Liquid Carton Market
Cartons
Cardboard Crates Market
Cartons
Digital Folding Cartons Market
Cartons
Cartoning Machines Market
Cartons
Beverage Cartons Market
Cartons
Global Printed Cartons Market
Cartons
Folding Carton in Healthcare Market
Cartons
Carton Sealer Machine Market
Cartons
Soap Boxes Market
Cartons
Litho Laminated Cartons Market
Cartons
Indonesia Folding Carton Packaging Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
Global Folding Carton Packaging Market