
 Global Packaging Inserts and Cushions Market | 2026-2036
Global Packaging Inserts and Cushions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Packaging Inserts and Cushions Market Intelligence
The shift toward bio-based and compostable materials is bifurcating the market between traditional polymer-based solutions and sustainable alternatives. Smurfit Kappa specializes in corrugated and molded pulp solutions to meet this environmental demand, particularly within the European market. In contrast, Sealed Air leverages its extensive portfolio of performance foams and air pillows, which are critical for protecting high-value electronics and medical devices during shipment. DS Smith also competes in the fiber-based segment, focusing on custom die-cut inserts for e-commerce.
Packaging inserts and cushions are engineered materials designed to immobilize, brace, and protect products within an outer container during transit and handling. Their primary function is to absorb shock and prevent damage, with material selection based on product fragility, weight, and vibration sensitivity. Molded pulp and corrugated paper materials are gaining share from traditional foams due to sustainability mandates. Within end-use industries, the electronics sector commands a significant portion of the market due to the high value and fragility of its components.
Regulations like the European Union's directives under the Green Deal and REACH are restricting certain chemical agents used in foam production. In the United States, the FDA sets strict material safety standards for inserts and cushions that come into contact with food and pharmaceuticals. These regulatory frameworks compel manufacturers to innovate toward safer and more recyclable materials. Consequently, balancing protection performance with environmental compliance will determine future market leadership.
Market Dynamics
The central structural force shaping the market is the bifurcation between traditional, high-performance polymer foams and emerging sustainable alternatives. This dynamic is driven by regulatory pressure for circularity and corporate mandates for environmentally responsible sourcing, creating distinct value chains.
Growth Catalysts
- Electronics Sector Demand:The need to protect high-value, fragile components in smartphones, laptops, and servers drives consistent demand for engineered cushioning, particularly anti-static foam and custom-molded pulp inserts for shock absorption.
- Sustainability Mandates:Regulations under the European Green Deal and similar policies globally are accelerating the transition from plastic foams to recyclable and compostable materials like corrugated paperboard and molded pulp, creating new growth avenues.
- E-commerce Expansion:The proliferation of direct-to-consumer shipping necessitates robust protective packaging to prevent damage during last-mile delivery, boosting volume for die-cut inserts, air pillows, and paper-based void fill solutions across numerous consumer goods categories.
Market Restraints
- Performance Gaps in Sustainable Materials:While gaining share, some bio-based materials like molded pulp do not yet match the shock absorption and moisture resistance of performance foams, limiting their use for extremely sensitive or heavy industrial goods.
- Polymer Feedstock Volatility:The price of polymer-based cushions, such as polyethylene and polyurethane foams, is directly tied to fluctuating crude oil and natural gas prices, creating cost instability for manufacturers and end-users.
- Chemical Use Regulations:The European Union's REACH regulation restricts certain blowing agents and flame retardants used in foam production, increasing compliance costs and forcing reformulation, which can impact material performance and availability.
Strategic Opportunities
- Insulated Packaging for Cold Chain:There is a significant opportunity in developing sustainable, fiber-based insulated inserts for the shipment of pharmaceuticals and perishable foods, offering an alternative to traditional expanded polystyrene (EPS) coolers.
- Smart Cushioning Integration:Incorporating low-cost sensors, such as shock or temperature indicators, directly into packaging inserts provides valuable supply chain data and an opportunity for value-added services for high-value goods.
- Geographic Expansion in Southeast Asia:Rising manufacturing output and burgeoning e-commerce markets in countries like Vietnam and Indonesia represent underpenetrated regions for advanced cushioning solutions beyond basic void fill.
Industry Challenges
- Complex Compliance Navigation:Manufacturers face the challenge of aligning product portfolios with divergent international standards, such as FDA food-contact requirements in the United States versus the EU's stringent recyclability and compostability criteria.
- Capital-Intensive Material Transition:Shifting production from extruded foam processes to molded pulp manufacturing requires significant capital investment in new machinery, retooling, and the establishment of a fiber-based raw material supply chain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Packaging Inserts and Cushions Market |
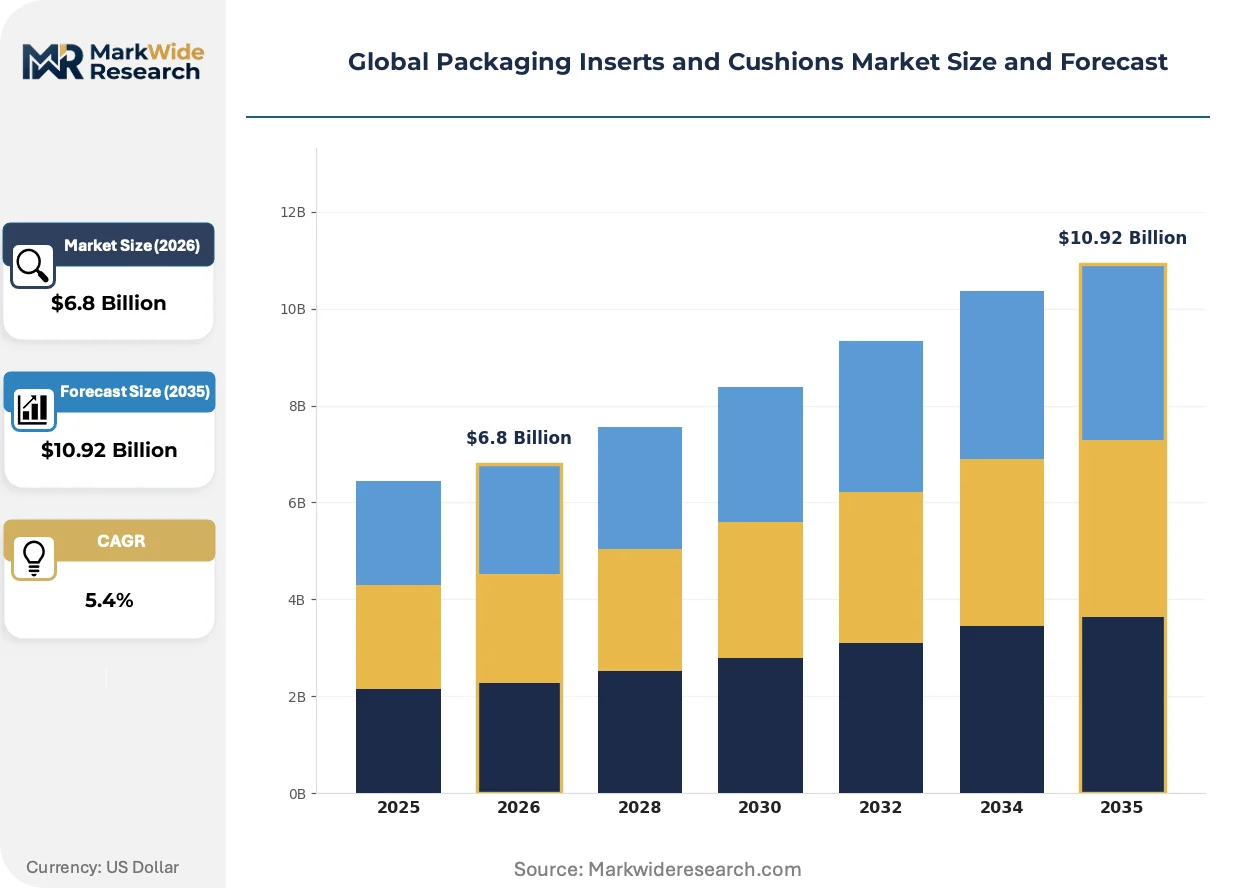
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Foam, Corrugated Paper, Molded Pulp, Plastic, Air Pillows End Use Industry: Electronics, Pharmaceuticals, Cosmetics, Food & Beverage, Personal Care Product Design: Custom Inserts, Pre-formed Cushions, Blister Packs, Die-cut Inserts, Foam Sheets Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Packaging Suppliers |
| Companies Covered | Pregis LLC, Huhtamaki, Smurfit Kappa, Plastifoam Company, Reflex Packaging, Sealed Air, Sonoco Products Company, Salazar Packaging, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Packaging Inserts and Cushions Market Strategic Shifts & Innovations
Material science innovation is the defining theme, driven by a persistent need to reconcile high-level product protection with circular economy principles. This is forcing a re-evaluation of material composition, design for disassembly, and end-of-life management across the entire packaging ecosystem.
Molded pulp, derived from recycled paper or virgin fibers, provides a customizable and recyclable protective solution. E-commerce and consumer electronics companies are rapidly adopting these inserts to meet their corporate sustainability targets. This technology is supplanting expanded polystyrene (EPS) and other non-recyclable foams for applications where custom-fit protection and environmental branding are critical.
European Union directives under the Green Deal are establishing strict targets for packaging waste reduction and recyclability. This regulatory pressure compels a systemic shift away from single-use plastic cushions toward mono-material solutions that are easier to recycle. The food and beverage industry is particularly affected, seeking materials that satisfy both EFSA food-contact safety and new environmental mandates.
A pronounced shift in buyer behavior is the prioritization of a positive "unboxing experience" within the direct-to-consumer channel. This trend moves procurement away from purely functional, generic void-fill toward aesthetically designed, custom-fit inserts that reinforce brand identity. This is most visible in the global cosmetics, luxury goods, and subscription box segments, where the insert itself becomes part of the product presentation.
Global Packaging Inserts and Cushions Market Segmentation
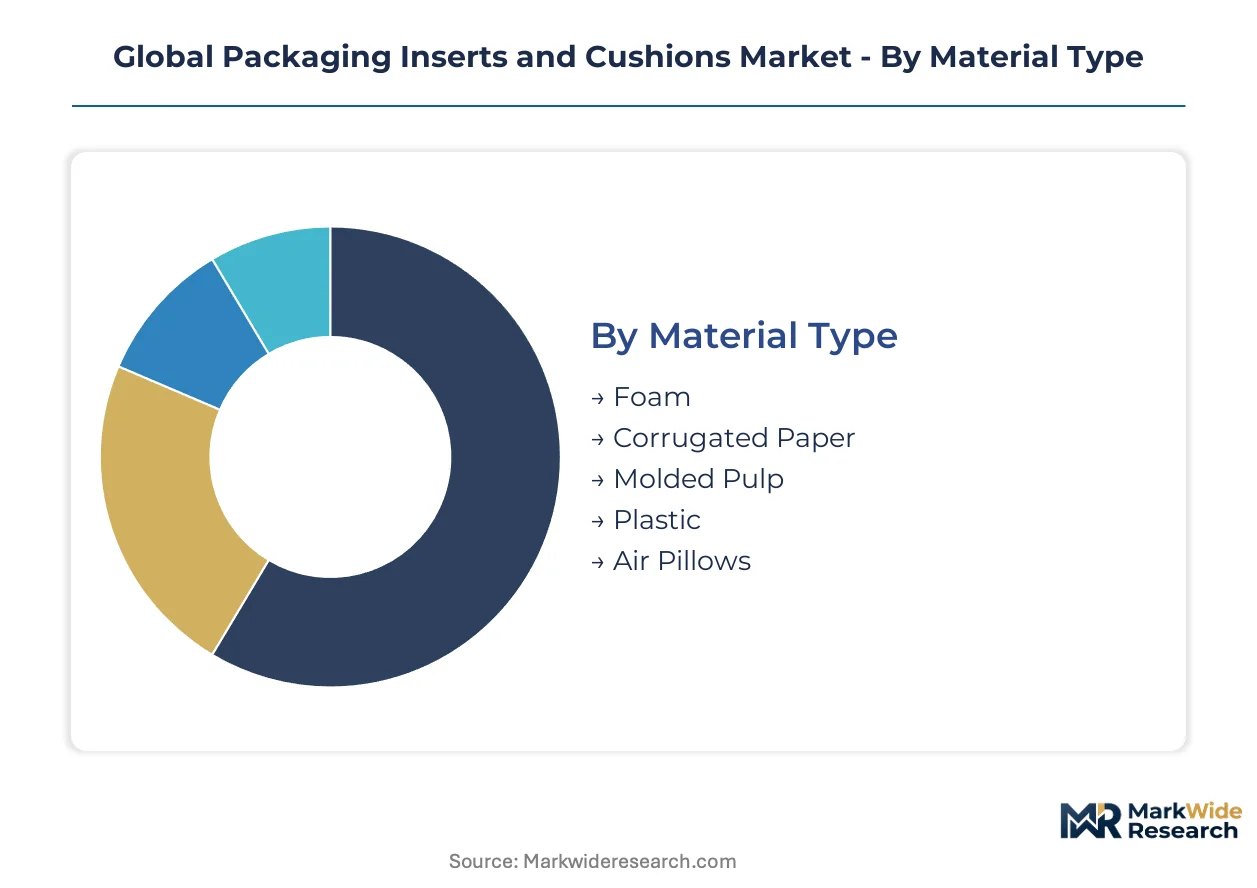
The global packaging inserts and cushions market segments into distinct categories based on material, end-use, product design, and distribution. Each segment reflects unique demand drivers and supply chain dynamics across various industries. Understanding these distinctions is critical for manufacturers to tailor solutions effectively.
Material Type:
The material type segmentation highlights the ongoing tension between established polymer-based solutions and newer sustainable alternatives, with demand concentration varying significantly by region.
- Molded Pulp:Composed of recycled paper fibers or virgin pulp, molded pulp provides custom-fit, protective packaging that is both recyclable and compostable. Demand is accelerating in Europe due to stringent Green Deal regulations and corporate sustainability targets.
- Foam:This category includes polyethylene, polyurethane, and expanded polystyrene, offering superior shock absorption and cushioning properties for fragile items. The electronics sector in Asia, particularly China and South Korea, relies heavily on foam for component protection during manufacturing and shipping.
- Corrugated Paper:Corrugated paperboard inserts offer versatile, cost-effective protection, often custom-die-cut for specific product dimensions. E-commerce platforms globally utilize corrugated paper solutions for void fill and bracing due to their recyclability and availability.
- Plastic:Plastic inserts and cushions, including vacuum-formed trays and rigid plastic protectors, provide clear visibility and robust support for various consumer goods. The cosmetics and personal care industries frequently use plastic for product presentation and security.
- Air Pillows:Lightweight and inflatable, air pillows fill voids within shipping containers, preventing product movement and reducing shipping weight. Logistics companies in North America and Europe widely adopt air pillows for their efficiency and cost-effectiveness in diverse applications.
Foam commands the established base in high-performance applications. The steepest expansion runs through molded pulp, driven by environmental mandates.
End Use Industry:
End-use industries dictate specific performance requirements for packaging inserts and cushions, with high-value sectors demanding advanced protective solutions.
- Electronics:This segment requires anti-static, high-cushioning materials to protect sensitive components like circuit boards, smartphones, and laptops from shock and vibration damage. The consumer electronics manufacturing hubs in Southeast Asia drive substantial demand for specialized inserts.
- Pharmaceuticals:Inserts and cushions for pharmaceuticals must meet strict regulatory standards for material safety and product integrity, often requiring temperature control and sterile packaging. North American and European pharmaceutical companies prioritize solutions that maintain product efficacy during transit.
- Food & Beverage:Packaging inserts in this sector ensure product stability and prevent breakage, particularly for fragile items like glass bottles or delicate produce. Food manufacturers in Germany increasingly adopt fiber-based solutions for sustainability and compliance.
- Cosmetics:Custom-designed inserts enhance product presentation and protect delicate cosmetic items, contributing to the unboxing experience. Luxury brands in France and Italy invest in aesthetically pleasing inserts for their premium products.
- Personal Care:This category encompasses a wide range of products, from toiletries to hygiene items, requiring cost-effective and functional cushioning to prevent damage during distribution. Mass-market personal care brands globally seek efficient and recyclable packaging solutions.
The electronics sector consistently generates the highest demand for advanced cushioning. Pharmaceutical and food and beverage applications are undergoing rapid material transformation.
Product Design:
Product design differentiates packaging inserts and cushions by their customization level, protective capabilities, and application versatility.
- Custom Inserts:These are precisely engineered to fit specific product contours, providing maximum protection and enhancing brand presentation. Luxury goods manufacturers and high-end electronics brands in Japan and the United States frequently commission custom designs.
- Die-cut Inserts:Produced by cutting flat sheets of material, typically corrugated paper or foam, into specific shapes for bracing and separation. E-commerce fulfillment centers globally use die-cut inserts for efficient and flexible packaging of diverse items.
- Pre-formed Cushions:Standardized cushioning shapes, often made from foam or molded pulp, offer general protection for various products. Automotive parts suppliers utilize pre-formed cushions for robust component protection during shipment.
- Blister Packs:Thermoformed plastic packaging that encases products, providing protection and visual display, commonly used for small consumer goods. Retailers of hardware and small electronics in the United Kingdom rely on blister packs for security and merchandising.
- Foam Sheets:Versatile sheets of foam material that can be cut, wrapped, or layered to provide cushioning for irregularly shaped or multiple items. Industrial manufacturers often use foam sheets for internal packaging and protection of components.
Custom inserts offer tailored protection and brand enhancement. Die-cut inserts provide scalable and adaptable solutions for diverse product lines.
Distribution Channel:
The distribution channel impacts how packaging inserts and cushions reach end-users, reflecting different procurement strategies and supply chain structures.
- Direct Sales:Manufacturers sell directly to large industrial clients or specific brand owners, often involving custom solutions and long-term contracts. Major electronics companies often procure specialized inserts directly from manufacturers.
- Wholesale Distributors:These intermediaries supply a broad range of packaging materials to various businesses, including small and medium-sized enterprises. Industrial suppliers in North America frequently source packaging inserts through wholesale networks.
- Online Retail:E-commerce platforms facilitate the purchase of packaging inserts and cushions, particularly for smaller businesses or individual consumers. Small businesses in Australia increasingly use online channels for purchasing void fill and basic cushioning.
- Packaging Suppliers:Companies that offer integrated packaging solutions, often including design, material sourcing, and assembly, serve diverse industries. Food and beverage processors in Germany partner with packaging suppliers for comprehensive material and design services.
Wholesale distributors form a critical conduit for broad market reach. Direct sales facilitate specialized, high-volume procurement for large enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global packaging inserts market exhibits a complex trade dynamic, with significant regional variations in both manufacturing output and consumption patterns. Export-oriented economies often drive demand for protective solutions, while import-heavy nations focus on efficient distribution packaging. This balance influences material choices and regulatory compliance across diverse geographies.
Germany
Demand for fiber-based solutions is high due to robust manufacturing and a strong food and beverage sector. German regulations under the EU Green Deal compel manufacturers to adopt recyclable materials for a circular economy. The Rhine-Ruhr industrial region sees significant innovation in molded pulp packaging for industrial goods and consumer products.
United States
The electronics sector and expansive e-commerce operations fuel consistent demand for advanced cushioning and void fill. The FDA sets strict material safety standards for food and pharmaceutical contact applications, influencing material selection. Silicon Valley and other tech hubs utilize custom inserts for high-value components, prioritizing anti-static properties.
China
Extensive electronics manufacturing and a burgeoning domestic e-commerce market propel demand for both foam and sustainable alternatives. China's dual carbon goals promote a systemic shift towards recyclable packaging materials across many industries. Production clusters in the Pearl River Delta integrate advanced cushioning into global supply chains for consumer electronics.
Vietnam
Rising manufacturing output, particularly in electronics and textiles, drives demand for cost-effective and protective packaging solutions. Government initiatives to attract foreign investment indirectly support the growth of local packaging material production capabilities. Industrial zones around Ho Chi Minh City are experiencing increased adoption of advanced cushioning solutions for export goods.
France
Luxury goods and pharmaceutical industries require bespoke, high-performance inserts that enhance brand presentation and product integrity. French environmental regulations, aligned with the EU Green Deal, prioritize bio-based and recyclable materials for all packaging. The Île-de-France region, with its luxury and pharma clusters, drives innovation in premium packaging design and material science.
Global Packaging Inserts and Cushions Market Key Industry Players
Concentration sits with large, diversified packaging conglomerates offering a broad material portfolio. The market structure exhibits a tiered consolidation, with global players dominating the high-performance and specialized segments. Strategic archetypes include material innovators, integrated solution providers, and regional specialists. Dominant competitive moves involve strategic partnerships for sustainable material development and significant capital investment in advanced manufacturing technologies.
Within the fiber-based packaging segment, Smurfit Kappa and DS Smith exemplify integrated providers specializing in corrugated and molded pulp solutions. These companies leverage extensive European operations to meet stringent sustainability mandates, particularly within the e-commerce sector. Sealed Air, on the other hand, represents a global leader in performance foams and air pillows, critical for high-value electronics and medical devices. This player maintains a strong presence in North America and Europe, focusing on shock absorption and void fill. These distinct approaches underscore the market's material bifurcation between traditional polymers and sustainable alternatives, influencing global supply chain choices.
| Leading Market Players |
|---|
| Pregis LLC |
| Huhtamaki |
| Smurfit Kappa |
| Plastifoam Company |
| Reflex Packaging |
| Sealed Air |
| Sonoco Products Company |
| Salazar Packaging |
| DS Smith |
| Others |
Cost & Logistics Intelligence
Three-month lead times for custom molded pulp inserts reflect regional production clusters and fiber material availability, directly influencing pricing power for specialized solutions. This market's supply chain configuration, particularly for polymer-based options, remains sensitive to global commodity price fluctuations.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for high-volume packaging inserts. Price differentiation stems from customization level for complex electronics components and certification for food-contact materials under FDA standards. Pricing pressure intensifies for standard void-fill solutions due to increased competition from paper-based alternatives. E-commerce platforms exhibit the highest price sensitivity for basic cushioning, while luxury goods brands prioritize bespoke design and are less sensitive to cost.
Supply Chain Analysis
Crude oil price volatility underpins the cost structure for traditional polymer foams, impacting manufacturers globally. Geographic supply concentrates in China for electronics manufacturing inputs and in Germany for advanced fiber-based solutions. Raw material dependencies include recycled paper fibers for molded pulp and petroleum derivatives for polyethylene foams. Commodity price volatility for polymer feedstocks represents a structural risk. Distribution channels predominantly run through wholesale distributors supplying diverse industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market presents a fragmentation opportunity, driven by the increasing demand for sustainable materials and a positive unboxing experience, creating niches across end-use industries.
For Market Incumbents: Consolidate market share in fiber-based packaging by acquiring specialized molded pulp manufacturers in Europe. Invest heavily in R&D to close performance gaps between bio-based materials and traditional foams, particularly for moisture resistance and shock absorption. This strategy mitigates threats from stringent EU Green Deal regulations and emerging sustainable material innovators. Expand capacity for certified food-contact packaging materials to meet evolving regulatory requirements.
For New Entrants and Emerging Players: Unaddressed demand for sustainable insulated packaging in cold chain logistics offers a significant entry point. Target the pharmaceutical and perishable food sectors by developing fiber-based alternatives to expanded polystyrene. Focus on integrating low-cost sensors into packaging inserts to provide value-added supply chain data for high-value goods. A go-to-market angle emphasizing full circularity and traceable material sourcing will resonate with corporate sustainability mandates.
For Investors and Strategic Acquirers: Long-term, this sits as a material transformation play because regulatory pressure and consumer preferences are driving a systemic shift towards sustainable alternatives. Target innovators in fiber-based packaging solutions, especially those with patented processes for enhanced performance or unique material compositions. The rapid adoption rates of molded pulp in new end-use industries beyond consumer electronics represent a key signal to watch for inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Molded Pulp | Addresses the growing demand for sustainable packaging solutions in European markets. |
| R&D in Bio-based Performance Foams | Closes performance gaps between traditional polymers and eco-friendly cushioning alternatives. |
| Strategic Partnership for Sensor Integration | Enhances supply chain visibility and offers value-added services for high-value product shipments. |
| Geographic Expansion into Southeast Asia | Captures burgeoning e-commerce and manufacturing growth in underpenetrated regional markets. |
| Acquisition of Cold Chain Packaging Specialist | Diversifies product portfolio into the high-growth segment of temperature-controlled logistics. |
Research Approach
A spread of perspectives from packaging procurement managers, material science engineers, sustainability officers, and logistics directors converged on the working assumptions for this study. Primary interviews with industry stakeholders were triangulated with secondary validation from industry association reports, regulatory body publications like the EU Green Deal, corporate sustainability reports, and trade journals. This approach facilitated both bottom-up market sizing and top-down validation.
The market segmentation dimensions modeled include material type, end-use industry, product design, and distribution channel, along with regional regulatory frameworks. Compound Annual Growth Rates were derived from historical data analysis, projected market drivers, and expert interviews across the analysis window. Forecast inputs incorporated raw material price forecasts for both fiber and polymer feedstocks, alongside e-commerce growth projections.
Forecasts assume regulatory continuity in regimes such as the European Union, United States, and China; material policy shifts would require re-modeling. These projections reflect assumptions regarding technological advancements and market dynamics. Practitioners should keep alternative scenarios live as unforeseen geopolitical events affecting supply chains and rapid shifts in consumer sustainability preferences evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Adhesive Bubble Wrap Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
Secondary Containment Trays Market
Protective Packaging
Padded Mailers Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Padded Dividers Market
Protective Packaging
Thermal Insulated Mailers Market
Protective Packaging
North America Protective Packaging Market
Protective Packaging
Corrugated Bubble Wrap Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Latin America Protective Packaging Market
Protective Packaging
Paper Cushion Systems Market
Protective Packaging
Foam Protective Packaging Market