
 Latin America Protective Packaging Market | 2026-2036
Latin America Protective Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Protective Packaging Market Foresight
Modular protective packaging configurations is hardening as the dominant procurement pattern across Latin American industrial buyers, replacing one-size commodity orders with segment-specific cushioning systems. Sealed Air Corporation leverages its regional foam fabrication network to serve automotive and electronics clusters in Mexico. Smurfit Kappa Group anchors corrugated protective solutions through integrated paperboard mills in Colombia and Brazil. Sonoco Products Company differentiates via molded fiber and tube-based protection for pharmaceutical distribution chains.
Latin America protective packaging encompasses engineered materials and structures designed to prevent mechanical damage, moisture ingress, and thermal shock during handling, transit, and storage, typically incorporating polyethylene foams, corrugated fiberboard fluting configurations, or air-cushioning films with specified burst strengths and compression resistance. Its primary purpose is maintaining product integrity from manufacturing point through last-mile delivery across fragmented logistics networks. Corrugated boxes and foam segments command the largest volume share due to universal applicability across food, electronics, and pharmaceutical supply chains. Flexible packaging and bio-based materials represent the fastest-expanding categories, driven by regulatory pressure on single-use plastics and retailer sustainability scorecards. Rigid protective packaging retains margin concentration in pharmaceutical cold-chain applications where thermal insulation performance commands premium pricing.
Brazil's ANVISA enforces pharmaceutical packaging integrity standards that elevate barrier specifications for temperature-sensitive drug distribution. Mexico's environmental regulator SEMARNAT implements extended producer responsibility frameworks affecting plastic protective material recovery quotas. Colombia's Ministry of Environment advances bio-based packaging certification pathways that reshape material selection for export-oriented manufacturers. Stakeholders must monitor regulatory divergence across Mercosur and Pacific Alliance frameworks when configuring regional product platforms and recycling compliance strategies.
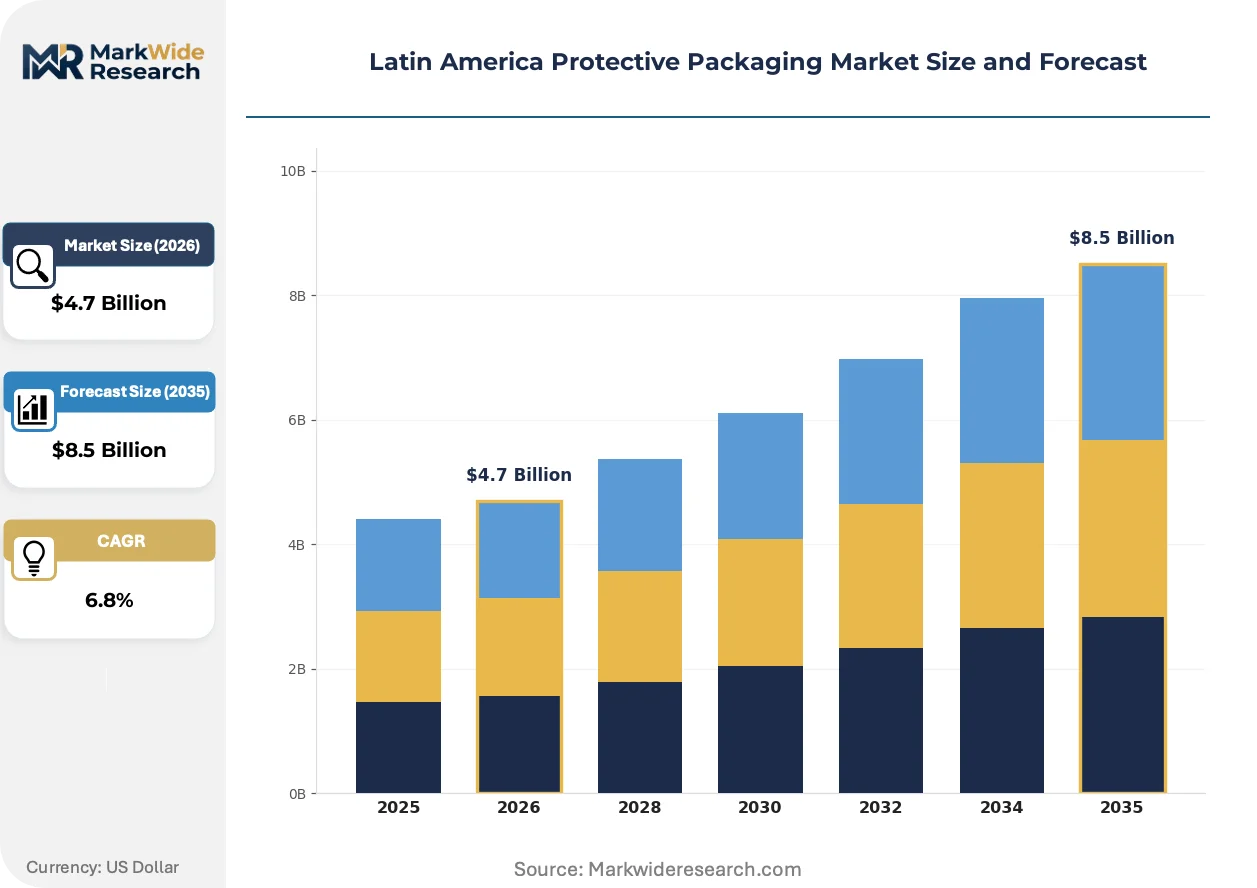
Market Dynamics
Modular protective packaging configurations are hardening as the dominant procurement pattern across Latin American industrial buyers, replacing one-size commodity orders with segment-specific cushioning systems engineered for automotive, pharmaceutical, and electronics supply chains.
Growth Catalysts
- E-commerce logistics scaling:Online retail penetration across Brazil and Mexico is driving protective packaging procurement volumes as fulfillment networks expand last-mile handling capacity.
- ANVISA pharmaceutical mandates:Brazil's national health surveillance agency enforces serialization and barrier-performance standards that elevate primary and secondary packaging specifications for temperature-sensitive drug distribution.
- Automotive supplier corridor concentration:Mexico's Querétaro and Tijuana manufacturing clusters require just-in-time engineered foam and corrugated protection systems for precision parts delivery.
Market Restraints
- Resin price volatility:Polyethylene and polypropylene input costs fluctuate with petrochemical feedstock pricing, compressing converter margins on foam and flexible film production.
- Recycling infrastructure gaps:Extended producer responsibility frameworks under SEMARNAT face uneven municipal collection capacity, creating compliance cost uncertainty for plastic protective material recovery quotas.
- Corrugated fiberboard supply concentration:Integrated paperboard mill capacity clusters in Colombia and Brazil limit alternative sourcing options for regional box converters during demand spikes.
Strategic Opportunities
- Colombia bio-based certification pathways:The Ministry of Environment's advancing certification frameworks for renewable packaging materials create first-mover positioning for export-oriented manufacturers serving EU markets.
- Cold-chain pharmaceutical expansion:Thermal insulation performance requirements for biologics distribution present premium pricing capture in rigid protective packaging for temperature-controlled logistics.
- Flexible film and air-cushioning convergence:Lightweight barrier films combined with automated inflation systems are penetrating electronics and consumer goods fulfillment centers seeking dimensional weight reduction.
Industry Challenges
- Barrier-performance engineering talent scarcity:Formulation chemists with multi-layer coextrusion expertise for pharmaceutical and food-grade specifications command premium compensation in São Paulo and Mexico City labor markets.
- Dual regulatory compliance complexity:Mercosur and Pacific Alliance framework divergence forces manufacturers to maintain parallel product platforms and recycling compliance strategies across Brazilian and Mexican regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Protective Packaging Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Foam, Bubble Wrap, Corrugated Boxes Material: Plastic, Paper, Metal, Bio-based End User: Food & Beverage, Consumer Electronics, Pharmaceuticals, E-commerce Packaging Type: Flexible Packaging, Rigid Packaging, Dieline Packaging, Others |
| Companies Covered | Sealed Air Corporation, Sonoco Products Company, Smurfit Kappa Group, Intertape Polymer Group Inc., Crown Holdings Inc., International Paper Company, Huhtamaki Group, Storopack Hans Reichenecker GmbH, WestRock Company, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Protective Packaging Market Shifts & Advancements
Active material science development and automated packaging line integration are compressing traditional protective packaging formats while elevating performance specifications across Latin American supply chains.
Smart active packaging systems incorporating moisture indicators and shock sensors are integrating into high-value pharmaceutical and electronics shipments. Brazilian and Mexican 3PL operators are piloting these technologies for insurance claim reduction and real-time damage attribution. The integration of sensor networks with warehouse management systems is enabling predictive cushioning replacement protocols.
SEMARNAT's extended producer responsibility frameworks are tightening plastic recovery quotas and accelerating investment in mechanically recycled content streams. Industrial converters face reformulation requirements to meet post-consumer recycled minimums without degrading burst strength specifications. Automotive and appliance manufacturers in Mexico's Bajío region are responding with supplier sustainability scorecards that weight circular material content.
Buyer procurement patterns are consolidating annual protective packaging volumes into multi-year framework agreements with performance-based specifications. Electronics assemblers in Guadalajara and medical device distributors in São Paulo are replacing spot purchasing with engineered cushioning system contracts. This concentration is most visible among multinational OEMs seeking harmonized protection standards across Brazilian and Mexican production facilities.
Latin America Protective Packaging Market Segmentation
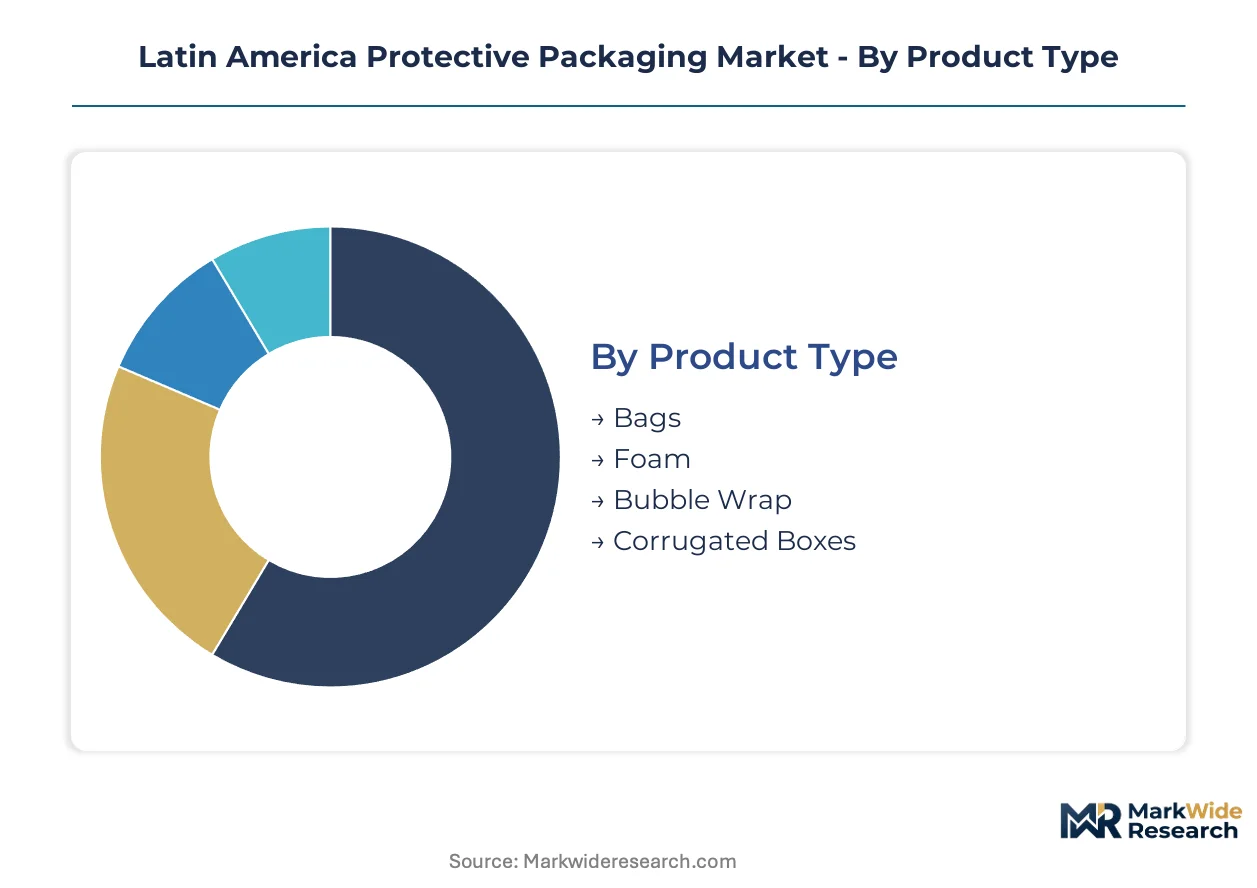
Protective packaging procurement across Latin America fragments along performance requirements and regulatory exposure. Buyers segment orders by product vulnerability, logistics handling intensity, and compliance jurisdiction rather than commodity price alone.
Product Type:
Material durability against handling stress drives selection for automotive and pharmaceutical shipments.
- Corrugated Boxes:Multi-wall fiberboard constructions with specified edge crush test ratings dominate Brazil's food export corridors and Mexico's automotive parts networks. ANVISA serialization mandates elevate box specifications for pharmaceutical secondary packaging.
- Foam:Polyethylene and polyurethane foam systems provide engineered cushioning for electronics assemblers in Guadalajara and precision components near Querétaro. Just-in-time delivery requirements favor modular foam configurations over commodity sheet stock.
- Bubble Wrap:Air-cushioning films with defined burst strengths serve consumer goods fulfillment centers seeking dimensional weight reduction.
- Bags:Flexible barrier pouches incorporate moisture vapor transmission rate specifications for pharmaceutical and food-grade applications.
Volume sits with corrugated fiberboard; growth tilts toward engineered foam systems.
Material:
Regulatory pressure on recovery quotas is restructuring raw material procurement across converter networks.
- Plastic:Polyethylene films and expanded polystyrene dominate electronics and appliance protection. SEMARNAT extended producer responsibility frameworks force reformulation toward post-consumer recycled content without degrading performance specifications.
- Paper:Recycled-content corrugated medium and linerboard anchor sustainable packaging claims for export-oriented manufacturers. Colombia's Ministry of Environment certification pathways accelerate paper-based substitution in EU-bound shipments.
- Bio-based:Molded fiber and starch-based cushioning gain traction among medical device distributors responding to retailer sustainability scorecards.
- Metal:Aluminum barrier laminates retain niche positioning in pharmaceutical cold-chain applications requiring thermal reflection.
Plastic retains volume leadership; bio-based materials climb the fastest on regulatory tailwinds.
End User:
Supply chain handling intensity and product value density determine protection investment levels.
- E-commerce:Automated fulfillment networks across São Paulo and Mexico City drive procurement of lightweight, right-sized cushioning systems. Last-mile damage rates dictate air-cushioning and corrugated insert specifications.
- Pharmaceuticals:Temperature-sensitive biologics distribution commands rigid insulated packaging with phase-change material integration. Brazil's ANVISA mandates elevate barrier-performance requirements for primary and secondary packaging layers.
- Consumer Electronics:Guadalajara assemblers specify anti-static foam and corrugated combinations for smartphone and laptop export.
- Food & Beverage:Moisture-resistant corrugated and insulated shippers protect perishable exports through fragmented cold-chain infrastructure.
E-commerce captures current volume expansion; pharmaceuticals offer the steepest margin capture.
Packaging Type:
Structural rigidity requirements separate commodity from premium protective applications.
- Rigid Packaging:Molded pulp, expanded polystyrene coolers, and engineered foam inserts protect high-value pharmaceuticals and electronics. Thermal insulation performance commands premium pricing in cold-chain logistics.
- Flexible Packaging:Air pillows, bubble films, and padded mailers reduce dimensional weight for consumer goods fulfillment. Automated inflation systems penetrate electronics distribution centers.
- Dieline Packaging:Custom-cut corrugated inserts with integrated cushioning zones serve automotive and appliance manufacturers seeking exact fit protection.
- Others:Suspension packaging and inflatable dunnage systems address irregular geometry protection for industrial equipment.
Rigid formats concentrate margin; flexible systems expand most quickly on e-commerce penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Manaus Free Trade Zone tax incentives concentrate electronics assembly operations, driving specialized foam and anti-static packaging procurement from regional converters.
Brazil
ANVISA pharmaceutical serialization mandates elevate barrier-performance specifications for temperature-sensitive drug distribution across São Paulo and Rio de Janeiro medical corridors. The regulator's traceability requirements force secondary packaging upgrades for export-oriented manufacturers. São Paulo's electronics assemblers specify anti-static foam systems for smartphone component protection.
Mexico
SEMARNAT extended producer responsibility frameworks tighten plastic recovery quotas for automotive suppliers operating near Querétaro and Tijuana manufacturing clusters. The environmental regulator's compliance deadlines accelerate converter investment in mechanically recycled content streams. Guadalajara's consumer electronics distributors consolidate procurement into multi-year framework agreements with performance specifications.
Colombia
The Ministry of Environment's bio-based certification pathways reshape material selection for export-oriented manufacturers serving EU sustainability scorecards. Bogotá-based converters pivot toward molded fiber and starch-based cushioning systems. Medellín's textile and appliance exporters adopt paper-based substitution strategies for European-bound shipments.
Argentina
Automotive parts manufacturers in Córdoba and Buenos Aires provinces require engineered corrugated protection for just-in-time delivery to Brazilian assembly plants. The national industrial promotion agency's export financing programs support packaging material localization. Rosario's agricultural machinery sector drives demand for heavy-duty dunnage systems.
Chile
Pharmaceutical cold-chain logistics operators in Santiago's distribution corridor invest in rigid insulated packaging with phase-change material integration for biologics export. The national pharmaceutical regulator enforces temperature integrity standards for sea-air multimodal shipments. Valparaíso port modernization expands automated handling capacity for temperature-controlled cargo.
Latin America Protective Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Latin America's protective packaging value chain. The market structure tilts toward consolidation among integrated paperboard producers while foam fabrication remains fragmented across regional converters. Two strategic archetypes dominate: multinational material science platforms with captive resin supply and mid-cap specialists with vertical control over molding operations. Competitive intensity centers on backward integration into recycled feedstock streams and geographic proximity to automotive and pharmaceutical clusters.
Among North American-based material science platforms, Sealed Air Corporation and Sonoco Products Company exemplify the multinational archetype with regional foam fabrication and molded fiber capabilities. Smurfit Kappa Group anchors the integrated paperboard tier through mill ownership in Colombia and Brazil. These three occupy positions spanning the corrugated, foam, and fiber-based protection segments without overlapping specialization claims.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Sonoco Products Company |
| Smurfit Kappa Group |
| Intertape Polymer Group Inc. |
| Crown Holdings Inc. |
| International Paper Company |
| Huhtamaki Group |
| Storopack Hans Reichenecker GmbH |
| WestRock Company |
| Others |
Supply & Pricing Matrix
Automotive OEMs and pharmaceutical distributors in Brazil and Mexico anchor protective packaging procurement through multi-year framework agreements that compress spot-market liquidity and elevate contract-based pricing power for integrated converters. This buyer concentration forces regional foam and corrugated suppliers into performance-specification bidding rather than commodity volume competition, with ANVISA compliance tiers and SEMARNAT recovery quotas acting as non-negotiable price floors.
Pricing Analysis
Short lead-time premiums of 15-25% above standard contract rates apply to just-in-time automotive orders from Querétaro and Tijuana clusters, while spot inventory discounts emerge for bulk corrugated purchases during Brazil's harvest export lulls. Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-certified pharmaceutical barrier systems from general industrial foam and commodity bubble wrap. Cost compression in polyethylene foam is intensifying because resin feedstock volatility transfers directly to converter margins. E-commerce fulfillment centers exhibit highest price sensitivity due to dimensional weight optimization mandates, while cold-chain pharmaceutical buyers show lowest sensitivity given thermal performance non-negotiability.
Supply Chain Analysis
Polyethylene resin supply rests on petrochemical complexes in Brazil, Mexico, and the US Gulf Coast, with integrated paperboard fiber sourcing anchored in Colombia and Brazil. Molded fiber pulp feeds from Chilean and Brazilian forestry operations, while specialty foam chemicals draw from German and Japanese additive suppliers. Single-source vulnerability concentrates in Colombia's integrated linerboard mills, where capacity constraints during peak agricultural export windows propagate downstream. Distribution runs through converter-owned warehousing near São Paulo, Mexico City, and Bogotá, with third-party logistics penetration rising for last-mile e-commerce fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
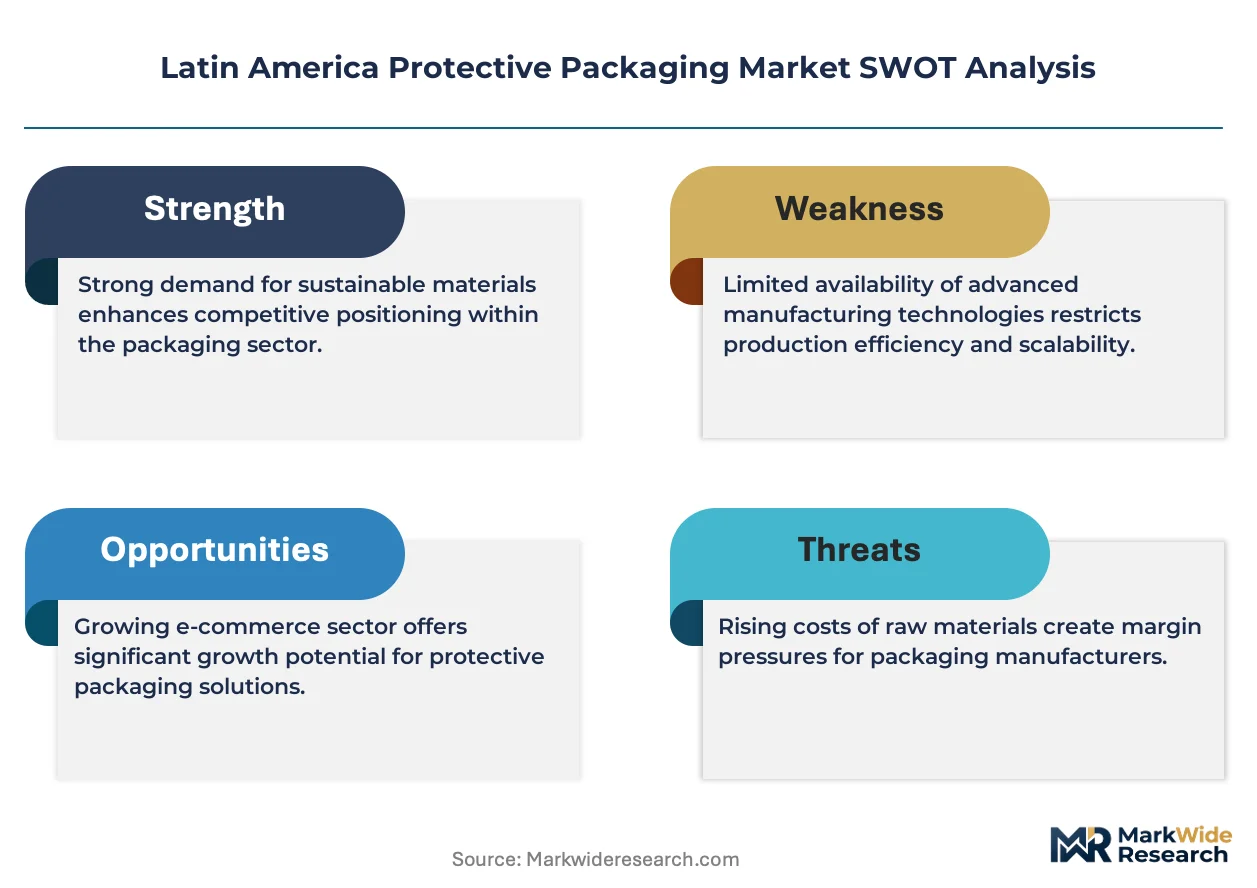
Latin America's protective packaging market operates under supply-constrained conditions where integrated paperboard mill capacity in Colombia and Brazil props pricing power for corrugated converters serving automotive and pharmaceutical corridors.
For Market Incumbents: Deepen backward integration into recycled polyethylene feedstock streams to insulate foam margins from petrochemical volatility and SEMARNAT compliance cost uncertainty. Secure multi-year offtake agreements with Guadalajara electronics assemblers before competitor capacity additions in Mexico's Bajío region erode pricing power. ANVISA serialization mandate upgrades present a defensive moat against commodity foam importers lacking barrier-performance certification capabilities. For New Entrants and Emerging Players: Colombia's Ministry of Environment bio-based certification pathways open a window for molded fiber specialists to capture EU-bound export manufacturer contracts ahead of incumbent converter retooling. Target Bogotá and Medellín textile exporters with starch-based cushioning alternatives to plastic dunnage, leveraging sustainability scorecard pressure from European retailers. A technical partnership with established pulp suppliers accelerates certification timeline versus greenfield mill investment. For Investors and Strategic Acquirers: The window for entry favors mid-cap foam fabricators with captive molding operations and geographic proximity to Mexico's automotive supplier corridor. Long-term viability hinges on converter ability to serve dual regulatory compliance across Mercosur and Pacific Alliance jurisdictions without parallel product platform duplication. Watch SEMARNAT enforcement intensity on plastic recovery quotas as the inflection indicator for bio-based material substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstock | SEMARNAT recovery quotas force converter investment in mechanically recycled polyethylene streams without performance degradation. |
| Multi-Year Framework Agreement Consolidation | Guadalajara electronics assemblers and São Paulo pharmaceutical distributors are replacing spot purchasing with engineered cushioning contracts. |
| Bio-Based Certification Pathway Investment | Colombia's Ministry of Environment frameworks enable first-mover positioning for EU-bound export manufacturers. |
| Cold-Chain Thermal Performance Specialization | ANVISA temperature integrity standards for biologics distribution command premium pricing in rigid insulated packaging. |
| Automotive Corridor Proximity Expansion | Querétaro and Tijuana just-in-time delivery requirements favor regional foam fabrication over centralized production. |
Research Methodology
Multi-period observation of converter capacity utilization, resin import volumes, and pharmaceutical serialization compliance rates anchored the trend analysis, supplemented by interviews with plant managers at integrated paperboard mills, procurement leads at automotive Tier 1 suppliers, distribution channel partners in São Paulo and Mexico City, and regulatory affairs directors navigating ANVISA and SEMARNAT frameworks. Secondary validation drew from customs trade data on polyethylene and corrugated fiberboard flows, ANVISA serialization compliance bulletins, SEMARNAT extended producer responsibility reporting, and SEC 10-K disclosures from multinational packaging platforms. Bottom-up demand modeling across end-use segments triangulated against top-down macroeconomic projections.
Segment-weighting approaches distributed total market value across product type, material composition, end-user vertical, and packaging format dimensions, with regional regulatory cluster exposure acting as an additional modeling layer. CAGRs were derived from fitted growth curves applied to segment-level baseline values, incorporating e-commerce penetration trajectories, automotive production forecasts, and pharmaceutical cold-chain expansion assumptions throughout the forecast period. Industry-specific inputs included ANVISA mandate implementation timelines and SEMARNAT enforcement intensity scenarios.
Caveats apply where resin price volatility spikes, regulatory enforcement delays, or recycling infrastructure buildout shortfalls could materially shift the outlook. Forecasts embed assumptions on trade policy continuity within Mercosur and Pacific Alliance frameworks. A small set of named triggers—SEMARNAT quota tightening velocity, ANVISA barrier specification updates, and integrated mill capacity expansion announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Packaging and Protective Packaging Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Insulated Shipping Boxes Market
Protective Packaging
Molded Fiber Pulp Edge Protectors Market
Protective Packaging
Asia-Pacific Protective Packaging Market
Protective Packaging
Thermal Insulated Mailers Market
Protective Packaging
North America Protective Packaging Market
Protective Packaging
Insulated Packaging Market
Protective Packaging
Fiber Cushioning Market
Protective Packaging
Static Shielding Bags Market
Protective Packaging
Middle East and Africa Protective Packaging Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Protective Wrapping Paper Market
Protective Packaging
Padded Dividers Market
Protective Packaging
Foam Mesh Sleeves Market