
 Insulated Styrofoam Shipping Boxes Market | 2026-2036
Insulated Styrofoam Shipping Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Styrofoam Shipping Boxes Market Foresight
North American expanded polystyrene producers is recalibrating capacity allocation toward pharmaceutical-grade insulation as temperature-sensitive logistics tighten. Sonoco ThermoSafe leverages its integrated foam molding and testing infrastructure to dominate validated cold-chain packaging lanes. Cold Chain Technologies anchors its position through reusable box programs that reduce per-shipment material costs for high-volume biologics distributors.
Insulated Styrofoam shipping boxes are rigid thermal containers fabricated from expanded polystyrene foam with wall densities typically ranging from 1.0 to 2.0 pounds per cubic foot, engineered to maintain internal temperatures between 2°C and 8°C for 48 to 96 hours using gel-pack or phase-change refrigerants. Their primary purpose is protecting temperature-sensitive cargo—vaccines, biologics, fresh proteins, and diagnostic reagents—from ambient thermal excursions during ground and air transit. Custom boxes command premium positioning because pharma clients require exact dimensional fits for palletized airfreight and automated packing lines, while disposable boxes dominate e-commerce food delivery where reverse logistics costs erode reusable economics. Reusable boxes are gaining fastest in European logistics corridors where circular-packaging mandates and return-loop infrastructure mature.
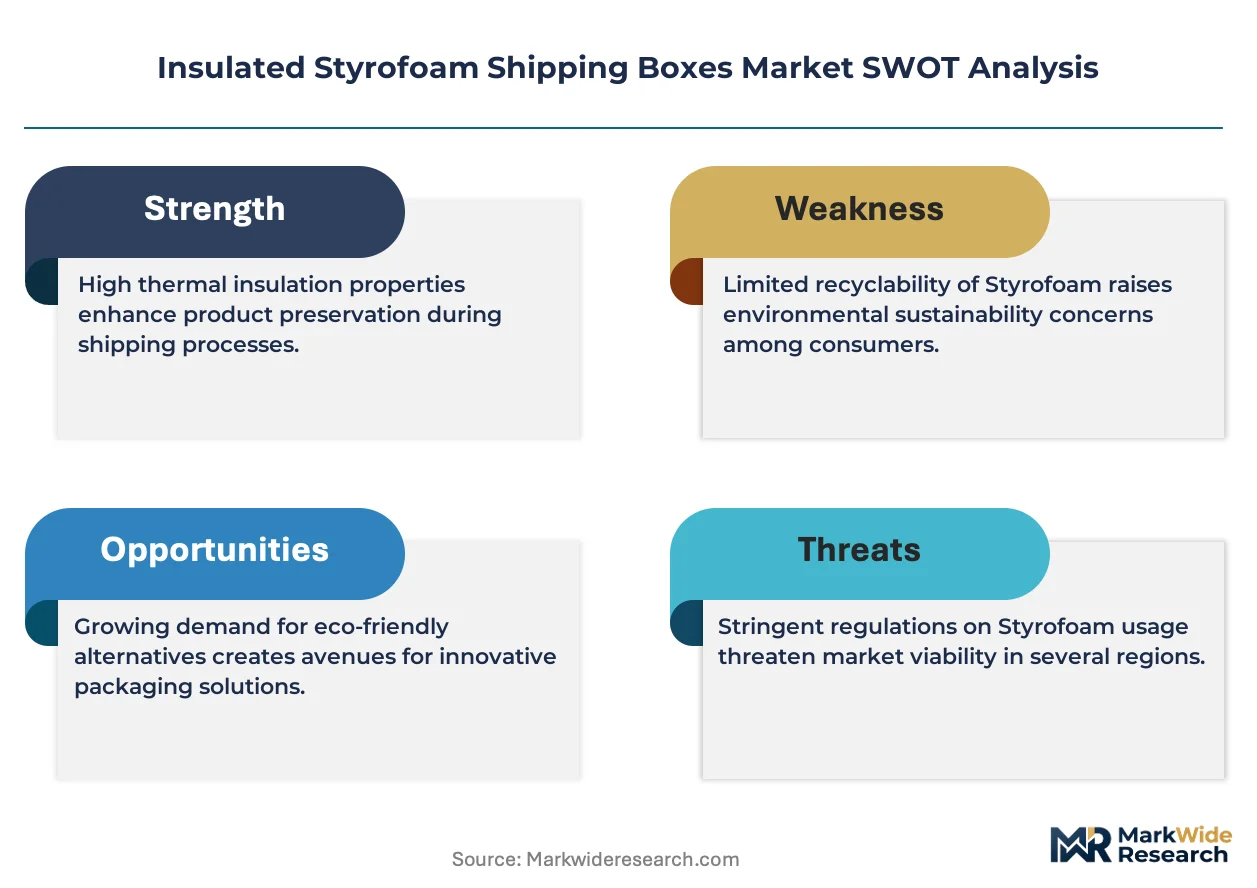
The US FDA, EMA, and IATA's CEIV Pharma certification collectively shape product standards by mandating documented thermal validation, qualification protocols, and chain-of-custody traceability for temperature-controlled shipments. REACH restrictions on styrene monomer residuals and emerging state-level EPS bans in California and New York are forcing reformulation toward recycled-content or alternative insulation substrates. Stakeholders must monitor regulatory divergence between federal permissiveness and state-level material restrictions when planning long-term capacity investments and resin sourcing strategies.
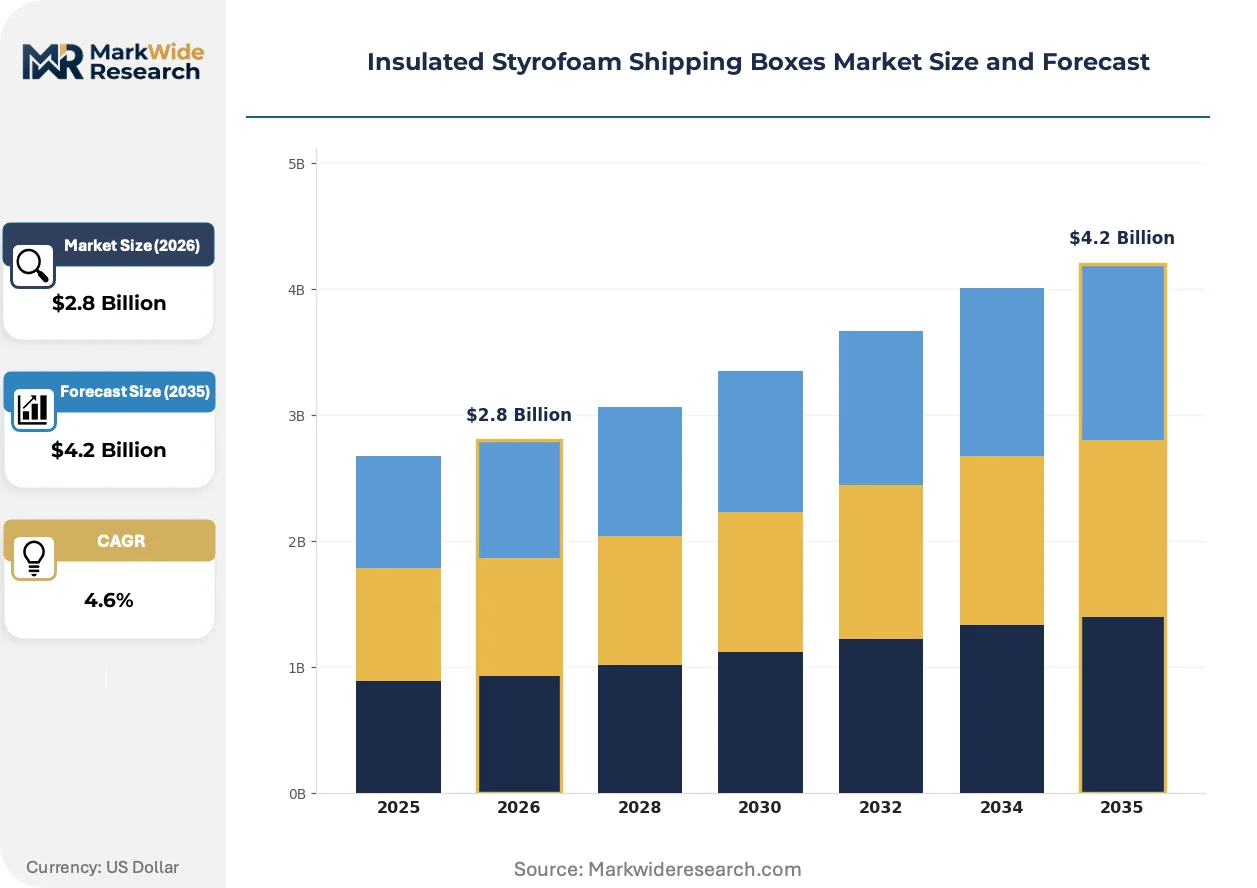
Market Dynamics
Pharmaceutical cold-chain logistics is tightening thermal-performance requirements as biologics and mRNA therapies multiply temperature-sensitive shipment volumes. This demand compression is forcing expanded polystyrene manufacturers to recalibrate resin formulations and wall-density specifications toward validated 2°C-to-8°C stability windows.
Growth Catalysts
- EMA cold-chain protocols:European Medicines Agency qualification standards for temperature-controlled packaging are mandating documented thermal validation across central European pharma manufacturing clusters. German distributors are expanding procurement of certified insulated boxes to maintain compliance with cross-border shipment requirements.
- Biologics distribution networks:Cell and gene therapies requiring strict cold-chain custody are multiplying point-to-point shipment lanes. Insulated Styrofoam containers with phase-change refrigerants are capturing volume from passive cooling alternatives in high-value therapeutic segments.
- Gel-pack integration advances:Engineered eutectic solutions are extending stable temperature maintenance from 48 hours toward 96-hour durations. This capability expansion is opening intercontinental airfreight corridors previously requiring active temperature-controlled containers.
Market Restraints
- Styrene monomer volatility:Feedstock price swings in benzene and ethylene derivatives are compressing margin predictability for expanded polystyrene molders. Producers lack long-term hedging instruments for petrochemical input exposure.
- California and New York EPS prohibitions:State-level bans on single-use expanded polystyrene are fragmenting addressable market geography. Manufacturers face stranded capacity risk in coastal manufacturing facilities serving food-service and e-commerce segments.
- Plant fiber insulation substitution:Molded pulp and mycelium-based thermal packaging are capturing share in meal-kit and fresh-protein delivery where 24-hour protection suffices. These alternatives bypass regulatory scrutiny targeting petroleum-derived foams.
Strategic Opportunities
- Reusable box programs:Circular-packaging mandates in European logistics corridors are creating infrastructure for return-loop container systems. Cold Chain Technologies and similar operators are deploying tracking-enabled boxes with deposit-based recovery models.
- India pharmaceutical exports:Central Drugs Standard Control Organization export certification requirements are expanding validated packaging demand from Indian generic manufacturers. Domestic molded-foam capacity remains underdeveloped relative to outbound cold-chain volume growth.
- Phase-change material convergence:Integration of bio-based phase-change materials with recycled-content polystyrene walls is enabling sustainability claims without sacrificing thermal performance. This formulation hybridization addresses REACH restrictions on virgin resin content.
Industry Challenges
- Thermal validation engineering capacity:Qualified packaging engineers capable of executing ISTA 7E and WHO PQS qualification protocols are concentrated among a handful of specialized consultancies. Box manufacturers face recruitment bottlenecks for in-house testing capability.
- Return-loop logistics coordination:Reusable container programs require reverse-shipment infrastructure that conflicts with just-in-time pharmaceutical distribution patterns. Third-party logistics providers resist absorbing cleaning and inspection costs without guaranteed volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Styrofoam Shipping Boxes Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Boxes, Custom Boxes, Disposable Boxes, Reusable Boxes End User: Pharmaceuticals, Food & Beverage, E-Commerce, Logistics Application: Temperature-Sensitive Goods, perishable Items, Electronics, Chemicals Distribution Channel: Online Retailers, Wholesale Distributors, Direct Sales, Supermarkets |
| Companies Covered | Sonoco ThermoSafe, Cold Chain Technologies, Cryopak, TemperPack, Pelican BioThermal, Softbox Systems, Intelsius, Exeltainer, Therapak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Styrofoam Shipping Boxes Market Shifts & Advancements
Material science advances and regulatory stringency are converging to reshape insulated container specifications. Manufacturers are racing to satisfy pharmaceutical-grade thermal validation while navigating petrochemical substitution pressures.
Vacuum-insulated panel technology is expanding into pharmaceutical cold-chain applications previously dominated by expanded polystyrene. Biologics distributors with high-value cargo are adopting VIP-composite boxes for 120-hour temperature stability in intercontinental shipments. This thermal performance extension is compressing demand for active temperature-controlled airfreight containers on trans-Pacific lanes.
REACH restrictions on styrene monomer residuals are forcing reformulation toward recycled-content substrates across European manufacturing. ECHA enforcement of Substance of Very High Concern thresholds is disqualifying virgin polystyrene formulations from pharmaceutical packaging tenders. German and Swiss contract packagers are qualifying dual-source supply chains mixing post-industrial recycled content with bio-based phase-change materials.
Consolidated buying by specialty pharmacy distributors is compressing supplier negotiation cycles and unbundling after-sales validation support. Large biologics shippers are bringing thermal testing in-house while demanding per-unit pricing reductions from box manufacturers. This procurement concentration is most visible in United States distribution networks where three national specialty pharmacies control majority volume for temperature-sensitive therapies.
Insulated Styrofoam Shipping Boxes Market Segmentation
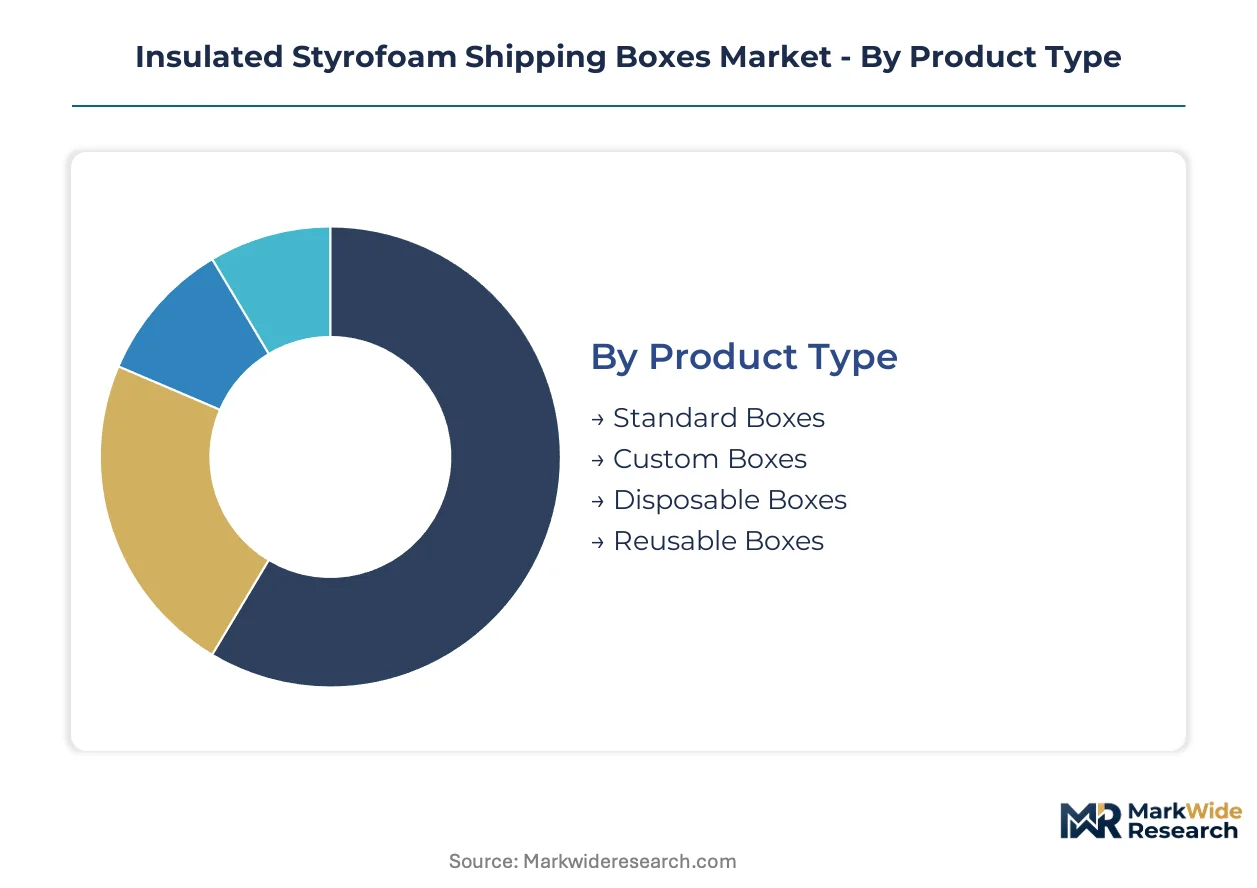
Segmentation in insulated Styrofoam shipping boxes reveals how thermal performance requirements diverge across custody-value tiers and logistics intensity. Product architecture, end-use specifications, and channel economics each reshape procurement patterns and margin structures for molders.
Product Type:
Customization intensity spans from commodity disposables to engineered reusables, with each tier demanding distinct resin formulations and validation protocols.
- Standard Boxes:Off-the-shelf dimensions with 1.0 to 1.5 PCF wall densities serve high-volume food distributors and generic pharma shipments. German cold-chain operators favor these for palletized airfreight where dimensional consistency enables automated packing line integration.
- Custom Boxes:Client-specified interior cavities and reinforced corner posts accommodate irregular biologics vial configurations and automated fulfillment robotics. Swiss contract packagers commission these for high-value cell therapies requiring exact gel-pack positioning.
- Disposable Boxes:Single-use expanded polystyrene containers dominate meal-kit delivery and fresh-protein e-commerce where reverse logistics costs exceed material value. California's EPS prohibitions are compressing addressable geography for this segment.
- Reusable Boxes:Trackable containers with deposit-based recovery models capture volume in European circular-packaging corridors. Cold Chain Technologies and similar operators deploy RFID-enabled units for high-frequency biologics lanes.
Leading the category by volume: Standard Boxes. Expanding most quickly: Reusable Boxes.
End User:
Regulatory stringency and cargo value create sharp demand stratification across custody-sensitive industries.
- Pharmaceuticals:Validated 2°C-to-8°C stability windows for vaccines, biologics, and diagnostic reagents require ISTA 7E qualification documentation. EMA protocols and FDA guidance drive procurement of certified containers with phase-change refrigerant integration.
- Food & Beverage:Fresh proteins, dairy, and specialty ingredients demand 48-hour thermal protection without pharmaceutical-grade validation. Gel-pack configurations here prioritize cost efficiency over extended duration.
- E-Commerce:Direct-to-consumer meal kits and perishable subscriptions favor lightweight disposables with 24-hour protection windows. Last-mile density and packaging waste regulations reshape regional channel viability.
- Logistics:Third-party cold-chain providers maintain mixed fleets serving multiple custody tiers. These operators balance reusable asset utilization against customer-specific validation requirements.
Dominant by revenue: Pharmaceuticals. Gaining share fastest: E-Commerce.
Application:
Thermal excursion tolerance and cargo value determine insulation density and refrigerant pairing.
- Temperature-Sensitive Goods:Vaccines, insulin, and biologics mandate strict 2°C-to-8°C custody with documented chain-of-custody traceability. WHO PQS qualification protocols govern container selection for international health program shipments.
- Perishable Items:Fresh produce, seafood, and floral products accept broader temperature bands in exchange for cost minimization. Gel-pack configurations here emphasize weight reduction over precision.
- Electronics:Semiconductor components and precision instruments require protection against thermal shock rather than narrow temperature maintenance. Anti-static coatings and vibration damping accompany insulation in this niche.
- Chemicals:Laboratory reagents and industrial compounds with temperature-dependent stability profiles need container compatibility verification. REACH substance restrictions influence resin selection for European chemical shipments.
Highest validation burden: Temperature-Sensitive Goods. Steepest expansion trajectory: Perishable Items.
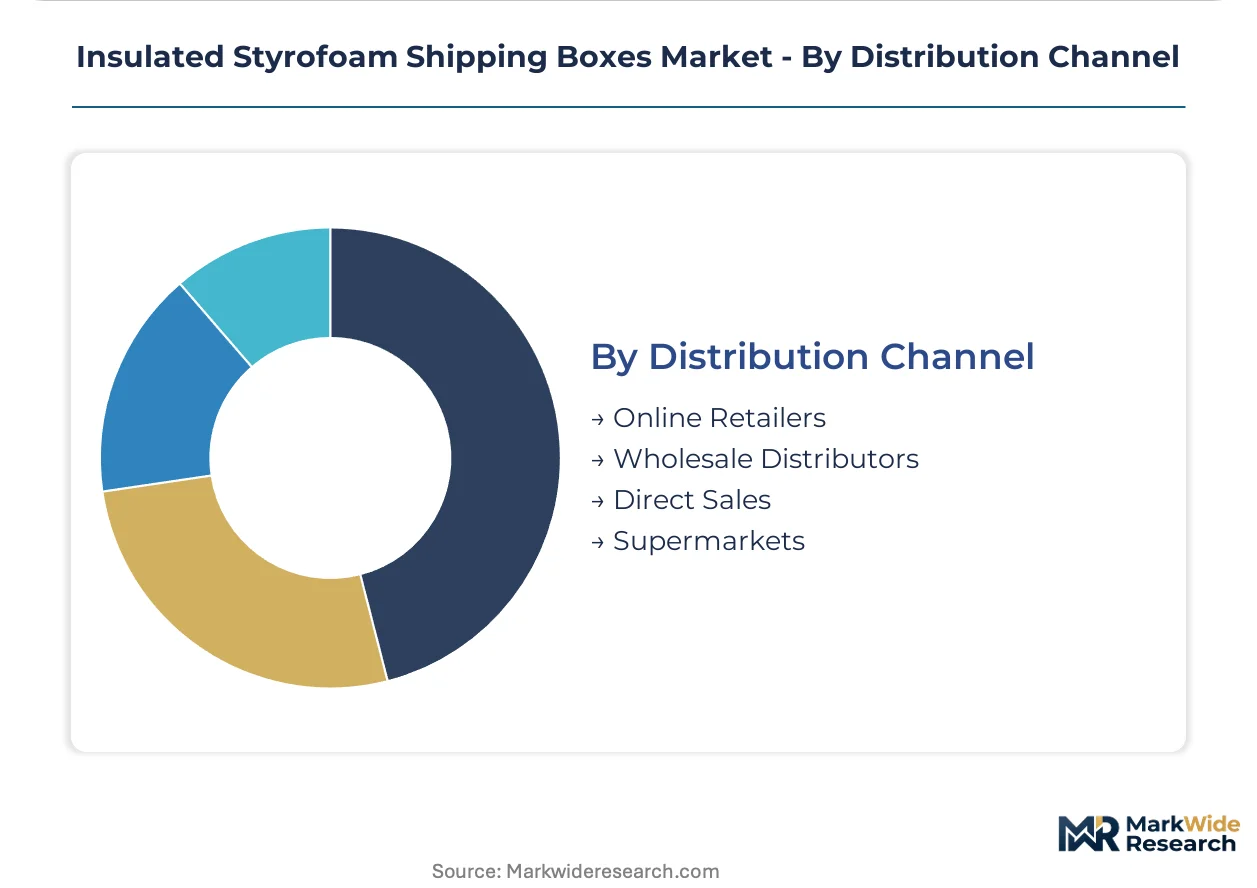
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and geographic coverage needs.
- Online Retailers:Digital procurement platforms aggregate small-lot orders from regional food distributors and independent pharmacies. These channels emphasize rapid fulfillment and standardized specifications over customization.
- Wholesale Distributors:Regional logistics specialists maintain inventory for same-day delivery to cold-chain operators and food-service networks. Technical consultation and after-sales validation support differentiate these relationships.
- Direct Sales:Large biologics manufacturers negotiate multi-year contracts with molders for validated container programs. These arrangements include dedicated engineering resources and thermal testing collaboration.
- Supermarkets:Grocery chains with private-label meal-kit operations procure disposables through centralized purchasing. Volume commitments and sustainability scoring influence supplier selection.
Capturing majority volume: Wholesale Distributors. Climbing the fastest: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in the US Gulf Coast and North Sea basin anchors expanded polystyrene manufacturing clusters. German chemical parks and Louisiana resin corridors supply molding operations serving pharmaceutical cold-chain networks. Regulatory divergence between federal standards and state-level material bans fragments procurement geography.
United States
FDA temperature-controlled packaging guidance and biologics distribution expansion drive demand for validated containers. California and New York EPS prohibitions compress disposable box addressability in coastal markets. Houston-Galveston petrochemical corridors feed molding operations supplying domestic pharma logistics.
Germany
EMA cold-chain protocols and central European pharma manufacturing clusters sustain procurement pull for certified insulated boxes. REACH restrictions on styrene monomer residuals force reformulation toward recycled-content substrates. Frankfurt-Rhine-Main logistics hubs concentrate contract packaging operations qualifying dual-source supply chains.
India
CDSCO export certification requirements and generic pharmaceutical outbound growth expand validated packaging demand. Domestic molded-foam capacity remains underdeveloped relative to cold-chain volume expansion. Mumbai-Pune pharmaceutical corridors drive procurement of temperature-stable containers for international shipments.
Switzerland
Swissmedic qualification standards and high-value cell therapy distribution tighten thermal-performance requirements. Bio-based phase-change material integration advances in Basel-Zurich manufacturing zones. Alpine logistics corridors prioritize reusable container programs with deposit-based recovery models.
China
NMPA biologics approval acceleration and domestic vaccine distribution network expansion multiply temperature-sensitive shipment volumes. Yangtze River Delta molding clusters scale pharmaceutical-grade insulation capacity. Shanghai cold-chain infrastructure investments support intercontinental airfreight container demand.
Insulated Styrofoam Shipping Boxes Market Competitive Landscape
Global majors compete with regional champions across thermal validation capabilities and circular-packaging infrastructure. The vendor base stratifies into three tiers: integrated packaging conglomerates with foam molding and testing infrastructure, specialized cold-chain container operators with reusable asset programs, and regional molders serving food-service and e-commerce disposables. Consolidation pressure concentrates among mid-cap specialists lacking in-house qualification engineering. Dominant competitive moves include backward integration into resin formulation and geographic expansion through distribution partnerships.
Among integrated packaging specialists, Sonoco ThermoSafe and Cold Chain Technologies exemplify divergent strategic archetypes. Sonoco ThermoSafe occupies a position representing captive foam molding and thermal testing infrastructure. Cold Chain Technologies anchors the reusable container segment with tracking-enabled deposit-recovery systems. Cryopak sits within the mid-tier specialist category, occupying a position between integrated conglomerates and regional disposables manufacturers.
| Leading Market Players |
|---|
| Sonoco ThermoSafe |
| Cold Chain Technologies |
| Cryopak |
| TemperPack |
| Pelican BioThermal |
| Softbox Systems |
| Intelsius |
| Exeltainer |
| Therapak |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists in North American expanded polystyrene molding have compressed supplier counts across pharmaceutical-grade insulation tiers, tightening pricing discipline while concentrating resin procurement leverage. This ownership pattern feeds directly into supply behavior: fewer independent molders negotiate benzene derivative contracts collectively, and pricing power shifts toward buyers with multi-year validated container programs.
Pricing Analysis
Warranty and thermal validation service bundling separates premium container pricing from commodity disposable tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ISTA 7E qualification documentation inclusion versus bare per-unit transactions. Price differentiation hinges on certification grade and volume scale, with large biologics shippers extracting per-unit reductions by bringing testing in-house. Pricing pressure stems from consolidated specialty pharmacy buying power. E-commerce food distributors show highest price sensitivity; validated pharma buyers accept premium positioning.
Supply Chain Analysis
Workforce availability constraints in German chemical parks and Louisiana resin corridors are pushing molding capacity toward automated production lines. Supply concentrates in the United States, Germany, and China, with Houston-Galveston and Yangtze River Delta clusters feeding pharmaceutical cold-chain networks. Raw material dependencies center on benzene derivatives, ethylene feedstocks, and engineered eutectic gel formulations. Single-source vulnerability in phase-change refrigerant chemistry creates exposure. Distribution runs through wholesale distributors with regional inventory positions, though direct sales channels are gaining share among large biologics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive resin formulation capabilities to hedge petrochemical input volatility and satisfy REACH recycled-content mandates.
For Market Incumbents: Extend thermal validation engineering capacity through recruitment pipelines targeting ISTA-qualified consultants, insulating against qualified packaging engineer scarcity. Deepen backward integration into post-industrial recycled polystyrene sourcing to preempt ECHA Substance of Very High Concern disqualification. Defend position against vacuum-insulated panel substitution in intercontinental airfreight by emphasizing 48-to-96-hour phase-change reliability at lower unit economics.
For New Entrants and Emerging Players: Launch via digital procurement platforms aggregating small-lot orders from independent pharmacies and regional food distributors, bypassing entrenched wholesale relationships. Target India's underdeveloped molded-foam capacity relative to CDSCO-certified export growth, where domestic supply lags pharmaceutical cold-chain expansion. White-space exists in bio-based phase-change material integration with recycled-content walls, addressing sustainability procurement scoring without sacrificing thermal performance.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap molders with stranded California or New York capacity facing EPS prohibition headwinds, available at compressed multiples. Long-term viability favors operators with reusable container infrastructure in European circular-packaging corridors, where deposit-recovery models generate recurring revenue streams. Watch for IATA CEIV Pharma certification acceleration as inflection signal indicating consolidation appetite among third-party logistics providers seeking validated asset control.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin Sourcing | ECHA enforcement of SVHC thresholds is disqualifying virgin polystyrene from pharmaceutical tenders. |
| Reusable Container Program Expansion | European circular-packaging mandates are creating infrastructure for return-loop deposit-recovery models. |
| Thermal Validation Engineering Capacity Buildout | Qualified packaging engineers capable of ISTA 7E protocols are concentrated among specialized consultancies. |
| Geographic Manufacturing Footprint Shift | California and New York EPS prohibitions are compressing disposable box addressability in coastal markets. |
| Bio-Based Phase-Change Material Integration | REACH restrictions on styrene monomer residuals are forcing reformulation toward sustainability claims. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with thermal packaging engineers, cold-chain logistics directors, pharmaceutical procurement managers, and expanded polystyrene plant managers. Secondary sources included FDA temperature-controlled packaging guidance documents, EMA qualification standards, IATA CEIV Pharma certification records, ECHA REACH substance restriction databases, and customs trade flows for insulated container categories. Bottom-up volume modeling triangulated against top-down market sizing from petrochemical feedstock consumption patterns.
Granularity-level modeling operated at product type, end user, application, and distribution channel dimensions, with additional disaggregation by regional regulatory cluster and thermal performance tier. CAGRs were derived from regression analysis of historical shipment volumes against pharmaceutical cold-chain expansion indicators and biologics approval trajectories. Forecast inputs incorporated gel-pack integration advance timelines, reusable container program adoption curves, and state-level EPS prohibition implementation schedules.
Feedstock price volatility in benzene and ethylene derivatives, regulatory divergence between federal FDA guidance and state-level material bans, and vacuum-insulated panel technology cost curves are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about EMA protocol stability and circular-packaging mandate enforcement continuity. Material deviation in named triggers warrants pause and re-evaluation of capacity investment and resin sourcing strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Thermal Insulated Mailers Market
Protective Packaging
Thermal Insulated Bubble Wrap Market
Protective Packaging
Insulated Packaging Market
Protective Packaging
Molded Fiber Pulp Edge Protectors Market
Protective Packaging
Middle East and Africa Protective Packaging Market
Protective Packaging
Static Shielding Bags Market
Protective Packaging
Corrugated Bubble Wrap Market
Protective Packaging
Void Fill Pillows Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Foam Mesh Sleeves Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Anti-Static Foam Packaging Market
Protective Packaging
North America Protective Packaging Market
Protective Packaging
Global Packaging Inserts and Cushions Market
Protective Packaging
Inflatable Packaging Market