
 Corrugated Bubble Wrap Market | 2026-2036
Corrugated Bubble Wrap Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Bubble Wrap Market Outlook
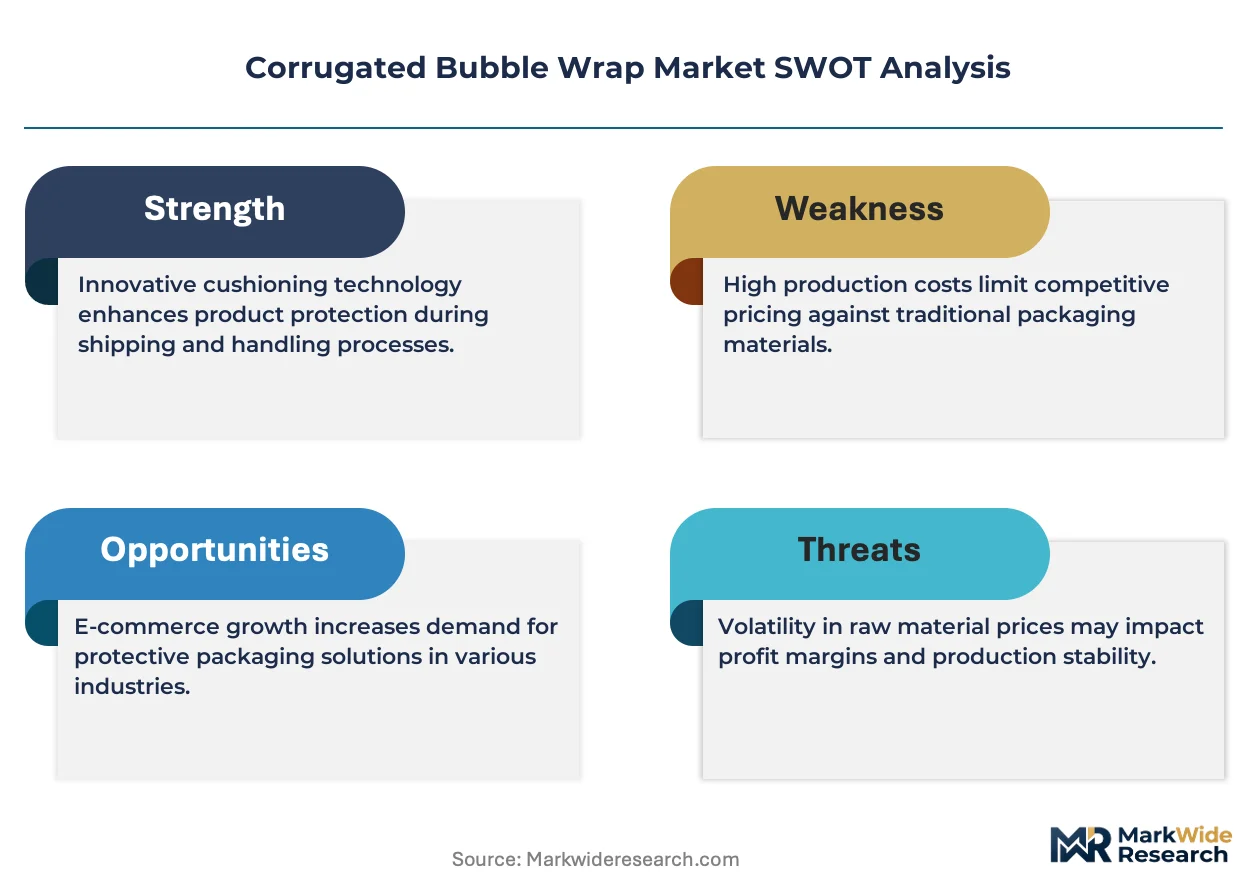
EU Packaging and Packaging Waste Regulation targets for recyclability is expanding the addressable market for corrugated bubble wrap as brand owners seek single-material protective solutions. Sealed Air Corporation leverages its R&D infrastructure to develop fiber-based cushioning architectures that align with extended producer responsibility mandates. Pregis LLC anchors North American supply through regional manufacturing scale and direct-to-fulfillment-center distribution networks.
Corrugated bubble wrap combines a fluted paperboard substrate with integrated air-cell cushioning layers, typically manufactured through lamination of kraft linerboard with extruded polyethylene bubble film to create a rigid yet shock-absorbing protective material for shipping fragile goods. Standard bubble wrap dominates unit volume across logistics applications, while anti-static variants command premium positioning in electronics manufacturing where electrostatic discharge protection determines material specification. Perforated formats sustain faster throughput in high-velocity e-commerce packing stations, reducing labor cost per package.
FDA guidelines for food-contact packaging materials and EPA recycled content requirements shape product formulation decisions for manufacturers serving dual-use industrial and consumer markets. REACH restrictions on persistent chemicals influence adhesive and coating selections in European supply chains, while ISO 18616 standards for transport packaging performance set baseline testing protocols. Stakeholders must monitor evolving extended producer responsibility fee structures to determine whether captive recycling infrastructure or third-party compliance services offer lower total cost of ownership.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles for protective packaging converters, forcing rapid migration from multi-material laminates toward single-substrate corrugated-bubble hybrids that satisfy extended producer responsibility mandates without performance degradation.
Growth Catalysts
- E-commerce fulfillment density:German automotive parts distributors specify corrugated-bubble hybrids for just-in-time delivery networks, creating specification pull through tier-one logistics providers.
- REACH compliance architecture:Persistent chemical restrictions on adhesives and coatings are eliminating competing foam-based alternatives, redirecting specification toward fiber-cushion architectures.
- Perforation technology:Inline micro-perforation systems reduce pack-station labor time by enabling tear-line dispensing without cutting tools, accelerating throughput at high-velocity fulfillment centers.
Market Restraints
- Kraft linerboard input volatility:Pulp price swings compress converter margins during contract-renewal windows, forcing pass-through negotiations with fulfillment-center buyers.
- Extruded polyethylene supply concentration:European bubble film production clusters in Benelux chemical corridors, creating geographic single-point vulnerability for laminated hybrid supply.
- Anti-static performance ceiling:Fiber-based substrates cannot match conductive foam dissipation rates for high-sensitivity semiconductor wafer transport, limiting addressable electronics verticals.
Strategic Opportunities
- Indian cross-border e-commerce:DGFT export-packaging compliance requirements for electronics and pharmaceuticals create specification entry points for certified corrugated-bubble suppliers.
- Food-contact certification:FDA guidelines for fiber-based cushioning in direct-contact applications open chilled meal-kit and specialty food subscription channels.
- Digital printing integration:Combined corrugated-bubble substrates with inline variable-data printing enable brand-owner unboxing experience customization without secondary label application.
Industry Challenges
- Adhesive formulation expertise:Water-based bonding chemistries that maintain fiber-to-film lamination integrity through humidity cycling require polymer science capabilities scarce among traditional paperboard converters.
- ISO 18616 certification timelines:Transport-packaging performance testing protocols demand 12-18 month validation cycles, delaying new product commercialization and locking incumbents into existing specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Bubble Wrap Market |
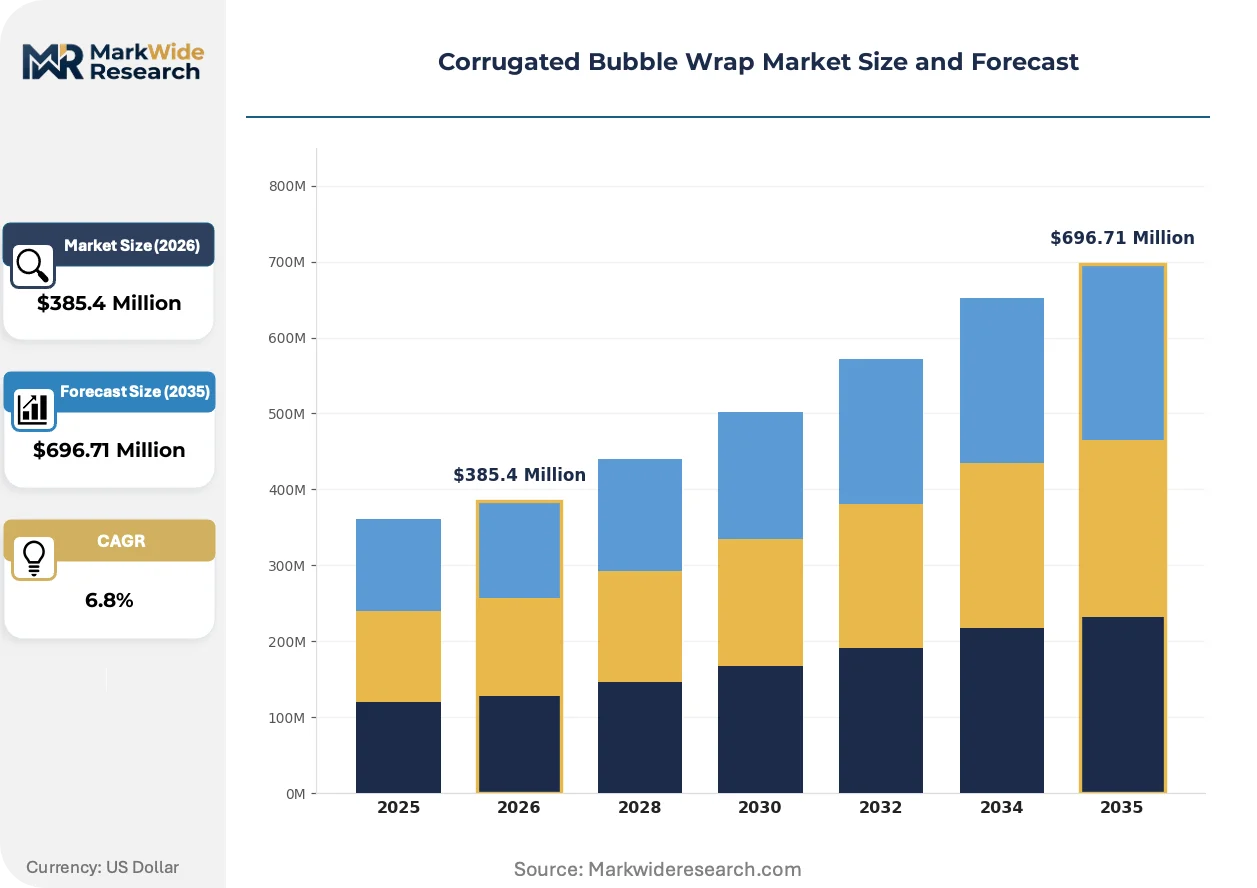
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bubble Wrap, Perforated Bubble Wrap, Anti-Static Bubble Wrap, UV-Resistant Bubble Wrap End User: Retail, E-Commerce, Manufacturing, Logistics Thickness: 3/16 Inch, 1/2 Inch, 5/16 Inch, 1/4 Inch Application: Packaging, Cushioning, Insulation, Void Fill |
| Companies Covered | Delux Packaging, Conitex Sonoco, Larsan Packaging Products, Western Container Corp., Cougar Packaging Solutions, Albert Paper Products, Alpha Packaging, Sealed Air Corporation, Pregis LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Bubble Wrap Market Strategic Shifts
Active material science development is collapsing the performance gap between fiber-based cushioning and synthetic alternatives, while regulatory pressure and fulfillment automation are reshaping how protective packaging is specified, procured, and deployed across logistics networks.
Micro-flute corrugation bonded to nano-cellular air retention layers is electrifying protective performance benchmarks for glassware and precision instrumentation. German appliance manufacturers are qualifying these hybrids for export crating replacement, eliminating wooden crate weight and customs treatment documentation. The technology is electrifying converter R&D allocation toward substrate-engineering capabilities that paperboard mills previously outsourced to film suppliers.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating oil-grease-resistant coatings from competing molded-fiber formats. Food-contact packaging specifications for meal-kit delivery are redirecting toward corrugated-bubble laminates with compliant water-based barriers. European cold-chain logistics providers are responding by consolidating supplier qualification around fiber-cushion architectures that satisfy both EFSA contact standards and ECHA substance restrictions.
Direct-to-fulfillment-center procurement contracts are displacing distributor-mediated purchasing for high-volume e-commerce packagers. Amazon, Zalando, and Otto Group operations in Poland and the Czech Republic are negotiating multi-year supply agreements with converters who co-locate slitting and perforation operations near sortation hubs. This concentration is most visible in Central European logistics corridors where last-mile density justifies dedicated packaging inventory programs.
Corrugated Bubble Wrap Market Segmentation
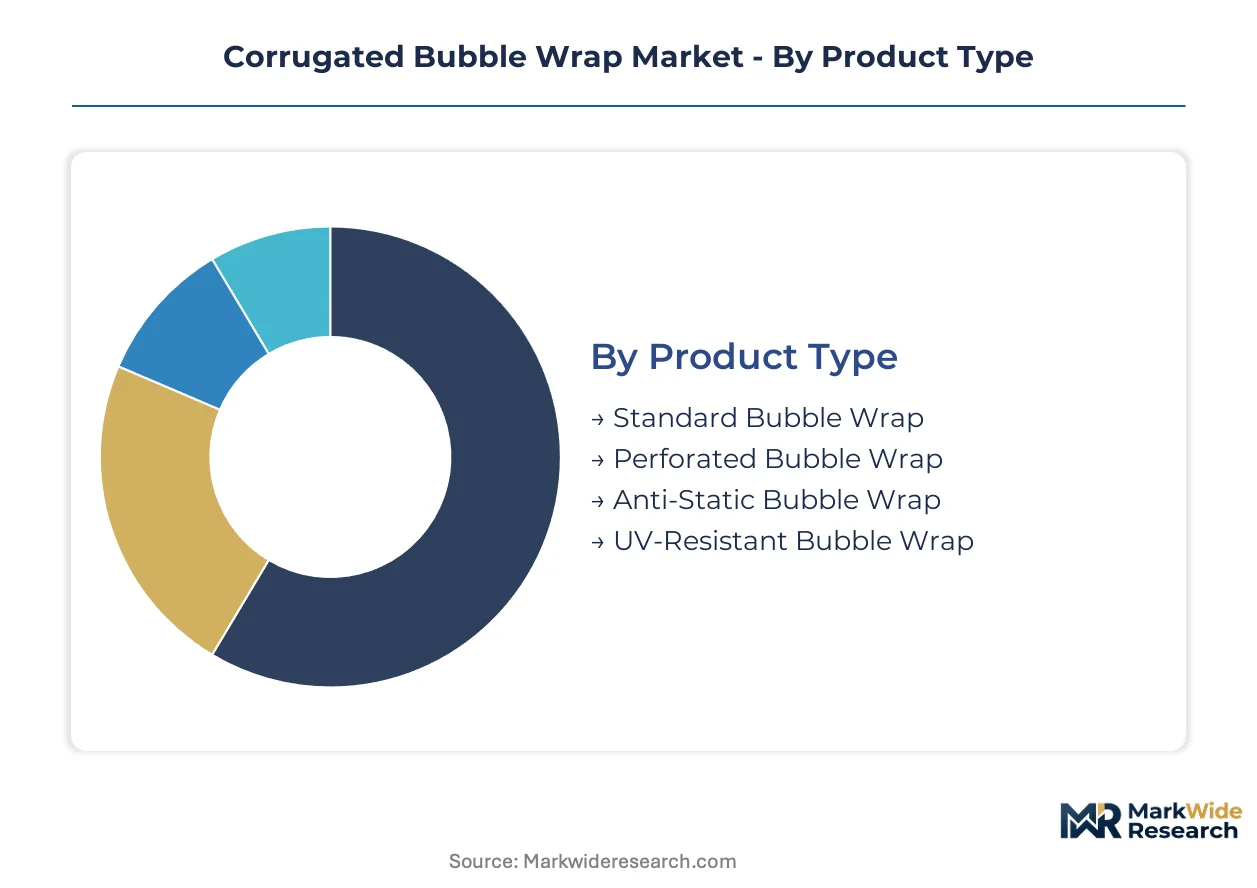
Corrugated bubble wrap specifications diverge sharply across fulfillment velocity, electrostatic sensitivity, and climate exposure. Converters align product architectures with distinct performance thresholds rather than commodity substitution.
Product Type:
Material engineering determines air retention, surface resistivity, and degradation resistance under mechanical stress.
- Standard Bubble Wrap:Kraft linerboard laminated with extruded polyethylene bubble film delivers baseline shock absorption for general merchandise. E-commerce fulfillment centers in Germany and Poland specify this format for high-velocity packing stations where throughput economics dominate material selection.
- Perforated Bubble Wrap:Inline micro-perforation creates tear-line dispensing without cutting tools, reducing pack-station labor time. Amazon and Zalando operations in Central Europe negotiate dedicated supply agreements for this format to accelerate throughput at sortation hubs.
- Anti-Static Bubble Wrap:Carbon-loaded polyethylene formulations dissipate electrostatic discharge for electronics manufacturing. REACH restrictions on persistent chemicals in competing foam alternatives redirect specification toward fiber-cushion architectures with compliant conductive coatings.
- UV-Resistant Bubble Wrap:Stabilized polyethylene layers retard photodegradation during extended outdoor storage. Agricultural equipment distributors in Spain and Italy specify this variant for export crating replacement.
Mature deployment sits with Standard Bubble Wrap. Newer deployment is concentrated in Perforated Bubble Wrap.
End User:
Procurement scale and specification authority vary dramatically across buyer categories.
- E-Commerce:Direct-to-fulfillment-center contracts displace distributor channels. Otto Group and Czech logistics consolidators negotiate multi-year supply agreements with converters co-located near last-mile hubs.
- Manufacturing:Automotive parts distributors in Germany specify corrugated-bubble hybrids for just-in-time delivery networks, creating specification pull through tier-one logistics providers.
- Logistics:Third-party packagers serving cross-border pharmaceutical exports require DGFT-compliant certification for Indian market entry.
- Retail:Store replenishment operations favor lower-unit-cost standard formats with less perforation investment.
Specification authority concentrates with E-Commerce. Margin compression is most severe in Retail.
Thickness:
Cell height directly maps to cushioning coefficient and material yield per square meter.
- 3/16 Inch:Micro-cellular architecture suits lightweight electronics and glassware where space efficiency trumps impact absorption.
- 1/2 Inch:Maximum loft configuration protects heavy industrial components and German appliance exports requiring wooden crate replacement.
- 5/16 Inch:Intermediate specification balances protection density with roll handling ergonomics for manual packing stations.
- 1/4 Inch:Versatile mid-range format dominates contract manufacturing where SKU variety precludes thickness specialization.
Volume leadership belongs to 1/4 Inch. Steepest expansion trajectory occurs in 1/2 Inch for export crating substitution.
Application:
Functional deployment determines lamination integrity requirements and barrier specifications.
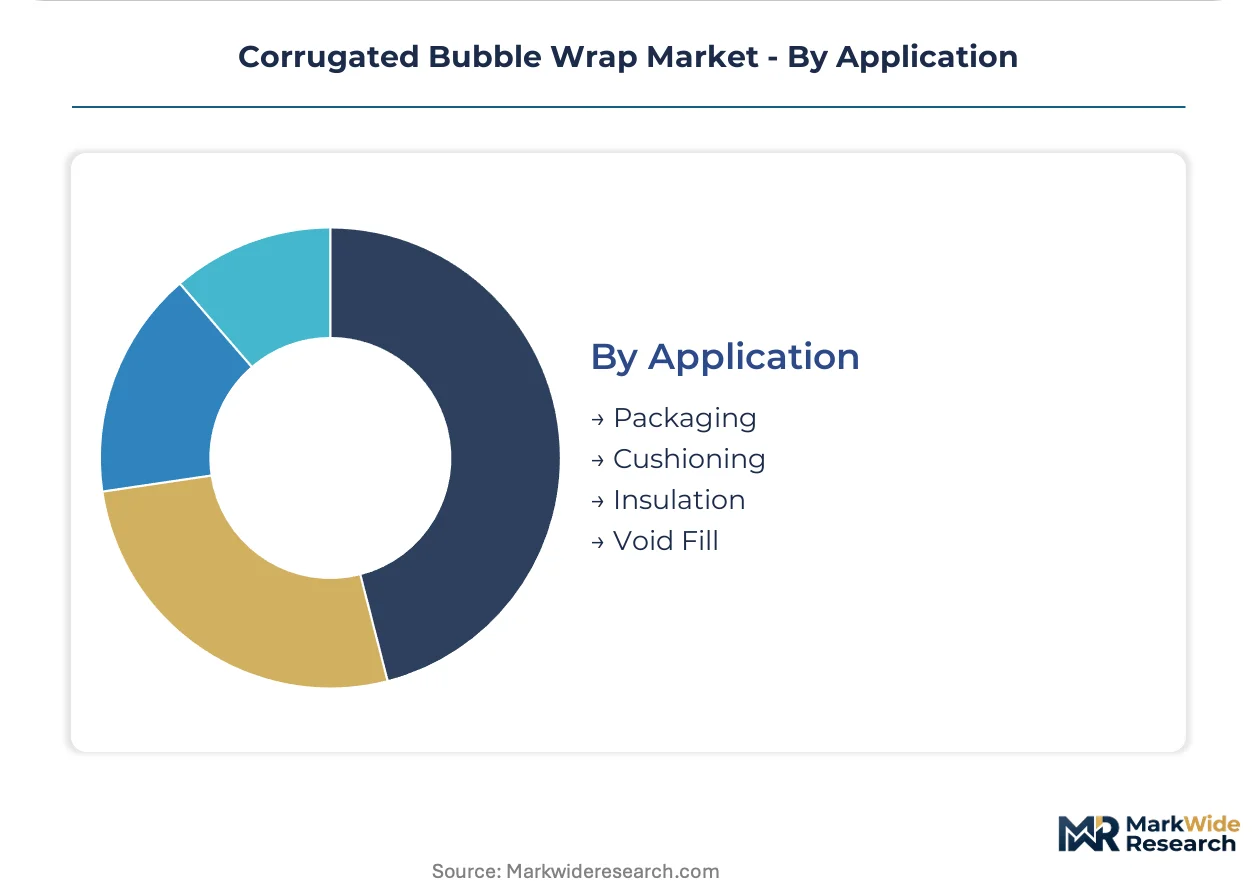
- Packaging:Primary containment function demands FDA-compliant water-based adhesives for food-contact meal-kit applications.
- Cushioning:Impact absorption specifications follow ISO 18616 transport packaging protocols with 12-18 month validation cycles.
- Insulation:Thermal resistance applications in European cold-chain logistics require EFSA contact standards plus ECHA substance compliance.
- Void Fill:Lowest-performance use case tolerates thinner substrates and higher recycled content ratios.
Regulatory complexity peaks in Packaging. Technical validation burden is heaviest in Cushioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr industrial corridor logistics hubs anchor European corrugated bubble wrap procurement, with fulfillment centers clustering around Dortmund and Duisburg to service just-in-time automotive parts distribution networks.
Germany
Automotive tier-one suppliers in Stuttgart and Wolfsburg specify corrugated-bubble hybrids for powertrain component exports. REACH restrictions on persistent chemicals in foam alternatives redirect specification toward fiber-cushion architectures. Bavarian packaging converters near Munich are qualifying micro-flute laminates for appliance export crating replacement.
United States
FDA food-contact guidelines drive meal-kit subscription packaging specifications toward water-based adhesive laminates. EPA recycled content requirements shape converter formulation decisions for dual-use industrial and consumer markets. Chicago-area fulfillment centers negotiate direct procurement contracts bypassing traditional distributor channels.
China
Cross-border e-commerce export zones in Shenzhen and Hangzhou demand DGFT-compliant protective packaging for electronics and pharmaceutical shipments. MIIT industrial standards for transport packaging performance accelerate ISO 18616 certification adoption. Yangtze River Delta converters are scaling slitting operations near Shanghai sortation hubs.
India
Pharmaceutical export corridors from Maharashtra and Gujarat require certified cushioning for temperature-sensitive drug shipments. BIS packaging standards and DGFT compliance mandates create specification barriers for uncertified suppliers. Mumbai-Pune logistics clusters are consolidating supplier qualification around fiber-cushion architectures.
Poland
Central European fulfillment density around Warsaw and Wrocław attracts converter co-location investments from German and Dutch suppliers. EU Packaging and Packaging Waste Regulation extended producer responsibility fees favor single-material substrates over multi-material alternatives. Silesian industrial zones are emerging as slitting and perforation capacity hubs for Amazon and Zalando operations.
Corrugated Bubble Wrap Market Competitive Environment
The competitive structure tilts toward diversified packaging conglomerates with integrated R&D infrastructure. Tier-one players leverage extended producer responsibility compliance expertise to secure multi-year direct procurement contracts from fulfillment-center operators. Three archetypes dominate: fiber-cushion specialists with lamination chemistry capabilities, diversified protective packaging multinationals with regional manufacturing scale, and regional converters with co-location proximity to logistics hubs. Dominant competitive moves include backward integration into kraft linerboard supply and captive perforation technology licensing.
Among North American protective packaging leaders, Sealed Air Corporation and Pregis LLC exemplify the diversified multinational archetype with established fulfillment-center distribution networks. Delux Packaging and Conitex Sonoco represent regional converter models with co-location strategies near high-velocity logistics corridors. These named entities anchor the competitive spectrum without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Delux Packaging |
| Conitex Sonoco |
| Larsan Packaging Products |
| Western Container Corp. |
| Cougar Packaging Solutions |
| Albert Paper Products |
| Alpha Packaging |
| Sealed Air Corporation |
| Pregis LLC |
| Others |
Value Chain & Pricing Dynamics
E-commerce fulfillment centers in Germany and Poland concentrate procurement authority, forcing converters toward contract-based long-term offtake structures that lock in volume commitments against kraft linerboard price volatility.
Pricing Analysis
Throughput-based pricing anchors converter-buyer negotiations, with pack-station labor savings from perforated formats commanding 15-20% premiums over standard laminates. Three-tier pricing structure across anti-static, perforated, and standard levels reflects certification grade and electrostatic performance differentiation. Cost compression in standard formats is intensifying because pulp price pass-through clauses trigger quarterly renegotiations. Retail replenishment operations exhibit highest price sensitivity, while automotive tier-one suppliers prioritize performance consistency over unit cost.
Supply Chain Analysis
Specialized adhesive chemists in German and Dutch manufacturing corridors face recruitment constraints, slowing lamination R&D scale-up for water-based bonding systems. Raw material flows draw from Benelux polyethylene extrusion clusters, Scandinavian kraft pulp mills, and regional coating chemical suppliers. Single-source vulnerability concentrates in bubble film production along the Rotterdam-Antwerp chemical corridor. Distribution runs through direct-to-fulfillment-center contracts that displace traditional wholesale channels near Warsaw and Prague logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adhesive formulation expertise scarcity props pricing power for converters with captive polymer science capabilities, as water-based lamination chemistry talent remains concentrated among German and Dutch specialists.
For Market Incumbents: Deepen backward integration into kraft linerboard supply through mill partnerships or captive pulp sourcing, insulating margin compression from spot market volatility. Secure ISO 18616 certification ahead of competitors to lock automotive and appliance export specifications before validation timelines extend further. Prioritize co-location investments near Czech and Polish sortation hubs where Amazon and Zalando procurement concentration accelerates. For New Entrants and Emerging Players: Indian pharmaceutical exporters represent an underserved buyer archetype with DGFT compliance requirements creating specification barriers for uncertified competitors. Target cross-border e-commerce corridors in Shenzhen and Hangzhou where MIIT standards adoption lags behind European REACH alignment. Pursue white-label manufacturing partnerships with established European converters to bypass 12-18 month certification timelines. For Investors and Strategic Acquirers: The window for entry favors regional converters with proven lamination chemistry capabilities and existing fulfillment-center relationships. Mid-cycle positioning around fiber-cushion specialists offers 5-10 year viability as extended producer responsibility fees reshape competitive economics. Monitor REACH restriction expansion on persistent chemicals as the inflection signal for accelerated foam substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Supply | Captive pulp sourcing insulates Sealed Air and Pregis from linerboard price volatility. |
| Micro-Perforation Technology Licensing | Inline tear-line systems reduce Amazon pack-station labor time without cutting tools. |
| Co-Location Near Sortation Hubs | Polish and Czech proximity investments capture Otto Group direct procurement contracts. |
| Anti-Static Coating R&D | Carbon-loaded formulations penetrate semiconductor packaging limited by fiber dissipation ceilings. |
| Food-Contact Certification Investment | FDA-compliant laminates unlock meal-kit subscription channels for chilled delivery applications. |
Study Parameters
Multi-period observation of e-commerce fulfillment center procurement volumes, pulp futures pricing, and REACH regulatory filing timelines anchored the trend analysis, supplemented by interviews with packaging converters, logistics procurement managers, and adhesive R&D directors. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, EPA recycled content guidance, customs trade data for corrugated materials, and SEC filings from protective packaging multinationals. Bottom-up shipment data triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrices modeled corrugated bubble wrap demand across product type, end-use vertical, thickness specification, and geographic production hub dimensions. CAGRs were derived from regression analysis of historical fulfillment center expansion rates and projected e-commerce penetration curves. Forecast inputs included automotive export volume trajectories from Stuttgart and Wolfsburg, and cold-chain logistics infrastructure buildout across European meal-kit delivery corridors.
Revisions become necessary when REACH restriction scope expands beyond per- and polyfluoroalkyl substances, or when kraft linerboard supply disruptions exceed historical volatility bands. Material deviation in these triggers warrants pause and re-evaluation of capacity expansion assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Static Shielding Bags Market
Protective Packaging
Paper Cushion Systems Market
Protective Packaging
Asia-Pacific Protective Packaging Market
Protective Packaging
Protective Wrapping Paper Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
Insulated Shippers Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
Anti-Corrosive Packaging Market
Protective Packaging
Insulated Packaging Market
Protective Packaging
Padded Dividers Market
Protective Packaging
Anti-Static Foam Packaging Market
Protective Packaging
Secondary Containment Trays Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Padded Mailers Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Fiber Cushioning Market