
 Bubble Wrap Packaging Market | 2026-2036
Bubble Wrap Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bubble Wrap Packaging Market Analysis
Aftermarket protective packaging services is tilting margin pools away from commodity film sales toward value-added fulfillment solutions. Sealed Air Corporation dominates inflatable barrier systems for high-velocity distribution centers. Pregis LLC specializes in on-demand air cushioning equipment that reduces warehouse storage requirements. Smurfit Kappa leverages its corrugated integration to bundle bubble wrap with box shipments for European e-commerce clients.
Bubble wrap packaging consists of polyethylene film layers fused to form sealed air pockets that absorb mechanical shock during transit, typically manufactured through extrusion lamination with air inflation at 3-8 psi depending on protection grade. Its primary commercial purpose is preventing product damage in parcel distribution networks handling irregular drop and vibration stresses. Air pocket configurations lead volume across the product type dimension due to universal applicability in general merchandise shipping, while biodegradable variants represent the fastest-growing segment as the EU Packaging and Packaging Waste Regulation mandates recyclability thresholds. Within end user categories, e-commerce operations command the largest share of demand, though electronics manufacturing retains premium pricing through anti-static specifications required for semiconductor component protection.
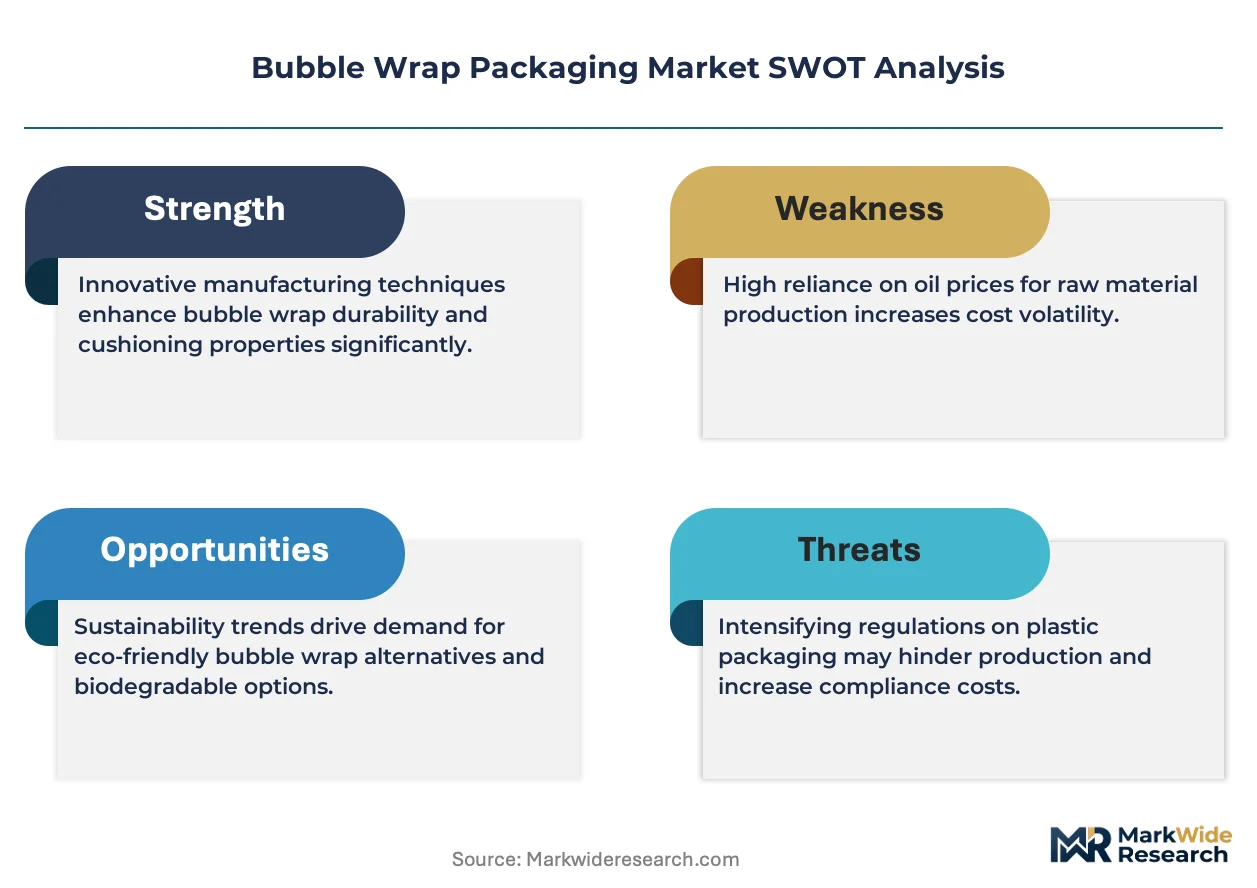
The EU Packaging and Packaging Waste Regulation and FDA food contact material standards collectively shape material composition requirements, with the former mandating recycled content minimums and the latter governing direct food packaging applications. REACH chemical restrictions limit certain plasticizers in European-manufactured films, redirecting formulation investments toward compliant polymer blends. California's SB 54 extended producer responsibility framework imposes parallel compliance obligations for US-market suppliers. Stakeholders must monitor evolving extended producer responsibility schemes to anticipate which material technologies will secure preferential market access.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing material recomposition across the value chain, converting linear polyethylene supply into circular recovery systems that demand new polymer formulations and recycling infrastructure investments.
Growth Catalysts
- E-commerce fulfillment velocity:Parcel throughput at German and Dutch distribution centers requires automated cushioning systems that integrate with high-speed sortation equipment. On-demand air inflation equipment reduces warehouse footprint requirements by eliminating pre-inflated inventory storage.
- REACH chemical compliance:Restrictions on phthalate plasticizers redirect European manufacturers toward bio-based polymer blends that meet food-contact migration limits. Reformulation investments create barrier-to-entry advantages for compliant suppliers.
- Automotive component exports:German OEM supply chains mandate vibration-dampening specifications for precision electronics and glass assemblies shipped to assembly plants across Central Europe.
Market Restraints
- Polyethylene resin price volatility:Ethylene feedstock costs tied to naphtha cracking margins in Rotterdam and Antwerp create quarterly margin compression for film extruders without pass-through contracts.
- Corrugated substitution:Molded pulp and honeycomb paperboard systems displace air cushioning in luxury goods and consumer electronics packaging where unboxing experience drives brand positioning.
- California SB 54 compliance:Extended producer responsibility fees on plastic packaging raise landed costs for US-bound shipments, favoring domestic film production over European imports.
Strategic Opportunities
- Biodegradable film development:PLA-PHA copolymer formulations that degrade in industrial composting facilities align with France's AGEC law banning single-use plastics from e-commerce shipments by 2025.
- Anti-static specifications:Semiconductor fabrication equipment and EV battery component shipments require ionic contamination control that commands premium pricing over standard-grade cushioning.
- On-site inflation services:Equipment-leasing models that place inflation machinery at 3PL warehouses convert capital expenditure into recurring revenue streams while locking in film supply contracts.
Industry Challenges
- Recycling stream contamination:Multi-layer barrier films with nylon or EVOH interlayers complicate mechanical recycling at European sorting facilities, requiring investment in chemical depolymerization partnerships.
- Food-contact certification timelines:FDA migration testing and EU 10/2011 compliance documentation for direct-contact applications extend new product introduction cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bubble Wrap Packaging Market |
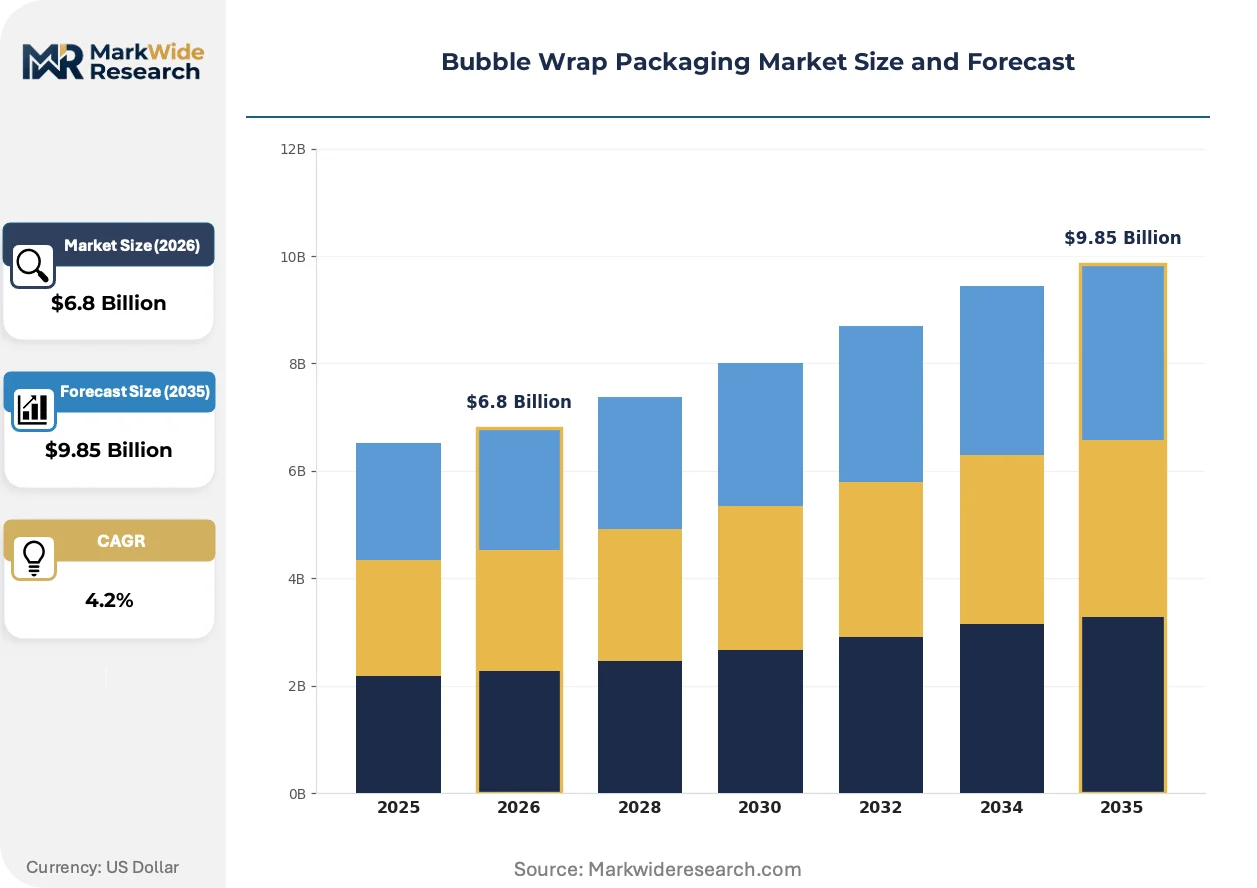
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Pocket, Anti-Static, Biodegradable, Cushioning End User: eCommerce, Electronics, Furniture, Food Packaging Thickness: Single Layer, Double Layer, Triple Layer, Custom Packaging Type: Rolls, Sheets, Pouches, Bagged |
| Companies Covered | Jiffy Packaging, Storopack Hans Reichenecker GmbH, Sealed Air Corporation, Nefab Group, Smurfit Kappa, Pregis LLC, Veritiv Corporation, FP International, Automated Packaging Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bubble Wrap Packaging Market Emerging Trajectories
Digital printing and smart packaging integration are compressing batch sizes and enabling traceability requirements that reshape how protective packaging is specified and sourced across European supply chains.
Barrier-coated paper films with micro-encapsulated air pockets are virtualizing the protective function of conventional polyethylene bubble wrap. German pharmaceutical distributors adopt these fiber-based systems for temperature-sensitive shipments requiring controlled atmosphere integrity. The technology is virtualizing material procurement decisions by decoupling cushioning performance from fossil-based feedstock dependencies.
REACH authorization requirements for intentionally added microplastics compel reformulation of release agents and slip additives used in extrusion lamination. Film processors in Belgium and the Netherlands invest in plasma surface treatment systems that eliminate silicone-based coatings. Small-format e-commerce parcels face the strictest compliance timelines, accelerating adoption of water-based coating alternatives.
Consolidation among European 3PL providers concentrates specification authority at fewer procurement desks in Rotterdam, Hamburg, and Milan. These buyers demand outcome-based contracts that transfer damage-rate liability to packaging suppliers rather than purchasing materials on unit-cost metrics. The shift is most visible in cross-border fashion and cosmetics fulfillment, where brand owners penalize logistics partners for unboxing experience failures.
Bubble Wrap Packaging Market Segmentation
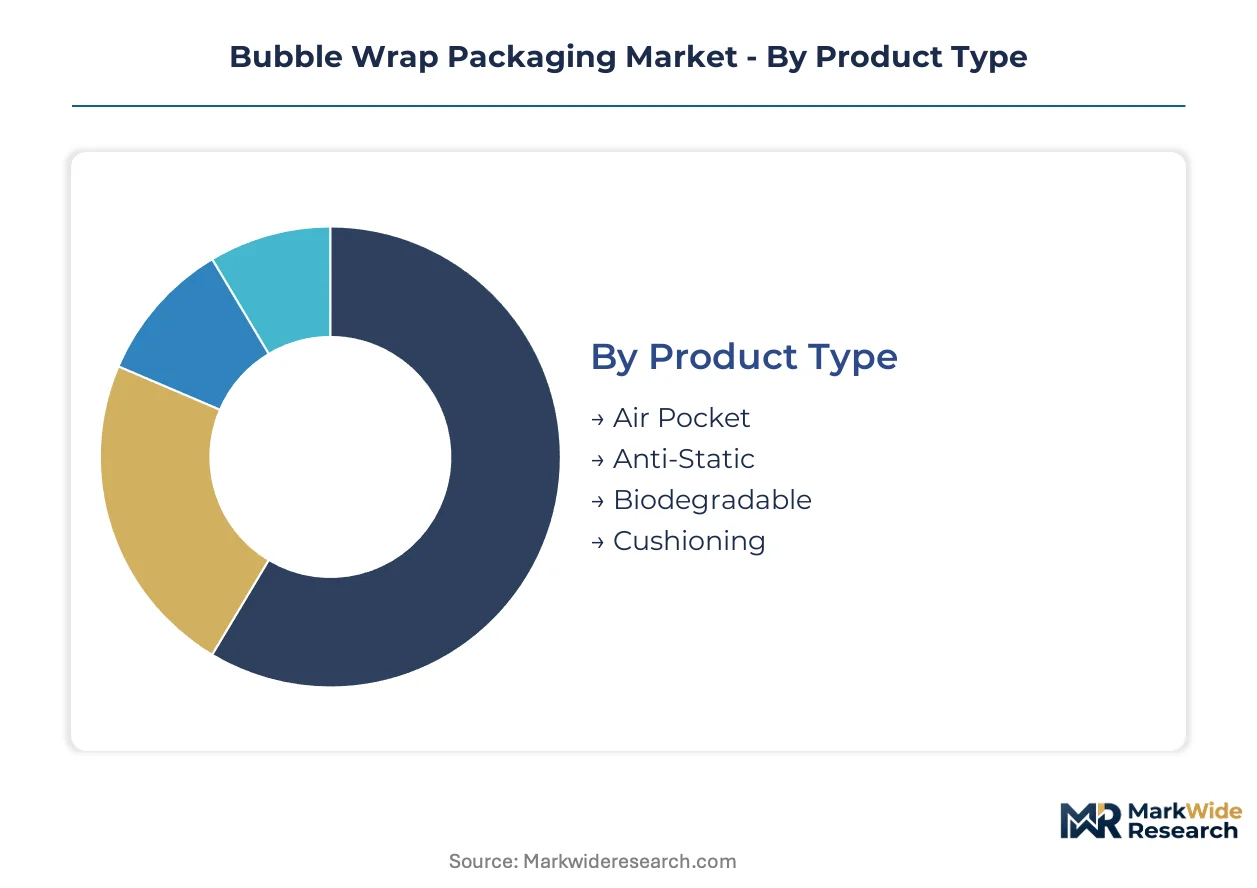
Segmentation in bubble wrap packaging reflects divergent technical requirements across fulfillment velocity tiers and regulatory compliance thresholds. Material specifications, inflation methods, and end-use damage sensitivity create distinct purchasing criteria that reshape supplier positioning.
Product Type:
Use-case spectrum spans general merchandise protection through specialized contamination control, with formulation chemistry determining access to regulated end markets.
- Air Pocket:Extruded polyethylene film fused at 3-8 psi inflation pressure creates the standard cushioning matrix for parcel distribution networks. German automotive component exports and Dutch e-commerce fulfillment centers concentrate procurement of this configuration for vibration dampening across irregular drop stresses.
- Biodegradable:PLA-PHA copolymer formulations degrade in industrial composting facilities, aligning with France's AGEC law mandates for e-commerce packaging. REACH authorization requirements for intentionally added microplastics accelerate reformulation investments toward water-based coating alternatives in Belgian and Dutch extrusion plants.
- Anti-Static:Ionic contamination control specifications serve semiconductor fabrication equipment and EV battery component shipments requiring premium-grade protection.
- Cushioning:Multi-layer barrier constructions with nylon or EVOH interlayers address temperature-sensitive pharmaceutical distribution requirements.
Established volume favors Air Pocket; emerging adoption favors Biodegradable.
End User:
Customer type determines specification authority concentration, with centralized procurement at major 3PL hubs versus fragmented purchasing across manufacturing verticals.
- eCommerce:High-velocity distribution centers in Rotterdam and Hamburg require automated cushioning systems integrated with sortation equipment. On-demand air inflation equipment eliminates pre-inflated inventory storage, compressing warehouse footprint requirements while locking in film supply contracts through equipment-leasing models.
- Electronics:Anti-static specifications for semiconductor and battery components command premium pricing tiers. German OEM supply chains mandate vibration-dampening standards for precision assemblies shipped to Central European assembly plants.
- Furniture:Large-format protection requirements drive demand for custom thickness configurations and reinforced edge cushioning.
- Food Packaging:FDA migration testing and EU 10/2011 compliance documentation extend new product introduction cycles for direct-contact applications.
Procurement centralization concentrates in eCommerce; margin expansion concentrates in Electronics.
Thickness:
Structural layering correlates with protection grade and cost tier, from lightweight consumer parcels through heavy industrial shipments.
- Single Layer:Lightweight polyethylene construction serves small-format fashion and cosmetics parcels where unboxing experience drives brand positioning. California SB 54 extended producer responsibility fees raise landed costs for plastic packaging, favoring thinner material profiles that minimize fee exposure.
- Double Layer:Reinforced air retention suits cross-border shipments with extended transit times and multiple handling points.
- Triple Layer:Maximum impact absorption for automotive glass assemblies and precision electronics requiring drop-test certification.
- Custom:Application-specific calibrations for pharmaceutical temperature-controlled shipments and irregular geometry protection.
Volume scale sits with Single Layer; performance premium sits with Triple Layer.
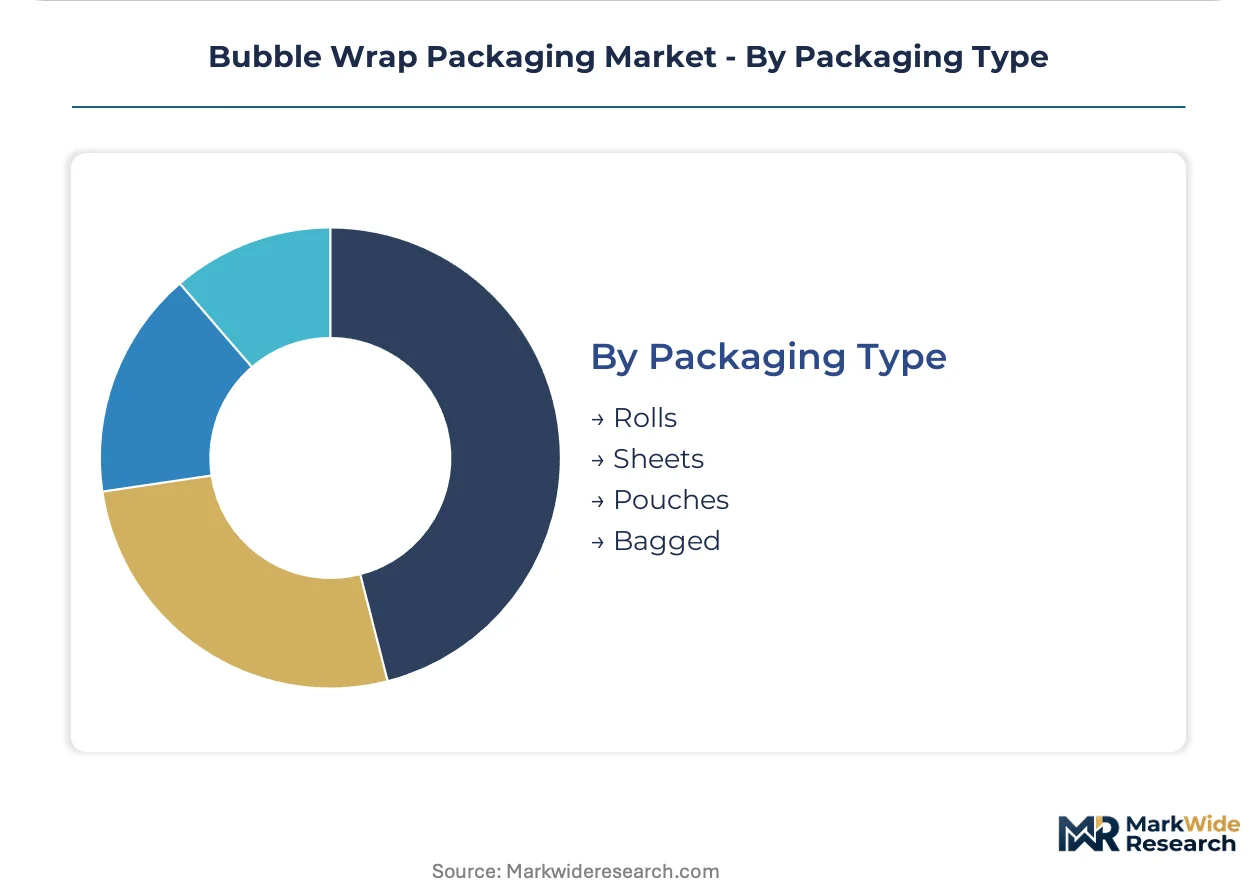
Packaging Type:
Format configuration determines downstream handling efficiency across automated versus manual fulfillment lines.
- Rolls:Continuous film feeds integrate with on-demand inflation equipment at 3PL warehouses, converting capital expenditure into recurring revenue streams. Rotterdam and Milan consolidation among European logistics providers concentrates specification authority for outcome-based damage-rate contracts.
- Sheets:Pre-cut dimensions suit manual packing stations in furniture and electronics assembly operations.
- Pouches:Self-contained cushioning for individual item protection in pharmaceutical and cosmetics distribution.
- Bagged:Pre-inflated convenience formats for low-volume shippers without capital equipment investment.
Automation alignment favors Rolls; flexibility favors Sheets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in German automotive supply chains show the least price elasticity, absorbing premium cushioning costs to meet vibration-dampening mandates. Dutch and Belgian e-commerce fulfillment centers operate at the opposite extreme, where parcel throughput volumes compress margins and drive automated equipment adoption.
Germany
Automotive component exports to Central European assembly plants require precision electronics protection and glass assembly cushioning. REACH chemical restrictions on phthalate plasticizers redirect manufacturers toward bio-based polymer blends. Stuttgart and Munich industrial corridors concentrate OEM supply chain procurement authority.
Netherlands
Rotterdam distribution hubs handle cross-border fashion and cosmetics fulfillment requiring high-velocity sortation integration. The EU Packaging and Packaging Waste Regulation mandates recyclability thresholds that accelerate biodegradable film adoption. Dutch 3PL consolidation concentrates specification authority at fewer procurement desks demanding outcome-based damage-rate contracts.
United States
California SB 54 extended producer responsibility fees raise landed costs for plastic packaging, favoring domestic film production over European imports. FDA food contact material standards govern direct-contact applications with migration testing protocols. Southeast distribution corridors from Atlanta to Dallas anchor e-commerce fulfillment infrastructure investment.
France
AGEC law bans single-use plastics from e-commerce shipments by 2025, accelerating PLA-PHA copolymer formulation demand. Pharmaceutical distributors in Lyon and Paris adopt barrier-coated paper films for temperature-sensitive shipments. French industrial composting facility networks support biodegradable variant degradation requirements.
Belgium
Antwerp petrochemical clusters supply ethylene feedstock for polyethylene resin extrusion, tying film processor margins to naphtha cracking volatility. ECHA authorization requirements for intentionally added microplastics compel reformulation of release agents. Belgian extrusion plants invest in plasma surface treatment systems eliminating silicone-based coatings.
Bubble Wrap Packaging Market Vendor Landscape
Capability concentration sits with integrated material-science specialists; scale advantage sits with diversified packaging conglomerates. The market structures around three tiers: multinational film extruders with captive resin supply, regional equipment-integrated service providers, and niche biodegradable formulation developers. Consolidation pressure runs through automated fulfillment integration and circular material certification requirements.
Within the integrated protective packaging tier, Sealed Air Corporation, Pregis LLC, and Smurfit Kappa exemplify divergent strategic positioning. Sealed Air represents the capital equipment-anchored model placing inflation machinery at 3PL warehouses. Pregis occupies the on-demand air cushioning specialization reducing warehouse footprint requirements. Smurfit Kappa leverages corrugated integration to bundle bubble wrap with box shipments for European e-commerce clients.
| Leading Market Players |
|---|
| Jiffy Packaging |
| Storopack Hans Reichenecker GmbH |
| Sealed Air Corporation |
| Nefab Group |
| Smurfit Kappa |
| Pregis LLC |
| Veritiv Corporation |
| FP International |
| Automated Packaging Systems |
| Others |
Supply Flow & Price Mechanics
Antwerp petrochemical clusters anchor European polyethylene resin supply, with naphtha cracking margins at Rotterdam-Antwerp hubs transmitting directly into film extruder cost structures and downstream pricing power for captive producers.
Pricing Analysis
After-sales equipment-leasing revenue streams now eclipse commodity film margins for integrated suppliers. Three-tier pricing structure across premium anti-static specifications, standard air-pocket grades, and economy single-layer formats reflects certification complexity and performance tier differentiation. Cost compression in standard-grade segments is intensifying because Dutch and Belgian 3PL procurement desks consolidate volume and demand outcome-based damage-rate contracts rather than unit-cost metrics. Electronics manufacturers show the least price sensitivity, absorbing ionic contamination control premiums, while fashion and cosmetics fulfillment operations drive the hardest unit-cost negotiations.
Supply Chain Analysis
Extended payment terms from Rotterdam distribution hubs to film processors are restructuring working capital requirements across the value chain. Belgium, Germany, and the Netherlands concentrate extrusion capacity, with ethylene feedstock drawing from Antwerp naphtha crackers and Ludwigshafen steam crackers. Multi-layer barrier constructions with nylon or EVOH interlayers create single-source vulnerability for pharmaceutical-grade supply. Distribution runs through consolidated 3PL procurement desks in Hamburg, Rotterdam, and Milan that specify outcome-based contracts transferring damage liability upstream.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where on-site inflation equipment leasing and outcome-based damage contracts expand lifetime value faster than standalone film sales.
For Market Incumbents: Pre-empt corrugated substitution threats by accelerating biodegradable PLA-PHA formulation investments ahead of France's AGEC law enforcement. Capture specification authority at consolidating Rotterdam and Milan 3PL hubs through equipment-anchored service contracts. Deepen backward integration into ethylene feedstock through Antwerp cluster partnerships to defend margin position against resin price volatility.
For New Entrants and Emerging Players: Build out biodegradable film capabilities targeting French e-commerce fulfillment networks facing 2025 single-use plastic prohibitions. White-space exists in barrier-coated paper films for German pharmaceutical temperature-sensitive shipments. Lead with industrial composting certification partnerships as the go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors equipment-integrated service providers over commodity extruders. Long-term viability rests on circular material certification capabilities and 3PL specification authority concentration. Acquisition targets should demonstrate REACH-compliant formulation pipelines and established Rotterdam or Hamburg logistics relationships. The inflection signal to watch is chemical depolymerization partnership announcements addressing multi-layer film recycling constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Film Scale-Up | PLA-PHA copolymer investments secure preferential access to French e-commerce fulfillment networks. |
| On-Site Equipment Leasing | Inflation machinery placement at Rotterdam 3PL hubs converts capital expenditure into recurring revenue streams. |
| REACH Compliance Certification | Phthalate-free polymer blends meet EU 10/2011 migration limits for food-contact applications. |
| Chemical Recycling Partnership | Depolymerization alliances address EVOH-nylon interlayer contamination blocking mechanical recycling. |
| Anti-Static Specification Development | Ionic contamination control commands premium positioning for semiconductor and EV battery component shipments. |
Methodological Framework
Desk research of trade customs data, EU regulatory filings, and petrochemical industry reports preceded structured interviews with film extrusion plant managers, 3PL procurement directors, automotive packaging engineers, and pharmaceutical distribution specialists. Primary fieldwork captured specification authority concentration trends and equipment-leasing contract structures. Secondary validation drew from ECHA substance registrations, EU Packaging and Packaging Waste Regulation impact assessments, and polyethylene resin pricing benchmarks. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, and regional dimensions.
Assumptions held fixed include REACH authorization timelines for intentionally added microplastics and existing EU member state enforcement patterns for extended producer responsibility schemes. Variables incorporated resin price volatility bands and 3PL consolidation trajectories. Segmentation dimensions modeled encompass product type, end user category, thickness configuration, and packaging format across the projection horizon. CAGRs were derived from trend extrapolation of e-commerce parcel throughput and automotive export volumes, cross-referenced with regulatory compliance investment cycles.
Sensitivities concentrate around ethylene feedstock cost spikes, accelerated biodegradable mandate enforcement, and chemical recycling infrastructure buildout delays. Forecasts reflect these documented assumptions. Macroeconomic contraction in German automotive exports, regulatory deviation from EU Packaging and Packaging Waste Regulation recyclability thresholds, or breakthroughs in molded pulp substitution technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Insulated Styrofoam Shipping Boxes Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
Static Shielding Bags Market
Protective Packaging
North America Insulated Packaging Market
Protective Packaging
Fiber Cushioning Market
Protective Packaging
Foam Edge Protectors Market
Protective Packaging
Molded Fiber Pulp Edge Protectors Market
Protective Packaging
Anti-Corrosive Packaging Market
Protective Packaging
Paper Cushion Systems Market
Protective Packaging
Padded Mailers Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
Protective Wrapping Paper Market
Protective Packaging
Insulated Packaging Market
Protective Packaging
Secondary Containment Trays Market
Protective Packaging
Padded Dividers Market