
 North America Protective Packaging Market | 2026-2036
North America Protective Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Protective Packaging Market Analytics
Mexico's industrial corridor expansion is reconfiguring regional supply chain geography for protective packaging producers. Sealed Air Corporation leverages its thermoforming and inflatable systems expertise to anchor high-volume automotive parts protection across the border region. Smurfit WestRock sustains integrated paperboard and molded fiber capacity that competes directly with plastic alternatives in cost-sensitive segments. Pregis LLC specializes in on-demand inflatable and paper-based systems, positioning its portfolio toward warehouse automation compatibility.
Protective packaging encompasses engineered materials and systems designed to absorb mechanical shock, vibration, and environmental stress during product transit, distribution, and storage. Foam formulations achieve cushioning through controlled cell structure density ranging from soft polyurethane to rigid expanded polystyrene, while paper-based alternatives utilize molded pulp or corrugated fanfold geometries to distribute impact forces across fragile goods. Bubble wrap and air cushion segments dominate unit volume in e-commerce fulfillment, though margin pools concentrate in biodegradable material grades where brand owners pay premiums for compostable end-of-life credentials. Paperboard material demand accelerates fastest among food and beverage end users seeking fiber-based thermal and structural protection that satisfies retailer sustainability scorecards.
The US EPA regulates recycled content claims under its comprehensive procurement guidelines, while state-level extended producer responsibility frameworks in California and Maine mandate post-consumer recovery targets that reshape material selection across the value chain. Health Canada and PMRA oversee chemical migration limits for food-contact protective packaging, creating dual compliance obligations for cross-border suppliers serving integrated North American supply chains. Stakeholders must monitor how provincial and state-level packaging reduction mandates diverge in stringency, as this fragmentation will determine which material technologies achieve scalable deployment across the region.
Market Dynamics
Extended producer responsibility frameworks across California and Maine are forcing protective packaging producers to redesign material specifications and reclaim infrastructure before 2030 deadlines. E-commerce fulfillment networks accelerate demand for automated-compatible formats that compress warehouse labor intensity.
Growth Catalysts
- California's SB 54 mandates:Post-consumer recycled content thresholds for single-use packaging create guaranteed offtake for molded pulp and paper-based cushioning systems. Brand owners now contract multiyear supply agreements to secure compliant materials.
- Automotive manufacturing clusters:The US Southeast concentration of electric vehicle battery and component assembly drives engineered foam specifications for high-value, shock-sensitive modules. Tier-1 suppliers specify dual-density polyurethane for thermal and mechanical protection.
- On-demand inflatable systems:Warehouse automation compatibility allows fulfillment centers to deploy air cushion generation at pack stations, eliminating pre-inflated inventory storage. Robotics integrators specify these formats for seamless pick-to-ship workflows.
Market Restraints
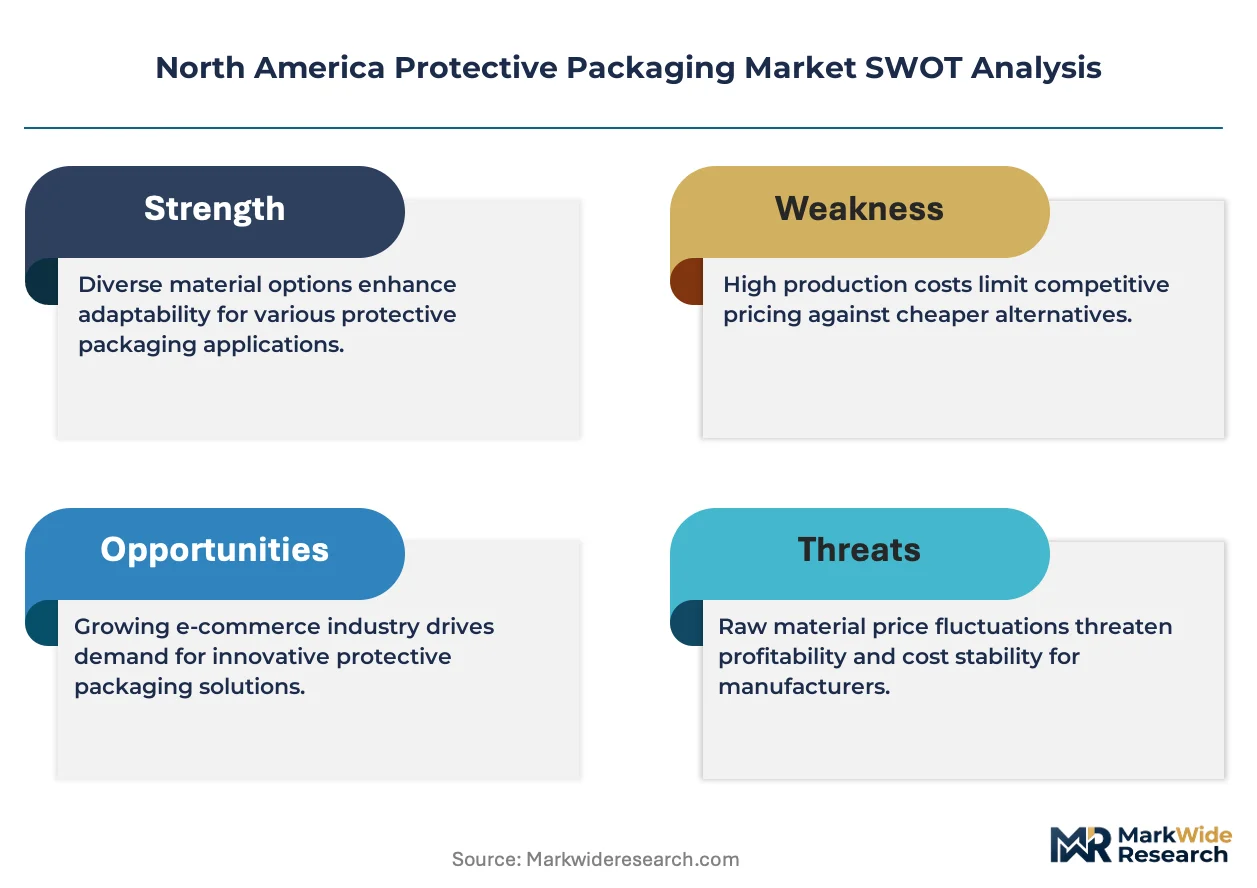
- Resin price volatility:Expanded polystyrene and polyurethane feedstock costs fluctuate with crude oil derivatives, compressing margins for foam-dominant product lines. Producers lack pricing power to pass through petrochemical input spikes.
- Canadian chemical migration limits:Health Canada and PMRA impose stricter food-contact thresholds than US FDA equivalents, forcing dual formulation compliance for cross-border suppliers. Testing duplication adds 12-18 months to product qualification.
- Molded pulp drying energy intensity:Thermal curing processes consume natural gas at rates that conflict with Scope 1 reduction commitments. Pulp-based alternatives face carbon accounting scrutiny despite end-of-life biodegradability advantages.
Strategic Opportunities
- US EPA sustainable materials management:Federal procurement guidelines create preferential purchasing pathways for protective packaging with verified recycled content. Federal supply contractors can secure five-year sole-source agreements.
- Mexico's Bajío industrial corridor:Appliance and electronics manufacturing expansion near León and Querétaro lacks localized molded fiber capacity. First-mover producers can anchor regional supply with shorter lead times than US imports.
- Thermal protection convergence:Phase-change material integration with fiber-based insulation enables temperature-sensitive pharmaceutical and meal-kit segments to abandon expanded polystyrene coolers. Cold chain compliance without landfill penalties attracts premium positioning.
Industry Challenges
- Automated packaging line integration:Legacy fulfillment infrastructure operates at speeds incompatible with next-generation paper-based cushioning dispensers. Retrofit capex requirements stall adoption at mid-tier e-commerce operators.
- Biodegradability certification timelines:ASTM D6400 and D6868 testing protocols require 180-day industrial composting validation. Product development cycles extend 9-14 months, delaying revenue recognition against sustainability procurement deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Protective Packaging Market |
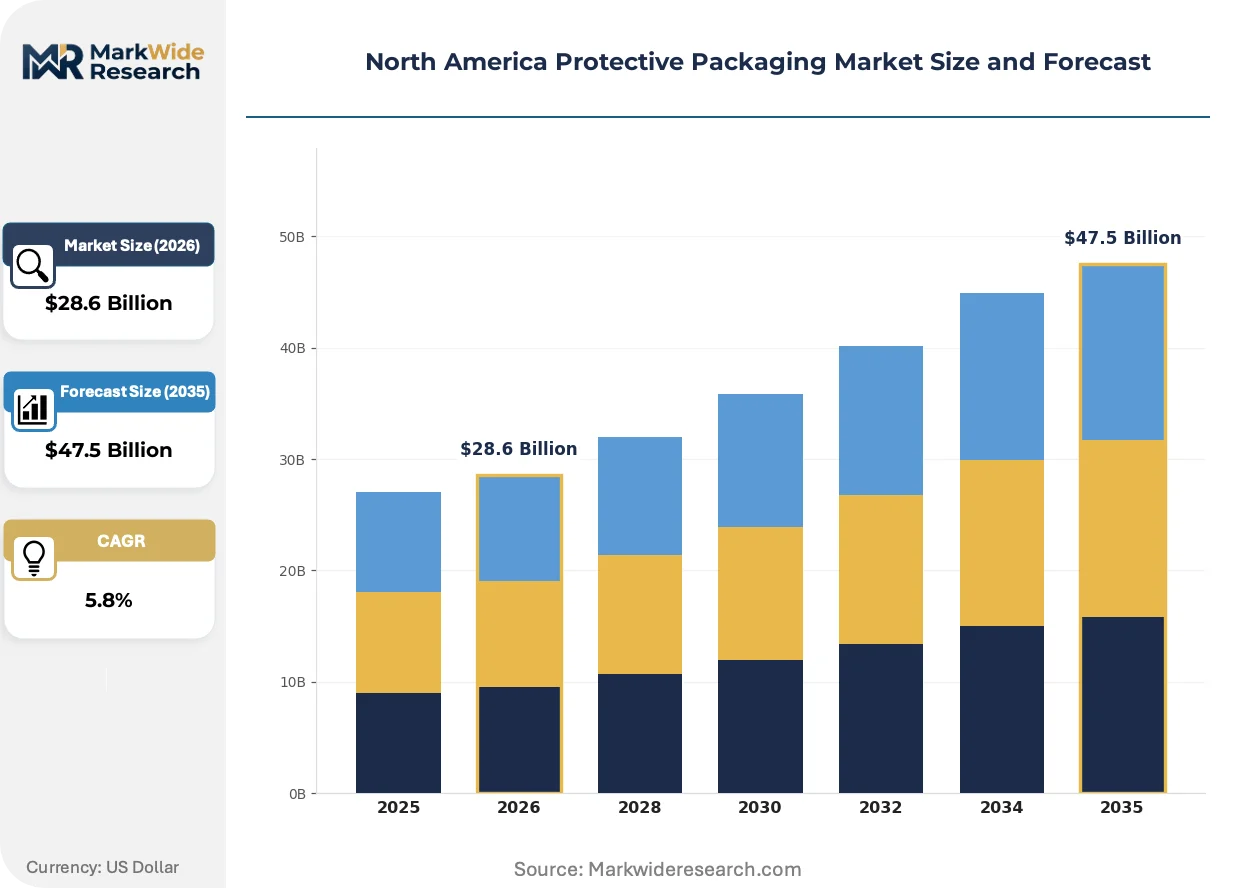
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Bubble Wrap, Air Cushion, Paper Material: Plastic, Paperboard, Metal, Biodegradable End User: Electronics, Food & Beverage, Pharmaceuticals, E-Commerce Packaging Type: Boxes, Bags, Pouches, Sleeves |
| Companies Covered | Sealed Air Corporation, Smurfit WestRock, Pregis LLC, Sonoco Products Company, Intertape Polymer Group Inc., Ranpak Holdings Corp., WestRock Company, DS Smith plc, Storopack Hans Reichenecker GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Protective Packaging Market Evolving Landscape
Material science advances and regulatory stringency are compressing the viable design space for protective packaging, favoring formats that simultaneously satisfy automation, carbon accounting, and end-of-life performance requirements.
Fiber-based molded pulp with engineered rib geometries is collapsing the performance gap with expanded polystyrene for medium-weight consumer electronics. Major appliance manufacturers now specify molded pulp corner and edge protectors for refrigerator and dishwasher shipments. The technology is collapsing capital allocation toward thermoforming equipment as pulp tooling achieves comparable unit economics at volumes above 500,000 annual units.
State-level extended producer responsibility laws in Maine and Oregon mandate producer-funded collection and processing infrastructure for packaging materials. These frameworks impose fee structures that penalize non-recyclable formats and subsidize fiber-based alternatives. Food and beverage brands serving these states accelerate specification changes to avoid per-unit compliance cost penalties that compound across high-volume SKUs.
Buyers now unbundle protective packaging procurement from primary contract packaging services, establishing direct supplier relationships to secure sustainability credentials and cost transparency. Third-party logistics providers lose margin on material markup as shippers negotiate direct terms with Sealed Air, Pregis, and molded fiber specialists. This disintermediation concentrates in California and Washington state markets where retailer scorecard requirements demand supply chain visibility to the primary converter level.
North America Protective Packaging Market Segmentation
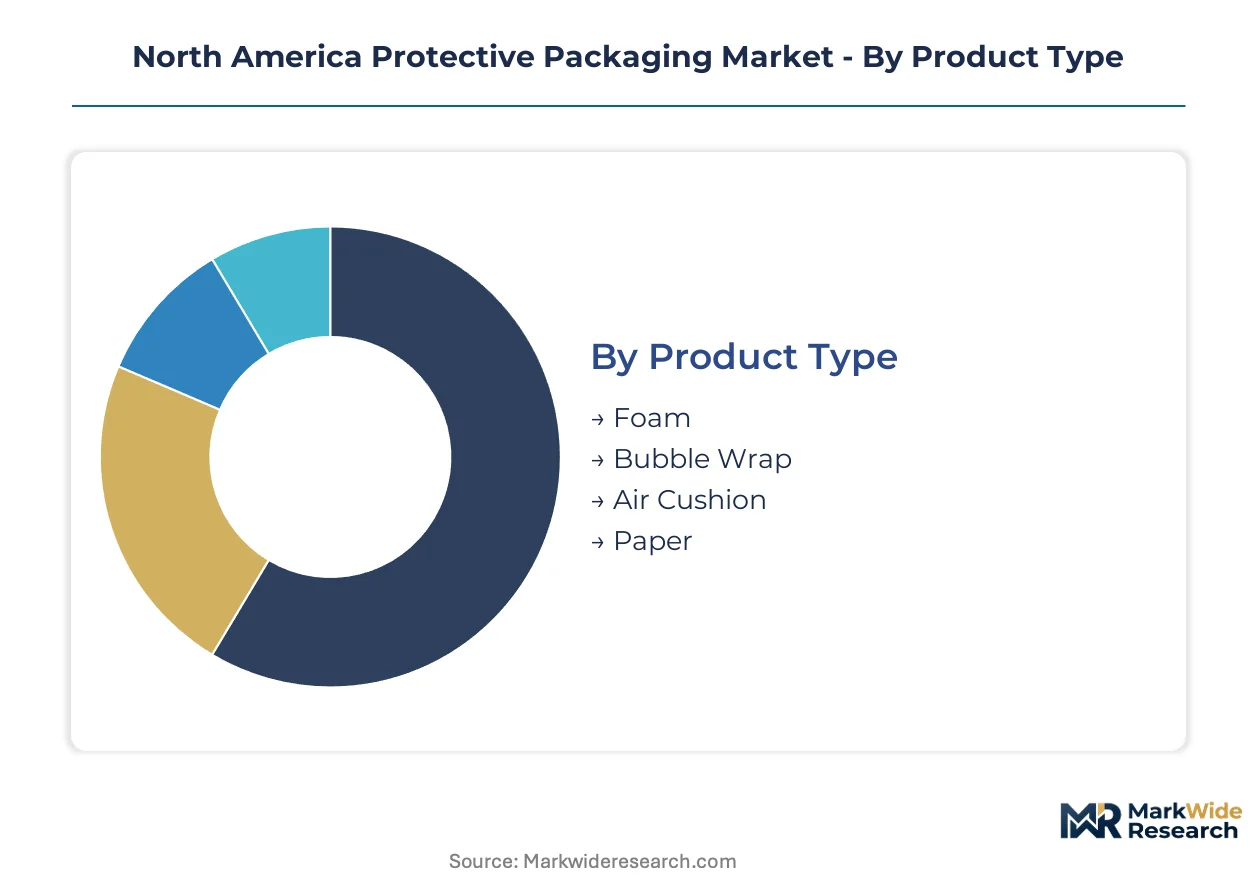
Protective packaging segmentation reveals how material specifications, end-use requirements, and format compatibility determine procurement priorities across North American supply chains. Each dimension carries distinct margin profiles and regulatory exposure that reshape supplier positioning.
Product Type:
Mature formats dominate installed capacity while emerging systems capture automation-driven replacement cycles.
- Foam:Engineered polyurethane and expanded polystyrene formulations deliver controlled cell-structure density for shock absorption in automotive battery modules and appliance shipments. US Southeast manufacturing clusters specify dual-density grades for thermal and mechanical protection of high-value components.
- Bubble Wrap:Pre-formed air-entrapment films retain unit volume leadership in fulfillment networks despite margin compression. E-commerce operators in California and Texas maintain legacy stocking agreements though warehouse footprints shrink for pre-inflated inventory.
- Air Cushion:On-demand inflation systems align with robotic pick-to-ship workflows.
- Paper:Molded pulp and corrugated fanfold geometries displace plastic in sustainability-mandated segments.
Foam handles the majority of throughput; paper is expanding most quickly on share.
Material:
Cost tiers separate commodity feedstocks from certified sustainable alternatives commanding procurement premiums.
- Plastic:Expanded polystyrene and polyethylene films retain cost advantages in high-volume segments. Resin price volatility tied to crude oil derivatives compresses margins unpredictably, limiting producer pricing power during petrochemical input spikes.
- Paperboard:Recycled-content corrugated and molded fiber formats satisfy retailer sustainability scorecards. California's SB 54 mandates guarantee offtake for post-consumer recycled thresholds, locking in multiyear supply agreements from brand owners.
- Metal:Protective foils and barrier laminations serve pharmaceutical cold chain requirements.
- Biodegradable:Compostable polymers and fiber-based alternatives carry ASTM D6400 certification premiums. Maine and Oregon extended producer responsibility frameworks subsidize these formats through fee structures penalizing non-recyclable alternatives.
Plastic maintains volume leadership; biodegradable grades are gaining share fastest.
End User:
Application-specific performance requirements fragment procurement specifications across verticals.
- Electronics:Anti-static foam and molded pulp corner protectors shield smartphones, laptops, and consumer devices during transit. Major manufacturers now specify fiber-based edge protection for medium-weight products above 500,000 annual unit thresholds.
- E-Commerce:Fulfillment networks drive automated-compatible format adoption to compress warehouse labor intensity. On-demand inflatable and paper-based dispensing systems integrate with robotics for seamless pack-station workflows.
- Food & Beverage:Fiber-based thermal protection satisfies retailer sustainability mandates.
- Pharmaceuticals:Phase-change material integration enables temperature-sensitive shipment compliance without expanded polystyrene landfill penalties.
E-commerce channels process the highest unit volumes; food and beverage specifications are climbing the fastest.
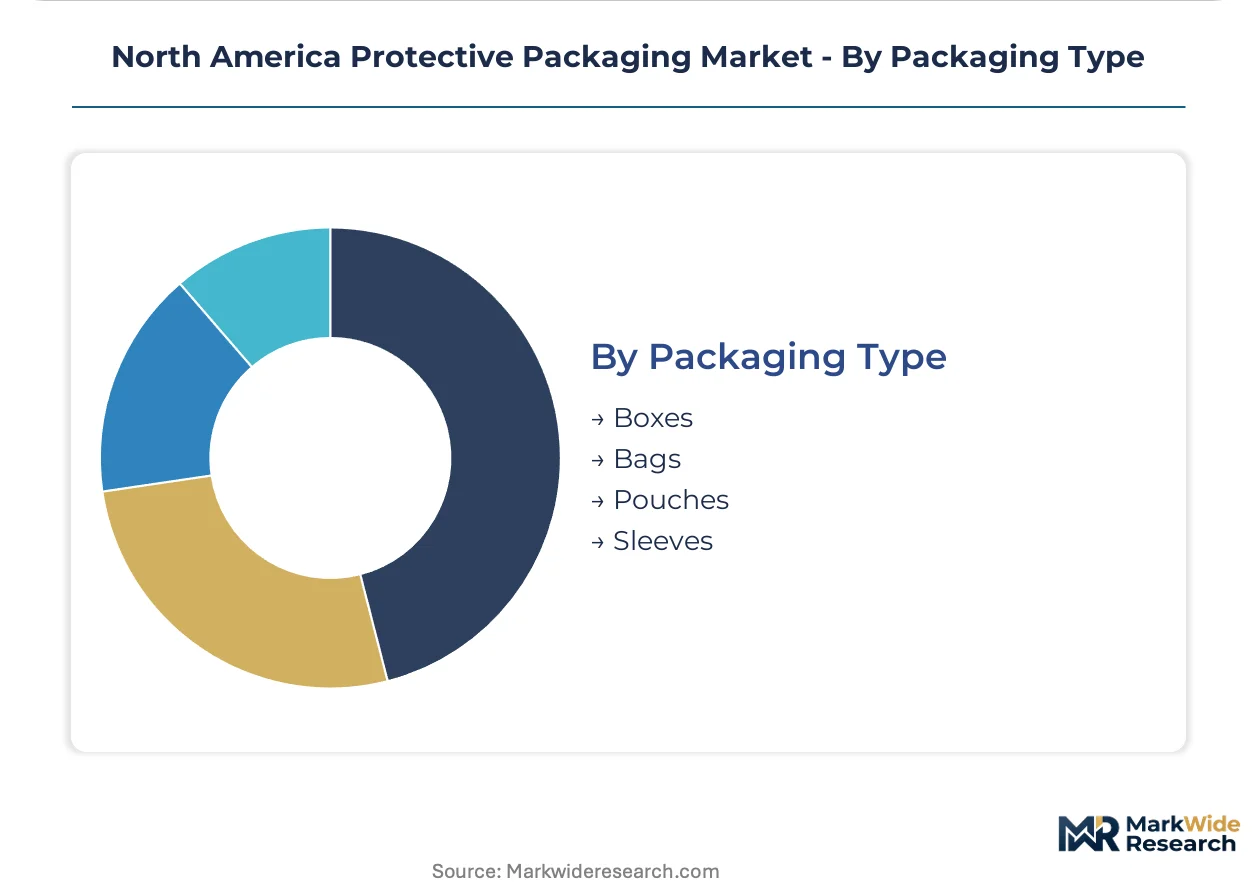
Packaging Type:
Format selection tracks customer automation infrastructure and product geometry requirements.
- Boxes:Corrugated containers with engineered inserts dominate business-to-business shipments. Retrofit capex requirements for next-generation paper-based cushioning dispensers stall adoption at mid-tier operators with legacy fulfillment lines.
- Bags:Flexible films and mailers serve lightweight e-commerce parcel delivery. Direct supplier relationships disintermediate third-party logistics providers as shippers negotiate terms with converters for sustainability scorecard visibility.
- Pouches:Stand-up and flat formats accommodate pharmaceutical unit-dose protection.
- Sleeves:Custom-fit corrugated and molded pulp enclosures wrap irregular appliance geometries.
Boxes handle the majority of shipment value; bags are expanding most quickly on unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA's sustainable materials management priorities anchor protective packaging demand across the dominant United States market, while Health Canada and state-level extended producer responsibility frameworks reshape cross-border supply chain specifications.
United States
Automotive battery manufacturing clusters in the US Southeast and e-commerce fulfillment networks drive engineered foam and paper-based cushioning adoption. California's SB 54 mandates post-consumer recycled content thresholds that lock in multiyear supply agreements from brand owners. The Texas Triangle and Georgia logistics corridors concentrate automated-compatible inflatable system deployment at high-volume pack stations.
Canada
Health Canada and PMRA impose stricter chemical migration limits for food-contact packaging than US FDA equivalents, forcing dual formulation compliance for cross-border suppliers. Ontario's manufacturing base and British Columbia's port logistics generate steady demand for temperature-sensitive pharmaceutical protection. The Greater Toronto Area anchors regional distribution for US-based protective packaging producers serving integrated North American supply chains.
Mexico
The Bajío industrial corridor near León and Querétaro lacks localized molded fiber capacity despite accelerating appliance and electronics manufacturing expansion. Federal environmental regulations under SEMARNAT and state-level industrial incentives attract cross-border investment in sustainable packaging infrastructure. Northern border states concentrate maquiladora operations that demand just-in-time protective materials for automotive parts exports to US assembly plants.
North America Protective Packaging Market Competitive Landscape
Capability concentration sits with specialized material science developers; scale advantage sits with integrated paperboard and resin-based producers. The market structure reflects a tiered competitive environment where automation compatibility and sustainability certification separate premium positioning from commodity supply. Three archetypes dominate: vertically integrated paperboard converters, on-demand inflatable system specialists, and engineered foam compounders. Capacity expansion in Mexico's industrial corridor and portfolio diversification toward biodegradable grades represent the dominant competitive moves.
Among US-based diversified packaging conglomerates, Sealed Air Corporation and Smurfit WestRock exemplify contrasting strategic positions. Sealed Air occupies the automation-integrated tier with thermoforming and inflatable systems expertise. Smurfit WestRock represents the fiber-based scale advantage through integrated paperboard and molded fiber capacity. Pregis LLC sits within the specialized on-demand systems segment, positioning toward warehouse automation compatibility. These three anchors illustrate how material technology specialization and geographic footprint determine competitive differentiation.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Smurfit WestRock |
| Pregis LLC |
| Sonoco Products Company |
| Intertape Polymer Group Inc. |
| Ranpak Holdings Corp. |
| WestRock Company |
| DS Smith plc |
| Storopack Hans Reichenecker GmbH |
| Others |
Value Network & Pricing Analysis
US Gulf Coast petrochemical concentration feeds resin-dependent foam producers downstream, concentrating margin capture with integrated paperboard converters who control pulp sourcing through captive forestry operations. California's SB 54 compliance premiums and Mexican logistics arbitrage create geographic price spreads that reward multi-plant footprints.
Pricing Analysis
Geographic price spreads widen between California compliance-grade materials and commodity resin-based alternatives in Texas and Georgia. Three-tier pricing structure across certified sustainable, standard recycled-content, and virgin resin grades dominates procurement contracts. Price differentiation hinges on post-consumer recycled certification thresholds and automation compatibility specifications. Cost compression in expanded polystyrene foam runs through volatile benzene derivative feedstocks, while brand owners in California and Maine show lowest price sensitivity for ASTM D6400-certified biodegradable alternatives.
Supply Chain Analysis
Extended payment terms from appliance and automotive OEMs now stretch 90-120 days, forcing mid-tier converters to utilize supply-chain finance facilities anchored by major paperboard producers. Raw material sourcing concentrates in the United States, Canada, and Brazil for pulp feedstocks, with resin dependencies drawing from US Gulf Coast and Alberta petrochemical complexes. Single-source vulnerability sits with specialty foam blowing agents subject to EPA phase-down schedules. Distribution runs through third-party logistics hubs in the Texas Triangle and Inland Empire, with direct supplier relationships disintermediating traditional packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through direct procurement unbundling from contract packaging services, as sustainability scorecard requirements at major retailers and e-commerce platforms consolidate specification authority among fewer brand-owner procurement teams.
For Market Incumbents: Harden automation compatibility credentials through pack-station robotics integration partnerships, as warehouse labor compression becomes the primary selection criterion for e-commerce fulfillment networks. Deepen backward integration into molded fiber tooling capacity to capture margin pools shifting from thermoforming equipment. Defend against specialty pulp-based entrants by securing multiyear offtake agreements with California and Maine brand owners ahead of extended producer responsibility fee structures taking full effect. For New Entrants and Emerging Players: Pursue geographic white space in Mexico's Bajío industrial corridor, where appliance and electronics manufacturing expansion lacks localized molded fiber capacity against US import lead times. Target pharmaceutical cold chain segments with phase-change material integration offerings that eliminate expanded polystyrene landfill penalties. Establish direct relationships with third-party logistics providers operating automated fulfillment networks, bypassing incumbent distributor relationships through warehouse automation compatibility guarantees. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across on-demand inflatable system manufacturing, as equipment modularity reduces scale thresholds for viable entry. Long-term viability favors converters with integrated recycled-content pulp sourcing and multi-state regulatory compliance infrastructure. Acquisition targets should demonstrate established ASTM D6400 certification pipelines and existing relationships with California SB 54-mandated brand owners. Monitor state-level extended producer responsibility expansion beyond Maine and Oregon as the signal for accelerated fiber-based substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Pulp Sourcing | Captures margin from volatile OCC markets and secures California SB 54 compliance thresholds. |
| Automation-Compatible Pack Station Deployment | Aligns with Amazon and Walmart fulfillment robotics specifications for labor reduction. |
| Phase-Change Material Cold Chain Partnership | Enables pharmaceutical shippers to abandon expanded polystyrene without temperature excursion risk. |
| Mexico Bajío Regional Capacity Buildout | Shortens lead times for appliance manufacturers near León against US import alternatives. |
| ASTM D6400 Certification Pipeline Investment | Locks in premium positioning ahead of Maine and Oregon extended producer responsibility fee structures. |
Research Methodology
A standing panel of protective packaging procurement managers at major e-commerce platforms, automotive Tier 1 supplier logistics directors, sustainability compliance officers at food and beverage brands, and molded fiber equipment engineers provided ongoing calibration across the study period. Primary interview findings triangulated against secondary sources including US EPA sustainable materials management guidelines, California SB 54 regulatory filings, Health Canada PMRA food-contact notifications, and SEC 10-K disclosures from integrated paperboard producers. Bottom-up volume modeling across product type, material, end user, and packaging type dimensions converged with top-down macroeconomic anchoring.
Scenario bracketing around resin price volatility trajectories and state-level extended producer responsibility adoption timelines bounded the forecast range. Segmentation modeling captured material substitution dynamics, automation compatibility requirements, and regional regulatory stringency differentials. CAGRs derived from elasticity-adjusted demand curves incorporating e-commerce fulfillment network expansion and automotive manufacturing cluster relocation patterns. Industry-specific inputs included EPA recycled content procurement data and SEMARNAT environmental compliance tracking for Mexican manufacturing expansion.
Sensitivities concentrate around crude oil derivative price spikes, accelerated state-level packaging reduction mandates beyond California and Maine, and breakthrough molded pulp drying energy efficiency improvements. Forecasts reflect assumptions regarding sustained e-commerce fulfillment automation investment and stable federal procurement guidelines. Macroeconomic contraction, regulatory fragmentation across provincial and state jurisdictions, or disruptive alternative material technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Static Shielding Bags Market
Protective Packaging
Secondary Containment Trays Market
Protective Packaging
Insulated Styrofoam Shipping Boxes Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
Padded Dividers Market
Protective Packaging
Protective Wrapping Paper Market
Protective Packaging
Insulated Packaging Market
Protective Packaging
Foam Mesh Sleeves Market
Protective Packaging
Anti-Static Foam Packaging Market
Protective Packaging
Global Packaging Inserts and Cushions Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Packaging and Protective Packaging Market
Protective Packaging
Padded Mailers Market
Protective Packaging
High Pressure Protective Packaging Film Market
Protective Packaging
Void Fill Pillows Market