
 Digital Printed Pouch Market | 2026-2036
Digital Printed Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Printed Pouch Market Outlook
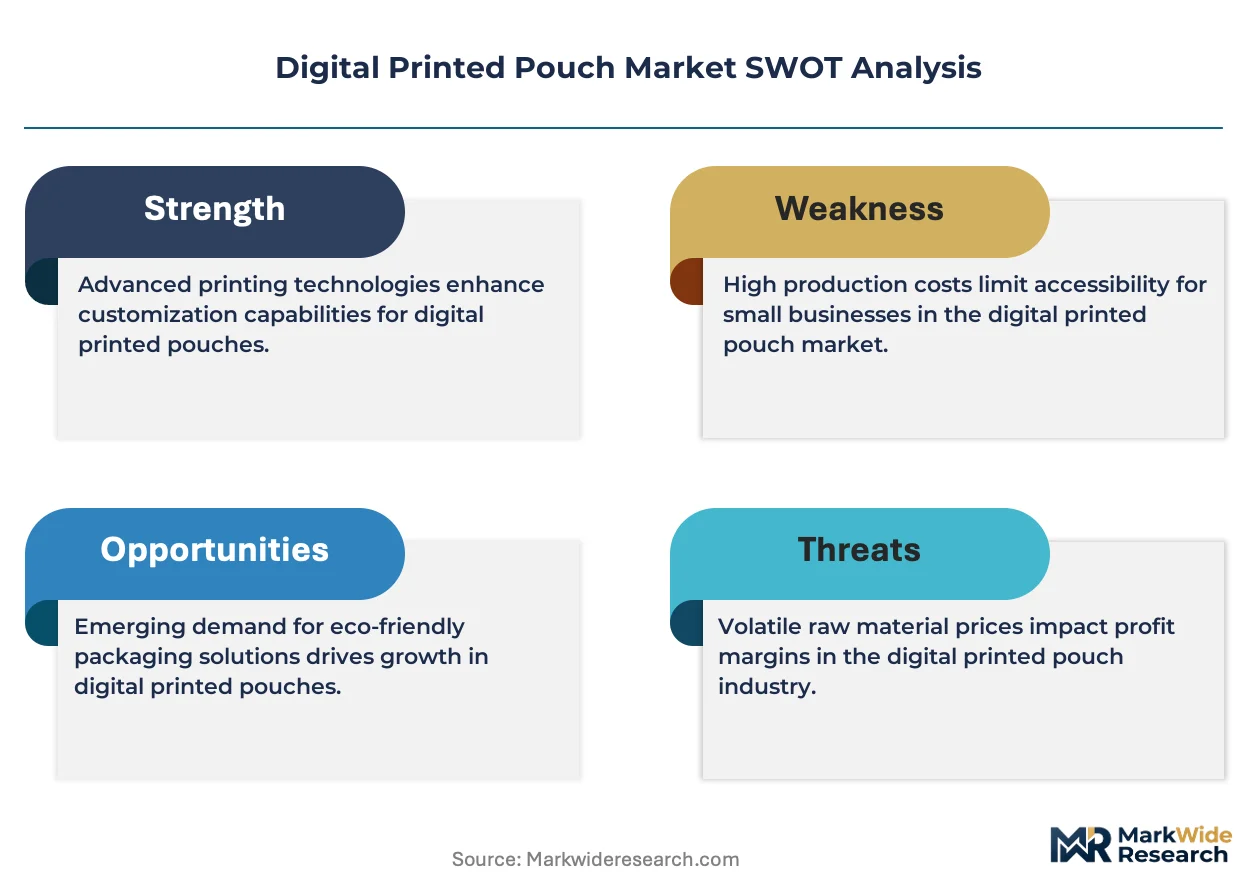
A capital-intensity divergence between billion-dollar multinationals and asset-light regional specialists is unwinding traditional competitive moats in flexible packaging. Amcor leverages its global extrusion and film supply network to offer integrated substrate-digital print solutions at scale. ePac Flexible Packaging anchors its strategy in a distributed micro-factory model, competing on turnaround speed for runs below ten thousand units. Mondi sustains technology leadership through dedicated R&D centers focused on barrier-coated paper substrates compatible with HP Indigo presses.
Digital printed pouches are flexible packaging formats produced via inkjet or electrophotographic deposition of CMYK and specialty inks directly onto rollstock, eliminating plate costs and enabling variable data printing with resolution thresholds of 1200 dpi or higher. Their primary commercial purpose is to reduce time-to-shelf for consumer brands requiring frequent graphic changes, regional versioning, or regulatory label updates. Stand-up pouches dominate value capture due to premium shelf positioning and higher ink coverage requirements, while flat pouches compete aggressively on unit economics for single-serve confectionery and sample packs. PET and BOPP material segments lead volume, though mono-material CPP structures are growing fastest as Extended Producer Responsibility schemes in Europe and North America penalize multi-layer laminates.
FDA food contact notification requirements govern ink migration limits for pouches holding edible contents in the United States, while REACH and the EU Packaging and Packaging Waste Regulation constrain substrate and ink chemistries across European markets. These frameworks shape demand by disqualifying certain solvent-based digital inks and mandating recyclability testing for printed structures. Stakeholders must monitor how emerging state-level extended producer responsibility laws in the United States interact with existing substrate certification pathways to avoid stranded inventory in regional supply chains.
Market Dynamics
SKU proliferation among food and beverage brands is compressing print run minimums, forcing converters to abandon rotogravure cylinders for digital workflows that enable same-day graphic changes without plate costs.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates are accelerating mono-material pouch adoption compatible with HP Indigo and Xeikon presses.
- Seasonal customization demand:Specialty confectionery and craft beverage producers require frequent graphic refreshes for limited-edition releases.
- Barrier-coated paper substrates:Advances in water-based coatings are opening new substrate options for brands targeting plastic reduction commitments.
Market Restraints
- Digital ink cost premiums:Electron beam-cured and UV-curable inks remain three to five times costlier than solvent-based gravure alternatives.
- Equipment concentration:High-performance digital press manufacturing concentrates in Israel, Japan, and the Netherlands, creating supply vulnerability.
- Migration testing complexity:FDA food contact notification requirements extend certification timelines for new ink formulations.
Strategic Opportunities
- Pharmaceutical compliance printing:Track-and-trace serialization requirements are creating demand for variable data-capable pouch formats.
- Extended Producer Responsibility schemes:California and New York state-level EPR laws are mandating recyclability labeling that favors digitally printed structures.
- Smart packaging convergence:Integration of NFC tags and printed electronics with digital graphics is enabling authentication and consumer engagement layers.
Industry Challenges
- Prepress technician scarcity:Color management expertise for extended gamut printing remains concentrated among legacy flexographic specialists.
- Legacy ERP integration:Converters' existing production scheduling systems require costly middleware to interface with digital press job management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Printed Pouch Market |
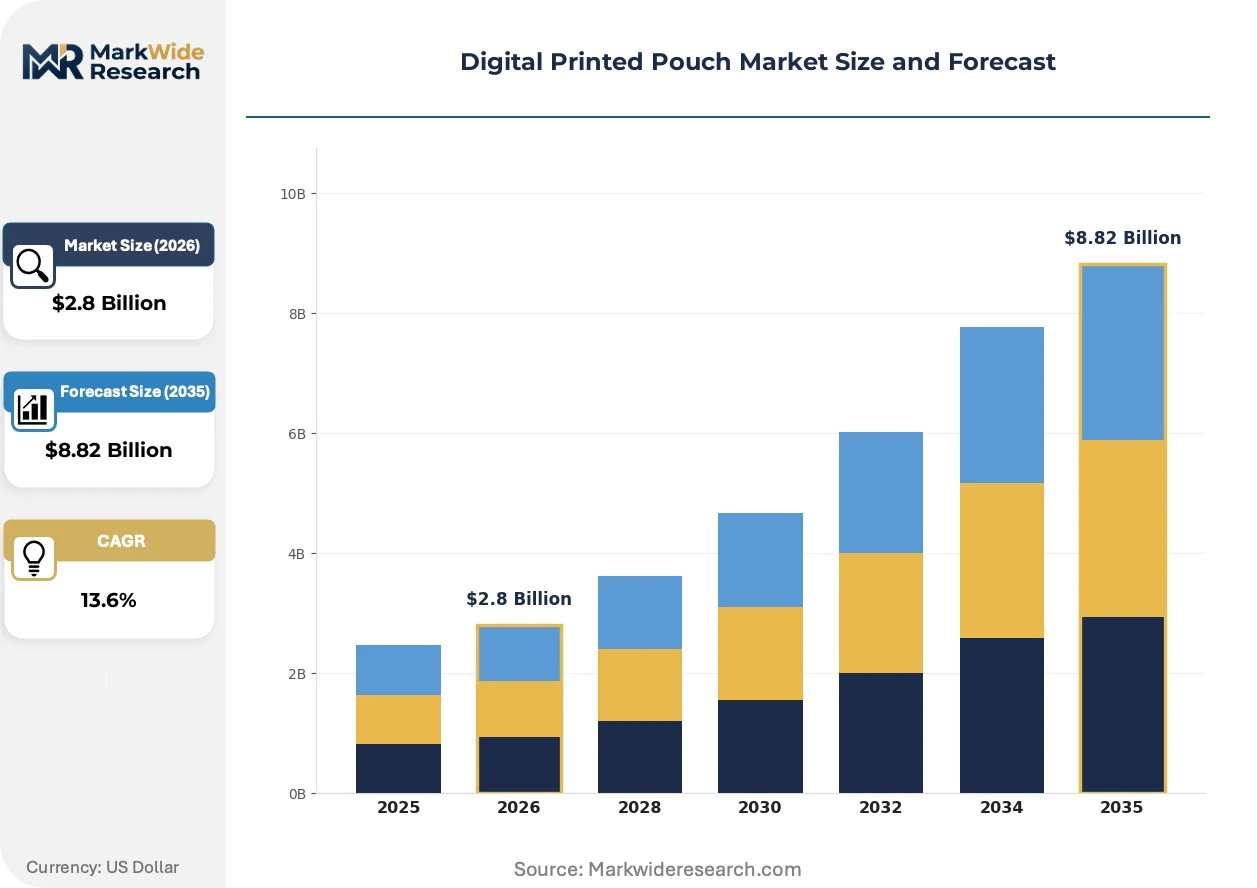
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Bottom Gusset Pouches, Custom-Shaped Pouches Material: PET, BOPP, CPP, Aluminum Foil End User: Food & Beverage, Healthcare, Personal Care, Home Care Packaging Type: Flexible Packaging, Rigid Packaging, Eco-Friendly Packaging, Vacuum Packaging |
| Companies Covered | Amcor, ePac Flexible Packaging, Mondi, ProAmpac, BaiShen Pack, Sonoco Products Company, YLTPACK, Sealed Air Corporation, Wolfparc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Printed Pouch Market Strategic Shifts
Electrophotographic and inkjet deposition technologies are compressing the traditional trade-off between print quality and economic run length, enabling new competitive positioning for mid-sized converters.
Water-based ink formulations are displacing UV-curable chemistries in food-contact applications. Premium snack brands in Germany and the Netherlands are specifying these inks for direct-contact structures. This shift is compressing the addressable market for solvent-based digital alternatives while expanding converter serviceable markets into previously restricted categories.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing substrate suppliers to reformulate barrier coatings. Industrial consequence includes accelerated R&D timelines for mineral-based and bio-derived alternatives. Mono-material polyethylene structures are capturing share in frozen food and pet care segments as multi-layer laminates face compliance headwinds.
Brand procurement teams are consolidating supplier relationships around converters offering integrated design-to-delivery platforms. Mid-sized specialty food producers are bypassing traditional broker networks for direct digital converter relationships. This pattern is most pronounced in German-speaking markets where distributed manufacturing networks reduce logistics costs for regional brands.
Digital Printed Pouch Market Segmentation
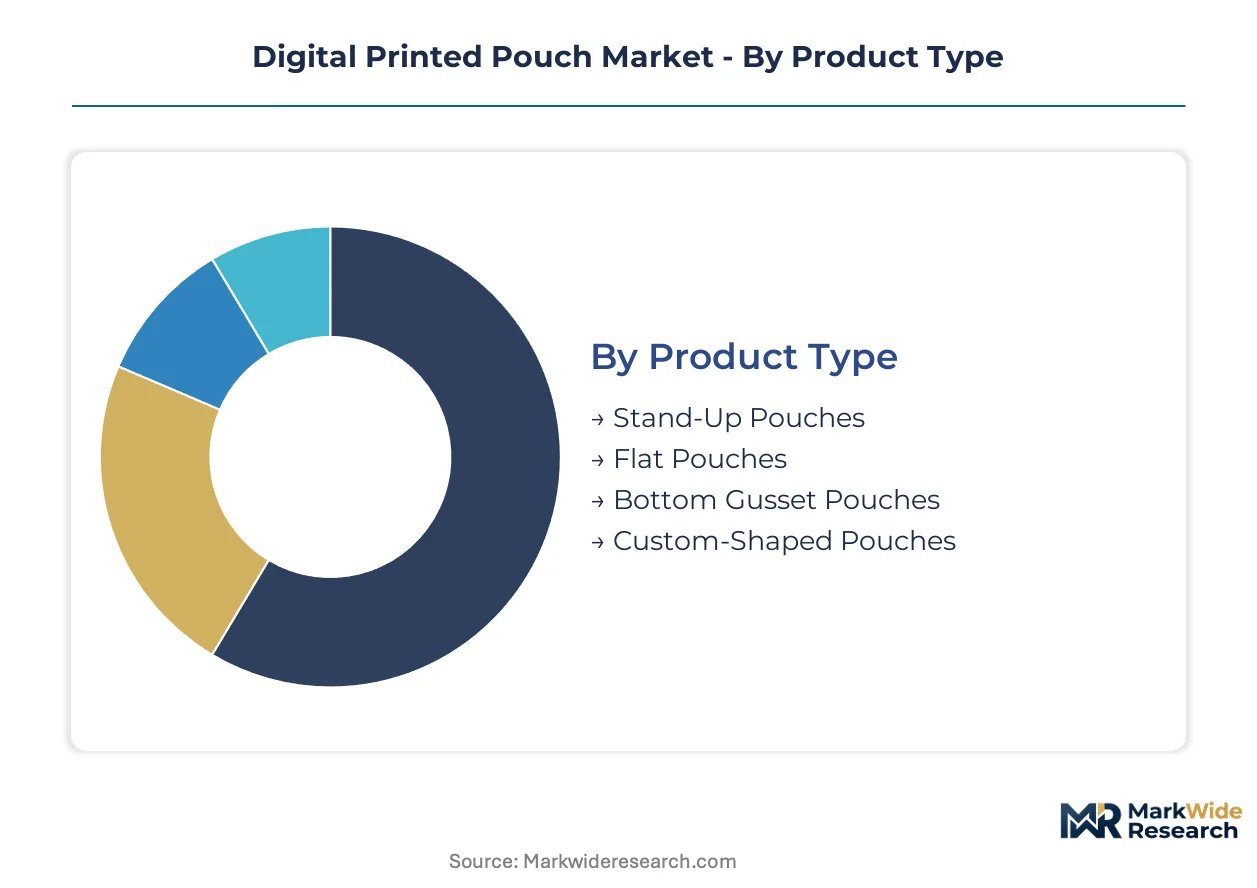
Segmentation in digital printed pouches reveals how substrate compatibility, barrier requirements, and regulatory constraints fragment demand across converter capabilities. Each dimension carries distinct margin structures and equipment lock-ins that shape competitive positioning.
Product Type:
Higher ink coverage and premium shelf positioning concentrate margin pools in three-dimensional formats that command brand investment.
- Stand-Up Pouches:These structures incorporate bottom gussets enabling vertical display, requiring 40-60% greater ink deposition than flat alternatives. German snack brands and Dutch craft beverage producers dominate specification, driven by seasonal graphic refreshes and limited-edition positioning.
- Flat Pouches:Simple two-seal constructions optimize unit economics for single-serve confectionery and sample packs. Demand concentrates in high-volume, low-SKU operations where digital print eliminates plate costs for frequent flavor rotations.
- Bottom Gusset Pouches:Reinforced base structures support heavier fill weights for pet food and frozen applications. Specifications favor mono-material polyethylene compatible with EU recyclability mandates.
- Custom-Shaped Pouches:Die-cut profiles enable brand differentiation through unique silhouettes. Production requires specialized sealing equipment that limits converter participation to specialists with format-flexible presses.
The dominant share belongs to Stand-Up Pouches, while Custom-Shaped Pouches is closing the gap fastest.
Material:
Substrate selection determines press compatibility, barrier performance, and end-of-life compliance—creating tiered serviceable markets for converter specialization.
- PET:Polyester films deliver dimensional stability and optical clarity for high-resolution graphics. Food & Beverage brands in North America specify PET for refrigerated ready-meal applications requiring FDA-compliant ink systems.
- BOPP:Biaxially oriented polypropylene offers moisture resistance and heat-seal latitude at lower cost than PET. Asian confectionery exporters favor BOPP for humidity-stable export packaging.
- CPP:Cast polypropylene structures enable mono-material recyclability under Extended Producer Responsibility schemes. European frozen food producers are migrating multi-layer laminates to CPP to satisfy PPWR requirements.
- Aluminum Foil:Metallized layers provide oxygen and light barriers for coffee and pharmaceutical applications. REACH Annex XVII constraints on per- and polyfluoroalkyl substances are accelerating foil replacement with mineral-coated alternatives.
PET retains the largest installed base, though CPP is expanding most quickly as regulatory pressure reshapes substrate preferences.
End User:
Application-specific barrier requirements and regulatory exposure create divergent customer lifetime values across verticals.
- Food & Beverage:The largest addressable market spanning snacks, beverages, and ready meals. SKU proliferation and seasonal customization compress run lengths, favoring digital over rotogravure for mid-sized brands.
- Healthcare:Pharmaceutical pouches require track-and-trace serialization and tamper-evident features. FDA 21 CFR Part 11 compliance and EU MDR labeling mandates drive variable data printing adoption.
- Personal Care:Cosmetic and hygiene brands leverage digital print for regional versioning and influencer collaboration packaging. Premium positioning justifies higher ink costs for short-run luxury samples.
- Home Care:Detergent and cleaning product pouches prioritize chemical resistance and child-resistant closures. Specifications favor robust substrates over graphic complexity.
Food & Beverage commands the deepest converter relationships, while Healthcare is gaining share fastest through compliance-driven specification.
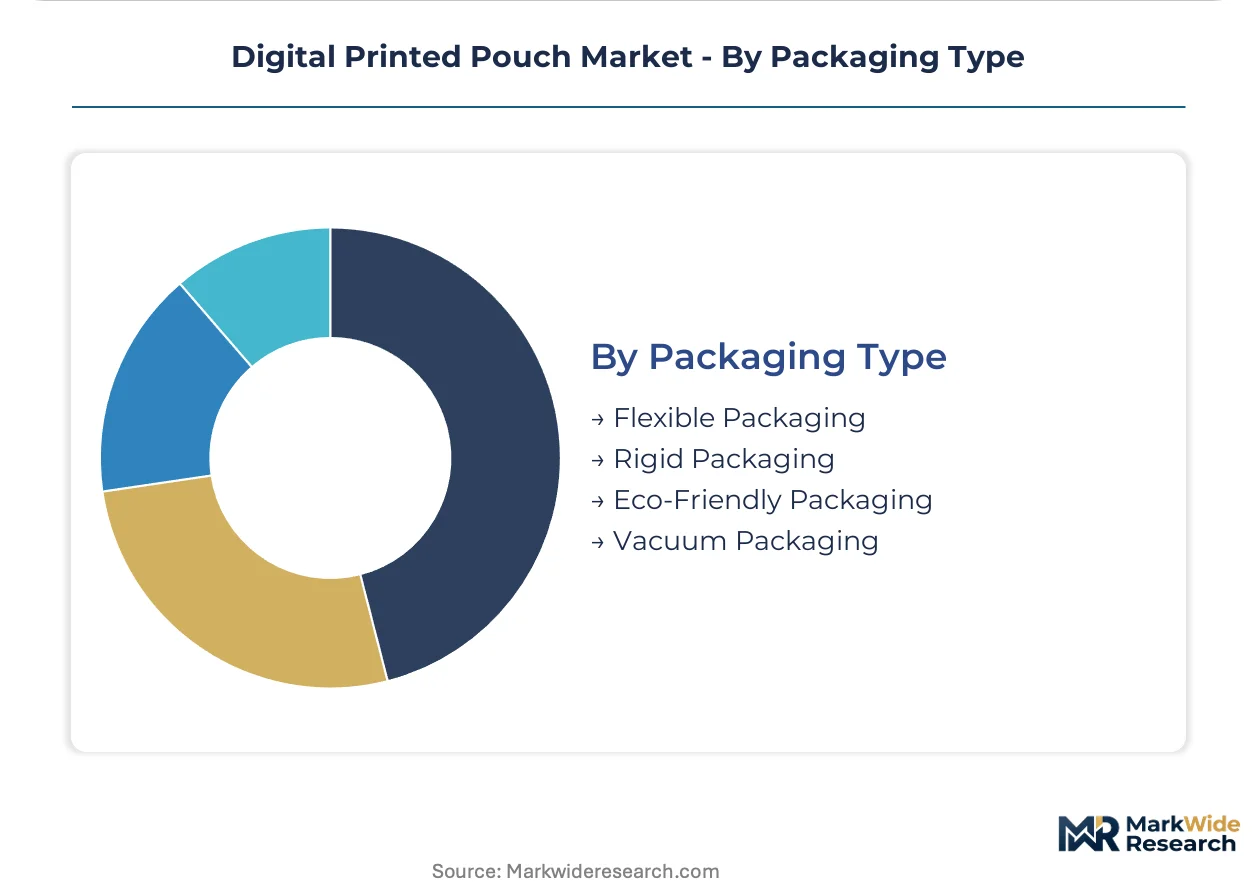
Packaging Type:
Structural format determines equipment investment, sustainability credentials, and supply chain integration depth.
- Flexible Packaging:Roll-fed pouch formats dominate digital print applicability, with HP Indigo and Xeikon presses optimized for web-based production. The category spans stand-up, flat, and gusseted constructions.
- Rigid Packaging:Limited digital penetration due to press format constraints; primarily relevant for pre-formed containers with sleeve labels rather than direct pouch printing.
- Eco-Friendly Packaging:Barrier-coated paper and mono-material structures align with plastic reduction commitments. Water-based ink formulations are displacing UV-curable chemistries in direct-contact applications.
- Vacuum Packaging:High-barrier requirements for protein preservation favor multi-layer laminates facing regulatory headwinds. Mono-material alternatives are emerging but with reduced shelf-life performance.
Flexible Packaging holds the established position, while Eco-Friendly Packaging is climbing the fastest as brand sustainability targets harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the Netherlands show low price elasticity for short-run customization, while US and Chinese purchasers drive hard on unit economics for commodity formats. This divergence shapes converter investment patterns across major demand centers.
Germany
Mid-sized snack producers and craft beverage brands dominate specification for seasonal and limited-edition pouches. REACH and the EU Packaging and Packaging Waste Regulation enforce strict recyclability mandates that favor mono-material structures. The Rhine-Ruhr industrial corridor hosts concentrated converter capacity serving pan-European brand portfolios.
United States
Food and beverage SKU proliferation compresses print run minimums, pushing brands toward digital workflows. FDA food contact notification requirements govern ink migration limits for edible contents. The Chicago-Milwaukee corridor anchors flexible packaging converter density, with distributed manufacturing models expanding into secondary metro areas.
China
Asian confectionery exporters specify humidity-stable formats for cross-border shipment. GB standards and MIIT regulations shape substrate and ink compliance frameworks. The Yangtze River Delta industrial cluster concentrates film extrusion and digital press installation capacity for export-oriented production.
Netherlands
Premium snack brands specify water-based ink formulations for direct-contact applications. ECHA restrictions on per- and polyfluoroalkyl substances accelerate barrier coating reformulation. The Eindhoven-Tilburg manufacturing belt hosts specialized R&D facilities for next-generation substrate development.
India
Domestic FMCG brands adopt digital print for regional language versioning and festival-season customization. FSSAI labeling mandates and BIS standards constrain packaging material selection. The Mumbai-Pune industrial corridor attracts converter investment targeting both domestic consumption and Middle East export markets.
Digital Printed Pouch Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, creating a two-speed competitive dynamic. Billion-dollar multinationals leverage global extrusion networks and captive film supply to offer substrate-print integration at scale. Regional specialists compete on turnaround velocity and minimum order flexibility. Strategic moves concentrate on distributed manufacturing partnerships and barrier-coated paper R&D rather than capacity arms races.
Within the integrated multinational tier, Amcor and Mondi exemplify scale-driven positioning through global manufacturing footprints and dedicated technology centers. Among asset-light specialists, ePac Flexible Packaging occupies a distinctive position with its distributed micro-factory model targeting sub-ten-thousand-unit runs. These three entities represent contrasting archetypes: integrated substrate-print scale, technology-led substrate innovation, and velocity-focused distributed production.
| Leading Market Players |
|---|
| Amcor |
| ePac Flexible Packaging |
| Mondi |
| ProAmpac |
| BaiShen Pack |
| Sonoco Products Company |
| YLTPACK |
| Sealed Air Corporation |
| Wolfparc |
| Others |
Value Chain & Pricing Dynamics
Sixty-day plate-to-shelf cycles in rotogravure workflows concentrate pricing power with converters holding cylinder inventory, while digital print's same-day graphic changes compress lead times and redistribute margin capture toward asset-light regional specialists serving sub-ten-thousand-unit runs.
Pricing Analysis
After-sales service contracts for press maintenance and color management training drive lifetime value for digital press manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates HP Indigo-certified converters from Xeikon-tier regional players and entry-level inkjet operators. Cost compression in short-run segments is intensifying because ePac's distributed micro-factory model eliminates freight surcharges for local brands. Mid-sized snack producers in Germany show lowest price sensitivity for seasonal customization, while Asian confectionery exporters drive hardest on unit economics for commodity flat pouches.
Supply Chain Analysis
Inventory concentration in Israel, Japan, and the Netherlands for high-performance digital press manufacturing creates single-source vulnerability for converters expanding capacity. Raw material flows draw from German film extrusion clusters for BOPP, Chinese petrochemical corridors for CPP, and Dutch coating specialists for barrier-coated paper substrates. Tariff exposure on electrophotographic drums and UV-curable ink feedstocks threatens margin stability for North American converters. Distribution runs through converter-direct relationships with mid-sized brands, bypassing traditional broker networks in German-speaking markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital printed pouch adoption represents a high-growth disruption as EU Packaging and Packaging Waste Regulation recyclability mandates force substrate migration toward mono-material structures compatible with HP Indigo and Xeikon presses.
For Market Incumbents: Fortify captive film supply positions through backward integration into CPP extrusion for mono-material compliance, and lock in long-term service contracts with snack brands requiring seasonal graphic refreshes. Amcor's global substrate-print integration and Mondi's barrier-coated paper R&D centers exemplify defensive positioning against ePac's velocity-focused distributed manufacturing threat.
For New Entrants and Emerging Players: FDA food contact notification fast-track pathways for water-based ink formulations open white-space in direct-contact food applications previously restricted to solvent-based gravure. Target pharmaceutical compliance printing for track-and-trace serialization, and pursue distributed micro-factory partnerships in secondary US metro areas outside the Chicago-Milwaukee corridor.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because Extended Producer Responsibility scheme expansion across California, New York, and European markets structurally favors digitally printed recyclable structures over multi-layer laminate alternatives. Acquisition candidates include regional converters with installed HP Indigo capacity and established FDA ink certification pathways. Monitor state-level EPR law passage as inflection signal for demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Substrate Migration | EU PPWR compliance locks in converter specialization for CPP and polyethylene structures. |
| Water-Based Ink Formulation R&D | German snack brands specify REACH-compliant coatings for direct-contact applications. |
| Distributed Micro-Factory Expansion | ePac's regional hub model reduces logistics costs for mid-sized craft beverage producers. |
| Pharmaceutical Serialization Integration | FDA 21 CFR Part 11 mandates drive variable data printing adoption for compliance pouches. |
| Barrier-Coated Paper Scale-Up | Mondi's Eindhoven-Tilburg R&D facilities target plastic reduction commitments from premium brands. |
Study Parameters
The analysis maps stand-up pouch, flat pouch, and custom-shaped pouch sub-sectors, each validated through converter operations directors, brand packaging procurement managers, digital press field engineers, and regulatory compliance officers. Primary interview intelligence triangulates against secondary sources including FDA food contact notification databases, ECHA REACH Annex XVII substance restrictions, EU PPWR regulatory filings, and flexible packaging trade association capacity surveys. Bottom-up unit economics modeling and top-down value chain aggregation ensure cross-verification.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions include product type, material substrate, end-use vertical, and packaging format, with regional regulatory cluster as an industry-specific overlay. CAGRs derive from run-length compression trends, SKU proliferation rates, and substrate substitution elasticity. Forecast inputs incorporate digital press installation capacity, ink formulation certification timelines, and Extended Producer Responsibility scheme rollout schedules.
Decision-makers should treat outputs as directional under assumptions of continued EU PPWR enforcement and stable digital ink cost premiums; material deviation in regulatory stringency or feedstock pricing would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Brazil Pouch Packaging Market
Pouch
Flat Bottom Pouch Market
Pouch
Ziplock Products Market
Pouch
Canada Pouch Packaging Market
Pouch
Russia Pouch Packaging Market
Pouch
Stand-Up Pouches Market
Pouch
Heat Seal Pouch Market
Pouch
Thailand Pouch Packaging Market
Pouch
Doyen Style Pouches Market
Pouch
Spout and Non-Spout Liquid Pouch Packaging Market
Pouch
Asia-Pacific Pouch Packaging Market
Pouch
Argentina Pouch Packaging Market
Pouch
MAP Flow Wrappers Market
Pouch
Mexico Pouch Packaging Market
Pouch
Pouch Dispensing Fitment Market
Pouch
Child Resistant Single Dose Pouches Market