
 Oxygen Therapy Equipment Market | 2026-2036
Oxygen Therapy Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Therapy Equipment Market Intelligence
The shift towards high-efficiency, portable oxygen concentrators is unwinding the traditional reliance on stationary liquid oxygen systems for chronic care. Koninklijke Philips N.V. leverages its strong brand in home healthcare and connected care platforms to capture this trend. Inogen, Inc. specializes exclusively in portable oxygen concentrators, competing on device weight and battery duration. Linde Healthcare sustains a dominant position in the traditional medical gas supply chain for hospitals.
Oxygen therapy equipment encompasses medical devices designed to administer oxygen at concentrations higher than ambient air. These systems, including concentrators and cylinders, must deliver purified oxygen, often at purities exceeding 90%, to treat hypoxemia. Portable oxygen concentrators represent the fastest-growing product category, displacing traditional oxygen cylinders in ambulatory care. While Chronic Obstructive Pulmonary Disease (COPD) remains the principal application, the home care providers segment is expanding rapidly due to patient preference.
Regulatory oversight from bodies like the US FDA, which classifies these as Class II devices, and the European Union's MDR framework dictates stringent standards for safety. In China, the NMPA enforces specific GB standards for medical-grade oxygen concentrators, governing market access and post-market surveillance. Future competitive advantage will depend on integrating remote patient monitoring capabilities and navigating evolving reimbursement policies for home-based care.
Market Dynamics
The primary force shaping this market is the decentralization of chronic respiratory care. This shifts the market's center of gravity from hospital-based bulk gas supply towards patient-centric, portable electronic devices for home use, altering supply chains and competitive dynamics.
Growth Catalysts
- Miniaturization Technology:Advances in battery technology and pulse dose delivery systems enable the creation of lighter, more efficient portable oxygen concentrators.
- Aging Demographics:A growing elderly population with high incidences of COPD in developed nations like Japan and Germany creates a sustained demand base for long-term oxygen therapy.
- Home Care Expansion:Favorable reimbursement policies for out-of-hospital treatment are accelerating adoption within the home care providers segment as healthcare systems seek to reduce hospital stays.
Market Restraints
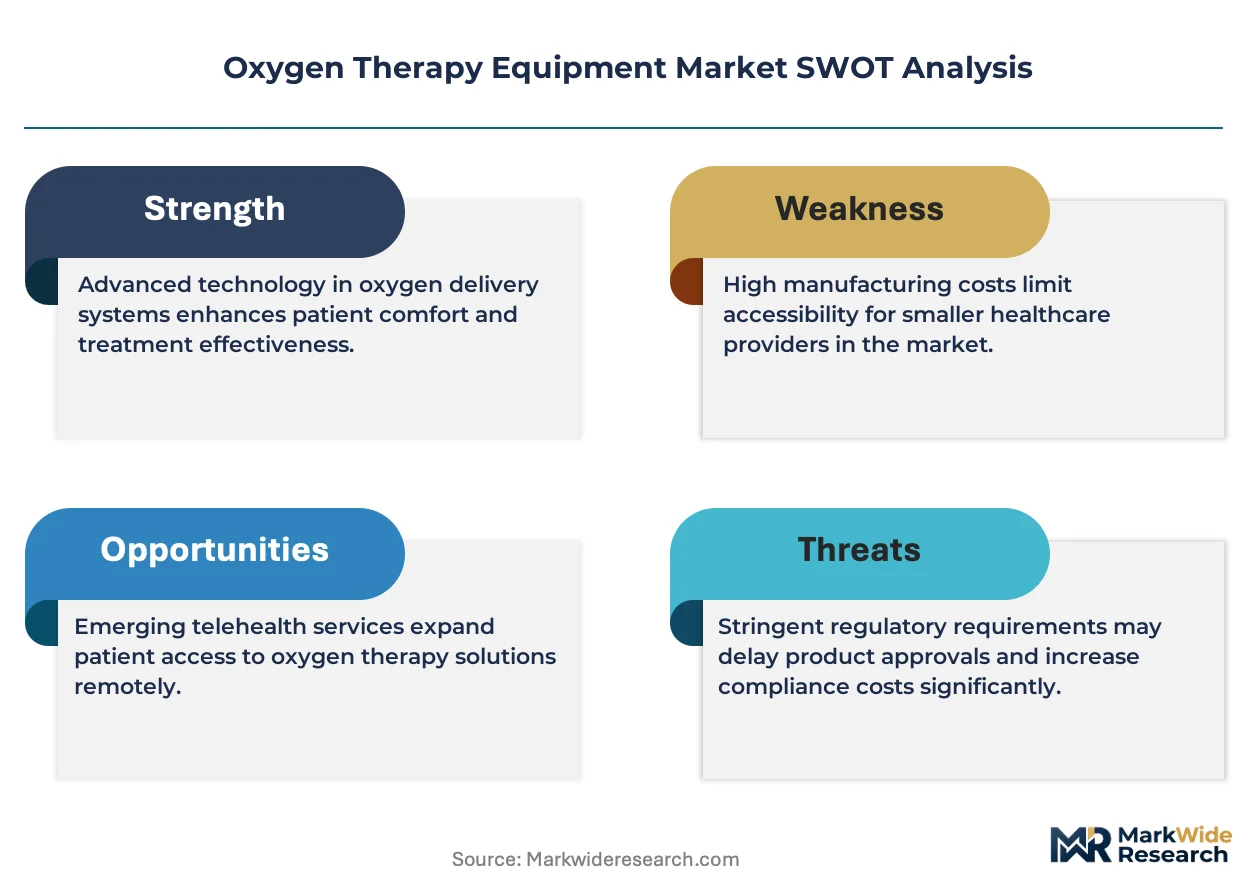
- Regulatory Scrutiny:Stringent classification as Class II devices by the US FDA and adherence to the EU's MDR framework impose significant development costs and lengthy approval timelines.
- Reimbursement Complexity:Inconsistent and often declining reimbursement rates for home oxygen equipment can limit patient access and provider investment in newer, more expensive technologies.
- High Initial Cost:The substantial upfront purchase price of advanced portable oxygen concentrators remains a barrier for many patients and providers compared to traditional oxygen cylinders.
Strategic Opportunities
- Remote Patient Monitoring:Integrating digital health platforms and sensors into oxygen concentrators offers a significant opportunity to provide real-time patient data and improve care outcomes.
- Emerging Economies:Untapped markets in regions with rising respiratory disease prevalence, such as India and Southeast Asia, present considerable expansion potential for accessible oxygen therapy solutions.
- Expanded Clinical Applications:Research into the efficacy of oxygen therapy for conditions beyond COPD, such as cluster headaches and palliative care, could open new niche markets.
Industry Challenges
- Component Supply Chains:Dependence on a limited number of suppliers for critical components like molecular sieves and specialized compressors creates vulnerability to supply chain disruptions and price volatility.
- Global Compliance Burden:Manufacturers face the operational complexity of navigating and maintaining compliance with disparate regulatory systems, including FDA, MDR, and NMPA standards, to achieve global market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Therapy Equipment Market |
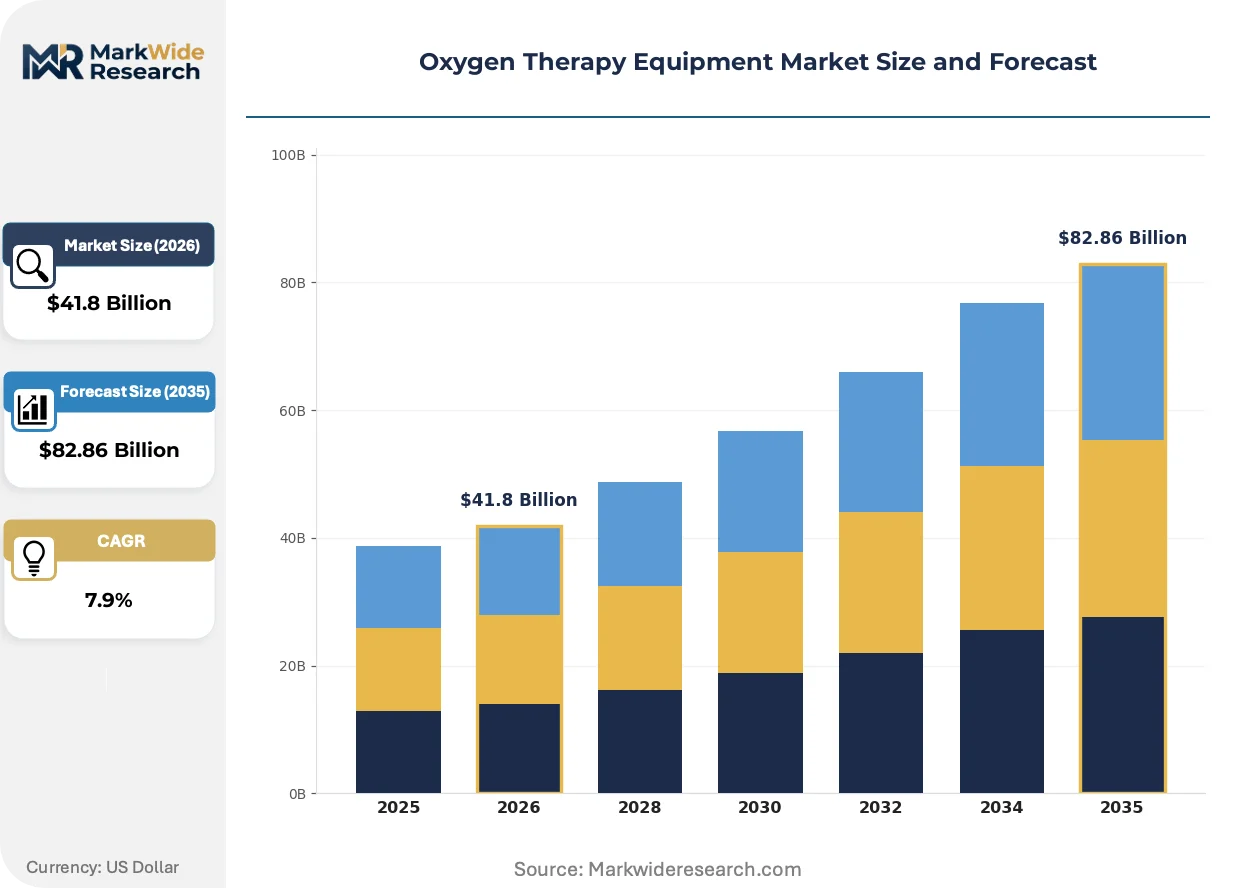
| Market Size in 2026 | $41.8 Billion |
| Market Size in 2035 | $82.86 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrators, Cylinders, Liquid Oxygen Systems, Portable Oxygen, Oxygen Conservers Application: Chronic Obstructive Pulmonary Disease, Pneumonia, Sleep Apnea, Pulmonary Fibrosis, Carbon Monoxide Poisoning End User: Hospitals, Home Care Providers, Rehabilitation Centers, Specialized Clinics, Long-Term Care Facilities Delivery Technology: Continuous Flow, Pulse Dose, Reservoir, Demand Flow Systems, Diaphragm Compressors |
| Companies Covered | Koninklijke Philips N.V., Linde Healthcare, Chart Industries, Invacare Corporation, Becton, Dickinson and Company, Fisher & Paykel Healthcare Limited, Drägerwerk AG & Co. KGaA, Teleflex Incorporated, Inogen, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Therapy Equipment Market Strategic Shifts & Innovations
The fundamental model for delivering respiratory support is shifting from a centralized, logistics-heavy gas supply chain to a decentralized, device-centric ecosystem. This transition prioritizes patient mobility and data connectivity over bulk oxygen distribution.
Advanced sieve bed materials and sophisticated pulse-dose algorithms enable smaller, lighter portable oxygen concentrators. Ambulatory patients with chronic conditions are the primary adopters, seeking active lifestyles. This technology trend is fragmenting the market once dominated by stationary systems, creating new segments based on device weight and battery duration.
Europe's Medical Device Regulation (MDR) has intensified the regulatory landscape. It mandates more rigorous clinical evidence and post-market surveillance, raising the bar for market entry. This affects all manufacturers, who must invest more in clinical data generation and quality management systems to maintain their CE marking for Class II devices.
A behavioral shift towards consumer-like purchasing criteria is evident, with patients prioritizing factors like device weight and noise level. This focus on user experience challenges the traditional durable medical equipment (DME) channel, which competed on cost and logistics. The consumerization trend is most apparent in North America, where patient choice heavily influences selection.
Oxygen Therapy Equipment Market Segmentation
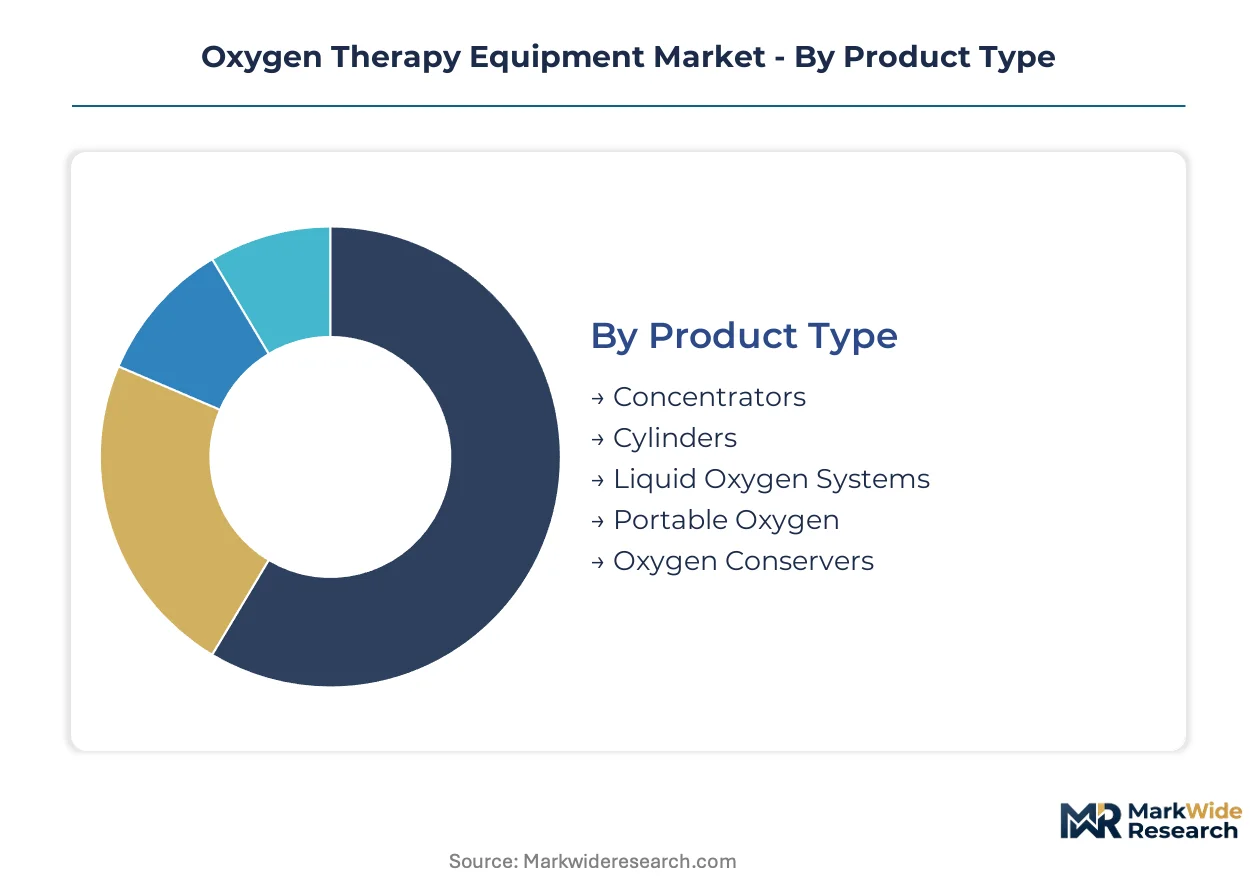
Market segmentation provides a granular view of the Oxygen Therapy Equipment landscape, revealing the interplay between product innovation, clinical applications, and evolving end-user preferences. This analysis highlights critical shifts in care delivery models and technological adoption across various segments.
Product Type:
The product landscape reflects a channel-driven shift, moving from institutional supply models to patient-centric devices distributed through varied outlets.
- Concentrators:These devices extract and purify oxygen from ambient air, providing a continuous supply without requiring refills. Demand concentrates in home care settings, particularly for aging populations in countries like Japan, driven by miniaturization technology.
- Portable Oxygen:These compact, battery-powered devices offer ambulatory patients increased mobility and independence for active lifestyles. Demand concentrates among home care providers as patients increasingly prefer treatment outside of hospital settings.
- Cylinders:These traditional systems store oxygen as high-pressure gas, requiring regular refills and transport.
- Liquid Oxygen Systems:These systems store oxygen in cryogenic form, providing a high-purity, long-lasting supply primarily for stationary use.
- Oxygen Conservers:These devices optimize oxygen delivery by releasing it only during inhalation, extending the duration of supply from cylinders or liquid oxygen systems.
Cylinders and stationary liquid oxygen systems dominate the installed base. Portable oxygen concentrators are where expansion concentrates.
Application:
Application segments highlight the primary disease burdens driving oxygen therapy demand and patient volume.
- Chronic Obstructive Pulmonary Disease:This long-term respiratory condition involves persistent airflow limitation, necessitating sustained oxygen therapy for symptom management. Demand concentrates in developed nations with aging demographics, such as Germany, due to high disease prevalence.
- Sleep Apnea:Characterized by intermittent breathing cessation during sleep, this condition often requires positive airway pressure or supplemental oxygen. Demand concentrates with improved diagnostic capabilities and patient preference for home-based treatment.
- Pneumonia:This acute lung infection can cause hypoxemia, requiring short-term oxygen support during recovery.
- Pulmonary Fibrosis:A progressive and irreversible lung disease involving scarring, pulmonary fibrosis often leads to chronic hypoxemia and a long-term need for oxygen.
- Carbon Monoxide Poisoning:This acute toxicity requires immediate high-concentration oxygen therapy to displace carbon monoxide from hemoglobin.
Chronic Obstructive Pulmonary Disease accounts for the largest patient volume. Sleep Apnea is gaining share fastest due to improved diagnostics.
End User:
End-user categories delineate where oxygen therapy is administered, reflecting evolving preferences for cost-efficient care settings.
- Home Care Providers:This segment delivers oxygen therapy directly to patient residences, emphasizing convenience and reducing hospital stays. Demand concentrates due to favorable reimbursement policies for out-of-hospital treatment.
- Hospitals:These acute care settings require high-flow oxygen for critical conditions, surgical recovery, and emergency interventions. Demand concentrates in traditional medical gas supply chains for inpatient care.
- Rehabilitation Centers:These facilities provide post-acute care, supporting patients in respiratory recovery and long-term pulmonary rehabilitation.
- Specialized Clinics:Outpatient clinics focus on specific respiratory conditions, offering diagnostic services and tailored oxygen therapy management.
- Long-Term Care Facilities:These institutions cater to extended patient stays, managing chronic conditions and providing continuous oxygen support.
Hospitals traditionally provided the majority of oxygen therapy. The market focus is now shifting towards home care providers for chronic conditions.
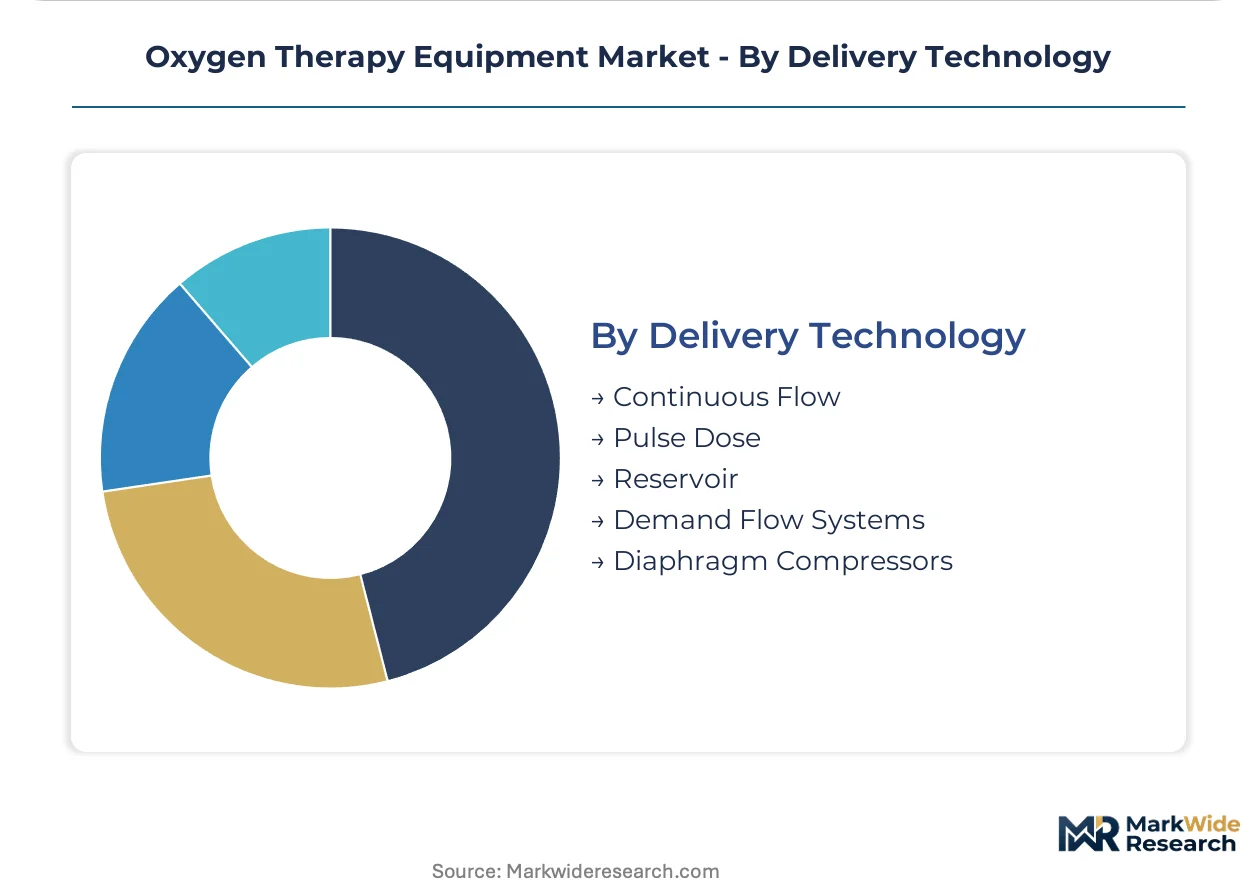
Delivery Technology:
Delivery technology segments illustrate innovations enhancing patient mobility and optimizing oxygen utilization for improved outcomes.
- Pulse Dose:This technology delivers oxygen in short, concentrated bursts only during the patient's inhalation, conserving the oxygen supply. Demand concentrates in portable oxygen concentrators, driven by battery miniaturization and active patient lifestyles.
- Continuous Flow:This traditional method provides a constant stream of oxygen, suitable for patients with higher liter flow requirements or severe hypoxemia. Demand concentrates in stationary concentrators and hospital settings.
- Reservoir:These systems store a small volume of oxygen for immediate delivery, often integrated into other devices to optimize efficiency.
- Demand Flow Systems:Similar to pulse dose, these systems deliver oxygen only when the patient initiates an inspiratory effort, enhancing efficiency.
- Diaphragm Compressors:These are critical components within oxygen concentrators, responsible for generating the air pressure required for oxygen separation.
Continuous flow systems remain foundational for high-volume oxygen delivery. Pulse dose technology is driving efficiency and portability in home care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global oxygen therapy equipment market reflects a complex interplay between manufacturing hubs and high-demand consumption regions. Countries with advanced medical device industries often serve as exporters, while nations with aging populations or rising respiratory disease prevalence drive significant import volumes. This dynamic shapes global supply chains for critical medical devices.
United States
The United States market experiences high demand due to an aging population and significant prevalence of Chronic Obstructive Pulmonary Disease. US FDA classification as Class II devices mandates rigorous safety and efficacy standards for market entry. The Boston-Cambridge biomedical cluster actively develops advanced pulse dose delivery systems.
Germany
Germany exhibits robust demand, driven by its aging demographics and a strong emphasis on decentralized chronic respiratory care. The European Union's MDR framework dictates stringent standards for device safety and clinical evidence. Bavaria's medical technology sector concentrates on developing high-efficiency compressors for concentrators.
Japan
Japan's market sees sustained demand from its rapidly aging population and high prevalence of chronic respiratory conditions. PMDA regulations ensure strict oversight for medical devices, including oxygen concentrators. Tokyo's medical device ecosystem fosters integrating digital health platforms into home-based oxygen therapy.
China
Demand in China is expanding due to a rising prevalence of respiratory diseases and increasing access to healthcare services. The NMPA enforces specific GB standards for medical-grade oxygen concentrators, controlling domestic market access. The Yangtze River Delta region serves as a significant manufacturing hub for medical device components.
India
India presents a substantial market opportunity, driven by its large population and a high burden of respiratory infections. CDSCO regulations govern the import and manufacturing of medical devices to ensure quality standards. Bengaluru's med-tech startups are actively developing cost-effective, portable oxygen therapy solutions.
Oxygen Therapy Equipment Market Key Industry Players
Listed leaders compete with private specialists across the rapidly evolving home care and portable device segments. The market structure exhibits a blend of established industrial gas suppliers and specialized medical device manufacturers. Strategic archetypes include diversified healthcare conglomerates, focused portable oxygen concentrator innovators, and traditional medical gas providers. Companies frequently engage in strategic partnerships for technology co-development and pursue geographic expansion into emerging economies.
Specialists in portable oxygen concentrators, such as Inogen, Inc., exemplify the market's shift towards patient mobility and device miniaturization. This California-based company competes on device weight and battery duration. Koninklijke Philips N.V., a Netherlands-based conglomerate, occupies a position leveraging its strong brand in home healthcare and connected care platforms, integrating connected care solutions. Linde Healthcare, a global industrial gas company, anchors the traditional medical gas supply chain for hospitals and long-term care facilities, sustaining its dominant position. These entities represent distinct approaches to serving the diverse needs of the oxygen therapy market, from high-tech personal devices to large-scale institutional supply.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Linde Healthcare |
| Chart Industries |
| Invacare Corporation |
| Becton, Dickinson and Company |
| Fisher & Paykel Healthcare Limited |
| Drägerwerk AG & Co. KGaA |
| Teleflex Incorporated |
| Inogen, Inc. |
| Others |
Cost & Logistics Intelligence
The US FDA's Class II device classification gates both supply qualification and price differentiation for oxygen therapy equipment, particularly impacting advanced portable concentrators. This regulatory barrier influences market access and cost structures for manufacturers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for bulk medical gases and hospital-grade equipment. Price differentiation stems from CE marking certification levels for European distribution and the integration of remote patient monitoring capabilities. Pricing softness for home-based portable concentrators stems from declining reimbursement rates and intense competition on device weight. Home care providers exhibit higher price sensitivity compared to hospitals, which prioritize reliability and large-scale supply.
Supply Chain Analysis
Strategic stockpiling of critical components mitigates supply chain disruptions for oxygen therapy equipment manufacturers. Component supply concentrates in China for specialized compressors and molecular sieves, with battery components sourced from East Asian producers. Single-source vulnerability for these specialized inputs creates significant price volatility. Distribution runs through established durable medical equipment channels and increasingly direct-to-patient models for portable devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oxygen therapy equipment market presents a defensive moat, largely due to regulatory entrenchment and high switching costs for chronic care patients. This stability underpins long-term investment viability despite evolving technological landscapes.
For Market Incumbents: Secure long-term contracts with large hospital networks and Group Purchasing Organizations to counter margin pressure from new portable device entrants. Invest in US FDA and EU MDR certification for next-generation pulse dose delivery systems, leveraging existing regulatory expertise. Deepen vertical integration into specialized compressor manufacturing to mitigate component supply chain vulnerability. Expand connected care platforms to enhance patient retention and differentiate from lower-cost alternatives.
For New Entrants and Emerging Players: NMPA fast-track approvals in China offer a pathway for market entry for accessible oxygen therapy solutions. Target the emerging economies segment, particularly India and Southeast Asia, with cost-effective portable oxygen concentrators. Focus on expanded clinical applications beyond COPD, such as cluster headaches, leveraging direct-to-consumer digital marketing. Emphasize device weight and battery duration as primary go-to-market differentiators for active patient lifestyles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downwards across the home care providers segment due to the rise of portable, electronic devices. The long-term viability of this market over a five-to-ten-year window remains strong, driven by aging populations and decentralization trends. Target mid-cap specialists in digital health platforms and remote patient monitoring, offering recurring revenue streams. A critical signal to watch is the adoption rate of software-as-a-service models for home-based oxygen therapy management.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Validates device safety and efficacy for critical US market access. |
| CE Marking Pathway | Ensures compliance with European Union's stringent MDR framework. |
| Hospital System Partnership | Secures long-term contracts for traditional medical gas supply chains. |
| Software Companion Development | Integrates remote patient monitoring for enhanced care management. |
| Reimbursement Strategy Optimization | Improves patient access and provider investment in advanced technologies. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during primary research, including clinicians, hospital procurement managers, and medical device engineers. This primary data was validated against extensive secondary sources like US FDA filings, EU MDR documentation, and company annual reports. The analysis employed both bottom-up and top-down triangulation to ensure robust market sizing. This comprehensive approach informed volume and value assessments.
The analysis window encompasses a detailed analytical framework, segmenting the market by product type, application, end user, and delivery technology. Compound annual growth rates were derived from historical data trends and projected shifts in demand drivers. Key forecast inputs included aging demographics in developed nations and rising respiratory disease prevalence globally. This multi-dimensional modeling ensures granular market insights over the projection horizon.
Decision-makers should treat outputs as directional under current reimbursement policies and regulatory frameworks; material deviation would warrant model refresh. Forecasts reflect assumptions on technological advancements and component supply chain stability. Revision becomes warranted when major regulatory shifts or unforeseen supply disruptions cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Brazil Therapeutic Respiratory Devices Market
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
Virus-Induced Asthma Treatment Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market
Respiratory Therapy
Breathing Disorders Treatment Market
Respiratory Therapy
Pediatric Respiratory Disease Treatment Market
Respiratory Therapy
United States Idiopathic Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Bronchial Thermoplasty Market
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Artificial Lung Market
Respiratory Therapy
Emphysema Treatment Market
Respiratory Therapy
Healthcare Powered Air Purifying Respirator Market
Respiratory Therapy
Respiratory Disorders Treatment Market
Respiratory Therapy
Respiratory Inhaler Market
Respiratory Therapy
Interventional Pulmonology Market
Respiratory Therapy
Nitric Oxide Management Systems Market