
 Severe Acute Respiratory Syndrome Treatment Market | 2026-2036
Severe Acute Respiratory Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Severe Acute Respiratory Syndrome Treatment Market Analytics
Hospital systems are reorganizing their formulary priorities around respiratory antivirals and intensive care biologics, shifting procurement budgets away from chronic disease portfolios. Pfizer Inc leverages its manufacturing scale to secure multi-year hospital supply agreements across North America and Europe. Roche Holding AG differentiates through diagnostic-therapeutic integration, pairing its respiratory testing platforms with biologic treatment protocols. Gilead Sciences Inc anchors its position in antiviral development, sustaining R&D investment in RNA-targeting mechanisms for coronaviral infections.
Severe Acute Respiratory Syndrome treatment encompasses pharmacological and supportive interventions targeting acute viral pneumonia with systemic inflammatory progression, typically involving oxygen supplementation, mechanical ventilation coordination, and targeted antiviral or immunomodulatory administration. Monoclonal antibodies and antivirals command the primary therapeutic focus, with intravenous delivery dominating critical care settings due to rapid bioavailability requirements in deteriorating patients. The hospital end-user segment leads absolute consumption, though home care channels are expanding for post-acute recovery protocols. Pulmonary disorders and infectious diseases therapy areas concentrate the majority of clinical trial investment and regulatory priority.
The FDA, EMA, and WHO shape market access through emergency use authorization frameworks, adaptive licensing pathways, and prequalification standards that determine which therapies reach outbreak-response stockpiles. China's NMPA accelerates domestic approval timelines for respiratory biologics, creating parallel regulatory tracks that influence multinational development strategies. Stakeholders must monitor how national pandemic preparedness budgets and critical care infrastructure investments reshape procurement concentration across health system tiers.
Market Dynamics
Hospital procurement officers are consolidating respiratory therapeutic purchasing into centralized pandemic preparedness frameworks, compressing vendor selection cycles and favoring suppliers with integrated diagnostic-therapeutic platforms over standalone pharmaceutical vendors.
Growth Catalysts
- EMA Adaptive Pathway Programs:The European Medicines Agency's accelerated approval mechanisms for respiratory biologics compress clinical trial timelines, enabling faster market entry for novel monoclonal antibody therapies targeting severe viral pneumonia.
- Intensive Care Capacity Expansion:Health systems in Germany, the United States, and China are retrofitting general wards into high-dependency respiratory units, creating sustained demand for intravenous antiviral delivery systems and mechanical ventilation coordination protocols.
- RNA-Targeting Platforms:Next-generation nucleoside analog mechanisms are displacing older polymerase inhibitors in hospital formularies, driven by superior efficacy against emergent coronaviral variants with reduced resistance profiles.
Market Restraints
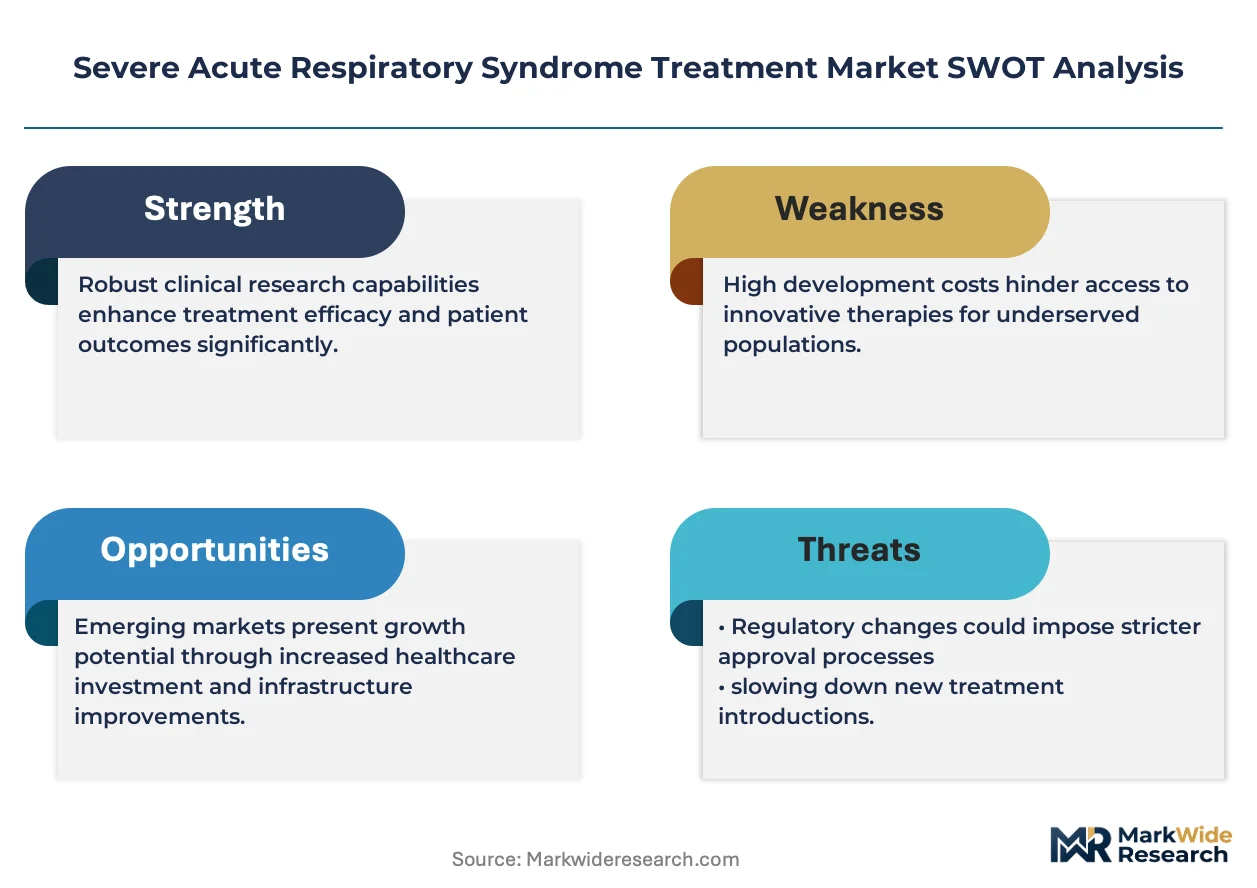
- Active Pharmaceutical Ingredient Concentration:Over 70% of antiviral raw material synthesis concentrates in Chinese and Indian contract manufacturing organizations, exposing supply continuity to geopolitical friction and export restriction risk.
- Cold Chain Infrastructure Gaps:Monoclonal antibody therapies requiring minus 70-degree Celsius storage face distribution bottlenecks in secondary and tertiary hospital networks across Eastern Europe and Southeast Asia.
- Reimbursement Compression:National health technology assessment bodies in France, England, and Italy are tightening cost-effectiveness thresholds for novel respiratory biologics, extending market access negotiation timelines by 12-18 months post-approval.
Strategic Opportunities
- Post-Acute Home Care Channels:Subcutaneous antiviral formulations and portable oxygen concentrators are opening reimbursement pathways for hospital-at-home recovery protocols in Medicare Advantage and private payer networks across the United States.
- WHO Prequalification Standards:Alignment with World Health Organization outbreak response stockpile criteria creates procurement access to government pandemic reserves in 40+ low and middle-income countries lacking domestic regulatory capacity.
- Diagnostic-Therapeutic Integration:Multiplex respiratory panels combined with AI-guided treatment algorithms are compressing time-to-therapy initiation in emergency departments, creating bundled purchasing opportunities for platform vendors.
Industry Challenges
- Specialized Critical Care Workforce Scarcity:Pulmonary-critical care physicians and respiratory therapists trained in mechanical ventilation management and extracorporeal membrane oxygenation coordination remain concentrated in academic medical centers, limiting protocol rollout to community hospitals.
- Multipurpose Manufacturing Facility Conversion:Antiviral active pharmaceutical ingredient production requires dedicated containment infrastructure that cannot pivot to other therapeutic categories, stranding capital during demand troughs between outbreak cycles.
- Regulatory Divergence Across Jurisdictions:China's NMPA, the FDA, and EMA maintain non-harmonized stability testing and viral clearance validation standards, forcing parallel development tracks that duplicate clinical and manufacturing documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Severe Acute Respiratory Syndrome Treatment Market |
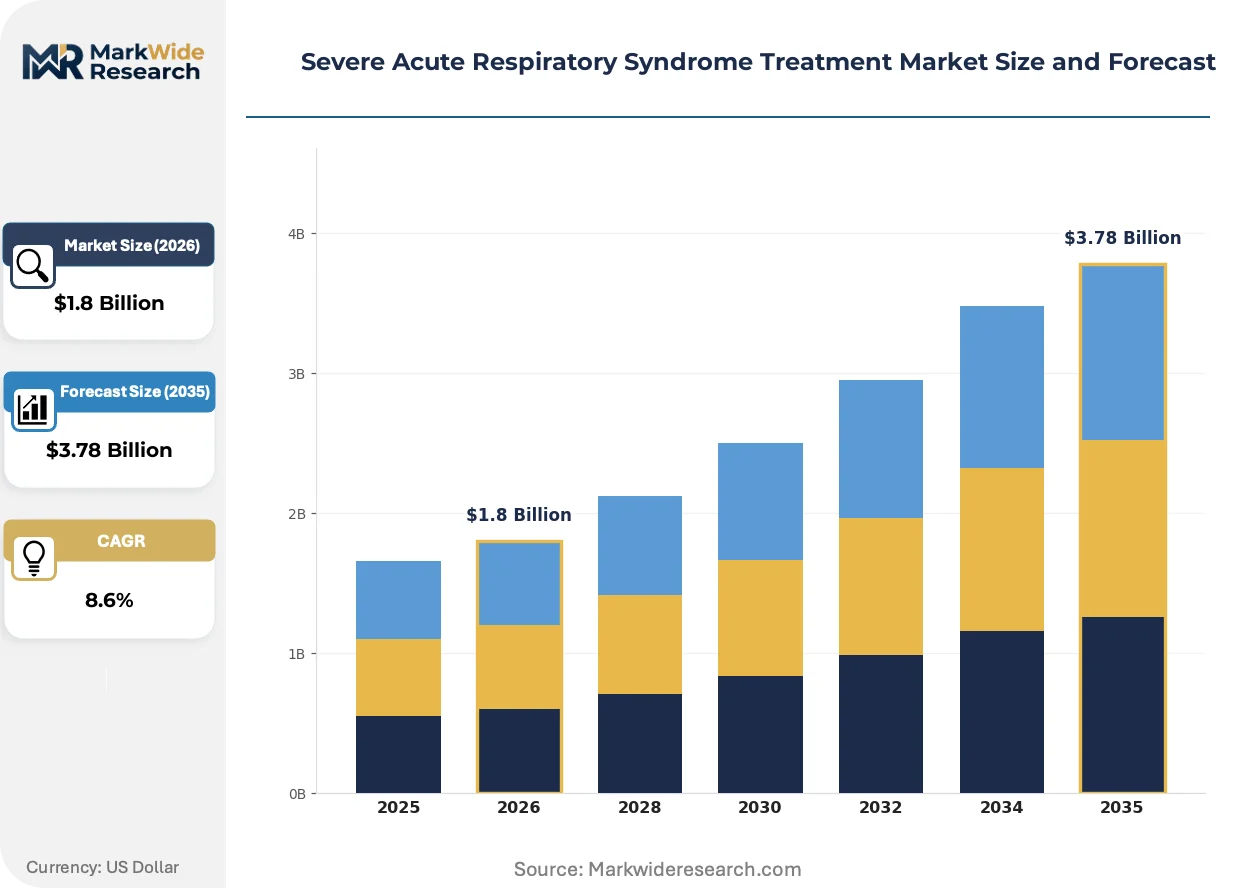
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirals, Monoclonal Antibodies, Vaccines, Supportive Care Delivery Mode: Intravenous, Inhalation, Oral, Subcutaneous End User: Hospitals, Clinics, Home Care, Research Laboratories Therapy Area: Pulmonary Disorders, Infectious Diseases, Critical Care, Immunology |
| Companies Covered | Pfizer Inc, Novartis AG, GlaxoSmithKline plc, Johnson & Johnson, Roche Holding AG, AbbVie Inc, Sanofi S.A, Gilead Sciences Inc, AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Severe Acute Respiratory Syndrome Treatment Market Evolving Landscape
Respiratory therapeutic development is converging around point-of-care delivery systems and algorithm-guided dosing, compressing the gap between diagnosis and treatment initiation while reducing reliance on centralized pharmacy infrastructure.
Portable nebulizer technologies incorporating vibrating mesh atomization are miniaturizing antiviral and bronchodilator delivery systems for emergency department and ambulance deployment. Hospital systems in Texas, Bavaria, and Zhejiang Province are piloting these devices for pre-hospital respiratory failure intervention. The technology is miniaturizing treatment initiation from centralized intensive care units to first-responder environments, expanding the addressable patient window before mechanical ventilation becomes necessary.
The FDA's Project NextGen initiative is streamlining immunobridging study designs for updated coronaviral monoclonal antibodies, reducing reliance on large-scale efficacy trials during variant emergence. This regulatory flexibility accelerates iterative product updates but intensifies post-market surveillance obligations for sponsors. Biologic developers are responding by embedding real-world evidence collection infrastructure directly into hospital distribution agreements.
Health system purchasing consortia are consolidating respiratory therapeutic procurement into multi-year framework contracts with volume guarantees and price escalation caps. Group purchasing organizations in the United States and hospital alliance networks in Germany are displacing individual hospital formulary decisions with centralized therapeutic class reviews. This concentration is most visible in academic medical center systems, where procurement committees now prioritize suppliers offering integrated training and outcomes reporting alongside product supply.
Severe Acute Respiratory Syndrome Treatment Market Segmentation
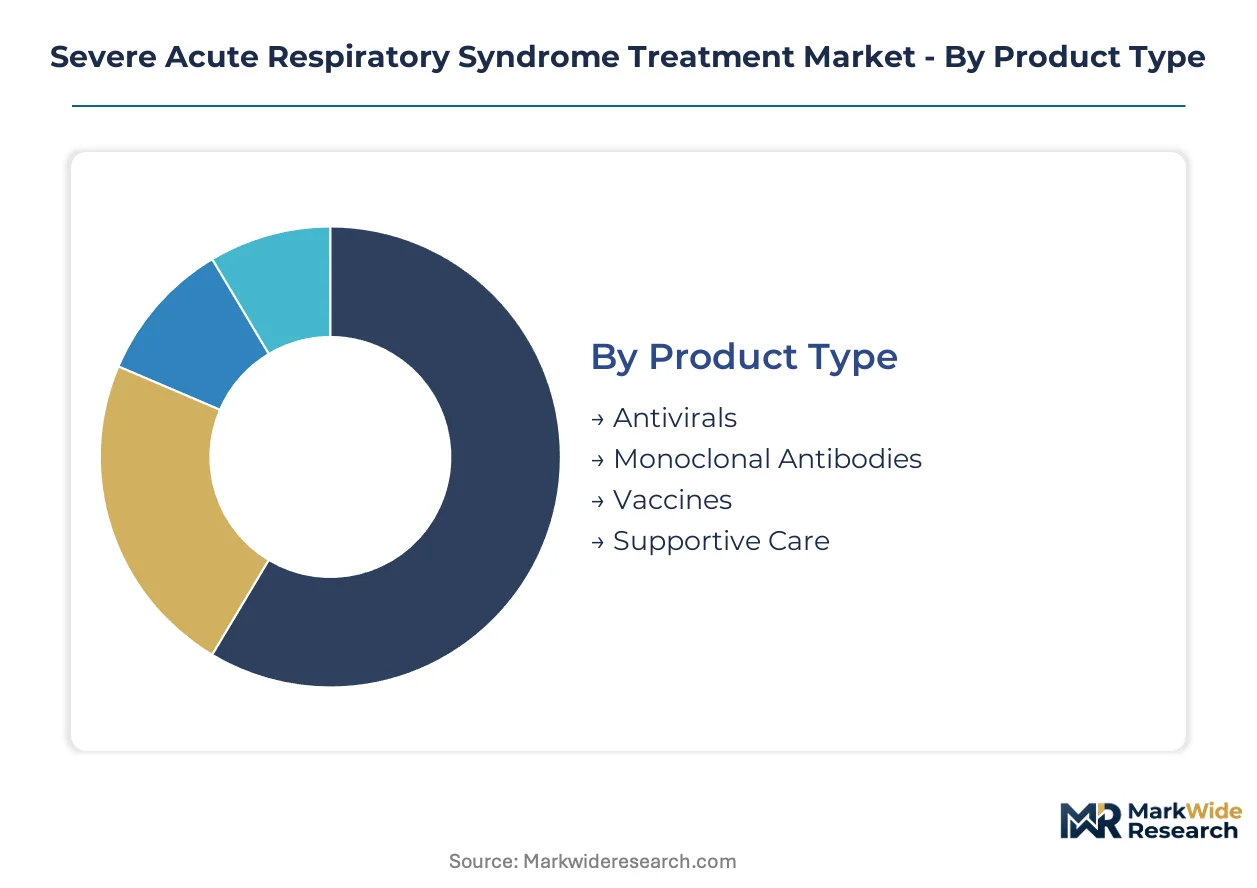
Treatment modality selection in severe respiratory syndrome management hinges on disease severity staging, bioavailability requirements, and care setting capabilities. Segmentation reveals how hospital procurement frameworks prioritize rapid-onset delivery systems while post-acute channels drive formulation diversification.
Product Type:
Antivirals face intensifying substitution pressure from monoclonal antibodies in critical care protocols, where immunomodulatory mechanisms demonstrate superior efficacy in cytokine storm management.
- Antivirals:RNA polymerase inhibitors and nucleoside analogs form the pharmacological backbone of early-stage intervention. Hospital formularies in the United States and Germany are prioritizing agents with pan-coronaviral activity to reduce resistance-driven obsolescence.
- Monoclonal Antibodies:Engineered immunoglobulins targeting spike protein epitopes or inflammatory cytokines command premium procurement budgets in intensive care units. China's NMPA accelerated approval pathways are expanding domestic manufacturing capacity for these biologics.
- Vaccines:Prophylactic immunization remains outside acute treatment protocols but shapes market preparedness dynamics.
- Supportive Care:Oxygen delivery systems, mechanical ventilation coordination, and extracorporeal membrane oxygenation sustain patients through respiratory failure.
Antivirals anchors the volume base while monoclonal antibodies gains share at the steepest rate.
Delivery Mode:
Cost tier differentiation separates emergency department deployment from step-down care, with intravenous systems commanding infrastructure investment while subcutaneous alternatives reduce per-dose administration burden.
- Intravenous:Direct vascular administration achieves therapeutic plasma concentrations within minutes of infusion initiation. Academic medical centers in Texas and Bavaria are standardizing smart-pump integration with electronic health record systems to reduce dosing errors.
- Subcutaneous:Depot formulations and prefilled autoinjectors enable post-acute administration without vascular access maintenance. Medicare Advantage networks are piloting reimbursement for home-based subcutaneous antiviral protocols.
- Inhalation:Nebulized delivery targets pulmonary tissue directly, reducing systemic exposure.
- Oral:Capsule and tablet formulations serve prophylactic and mild-disease outpatient management.
Intravenous dominates value capture while subcutaneous expands most quickly into ambulatory settings.
End User:
Customer type concentration reflects care acuity gradients, with tertiary hospitals absorbing complex mechanical ventilation cases while home care channels capture stable post-intensive care transitions.
- Hospitals:Tertiary and quaternary centers concentrate extracorporeal membrane oxygenation capabilities and specialized pulmonary-critical care staffing. Group purchasing organizations are consolidating antiviral procurement across multi-hospital systems.
- Home Care:Portable oxygen concentrators and remote patient monitoring platforms extend recovery protocols beyond discharge. Zhejiang Province health authorities are reimbursing hospital-at-home respiratory management.
- Clinics:Urgent care and outpatient infusion centers handle stable patients requiring parenteral therapy.
- Research Laboratories:Contract research organizations and academic centers conduct therapeutic development and variant surveillance.
Hospitals anchors the volume base while home care gains share at the steepest rate.
Therapy Area:
Application maturity varies across clinical domains, with infectious disease protocols well-established while immunology-directed interventions represent emerging therapeutic frontiers.
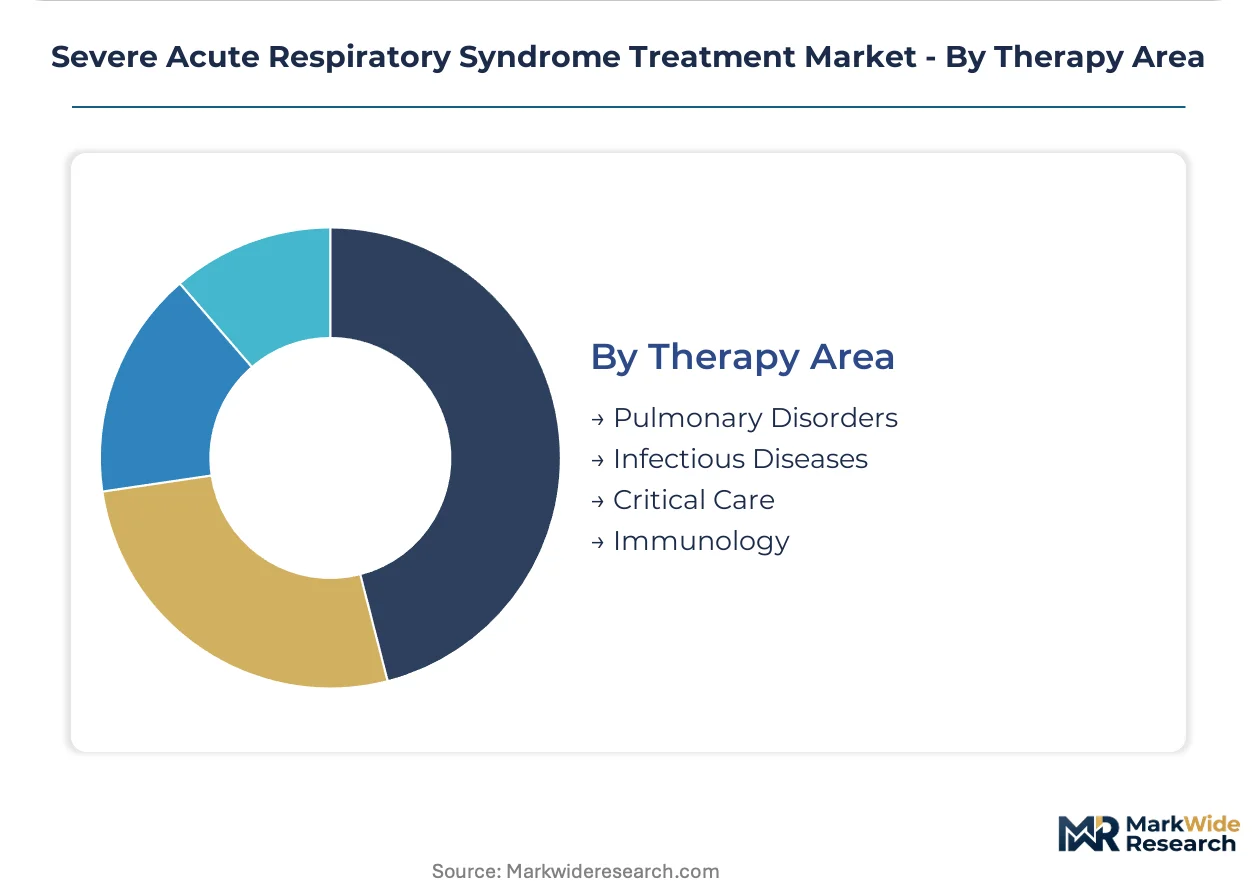
- Pulmonary Disorders:Acute respiratory distress syndrome management and mechanical ventilation weaning protocols define core clinical competency. German hospital networks are retrofitting general wards into high-dependency respiratory units.
- Critical Care:Multi-organ support coordination and hemodynamic stabilization frame the most resource-intensive treatment segment. The FDA's emergency use authorization frameworks prioritize therapies demonstrating mortality reduction in this population.
- Infectious Diseases:Viral load suppression and resistance surveillance guide antiviral selection.
- Immunology:Cytokine modulation and immune reconstitution address hyperinflammatory complications.
Pulmonary disorders anchors the volume base while immunology climbs the fastest as precision biologics penetrate protocol guidelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure anchors European distribution networks for temperature-sensitive biologics, while the Beijing-Shanghai high-speed rail corridor enables rapid domestic transport of antiviral stockpiles across China's hospital procurement zones.
United States
Academic medical centers in Texas and Massachusetts drive monoclonal antibody protocol adoption through intensive care research consortia. The FDA's Project NextGen initiative compresses immunobridging study timelines for updated coronaviral therapeutics. Hospital alliance networks in the Northeast Corridor consolidate procurement into multi-year framework contracts with integrated outcomes reporting requirements.
Germany
Bavarian hospital networks retrofit general wards into high-dependency respiratory units, sustaining demand for intravenous antiviral delivery systems. The EMA's adaptive pathway programs accelerate respiratory biologic approvals through rolling data submission frameworks. The Rhine-Ruhr metropolitan cluster concentrates pulmonary-critical care physician training programs that limit protocol rollout capacity to community hospitals.
China
Zhejiang Province health authorities reimburse hospital-at-home respiratory management, expanding post-acute care channels beyond tertiary facilities. The NMPA accelerates domestic approval timelines for respiratory biologics through parallel regulatory tracks. The Yangtze River Delta manufacturing belt concentrates contract manufacturing organization capacity for antiviral active pharmaceutical ingredient synthesis.
United Kingdom
NHS England's specialized commissioning frameworks concentrate extracorporeal membrane oxygenation capabilities in London and Manchester academic centers. The MHRA aligns with EMA emergency use authorization standards while maintaining independent viral clearance validation requirements. The Cambridge-Oxford-London life sciences triangle anchors respiratory therapeutic development infrastructure for clinical trial execution.
India
CDSCO accelerated approval pathways for respiratory antivirals expand access to government hospital procurement systems in Maharashtra and Karnataka. The country's national pharmaceutical regulator harmonizes stability testing standards with WHO prequalification criteria for outbreak response stockpiles. Hyderabad's pharmaceutical manufacturing cluster scales nucleoside analog production for export to Southeast Asian and African markets.
Severe Acute Respiratory Syndrome Treatment Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and diagnostic-therapeutic integration capabilities. The vendor base stratifies into three tiers: multinational pharmaceutical conglomerates with hospital supply agreements, mid-cap biologics developers with EMA adaptive pathway approvals, and regional generic manufacturers serving government procurement tenders. Strategic archetypes include platform integrators bundling testing with treatment, scale operators securing multi-year volume guarantees, and niche developers targeting cytokine storm immunomodulation. Competitive moves concentrate on diagnostic-therapeutic bundling and backward integration into active pharmaceutical ingredient production.
Among scale-driven pharmaceutical conglomerates, Pfizer Inc and Roche Holding AG exemplify divergent strategic positioning. Pfizer leverages manufacturing scale to anchor hospital procurement frameworks across North American and European health systems. Roche occupies a position within the platform integration archetype, pairing diagnostic testing infrastructure with biologic treatment protocols. Gilead Sciences Inc sits within the antiviral specialization tier, sustaining RNA-targeting mechanism development for coronaviral infections. Each represents distinct competitive vectors: manufacturing scale, diagnostic-therapeutic bundling, and therapeutic mechanism focus.
| Leading Market Players |
|---|
| Pfizer Inc |
| Novartis AG |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Roche Holding AG |
| AbbVie Inc |
| Sanofi S.A |
| Gilead Sciences Inc |
| AstraZeneca plc |
| Others |
Value Network & Pricing Analysis
RNA-targeting nucleoside analogs displacing older polymerase inhibitors simultaneously concentrate active pharmaceutical ingredient synthesis in China's Yangtze River Delta and compress pricing premiums for first-generation antivirals. Hospital procurement officers exploit this substitution dynamic to renegotiate multi-year supply agreements around pan-coronaviral efficacy benchmarks rather than branded molecule loyalty.
Pricing Analysis
Three-tier pricing structure across premium monoclonal antibodies, standard antiviral formulations, and economy-positioned supportive care equipment dominates hospital procurement frameworks. Price differentiation separates spike-protein-targeting biologics with EMA adaptive pathway approval from nucleoside analogs facing generic substitution pressure. Pricing pressure stems from group purchasing organization consolidation in the United States and Germany, where volume guarantees override individual hospital formulary autonomy. Community hospitals and secondary care networks exhibit highest price sensitivity, while academic medical centers prioritize clinical outcomes data over per-dose cost.
Supply Chain Analysis
Cold chain infrastructure gaps at the Port of Rotterdam pharmaceutical hub bottleneck monoclonal antibody distribution to Eastern European hospital networks. Active pharmaceutical ingredient synthesis draws from contract manufacturing organizations in China, India, and Switzerland, with nucleoside analog intermediates particularly concentrated in Hyderabad and Zhejiang Province. Single-source vulnerability characterizes minus 70-degree Celsius storage equipment procurement, where German and Japanese suppliers dominate. Distribution runs through hospital alliance networks and government pandemic stockpile managers rather than traditional pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as post-acute home care channels and diagnostic-therapeutic integration create distinct vendor archetypes outside traditional pharmaceutical scale economics. Demand-side shift toward hospital-at-home reimbursement protocols in Medicare Advantage and Zhejiang Province splits procurement authority between centralized hospital systems and distributed home care providers.
For Market Incumbents: Secure backward integration into active pharmaceutical ingredient production to offset Chinese and Indian contract manufacturing concentration risk. Anchor hospital procurement frameworks with integrated diagnostic-therapeutic platforms that bundle respiratory testing with biologic treatment protocols. Capacity expansion in Bavaria and Texas academic medical center corridors reinforces intensive care unit formulary control against mid-cap biologics developers with EMA adaptive pathway approvals.
For New Entrants and Emerging Players: WHO prequalification fast-track alignment opens government pandemic reserve procurement in 40-plus low and middle-income countries lacking domestic regulatory capacity. Subcutaneous antiviral formulations for hospital-at-home protocols represent the most penetrable segment, with Medicare Advantage networks piloting reimbursement pathways. Go-to-market angle centers on portable nebulizer technologies with vibrating mesh atomization for emergency department and ambulance deployment.
For Investors and Strategic Acquirers: Capital is best deployed toward diagnostic-therapeutic platform integrators with embedded real-world evidence collection infrastructure. Long-term viability over the next decade hinges on regulatory agility for iterative monoclonal antibody updates under FDA Project NextGen immunobridging study frameworks. Signal to watch is NMPA domestic approval timeline compression for respiratory biologics, which would validate parallel regulatory track strategies and strain multinational development resource allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Adaptive Pathway Alignment | Rolling data submission compresses respiratory biologic approval timelines for Bavarian hospital networks. |
| Diagnostic-Therapeutic Platform Integration | Multiplex respiratory panels with AI-guided algorithms bundle testing and treatment for emergency departments. |
| Cold Chain Infrastructure Investment | Minus 70-degree Celsius storage capacity expansion addresses distribution bottlenecks in Eastern Europe. |
| WHO Prequalification Standardization | Outbreak response stockpile criteria unlock government procurement in low and middle-income countries. |
| Subcutaneous Formulation Development | Depot antiviral delivery enables hospital-at-home reimbursement in Medicare Advantage networks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA emergency use authorization filings, EMA adaptive pathway submission data, ClinicalTrials.gov respiratory therapeutic protocols, and hospital procurement database records. Drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided qualitative input on formulary prioritization and reimbursement negotiation dynamics. Bottom-up patient population modeling and top-down health system expenditure analysis triangulate market size estimates.
Segmentation dimensions modeled include treatment modality, delivery mode, end-user care setting, and therapy area specialization across the projection horizon. CAGRs derive from epidemiological forecasting for severe viral pneumonia incidence, health system intensive care capacity expansion plans, and regulatory approval timeline probability weighting. Forecast inputs incorporate NMPA domestic approval acceleration scenarios and EMA rolling review framework adoption rates.
The analysis sits within stated boundaries; outcomes outside sustained pandemic preparedness budget allocation or harmonized regulatory standards would require recalibration. Forecasts assume continued emergency use authorization framework utilization and stable contract manufacturing organization export capacity. Practitioners should keep alternative scenarios live as geopolitical friction around active pharmaceutical ingredient trade and reimbursement compression in European health technology assessment bodies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market
Respiratory Therapy
Interventional Pulmonology Market
Respiratory Therapy
Viral Pneumonia Treatment Market
Respiratory Therapy
Chronic Obstructive Pulmonary Disease Treatment Market
Respiratory Therapy
Global Pulmonary Surfactant Market
Respiratory Therapy
Asia-Pacific Topical Oxygen Therapy Market
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
United States Idiopathic Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Cough Systems Market
Respiratory Therapy
Metered Dose Inhalers Market
Respiratory Therapy
Global Bronchitis Treatment Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
Pediatric Respiratory Disease Treatment Market