
 Medical Smart Glasses Market | 2026-2036
Medical Smart Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Smart Glasses Market Outlook
Modular hardware-software bundles are replacing standalone device sales and is realigning procurement patterns across hospital systems. Vuzix leverages its optical waveguide manufacturing to sustain premium positioning in surgical visualization. Google competes through cloud-integrated software stacks that anchor enterprise health deployments. EssilorLuxottica dominates prescription-compatible frame design, extending its eyewear channel control into clinical settings.
Medical smart glasses combine near-eye displays, optical see-through waveguides, and biometric sensors to overlay diagnostic data onto a clinician's field of view during live procedures. These devices process real-time imaging feeds, patient vitals, and navigation cues through edge computing architectures with sub-40ms latency to preserve surgical precision. Augmented reality glasses now lead hardware shipments as hospitals prioritize hands-free information access over fully immersive virtual reality isolation. Surgery assistance applications command the deepest margin pools because institutions pay premium pricing for FDA-cleared platforms that reduce operative time and complication rates. Bluetooth connectivity remains the baseline technology layer, though eye tracking is gaining fastest as surgeons demand gaze-controllable interfaces that eliminate physical contact with sterile equipment.
FDA 510(k) clearance requirements and CE marking under the EU Medical Device Regulation shape product development timelines and constrain market access for uncertified entrants. The FCC governs wireless transmission protocols for connected glasses in the United States, while ISO 13485 quality management standards govern manufacturing audits for international suppliers. Stakeholders must monitor evolving cybersecurity guidance from health regulators as network-connected eyewear becomes standard in operating rooms and remote consultation workflows.
Market Dynamics
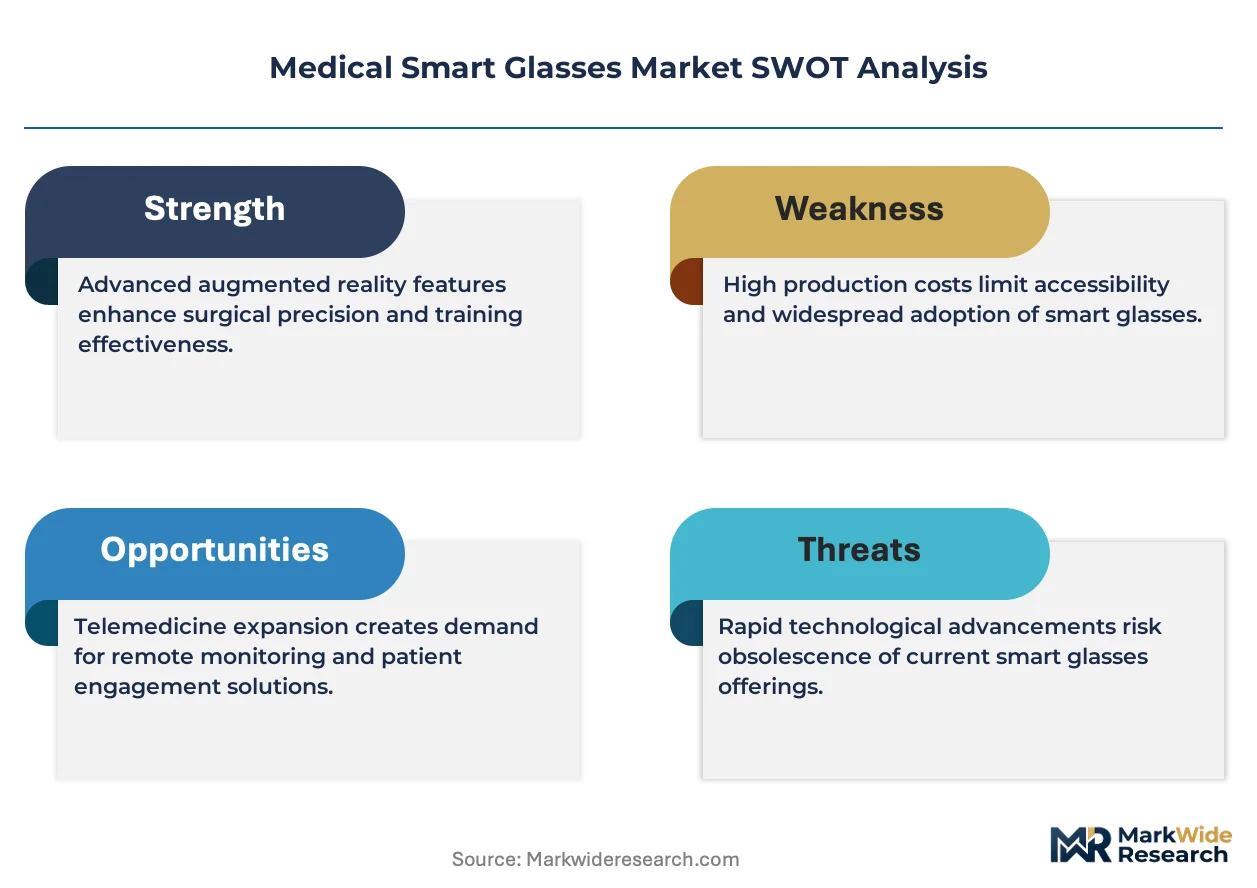
The transition from standalone hardware sales to modular hardware-software bundles is restructuring procurement patterns across hospital systems, forcing manufacturers to anchor recurring revenue streams through cloud-integrated platforms rather than device margins alone.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for Class II medical devices are reducing time-to-market for augmented reality surgical platforms, particularly for real-time navigation overlays in orthopedic procedures.
- Germany hospital digitization mandates:Federal funding for pilot programs in remote surgical support is concentrating demand for prescription-compatible smart glass systems in university medical centers.
- Edge computing latency reduction:Sub-40ms processing architectures are enabling gaze-controllable surgical interfaces that eliminate physical contact with sterile equipment, expanding adoption in infection-sensitive operating environments.
Market Restraints
- Optical waveguide supply concentration:Premium waveguide manufacturing capabilities cluster with a limited supplier base in East Asia, creating input bottlenecks for manufacturers targeting surgical visualization markets.
- EU Medical Device Regulation compliance costs:CE marking requirements under MDR impose extended audit timelines and quality management system investments that constrain capital deployment for mid-scale hardware entrants.
- Virtual reality isolation trade-off:Fully immersive VR headsets compete for training budgets despite surgical preference for optical see-through displays, fragmenting addressable demand across hardware form factors.
Strategic Opportunities
- Japan telemedicine infrastructure expansion:METI-funded rural healthcare connectivity programs are creating first-mover advantages for manufacturers offering remote consultation workflows through network-connected eyewear.
- Biometric sensor convergence:Integration of pupillometry and gaze tracking with diagnostic imaging overlays is opening premium pricing tiers for neurology and anesthesia monitoring applications.
- India PLI scheme for medical electronics:Production-linked incentives for domestic manufacturing of health devices are attracting assembly investment for cost-optimized smart glass variants targeting price-sensitive hospital procurement.
Industry Challenges
- ISO 13485 quality system implementation:Medical device manufacturing audits require specialized documentation protocols that extend supplier qualification timelines and strain in-house regulatory capacity.
- Cybersecurity guidance evolution:Health regulators are issuing iterative network security standards for connected eyewear that demand continuous software update architectures, complicating long-term product support commitments.
- Interoperability with legacy PACS infrastructure:Hospital imaging archive systems use heterogeneous data formats that require custom integration engineering for real-time diagnostic feed rendering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Smart Glasses Market |
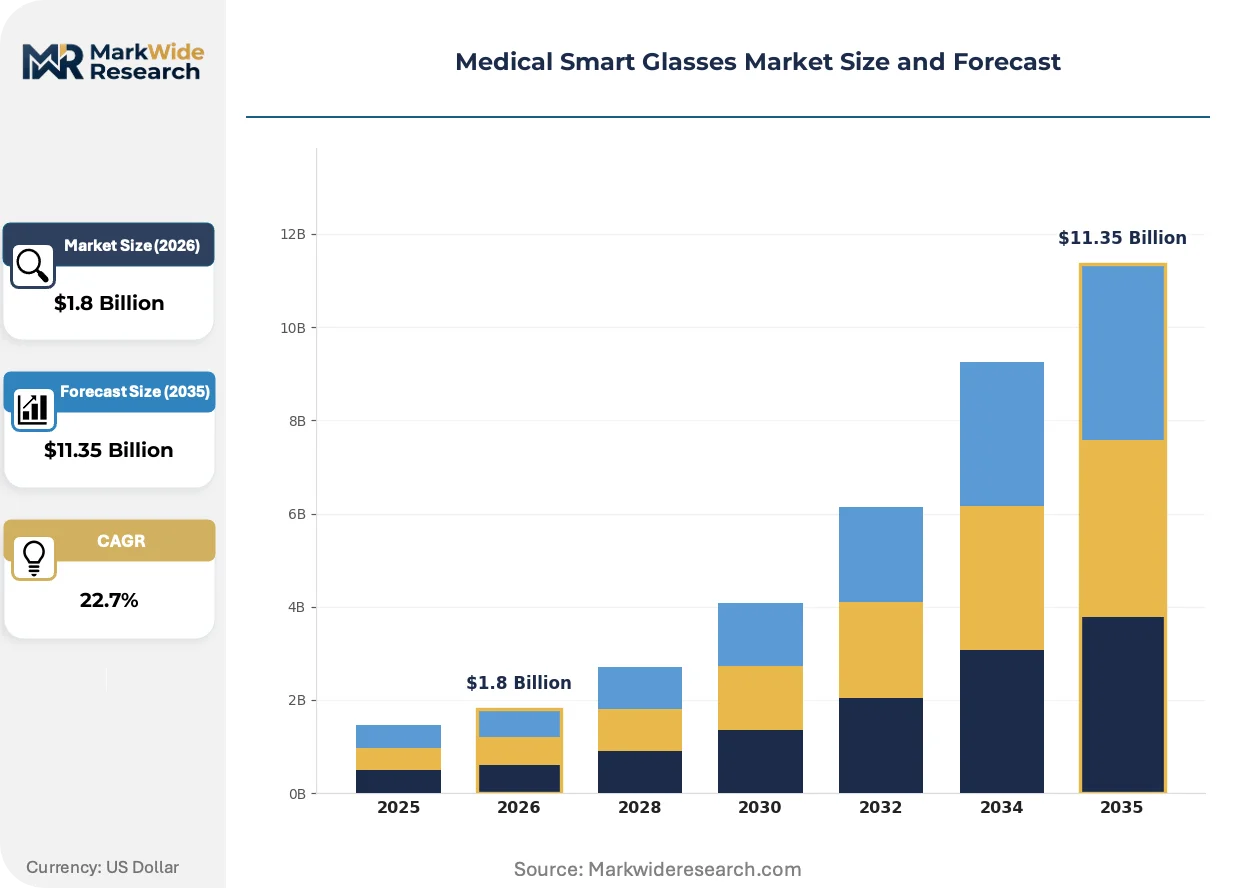
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Displays, Augmented Reality Glasses, Virtual Reality Glasses, Interactive Eyewear End User: Hospitals, Clinics, Surgical Centers, Telemedicine Providers Technology: Bluetooth Connectivity, Voice Control, Gesture Recognition, Eye Tracking Application: Surgery Assistance, Patient Monitoring, Medical Training, Remote Support |
| Companies Covered | Xreal, Rokid, Vuzix, Google, EssilorLuxottica, Meta, Dymesty, Amazon, RayNeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Smart Glasses Market Strategic Shifts
Three interconnected developments are compressing product lifecycles and redrawing competitive boundaries: optical waveguide manufacturing advances, regulatory pathway evolution for software-as-medical-device platforms, and procurement model restructuring toward subscription-based clinical tool access.
Optical see-through waveguide technology is converging with prescription lens fabrication processes, enabling manufacturers to embed near-eye displays within standard corrective eyewear form factors. Surgical centers in the United States are prioritizing these integrated systems over clip-on display attachments to reduce equipment changeover friction between procedures. This convergence is compressing the addressable market for standalone head-mounted displays while expanding the installed base for clinical augmented reality.
The EU Medical Device Regulation is reclassifying software-driven diagnostic overlays as standalone medical devices, subjecting algorithm update pipelines to formal change control procedures. Hardware manufacturers must now maintain parallel regulatory submissions for both physical devices and embedded software stacks, extending compliance resource requirements. Surgical navigation platforms with AI-enhanced image recognition are experiencing the most significant certification timeline impacts, driving consolidation around established quality management systems.
Hospital procurement departments are unbundling hardware acquisition from software licensing, favoring multi-year service agreements with guaranteed uptime and continuous feature deployment. This transition displaces capital expenditure approval cycles with operational budget commitments that align vendor incentives with clinical outcome metrics. The shift is most visible in German and Japanese university hospital systems, where centralized IT governance favors standardized enterprise deployments over departmental point solutions.
Medical Smart Glasses Market Segmentation
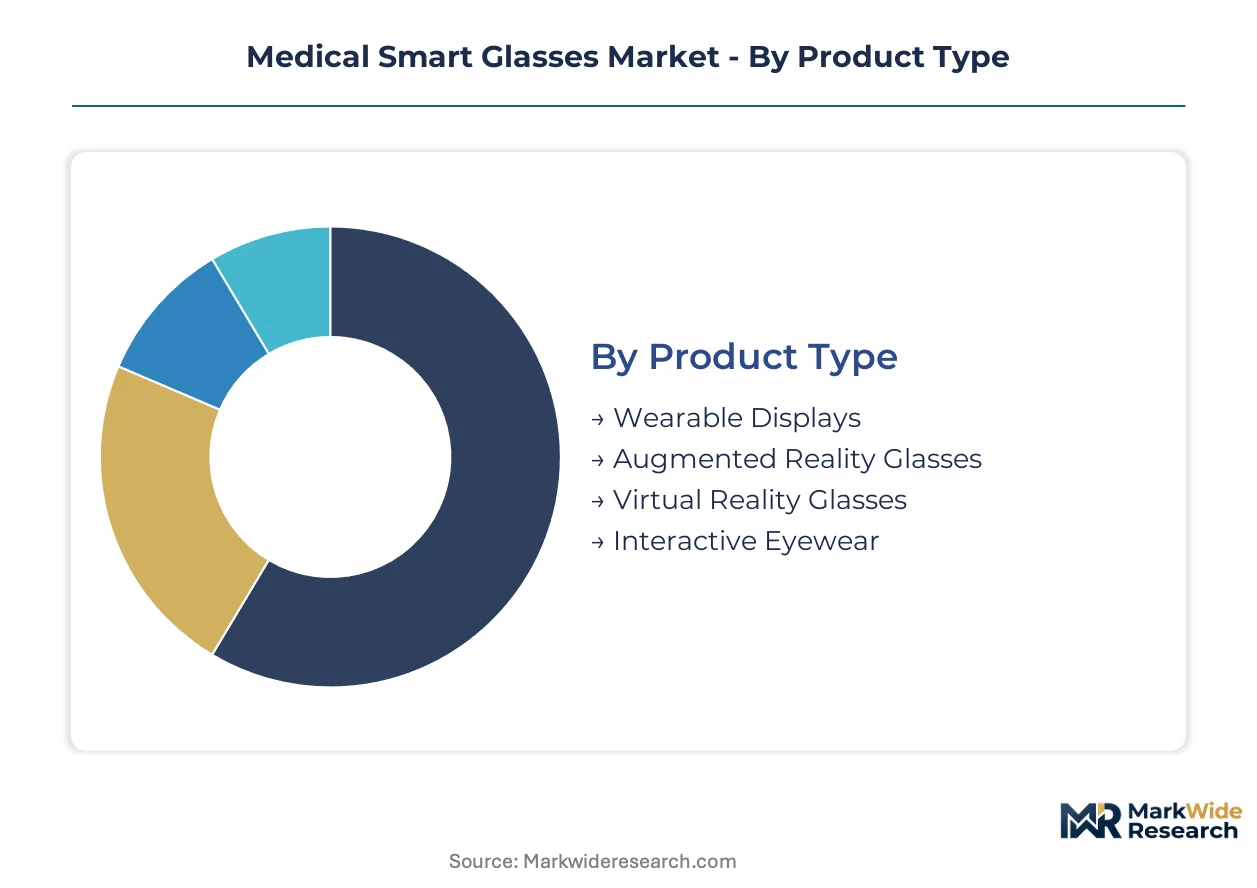
Medical smart glasses segment along four intersecting dimensions that determine pricing power, regulatory burden, and procurement velocity. Product form factor dictates hardware margins. End-user concentration shapes sales cycle length. Technology tier governs software attach rates. Application type defines reimbursement potential and clinical validation requirements.
Product Type:
Capital requirements vary sharply across form factors, with optical waveguide fabrication demanding the heaviest upfront manufacturing investment.
- Augmented Reality Glasses:Optical see-through waveguides overlay diagnostic data onto the clinician's live field of view with sub-40ms latency. Surgical centers in Germany and the United States concentrate procurement here, driven by hands-free navigation demands in sterile operating environments.
- Wearable Displays:Clip-on or integrated near-eye screens stream imaging feeds without full environmental overlay. Demand clusters in Japanese university hospitals piloting remote consultation workflows, constrained by prescription compatibility integration timelines.
- Virtual Reality Glasses:Fully immersive headsets isolate users for medical training simulations. Capital outlays concentrate in simulation centers rather than live procedure settings.
- Interactive Eyewear:Basic connected frames with limited display capability and sensor integration. Lowest hardware margins attract price-sensitive clinic procurement in India.
Most installed capacity flows through Augmented Reality Glasses. Expansion is steepest in Wearable Displays.
End User:
Customer scale and purchasing authority reshape go-to-market economics across institutional types.
- Surgical Centers:Ambulatory facilities with concentrated procedure volumes command premium pricing for FDA-cleared platforms that reduce operative time. Procurement in the United States prioritizes guaranteed uptime clauses over capital expenditure flexibility.
- Hospitals:Integrated health systems with centralized IT governance favor multi-year enterprise agreements bundling hardware, software, and continuous update pipelines. German hospital digitization mandates accelerate pilot program funding.
- Telemedicine Providers:Network-connected eyewear for remote diagnostic consultations. METI-funded rural healthcare programs in Japan create first-mover advantages for scalable deployment models.
- Clinics:Smaller outpatient settings with constrained capital budgets. India's PLI scheme for medical electronics attracts assembly investment for cost-optimized variants targeting this tier.
Revenue concentration sits with Surgical Centers. Volume expansion runs fastest through Telemedicine Providers.
Technology:
Interface sophistication determines software licensing attach rates and clinical workflow integration depth.
- Eye Tracking:Gaze-controllable interfaces eliminate physical contact with sterile equipment. Adoption concentrates in infection-sensitive orthopedic and neurosurgical settings where surgeons demand hands-free control.
- Bluetooth Connectivity:Baseline wireless transmission protocol for device pairing and data sync. FCC governance in the United States shapes transmission power and interference standards.
- Voice Control:Speech-activated command interfaces for documentation and navigation. Regulatory scrutiny of ambient audio capture complicates hospital cybersecurity compliance.
- Gesture Recognition:Hand-motion interfaces for non-contact system control. Higher processing overhead limits deployment in edge-computing-constrained environments.
Bluetooth Connectivity anchors current installed base. Eye Tracking gains share fastest among new deployments.
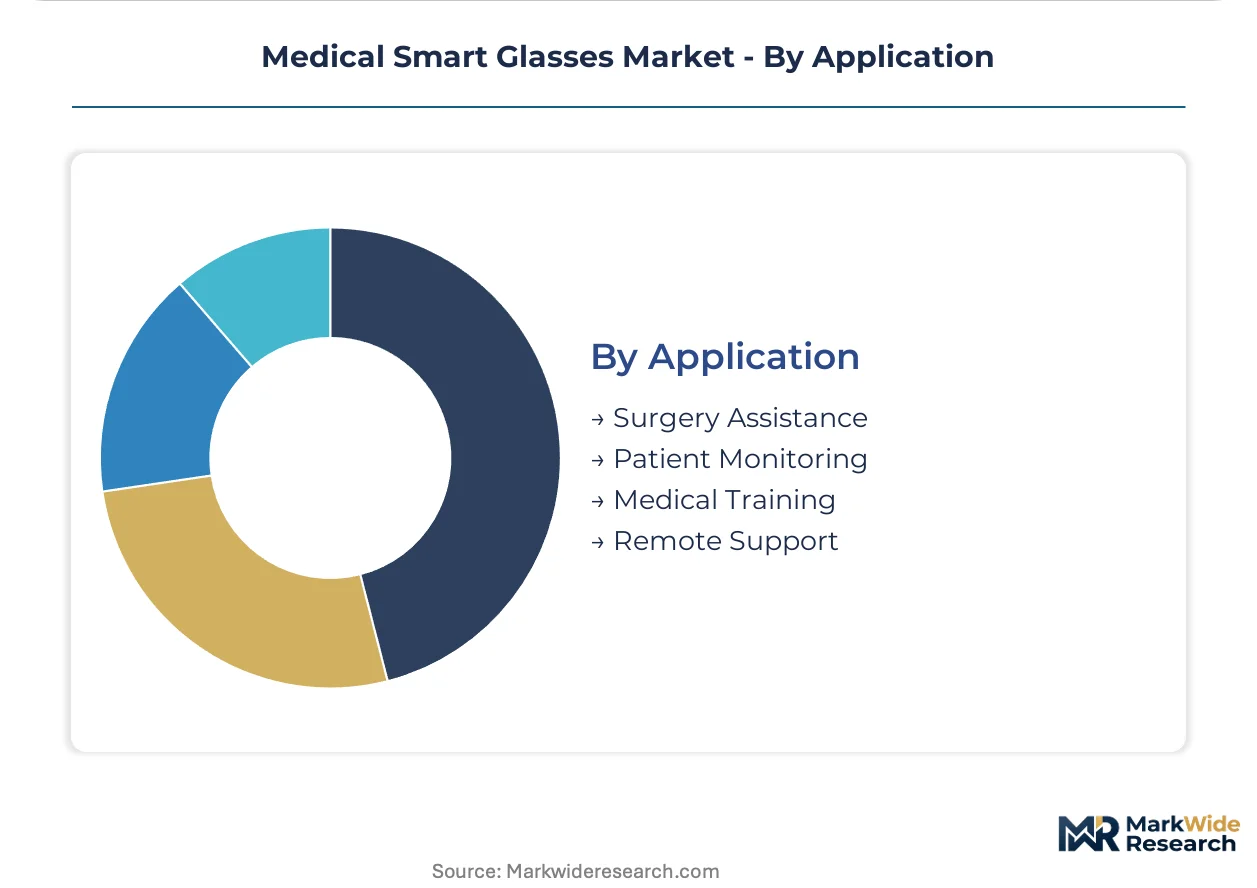
Application:
Clinical use case dictates regulatory pathway complexity and outcome-based pricing potential.
- Surgery Assistance:Real-time navigation overlays for live procedures command the deepest margin pools. FDA 510(k) clearance requirements for Class II medical devices extend development timelines but lock in premium pricing.
- Remote Support:Network-connected consultation workflows enabling specialist guidance across distances. Federal funding in Germany and infrastructure investment in Japan concentrate demand in university medical centers.
- Patient Monitoring:Continuous biometric sensor integration for anesthesia and neurology applications. Pupillometry convergence with diagnostic imaging opens premium pricing tiers.
- Medical Training:Simulation and education deployments compete with fully immersive VR alternatives, fragmenting budget allocation across hardware form factors.
Surgery Assistance captures the highest revenue per unit. Remote Support climbs the fastest as telemedicine infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical smart glasses manufacturing originated in Japanese precision optics clusters during the 1990s wave of head-mounted display development. German surgical instrument makers later integrated these displays into operating room workflows. Today, demand concentrates in hospital systems funding digitization pilots across three continents.
United States
Surgical centers in Cleveland Clinic and Mayo Clinic networks drive procurement of FDA-cleared augmented reality platforms for orthopedic navigation. The FDA 510(k) pathway for Class II medical devices accelerates market entry for hardware with real-time imaging overlays. Boston's medical device corridor hosts development labs refining sub-40ms latency architectures for sterile environments.
Germany
University medical centers in Berlin and Munich expand pilot programs for remote surgical support funded by federal hospital digitization mandates. CE marking under the EU Medical Device Regulation shapes quality management investments for manufacturers targeting European surgical visualization markets. The Baden-Württemberg precision engineering cluster supplies optical waveguide components to device integrators.
Japan
METI-funded rural healthcare connectivity programs concentrate demand for network-connected eyewear in prefectures facing specialist physician shortages. The PMDA governs software-as-medical-device classifications for diagnostic overlay algorithms. Nagoya's automotive optics suppliers pivot waveguide manufacturing capacity toward medical device specifications.
India
Production-linked incentives under the PLI scheme for medical electronics attract assembly investment for cost-optimized smart glass variants. The CDSCO regulates device safety standards for connected eyewear entering hospital procurement channels. Telangana's medical technology park in Hyderabad hosts pilot manufacturing lines targeting price-sensitive clinic tiers.
United Kingdom
NHS trusts in London and Manchester trial augmented reality platforms for surgical training and remote consultation workflows. MHRA post-Brexit regulatory frameworks diverge from EU MDR timelines, creating parallel certification requirements for manufacturers. The Cambridge technology cluster advances eye-tracking integration for gaze-controllable clinical interfaces.
Medical Smart Glasses Market Competitive Environment
Premium-margin players sit above commodity-margin players across the optical waveguide sophistication spectrum. The vendor base spans three tiers: waveguide fabricators capturing hardware margins, cloud-integrated platform operators anchoring recurring revenue, and eyewear channel incumbents controlling prescription-compatible distribution. Strategic archetypes include optical specialists, enterprise software stacks, and consumer eyewear conglomerates. Dominant competitive moves involve cloud partnership formations and regulatory certification pre-emption.
Within the optical specialist tier, Vuzix and Xreal exemplify divergent positioning strategies. Vuzix occupies the premium surgical visualization position through captive waveguide manufacturing. Xreal represents the volume-scalable alternative targeting cost-optimized clinical deployments. Google anchors the enterprise software stack archetype, leveraging cloud infrastructure to bundle hardware with continuous update pipelines. EssilorLuxottica sits within the eyewear channel control tier, extending prescription lens fabrication expertise into medical-grade frame integration.
| Leading Market Players |
|---|
| Xreal |
| Rokid |
| Vuzix |
| EssilorLuxottica |
| Meta |
| Dymesty |
| Amazon |
| RayNeo |
| Others |
Value Chain & Pricing Dynamics
Captive waveguide manufacturing in East Asia anchors both supply security and premium pricing power for surgical visualization tiers. FDA 510(k) clearance requirements and CE marking under EU MDR impose quality system investments that stratify hardware margins across certified and uncertified tiers.
Pricing Analysis
Subscription-based hardware-software bundles with guaranteed uptime clauses dominate procurement in German and United States hospital systems. Price differentiation rests on FDA clearance tier and optical waveguide sophistication, with Class II surgical platforms commanding substantial premiums over training-grade alternatives. Cost compression in prescription-compatible frames intensifies as EssilorLuxottica extends eyewear channel control. Telemedicine providers exhibit highest price sensitivity; surgical centers prioritize outcome guarantees over capital expenditure flexibility.
Supply Chain Analysis
Single-source vulnerability sits with optical waveguide fabrication concentrated in Japan, South Korea, and Taiwan. Critical inputs include precision glass substrates, micro-display panels, and biometric sensor arrays. Tariff exposure on East Asian optical components threatens margin stability for manufacturers lacking captive supply. Distribution runs through hospital GPO contracts and enterprise IT procurement channels, with German university medical centers piloting direct manufacturer partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory certification milestones, with FDA 510(k) pathway streamlining for Class II devices accelerating demand concentration in United States surgical centers.
For Market Incumbents: Anchor recurring revenue through cloud-integrated software stacks that lock hospital systems into multi-year service agreements. Defend against Xreal and Rokid volume plays by deepening captive waveguide production in Baden-Württemberg precision clusters. Prioritize ISO 13485 quality system investments to pre-empt EU MDR audit bottlenecks.
For New Entrants and Emerging Players: Launch via India's PLI scheme for medical electronics assembly to access price-sensitive clinic procurement channels. Target telemedicine infrastructure expansion in Japan's rural prefectures as the most penetrable white-space segment. Pursue METI-funded pilot program partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for optical waveguide specialists because manufacturing capability scarcity concentrates in East Asian precision clusters. Five-to-ten year viability hinges on regulatory certification pre-emption rather than hardware margin capture. Monitor FDA 510(k) clearance timeline compression as the critical inflection signal for platform valuation resets.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance timelines reduce time-to-market for orthopedic navigation platforms in Cleveland Clinic networks. |
| CE Marking Pathway | EU MDR compliance investments unlock procurement access to Berlin and Munich university medical center pilots. |
| Hospital System Partnership | Enterprise agreements with German centralized IT governance displace departmental point solutions. |
| Software Companion Development | Continuous update pipelines align vendor incentives with clinical outcome metrics under subscription models. |
| Reimbursement Strategy | Coding for remote surgical support procedures captures federal digitization mandate funding in Germany. |
Study Parameters
Bottom-up surgical center and hospital procurement modeling reconciled against top-down waveguide manufacturing capacity tracking forms the analytical core. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at FDA-cleared device manufacturers combined with secondary validation against FDA 510(k) filings, CE marking databases under EU MDR, hospital procurement contract repositories, and METI-funded pilot program disclosures.
Input-output matrices mapped optical waveguide supply from Nagoya and Baden-Württemberg clusters against end-user demand across surgical centers, hospitals, telemedicine providers, and clinics. Segmentation dimensions spanned product form factor, end-user concentration, technology tier, and application type with regional regulatory cluster overlays. CAGRs derived from installed base growth curves and replacement cycle analysis, incorporating edge computing latency benchmarks and prescription lens integration timelines as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cybersecurity guidance evolution and optical waveguide supply disruption scenarios. Forecasts reflect documented assumptions regarding FDA clearance timeline trajectories and EU MDR audit completion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
Global Tympanostomy Products Market
Medical Devices
Global Electromyography Devices Market
Medical Devices
Thoracolumbar Spine Devices Market
Medical Devices
Pericardial Patches Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
Global Transradial Access Market
Medical Devices
Europe Ablation Technologies Market
Medical Devices
Global 3D Printed Surgical Models Market
Medical Devices
France Drug Delivery Devices Market
Medical Devices
Europe Biopsy Devices Market
Medical Devices
Global Lithotripsy Device Market
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Mexico Contraceptive Devices Market
Medical Devices
Transcatheter Mitral Valve Market