
 New Zealand Diabetes Devices Market | 2026-2036
New Zealand Diabetes Devices Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Diabetes Devices Market Outlook
Hospital procurement departments is bifurcating from bulk tender purchasing toward patient-specific subscription models for continuous glucose monitoring. Abbott Laboratories leverages its FreeStyle Libre ecosystem to anchor pharmacy-direct distribution across Auckland and Wellington. Dexcom competes through smartphone-integrated transmitters that reduce clinic visit dependency. Medtronic sustains its position via insulin pump-CGM hybrid systems tailored for Type 1 diabetes management in pediatric and adult populations.
Diabetes devices encompass instruments for glucose measurement, insulin administration, and metabolic data transmission, typically operating through electrochemical sensors with measurement ranges of 1.1–33.3 mmol/L and wireless data protocols such as Bluetooth Low Energy or near-field communication. These systems serve to reduce hyperglycemic episodes, optimize insulin dosing, and enable remote clinician oversight. Blood glucose monitors retain the largest installed base among product types, though continuous glucose monitors capture expanding reimbursement eligibility under Pharmac schedules. Wearable devices lead technology adoption, while cloud-based solutions attract telehealth-integrated home care providers seeking real-time dashboard access for remote patient cohorts.
Medsafe governs medical device registration and post-market vigilance, requiring adverse event reporting for software-enabled glucose sensors. Pharmac, New Zealand's pharmaceutical purchasing agency, determines which diabetes devices qualify for public subsidy, directly shaping patient access and manufacturer pricing negotiations. The Therapeutic Products Act introduces new risk-classification pathways that will affect clearance timelines for next-generation closed-loop systems. Stakeholders must monitor Pharmac's annual schedule reviews and Medsafe's evolving software-as-a-medical-device guidance to anticipate reimbursement shifts and compliance burdens.
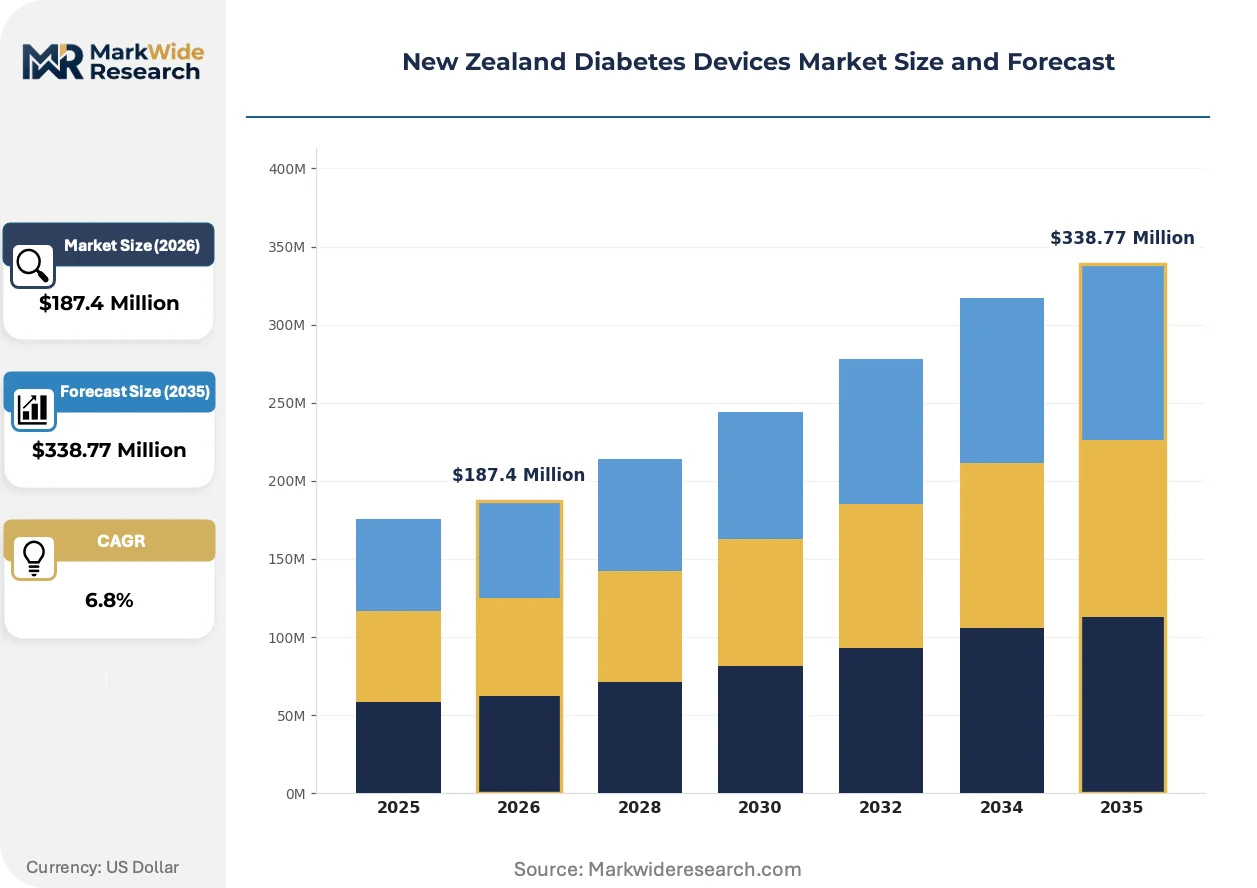
Market Dynamics
Pharmac's annual schedule reviews are compressing manufacturer pricing power while accelerating patient access to subsidized continuous glucose monitoring systems across New Zealand's district health boards.
Growth Catalysts
- Pharmac Reimbursement Expansion:Public subsidy eligibility for continuous glucose monitors now covers broader Type 2 diabetes populations, reducing out-of-pocket costs for patients in Auckland and Wellington metropolitan networks.
- Medsafe Software Guidance:Clarified regulatory pathways for Bluetooth-enabled glucose sensors are shortening clearance timelines for connected device submissions.
- Home Care Integration:Telehealth providers are embedding real-time glucose dashboards into remote patient monitoring programs, creating pull-through demand for cloud-compatible devices.
Market Restraints
- Sensor Import Concentration:Electrochemical sensor substrates rely on single-source Asian suppliers, exposing distributors to freight cost volatility and customs clearance delays.
- Pharmac Price Benchmarking:The pharmaceutical purchasing agency references Australian and UK tender outcomes, compressing margins for manufacturers seeking public formulary inclusion.
- Disposable Consumable Burden:Continuous glucose monitoring requires fortnightly sensor replacement, creating recurring cost barriers for uninsured patients outside subsidized cohorts.
Strategic Opportunities
- South Island Penetration:Canterbury and Otago health networks lag Auckland in CGM adoption, presenting whitespace for pharmacy-direct distribution models.
- Insulin Pump Convergence:Hybrid closed-loop systems that integrate pump and sensor data are capturing pediatric endocrinology referrals previously managed through multiple vendors.
- Pharmac Annual Reviews:Schedule updates in 2025-2026 are expected to expand real-time CGM eligibility, creating subsidy tailwinds for next-generation transmitter platforms.
Industry Challenges
- Software Validation Timelines:Medsafe's post-market surveillance requirements for algorithm-updating glucose sensors are extending compliance certification cycles.
- Clinical Workforce Constraints:Diabetes educator shortages in regional DHBs are limiting patient onboarding capacity for complex multi-device regimens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Diabetes Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Monitors, Insulin Pumps, Continuous Glucose Monitors, Lancets Application: Self-Monitoring, Continuous Monitoring, Insulin Delivery, Diabetes Management End User: Hospitals, Clinics, Home Care, Telehealth Technology: Wearable Devices, Smartphone Integration, Cloud-Based Solutions, Remote Monitoring |
| Companies Covered | Abbott Laboratories, Dexcom, Medtronic, Novo Nordisk, Sanofi, Roche Diagnostics, Eli Lilly, Insulet, Ypsomed, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Diabetes Devices Market Strategic Shifts
Wireless data protocols and cloud architecture are dissolving traditional boundaries between clinical settings and patient-managed care, enabling real-time metabolic oversight without geographic proximity to specialists.
Smartphone-integrated transmitters are fragmenting the legacy clinic-visit model for glucose data review. Patients in Auckland's integrated care networks now receive automated glycemic alerts on personal devices, reducing endocrinology appointment frequency by half. This connectivity is compressing reimbursement structures toward remote monitoring codes rather than face-to-face consultation billing.
Medsafe's evolving software-as-a-medical-device guidance is tightening adverse event reporting obligations for algorithm-enabled sensors. Manufacturers must now submit cybersecurity documentation and post-market performance data for cloud-connected glucose monitors. Pediatric and adult endocrinology practices are prioritizing vendors with established New Zealand regulatory histories to mitigate clearance uncertainty.
Subscription-based procurement is displacing bulk capital purchases in hospital pharmacy departments. District health boards in Wellington and Christchurch are piloting per-patient monthly fees for continuous glucose monitoring systems, transferring obsolescence risk to manufacturers. This shift favors vendors with integrated supply chains capable of managing sensor logistics and patient support within fixed per-capita payments.
New Zealand Diabetes Devices Market Segmentation
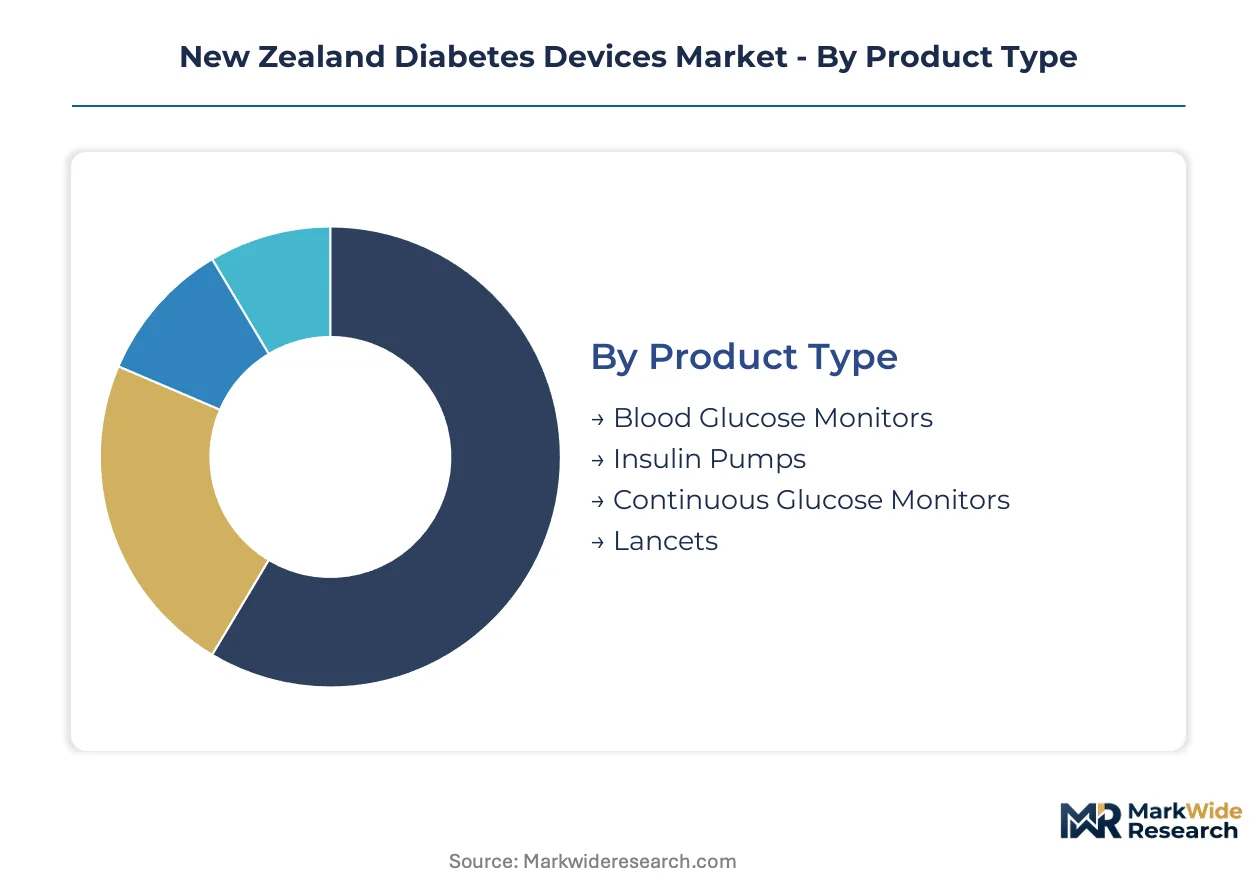
Segmentation in New Zealand's diabetes devices market reveals how procurement channels, reimbursement pathways, and patient acuity interact to shape vendor strategy. Each dimension carries distinct margin profiles and regulatory touchpoints that determine competitive positioning.
Product Type:
Hospital procurement departments source high-value systems through district health board tenders, while pharmacy-direct channels handle patient-owned consumables and replacement sensors.
- Continuous Glucose Monitors:Electrochemical sensors with Bluetooth Low Energy transmitters enable real-time glucose tracking without finger-prick calibration. Auckland and Wellington metropolitan networks concentrate demand where Pharmac subsidy expansion has accelerated patient onboarding. Fortnightly sensor replacement creates recurring revenue streams that manufacturers protect through pharmacy-direct subscription models.
- Blood Glucose Monitors:Portable electrochemical meters using test strips remain the installed base leader across New Zealand's regional DHBs. Canterbury and Otago health networks rely on these systems where CGM educator capacity remains constrained and out-of-pocket costs limit advanced system adoption.
- Insulin Pumps:Motor-driven reservoir devices for subcutaneous insulin infusion serve Type 1 diabetes populations through specialist endocrinology referrals.
- Lancets:Single-use sterile needles for capillary blood sampling attach to reusable lancing devices distributed through retail pharmacy.
By volume, Blood Glucose Monitors leads. By growth pace, Continuous Glucose Monitors is climbing the fastest.
Application:
Cost tiers separate acute inpatient management from ambulatory self-care, with subsidy eligibility determining which applications patients can afford.
- Continuous Monitoring:Real-time glucose data streams enable automated alerts and remote clinician oversight through cloud dashboards. Home care providers in Auckland's integrated networks embed these capabilities into telehealth programs, reducing emergency department presentations for hypoglycemic events.
- Insulin Delivery:Precision dosing systems integrate pump mechanics with sensor feedback for closed-loop glycemic control. Pediatric endocrinology practices prioritize hybrid systems that minimize parental intervention overnight.
- Self-Monitoring:Patient-operated glucose testing through portable meters supports medication adjustment between clinical visits.
- Diabetes Management:Comprehensive platforms combining glucose data, insulin logs, and lifestyle tracking for longitudinal metabolic oversight.
By patient population reach, Self-Monitoring leads. By subsidy momentum, Continuous Monitoring is expanding most quickly.
End User:
Customer type determines purchasing authority—DHB procurement officers negotiate tenders while individual patients respond to pharmacy marketing and clinician recommendations.
- Home Care:Patient-managed environments where real-time dashboards and smartphone alerts reduce dependency on clinic visits. Wellington and Christchurch DHBs pilot per-patient subscription fees that transfer device obsolescence risk to vendors.
- Telehealth:Remote monitoring programs requiring cloud-compatible devices with API access for third-party platform integration. Auckland's integrated care networks use these systems to halve endocrinology appointment frequency for stable patients.
- Hospitals:Acute inpatient settings where point-of-care glucose testing guides insulin dosing and discharge planning.
- Clinics:Specialist endocrinology and diabetes educator practices managing complex multi-device regimens.
By device volume, Hospitals leads. By channel innovation, Telehealth is gaining share fastest.
Technology:
Maturity curves separate established wearable hardware from emerging cloud architectures that Medsafe's software-as-a-medical-device guidance now regulates.
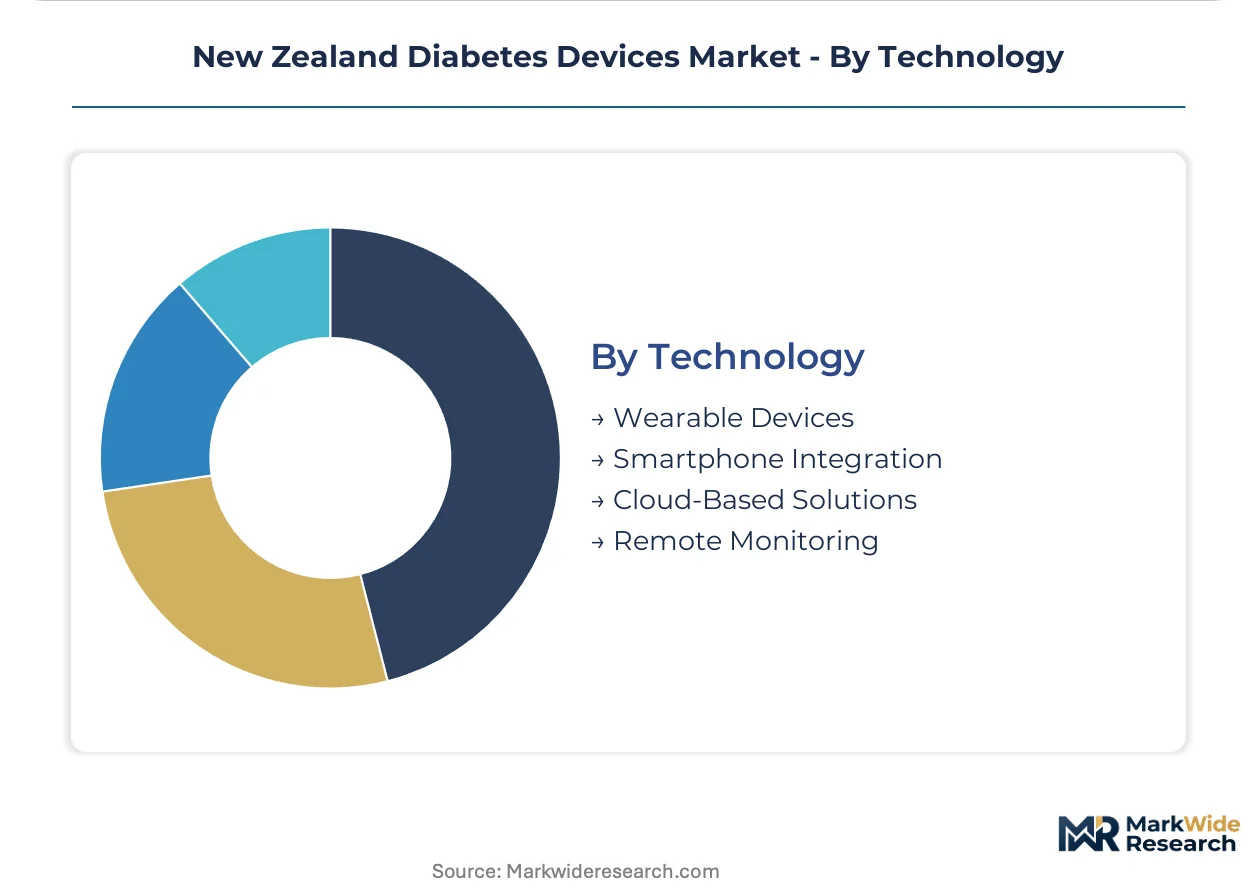
- Smartphone Integration:Native iOS and Android applications replace dedicated receiver hardware, reducing patient equipment burden. Dexcom and Abbott leverage this architecture to bypass traditional clinic-visit data review, capturing patients who prioritize convenience.
- Cloud-Based Solutions:Centralized data repositories enable multi-clinician access and population health analytics for DHB diabetes programs. Medsafe's tightened post-market surveillance requirements now mandate cybersecurity documentation and adverse event reporting for these systems.
- Wearable Devices:Body-worn sensors and transmitters using skin-adhesive patches for continuous glucose measurement.
- Remote Monitoring:Clinician-facing dashboards and alert systems for geographically distributed patient cohorts.
By installed base, Wearable Devices leads. By regulatory attention and vendor investment, Cloud-Based Solutions shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device exporters from the United States and Europe route diabetes technologies through Auckland's distribution hubs to serve dispersed patient populations across New Zealand's North and South Islands.
Auckland Metropolitan Network
Pharmac subsidy expansion and integrated care programs accelerate continuous glucose monitor adoption across Waitematā and Auckland District Health Boards. Medsafe's tightened post-market surveillance requirements shape clearance strategies for software-enabled sensors entering this corridor. Pharmacy-direct distribution models from Abbott Laboratories and Dexcom concentrate patient onboarding capacity in Auckland's urban core.
Wellington Region
Capital & Coast and Hutt Valley DHBs pilot subscription-based procurement that transfers device obsolescence risk to manufacturers. The Therapeutic Products Act's risk-classification pathways affect clearance timelines for closed-loop systems seeking pediatric endocrinology referrals. Wellington's proximity to Pharmac headquarters influences early access to schedule review outcomes.
Canterbury Health Network
Christchurch Hospital anchors South Island demand for insulin pump-CGM hybrid systems serving Type 1 diabetes populations. Diabetes educator shortages limit complex multi-device onboarding relative to northern networks. Telehealth-integrated remote monitoring programs create pull-through demand for cloud-compatible glucose sensors across rural Canterbury.
Otago and Southland
Southern DHB's geographically dispersed patient cohorts prioritize smartphone-integrated transmitters that reduce clinic visit dependency. Blood glucose monitors retain larger installed bases where CGM subsidy eligibility and specialist capacity lag metropolitan networks. Dunedin's endocrinology practice concentrates pediatric referrals for hybrid closed-loop system evaluations.
New Zealand Diabetes Devices Market Competitive Environment
Player mix skews toward multinational medical technology conglomerates with established regulatory histories in Australia-Pacific markets. Market structure concentrates around three firms controlling continuous glucose monitoring and insulin pump segments, with pharmaceutical manufacturers competing in adjacent insulin delivery. Strategic archetypes include sensor-software integrators, pump-sensor hybrid developers, and pharmacy-direct distributors. Dominant competitive moves encompass subscription-based procurement partnerships and regulatory pathway optimization for software-as-a-medical-device submissions.
Within the sensor-software integrator tier, Dexcom and Abbott Laboratories exemplify contrasting distribution philosophies. Dexcom occupies a position emphasizing smartphone-native architectures that bypass traditional clinic data review, while Abbott anchors pharmacy-direct subscription models across Auckland and Wellington networks. Medtronic represents the pump-sensor convergence archetype, with its hybrid closed-loop systems capturing pediatric and adult endocrinology referrals previously fragmented across multiple vendors.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom |
| Medtronic |
| Novo Nordisk |
| Sanofi |
| Roche Diagnostics |
| Eli Lilly |
| Insulet |
| Ypsomed |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day sensor substrate lead times from Asian manufacturing hubs concentrate procurement leverage among distributors with established customs brokerage relationships, compressing margin buffers for secondary market entrants while amplifying pricing power for integrated suppliers with captive inventory positions.
Pricing Analysis
Current-generation continuous glucose monitors command premium positioning against prior-generation blood glucose meters and next-generation closed-loop hybrid systems still navigating Medsafe clearance pathways. Subscription-based per-patient monthly fees dominate Wellington and Christchurch procurement pilots, transferring obsolescence risk to manufacturers. Price differentiation rests on Pharmac formulary inclusion status and Bluetooth-enabled software certification tiers. Pricing pressure intensifies as Pharmac benchmarks against Australian and UK tender outcomes, squeezing margins for public formulary aspirants. Uninsured patients outside subsidized cohorts exhibit highest price sensitivity, while pediatric endocrinology practices demonstrate lowest sensitivity given clinical outcome priorities.
Supply Chain Analysis
Port congestion across the Trans-Tasman trade lane elevates inbound logistics costs for electrochemical sensor substrates routed through Auckland distribution hubs. Manufacturing concentration in China, South Korea, and Malaysia feeds New Zealand's device import dependency. Raw material inputs span palladium-based electrode coatings, medical-grade adhesives, and Bluetooth Low Energy transmitter chipsets. Single-source Asian supplier vulnerability creates exposure to freight cost volatility and customs clearance delays. Distribution runs through district health board procurement officers for hospital systems, pharmacy-direct channels for patient-owned consumables, and telehealth-integrated platforms for remote monitoring programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The New Zealand diabetes devices market rewards players with established Medsafe regulatory histories and integrated logistics capabilities, as diabetes educator shortages and Pharmac schedule complexity create barriers for newcomers lacking specialized compliance expertise and DHB relationship networks.
For Market Incumbents: Shield formulary positions by deepening pharmacy-direct subscription infrastructure across Canterbury and Otago, where CGM educator capacity constraints limit competitor onboarding. Anchor Wellington DHB relationships through pilot participation in per-patient procurement models. Prioritize vertical integration into sensor logistics and patient support services to defend margins against Pharmac price benchmarking. For New Entrants and Emerging Players: Lead with smartphone-native architectures that bypass clinic-visit dependency, targeting Southern DHB's geographically dispersed cohorts where telehealth integration creates whitespace. Focus initial deployment on blood glucose monitor replacement cycles in regional networks lagging Auckland's CGM adoption curve. Partner with established telehealth platforms for API-integrated dashboard access rather than building proprietary cloud infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because Medsafe's software-as-a-medical-device guidance and Pharmac schedule complexity compound incumbency advantages over five-to-ten year horizons. Target acquisition profiles emphasizing established New Zealand adverse event reporting histories and DHB tender participation records. Monitor Pharmac annual schedule review announcements as inflection signals for subsidy expansion windows.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmac Schedule Alignment | Early engagement with Pharmac headquarters in Wellington accelerates subsidy eligibility timelines for novel transmitter platforms. |
| Medsafe Software Documentation | Cybersecurity submission packages for Bluetooth-enabled sensors reduce clearance uncertainty for algorithm-updating devices. |
| Diabetes Educator Partnership | Training program investments address workforce constraints limiting patient onboarding capacity in regional DHBs. |
| Pharmacy-Direct Distribution | Subscription models across Auckland and Wellington transfer device obsolescence risk while securing recurring revenue streams. |
| Telehealth Platform Integration | API access for cloud-compatible devices captures remote monitoring demand from integrated care networks halving clinic visit frequency. |
Study Parameters
Desk research of Pharmac schedule databases, Medsafe device registration records, and district health board tender documentation preceded structured interviews with hospital procurement managers, diabetes educator network coordinators, biomedical engineers, and telehealth platform integration specialists. Primary fieldwork across Auckland, Wellington, and Christchurch captured subscription procurement pilot details and CGM onboarding capacity constraints. Secondary validation drew from customs import records, medical device distributor financial disclosures, and clinician survey data. Bottom-up patient population estimates and top-down healthcare expenditure allocations were triangulated to anchor market sizing.
Variance decomposition across product type, application, end user, and technology dimensions shaped the analytical framework over the projection horizon. Segmentation modeling incorporated continuous glucose monitor subsidy eligibility tiers, blood glucose monitor installed base replacement cycles, insulin pump referral pathways, and cloud architecture adoption patterns. CAGRs were derived from patient population growth projections, reimbursement expansion scenarios, and technology substitution curves. Forecast inputs included Pharmac annual review timing assumptions and Medsafe software guidance evolution trajectories.
Forecasts assume regulatory continuity in Medsafe's post-market surveillance requirements and Pharmac's pharmaceutical purchasing authority; material policy shifts under the Therapeutic Products Act would require re-modeling clearance timelines and risk-classification pathways. Supply chain disruption scenarios from Asian manufacturing concentration and diabetes educator workforce constraints represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Canada Spinal Surgery Devices Market
Medical Devices
Hearing Loop Market
Medical Devices
Band Ligators Market
Medical Devices
Latin America Insulin Syringes Market
Medical Devices
Treatment Pumps Market
Medical Devices
Spinal Fusion Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
High Viscosity Bone Cement Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Sentinel Node Biopsy Market
Medical Devices
Gastric Bands Market
Medical Devices
3D Printed Implants Market
Medical Devices
Artificial Implants Market
Medical Devices
Intraoperative Sensor Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
Life Science Microscopy Devices Market