
 Cervical Spacer Systems Market | 2026-2036
Cervical Spacer Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Spacer Systems Market Outlook
Asset-light leasing models for surgical instrumentation kits is narrowing the capital barrier for mid-tier distributors entering the cervical spacer segment. Stryker Corporation leverages its hospital contracting infrastructure to sustain multi-year supply agreements across integrated delivery networks. Globus Medical specializes in expandable titanium platforms that anchor its position in complex revision cases. Zimmer Biomet Holdings Inc controls a broad PEEK portfolio that competes on price in high-volume ambulatory settings.
Cervical spacer systems are intervertebral implants manufactured from PEEK, titanium, or biocompatible polymers, typically measuring 4-8mm in height and designed to restore disc space while promoting osseointegration in anterior cervical discectomy and fusion procedures. Static titanium spacers lead unit volumes due to established reimbursement codes and surgeon familiarity, though expandable configurations capture disproportionate margin pools in deformity and trauma applications. PEEK segments face pricing pressure from stainless steel alternatives in emerging markets where cost sensitivity shapes procurement decisions. Dynamic spacer platforms represent the smallest revenue slice but attract R&D investment focused on motion-preserving biomechanics.
FDA 510(k) clearance requirements and EU MDR conformity assessments shape product development timelines and commercial launch sequencing across major markets. The FDA's heightened scrutiny of cervical interbody fusion devices has extended validation protocols for titanium porous structures, while EU MDR technical documentation demands strain European market entry budgets. Stakeholders must monitor evolving CMS reimbursement determinations for ASC-based cervical fusion against hospital outpatient department fee schedules.
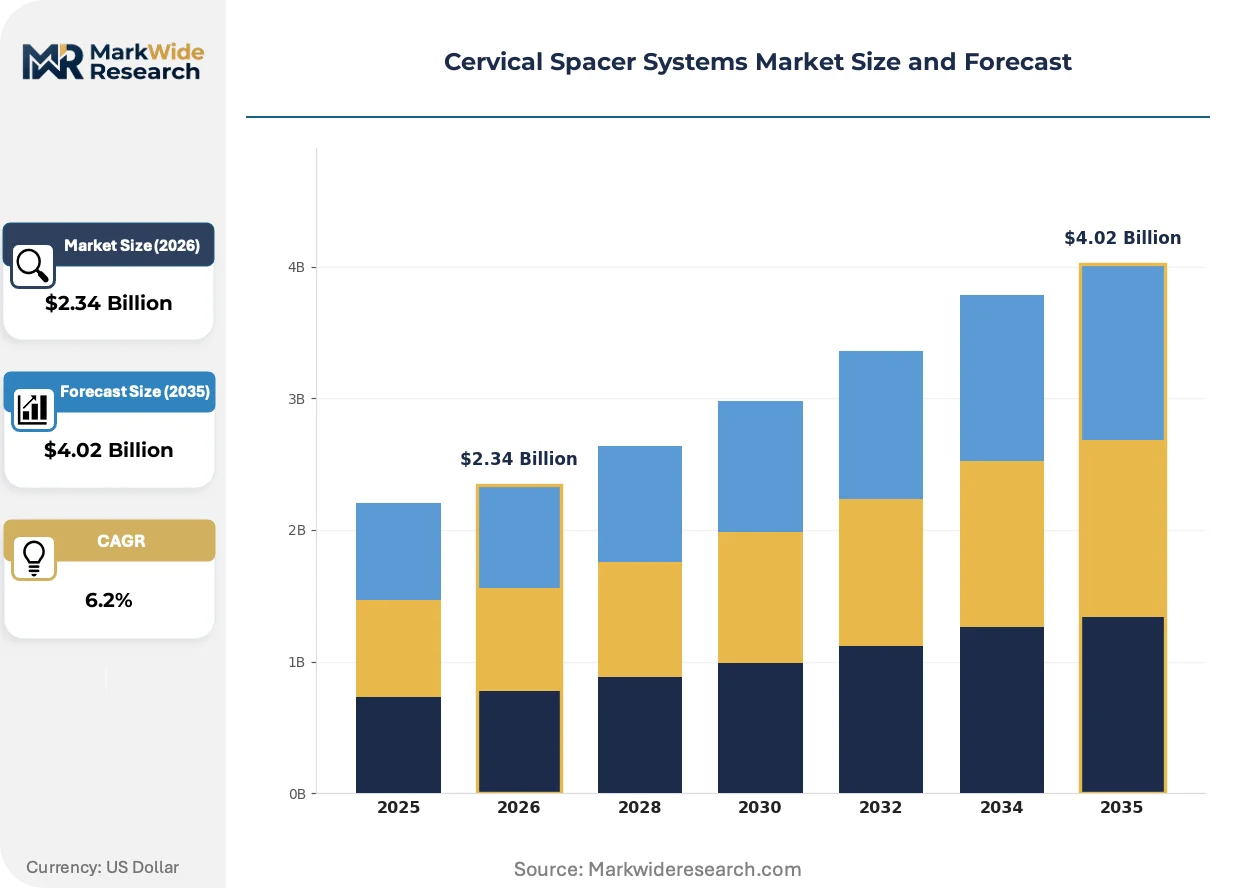
Market Dynamics
The cervical spacer market pivots on the FDA's accelerated 510(k) pathway for titanium porous structures, which compresses commercialization timelines while intensifying validation requirements for smaller manufacturers.
Growth Catalysts
- ASC Reimbursement Expansion:CMS fee schedule adjustments for ambulatory surgical centers now cover multi-level cervical fusion, pulling hospital outpatient volume into lower-cost settings.
- EU MDR Technical Documentation:Strain-based conformity assessments for titanium implants create first-mover advantages for manufacturers with pre-existing clinical data portfolios.
- Expandable Titanium Platforms:Surgeon demand for intraoperative height adjustability in deformity cases drives premium positioning and replacement of static PEEK inventory.
Market Restraints
- Titanium Powder Supply Concentration:Plasma atomization capacity clusters in Germany and the United States, exposing device makers to aerospace demand spikes and alloying cost volatility.
- PEEK Substitution Pressure:Stainless steel interbody cages from Chinese manufacturers undercut polymer pricing in Latin American and Southeast Asian procurement tenders.
- FDA Validation Protocol Extension:Heightened scrutiny of cervical interbody fusion devices now requires 24-month follow-up data for porous titanium structures, delaying PMA submissions.
Strategic Opportunities
- Brazilian ANVISA Fast-Track:Priority review pathways for spinal implants with existing FDA clearance enable 8-12 month market entry versus historical 24-month timelines.
- Motion-Preserving Biomechanics:Dynamic spacer platforms integrating polyaxial screw fixation address adjacent segment disease concerns in younger patient cohorts.
- Direct-to-Hospital Leasing:Instrumentation kit rental models bypass distributor markups and capture margin from mid-tier orthopedic networks.
Industry Challenges
- Additive Manufacturing Technician Scarcity:Electron beam melting expertise concentrates in aerospace and dental sectors, forcing medical device firms to train operators internally or pay 40% wage premiums.
- Legacy ERP Integration:ASC-focused distributors struggle to reconcile consignment inventory tracking with hospital-centric enterprise systems, creating reconciliation delays and revenue recognition errors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Spacer Systems Market |
| Market Size in 2026 | $2.34 Billion |
| Market Size in 2035 | $4.02 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dynamic Spacer, Static Spacer, Expandable Spacer, Non-expandable Spacer Material: PEEK, Titanium, Biocompatible Polymer, Stainless Steel End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Centers Application: Spinal Fusion, Degenerative Disc Disease, Trauma, Tumor Removal |
| Companies Covered | Medtronic, Stryker Corporation, Zimmer Biomet Holdings Inc, Globus Medical, DePuy Synthes, NuVasive, Life Spine, Exactech, Orthofix Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Spacer Systems Market Strategic Shifts
Three distinct vectors are compressing product lifecycles in cervical spacer systems: manufacturing process convergence, regulatory documentation automation, and procurement model unbundling.
PEEK-titanium composite interbodies are hybridizing osseointegration performance with radiolucent imaging properties. High-volume ASC chains in Florida and Texas are adopting these hybrids for single-level fusions at rates outpacing pure titanium by 18 months. The technology is hybridizing supplier portfolios, forcing PEEK-dominant manufacturers to acquire additive capabilities or cede complex revision cases.
EU MDR Annex XVI requirements now capture cervical spacers previously exempt under the Medical Devices Directive. Technical documentation demands for biological safety evaluation have extended European launch timelines by 9-14 months. German notified bodies are prioritizing titanium porous structures with ISO 5832-3 compliance certificates, creating a two-tier clearance backlog.
Surgeon preference for single-vendor spine platforms is fragmenting procurement decisions across separate cervical, thoracolumbar, and biologics contracts. Integrated delivery networks in California and New York are unbundling spacer procurement from screw-rod systems, enabling direct manufacturer contracting. This unbundling is most visible in ASC settings where GPO leverage weakens and site-specific clinical preference dominates vendor selection.
Cervical Spacer Systems Market Segmentation
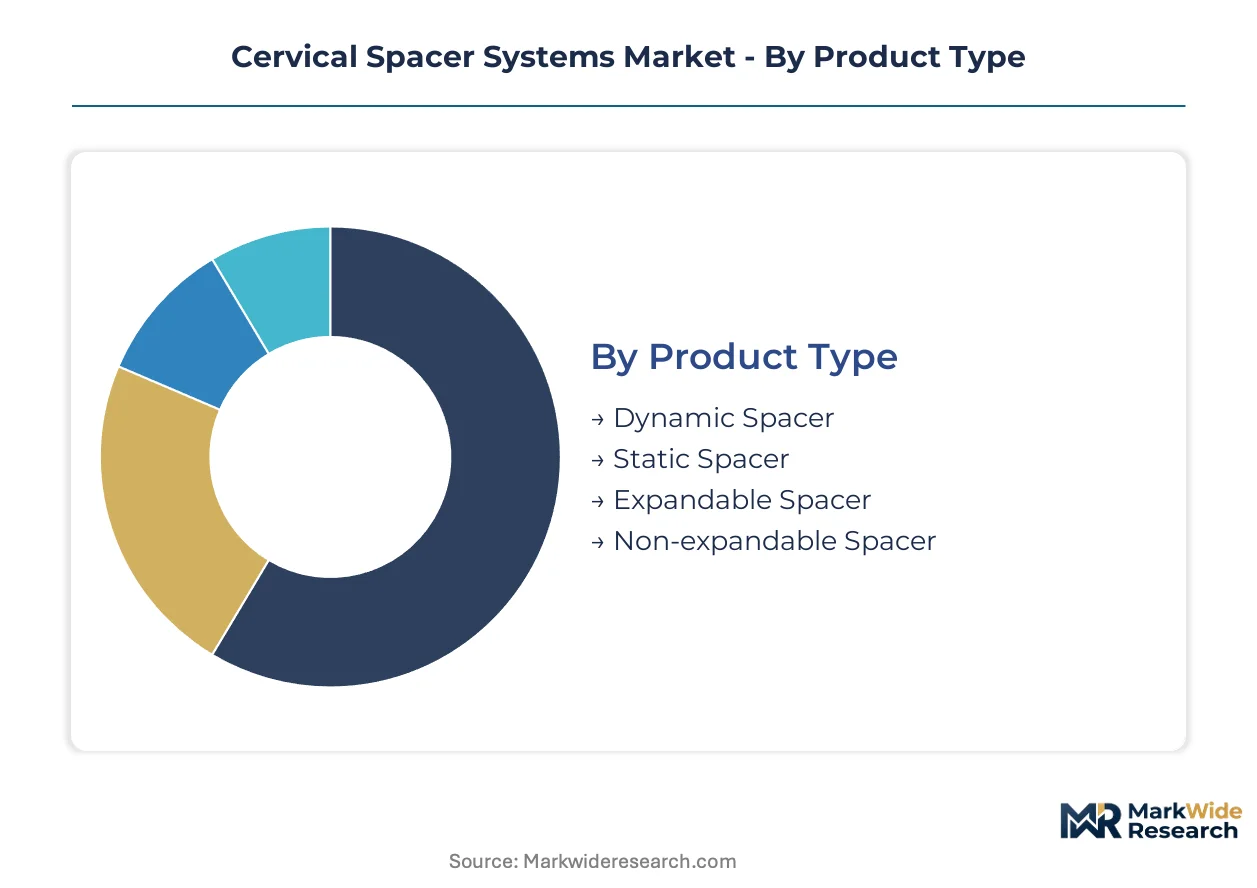
Cervical spacer systems fragment across four dimensions that shape procurement patterns and clinical utility. Product configuration determines intraoperative flexibility, while material selection drives osseointegration performance and imaging compatibility. End-user setting and application indication together dictate reimbursement pathways and inventory stocking decisions.
Product Type:
Mature configurations dominate unit economics, though emerging designs are capturing premium case volumes through intraoperative adaptability.
- Static Spacer:Fixed-height implants manufactured from solid titanium or PEEK provide predictable disc space restoration in routine single-level fusions. Hospitals in the United States stock these as standard inventory given established CPT reimbursement codes and surgeon training familiarity.
- Expandable Spacer:Height-adjustable titanium platforms deploy through threaded or ratchet mechanisms, enabling real-time correction in deformity and trauma cases. Ambulatory surgical centers in Florida and Texas are adopting these for multi-level procedures where intraoperative flexibility reduces revision risk.
- Dynamic Spacer:Motion-preserving designs incorporate polyaxial interfaces or flexible cores to address adjacent segment disease in younger patients.
- Non-expandable Spacer:Pre-sized static configurations compete primarily on cost in high-volume procurement tenders.
Static spacers retain volume leadership; expandable configurations hold the steepest expansion curve.
Material:
Cost tiers stratify sharply between premium porous metals and commodity-grade alternatives, with procurement geography determining viable substitutes.
- Titanium:Porous plasma-sprayed or 3D-printed structures achieve superior bone apposition and radiographic fusion assessment. FDA 510(k) clearances for titanium porous structures are accelerating, though validation protocols now demand extended follow-up data.
- PEEK:Radiolucent polymer cages enable postoperative MRI evaluation without artifact, dominating initial fusion cases where subsidence monitoring matters. Pricing pressure from Asian stainless steel manufacturers is eroding PEEK share in Latin American tenders.
- Biocompatible Polymer:Resorbable and composite formulations target pediatric and biologics-adjacent applications.
- Stainless Steel:Chinese-manufactured cages undercut polymer pricing in Southeast Asian and Brazilian public hospital procurement.
Titanium commands premium positioning; stainless steel is gaining share fastest in cost-constrained procurement environments.
End User:
Customer type determines capital intensity requirements and inventory model complexity, with site-specific clinical governance shaping vendor selection.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements covering cervical, thoracolumbar, and biologics portfolios, leveraging GPO scale for price protection.
- Ambulatory Surgical Centers:Freestanding facilities prioritize consignment inventory and instrument kit leasing to minimize capital outlay. CMS fee schedule expansion for multi-level cervical fusion is pulling hospital outpatient volume into these settings.
- Specialty Clinics:Orthopedic and neurosurgical focused practices drive adoption of motion-preserving platforms in younger patient cohorts.
- Rehabilitation Centers:Post-acute facilities influence downstream hardware selection through referral network relationships.
Hospitals retain procurement volume leadership; ambulatory surgical centers are climbing the fastest as site-of-care migration accelerates.
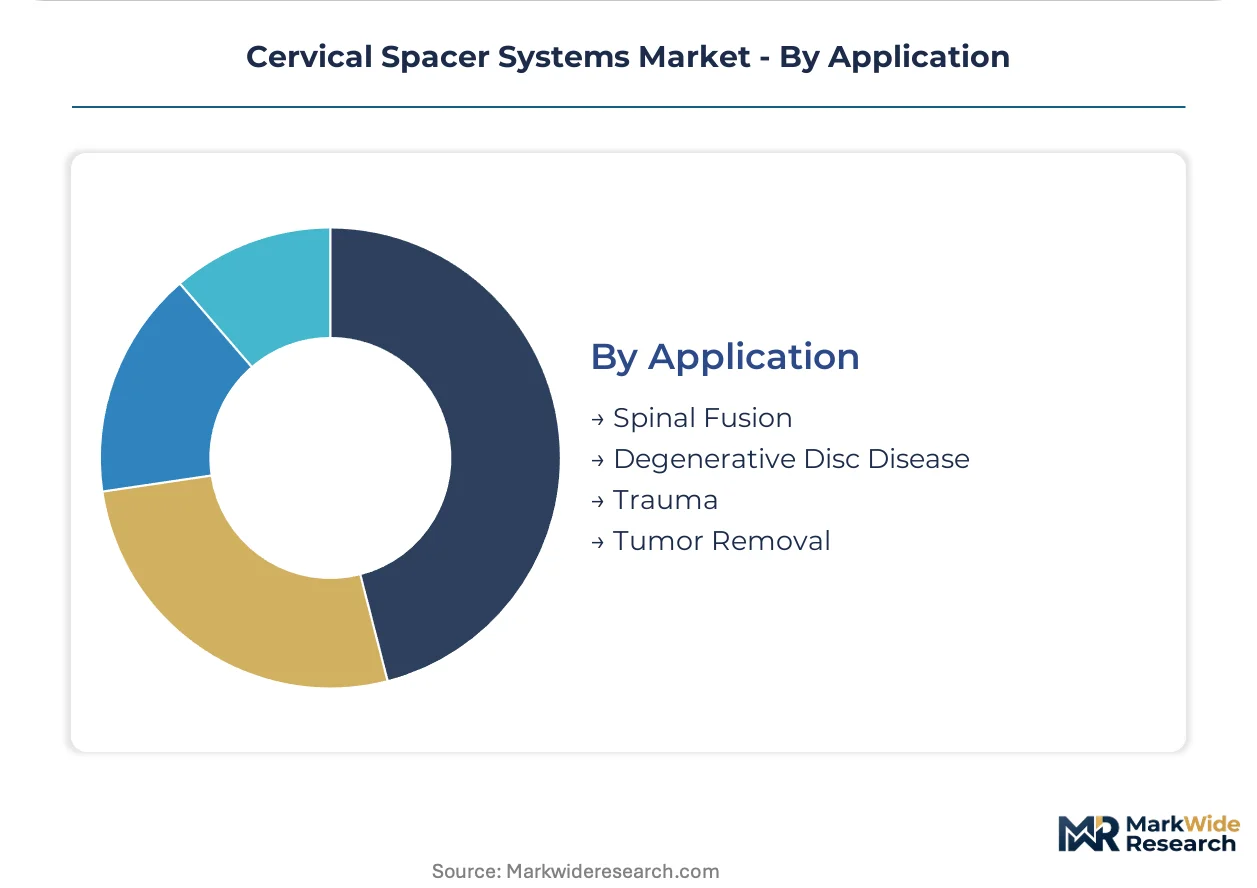
Application:
Clinical indication severity determines reimbursement tier and hardware specification requirements, with trauma and oncology cases demanding premium expandable configurations.
- Degenerative Disc Disease:Age-related cervical spondylosis generates the highest procedure volumes, typically addressed with single-level PEEK or titanium static spacers. Commercial payer coverage for motion-preserving alternatives is expanding the addressable patient population in the United States.
- Spinal Fusion:Elective anterior cervical discectomy and fusion procedures represent the core revenue base, with ASC migration shifting inventory requirements toward streamlined instrument kits.
- Trauma:Fracture and dislocation cases require expandable titanium platforms for intraoperative height restoration in unstable cervical segments.
- Tumor Removal:Oncologic resections demand custom sizing and multi-level reconstruction capabilities.
Spinal fusion retains procedural volume leadership; degenerative disc disease applications are expanding most quickly as aging demographics broaden the candidate pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in cervical spacer systems tilt toward net imports across emerging markets while established manufacturing clusters in Germany and the United States supply premium titanium porous structures to Asia-Pacific and Latin American distributors.
United States
Aging demographics and commercial payer expansion for motion-preserving alternatives drive procedural volume growth. FDA's accelerated 510(k) pathway for titanium porous structures compresses clearance timelines for domestic manufacturers. The Minneapolis-St. Paul corridor concentrates plasma atomization capacity serving aerospace and medical device demand simultaneously.
Germany
Strain-based EU MDR conformity assessments for titanium implants create first-mover advantages for manufacturers with pre-existing clinical data portfolios. German notified bodies prioritize ISO 5832-3 compliance certificates, generating a two-tier clearance backlog. The Stuttgart region anchors electron beam melting expertise shared between automotive and medical device sectors.
Brazil
ANVISA fast-track pathways for spinal implants with existing FDA clearance enable 8-12 month market entry versus historical 24-month timelines. Public hospital procurement tenders favor stainless steel alternatives over PEEK due to cost sensitivity. São Paulo's orthopedic distributor networks are consolidating to meet leasing model requirements from mid-tier ASC chains.
China
Domestic stainless steel interbody cage manufacturers undercut polymer pricing in Southeast Asian export markets. NMPA regulatory harmonization with ISO standards accelerates local production certification for porous titanium structures. The Yangtze River Delta clusters precision machining capacity serving both domestic hospital procurement and regional distributor networks.
Japan
PMDA reimbursement determinations for dynamic spacer platforms influence adoption rates among younger patient cohorts concerned with adjacent segment disease. METI industrial policy supports additive manufacturing technician training programs addressing aerospace-medical device labor competition. The Osaka-Kobe corridor concentrates PEEK composite processing expertise for hybrid implant production.
Cervical Spacer Systems Market Competitive Environment
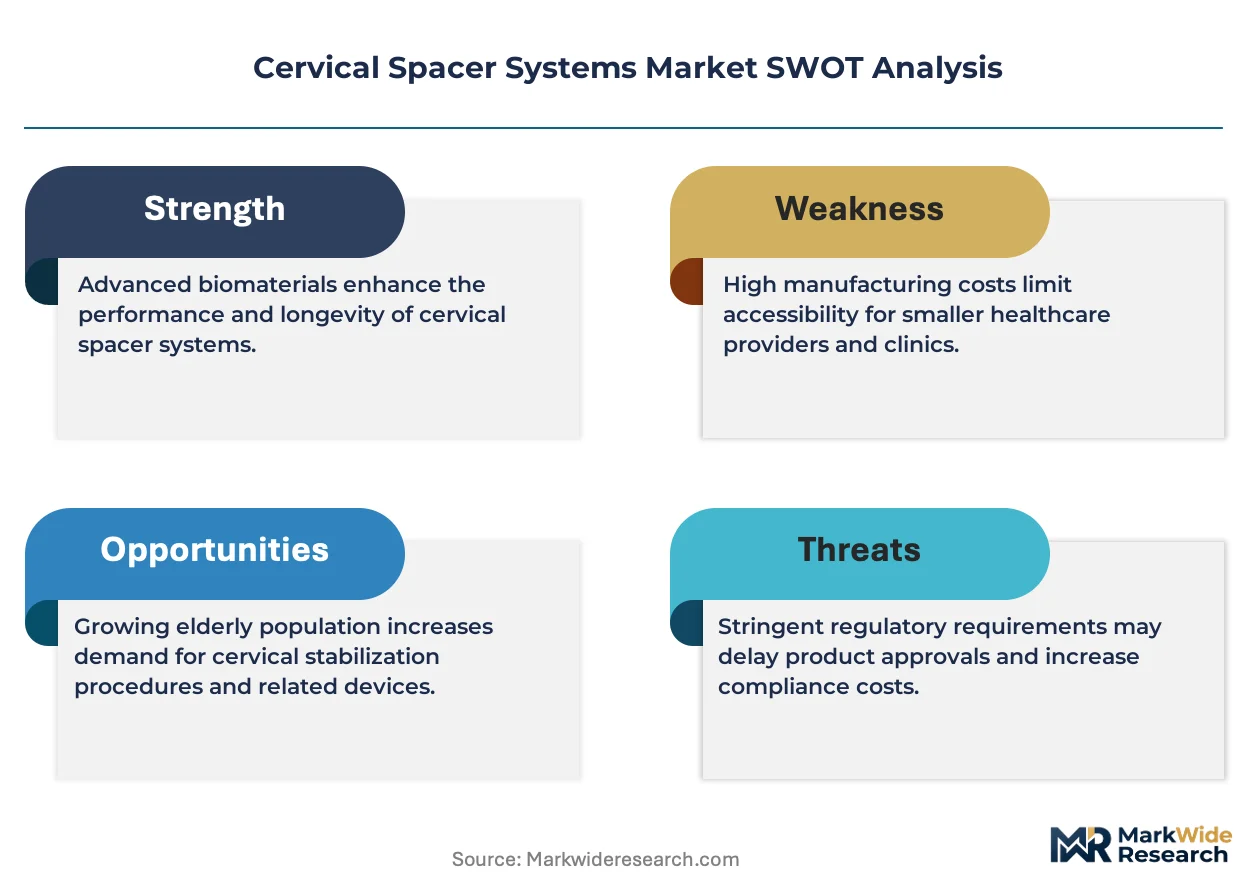
Platform integrators command the system tier; component specialists sit upstream supplying porous titanium structures and instrument kits to distributors lacking capital for full portfolio development. The vendor base stratifies across three tiers: multinational spine platforms with hospital contracting infrastructure, mid-tier distributors leasing instrumentation to ASCs, and regional stainless steel manufacturers competing on procurement tenders. Two dominant competitive moves define current positioning: direct-to-hospital leasing models that bypass distributor markups, and backward integration into plasma atomization capacity to secure titanium powder supply.
Among diversified orthopedic platforms, Stryker Corporation and Zimmer Biomet Holdings Inc exemplify contrasting material strategies—one leveraging titanium porous structures for complex revision positioning, the other anchoring PEEK portfolio breadth for high-volume ambulatory settings. Globus Medical occupies a specialist position in expandable configurations. These three entities represent the archetype spectrum from integrated delivery network contracting leverage to deformity-case premium capture.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| Zimmer Biomet Holdings Inc |
| Globus Medical |
| DePuy Synthes |
| NuVasive |
| Life Spine |
| Exactech |
| Orthofix Holdings |
| Others |
Value Chain & Pricing Dynamics
Plasma atomization undercapacity in Germany and the United States simultaneously constrains titanium powder availability and inflates input costs for porous structure manufacturers, compressing margins for device makers lacking long-term offtake agreements while enabling premium pricing for integrated suppliers with captive capacity.
Pricing Analysis
Hospital purchasing committees and ASC procurement officers anchor a three-tier pricing structure across premium, standard, and economy levels. Titanium porous structures command premium positioning against PEEK alternatives due to FDA 510(k) clearance scarcity and superior osseointegration performance. Cost compression in the stainless steel tier is intensifying because Chinese manufacturers are flooding Latin American tenders. Public hospital procurement teams in emerging markets exhibit the highest price sensitivity; integrated delivery networks in the United States demonstrate the lowest.
Supply Chain Analysis
Titanium powder feedstock draws from plasma atomization clusters concentrated in Germany, the United States, and Japan. Electron beam melting equipment, argon gas supplies, and ISO 5832-3 certified titanium sponge constitute critical input dependencies. Single-source vulnerability in aerospace-competing atomization capacity exposes medical device firms to allocation rationing during demand spikes. Distribution runs through orthopedic distributor networks with consignment inventory models dominating ASC channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron beam melting technician scarcity sits at the core of competitive positioning in this market, with firms possessing in-house training pipelines or aerospace sector recruitment access commanding manufacturing yield advantages that translate directly into margin expansion.
For Market Incumbents: Build regulatory data moats through 24-month follow-up studies for porous titanium structures ahead of FDA validation protocol extensions. Secure backward integration into plasma atomization capacity to insulate against aerospace demand spikes. Channel control through direct-to-hospital leasing models neutralizes distributor margin extraction. For New Entrants and Emerging Players: Mid-tier ASC chains in Florida and Texas represent the most penetrable entry point given GPO leverage fragmentation and site-specific clinical preference dominance. Brazilian ANVISA fast-track pathways for FDA-cleared devices compress market entry timelines versus historical benchmarks. Instrumentation kit rental partnerships with orthopedic distributors bypass capital-intensive inventory builds. For Investors and Strategic Acquirers: Capital is best deployed toward additive manufacturing specialists with electron beam melting capabilities and existing ISO 5832-3 compliance certificates. Long-term viability hinges on EU MDR technical documentation completion ahead of notified body prioritization shifts. Watch CMS reimbursement determinations for ASC-based multi-level cervical fusion as the inflection signal for site-of-care migration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed clearance timelines for titanium porous structures enable first-mover premium capture before validation protocols tighten further. |
| EU MDR Technical Documentation Investment | Strain-based conformity assessment completion secures notified body prioritization amid German backlog tiers. |
| Hospital System Partnership | Multi-year supply agreements across integrated delivery networks lock in volume commitments against GPO price protection. |
| Plasma Atomization Backward Integration | Captive titanium powder supply insulates margin from aerospace demand spikes and alloying cost volatility. |
| Reimbursement Strategy Development | CMS fee schedule alignment for ASC-based cervical fusion pulls hospital outpatient volume into lower-cost settings. |
Study Parameters
Cross-validation between surgeon interviews and hospital procurement database analysis anchors the qualitative findings. Primary fieldwork engaged spine surgeons, biomedical engineers, GPO contracts managers, and ASC operations directors across the United States, Germany, and Brazil. Secondary sources encompassed FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and ANVISA regulatory pathway records. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis were triangulated to converge on market sizing.
Calibration against historical clearance timelines and reimbursement expansion patterns shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product configuration, material composition, end-user setting, and application indication. CAGRs were derived from procedure volume trajectories, ASP evolution by material tier, and site-of-care migration coefficients. Forecast inputs incorporated FDA validation protocol extensions and EU MDR notified body capacity constraints.
Stress conditions across plasma atomization capacity utilization, CMS reimbursement determination timing, and Brazilian public hospital procurement tender participation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding surgeon adoption curves for expandable configurations and ASC infrastructure buildout rates. Cross-checking against hospital capital expenditure disclosures and orthopedic distributor inventory filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Nurse Call Systems Market
Medical Devices
Ovulation Microscope Market
Medical Devices
Osteosynthesis Devices Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
Phoropters Market
Medical Devices
Dual Balloon Angioplasty Catheter Market
Medical Devices
Bone Allografts Market
Medical Devices
Global Cardiac Pacemakers Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
Global Gynecology Robotic Surgery Market
Medical Devices
Catheter Introducer Sheaths Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Venous Device Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
Spinal Access Systems Market
Medical Devices
Heart Defect Closure Devices Market