
 Wilson Disease Drugs Market | 2026-2036
Wilson Disease Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Wilson Disease Drugs Market Analysis
A wide capital-intensity divergence between players is bifurcating the competitive landscape. Bausch Health leverages its established hepatology portfolio to sustain manufacturing economies of scale. Ultragenyx Pharmaceutical specializes in rare disease infrastructure, navigating complex reimbursement pathways with precision.
Wilson disease drugs encompass chelating agents, zinc supplements, and symptomatic treatments designed to reduce copper accumulation or block intestinal copper absorption through pharmacologic intervention. Chelating agents such as trientine and D-penicillamine function by binding excess copper for urinary excretion, while zinc salts inhibit copper absorption at the enterocyte level. Chelating agents command the largest current revenue pool due to decades of clinical validation, yet zinc supplements represent the fastest-expanding segment as physicians prioritize maintenance therapy with favorable tolerability profiles. Hospital pharmacies dominate distribution channels for initial diagnosis and acute management, though homecare settings are gaining structural importance as oral maintenance protocols extend treatment duration.
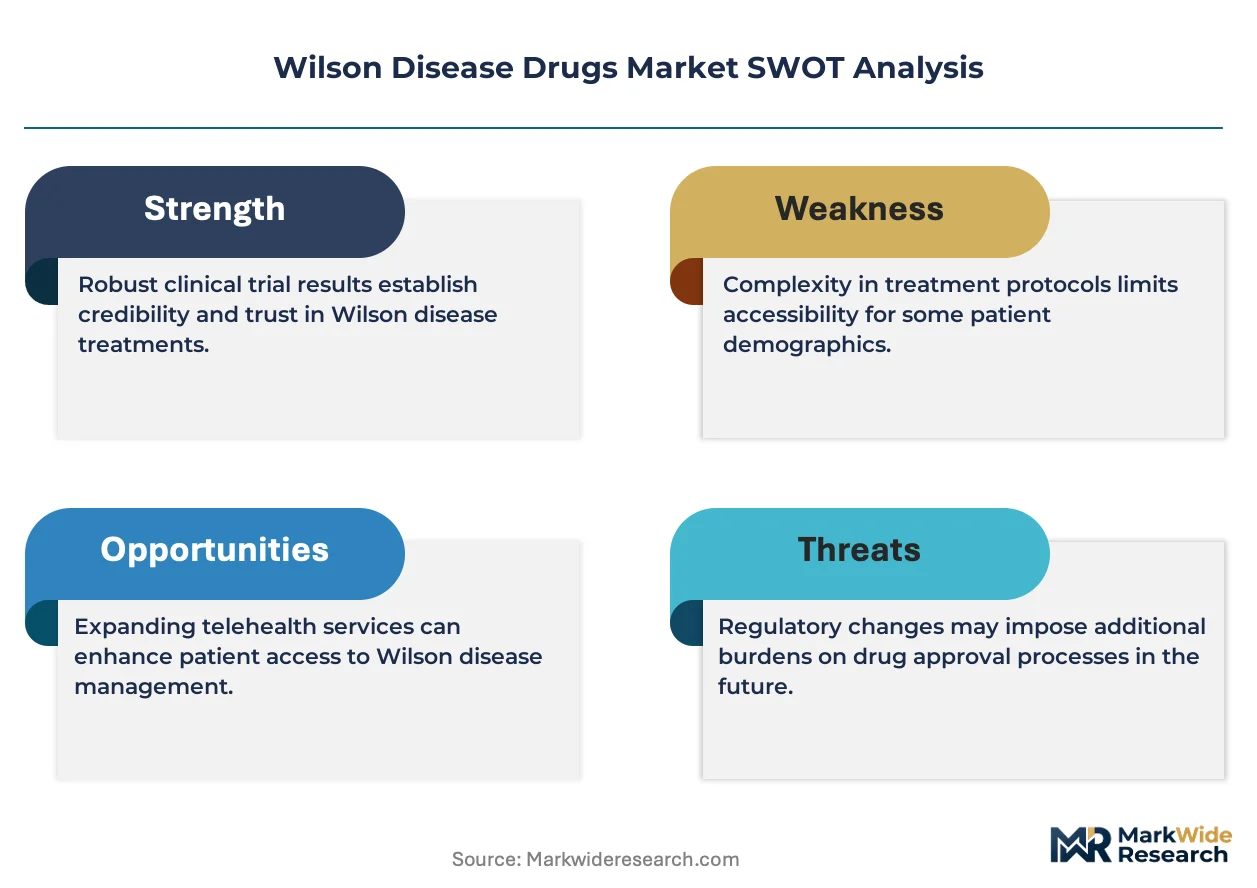
FDA orphan drug exclusivity provisions and EMA priority medicine frameworks shape clinical development incentives, while WHO essential medicines listing influences procurement standards in lower-resource health systems. The EU AI Act and GDPR impose emerging compliance burdens on digital diagnostic tools used for copper metabolism monitoring. Stakeholders must track evolving HTA body assessments of gene therapy alternatives and their potential displacement of chronic pharmacologic management.
Market Dynamics
Hospital-based treatment protocols for Wilson disease are expanding uptake of chelating therapies, while FDA orphan drug incentives and EMA priority medicine designations accelerate clinical trial investments across specialist hepatology networks.
Growth Catalysts
- Orphan Drug Incentives:FDA orphan drug exclusivity provisions reduce regulatory burden and extend market protection for developers of copper-chelating therapies. EMA priority medicine frameworks accelerate assessment timelines for novel treatments.
- Specialist Network Expansion:Dedicated hepatology centers in the United States, Germany, and Japan improve diagnostic capture rates and standardize maintenance protocols for chronic copper metabolism disorders.
- Zinc Salt Formulation Advances:Improved bioavailability in next-generation zinc supplements enables once-daily dosing that enhances patient adherence compared to legacy multi-dose regimens.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production for trientine and D-penicillamine concentrates among a limited number of specialized chemical manufacturers, creating vulnerability to single-source disruptions.
- Reimbursement Complexity:Rare disease drug pricing scrutiny from HTA bodies in Germany and France generates access delays and formulary restrictions for maintenance therapies.
- Diagnostic Underrecognition:Wilson disease symptom overlap with common psychiatric and hepatic conditions leads to prolonged time-to-diagnosis, compressing the addressable patient pool.
Strategic Opportunities
- Gene Therapy Pipeline:Emerging CRISPR-based approaches targeting ATP7B mutations offer potential curative alternatives to lifelong pharmacologic management, attracting venture investment.
- Homecare Channel Development:Oral maintenance protocols enable transition from hospital pharmacy dispensing to specialty pharmacy and direct-to-patient distribution models.
- Digital Diagnostic Integration:Copper metabolism monitoring apps and wearable biomarker sensors create companion diagnostic ecosystems that improve treatment titration precision.
Industry Challenges
- Clinical Trial Recruitment:Ultra-rare disease prevalence necessitates multi-country trial designs spanning the United States, Germany, and Japan to achieve statistically meaningful endpoints.
- Manufacturing Scale Economics:Small-batch production requirements for chelating agents limit process optimization and yield improvement compared to high-volume pharmaceutical categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wilson Disease Drugs Market |
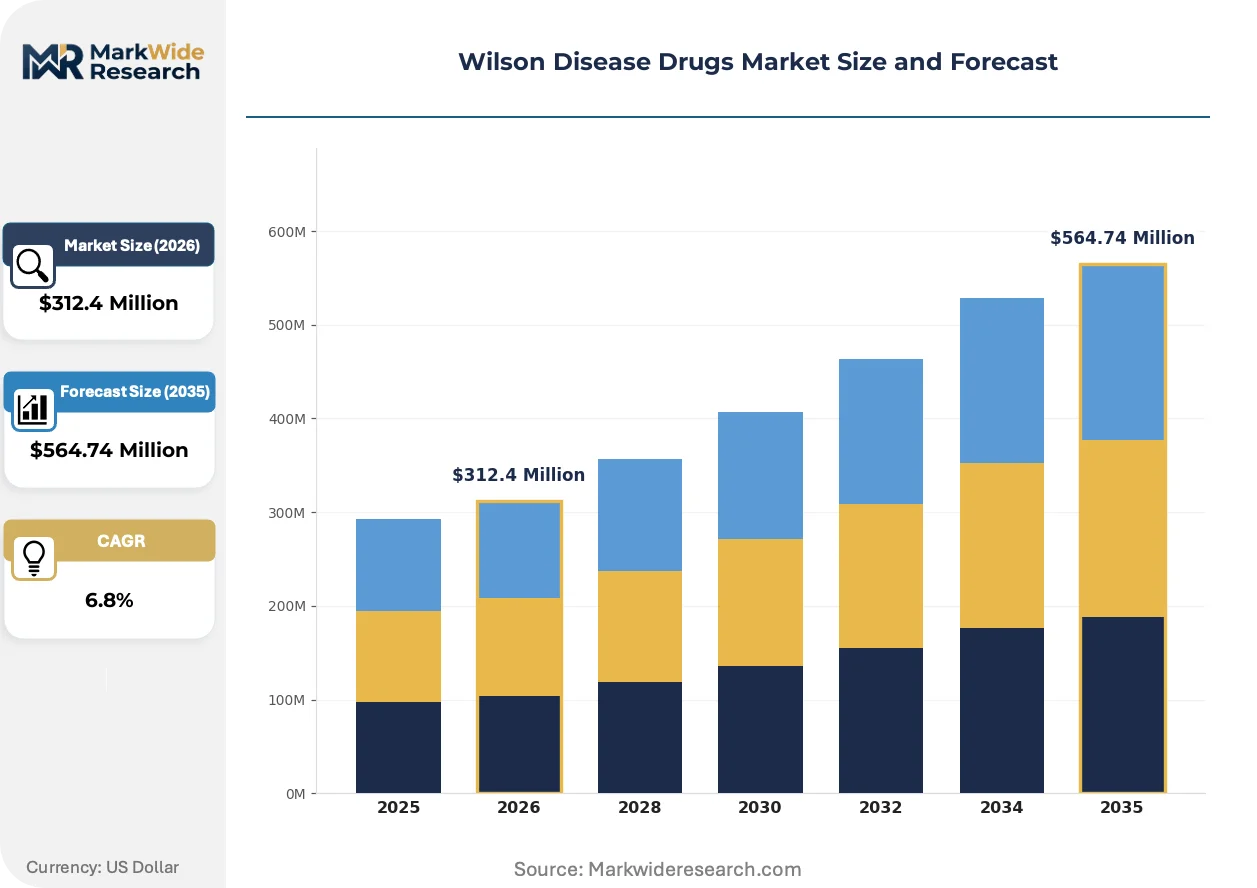
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chelating Agents, Zinc Supplements, Liver Transplantation, Symptomatic Treatments End User: Hospitals, Specialty Clinics, Community Pharmacies, Homecare Settings Administration Route: Oral, Intravenous, Subcutaneous, Transdermal Distribution Channel: Direct Sales, Retail Pharmacies, Hospital Pharmacies, Online Pharmacies |
| Companies Covered | GRANULES, Intas Pharmaceuticals, Bausch Health, Ultragenyx Pharmaceutical, Sun Pharmaceutical Industries, Dr. Reddy’s Laboratories, Teva Pharmaceutical, Orphalan, Eton Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wilson Disease Drugs Market Emerging Trajectories
Gene therapy development is displacing chronic pharmacologic management as the dominant strategic focus, while regulatory frameworks evolve to accommodate one-time curative interventions and digital health integration.
RNA interference therapeutics targeting hepatic copper accumulation are displacing conventional chelation regimens in preclinical and early clinical stages. Academic medical centers in the United States and Germany are prioritizing enrollment in siRNA trials for patients with neurological Wilson disease manifestations. This modality is displacing the assumption that lifelong daily medication represents the ceiling of therapeutic innovation.
The EU AI Act imposes algorithmic transparency requirements on diagnostic tools used for copper metabolism monitoring and predictive disease progression modeling. Developers must document training data provenance and clinical validation protocols for machine learning-based biomarker interpretation. European hepatology networks are responding by establishing qualified validator partnerships and restructuring digital tool procurement specifications.
Patient advocacy organizations are consolidating purchasing influence through centralized procurement of zinc supplements and chelating agents. Specialty pharmacies in Japan and Germany are negotiating direct manufacturer contracts that bypass traditional wholesale distribution tiers. This concentration is most visible in Germany, where national rare disease alliances leverage collective volume for preferential pricing and priority supply allocation.
Wilson Disease Drugs Market Segmentation
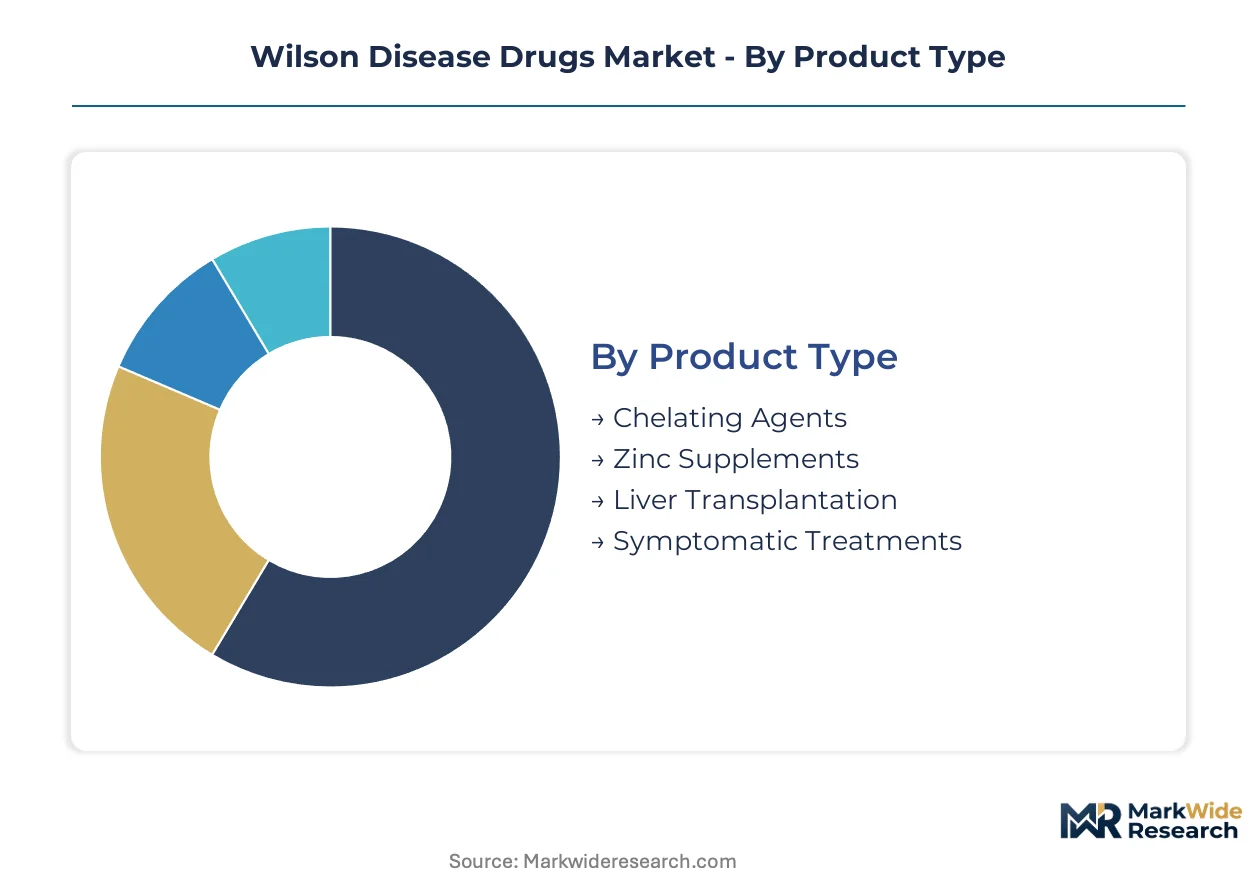
Wilson disease therapeutics fragment across product mechanisms, care settings, and delivery pathways that each carry distinct regulatory and reimbursement profiles. Understanding these divisions reveals where capital allocation concentrates and where patient access bottlenecks emerge.
Product Type:
FDA orphan drug exclusivity and EMA priority medicine frameworks create divergent development incentives across therapeutic categories, with chelating agents benefiting from decades of regulatory precedent while gene therapy alternatives navigate novel approval pathways.
- Chelating Agents:Trientine and D-penicillamine bind excess copper for urinary excretion through sulfhydryl coordination chemistry. Hospital-based hepatology networks in the United States and Germany drive demand concentration as these institutions standardize acute de-coppering protocols for newly diagnosed patients.
- Zinc Supplements:Zinc salts block intestinal copper absorption at the enterocyte level through metallothionein induction. Maintenance therapy protocols in Japan and community pharmacy channels in Germany favor this category for its tolerability profile and oral administration convenience.
- Liver Transplantation:Curative surgical intervention reserved for fulminant hepatic failure or chelation-resistant neurological deterioration. Procurement concentrates at academic medical centers with dedicated hepatobiliary surgery units.
- Symptomatic Treatments:Antipsychotics, anti-tremor agents, and hepatic support therapies address copper accumulation sequelae without modifying disease progression. Prescribing patterns follow psychiatric and neurological specialty referral networks.
Chelating agents handle the majority of throughput; zinc supplements are expanding most quickly on share as maintenance protocols lengthen treatment duration.
End User:
Cost tier differentiation separates acute intervention sites from chronic management venues, with reimbursement intensity declining as patients transition from hospital-based to ambulatory care.
- Hospitals:Academic medical centers and tertiary hepatology units manage initial diagnosis, acute chelation, and transplant evaluation. FDA breakthrough therapy designations and EMA priority medicine status accelerate trial enrollment at these sites.
- Specialty Clinics:Dedicated metabolic disease and hepatology clinics coordinate long-term copper monitoring and dose titration. Germany's national rare disease networks and Japan's designated intractable disease centers concentrate this capacity.
- Community Pharmacies:Dispensing points for maintenance zinc and oral chelating agents with established procurement relationships. Volume scales with outpatient prescribing authority expansion.
- Homecare Settings:Direct-to-patient distribution models for stable maintenance regimens. Payer pressure for cost containment drives structural shift toward this channel.
Hospitals capture the highest reimbursement per patient episode; homecare settings are gaining share fastest as oral maintenance protocols mature.
Administration Route:
Patient compliance requirements and pharmacokinetic profiles determine route selection, with oral formulations dominating chronic management and parenteral options reserved for acute or neurological presentations.
- Oral:Zinc salts and trientine capsules for maintenance therapy with established bioavailability profiles. Once-daily extended-release formulations under development target adherence improvement.
- Intravenous:Hospital-administered chelation for acute hepatic decompensation or pre-transplant stabilization. Administration concentrates at centers with continuous monitoring capability.
- Subcutaneous:Emerging depot formulations and investigational RNA interference therapeutics targeting hepatic copper metabolism. Early trials prioritize neurological Wilson disease cohorts.
- Transdermal:Experimental zinc and copper-modulating patches with limited current clinical validation. Development activity concentrates at academic spinouts with dermatology delivery expertise.
Oral administration handles the majority of patient-days; subcutaneous delivery is climbing the fastest as novel modalities advance through clinical pipelines.
Distribution Channel:
Supply chain configuration reflects product stability requirements, regulatory classification, and patient access urgency, with hospital pharmacies maintaining critical stock for acute presentations.
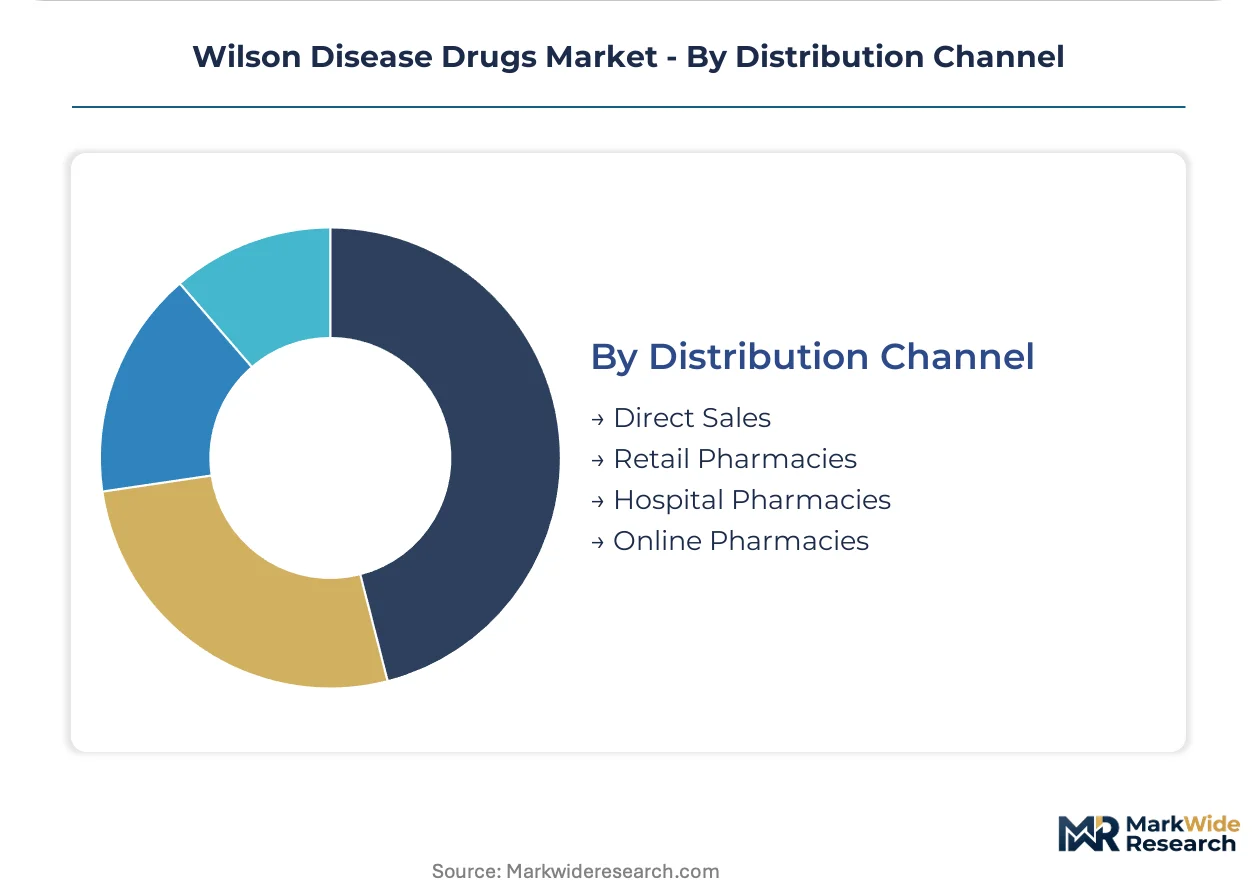
- Direct Sales:Manufacturer-to-institution contracts for high-cost chelating agents and transplant immunosuppressants. Germany's rare disease alliances leverage collective purchasing volume for preferential terms.
- Retail Pharmacies:Community-based dispensing for maintenance zinc and stable oral chelation regimens. Japan's pharmacy network density supports patient convenience for chronic therapy.
- Hospital Pharmacies:In-house procurement for acute chelation, intravenous formulations, and investigational access programs. Inventory management prioritizes rapid availability for hepatic emergencies.
- Online Pharmacies:Digital fulfillment for maintenance refills with prescription verification requirements. Growth constrained by controlled substance classification of certain chelating agents.
Hospital pharmacies manage the highest-value throughput; online pharmacies are gaining share fastest as maintenance patient populations expand and digital health integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany exceeds that in Japan by substantial margins, reflecting divergent HTA frameworks and rare disease procurement structures. The United States commands premium reimbursement for acute interventions. Market access velocity varies dramatically across these three concentrated demand centers.
United States
FDA orphan drug exclusivity provisions attract venture capital into ATP7B-targeting gene therapy pipelines. Academic medical centers in Boston and Philadelphia anchor clinical trial enrollment for novel chelating formulations. Hospital pharmacy procurement concentrates at tertiary hepatology units with established Wilson disease referral networks.
Germany
EMA priority medicine frameworks accelerate assessment timelines for copper metabolism therapeutics. National rare disease alliances leverage collective purchasing volume for preferential zinc supplement pricing. The Heidelberg and Hamburg metropolitan regions host specialized metabolic disease centers coordinating maintenance protocol standardization.
Japan
Designated intractable disease status under the Ministry of Health, Labour and Welfare secures subsidized patient cost-sharing for chronic chelation therapy. PMDA consultation programs de-risk development for novel zinc salt formulations. The Kanto region surrounding Tokyo maintains the highest specialist hepatology clinic density for diagnostic capture.
United Kingdom
NICE technology appraisals impose cost-effectiveness thresholds that delay formulary inclusion for maintenance therapies. NHS England specialized commissioning frameworks concentrate Wilson disease management at designated supra-regional centers. The Greater Manchester and London hepatology networks drive standardized care pathway implementation.
India
CDSCO accelerated approval pathways for orphan indications reduce regulatory timelines for imported chelating agents. Domestic API manufacturing for trientine concentrates in Hyderabad and Ahmedabad reduces import dependency for public sector procurement. Government hospital hepatology departments manage the majority of diagnosed cases through centralized state-level rare disease programs.
Wilson Disease Drugs Market Vendor Landscape
Concentration sits with diversified pharmaceutical conglomerates possessing established rare disease infrastructure. The vendor base spans three structural tiers: global generics manufacturers with hepatology portfolios, mid-cap specialists navigating orphan drug economics, and emerging biotechs advancing gene therapy alternatives. Strategic moves center on API supply security partnerships and direct-to-patient distribution channel development for maintenance regimens.
Within the diversified pharmaceutical tier, Bausch Health and Teva Pharmaceutical occupy positions sustained by manufacturing scale and established hepatology sales infrastructure. Ultragenyx Pharmaceutical exemplifies the rare disease specialist archetype, with organizational design optimized for complex reimbursement navigation and ultra-small patient population engagement. Indian generics manufacturers including Sun Pharmaceutical Industries and Dr. Reddy's Laboratories represent the cost-optimized supply segment, leveraging domestic API production and emerging market distribution density.
| Leading Market Players |
|---|
| GRANULES |
| Intas Pharmaceuticals |
| Bausch Health |
| Ultragenyx Pharmaceutical |
| Sun Pharmaceutical Industries |
| Dr. Reddy's Laboratories |
| Teva Pharmaceutical |
| Orphalan |
| Eton Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
FDA orphan drug exclusivity provisions gate both API supplier qualification and price differentiation for Wilson disease therapeutics, concentrating pricing power with manufacturers holding validated manufacturing records while forcing new entrants into protracted bioequivalence investments.
Pricing Analysis
Customization-premium spreads separate branded chelating agents from commodity zinc supplements, with D-penicillamine and trientine formulations commanding substantial markups over generic alternatives due to batch-specific validation requirements. Price differentiation rests on FDA manufacturing site inspection history and EMA GMP certification tier. Cost compression in the zinc supplement segment intensifies as Indian API manufacturers expand capacity. Community pharmacies exhibit highest price sensitivity, while academic medical centers prioritize supply security over unit cost.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient production for trientine and D-penicillamine, with Hyderabad and Ahmedabad hosting concentrated specialty chemical manufacturing clusters. Raw material dependencies include copper-chelating precursor chemicals, pharmaceutical-grade solvents, and specialized packaging for moisture-sensitive formulations. Single-source vulnerability permeates the API tier, where qualified alternative suppliers require multi-year regulatory revalidation. Distribution runs through hospital pharmacies for acute presentations, with specialty pharmacy networks handling maintenance therapy fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement coalitions in Germany and Japan, where national rare disease alliances aggregate volume sufficient to extract preferential terms from manufacturers.
For Market Incumbents: Compound manufacturing economies of scale by securing captive API supply through backward integration into Indian chemical synthesis partnerships. Prioritize EMA priority medicine designation maintenance to sustain pricing leverage against emerging gene therapy substitutes. Channel control through direct-to-patient distribution platforms defends margin position against specialty pharmacy intermediaries. For New Entrants and Emerging Players: Differentiate on subcutaneous depot formulation convenience for neurological Wilson disease cohorts underserved by oral maintenance protocols. White-space targets include homecare settings in Japan and community pharmacy channels in Germany where oral zinc protocols dominate. Pursue PMDA consultation program engagement as the go-to-market angle to accelerate Japanese market access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gene therapy manufacturing infrastructure, compressing returns for platform technologies lacking commercial-stage assets. Long-term viability over the coming decade favors developers with established hepatology sales infrastructure and validated rare disease reimbursement pathways. Acquisition target archetype: mid-cap specialists with EMA priority medicine status and concentrated German prescriber relationships. Monitor CRISPR clinical trial readouts as the inflection signal for chronic pharmacologic management displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| API Supply Security Partnership | Backward integration into Indian chemical manufacturing reduces single-source vulnerability for trientine precursors. |
| Direct-to-Patient Distribution Launch | Bypassing wholesale tiers captures margin compression from German rare disease alliance procurement concentration. |
| EMA Priority Medicine Designation Pursuit | Accelerated assessment timelines compress competitive entry windows for novel zinc salt formulations. |
| Gene Therapy Pipeline Advancement | CRISPR-based ATP7B targeting attracts venture allocation displacing chronic chelation assumptions. |
| Digital Diagnostic Integration | Copper metabolism monitoring apps create companion ecosystems improving treatment titration precision for hepatology networks. |
Methodological Framework
A standing panel of hepatology department heads, rare disease formulary directors, pharmaceutical regulatory affairs leads, and specialty pharmacy procurement managers provided ongoing calibration against evolving market conditions. Primary interview intelligence combined with secondary validation from FDA orphan drug designations, EMA priority medicine registers, ClinicalTrials.gov enrollment data, and national rare disease alliance procurement disclosures. Bottom-up patient population estimates triangulated against top-down pharmaceutical sales analytics across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including WHO essential medicines procurement records and national hepatology society treatment guidelines. The analytical framework modeled segmentation dimensions spanning product mechanism, administration route, care setting, and regional regulatory cluster. CAGRs derived from patient prevalence projections, treatment penetration assumptions, and pricing trajectory modeling. Forecast inputs incorporated HTA body reimbursement decisions and gene therapy pipeline advancement milestones.
Decision-makers should treat outputs as directional under assumptions of stable orphan drug incentive frameworks and continued specialist network expansion; material deviation in regulatory support levels or diagnostic capture rates would warrant model refresh. Recalibration cycles align with material shifts in EMA assessment timelines, gene therapy clinical readouts, and national rare disease procurement restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
Chronic Kidney Disease (CKD) Drugs Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Europe Pharmaceutical Warehousing Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
Sarcoidosis Drugs Market
Pharmaceuticals
Chronic Obstructive Pulmonary Disease Drugs Market
Pharmaceuticals
Middle East and Africa Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Bisphosphonates Market
Pharmaceuticals
Saudi Arabia Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Global Vaccine Contract Manufacturing Market